
 Europe Self Adhesives Label Market | 2026-2036
Europe Self Adhesives Label Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Self Adhesives Label Market Foresight
Food & Beverage is restructuring the largest share of demand as brands replace wet-glue labels with pressure-sensitive formats to cut downtime and enable recyclability claims. Avery Dennison Corporation dominates the premium film substrate segment through its specialized manufacturing footprint in Western Europe. UPM Raflatac leverages its renewable materials portfolio to anchor supply relationships with sustainability-focused CPG buyers. Mondi competes on integrated pulp-to-label economics that sustain margin pools across Central European paper grades.
Self adhesives labels are pressure-sensitive constructions comprising a face stock, adhesive layer, and release liner that bond to surfaces upon light pressure without heat, solvents, or water activation, typically specified for adhesion values between 0.5 and 5 N/25mm depending on substrate and permanence requirements. Film face stocks lead value contribution due to durability premiums in logistics and healthcare applications, while digital printing technology captures the fastest growth trajectory as short-run customization and variable data serialization displace conventional flexographic volumes in pharmaceutical and food segments. Paper substrates retain volume dominance in retail price-marking and promotional labeling where cost sensitivity outweighs performance requirements.
REACH compliance and the EU Packaging and Packaging Waste Regulation shape material selection by restricting certain adhesive chemistries and mandating recyclability design criteria across member states. ECHA substance evaluations and national extended producer responsibility schemes in France, Germany, and Italy are forcing reformulation investments that favor removable and repositionable adhesive categories. Stakeholders must monitor the interplay between emerging EU digital product passport requirements and existing serialization standards to align capital allocation across substrate, adhesive, and printing technology combinations.
Market Dynamics
Pharmaceutical serialization mandates under the EU Falsified Medicines Directive are forcing wholesale substrate and adhesive reformulation across European label supply chains, compressing legacy flexographic volumes while expanding digital-ready film specifications.
Growth Catalysts
- EU Falsified Medicines Directive:Track-and-trace serialization requirements in Germany and France are mandating high-resolution variable data labels that only pressure-sensitive constructions can reliably deliver.
- Food & Beverage line automation:Wet-glue-to-pressure-sensitive conversion programs are cutting changeover downtime by eliminating water-based adhesive drying stations and enabling faster format switching.
- Recyclability design criteria:The EU Packaging and Packaging Waste Regulation is pulling demand toward removable adhesive categories that maintain fiber recovery rates in paper recycling streams.
Market Restraints
- Petrochemical feedstock volatility:Acrylic and rubber-based adhesive polymers face margin compression from propylene and styrene price swings that resist pass-through in contract label markets.
- Release liner waste accumulation:Siliconized paper and film liners constitute 30-40% of label mass by weight, creating disposal cost burdens where national extended producer responsibility schemes lack recycling infrastructure.
- REACH substance restrictions:ECHA evaluations of certain tackifier resins and plasticizers are forcing unplanned reformulation cycles that extend qualification timelines with certified end-users.
Strategic Opportunities
- Italian pharmaceutical manufacturing expansion:Lombardy and Emilia-Romagna clusters are attracting serialization-ready label investments as drug production migrates from higher-cost Northern European sites.
- Digital product passport alignment:Emerging EU requirements for embedded traceability data are creating specification pull for RFID-enabled and QR-integrated label constructions.
- Renewable face stock penetration:UPM Raflatac's wood-based film alternatives and certified paper grades are opening premium positioning with sustainability-scored CPG procurement frameworks.
Industry Challenges
- Digital printing technician scarcity:Shortage of operators qualified on HP Indigo and Xeikon platforms is constraining capacity expansion despite equipment availability.
- Multi-substrate qualification timelines:Pharmaceutical and food safety certifications require 12-18 month validation cycles that lock out rapid material switching when supply disruptions occur.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Self Adhesives Label Market |
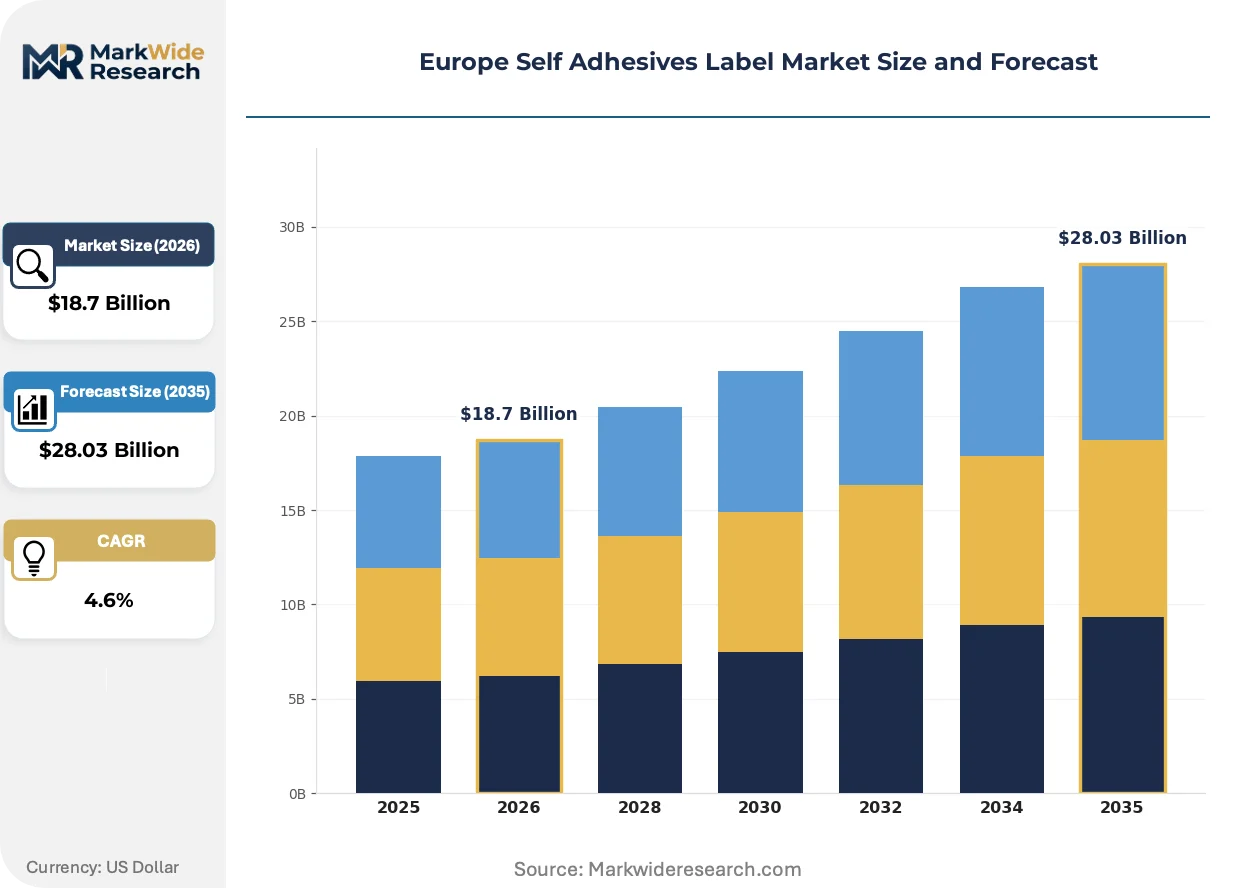
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.03 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper, Film, Metalized, Specialty End User: Food & Beverage, Healthcare, Retail, Logistics Technology: Digital Printing, Flexographic Printing, Offset Printing, Screen Printing Adhesive Type: Permanent, Removable, Repositionable, Pressure Sensitive |
| Companies Covered | Avery Dennison Corporation, UPM Raflatac, Fuji Seal International, Inc., H.B. Fuller Company, LINTEC Corporation, Mondi, Coveris, Herma, CCL Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Self Adhesives Label Market Shifts & Advancements
Digital printing technology is compressing minimum order quantities and enabling mass serialization, while regulatory pressure on recyclability is rewriting material specifications across substrate-adhesive combinations.
Laser die-cutting systems paired with digital presses are rewriting production economics for short-run pharmaceutical and craft beverage labels. German and French converters are deploying these lines to serve lot sizes below 5,000 units that flexographic equipment cannot address profitably. The technology is rewriting competitive positioning by collapsing tooling costs and enabling same-day turnaround on variable data jobs.
REACH compliance and the EU Packaging and Packaging Waste Regulation are mandating design-for-recycling criteria that restrict certain permanent adhesive chemistries. Label producers must now qualify removable and wash-off formulations that release cleanly during fiber recovery or container washing processes. Pharmaceutical and dairy segments in Germany and the Netherlands are most affected, with buyers now specifying adhesives against PPWR recyclability test protocols.
CPG procurement teams are consolidating supplier panels and demanding integrated substrate-adhesive-printing packages that reduce qualification overhead. This pattern is displacing fragmented sourcing of face stocks, adhesives, and conversion services. Food & Beverage multinationals headquartered in Switzerland and the Netherlands are driving this consolidation, using sustainability scorecards to filter vendor pools.
Europe Self Adhesives Label Market Segmentation
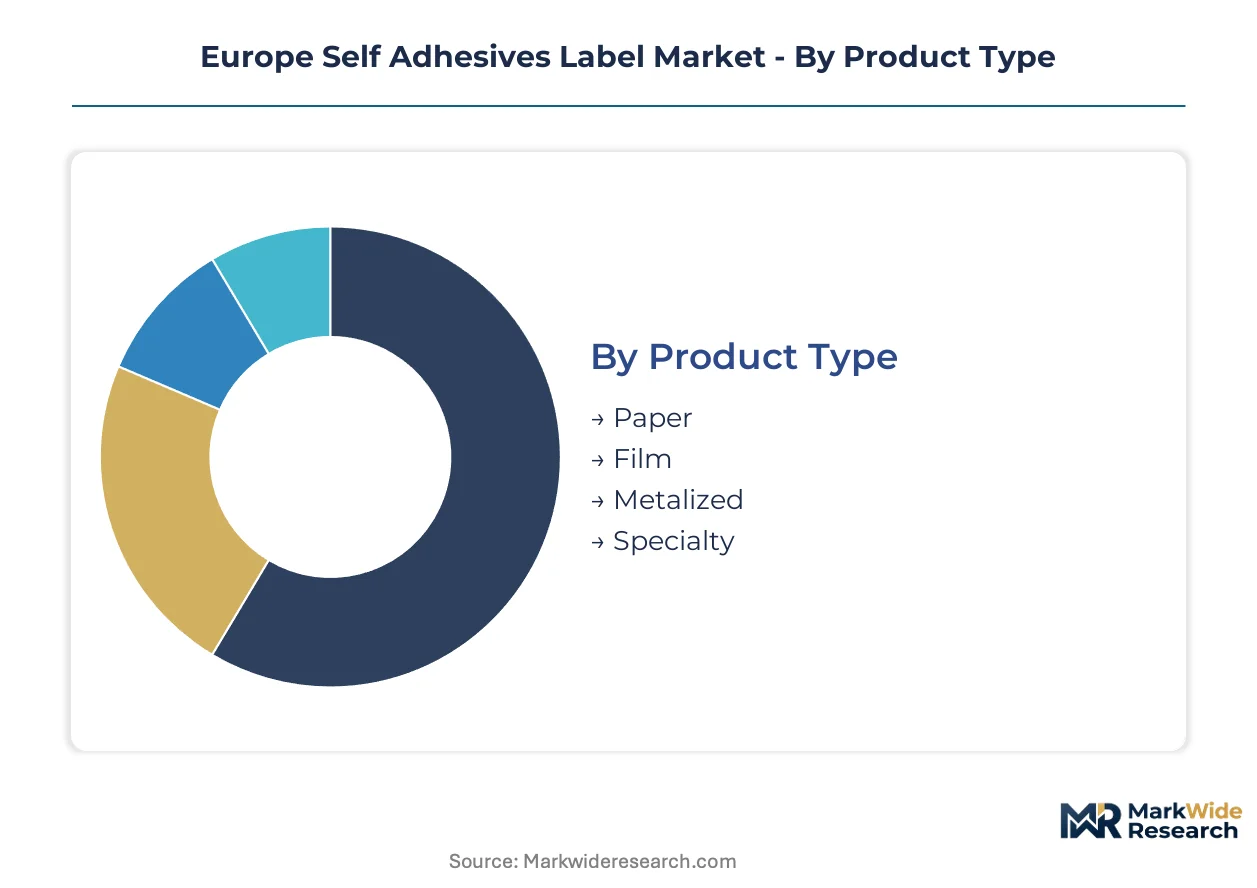
Segmentation in the Europe Self Adhesives Label Market reveals how substrate choices, adhesive chemistries, and printing technologies map to distinct certification burdens and supply chain configurations. Each dimension carries specific regulatory obligations that shape procurement patterns across German pharmaceutical clusters and French food manufacturing hubs.
Product Type:
Paper substrates carry lighter EFSA food-contact certification requirements than film grades, while metalized and specialty constructions face REACH substance restrictions on aluminum vapor deposition and holographic additives.
- Film:Polypropylene and polyethylene terephthalate constructions deliver moisture resistance and dimensional stability for pharmaceutical vial labeling and refrigerated logistics. German healthcare serialization mandates are concentrating demand for white and clear biaxially oriented polypropylene in Bavarian and Baden-Württemberg pharmaceutical corridors.
- Paper:Uncoated and coated wood pulp substrates dominate retail price-marking and promotional applications where cost sensitivity outweighs durability requirements. French hypermarket chains and Italian grocery cooperatives specify paper for short-life promotional cycles.
- Metalized:Vacuum-deposited aluminum layers on film or paper carriers create barrier properties and premium aesthetics for cosmetics and confectionery.
- Specialty:Holographic, tamper-evident, and temperature-indicating constructions serve anti-counterfeiting and cold-chain monitoring in Dutch pharmaceutical distribution.
Film sits at the top of the volume ranking, with specialty climbing the fastest.
End User:
Healthcare applications impose the most demanding adhesive qualification protocols, while food and beverage buyers prioritize line speed compatibility and recyclability credentials under EU Packaging and Packaging Waste Regulation test methods.
- Healthcare:Pharmaceutical vial labels, syringe labels, and blood bag tags require cytotoxicity testing and extractables profiling under EMA guidelines. Serialization-ready constructions with tamper-evident features are expanding fastest in German and French drug manufacturing clusters.
- Food & Beverage:Wet-glue-to-pressure-sensitive conversions are eliminating water-based adhesive drying stations in dairy, beverage, and prepared food lines. German and Dutch brands specify removable adhesives to maintain fiber recovery rates in paper recycling streams.
- Retail:Shelf-edge labels, price stickers, and promotional tags prioritize low-cost paper substrates with permanent acrylic adhesives.
- Logistics:Shipping labels and inventory tags demand thermal transfer and direct thermal face stocks with all-temperature adhesive performance for warehouse and transport environments.
Food & Beverage generates the largest order volumes, with healthcare expanding most quickly.
Technology:
Digital platforms carry lower setup costs but require HP Indigo and Xeikon operator certifications that constrain capacity expansion, while flexographic lines demand longer runs to amortize plate costs.
- Digital Printing:Electrophotographic and inkjet systems enable lot sizes below 5,000 units with variable data serialization for pharmaceutical track-and-trace. German and French converters deploy these lines where flexographic economics fail.
- Flexographic Printing:Rotary relief printing with photopolymer plates dominates long-run food and beverage labels where color consistency and metallic effects justify plate investment.
- Offset Printing:Lithographic transfer delivers fine detail and color fidelity for premium cosmetics and wine labels in Italian and Spanish production.
- Screen Printing:Thick ink deposits create tactile and opaque effects for industrial and safety labels requiring durability under chemical exposure.
Flexographic retains volume leadership, with digital gaining share fastest.
Adhesive Type:
Permanent adhesives face REACH scrutiny on tackifier resins, while removable and repositionable categories benefit from EU Packaging and Packaging Waste Regulation recyclability design criteria.
- Permanent:Acrylic and rubber-based polymers deliver high initial tack and ultimate adhesion for logistics, industrial, and pharmaceutical applications. ECHA evaluations of certain tackifier resins are forcing reformulation cycles that extend qualification timelines.
- Removable:Low-tack formulations release cleanly from glass and plastic containers without residue, supporting circular economy claims in German dairy and beverage packaging.
- Repositionable:Microsphere adhesives allow multiple application attempts for retail signage and temporary promotional materials.
- Pressure Sensitive:The foundational construction category encompassing permanent, removable, and repositionable variants that bond upon light pressure without heat or solvent activation.
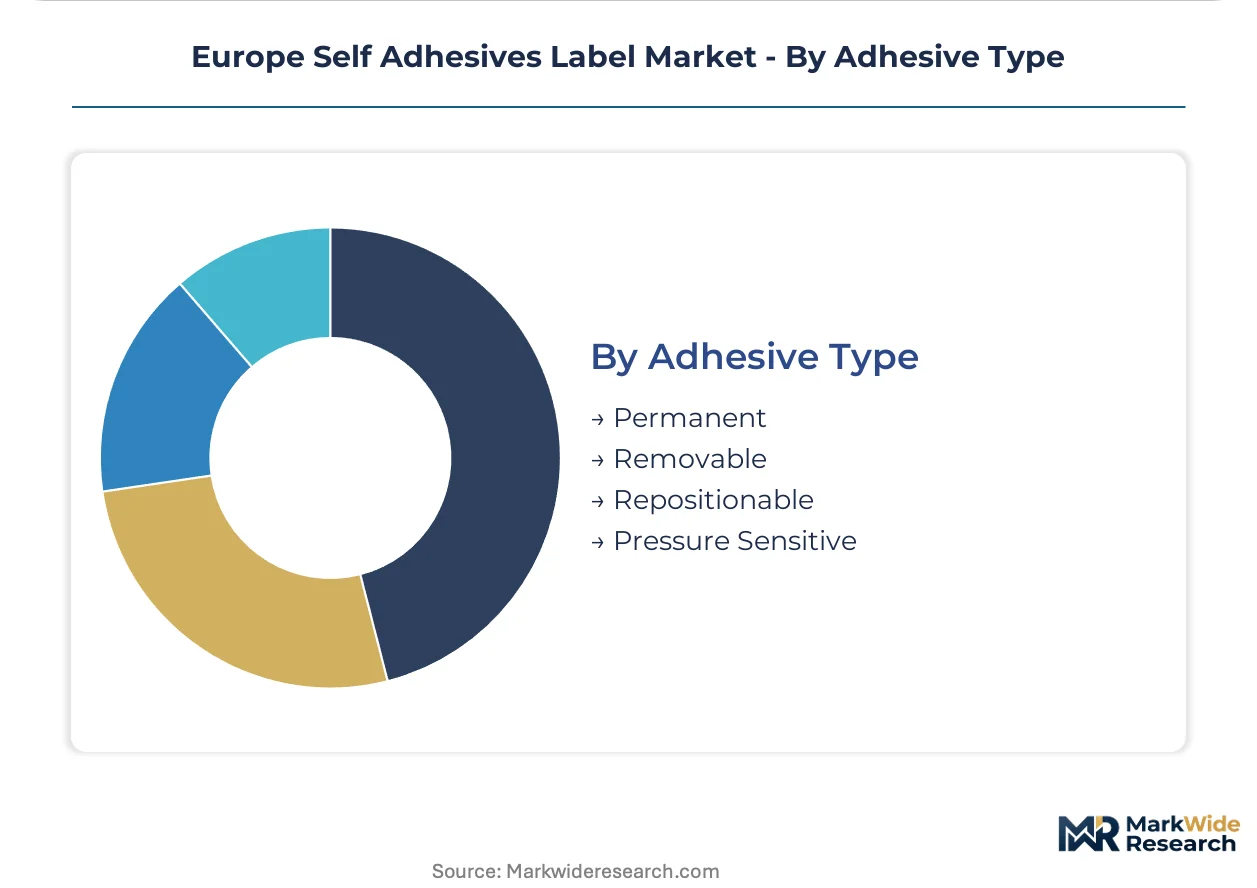
Permanent adhesives dominate by volume, with removable formulations expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration toward lower-cost compliance jurisdictions is reshaping label manufacturing footprints across Europe, as pharmaceutical serialization mandates and extended producer responsibility schemes create divergent cost structures between member states.
Germany
Bavarian and Baden-Württemberg pharmaceutical corridors drive demand for serialization-ready film constructions. REACH substance evaluations from ECHA force reformulation investments that extend qualification timelines with certified end-users. Stuttgart-based converters deploy laser die-cutting systems to serve short-run variable data jobs below 5,000 units.
France
Hypermarket chains and grocery cooperatives specify paper substrates for promotional labeling cycles. ANSM pharmaceutical serialization requirements pull demand toward high-resolution digital printing platforms. Île-de-France packaging hubs concentrate wet-glue-to-pressure-sensitive conversion programs for dairy and beverage lines.
Italy
Lombardy and Emilia-Romagna pharmaceutical clusters attract serialization-ready label investments as drug production migrates from higher-cost Northern European sites. EFSA food-contact certification requirements shape adhesive selection for pasta and olive oil exporters. Bologna-area converters specialize in premium wine label offset printing for export markets.
Netherlands
Dutch dairy and beverage brands specify removable adhesives to maintain fiber recovery rates under EU Packaging and Packaging Waste Regulation test protocols. Rotterdam logistics hubs demand thermal transfer face stocks with all-temperature adhesive performance. Amsterdam-headquartered CPG procurement teams consolidate supplier panels using sustainability scorecards.
United Kingdom
London and Southeast England pharmaceutical distribution networks require tamper-evident constructions for import compliance. MHRA post-Brexit serialization standards diverge from EU Falsified Medicines Directive, creating dual qualification burdens. Midlands-based converters serve craft beverage segments with digital printing for lot sizes below 5,000 units.
Europe Self Adhesives Label Market Competitive Landscape
Strategic partnerships dominate the current landscape as substrate suppliers, adhesive formulators, and printing technology providers bundle capabilities to meet consolidated CPG procurement requirements. The vendor base stratifies across three tiers: integrated pulp-to-label conglomerates with captive raw material positions; specialized film and adhesive technology houses; and regional converters competing on turnaround speed and customization. Two archetypes define competitive positioning: sustainability-scored suppliers capturing premium procurement frameworks, and automation-focused operators serving pharmaceutical serialization demand. M&A activity and capacity expansion in digital printing platforms represent the dominant competitive moves.
Within the integrated materials tier, Avery Dennison Corporation and UPM Raflatac exemplify divergent strategic anchors. The former occupies a position emphasizing specialized manufacturing footprints and premium film substrate portfolios. The latter represents renewable materials positioning through wood-based film alternatives and certified paper grades. Mondi sits within the pulp-to-label economics archetype, leveraging captive fiber supply across Central European operations. These three entities collectively illustrate how substrate-adhesive integration, sustainability credentials, and geographic manufacturing density serve as the primary vectors of differentiation in European label supply.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| UPM Raflatac |
| Fuji Seal International, Inc. |
| H.B. Fuller Company |
| LINTEC Corporation |
| Mondi |
| Coveris |
| Herma |
| CCL Industries |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation recyclability design criteria gate qualified supply and premium-tier pricing access for European label converters, as pharmaceutical and dairy buyers in Germany and the Netherlands now specify adhesives against PPWR test protocols that exclude uncertified competitors from high-margin serialization contracts.
Pricing Analysis
Direct-to-OEM volume discounts dominate contract structures, with three-tier pricing separating serialization-ready film constructions from standard food-grade paper and economy logistics labels. Price differentiation rests on REACH compliance certification and digital printing capability, with German pharmaceutical buyers least sensitive and Italian retail cooperatives most cost-conscious. Pricing pressure stems from petrochemical feedstock volatility in acrylic adhesive polymers, compressing margins where propylene cost pass-through remains incomplete.
Supply Chain Analysis
Siliconized release liner supply rests on Finnish and German specialty paper producers, while face stock films draw from Belgium and the Netherlands. Raw material dependencies include biaxially oriented polypropylene, acrylic emulsion polymers, and thermal transfer coatings. Single-source vulnerability concentrates in tackifier resins subject to ECHA substance evaluations. Distribution runs through converter networks serving Bavarian pharmaceutical corridors and Île-de-France packaging hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through wet-glue-to-pressure-sensitive conversion programs that eliminate drying station capital for food and beverage buyers while commanding premium pricing for serialization-ready film constructions.
For Market Incumbents: Cement backward integration into adhesive polymer production to defend against petrochemical margin compression and ECHA-driven reformulation cycles. Prioritize capacity addition in Lombardy pharmaceutical clusters to capture production migration from higher-cost Northern European sites. Lock in multi-year substrate-adhesive-printing bundles with Swiss and Dutch CPG procurement teams before supplier panel consolidation completes.
For New Entrants and Emerging Players: EU Falsified Medicines Directive serialization requirements in Italy and Spain open a window for digital-ready label investments where incumbent flexographic capacity cannot serve lot sizes below 5,000 units. Target craft beverage segments in UK Midlands and Spanish wine export corridors with laser die-cutting paired with HP Indigo platforms. Lead with same-day variable data turnaround as the go-to-market wedge against established converter networks.
For Investors and Strategic Acquirers: Roll-up economics work for regional digital printing specialists because pharmaceutical serialization mandates and CPG procurement consolidation are simultaneously fragmenting addressable demand and raising minimum capability thresholds. Long-term viability favors converters with integrated adhesive qualification labs and EFSA food-contact certification infrastructure. Watch Italian pharmaceutical manufacturing employment data as the inflection signal for serialization-ready label demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Adhesive Polymer Production | Captures margin pools threatened by ECHA tackifier resin restrictions and propylene volatility. |
| Digital Printing Platform Deployment | Serves sub-5,000 unit pharmaceutical lots that flexographic economics cannot address profitably. |
| Serialization-Ready Film Certification Investment | Qualifies supply relationships with German and French pharmaceutical manufacturers under EU Falsified Medicines Directive. |
| Regional Converter Acquisition in Southern Europe | Positions for Lombardy and Emilia-Romagna pharmaceutical production migration from Northern European sites. |
| Removable Adhesive Formulation Development | Meets EU Packaging and Packaging Waste Regulation recyclability criteria for Dutch dairy and German beverage brands. |
Research Methodology
Multiple input streams — converter production data, adhesive formulation disclosures, and pharmaceutical procurement contracts — were reconciled through primary interviews with plant managers at German and Italian label converters, procurement leads at French hypermarket chains, and regulatory affairs directors at Belgian adhesive suppliers, validated against ECHA substance evaluation databases, Cefic chemical trade statistics, and SEC filings from listed materials companies, with bottom-up capacity modeling cross-checked against top-down demand aggregation from end-use segment analysis.
Historical volume trajectories were cross-referenced against panel input from industry participants to construct projections across the analysis window, with segmentation modeling covering substrate type, adhesive chemistry, printing technology, and end-use application, deriving growth rates from pharmaceutical serialization mandate implementation timelines and food and beverage automation investment patterns.
Revisions become necessary when ECHA expands substance restriction lists, EU digital product passport requirements accelerate, or petrochemical feedstock volatility exceeds historical bands. A small set of named triggers — EMA serialization standard updates, Italian pharmaceutical employment shifts, and PPWR enforcement intensity — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Metallic Labels Market
Labels
Industrial Label Printers Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Ripeness Indicator Labels Market
Labels
Shipping Label Market
Labels
Fiber Optic Labels Market
Labels
Repositionable Labels Market
Labels
Holographic Scratch-Off Labels Market
Labels
GCC Labels and Release Liners Market
Labels
Polyester Labels Market
Labels
Retro-Reflective Labels Market
Labels
Oxygen Indicator Labels Market
Labels
GCC Labeling Market
Labels
Pin Feed Labels Market
Labels
Sustainable Labels Market
Labels
Indicative Seals Market