
 BOPP Tobacco Films Market | 2026-2036
BOPP Tobacco Films Market Size, Share, and Industry Trends Forecast 2026-2036
BOPP Tobacco Films Market Intelligence
Asset-light leasing models for biaxial orientation lines are reconfiguring competitive entry barriers in tobacco-grade film supply. Uflex Limited leverages captive resin sourcing and backward integration into polypropylene to sustain margin control across South Asian markets. Cosmo Films anchors its position through specialized coating capabilities that meet tobacco-industry barrier specifications. Innovia Films competes on optical clarity consistency for premium cigarette overwrap segments.
Biaxially oriented polypropylene tobacco films are thermoplastic polymer sheets stretched in machine and transverse directions to achieve controlled thickness, typically 18–25 micrometers, with heat-seal layers for high-speed packaging integrity. These films provide moisture barrier, machinability, and print receptivity for tobacco product overwrap and inner liner applications. Transparent films dominate volume throughput due to standard cigarette packaging economics, while metallized films command premium positioning in moisture-sensitive and counterfeit-deterrent applications. Barrier films are gaining traction in chewing tobacco and snuff formats where extended shelf stability matters. Cast film process technology leads installed capacity, though extrusion coating lines are expanding for multi-layer functional structures.
FDA oversight of tobacco product packaging and modified risk claims in the United States shapes film specification requirements for domestic suppliers. REACH compliance and the EU Packaging and Packaging Waste Directive in Europe enforce recyclability and substance restriction standards that film converters must integrate into formulation design. India's BIS certification for food-contact and packaging materials creates compliance thresholds for imported and domestically produced tobacco films alike. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate recyclability mandates to align capital allocation with regulatory trajectory.
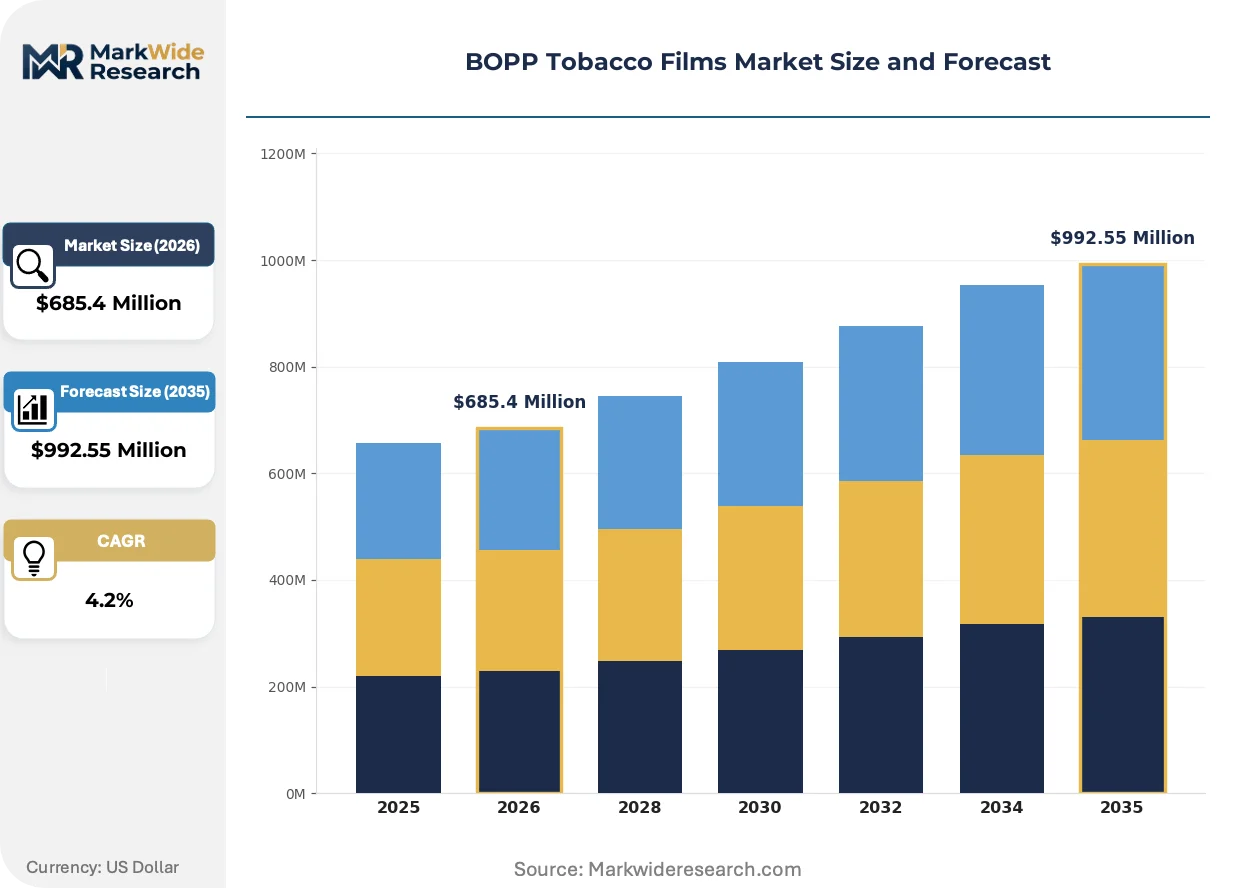
Market Dynamics
Anti-counterfeiting mandates from the European Union are compressing specification cycles for high-barrier metallized films, forcing converters to recalibrate coating investments against shorter compliance deadlines.
Growth Catalysts
- REACH substance restrictions:European recyclability mandates accelerate demand for mono-material BOPP structures that simplify end-of-life processing for cigarette packaging.
- India's export packaging cluster:Domestic tobacco processors in Gujarat and Andhra Pradesh are expanding conversion capacity to serve Middle East and African markets.
- High-speed metallization:Vacuum deposition advances enable sub-micron aluminum layers that satisfy moisture-barrier specifications without laminated complexity.
Market Restraints
- Propylene feedstock volatility:Crude-linked naphtha pricing transmits directly to resin costs, compressing margin predictability for non-integrated converters.
- Equipment oligopoly:Biaxial orientation line supply concentrates among German and Japanese machinery builders, extending delivery timelines beyond 18 months.
- Cellulose-based substitutes:Molded fiber and paper-based overwrap technologies advance in Nordic markets where single-use plastic taxes bite hardest.
Strategic Opportunities
- Chewing tobacco barrier films:Moisture-sensitive oral tobacco formats in the United States create specification openings for co-extruded oxygen-barrier structures.
- BIS certification alignment:India's harmonization of food-contact and packaging standards enables import substitution for previously duty-advantaged Southeast Asian suppliers.
- Asset-light leasing models:Third-party equipment financing lowers capital barriers for regional entrants seeking tobacco-grade film capacity without full ownership risk.
Industry Challenges
- Coating technician scarcity:Solvent-based and aqueous barrier coating expertise concentrates among aging workforces in European and Japanese converter bases.
- Multi-layer certification timelines:FDA tobacco product packaging reviews extend 12-18 months, freezing formulation changes for suppliers serving US manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BOPP Tobacco Films Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $992.55 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transparent Films, Metallized Films, Barrier Films, Coated Films Application: Cigarette Packaging, Chewing Tobacco Packaging, Rolling Tobacco Packaging, Snuff Packaging End User: Tobacco Manufacturers, Retailers, Distributors, Packaging Suppliers Technology: Cast Film Process, Blow Film Process, Extrusion Coating, Lamination |
| Companies Covered | Uflex Limited, Cosmo Films, Innovia Films, Polyplex Corporation, Treofan Group, Taghleef Industries, SRF Limited, SIBUR, Toray Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BOPP Tobacco Films Market Strategic Shifts & Innovations
Material scientists and packaging engineers are converging on functional layering strategies that reconcile barrier performance with mono-material recyclability, reshaping how tobacco films are specified and sourced.
Co-extruded high-barrier structures are hybridizing conventional BOPP substrates with ethylene vinyl alcohol and polyamide interlayers to achieve oxygen transmission rates below 1 cc/m²/day. Premium cigarette manufacturers in Japan and Switzerland are qualifying these structures for extended shelf-life applications. The technology is hybridizing competitive positioning between metallized film specialists and clear barrier converters.
The EU Packaging and Packaging Waste Directive's 2030 recyclability targets are forcing reformulation of heat-seal layers previously reliant on incompatible polyolefin blends. Converters must validate new sealant chemistries through accelerated aging protocols without sacrificing machinability on existing packaging lines. Metallized film segments face the steepest compliance costs due to aluminum recovery complexity.
Tobacco manufacturers are consolidating film supply relationships from multi-vendor portfolios toward single-source technical partnerships. This concentration transfers specification ownership from purchasing departments to R&D and regulatory affairs functions. The shift is most pronounced in Germany and the United Kingdom, where extended producer responsibility frameworks make packaging material choices a board-level compliance risk.
BOPP Tobacco Films Market Segmentation
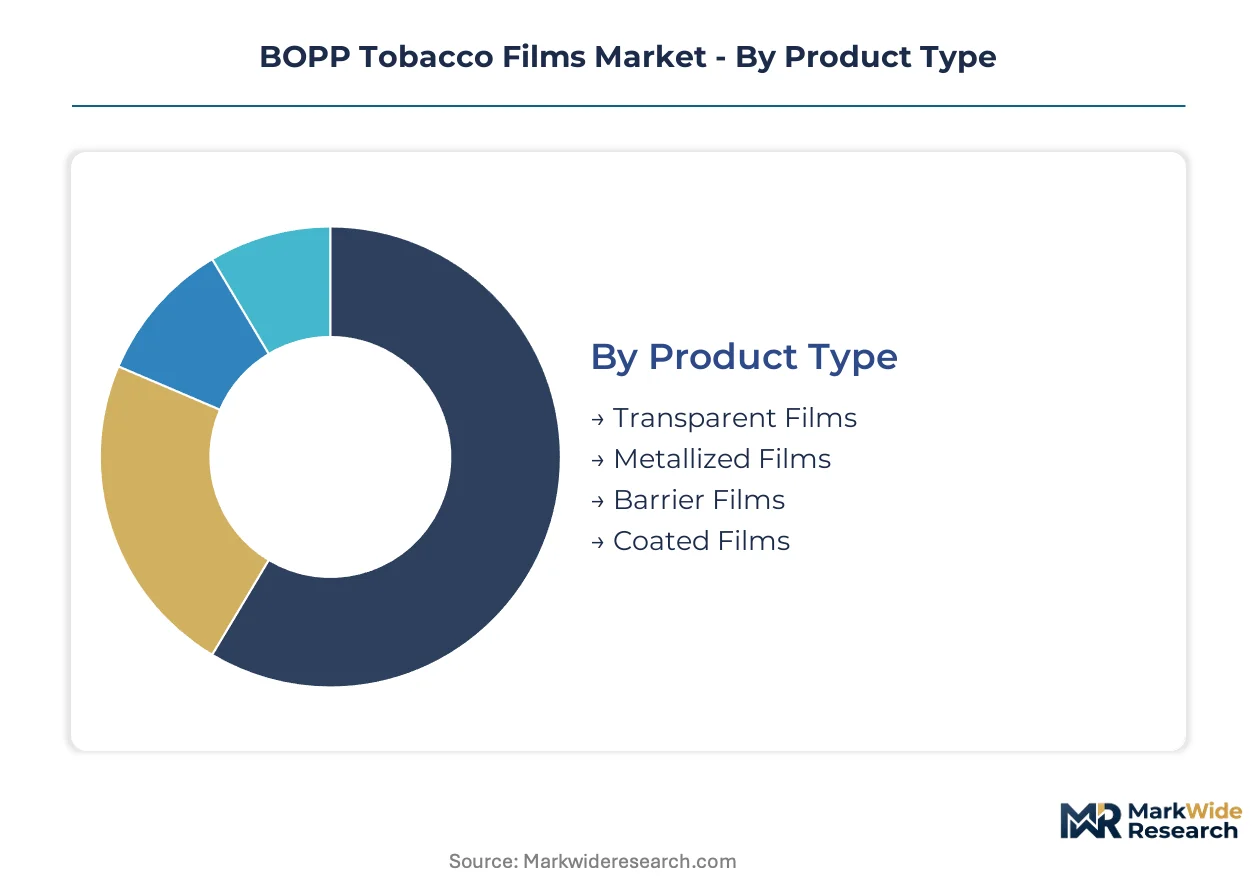
Tobacco film procurement cycles vary dramatically across product grades and end-use specifications. Understanding these velocity differentials helps converters align inventory positions with customer contract structures and regulatory compliance timelines.
Product Type:
Cycle times compress from standard transparent grades to specialized barrier formulations, with metallized and coated variants commanding extended qualification periods due to functional testing requirements.
- Transparent Films:Standard 18–25 micrometer BOPP substrates with heat-seal layers dominate high-speed cigarette overwrap applications. Demand concentrates among Indian export packaging clusters serving Middle East and African markets where cost efficiency governs procurement.
- Metallized Films:Vacuum-deposited aluminum layers achieve sub-micron moisture barriers without laminated complexity. European Union anti-counterfeiting mandates are accelerating specification turnover for these premium grades in deterrence-focused packaging.
- Barrier Films:Co-extruded structures with EVOH or polyamide interlayers target oxygen-sensitive oral tobacco formats. These films are gaining specification share in United States chewing tobacco segments where extended shelf stability drives material selection.
- Coated Films:Solvent-based and aqueous barrier coatings applied to BOPP substrates enable customized functional performance. REACH substance restrictions are forcing reformulation of sealant chemistries to meet 2030 recyclability targets.
Transparent films anchor the volume base while barrier films gain share at the steepest rate.
Application:
Cost tiers separate commodity cigarette overwrap from premium oral tobacco protection, with specification complexity and margin structure diverging sharply across these use cases.
- Cigarette Packaging:High-speed machinability and print receptivity define requirements for standard overwrap and inner liner applications. India's domestic processors in Gujarat and Andhra Pradesh are expanding conversion capacity to capture export demand from this segment.
- Chewing Tobacco Packaging:Moisture and oxygen barrier specifications exceed cigarette-grade requirements. FDA tobacco product packaging reviews extending 12–18 months freeze formulation changes for suppliers serving United States manufacturers in this category.
- Rolling Tobacco Packaging:Flexible pouch formats demand puncture resistance and resealability alongside barrier performance. Nordic markets show rising interest in cellulose-based substitutes where single-use plastic taxes apply pressure.
- Snuff Packaging:Extended shelf-life requirements drive adoption of metallized and high-barrier clear films. Japanese and Swiss premium manufacturers are qualifying co-extruded structures with oxygen transmission rates below 1 cc/m²/day.
Cigarette packaging commands the largest revenue pool while chewing tobacco applications expand most quickly.
End User:
Customer type determines contract structure, with integrated tobacco manufacturers driving standardization while packaging suppliers and distributors fragment demand across smaller batch sizes.
- Tobacco Manufacturers:Direct procurement from film converters enables specification ownership by R&D and regulatory affairs functions. Consolidation toward single-source technical partnerships is pronounced in Germany and the United Kingdom.
- Retailers:Private-label tobacco products create secondary demand for standard transparent grades with shorter lead times and flexible minimum order quantities.
- Distributors:Inventory carrying roles in fragmented regional markets favor commodity grades with predictable turnover and limited technical support requirements.
- Packaging Suppliers:Converter relationships with tobacco manufacturers position these intermediaries as specification influencers. Asset-light leasing models for biaxial orientation lines are lowering entry barriers for regional packaging suppliers.
Tobacco manufacturers dominate volume commitment while packaging suppliers capture the fastest expansion in technical partnership roles.
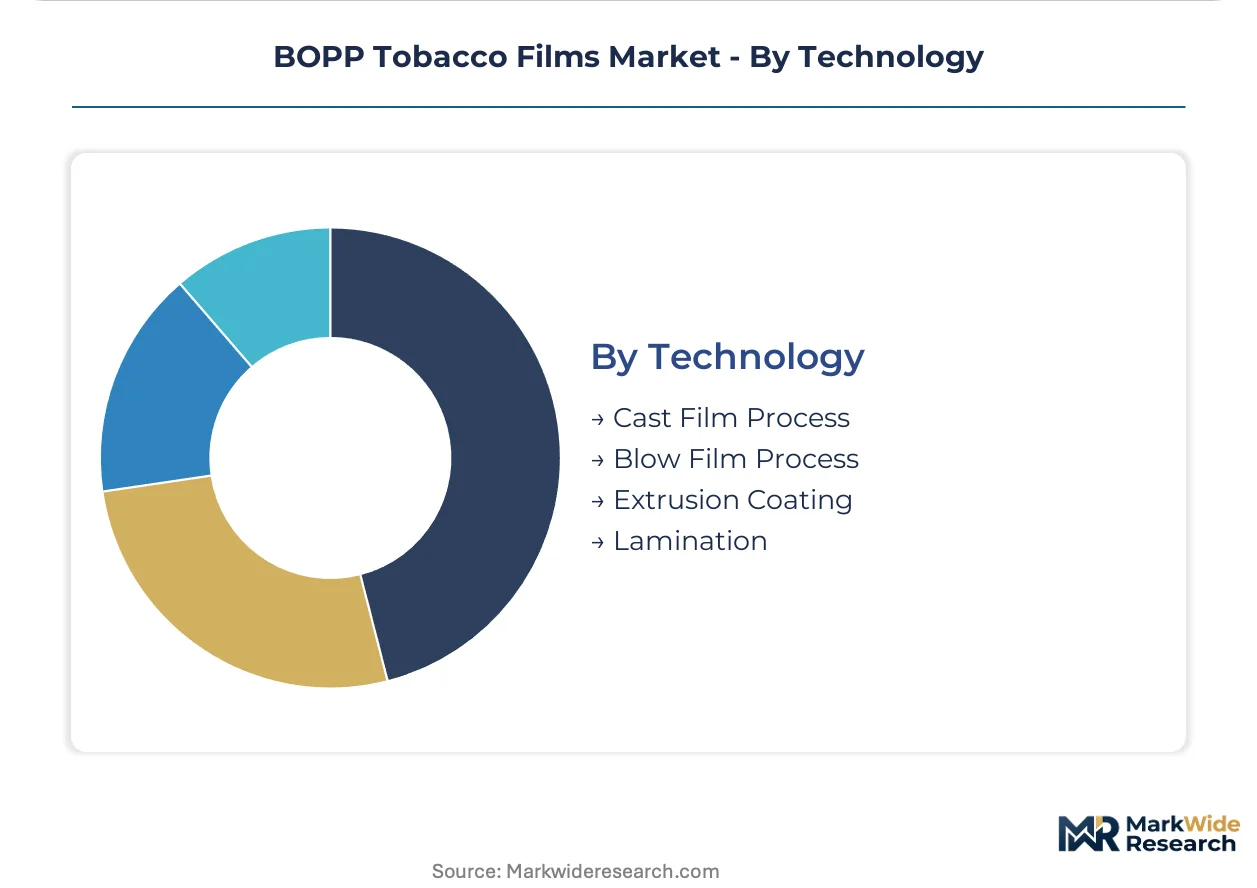
Technology:
Volume concentration favors mature cast film infrastructure, though extrusion coating and lamination capabilities are expanding to serve multi-layer functional structures.
- Cast Film Process:Tenter-frame biaxial orientation achieves controlled thickness and mechanical properties for standard tobacco grades. German and Japanese machinery builders concentrate supply, extending delivery timelines beyond 18 months for new capacity.
- Blow Film Process:Tubular orientation offers capital efficiency for smaller-scale production, though optical clarity and gauge control lag tenter-frame output.
- Extrusion Coating:Inline functional layer deposition enables multi-barrier structures without separate lamination steps. Coating technician scarcity concentrates expertise among aging workforces in European and Japanese converter bases.
- Lamination:Adhesive and thermal bonding of dissimilar substrates persists for specialized applications, though mono-material BOPP structures are displacing complex laminates under EU recyclability mandates.
Cast film process anchors installed capacity while extrusion coating climbs the fastest as converters invest in functional layering capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Anti-counterfeiting mandates and extended producer responsibility frameworks are redrawing procurement geography for tobacco-grade BOPP films. REACH substance restrictions and FDA packaging oversight create divergent compliance baselines across major demand centers.
India
Domestic tobacco processors in Gujarat and Andhra Pradesh are scaling conversion capacity to capture Middle East and African export demand. BIS certification harmonization for food-contact and packaging materials tightens import substitution thresholds for Southeast Asian competitors. Ahmedabad and Hyderabad clusters anchor film extrusion investment from both integrated resin producers and packaging suppliers.
Germany
EU Packaging and Packaging Waste Directive recyclability targets are forcing heat-seal layer reformulation among converters serving premium cigarette manufacturers. ECHA substance restrictions accelerate specification turnover for metallized barrier grades. The Rhine-Ruhr industrial corridor concentrates coating expertise and biaxial orientation line maintenance capabilities.
United States
FDA tobacco product packaging reviews extending 12–18 months freeze formulation changes for suppliers serving chewing tobacco and moist snuff segments. Moisture-sensitive oral tobacco formats in the Southeast drive specification openings for co-extruded oxygen-barrier structures. North Carolina and Virginia processing clusters dominate domestic tobacco film consumption.
Japan
Premium cigarette manufacturers are qualifying co-extruded structures with oxygen transmission rates below 1 cc/m²/day for extended shelf-life applications. METI industrial standards shape barrier film certification protocols for export-oriented packaging. The Chubu region around Nagoya anchors optical clarity consistency requirements for overwrap segments.
Switzerland
Premium positioning in cigarette overwrap segments demands metallized film grades with sub-micron aluminum deposition precision. Swissmedic packaging material guidelines intersect with EU anti-counterfeiting traceability requirements. The Basel-Zurich corridor hosts technical partnership consolidation between film converters and luxury tobacco brands.
BOPP Tobacco Films Market Key Industry Players
On the supply side, the industry is consolidating around three structural tiers: integrated resin-to-film producers, specialized coating converters, and regional packaging suppliers leveraging asset-light equipment leasing. Strategic archetypes include backward-integrated polypropylene specialists, barrier-coating technology licensors, and export-oriented Indian converters. Dominant competitive moves center on captive resin sourcing for margin control and multi-layer extrusion coating capacity expansion.
Among South Asian integrated producers, Uflex Limited anchors the backward-integrated archetype through captive polypropylene supply, while Cosmo Films occupies the specialized coating tier with barrier specification capabilities. Innovia Films exemplifies the optical clarity premium segment. These three entities represent distinct competitive positioning vectors—resin integration, functional layering, and premium overwrap consistency—rather than overlapping market coverage.
| Leading Market Players |
|---|
| Uflex Limited |
| Cosmo Films |
| Innovia Films |
| Polyplex Corporation |
| Treofan Group |
| Taghleef Industries |
| SRF Limited |
| SIBUR |
| Toray Industries |
| Others |
Cost & Logistics Intelligence
German and Japanese machinery builders concentrate biaxial orientation line supply, anchoring margin pools downstream with film converters who face 18-month delivery timelines and limited bargaining leverage on capital equipment.
Pricing Analysis
Certification level creates the primary spread across BOPP tobacco film tiers, with REACH-compliant and FDA-reviewed grades commanding substantial premiums over standard transparent substrates. Three-tier pricing structure separates metallized barrier films from clear high-performance grades from commodity overwrap specifications. Pricing pressure stems from propylene feedstock volatility transmitted through crude-linked naphtha costs, compressing margin predictability for non-integrated converters. Export-oriented packaging suppliers in India exhibit highest price sensitivity due to volume-driven procurement, while premium cigarette manufacturers in Switzerland and Japan show least sensitivity given specification rigidity.
Supply Chain Analysis
Export-control restrictions on advanced coating and metallization equipment limit technology flows from German and Japanese suppliers to emerging converters, constraining capacity expansion outside established bases. Manufacturing concentrates in India, Germany, and Japan, with resin supply anchored in Saudi Arabia, South Korea, and domestic Indian polypropylene production. Raw material dependencies center on propylene monomer, aluminum deposition targets, and specialized barrier coating chemistries. Single-source vulnerability runs through the German-Japanese equipment oligopoly. Distribution feeds through converter-direct relationships with tobacco manufacturers and packaging supplier intermediaries serving fragmented regional markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU anti-counterfeiting mandates and mono-material recyclability targets are disrupting specification cycles, creating acceleration windows for converters who can bridge barrier performance with simplified end-of-life processing.
For Market Incumbents: Entrench position through captive resin sourcing and backward integration into polypropylene production to insulate margins from feedstock volatility. Expand extrusion coating capacity in South Asian clusters to capture export demand from Middle East and African markets. Prioritize certification investment for REACH-compliant heat-seal layer reformulations ahead of 2030 deadlines.
For New Entrants and Emerging Players: Establish a beachhead in chewing tobacco barrier films for United States manufacturers, where FDA review timelines freeze incumbent formulation flexibility. Target asset-light leasing models for biaxial orientation lines to enter without full capital ownership risk. Lead with co-extruded oxygen-barrier specifications that hybridize metallized performance with mono-material recyclability.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed European coating specialists facing technician succession risks and REACH compliance cost burdens. Long-term viability hinges on positioning for mono-material BOPP structures that simplify recycling infrastructure. Watch for BIS certification alignment in India as signal for import substitution acceleration against Southeast Asian competitors.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polypropylene | Captive resin supply insulates Uflex and integrated players from naphtha-linked margin compression. |
| Extrusion Coating Capacity Expansion | Inline functional layering enables Cosmo Films to meet tobacco-industry barrier specifications without lamination complexity. |
| REACH-Compliant Heat-Seal Reformulation | New sealant chemistries validate through accelerated aging protocols for EU Packaging and Packaging Waste Directive alignment. |
| Asset-Light Equipment Leasing | Third-party financing lowers entry barriers for regional Indian packaging suppliers serving Gujarat and Andhra Pradesh clusters. |
| Co-Extruded Barrier Qualification | EVOH-polyamide interlayer structures below 1 cc/m²/day oxygen transmission capture Japanese and Swiss premium cigarette specifications. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with film converter plant managers, tobacco manufacturer procurement directors, packaging supplier technical leads, and regulatory affairs specialists at BIS and REACH compliance consultancies. Secondary validation drew from customs trade data, SEC filings of listed packaging material producers, ECHA substance restriction updates, and FDA tobacco product packaging submission databases. Bottom-up capacity assessments triangulated against top-down demand modeling across cigarette, chewing tobacco, and snuff application segments.
Calibration anchored volume and value outputs to installed biaxial orientation line capacity, resin price transmission elasticity, and qualification timeline assumptions across the projection horizon. Segmentation dimensions spanned product type, application format, end-user contract structure, and process technology. CAGRs derived from slope-intercept modeling of historical conversion capacity expansion correlated with tobacco shipment trajectories in key demand centers. Industry-specific inputs included metallization equipment utilization rates and barrier coating technician pipeline constraints.
Sensitivities concentrate around propylene feedstock volatility, EU recyclability mandate acceleration, and FDA review timeline extensions for oral tobacco packaging. Forecasts reflect documented assumptions on specification cycle compression and import substitution thresholds. Material shifts in REACH substance restrictions or BIS certification harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
Sugarcane Based PET Bottles Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
Plastic Ampoules Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Cast Films Market
Plastic Packaging
Advanced-Recycled Polyethylene for E-Commerce Packaging Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
Rewritable PVC Cards Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Plastic Lab Totes Market