

Holographic Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Holographic Labels Market Insights
Aftermarket authentication services is rewriting profit distribution across the holographic label value chain. Avery Dennison leverages its materials science platform to anchor premium security substrate supply. CCL Industries sustains dominant position through backward integration into metallized film production. KURZ Group differentiates via specialized hot-stamping equipment paired with consumable holographic foils.
Holographic labels are optically variable security devices manufactured through embossing or e-beam lithography of micro-structured interference patterns onto metallized films, typically 12-50 micron polyester or polypropylene substrates, designed to provide visual authentication and tamper evidence. The pharmaceutical packaging application commands premium pricing due to serialization mandates and track-and-trace requirements across regulated supply chains. Digital printing technology is capturing fastest growth as brands demand shorter runs with variable data integration for regionalized anti-counterfeiting campaigns. Polypropylene label material dominates volume production for its moisture resistance and conformability to curved container surfaces.
FDA drug supply chain security requirements and EU MDR traceability provisions are elevating holographic label specifications for pharmaceutical and medical device packaging. REACH restrictions on chromium-based holographic coatings are forcing European converters toward vacuum-deposited aluminum and diffractive optically variable ink alternatives. ISO 12931 performance criteria for authentication solutions provide the testing framework that procurement teams now embed in supplier qualification. Stakeholders must decide whether to build in-house holographic mastering capabilities or secure long-term supply agreements with specialized converters as authentication complexity escalates.
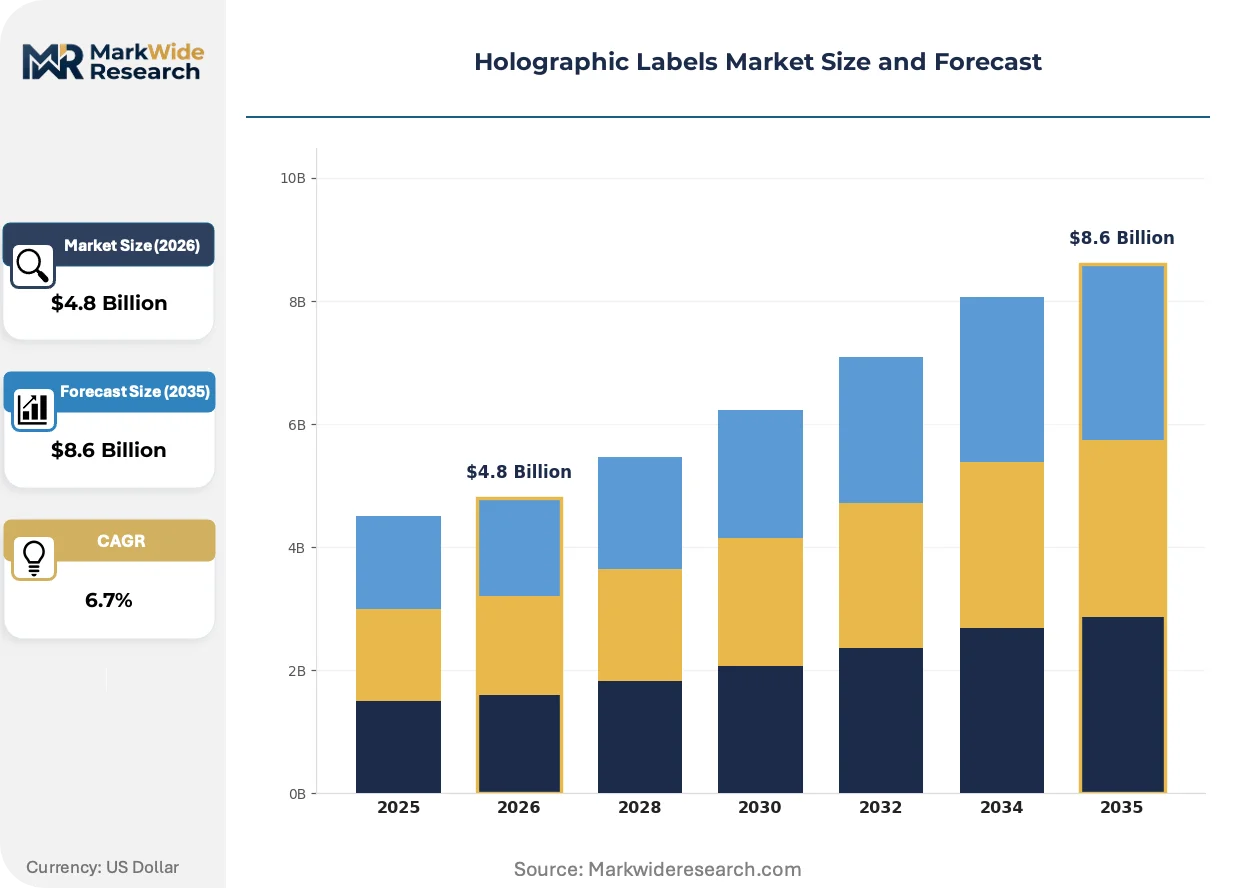
Market Dynamics
Pharmaceutical serialization mandates and anti-counterfeiting enforcement are compressing specification cycles across the holographic label supply chain. Mastering houses and converters must now align holographic feature complexity with track-and-trace data integration timelines.
Growth Catalysts
- EU MDR traceability provisions:Medical device packaging in Europe now requires visual authentication layers that holographic labels provide, pulling demand from sterile barrier systems into security substrates.
- India PLI scheme for packaging:Domestic brand owners are qualifying local holographic converters for export-bound pharmaceutical shipments, building captive authentication capacity.
- E-beam lithography mastering:Resolution improvements in direct-write electron beam systems are enabling nano-scale diffractive features that embossing cannot replicate, opening premium security tiers.
Market Restraints
- Aluminum vacuum deposition capacity:European metallized film supply concentrates among three integrated producers, creating input bottlenecks when REACH chromium restrictions redirect demand.
- Polyester substrate cost volatility:Biaxially oriented PET resin tracks petrochemical feedstock swings, compressing converter margins on fixed-price pharmaceutical contracts.
- Holographic inkjet substitution:Diffractive optically variable inkjet systems from security printers are capturing low-complexity authentication jobs without metallized film.
Strategic Opportunities
- Brazil ANVISA pharmaceutical track-and-trace:Serialization mandates for prescription medicines are creating first-mover advantages for holographic label converters with Portuguese-language technical support.
- Digital printing-holographic foil convergence:Hybrid presses integrating hot-stamping units with inkjet personalization are enabling variable holographic features at short-run economics.
- Smart packaging integration:NFC chip embedding within holographic label constructions is opening authentication-plus-engagement propositions for luxury cosmetics.
Industry Challenges
- Mastering engineer scarcity:E-beam lithography operation requires specialized optics and nanofabrication training that university programs have not scaled to industry demand.
- ISO 12931 certification timelines:Authentication performance testing against the standard's resistance criteria extends supplier qualification cycles by 8-14 months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Holographic Labels Market Trends and Innovations
Authentication technology is bifurcating between high-volume commodity holography and precision-engineered optical security. This divergence is reshaping capital allocation across mastering houses, metallized film producers, and label converters.
Nano-scale diffractive structures manufactured through direct-write e-beam lithography are digitizing the mastering workflow. Pharmaceutical packagers in Germany and Switzerland are adopting these digitally originated holograms for serialized anti-counterfeiting campaigns. The technology is digitizing what was previously a mechanical embossing process, compressing design-to-production cycles from weeks to days.
REACH restrictions on hexavalent chromium compounds in holographic coatings are forcing formulation changes across European converters. Vacuum-deposited aluminum layers and silicon oxide barrier coatings are displacing chromed surfaces in pharmaceutical and tobacco applications. French and Italian packaging converters are qualifying these alternative metallization processes under ECHA guidance timelines.
Brand owners are unbundling authentication procurement from primary label supply, creating direct relationships with holographic mastering specialists. Pharmaceutical and luxury goods verticals are driving this disintermediation, bypassing generalist converters for security feature specification. The pattern is most pronounced in California and New Jersey, where brand protection teams maintain dedicated vendor qualification programs.
Holographic Labels Market Segmentation
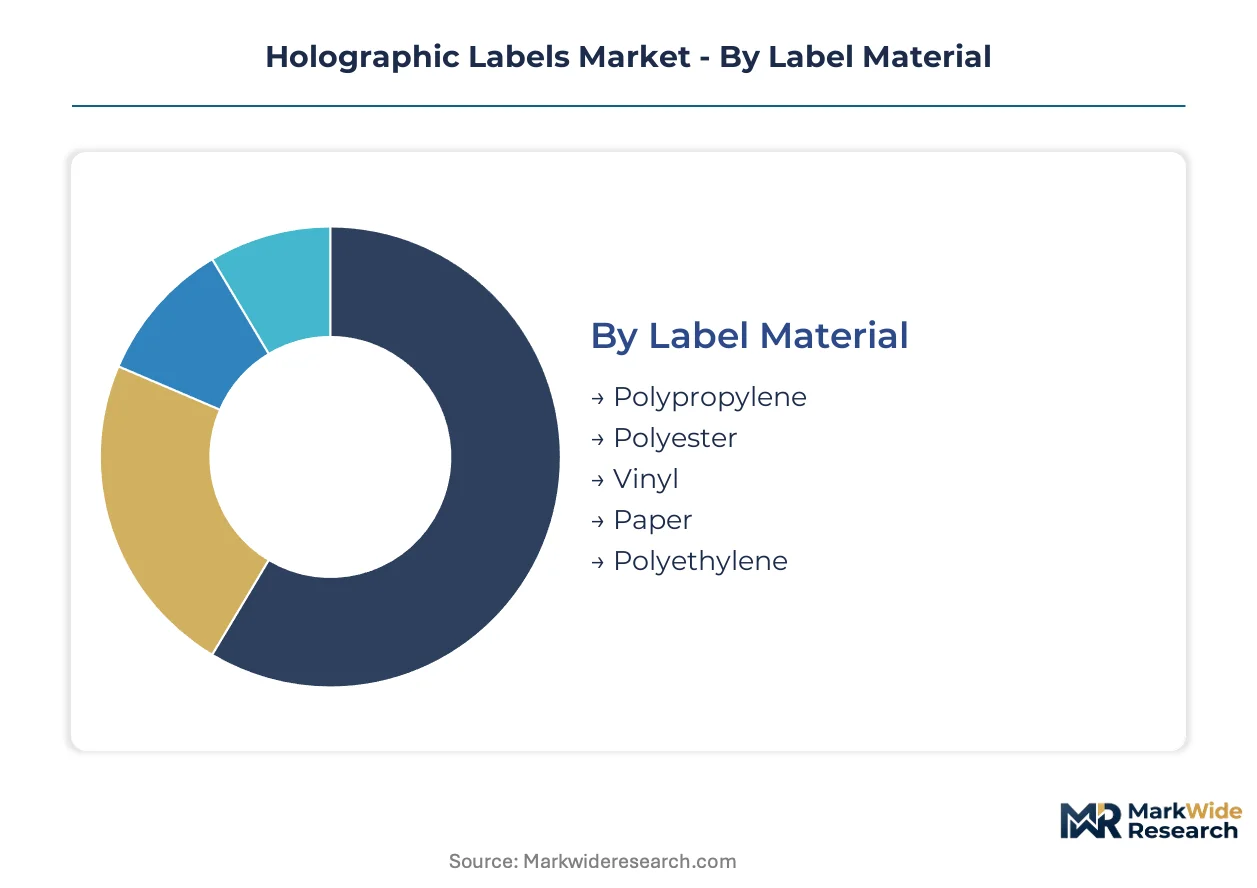
Holographic label segmentation reveals how substrate chemistry, printing precision, and end-use authentication requirements create distinct value tiers. Material selection and mastering complexity determine pricing architecture across pharmaceutical, luxury, and industrial applications.
Label Material:
Cost tier differentiation in holographic substrates separates moisture-resistant commodity films from premium polyester engineered for serialization durability.
- Polypropylene:Biaxially oriented polypropylene films at 20-40 micron thickness provide conformability to curved pharmaceutical vials and moisture barriers for tropical distribution. Demand concentrates in India where CDSCO serialization mandates for export pharmaceuticals drive volume procurement of polypropylene-based security labels.
- Polyester:Metallized polyethylene terephthalate substrates withstand high-temperature sterilization cycles and aggressive chemical exposure in medical device packaging. European converters under ECHA REACH timelines are qualifying vacuum-deposited aluminum polyester alternatives to hexavalent chromium coatings.
- Vinyl:Calendered vinyl films serve outdoor durability requirements in automotive aftermarket authentication with UV-stabilized holographic layers.
- Paper:Metallized paperboard substrates support tobacco tax stamp applications requiring destructible tamper evidence.
- Polyethylene:Low-density polyethylene films enable squeeze tube conformability in personal care packaging with limited holographic feature complexity.
Polyester commands the established base in pharmaceutical and medical device authentication. The steepest expansion runs through polypropylene as India's PLI scheme for packaging accelerates domestic converter qualification.
Printing Technology:
Application requirements for variable data integration and run-length economics determine technology selection across security label production.
- Digital:Inkjet and toner-based systems enable serialization with unique identifiers and regionalized holographic designs at lot sizes below 10,000 units. Pharmaceutical packagers in Germany and Switzerland adopt digital-holographic hybrid presses for track-and-trace campaigns.
- Flexographic:Central impression drum presses deliver metallized film registration accuracy at medium volumes for cosmetics and food branding applications.
- Offset:Lithographic printing provides color consistency and fine-line detail for premium tobacco and spirits authentication labels.
- Gravure:Cylinder-based engraving achieves uniform ink density for high-volume pharmaceutical security printing with holographic foil integration.
- Letterpress:Relief printing maintains tactile impression depth for braille-integrated pharmaceutical labels in European accessibility-compliant packaging.
Gravure retains volume leadership in high-run pharmaceutical security printing. Digital systems are gaining share fastest where serialization mandates demand variable holographic data.
Application:
End-use authentication intensity creates divergent specification requirements from sterile barrier systems to decorative luxury surfaces.
- Pharmaceutical Packaging:Unit-dose blister foils and vial labels combine holographic visual authentication with 2D data matrix serialization under FDA Drug Supply Chain Security Act and EU MDR traceability provisions.
- Cosmetics Decoration:Premium fragrance and skincare packaging employs multi-channel holographic foils for shelf differentiation and gray-market diversion control.
- Electronics Security:Smartphone and laptop component labels use nano-scale diffractive features to authenticate batteries, chargers, and replacement parts against counterfeiting.
- Food & Beverages Branding:High-value spirits and specialty foods deploy holographic tax stamps and brand protection labels with tamper-evident destructible substrates.
- Personal Care Authentication:Hair care and oral care products integrate holographic seals for e-commerce channel integrity verification.
Pharmaceutical packaging anchors revenue concentration due to regulatory compliance premiums. Cosmetics decoration is expanding most quickly as luxury brands unbundle authentication procurement from primary label supply.
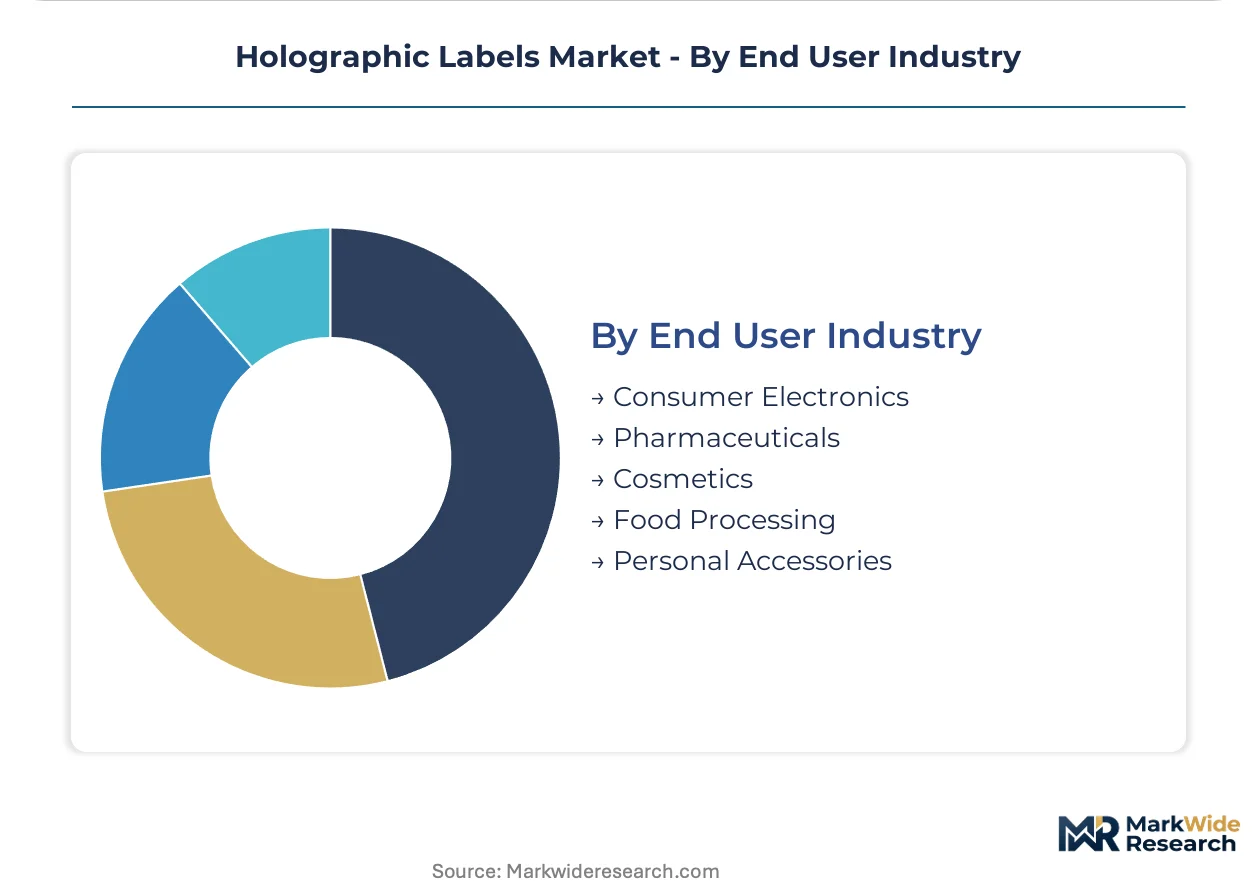
End User Industry:
Customer type determines security feature complexity, certification requirements, and supplier qualification timelines across holographic label procurement.
- Pharmaceuticals:Serialization mandates from FDA, EMA, and national regulators in Brazil and India require ISO 12931-certified authentication performance with 8-14 month supplier qualification cycles.
- Consumer Electronics:Brand protection teams at device manufacturers specify nano-scale diffractive structures for component authentication against aftermarket counterfeiting.
- Cosmetics:Luxury houses in France and Italy maintain direct relationships with holographic mastering specialists for limited-edition packaging security.
- Food Processing:Beverage and spirits producers deploy holographic tax stamps under national excise enforcement programs.
- Personal Accessories:Watch and leather goods brands integrate NFC-embedded holographic labels for authentication-plus-consumer engagement.
Pharmaceuticals dominates procurement value through compliance-driven specification premiums. Consumer electronics is climbing the fastest as supply chain security investments expand beyond devices to component ecosystems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian pharmaceutical exporters exhibit the highest price elasticity as domestic converters compete aggressively for CDSCO-mandated serialization contracts. German medical device manufacturers absorb premium pricing for REACH-compliant vacuum-deposited aluminum substrates without volume reduction.
United States
FDA Drug Supply Chain Security Act enforcement tightens authentication specifications for unit-dose packaging. New Jersey and California brand protection teams maintain dedicated holographic mastering vendor qualification programs. Serialization integrators in the Northeast corridor embed ISO 12931 performance testing into procurement workflows.
Germany
ECHA REACH timelines force rapid qualification of chromium-free metallization processes for pharmaceutical export packaging. Bavarian medical device clusters adopt e-beam lithography-originated holograms for serialized anti-counterfeiting campaigns. Stuttgart-area converters invest in vacuum deposition capacity to bypass aluminum supply bottlenecks.
India
PLI scheme incentives for packaging attract domestic holographic converter capacity expansion for export-bound pharmaceuticals. CDSCO serialization mandates for active pharmaceutical ingredients pull demand toward moisture-resistant polypropylene substrates. Gujarat and Maharashtra industrial corridors concentrate new metallized film production lines.
Switzerland
Swissmedic traceability provisions elevate holographic label specifications for high-value biologics packaging. Basel-area pharmaceutical headquarters source nano-scale diffractive features directly from specialized mastering houses. Zürich converters qualify hybrid digital-holographic presses for variable data integration at short runs.
Brazil
ANVISA pharmaceutical track-and-trace mandates create first-mover advantages for converters with Portuguese-language technical support. São Paulo packaging clusters qualify holographic tax stamp suppliers under national excise enforcement timelines. Domestic brand owners invest in authentication capacity for regionalized anti-counterfeiting campaigns.
Holographic Labels Market Competitive Landscape
Capability concentration sits with specialized mastering houses possessing e-beam lithography assets; scale advantage sits with integrated converters controlling metallized film supply. The vendor base stratifies across three tiers: premium security substrate specialists, mid-volume hybrid producers, and commodity holographic converters. Dominant competitive moves include backward integration into metallized film production and strategic partnerships for digital printing-holographic foil convergence.
Among North American materials science platforms, Avery Dennison anchors premium security substrate supply through its integrated film and adhesive capabilities. CCL Industries exemplifies the vertically integrated archetype through captive metallized film production. KURZ Group occupies a specialized position pairing hot-stamping equipment with consumable holographic foils for precision security applications.
| Leading Market Players |
|---|
| Avery Dennison |
| CCL Industries |
| 3M |
| UFlex |
| KURZ Group |
| Holostik |
| UPM |
| K Laser Technology |
| De La Rue |
| Others |
Pricing and Supply Chain Analysis
European metallized film production concentrates among three integrated suppliers, anchoring margin capture upstream while pharmaceutical converters absorb specification premiums downstream. REACH-driven chromium substitution redirects demand toward vacuum-deposited aluminum capacity, tightening input availability for mid-tier converters.
Pricing Analysis
Aftermarket authentication services now drive lifetime value beyond substrate sales, with serialization integrators bundling track-and-trace software into multi-year contracts. Three-tier pricing separates pharma-grade certified substrates from standard industrial holography and commodity decorative films. Cost compression in polypropylene label grades is intensifying as Indian domestic converters compete for CDSCO-mandated export contracts. Pharmaceutical packagers show lowest price sensitivity due to compliance-driven procurement, while cosmetics brands negotiate aggressively on decorative runs.
Supply Chain Analysis
Contract manufacturing for holographic mastering concentrates in Germany, Switzerland, and India, with e-beam lithography capacity held by specialized optical security houses. Raw material dependencies center on biaxially oriented polyester resin, vacuum-deposition aluminum feedstock, and diffractive optically variable inks. Single-source vulnerability runs through European metallized film supply as REACH restrictions consolidate demand among qualified producers. Distribution runs through converter networks that qualify directly with pharmaceutical brand protection teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-beam lithography operation demands specialized nanofabrication training that university programs have not scaled to industry need, creating persistent capability gaps across mastering houses and pharmaceutical authentication procurement.
For Market Incumbents: Insulate metallized film supply positions through captive vacuum-deposition capacity or long-term offtake agreements with European producers. Deepen ISO 12931 certification pipelines to extend supplier qualification timelines that lock out emerging competitors. Prioritize hybrid digital-holographic press installations to capture serialization-driven variable data demand.
For New Entrants and Emerging Players: Build out Portuguese-language technical support capabilities to capture ANVISA-mandated pharmaceutical track-and-trace demand in Brazil. Target cosmetics decoration segments where luxury houses unbundle authentication procurement from primary label supply. Lead with NFC-embedded smart packaging propositions for personal accessories brands seeking authentication-plus-consumer engagement.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed holographic converter platforms lacking upstream metallized film control. Five-to-ten year viability hinges on backward integration completion and digital printing convergence execution. Monitor CDSCO serialization mandate enforcement timelines in India as volume inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| E-beam Lithography Mastering Capacity Expansion | Enables nano-scale diffractive features that pharmaceutical packagers in Germany and Switzerland now specify for serialized campaigns. |
| Vacuum-Deposited Aluminum Qualification | Positions converters to supply REACH-compliant substrates as ECHA chromium restrictions eliminate legacy coating processes. |
| Hybrid Digital-Holographic Press Deployment | Captures variable data integration demand from pharmaceutical serialization mandates at short-run economics. |
| NFC Chip Embedding Integration | Opens authentication-plus-engagement propositions for luxury cosmetics and personal accessories brands. |
| Portuguese-Language Technical Support Buildout | Creates first-mover positioning for ANVISA pharmaceutical track-and-trace mandates across Brazilian packaging clusters. |
Research Methodology
A standing panel of holographic mastering engineers, pharmaceutical packaging procurement directors, metallized film plant managers, and brand protection specialists provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from ECHA regulatory filings, CDSCO serialization guidance documents, FDA Drug Supply Chain Security Act enforcement records, and ISO 12931 certification databases. Bottom-up volume modeling across substrate grades and top-down value triangulation against pharmaceutical packaging expenditure patterns anchored the analytical framework.
Scenario bracketing around REACH implementation timelines, PLI scheme incentive disbursement, and e-beam lithography adoption curves shaped the projection methodology. Segmentation dimensions included label material chemistry, printing technology precision tier, application authentication intensity, and end-user industry regulatory exposure. CAGRs derived from fitted growth curves against historical pharmaceutical packaging security spending patterns, with e-beam mastering capacity expansion and digital printing penetration as key industry-specific forecast inputs across the modeling period.
Stress conditions across aluminum vacuum-deposition capacity constraints, polyester resin price volatility, and holographic inkjet substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement intensity and technology adoption timelines. Quarterly review of CDSCO serialization mandate rollout pace and ECHA chromium restriction qualification progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.