
 Pressure Sensitive Tapes and Labels Market | 2026-2036
Pressure Sensitive Tapes and Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Sensitive Tapes and Labels Market Analysis
The EU Green Deal is realigning substrate specifications across the European adhesive materials sector, compelling converters to certify recyclability and reduce solvent-based chemistries. 3M Company leverages its polymer science infrastructure to develop lower-VOC adhesive platforms for regulated markets. Tesa SE anchors its European manufacturing base with ISO-certified cleanroom production for electronics-grade tapes. Avery Dennison Corporation competes through closed-loop label programs that align with retailer sustainability mandates.
Pressure sensitive tapes and labels are self-adhesive products constructed from facestock, pressure sensitive adhesive, and release liner, manufactured through slot-die coating or solventless extrusion processes to achieve defined peel adhesion and shear resistance values for bonding, sealing, identification, or insulation functions. The end user segmentation shows packaging applications dominating volume due to e-commerce logistics expansion, while electronics bonding tapes command premium margins driven by miniaturization and thermal management requirements. Material segmentation reveals polyethylene substrates sustaining cost-sensitive commodity demand, whereas foam tapes in automotive gasketing applications represent the fastest-growing value pool as electric vehicle platforms multiply.
The EPA regulates volatile organic compound emissions from adhesive coating operations in the United States, while REACH governs chemical substance registration and restriction across European supply chains, and China's MEE enforces air quality standards that affect solvent-based tape manufacturing in the Yangtze River Delta cluster. These frameworks collectively elevate compliance costs for imported products while creating certification barriers that favor established regional producers. Stakeholders must monitor evolving extended producer responsibility schemes and substrate recyclability thresholds to anticipate sourcing and formulation requirements.
Market Dynamics
E-commerce fulfillment automation is compressing label application cycles while EU Green Deal mandates force substrate reformulation across European converter networks. This dual pressure is restructuring procurement relationships between brand owners and adhesive material suppliers.
Growth Catalysts
- Automated Distribution Centers:E-commerce logistics operators deploy high-speed print-and-apply systems that consume thermal transfer and direct thermal labels at throughput rates exceeding manual operations. Robotic sortation infrastructure in China and the United States sustains volume pull for synthetic facestocks.
- REACH Chemical Registration:European adhesive formulators accelerate solventless UV-curable and hot-melt platform development to preempt substance restriction listings. Clean chemistry certification opens procurement channels with multinational consumer packaged goods brands.
- Electric Vehicle Battery Assembly:Foam bonding tapes with thermal conductivity and dielectric properties penetrate battery pack manufacturing for cell-to-cell attachment and module encapsulation. Automotive OEMs specify pressure sensitive solutions to reduce mechanical fastener count.
Market Restraints
- Petrochemical Feedstock Volatility:Acrylic and rubber-based adhesive polymers track crude oil and natural gas derivative pricing. Asian converters face margin compression when propylene and butadiene spot markets spike.
- Silicone Release Liner Concentration:Five specialized paper and film suppliers control fluorosilicone and platinum-catalyzed release coating capacity. Any disruption at German or Japanese liner producers propagates through global label laminate supply chains.
- Mechanical Fastener Substitution:Snap-fit plastic clips and ultrasonic welding displace double-sided foam tapes in automotive interior assembly. Appliance manufacturers revert to screws and rivets where peel strength requirements exceed tape performance envelopes.
Strategic Opportunities
- India Packaging Modernization:Domestic food and pharmaceutical labeling lags automated application penetration rates seen in China. Converter investment in Mumbai and Delhi NCR production lines addresses traceability mandates from the country's national food regulator.
- Bio-Based Adhesive Platforms:Starch-derived and lignin-based tackifiers advance toward commercial scale as the EU Green Deal tightens carbon intensity thresholds for public procurement. Certification under ISO 14021 environmental labeling protocols differentiates premium substrate offerings.
- RFID-Enabled Smart Labels:UHF inlay integration with pressure sensitive construction converges inventory visibility and adhesive identification functions. Apparel retailers deploy item-level tagging for omnichannel fulfillment accuracy.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in UV oligomer selection and tackifier compatibility commands premium compensation. European converters compete with pharmaceutical and coatings sectors for polymer science graduates.
- Recyclability Certification Timelines:APR and EPBP testing protocols for adhesive label removal in PET and HDPE recycling streams extend 12-18 months. Brand owner sustainability commitments outpace validated substrate availability.
- Legacy Coating Line Retrofit Costs:Solvent-based adhesive operations require thermal oxidizer installation or conversion to slot-die hot-melt systems to meet MEE air quality enforcement in the Yangtze River Delta cluster.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Sensitive Tapes and Labels Market |
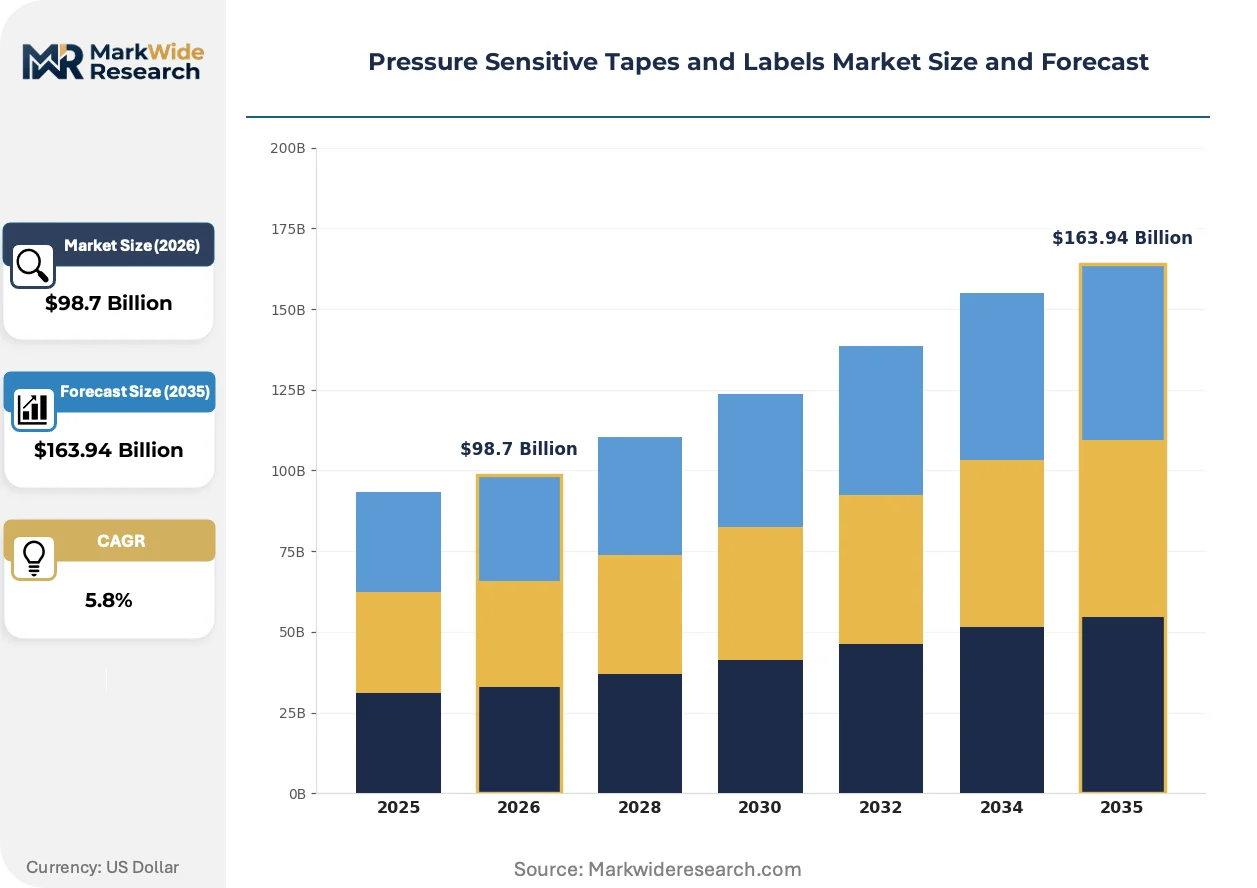
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $163.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Double-Sided Tapes, Masking Tapes, Electrical Tapes, Label Tapes Material: Polyethylene, Vinyl, Paper, Foam End User: Packaging, Automotive, Electronics, Construction Application: Labeling, Bonding, Sealing, Insulation |
| Companies Covered | 3M Company, Avery Dennison Corporation, Tesa SE, Nitto Denko Corporation, Berry Global Group, Inc., Intertape Polymer Group, Lintec Corporation, Henkel AG & Co. KGaA, Lohmann GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Sensitive Tapes and Labels Market Emerging Trajectories
Solventless adhesive coating platforms are displacing conventional solvent-based processes as environmental enforcement tightens across manufacturing clusters. Three convergent developments are restructuring competitive capabilities.
Hot-melt reactive polyurethane adhesive technology is rewriting performance boundaries for structural bonding applications. Automotive and electronics assemblers specify these systems for load-bearing joints previously reserved for mechanical fasteners. The technology compresses cure cycle variability and expands operating temperature envelopes.
REACH substance restriction candidate list expansion is forcing systematic adhesive ingredient reassessment. Formulators purge bisphenol A derivatives and certain phthalate plasticizers ahead of sunset date enforcement. Electronics-grade tape producers in Germany and France accelerate clean chemistry qualification to maintain CE marking compliance.
Brand owner sustainability scorecards now weight supplier carbon disclosure intensity in procurement decisions. Major European retailers require ISO 14064-verified greenhouse gas inventories from label converters. Tier-one packaging buyers consolidate vendor relationships around closed-loop liner recycling program participation.
Pressure Sensitive Tapes and Labels Market Segmentation
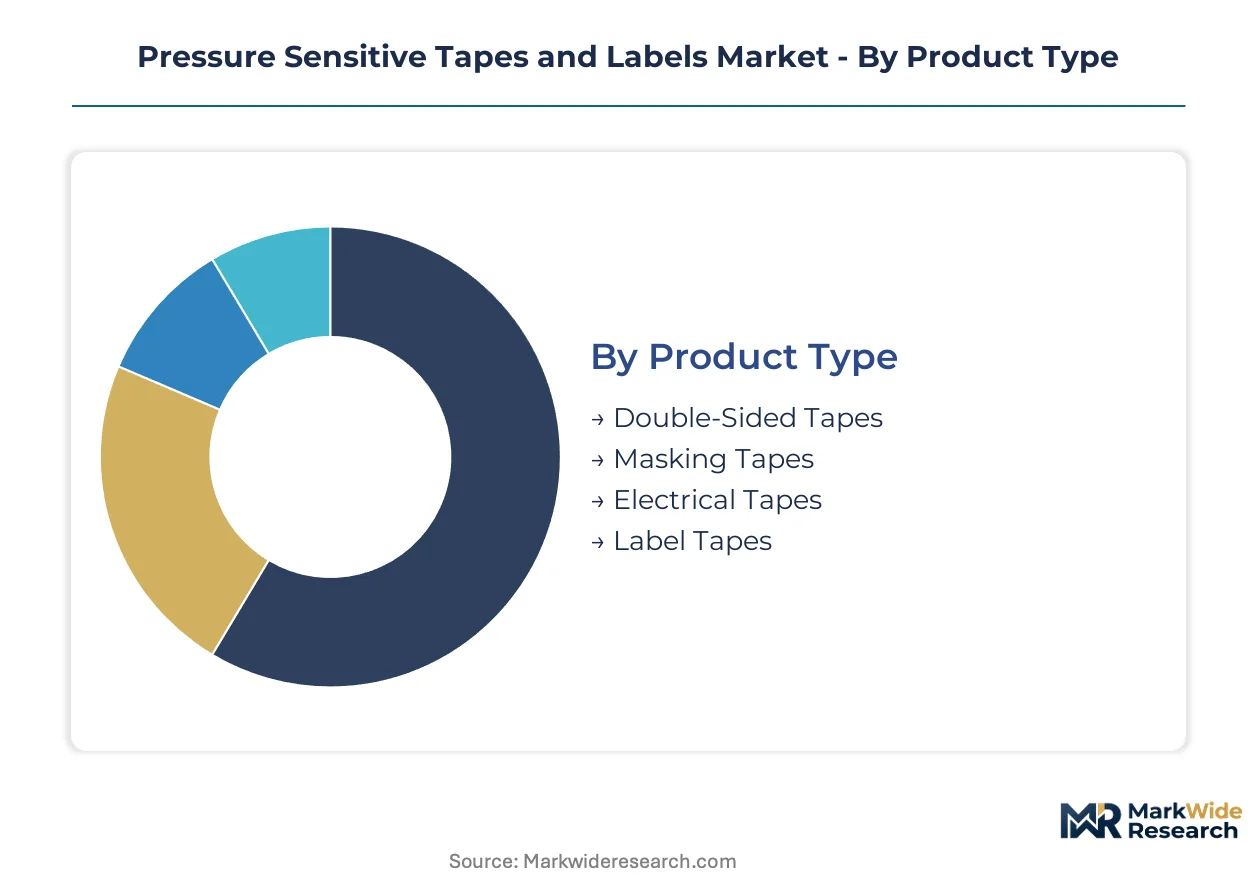
Pressure sensitive tapes and labels serve divergent performance requirements across commodity packaging and precision electronics assembly. Segmentation reveals where formulation complexity commands premium pricing versus where scale economies dominate procurement decisions.
Product Type:
Customization intensity varies from standardized masking tapes to engineered double-sided constructions with substrate-specific adhesive matching.
- Double-Sided Tapes:Carrier films or foams coated with adhesive on both sides enable invisible bonding in automotive interior trim and electronics display lamination. Electric vehicle battery pack assemblers specify acrylic foam constructions for cell-to-cell attachment in China and Germany manufacturing clusters.
- Label Tapes:Facestock-adhesive-liner laminates produced in roll or sheet format for variable information printing and pre-printed branding applications. E-commerce fulfillment centers in the United States and China consume direct thermal and thermal transfer constructions at automated print-and-apply stations.
- Masking Tapes:Crepe paper carriers with rubber-based adhesives formulated for clean removal after paint bake cycles.
- Electrical Tapes:PVC or vinyl carriers with pressure sensitive adhesive rated for dielectric strength and temperature resistance.
Most installed capacity flows through Label Tapes. Expansion is steepest in Double-Sided Tapes.
Material:
Raw material selection traces the cost-performance frontier from commodity polyethylene to functional foam substrates.
- Polyethylene:Low-density and linear low-density films provide moisture resistance and conformability for general-purpose labeling and carton sealing tapes. Cost-sensitive packaging converters in India specify PE facestocks for food and beverage labeling where recyclability certification remains secondary to unit economics.
- Foam:Acrylic, polyethylene, or polyurethane foam carriers deliver gap-filling, vibration damping, and thermal management in structural bonding applications. Automotive OEMs in Germany and Japan specify closed-cell acrylic foam tapes for exterior mirror assembly and battery module encapsulation.
- Vinyl:Plasticized PVC films offering durability and chemical resistance for floor marking and safety identification.
- Paper:Uncoated and coated paper facestocks for temporary labeling and price marking applications.
Polyethylene commands the largest production volume. Foam substrates are climbing the fastest as electric vehicle platforms multiply.
End User:
End-use concentration determines whether procurement emphasizes throughput scale or technical specification compliance.
- Packaging:Corrugated case sealing, pallet labeling, and variable information tags for logistics traceability. Automated distribution centers in China and the United States sustain demand for synthetic facestocks compatible with high-speed applicators.
- Electronics:Thermal interface materials, display bonding, and component fixation requiring cleanroom-grade adhesive platforms. REACH substance restrictions in Europe are accelerating solventless adhesive qualification for CE-marked consumer devices.
- Automotive:Interior trim attachment, wire harness wrapping, and exterior badge mounting with weathering resistance specifications.
- Construction:HVAC sealing, vapor barrier joining, and temporary surface protection with UV and moisture resistance requirements.
Packaging absorbs the majority of substrate tonnage. Electronics represents the steepest margin expansion trajectory.
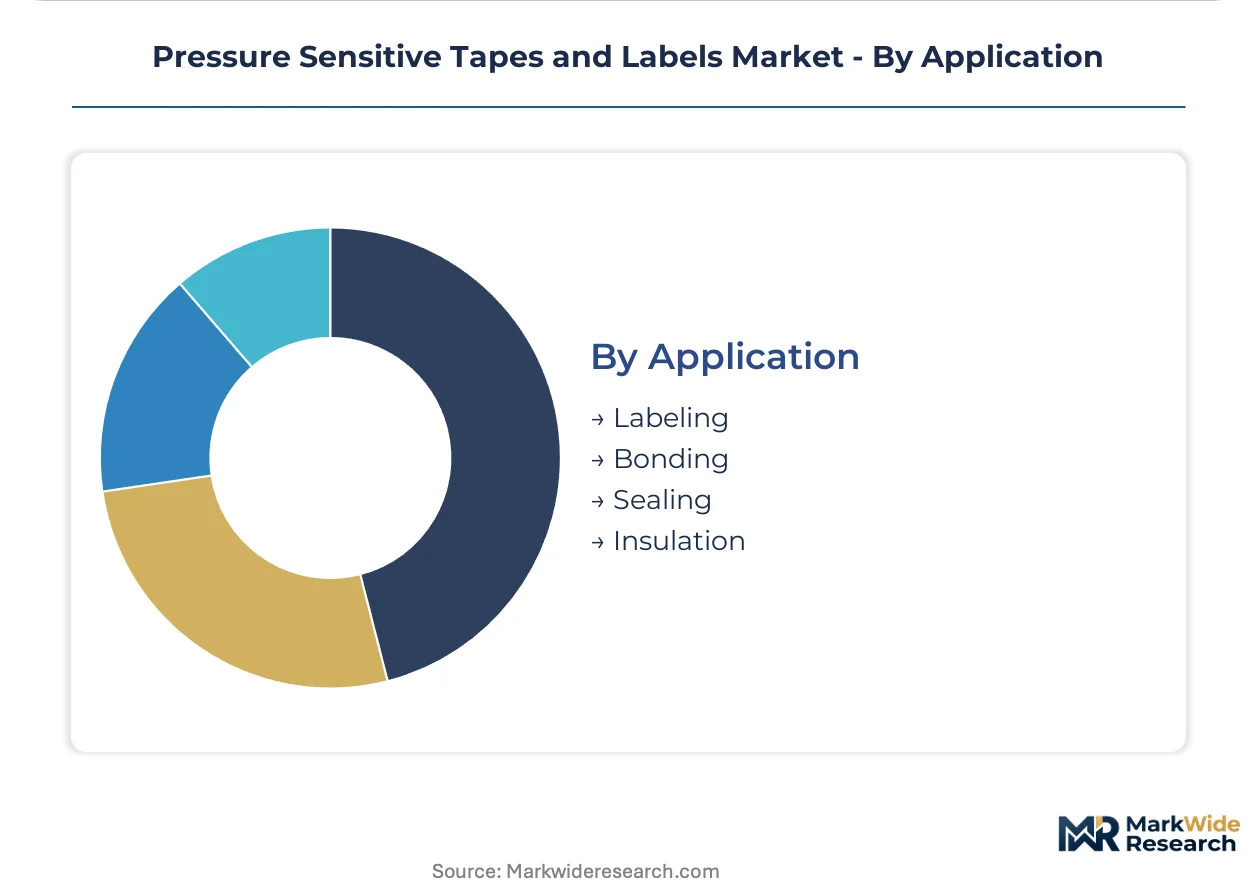
Application:
Functional application dictates adhesive formulation chemistry and liner release force specifications.
- Bonding:Structural attachment of dissimilar materials where mechanical fasteners are impractical or aesthetically unacceptable. Automotive and electronics assemblers specify hot-melt reactive polyurethane platforms for load-bearing joints previously reserved for welding.
- Labeling:Identification, branding, and traceability functions requiring print receptivity and applicator compatibility. EU Green Deal recyclability mandates are forcing substrate reformulation toward bio-based and wash-away adhesive systems.
- Sealing:Moisture, dust, and air barrier formation in packaging and building envelope applications.
- Insulation:Electrical isolation and thermal management in wire harness and battery pack construction.
Labeling applications process the highest substrate volume. Bonding functions are gaining share fastest as tape solutions displace mechanical fasteners.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The pressure sensitive tapes and labels industry traces its modern scale to post-war industrialization in the United States and Germany, where adhesive polymer science first achieved commercial manufacturing scale. Today, production concentrates across four major national clusters where regulatory frameworks and end-use demand intersect.
United States
E-commerce fulfillment automation drives thermal label consumption across automated distribution centers in California and Pennsylvania. EPA volatile organic compound regulations compel coating operations to install thermal oxidizers or convert to solventless platforms. The Chicago-Milwaukee corridor hosts major converter capacity serving retail logistics chains.
Germany
Automotive OEMs specify acrylic foam bonding tapes for electric vehicle battery assembly in Stuttgart and Munich manufacturing clusters. REACH substance restrictions accelerate bisphenol A and phthalate purge from adhesive formulations. The Rhine-Ruhr industrial zone anchors European electronics-grade tape production with cleanroom-certified facilities.
China
Domestic manufacturing scale and export packaging requirements sustain global volume leadership in the Yangtze River Delta. MEE air quality enforcement drives solvent-based coating line retrofits in Jiangsu and Zhejiang provinces. Shanghai and Suzhou host the densest concentration of label laminate production serving Asia-Pacific logistics networks.
Japan
Electronics miniaturization and thermal management applications command premium margins for precision bonding tapes in Osaka and Nagoya industrial zones. METI industrial standards govern adhesive performance specifications for consumer device assembly. The Kanto region concentrates research-intensive formulation development for next-generation display lamination.
India
Food and pharmaceutical traceability mandates from FSSAI accelerate automated label application penetration in Mumbai and Delhi NCR. Domestic packaging modernization lags Chinese throughput rates, creating expansion headroom for converter investment. The Gujarat industrial corridor attracts substrate manufacturing capacity serving export-oriented pharmaceutical labeling.
Pressure Sensitive Tapes and Labels Market Vendor Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and certification intensity. The market structure fragments between multinational material science conglomerates with integrated polymer supply and regional converters competing on logistics proximity. Three archetypes dominate: vertically integrated adhesive formulators, specialized electronics-grade cleanroom producers, and scale-driven packaging substrate converters. Competitive dynamics center on M&A consolidation of regional coating capacity and strategic partnerships between adhesive suppliers and liner recyclers.
Within the multinational tier, 3M Company and Avery Dennison Corporation represent integrated material science platforms with polymer development infrastructure spanning adhesive formulation through release liner engineering. Tesa SE occupies a position exemplifying European precision manufacturing specialization with cleanroom-certified electronics-grade capacity. These three entities anchor the premium-margin segment where REACH compliance and sustainability certification create procurement barriers for smaller competitors.
| Leading Market Players |
|---|
| 3M Company |
| Avery Dennison Corporation |
| Tesa SE |
| Nitto Denko Corporation |
| Berry Global Group, Inc. |
| Intertape Polymer Group |
| Lintec Corporation |
| Henkel AG & Co. KGaA |
| Lohmann GmbH & Co. KG |
| Others |
Supply Flow & Price Mechanics
EU Green Deal recyclability mandates are compelling brand owners to specify certified wash-away adhesives and bio-based facestocks, forcing converters to absorb reformulation costs or pass through premiums to maintain margin structures. This specification tightening concentrates procurement leverage among multinational consumer packaged goods buyers with volume commitments and sustainability scorecards.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs transaction dynamics, with REACH-compliant electronics-grade tapes commanding substantial premiums over commodity packaging substrates. Price differentiation rests on certification intensity and cleanroom production standards, with automotive OEMs least sensitive to unit cost and Indian food packaging converters most responsive to polyethylene substrate fluctuations. Cost compression in standard-grade label laminates is intensifying because of propylene derivative volatility and Asian overcapacity in thermal transfer facestocks.
Supply Chain Analysis
Dual-sourcing requirements from automotive and electronics OEMs mandate qualified backup suppliers for acrylic foam tapes and cleanroom-grade adhesives, elongating vendor onboarding timelines. Manufacturing gravity centers on China, Germany, and the United States, with raw material supply anchored in Korean petrochemical complexes for acrylic monomers and Japanese paper mills for silicone release liners. Single-source vulnerability concentrates in platinum-catalyzed release coating capacity controlled by five specialized suppliers. Distribution runs through converter networks with regional slitting and die-cutting operations positioned near end-use manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where electric vehicle battery assembly and electronics miniaturization are shifting procurement specifications toward thermal conductivity and dielectric performance tiers.
For Market Incumbents: Deepen backward integration into acrylic polymer production to offset propylene cost volatility and secure margin stability. Expand cleanroom-certified capacity in the Rhine-Ruhr corridor to capture REACH-driven specification upgrades among German automotive OEMs. Fortify against mechanical fastener substitution threats by qualifying hot-melt reactive polyurethane platforms for structural bonding applications previously reserved for welding. For New Entrants and Emerging Players: Solventless UV-curable adhesive technology offers a technology-first wedge into European electronics-grade tape production where incumbent qualification timelines create entry windows. Target India's pharmaceutical and food traceability labeling segment where automated application penetration lags Chinese benchmarks by several years. Pursue toll-coating partnerships with established liner suppliers to bypass capital-intensive coating line investments. For Investors and Strategic Acquirers: Asymmetric upside sits with regional converters possessing ISO 14064-verified carbon inventories and closed-loop liner recycling program participation, as these capabilities are becoming mandatory for Tier 1 packaging buyer qualification. Long-term viability favors specialists with formulation chemistry expertise in UV oligomer selection rather than commodity-scale polyethylene substrate producers. Watch for EU Green Deal carbon intensity threshold tightening as the inflection indicator that would accelerate bio-based adhesive platform adoption and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Polymer Production | Captive monomer supply insulates margins from Korean petrochemical spot market volatility. |
| Cleanroom Capacity Expansion | ISO-certified production in the Rhine-Ruhr corridor secures CE-marked electronics tape qualification. |
| Solventless Coating Line Conversion | MEE air quality compliance in Jiangsu province preserves Yangtze River Delta manufacturing access. |
| Bio-Based Adhesive Platform Development | Starch-derived tackifier certification under ISO 14021 opens EU public procurement channels. |
| Closed-Loop Liner Recycling Program | Retailer sustainability scorecard participation consolidates vendor relationships with multinational brand owners. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's manufacturing clusters. The approach combines structured interviews with adhesive formulators, converter procurement leads, automotive OEM specification engineers, and electronics contract manufacturers with secondary validation through customs trade data, EPA emissions filings, ECHA substance registrations, and SEC disclosures from listed material science conglomerates. Bottom-up segment sizing and top-down macroeconomic cross-checks ensure dimensional consistency across adhesive chemistry, substrate material, and end-use application.
Granularity extends to product type, material substrate, end-user industry, and functional application, with additional modeling of regulatory compliance tier and cleanroom certification status. Volume and value trajectories across the analysis window derive from elasticity-adjusted demand curves calibrated to e-commerce logistics expansion rates, electric vehicle production ramp schedules, and REACH substance restriction timelines. Industry-specific forecast inputs include propylene derivative pricing correlations, liner recycling program adoption curves, and automated print-and-apply system installation data from distribution center operators.
The model holds under sustained e-commerce logistics automation and progressive EU Green Deal implementation; deviation in petrochemical feedstock volatility or MEE enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tapes
Global Seam Sealing Tapes Market
Tapes
Foil Tapes Market
Tapes
Packaging Tapes Market
Tapes
Non-UV Dicing Tapes Market
Tapes
Sealing and Strapping Packaging Tapes Market
Tapes
Water Activated Tape Dispensers Market
Tapes
Security Tape Market
Tapes
Strapping Supplies Market
Tapes
Freezer Tape Market
Tapes
Automotive Tapes Market
Tapes
Correction Tapes Market
Tapes
Thermal Release Tapes Market
Tapes
Global Specialty Tapes Market
Tapes
Edge Band Tapes Market
Tapes
Tabbing Tapes Market
Tapes
Raffia Tape Stretching Line Market