
 Stretch Sleeve and Heat Shrink Labels Market | 2026-2036
Stretch Sleeve and Heat Shrink Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Stretch Sleeve and Heat Shrink Labels Market Outlook
Single-source procurement for printed sleeve films is consolidating toward multi-source agreements with regional converters. CCL Industries Inc. leverages its North American film extrusion network to secure supply continuity for beverage clients. Berry Global Inc. sustains cost competitiveness through captive resin compounding operations. Huhtamaki Oyj anchors its position with heat-shrink formulations optimized for high-speed applicator lines.
Stretch sleeves and heat shrink labels are polymer-based decorative and informational coverings that conform to container contours through elastic recovery or thermal contraction, typically manufactured via extrusion, printing, and seaming processes with thicknesses ranging from 40 to 80 microns to accommodate flexographic or rotogravure decoration. These labels serve primarily as 360-degree branding surfaces and tamper-evident seals for contoured packaging. Polyethylene formulations dominate material selection due to cost efficiency and recycling compatibility, while PVC faces structural decline amid sustainability pressures. Food and beverage applications generate the deepest margin pools, though pharmaceutical adoption is expanding fastest as traceability requirements intensify.
The FDA regulates indirect food-contact layers through 21 CFR compliance for adhesive and ink constituents, while the EPA oversees volatile organic compound emissions from solvent-based printing operations. The EU's REACH framework restricts phthalate plasticizers in PVC shrink films, redirecting formulation investment toward PET-G and oriented polystyrene alternatives. Stakeholders must monitor evolving extended producer responsibility schemes, as these will determine which material-recovery pathways receive infrastructure investment and regulatory preference.
Market Dynamics
Recyclability mandates across major economies are forcing material substitution away from PVC toward PET-G and oriented polystyrene formulations, reshaping converter investment priorities and resin sourcing strategies.
Growth Catalysts
- Beverage bottler expansion:PET container adoption in Latin American soft-drink production zones is accelerating sleeve-label demand, particularly near São Paulo state's contract labeling clusters.
- EU Packaging and Packaging Waste Regulation:Tightening recyclability mandates for plastic labels are redirecting formulation R&D toward compatible polymers and driving infrastructure investment.
- Pharmaceutical traceability requirements:Serialization and tamper-evident mandates are expanding heat-shrink adoption for vial and bottle security applications.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock fluctuations compress converter margins, particularly for polyethylene-dominant formulations.
- Supply concentration risk:Film extrusion capacity clusters in North American and European hubs, exposing buyers to logistics disruptions and currency exposure.
- REACH phthalate restrictions:ECHA limitations on plasticizers in legacy PVC shrink films strand existing equipment and force capital-intensive retooling.
Strategic Opportunities
- Extended producer responsibility schemes:EU member-state infrastructure investment preferences will advantage label-to-label recycling pathways over downcycling alternatives.
- High-speed applicator optimization:Heat-shrink formulations engineered for 600+ bottles-per-minute lines offer premium positioning in carbonated beverage bottling.
- Indian pharmaceutical export growth:CDSCO serialization requirements for export-bound generics create demand for tamper-evident sleeve labels in contract manufacturing zones.
Industry Challenges
- Flexographic-rotogravure skill scarcity:Narrow-web press operators with 40-80 micron film expertise command wage premiums, constraining regional converter expansion.
- Multi-source qualification timelines:Beverage clients require 12-18 month validation cycles for new film suppliers, delaying procurement diversification.
- Legacy seaming equipment incompatibility:PET-G and OPS alternatives demand solvent welding or ultrasonic bonding retrofits on existing sleeve production lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Stretch Sleeve and Heat Shrink Labels Market |
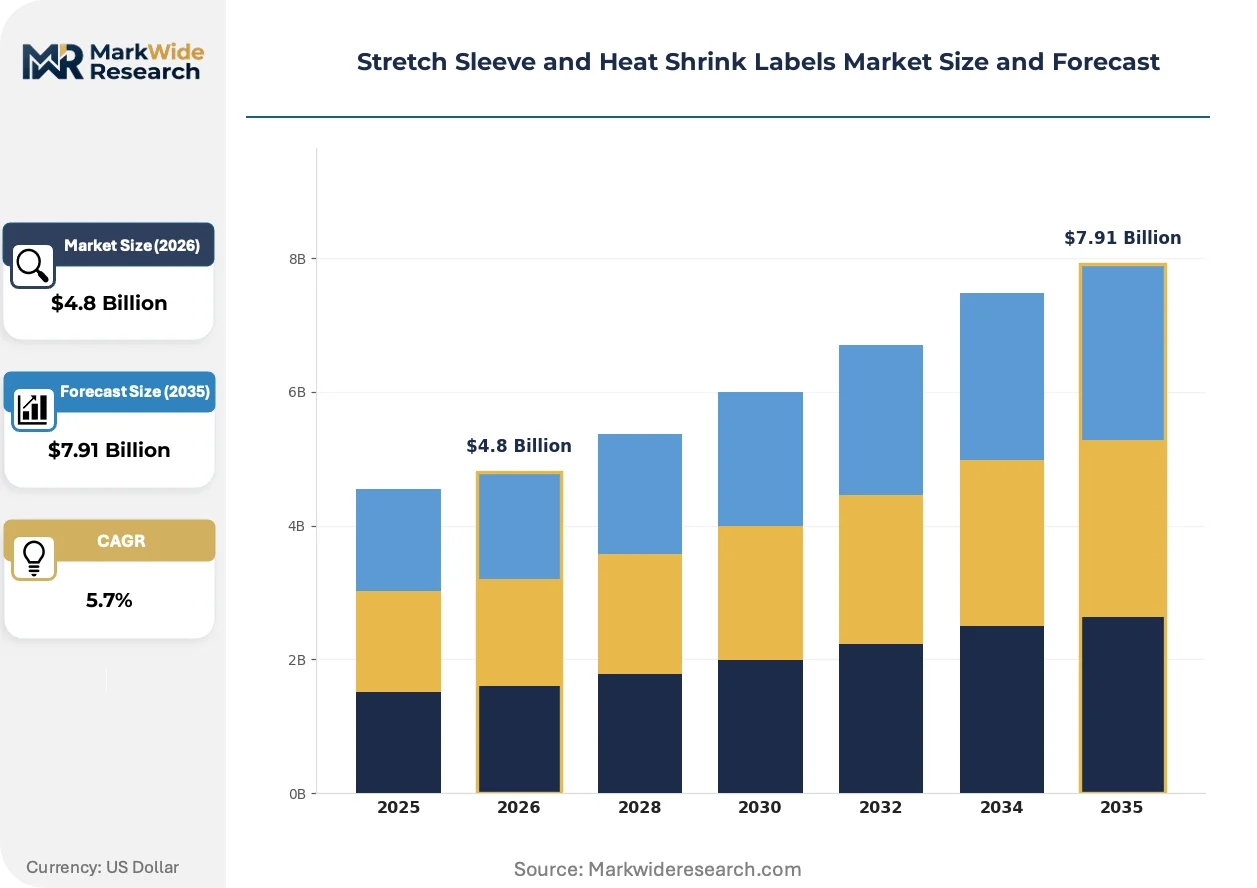
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stretch Sleeves, Heat Shrink Tubes, Label Applicators, Specialty Labels Material: Polyethylene, Polypropylene, PVC, PET Application: Food & Beverage, Cosmetics, Pharmaceuticals, Household Products End User: Manufacturers, Distributors, Retailers, E-commerce Platforms |
| Companies Covered | Fuji Seal International, Amcor PLC, Berry Global Inc., Taghleef Industries, Avery Dennison Corporation, CCL Industries Inc., Huhtamaki Oyj, Coveris, Klöckner Pentaplast, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Stretch Sleeve and Heat Shrink Labels Market Strategic Shifts
Digital printing integration and mono-material design are converging to eliminate separation steps in recycling streams, while regulatory pressure on carbon intensity accelerates low-temperature shrink formulations.
Laser-marking systems for variable data serialization are converging with heat-shrink label substrates to eliminate ink-based coding entirely. Pharmaceutical packagers in European markets are piloting these systems for compliance with FMD serialization mandates. The technology is compressing lead times for lot-specific label runs while reducing VOC emissions from solvent-based coding operations.
REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC formulation abandonment across EU member states. Converter investment is redirecting toward PET-G extrusion lines and oriented polystyrene alternatives with comparable clarity and shrink performance. Beverage applications in Germany and France face the most acute transition pressure, with brand owners demanding 2025 compliance timelines.
Single-source procurement contracts for printed sleeve films are fragmenting toward multi-source agreements with regional converters. Large beverage bottlers in North America are qualifying secondary film suppliers to mitigate supply continuity risks exposed by recent logistics disruptions. This pattern is most pronounced in California and Texas production corridors, where proximity to Mexican converter networks offers tariff-advantaged alternatives.
Stretch Sleeve and Heat Shrink Labels Market Segmentation
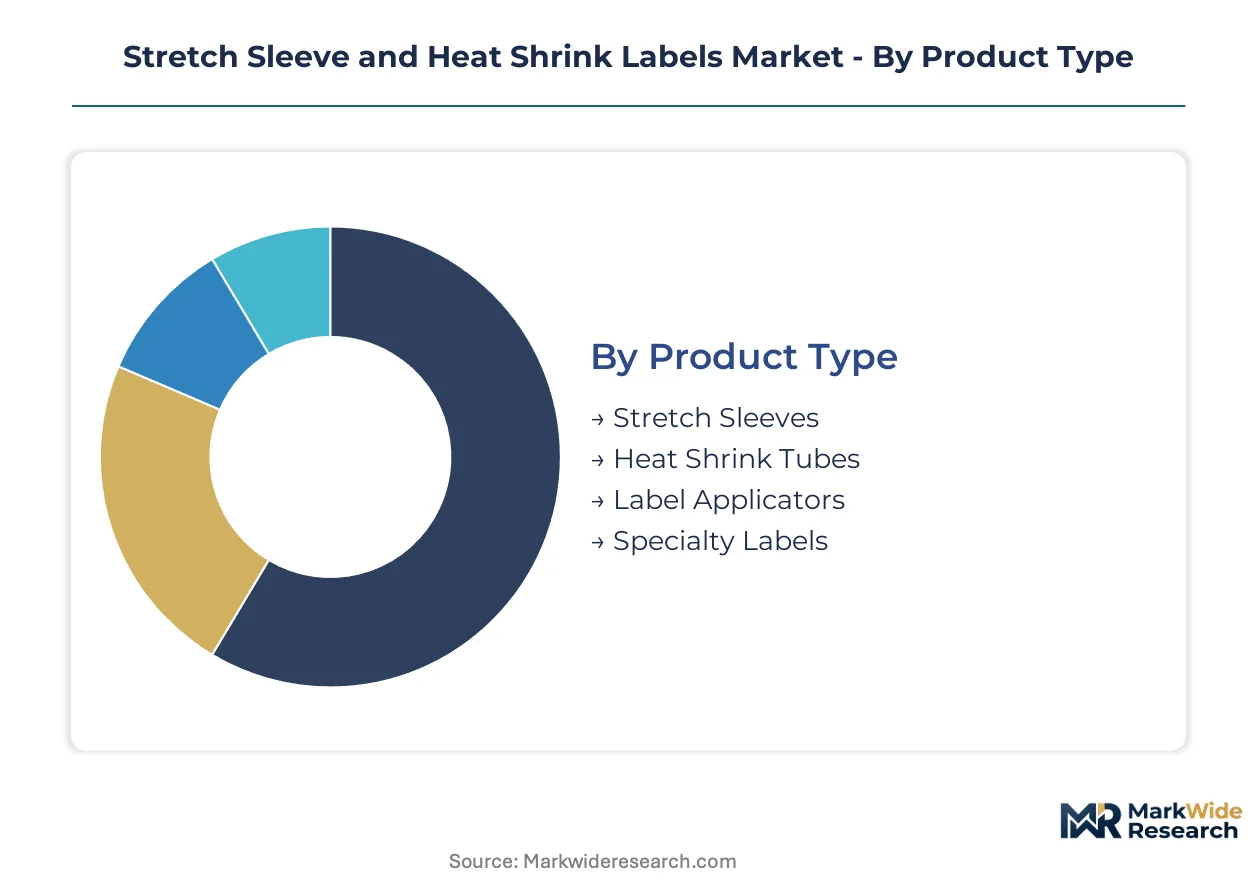
Segmentation in sleeve and shrink labels reveals how material choices, application requirements, and end-user procurement patterns create distinct competitive arenas. Understanding these divides exposes where formulation R&D investments concentrate and which customer relationships command premium positioning.
Product Type:
Integration depth varies sharply across product categories, with standalone decorative sleeves serving fundamentally different operational roles than embedded applicator systems.
- Stretch Sleeves:Elastic polymer tubes that recover mechanically around container contours without heat activation, typically 40-60 microns thick for hand or semi-automatic application. São Paulo beverage bottlers are expanding stretch sleeve adoption for PET carbonated drinks, driven by lower energy costs versus heat-shrink alternatives and compatibility with existing cold-fill lines.
- Heat Shrink Tubes:Thermally activated sleeves that contract 30-70% when exposed to steam or hot-air tunnels, forming tamper-evident seals with 360-degree decoration capability. Pharmaceutical packagers in Germany are qualifying heat-shrink tubes for vial bundling under EMA serialization mandates, replacing cardboard secondary packaging.
- Label Applicators:Automated handling systems integrate sleeve placement with container conveyance at 400-800 units per minute. Equipment procurement concentrates among North American contract packagers seeking line speed upgrades.
- Specialty Labels:Includes holographic security sleeves and temperature-indicating formats for cold-chain monitoring. Demand from Indian pharmaceutical exporters is climbing under CDSCO traceability requirements.
Stretch sleeves lead volumes today; label applicators are gaining share fastest as bottlers automate existing lines rather than greenfield capacity.
Material:
Cost tiers stratify material selection, with commodity polyolefins anchoring volume and engineering polymers capturing margin in regulated applications.
- Polyethylene:Linear low-density formulations dominate beverage applications due to cost efficiency and established recycling streams. Brazilian converters are expanding LLDPE extrusion capacity to serve regional soft-drink growth.
- Polypropylene:Oriented films offer higher shrink force and clarity for contoured cosmetic containers. European brand owners are qualifying PP alternatives as REACH phthalate restrictions strand PVC capacity.
- PVC:Legacy formulations face structural decline amid ECHA plasticizer limitations and brand-owner sustainability commitments. Remaining demand concentrates in non-EU pharmaceutical markets with less stringent chemical regulations.
- PET:Glycol-modified PET-G delivers optical clarity and controlled shrink performance for premium beverage and personal care positioning. German converters are retooling extrusion lines to capture PET-G demand from departing PVC users.
Polyethylene leads volumes today; PET is gaining share fastest as brand owners prioritize recyclability and optical performance.
Application:
Application segmentation tracks how regulatory intensity and margin structure reshape converter customer targeting across end-use verticals.
- Food & Beverage:Carbonated soft drinks, bottled water, and craft beer generate the deepest volume pools with standardized 40-50 micron specifications. Latin American bottlers are consolidating procurement around regional converters to secure supply continuity.
- Cosmetics:Premium skincare and fragrance applications demand high-clarity films with metallic decoration and precise shrink control on irregular contours. French and Italian brand owners are driving specification tightening for shelf differentiation.
- Pharmaceuticals:Serialization-ready sleeves with integrated tamper-evidence are expanding fastest as FDA 21 CFR and EU FMD mandates harden. Indian contract manufacturers are investing in sleeve-label capability for export-bound generics.
- Household Products:Cleaning and automotive chemical containers prioritize chemical resistance and abuse-resistant sleeve durability. North American private-label retailers are qualifying secondary suppliers to reduce concentration risk.
Food & beverage leads volumes today; pharmaceuticals is gaining share fastest as traceability mandates harden across major economies.
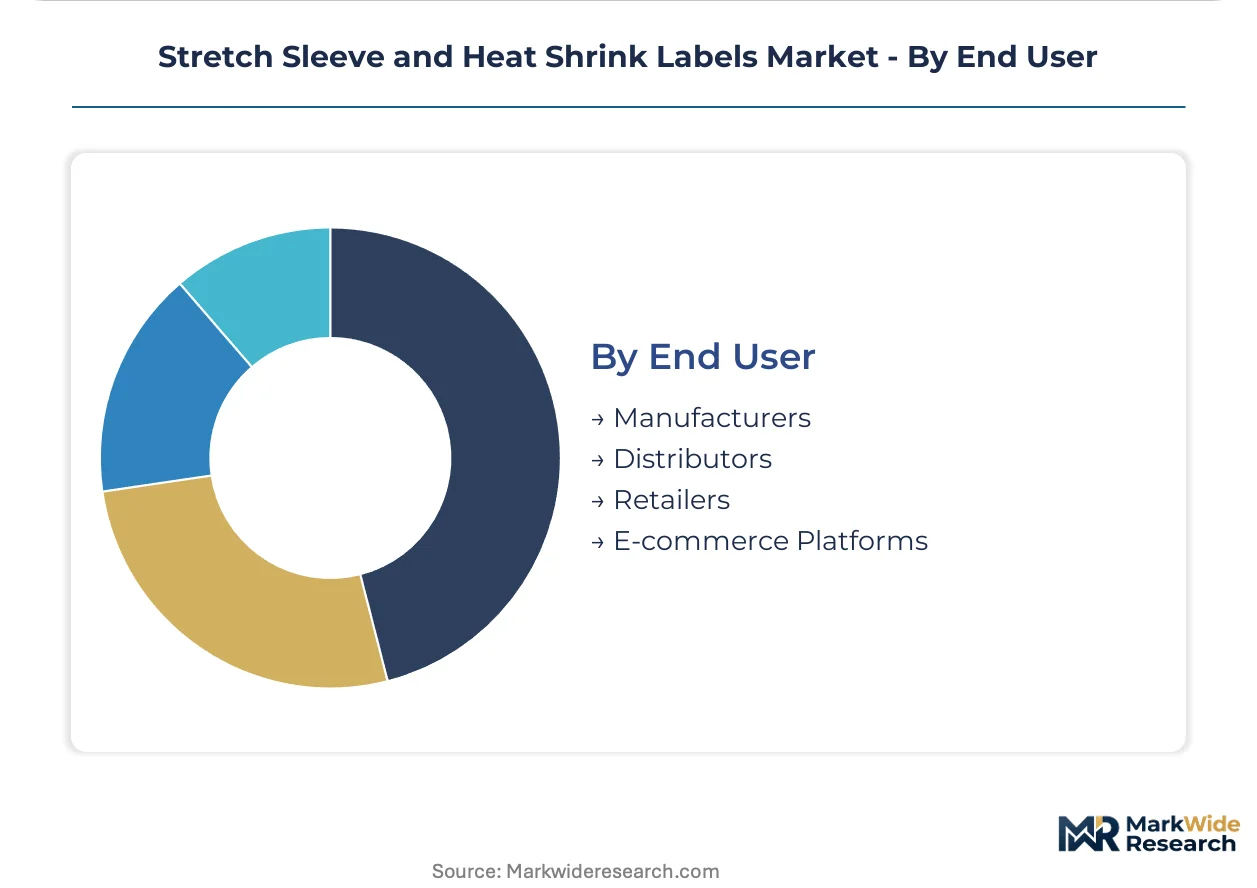
End User:
Customer type segmentation exposes how procurement sophistication and technical qualification requirements fragment the vendor landscape.
- Manufacturers:Brand-owning producers with captive bottling lines specify films directly and validate converters through 12-18 month qualification cycles. Beverage manufacturers in California and Texas are diversifying toward Mexican converter networks.
- Distributors:Regional packaging suppliers aggregate demand from smaller bottlers and coordinate film sourcing with printing services. Brazilian distributors are consolidating around São Paulo state labeling clusters.
- Retailers:Private-label owners specify sleeve formats for contract-manufactured store brands, prioritizing cost control and supply security over technical differentiation.
- E-commerce Platforms:Direct-to-consumer brands demand short-run digital printing with rapid turnaround, compressing traditional converter lead times and margin structures.
Manufacturers lead volumes today; e-commerce platforms are gaining share fastest as direct-to-consumer beverage brands proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting sleeve-label production toward jurisdictions with lower compliance costs and established resin supply chains. Brazil's São Paulo state captures beverage bottler investment as EU REACH restrictions elevate European conversion costs. Mexican converter networks near the US border gain share from California and Texas manufacturers seeking tariff-advantaged alternatives.
United States
California and Texas beverage bottlers are diversifying procurement toward Mexican converter networks to mitigate logistics concentration risk. The FDA enforces 21 CFR compliance for indirect food-contact adhesive and ink constituents. Contract labeling clusters in the Los Angeles basin and Dallas-Fort Worth corridor are qualifying secondary film suppliers to reduce single-source dependency.
Germany
Pharmaceutical packagers are qualifying heat-shrink tubes for vial bundling under EMA serialization mandates. ECHA REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC formulation abandonment and retooling toward PET-G extrusion. Converter investment concentrates in the North Rhine-Westphalia industrial belt to capture departing PVC capacity.
Brazil
São Paulo state's contract labeling services are expanding sleeve-label adoption for PET carbonated drink containers. ANVISA pharmaceutical traceability requirements are accelerating tamper-evident sleeve demand for export-bound generics. Soft-drink production zones in the Campinas corridor are consolidating procurement around regional converters.
India
Pharmaceutical contract manufacturers are investing in sleeve-label capability for CDSCO serialization requirements on export-bound generics. BIS standards govern food-contact material safety for domestic beverage applications. Labeling capacity clusters in Maharashtra's Mumbai-Pune industrial corridor are expanding to serve European and North American export demand.
Mexico
Baja California and Nuevo León converter facilities are capturing procurement diversification from US beverage bottlers seeking supply continuity. The country's national environmental regulator oversees VOC emissions from solvent-based printing operations. Monterrey's film extrusion hub is expanding LLDPE capacity to serve cross-border soft-drink production.
Stretch Sleeve and Heat Shrink Labels Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue digital printing and mono-material formulations to bypass legacy equipment barriers. The market structures around three tiers: multinational film extruders with captive resin operations, regional converters with specialized seaming expertise, and equipment-integrated solution providers. Consolidation pressure intensifies as beverage clients demand 12-18 month qualification cycles that favor incumbents with validated track records. Strategic moves center on backward integration into resin compounding and geographic expansion toward Latin American production zones.
Among diversified packaging conglomerates, CCL Industries Inc., Berry Global Inc., and Huhtamaki Oyj exemplify distinct archetypes within the competitive set. CCL Industries Inc. represents the North American film extrusion network model securing supply continuity through regional converter relationships. Berry Global Inc. occupies a position anchored by captive resin compounding operations that sustain cost competitiveness across polyethylene-dominant formulations. Huhtamaki Oyj sits within the specialty formulation tier with heat-shrink expertise optimized for high-speed applicator lines. These three entities collectively illustrate how scale, vertical control, and technical specialization define competitive positioning in sleeve and shrink label supply.
| Leading Market Players |
|---|
| Fuji Seal International |
| Amcor PLC |
| Berry Global Inc. |
| Taghleef Industries |
| Avery Dennison Corporation |
| CCL Industries Inc. |
| Huhtamaki Oyj |
| Coveris |
| Klöckner Pentaplast |
| Others |
Value Chain & Pricing Dynamics
Performance-grade divergence between high-speed applicator-compatible formulations and commodity sleeve films manifests in both pricing premiums and supply chain configuration. Premium PET-G and oriented polystyrene grades command 15-25% markups over standard polyethylene while requiring dedicated extrusion lines and solvent-welding seaming capacity that commodity converters lack.
Pricing Analysis
Distributor margins in Latin American beverage corridors compress as São Paulo-based contract labeling clusters consolidate procurement around regional converters. Three-tier pricing structure across premium, standard, and economy levels separates optical-grade PET-G for cosmetics from LLDPE beverage sleeves and downcycled regrind formulations. Pricing pressure stems from ethylene feedstock volatility and resin price pass-through clauses in annual contracts. Brand-owning manufacturers exhibit lowest price sensitivity for pharmaceutical serialization grades, while private-label retailers drive aggressive cost negotiation on household product sleeves.
Supply Chain Analysis
EU domestic-content mandates under extended producer responsibility schemes are reshaping sourcing toward regional PET-G extrusion capacity in Germany and France. Raw material dependencies center on ethylene and propylene feedstocks from Gulf Coast petrochemical complexes, glycol modifiers for PET-G clarity, and phthalate-free plasticizer alternatives. Single-source vulnerability concentrates in North American film extrusion hubs exposed to logistics disruptions. Distribution runs through converter-direct relationships for large beverage bottlers and distributor-aggregated channels for smaller regional players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The stretch sleeve and heat shrink labels market reads as a late-cycle quality story where beverage and pharmaceutical end-users are prioritizing recyclability-certified formulations over lowest-unit-cost alternatives.
For Market Incumbents: Lock in multi-year supply agreements with São Paulo beverage bottlers before Mexican converter networks capture cross-border procurement diversification. Prioritize backward integration into captive resin compounding to defend margin position against ethylene price volatility. Invest in ultrasonic seaming retrofits to service departing PVC users in EU member states facing ECHA plasticizer restrictions.
For New Entrants and Emerging Players: Regional distributors in India's Mumbai-Pune corridor offer the most penetrable channel access for pharmaceutical export-focused sleeve labels. Target CDSCO-compliant serialization formats for contract manufacturers serving European and North American generics markets. Lead with digital printing capability and sub-500 unit minimum order quantities to capture e-commerce platform demand from direct-to-consumer beverage brands.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialty formulation players possessing PET-G extrusion expertise and validated pharmaceutical track records. Five-to-ten year viability favors converters with mono-material design capabilities aligned to EU Packaging and Packaging Waste Regulation recycling pathways. Monitor German converter retooling announcements as an inflection signal for PET-G capacity shortage premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive ethylene sourcing insulates Berry Global and peers from feedstock volatility compressing converter margins. |
| PET-G Extrusion Line Expansion | German converters in North Rhine-Westphalia capture demand from PVC formulation abandonment under REACH Annex XVII. |
| Digital Printing Platform Deployment | Short-run capability addresses e-commerce platform requirements for rapid turnaround on limited SKU launches. |
| High-Speed Applicator Optimization | Formulations engineered for 600+ bottles-per-minute lines secure premium positioning with Coca-Cola and Pepsi bottlers. |
| Extended Producer Responsibility Partnership | Label-to-label recycling pathway investment aligns with EU member-state infrastructure preferences advantaging mono-material designs. |
Study Parameters
Bottom-up beverage and pharmaceutical end-use modeling reconciled against top-down film extrusion capacity tracking forms the analytical core of this study. Primary interviews with plant managers at North American and European converters, procurement leads at Latin American soft-drink bottlers, regulatory affairs specialists at pharmaceutical packagers, and distribution channel partners in São Paulo and Mumbai-Pune corridors combined with secondary validation from FDA 21 CFR filings, ECHA REACH substance restrictions, ANVISA traceability guidelines, customs trade data, and SEC disclosures from listed packaging conglomerates.
Historical trendline analysis of sleeve-label adoption rates across carbonated beverage, bottled water, craft beer, and pharmaceutical vial applications informed projection modeling. Segmentation dimensions include product type, material formulation, application vertical, and end-user procurement sophistication across the projection horizon. CAGRs derived from elasticity-adjusted demand curves incorporating ethylene price sensitivity, regulatory compliance cost pass-through, and automation investment cycles in bottling lines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU extended producer responsibility implementation timelines and PVC phase-out acceleration. Forecasts reflect documented assumptions regarding resin supply continuity and qualification cycle durations. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
India Print Label Market
Labels
Wrap Around Labels Market
Labels
Global Label Adhesive Market
Labels
Ripeness Indicator Labels Market
Labels
Global Cryogenic Label Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Global Waterproof Labels Market
Labels
Europe Shrink and Stretch Sleeve Label Market
Labels
Fiber Optic Labels Market
Labels
Stretch Sleeve Labels Market
Labels
Global Automotive Labels Market
Labels
GCC Labeling Market
Labels
Safety Labels Market
Labels
Extended Text Labels Market
Labels
Screen Print Label Market
Labels
Shrink Sleeve Label Applicator Market