
 Wet Glue Labels Market | 2026-2036
Wet Glue Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Wet Glue Labels Market Outlook
REACH compliance is shifting the cost-of-entry calculus for wet glue label suppliers entering European markets. Ahlstrom-Munksjö leverages its fiber-based substrate expertise to serve premium beverage accounts with FSC-certified paper stocks. CCL Industries anchors its position through multi-continent manufacturing scale and pharmaceutical-grade wet glue certification. Multi-Color Corporation specializes in high-speed rotary application systems for carbonated soft drink bottlers.
Wet glue labels are paper or film substrates coated with water-activated or solvent-based adhesives, applied via brush, roller, or jet systems to glass, metal, or plastic containers at line speeds exceeding 60,000 bottles per hour. The paper material segment dominates volume due to cost parity and established recycling streams, though film substrates are gaining share in pharmaceutical applications requiring moisture resistance. Food and Beverage end-use leads absolute consumption, while Personal Care represents the fastest-growing vertical as cosmetic houses return to tactile glass packaging.
The EPA regulates volatile organic compound emissions from solvent-based adhesive operations in US converting facilities, while REACH restricts hazardous substance migration into food-contact packaging across Europe. ECHA's ongoing substance evaluations are pressuring formulators to eliminate residual formaldehyde and phthalate plasticizers from water-based adhesive recipes. Stakeholders must monitor regulatory divergence between California's Proposition 65 enforcement trends and EU harmonized standards to avoid duplicative compliance investments.
Market Dynamics
REACH substance evaluations are forcing adhesive formulators to eliminate residual formaldehyde and phthalate plasticizers from water-based recipes, compressing supplier margins while elevating compliance costs for European market entry.
Growth Catalysts
- EU Green Deal packaging directives:Mandates for recyclable chemistries are accelerating bio-based adhesive reformulation investments across converting facilities.
- Glass packaging revival:Beverage bottlers are expanding wet glue label procurement as brands pursue premium aesthetics in craft beer and mineral water segments.
- Rotary application speed thresholds:High-speed jet systems exceeding 60,000 bottles per hour are sustaining paper substrate dominance in carbonated soft drink lines.
Market Restraints
- Solvent-based adhesive emission controls:EPA volatile organic compound regulations add capital burden to US converting operations.
- Film substrate cost premium:Moisture-resistant pharmaceutical-grade films carry 40-60% raw material cost escalation versus paper stocks.
- Regulatory divergence friction:California Proposition 65 enforcement trends create duplicative compliance investments alongside EU harmonized standards.
Strategic Opportunities
- Personal Care glass pivot:Cosmetic houses returning to tactile packaging are opening high-margin wet glue label demand in fragrance and skincare.
- Pharmaceutical moisture resistance:Film substrate penetration in prescription bottle labeling offers technical differentiation.
- FSC-certified paper stocks:Forest Stewardship Council chain-of-custody certification is becoming a procurement gate for premium beverage accounts.
Industry Challenges
- Adhesive chemist talent scarcity:Formulation expertise bridging bio-based performance parity with legacy solvent systems commands wage premiums.
- Legacy line retrofit capex:Water-activated brush systems require synchronized drying tunnel investments incompatible with leased bottling facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wet Glue Labels Market |
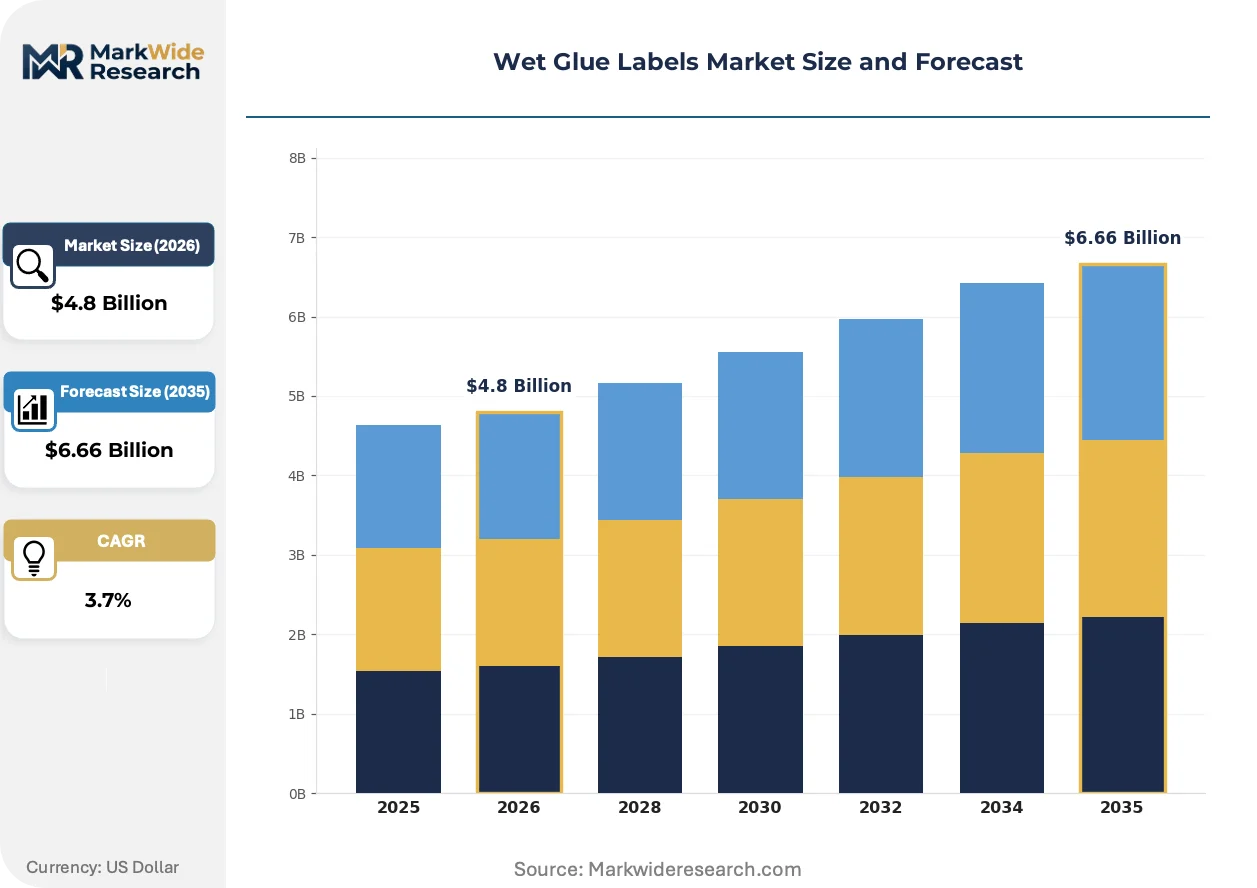
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Pressure-Sensitive, In-Mold, Wrap-Around, Resealable End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Material Type: Paper, Plastic, Film, Composite Adhesive Type: Hot Melt, Solvent-Based, Water-Based, Others |
| Companies Covered | Ahlstrom-Munksjö, Global Printing And Packaging Co., CCL Industries, Optimum Group, Chromaprint India, All4Labels, Sappi, Huhtamaki Oyj, Multi-Color Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wet Glue Labels Market Strategic Shifts
Digital printing integration with wet glue application lines is compressing minimum order quantities and enabling mass customization for regional beverage launches.
High-speed rotary application systems are consolidating market share among carbonated soft drink bottlers seeking throughput optimization. These systems integrate vision-guided label placement with real-time adhesive viscosity monitoring. The technology is consolidating supplier relationships around equipment- adhesive bundled service contracts.
REACH restrictions on hazardous substance migration into food-contact packaging are forcing adhesive formulators to accelerate bio-based recipe development. Industrial consequence includes extended qualification timelines for new chemistries. Beverage end-use segments in Germany and France are responding by consolidating procurement around pre-qualified supplier pools.
Buyer concentration among multinational beverage groups is compressing wet glue label supplier margins through volume-consolidated tender processes. Regional craft breweries are being displaced from direct supplier relationships as distributors assume procurement aggregation. This pattern is most visible in German mineral water and craft beer segments where cooperative buying groups now dominate adhesive specification.
Wet Glue Labels Market Segmentation
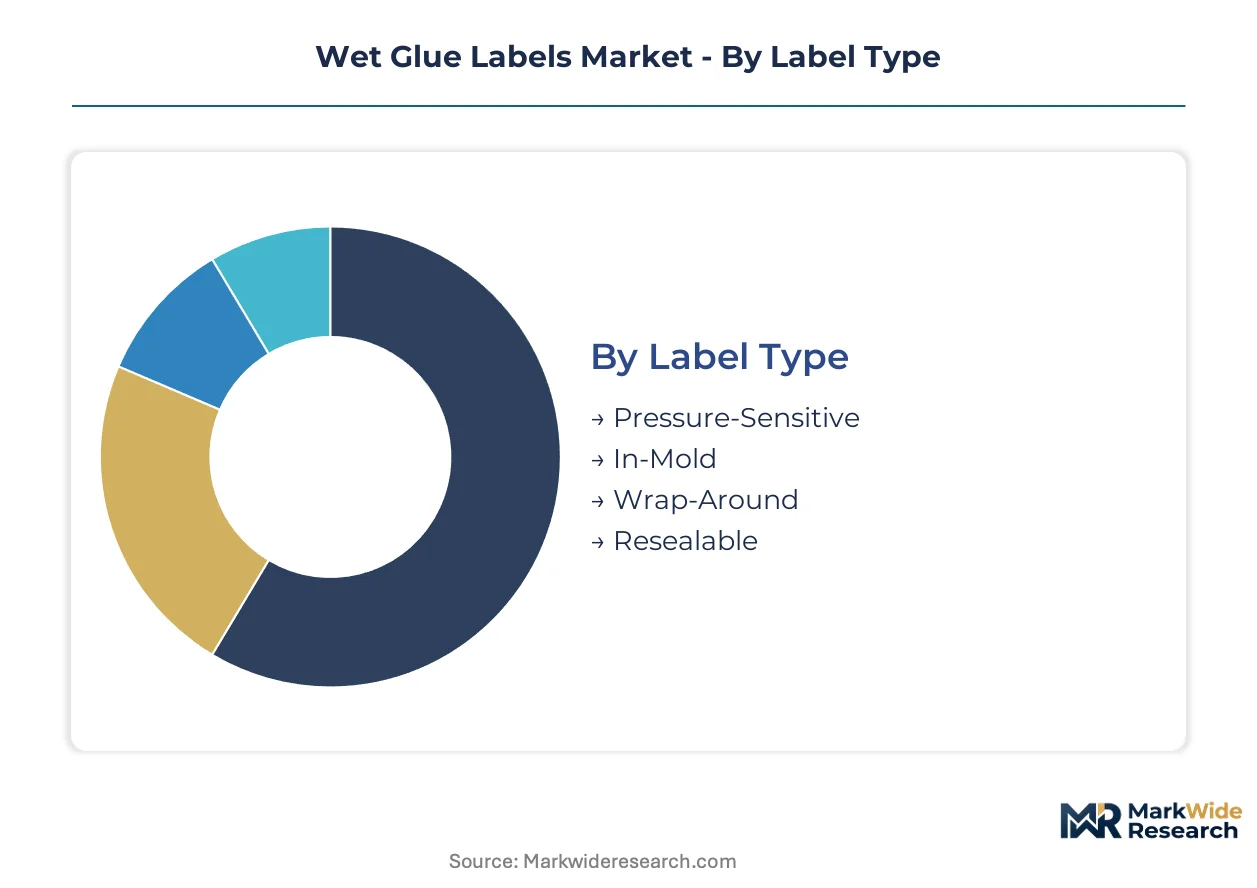
Wet glue label procurement decisions cascade through four intersecting axes: substrate chemistry, adhesive activation mechanism, container geometry, and end-use regulatory exposure. Buyers configure specifications around line speed thresholds, recycling compliance, and tactile brand differentiation.
Label Type:
Container geometry and application mechanics define functional performance tiers across bottling operations.
- Wrap-Around:Continuous paper or film substrates encircle cylindrical glass or metal containers with 360-degree graphics coverage. German mineral water bottlers and craft breweries in Bavaria sustain high-volume procurement for premium shelf presence.
- Pressure-Sensitive:Pre-coated adhesives eliminate wet application infrastructure, enabling retrofitting of legacy bottling lines without drying tunnel investments. Demand concentrates among mid-scale beverage distributors seeking operational flexibility.
- In-Mold:Labels fuse with container surfaces during blow-molding or injection processes, delivering permanent adhesion for industrial chemical packaging.
- Resealable:Multi-layer constructions with repositionable adhesive zones serve condiment and sauce segments requiring repeated container access.
Wrap-Around leads on scale; Resealable climbs the fastest on functional differentiation.
End Use Industry:
Regulatory stringency and brand positioning intensity vary sharply across downstream verticals.
- Food & Beverage:Absolute volume concentration with EFSA migration limits and FDA food-contact compliance governing adhesive specification. Carbonated soft drink bottlers in Germany and France drive rotary application system procurement.
- Personal Care:Cosmetic houses returning to tactile glass packaging for fragrance and skincare are opening high-margin demand channels. Moisture-resistant film substrates gain traction against bathroom humidity exposure.
- Pharmaceuticals:EMA and FDA label integrity requirements mandate tamper-evident wet glue adhesion for prescription bottles. Moisture resistance specifications favor film over paper substrates.
- Household Products:Industrial chemical resistance and cost minimization dominate procurement criteria for cleaning and detergent containers.
Food & Beverage dominates absolute volume; Personal Care shows steepest expansion trajectory on packaging premiumization.
Material Type:
Substrate selection balances recycling stream compatibility, moisture resistance, and unit economics.
- Paper:FSC-certified stocks dominate beverage applications with established mechanical recycling pathways and cost parity. REACH-compliant adhesive formulations face qualification bottlenecks but sustain procurement preference.
- Film:Polypropylene and polyethylene constructions deliver moisture barrier performance for pharmaceutical and personal care end-uses. Raw material cost premiums of 40-60% versus paper compress adoption outside specification-critical segments.
- Plastic:Rigid substrates for specialty container formats requiring dimensional stability under temperature cycling.
- Composite:Multi-layer laminates combining paper tactile properties with film barrier performance for premium cosmetic applications.
Paper holds volume leadership; Film gains share fastest on technical specification tightening.
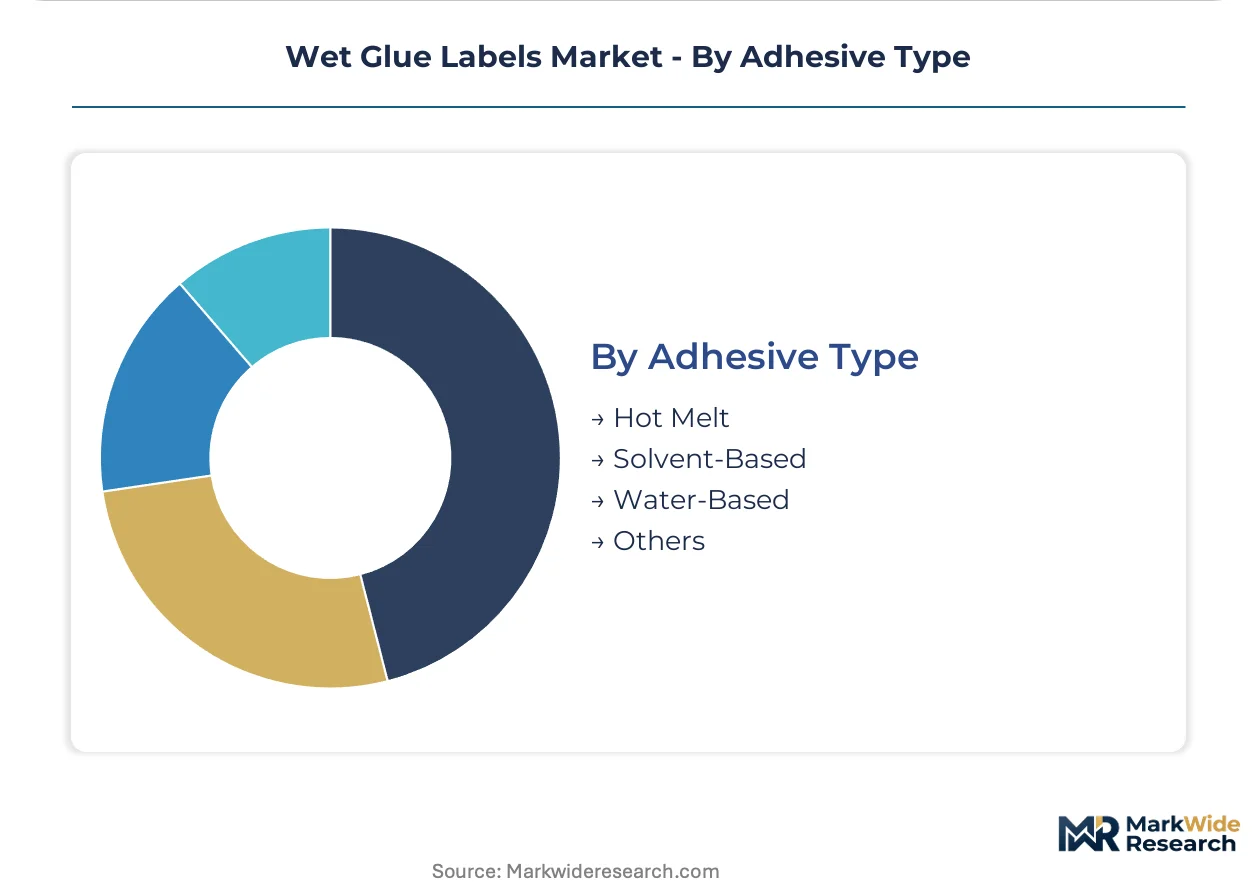
Adhesive Type:
Chemistry selection determines emission profiles, activation infrastructure, and line speed compatibility.
- Water-Based:Dominant chemistry for paper substrates with ECHA-driven elimination of formaldehyde and phthalate residuals. Extended qualification timelines are compressing supplier margins while elevating compliance costs.
- Solvent-Based:Superior adhesion to film substrates and glass under high-humidity conditions. EPA VOC emission controls add capital burden to US converting operations, constraining greenfield investment.
- Hot Melt:Thermoplastic formulations enabling rapid set times for high-speed rotary lines exceeding 60,000 bottles per hour.
- Others:Bio-based and UV-curable experimental chemistries responding to EU Green Deal recyclable packaging mandates.
Water-Based leads on installed base; bio-based alternatives within Others category show fastest development pipeline velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive chemists and rotary application engineers cluster in German industrial corridors and US Midwest converting hubs, anchoring wet glue label technical development. These talent concentrations shape regional procurement patterns and regulatory compliance capabilities.
Germany
Craft breweries in Bavaria and mineral water bottlers in the Rhön Mountains sustain high-volume wet glue procurement for premium glass aesthetics. REACH substance evaluations pressure formulators to eliminate formaldehyde residuals from water-based recipes. The Baden-Württemberg converting corridor hosts specialist firms qualifying bio-based adhesives for EU Green Deal compliance.
United States
Carbonated soft drink bottlers in the Southeast and craft beer producers in Colorado drive rotary system adoption exceeding 60,000 bottles per hour. EPA volatile organic compound regulations burden solvent-based adhesive operations with emission control capital requirements. Wisconsin and Ohio paper converting clusters specialize in FSC-certified stocks for beverage accounts.
France
Cosmetic houses in the Grasse fragrance cluster and Paris-region skincare formulators return to tactile glass packaging, opening high-margin wet glue demand. EFSA migration limits govern adhesive specification for food-contact applications. The Lyon industrial basin concentrates film substrate laminators serving pharmaceutical moisture-resistance requirements.
China
Domestic beverage brands in Guangdong and Zhejiang provinces expand wet glue procurement as premium glass packaging displaces plastic alternatives. GB standards for food-contact materials pressure adhesive formulators toward water-based system migration. The Yangtze River Delta hosts converting facilities integrating digital printing with high-speed application lines.
India
Pharmaceutical exporters in Hyderabad and Mumbai drive moisture-resistant film substrate adoption for prescription bottle exports to regulated markets. CDSCO label integrity requirements align with EMA and FDA standards for tamper-evident adhesion. The Gujarat chemical corridor supplies adhesive raw materials facing FSSAI food-contact compliance scrutiny.
Wet Glue Labels Market Competitive Environment
The competitive structure tilts toward substrate specialists and multi-continent converters with pharmaceutical-grade certifications. Three archetypes dominate: fiber-based paper stock specialists with forest stewardship credentials, film substrate laminators serving moisture-critical applications, and integrated converters bundling equipment-adhesive service contracts. Scale-driven capacity expansion and bio-based adhesive qualification partnerships represent the dominant competitive moves as regulatory timelines compress.
Among Nordic fiber specialists, Ahlstrom-Munksjö occupies a position exemplifying FSC-certified paper stock leadership for premium beverage accounts. CCL Industries anchors the multi-continent converter archetype with pharmaceutical-grade wet glue certification spanning regulatory jurisdictions. Multi-Color Corporation represents the equipment-integrated service model, specializing in high-speed rotary application systems for carbonated soft drink bottlers.
| Leading Market Players |
|---|
| Ahlstrom-Munksjö |
| Global Printing And Packaging Co. |
| CCL Industries |
| Optimum Group |
| Chromaprint India |
| All4Labels |
| Sappi |
| Huhtamaki Oyj |
| Multi-Color Corporation |
| Others |
Value Chain & Pricing Dynamics
Multinational beverage group procurement consolidation is compressing supplier margins through volume-tender aggregation, forcing converters to absorb REACH compliance costs or exit European qualification pools. This demand-side concentration rewards scaled players with bundled equipment-adhesive service contracts while fragmenting unbundled spot suppliers.
Pricing Analysis
Bundled equipment-adhesive service contracts dominate carbonated soft drink procurement, while unbundled spot transactions persist among regional craft breweries. Three-tier pricing structure across FSC-certified premium stocks, standard paper grades, and economy non-certified substrates reflects certification grade and volume scale differentiation. Cost compression in economy tiers is intensifying because cooperative buying groups now dictate adhesive specifications in German mineral water segments. Mid-scale beverage distributors exhibit highest price sensitivity; pharmaceutical-grade film buyers demonstrate lowest sensitivity due to moisture-resistance specification rigidity.
Supply Chain Analysis
REACH and FDA food-contact certification gating restricts adhesive formulation supply to qualified German, US, and Chinese converting clusters. Raw material dependencies center on wood pulp for FSC-certified paper stocks, petroleum-derived polymers for film substrates, and bio-based resin feedstocks for Green Deal-compliant adhesives. Single-source vulnerability concentrates in specialty adhesive chemist talent pools anchored in Baden-Württemberg and Wisconsin corridors. Distribution runs through multinational beverage group procurement hubs, cooperative buying groups, and pharmaceutical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Wet Glue Labels Market functions as a stable compounder anchored by irreplaceable glass packaging aesthetics in premium beverage and personal care segments. Regulatory tailwinds from EU Green Deal mandates sustain bio-based adhesive reformulation investment cycles.
For Market Incumbents: Extend qualification pool dominance by accelerating bio-based adhesive partnerships in the Baden-Württemberg corridor and locking in FSC-certified pulp supply through backward integration into Nordic fiber networks. Rotary application system bundling with adhesive supply contracts defends against unbundled spot competitors. For New Entrants and Emerging Players: EU Green Deal packaging directives in Germany open a window for bio-based adhesive specialists to penetrate craft brewery cooperative buying groups displaced from direct supplier relationships. Target personal care glass packaging pivots in the Grasse fragrance cluster with moisture-resistant film substrate laminations. Lead with digital printing integration enabling mass customization for regional beverage launches. For Investors and Strategic Acquirers: Asymmetric upside sits with film substrate laminators possessing pharmaceutical-grade certifications spanning EMA and FDA jurisdictions. Five-to-ten-year viability rests on moisture-resistance specification tightening in prescription bottle labeling. Watch for CDSCO alignment with EMA standards as inflection signal for Indian pharmaceutical export demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Based Adhesive Qualification Partnership | REACH compliance in EU Green Deal frameworks locks in premium beverage procurement relationships. |
| Rotary Application System Bundling | Equipment-adhesive service contracts consolidate supplier relationships with carbonated soft drink bottlers exceeding 60,000 bottles per hour. |
| FSC-Certified Pulp Supply Integration | Forest Stewardship Council chain-of-custody certification gates procurement for premium mineral water and craft beer accounts. |
| Film Substrate Lamination Capacity Addition | Moisture-resistant pharmaceutical-grade construction addresses EMA and FDA label integrity requirements. |
| Digital Printing Platform Integration | Mass customization capability compresses minimum order quantities for regional beverage launch cycles. |
Study Parameters
Multiple input streams — adhesive formulation specialists, beverage procurement directors, pharmaceutical packaging engineers, and converting facility managers — were reconciled with secondary validation from ECHA substance evaluation databases, EPA VOC emission filings, and FSC chain-of-custody certification records. Bottom-up production capacity assessments across German, US, and Chinese converting corridors were triangulated against top-down demand modeling from beverage bottler capex disclosures and pharmaceutical packaging spend patterns.
Data-stream reconciliation anchored volume and value outputs across the projection horizon. Segmentation dimensions modeled include substrate chemistry, adhesive activation mechanism, container geometry, and end-use regulatory exposure. CAGRs were derived from installed base growth rates, line speed threshold adoption curves, and bio-based adhesive qualification timeline compression. Industry-specific forecast inputs incorporated rotary application system deployment rates and REACH substance evaluation schedule impacts.
Revisions become necessary when EU Green Deal packaging directive implementation timelines accelerate, bio-based adhesive performance parity milestones shift, or multinational beverage group procurement consolidation patterns alter. A model refresh is warranted upon material change in ECHA formaldehyde residual limit enforcement or FDA food-contact adhesive specification updates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Extended Text Labels Market
Labels
Freezer Label Market
Labels
HAZMAT Labels Market
Labels
Roll-fed Wraparound Label Substrates Market
Labels
Print Label Market
Labels
Oxygen Indicator Labels Market
Labels
Domed Labels Market
Labels
Global Automotive Labels Market
Labels
Coated Wet Glue Label Market
Labels
Foil Labels Market
Labels
Water Dissolvable Labels Market
Labels
Warning Labels and Stickers Market
Labels
Shrink Sleeve Labels Market
Labels
Hang Tags Market
Labels
Barcode Label Printer Market
Labels
Asia-Pacific Self-Adhesive Labels Market