
 Domed Labels Market | 2026-2036
Domed Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Domed Labels Market Outlook
Maintenance subscription programs for label durability certification is consolidating supplier relationships across the value chain. 3M Company leverages its materials science portfolio to anchor premium positioning in automotive and industrial segments. Avery Dennison competes through extensive geographic reach and digital printing integration. NFI Corp. specializes in custom-engineered domed solutions for medical device and electronics branding requirements.
Domed labels are three-dimensional graphic overlays created by dispensing clear polyurethane or epoxy resin over printed substrates, producing a raised lens effect that enhances durability, chemical resistance, and tactile brand presence. The manufacturing process involves precision-controlled resin dispensing with cure times calibrated to substrate type, typically achieving Shore A hardness ratings between 80 and 95 for industrial applications. Polycarbonate substrates dominate product branding applications due to optical clarity and impact resistance, while vinyl formulations sustain growth in outdoor industrial marking where flexibility and cost efficiency matter. Digital printing technology leads technology segmentation for short-run customization, though screen printing retains margin pools in high-volume automotive identification programs.
EPA guidelines on volatile organic compound emissions shape resin formulation choices for US-based manufacturers, while REACH restrictions on isocyanate content in Europe constrain raw material sourcing for polyurethane doming systems. FDA labeling requirements for medical devices and durable goods create compliance thresholds that filter supplier capabilities in healthcare end-use segments. Stakeholders must monitor evolving chemical safety standards across multiple jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
REACH compliance in Europe is tightening material specifications for polyurethane resins, forcing reformulation investments across the domed labels supply chain while concentrating procurement among qualified suppliers.
Growth Catalysts
- Automotive OEM branding mandates:German automotive suppliers around Stuttgart and Munich are specifying domed labels for durable exterior identification, creating volume pull for Shore A 85+ hardness formulations.
- EPA VOC emission guidelines:US manufacturers are accelerating low-VOC resin adoption ahead of enforcement timelines, filtering the supplier base toward compliant coating systems.
- Digital printing convergence:Short-run customization demand from medical device branding programs is compressing minimum order quantities and expanding addressable job sizes.
Market Restraints
- Isocyanate supply concentration:REACH restrictions on isocyanate content in Europe constrain raw material sourcing to a narrow qualified supplier base, creating input cost volatility.
- Epoxy substitution threat:Lower-cost epoxy doming systems are capturing price-sensitive outdoor industrial marking applications where optical clarity requirements are relaxed.
- Cure time technical limitations:Polycarbonate substrate compatibility requires extended cure cycles that constrain throughput versus vinyl alternatives.
Strategic Opportunities
- Medical device certification white space:FDA labeling requirements for durable healthcare goods are creating compliance thresholds that filter out commodity suppliers.
- Maintenance subscription programs:Durability certification services are consolidating long-term supplier relationships and embedding vendors into OEM quality systems.
- Screen-digital hybrid workflows:Convergence of high-volume automotive programs with short-run customization is enabling margin capture across both volume tiers.
Industry Challenges
- Resin formulation skill scarcity:Polyurethane chemistry expertise for Shore hardness calibration is concentrating among legacy technicians with limited knowledge transfer pipelines.
- Multi-jurisdiction qualification timelines:Simultaneous EPA, REACH, and FDA compliance requirements are extending product launch cycles and freezing development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Domed Labels Market |
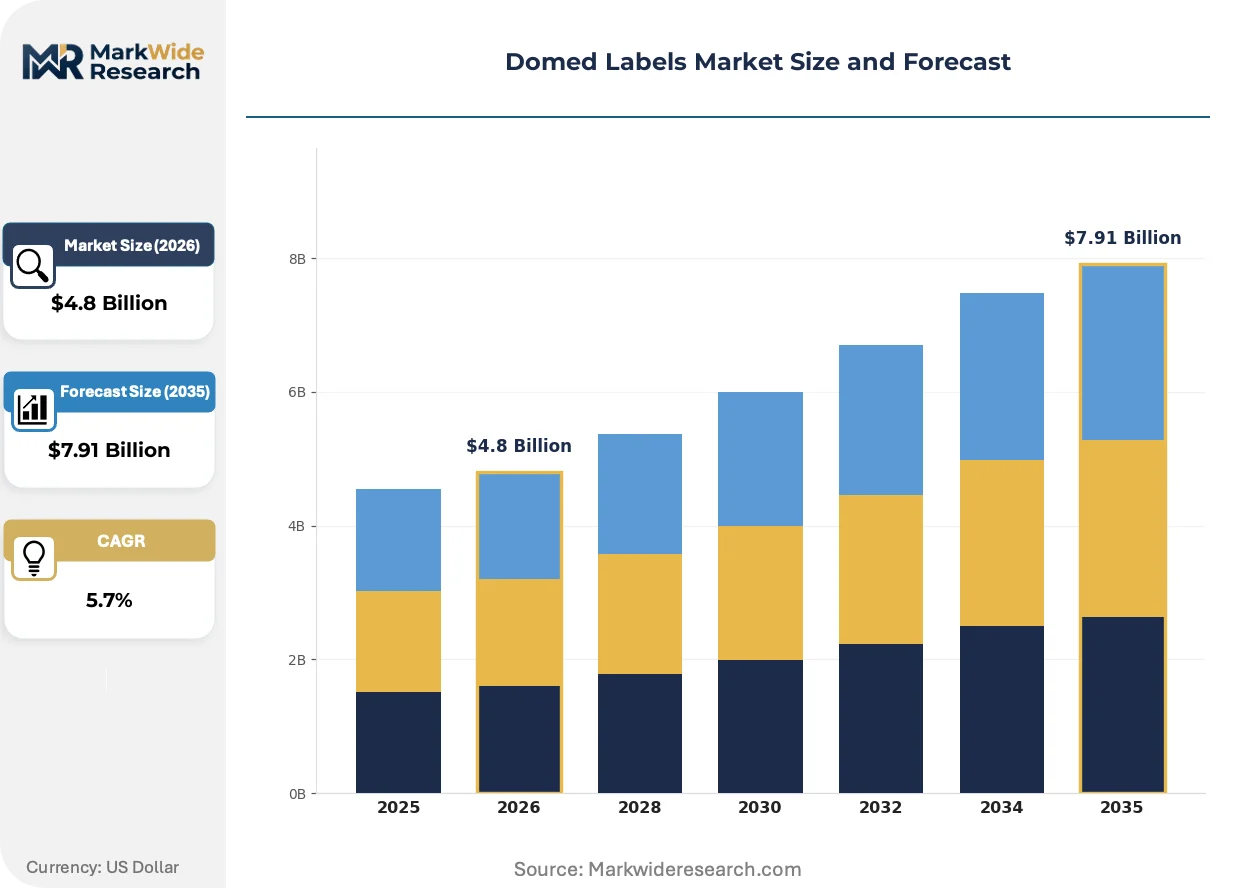
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polycarbonate, Acrylic, Polyester, Vinyl Application: Product Branding, Industrial Marking, Appliance Labeling, Automotive Identification End User: Manufacturers, Retailers, Logistics Companies, Healthcare Providers Technology: Digital Printing, Screen Printing, Offset Printing, Flexographic Printing |
| Companies Covered | Tailored Label Products, Trident Solutions, NFI Corp., 3M Company, Prynт Group, Lustre-Cal LLC, Maverick Label, Avery Dennison, Advanced Labelworx, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Domed Labels Market Strategic Shifts
Precision resin dispensing systems are compressing cure-time variability while regulatory chemistry constraints are forcing material science investments across the value chain.
Automated vision-guided dispensing equipment is automating bead placement accuracy to within 0.1mm tolerance, eliminating manual operator dependency. Tier 1 automotive suppliers in Germany are adopting these systems at replacement cycle pace to meet OEM zero-defect protocols. This is automating quality consistency while compressing labor cost structures in high-volume programs.
REACH Annex XVII restrictions on isocyanate monomer content are forcing aliphatic polyurethane formulation shifts across European production facilities. Industrial coating manufacturers are qualifying alternative curative systems ahead of 2025 enforcement windows. Medical device labeling applications face the steepest requalification burdens due to biocompatibility re-certification requirements.
After-sales durability certification is unbundling from product supply and migrating to subscription-based verification models. Automotive OEMs in Germany's supplier corridor are contracting multi-year label performance guarantees separate from initial procurement. This behavioral shift is most visible in Stuttgart-area manufacturing clusters where supplier consolidation programs favor embedded service relationships.
Domed Labels Market Segmentation
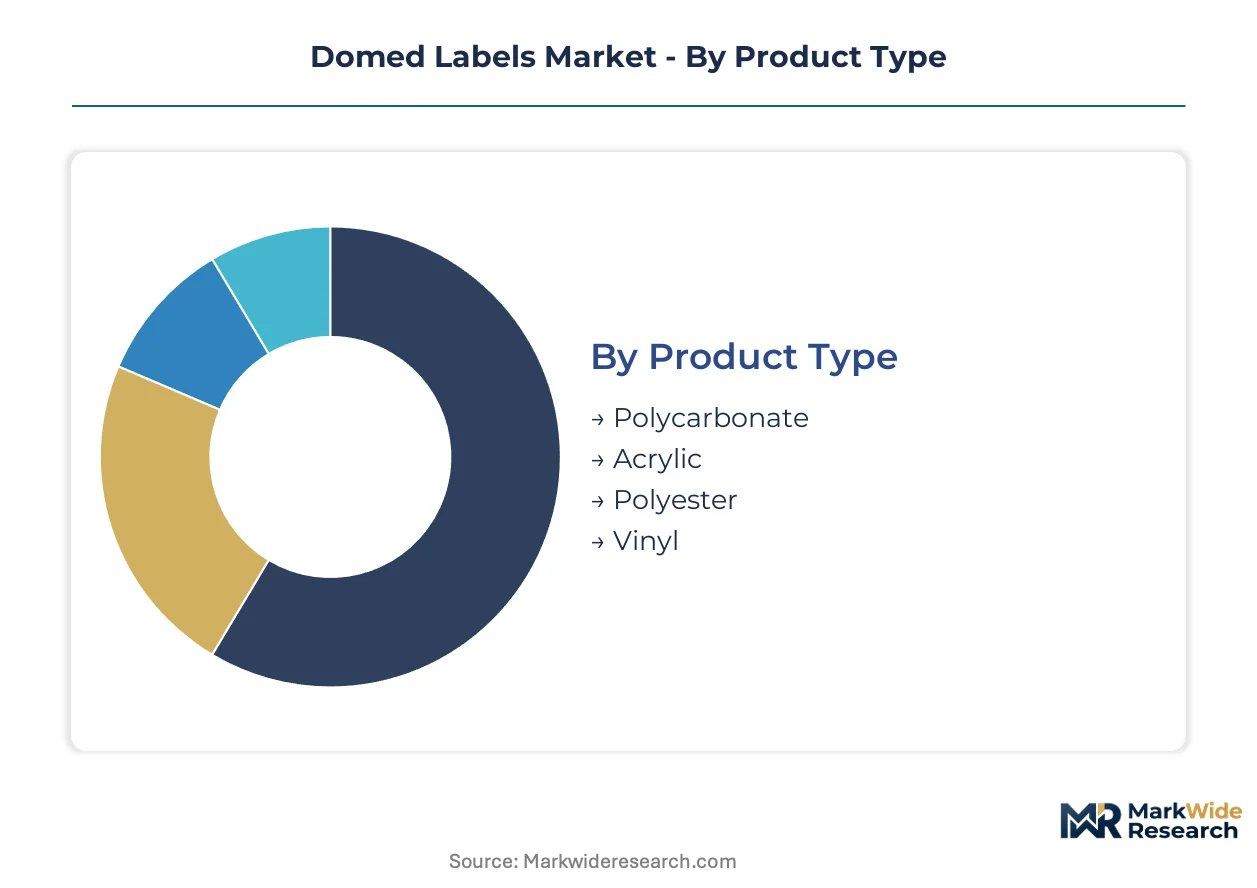
Domed labels serve both standalone branding applications and embedded identification systems, with substrate choice and printing technology determining integration depth across industrial supply chains. Segmentation reveals where technical specifications create vendor lock-in versus commodity substitution risk.
Product Type:
Substrate selection maps directly to integration architecture—optical-grade materials anchor premium embedded systems while flexible films serve standalone outdoor applications.
- Polycarbonate:Optical clarity and impact resistance make this the default for automotive identification programs requiring zero-defect protocols. German OEMs around Stuttgart specify polycarbonate domed labels for exterior badging where Shore A 85+ hardness must survive thermal cycling.
- Vinyl:Cost-efficient flexibility dominates outdoor industrial marking where substrate conformability matters more than optical precision. Logistics companies in the US specify vinyl formulations for container tracking labels exposed to weathering and mechanical abrasion.
- Acrylic:UV stability and surface hardness suit premium product branding in consumer electronics where tactile brand presence commands shelf differentiation.
- Polyester:Chemical resistance and dimensional stability anchor appliance labeling programs where detergent and solvent exposure is routine.
Volume placements concentrate in vinyl; the faster expansion belongs to polycarbonate.
Application:
Application segmentation tracks durability requirements from cosmetic branding to mission-critical identification under regulatory scrutiny.
- Automotive Identification:Exterior and under-hood labeling must survive thermal shock, fluid exposure, and mechanical abrasion across vehicle lifespans. Tier 1 suppliers in Germany's automotive corridor specify domed labels with 10-year durability guarantees for VIN plates and component tracking.
- Product Branding:Consumer goods and electronics leverage the tactile lens effect for shelf differentiation and premium positioning. Medical device manufacturers face FDA labeling requirements that filter commodity suppliers from durable healthcare goods programs.
- Industrial Marking:Asset tags and safety warnings in manufacturing environments prioritize chemical resistance and legibility degradation schedules.
- Appliance Labeling:White goods and HVAC equipment require substrate stability through temperature cycling and cleaning agent exposure.
Revenue concentration sits with automotive identification; product branding climbs fastest on medical device certification demand.
End User:
Procurement sophistication varies sharply—OEM quality systems embed suppliers while logistics operators treat labels as consumable spend.
- Manufacturers:Automotive and electronics OEMs drive specification complexity through zero-defect protocols and multi-year durability guarantees. Maintenance subscription programs for label certification are consolidating supplier relationships among German automotive producers.
- Healthcare Providers:FDA compliance thresholds for medical device labeling filter out generalist converters, creating white space for qualified specialists.
- Retailers:Private-label branding programs demand short-run customization with compressed lead times.
- Logistics Companies:Asset tracking applications prioritize cost efficiency and weather resistance over optical precision.
Procurement volume clusters with manufacturers; healthcare providers represent the steepest expansion trajectory on regulatory compliance barriers.
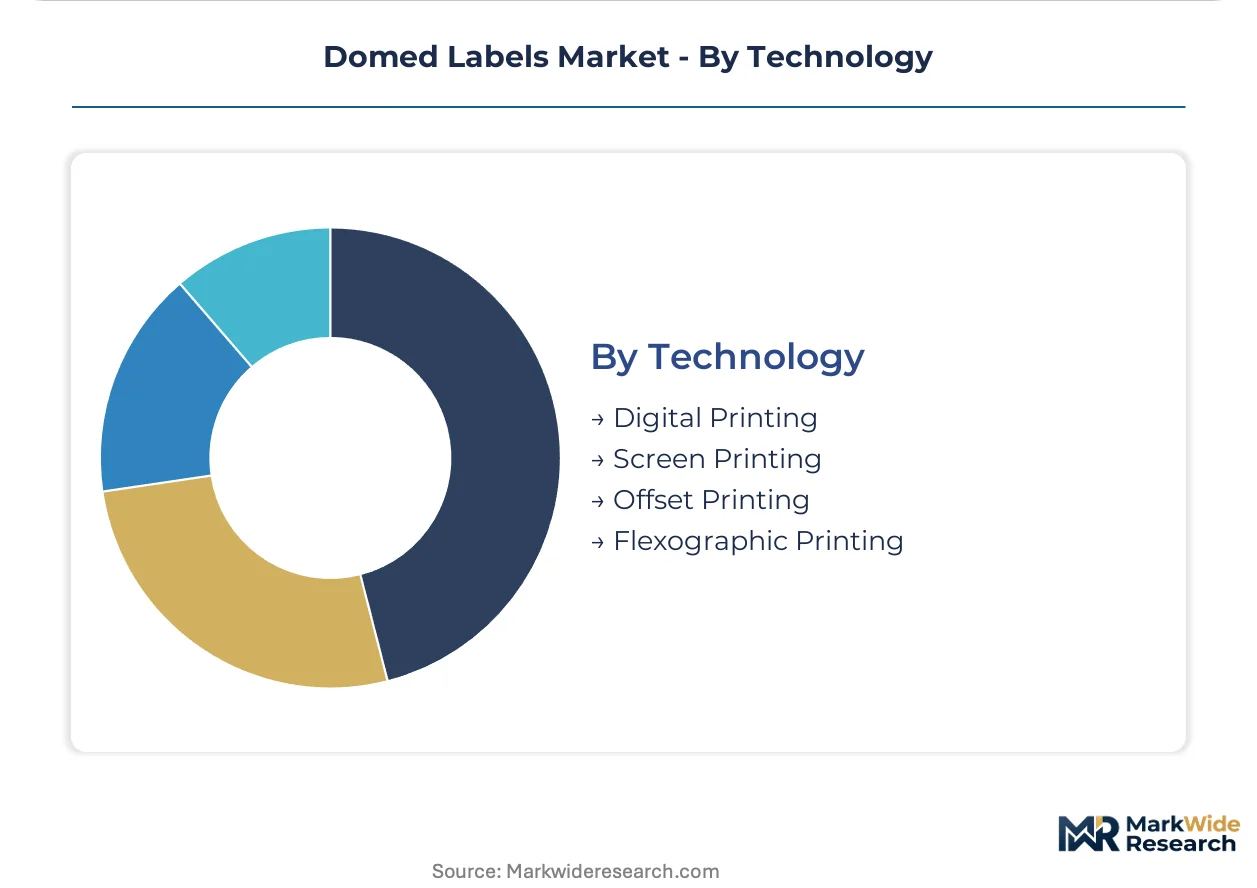
Technology:
Printing technology segmentation separates high-volume automotive programs from short-run customization markets with incompatible equipment economics.
- Digital Printing:Variable data capability and zero plate costs enable lot-size-one production for medical device branding and promotional programs. Digital workflows are compressing minimum order quantities across healthcare and retail segments.
- Screen Printing:Ink film thickness and color saturation retention dominate high-volume automotive identification where Pantone matching and durability specifications are non-negotiable.
- Flexographic Printing:Roll-to-roll efficiency serves label converters feeding high-speed applicators in beverage and consumer goods packaging.
- Offset Printing:Fine detail reproduction and color consistency anchor premium product branding for cosmetics and electronics.
Screen printing holds the volume base; digital printing gains share fastest on customization demand from healthcare and retail segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany's automotive supplier corridor while consumption spreads across industrialized economies with stringent durability requirements. Manufacturing gravitates toward regions with established coating chemistry expertise and OEM proximity. Demand fragmentation follows automotive, medical device, and industrial asset tracking applications.
Germany
Tier 1 automotive suppliers around Stuttgart and Munich specify Shore A 85+ hardness domed labels for exterior badging and VIN plate applications. ECHA REACH Annex XVII restrictions on isocyanate content force aliphatic polyurethane reformulation across Baden-Württemberg production facilities. Stuttgart-area manufacturing clusters embed suppliers into multi-year durability guarantee contracts separate from initial procurement.
United States
Medical device manufacturers in Minnesota and Massachusetts drive FDA-compliant labeling demand for durable healthcare goods. EPA guidelines on volatile organic compound emissions accelerate low-VOC resin adoption ahead of enforcement timelines. Logistics operators in the Midwest specify vinyl formulations for container tracking labels exposed to weathering and mechanical abrasion.
China
Consumer electronics OEMs in the Yangtze River Delta leverage domed labels for premium product branding and tactile shelf differentiation. GB standards for chemical safety in industrial coatings shape resin formulation choices for domestic manufacturers. Shenzhen and Dongguan production clusters serve export-oriented electronics assembly with compressed lead time requirements.
Japan
Automotive and electronics manufacturers in the Kanto and Kansai regions demand zero-defect protocols for embedded identification systems. METI industrial standards for chemical substance management influence polyurethane sourcing decisions. Nagoya-area automotive suppliers specify polycarbonate substrates for under-hood labeling surviving thermal shock and fluid exposure.
United Kingdom
Pharmaceutical and medical device producers in the Southeast contract specialized converters for FDA-equivalent MHRA compliance. UK REACH adoption maintains chemical safety alignment with European restrictions post-Brexit. Cambridge and Oxford medical technology clusters filter commodity suppliers through biocompatibility certification requirements.
Domed Labels Market Competitive Environment
Top-tier vendors anchor premium automotive and medical device segments, while mid-scale converters compete on short-run customization and geographic reach. The supplier base stratifies across materials science conglomerates, specialized coating converters, and digital printing integrators. Three archetypes dominate: diversified materials portfolios, custom-engineered solutions, and high-volume automotive programs. Consolidation concentrates among qualified REACH-compliant suppliers, while strategic partnerships embed vendors into OEM quality systems.
Within the diversified materials tier, 3M Company and Avery Dennison occupy positions leveraging broad technology portfolios and extensive geographic footprints. NFI Corp. exemplifies the custom-engineered specialist archetype, anchoring medical device and electronics branding requirements where FDA compliance thresholds filter generalist competitors. These three entities represent the competitive spectrum from scale-driven standardization to qualification-intensive specialization.
| Leading Market Players |
|---|
| Tailored Label Products |
| Trident Solutions |
| NFI Corp. |
| 3M Company |
| Prynт Group |
| Lustre-Cal LLC |
| Maverick Label |
| Avery Dennison |
| Advanced Labelworx |
| Others |
Value Chain & Pricing Dynamics
Polyurethane resin costs cascade through three pricing tiers, with aliphatic formulations for REACH-compliant European automotive programs commanding premiums over commodity aromatic systems serving vinyl-based outdoor marking applications.
Pricing Analysis
Margin tightening in polycarbonate substrate tiers reflects isocyanate supply concentration and extended cure-cycle throughput penalties. Three-tier pricing structure across premium, standard, and economy levels separates FDA-certified medical device programs from automotive identification volumes and logistics-grade vinyl marking. Pricing pressure intensifies in standard-tier automotive supply as epoxy substitution threats capture outdoor industrial applications. Logistics operators exhibit highest price sensitivity; German OEMs embedded in multi-year durability guarantee contracts show lowest.
Supply Chain Analysis
Return flows of defective domed labels from automotive OEM quality gates feed back into resin requalification cycles, compressing formulation iteration timelines. Supply concentrates in Germany, the United States, and China. Raw material sourcing draws from isocyanate monomer producers, polycarbonate film extruders, and digital ink formulators. Single-source vulnerability in European aliphatic polyurethane curatives creates qualification bottlenecks. Distribution runs through Tier 1 automotive supplier networks and specialized medical device converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance deadlines and FDA requalification burdens are consolidating the supplier base, eliminating generalist converters lacking formulation chemistry depth and multi-jurisdiction certification resources.
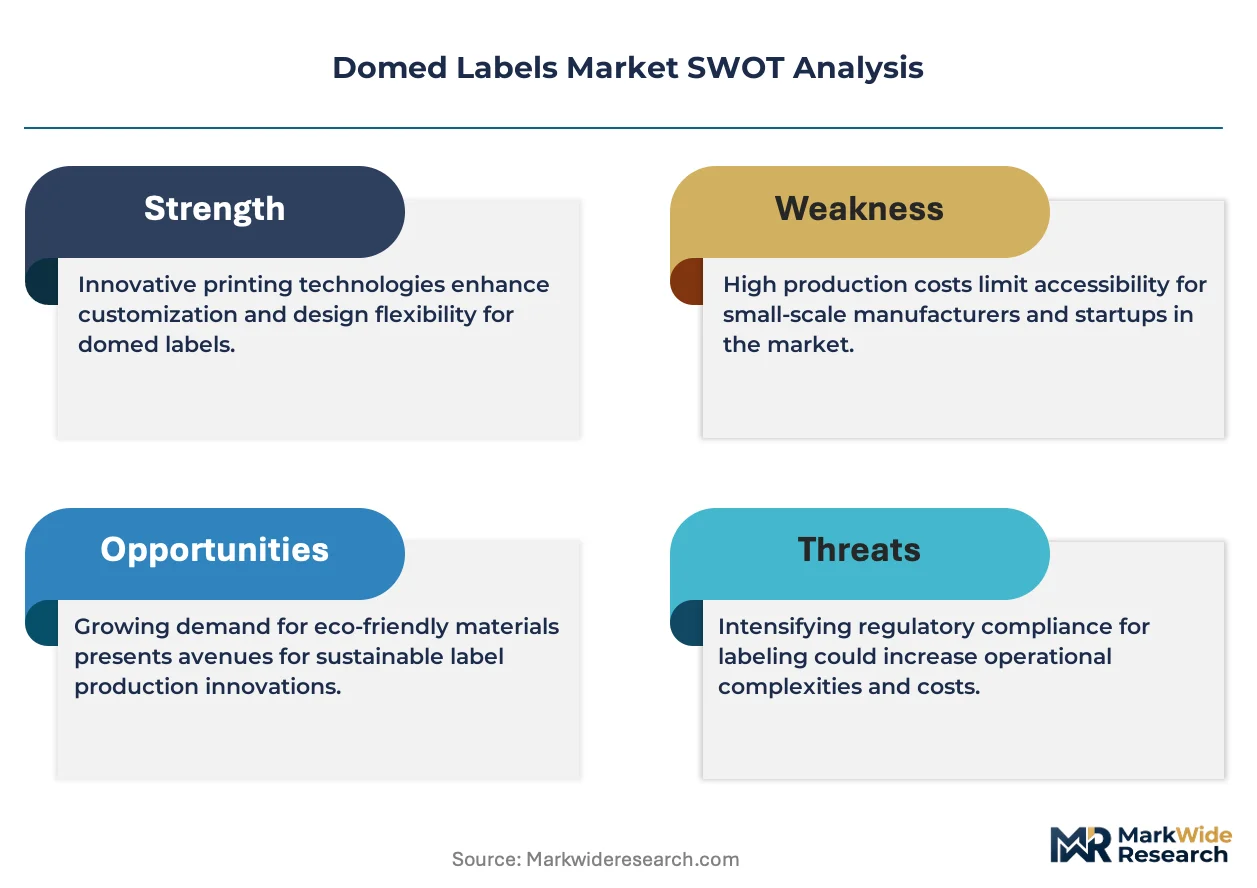
For Market Incumbents: Anticipate epoxy substitution threats in outdoor industrial marking by anchoring polycarbonate automotive programs through embedded durability subscription services. Deepen backward integration into aliphatic polyurethane resin production to secure REACH-compliant supply. Certify alternative curative systems ahead of enforcement windows to freeze out reformulation-lagged competitors. For New Entrants and Emerging Players: Medical device OEMs in Minnesota and Massachusetts represent the most penetrable buyer archetype, as FDA compliance thresholds filter commodity suppliers from durable healthcare goods programs. Target short-run digital customization for healthcare branding applications where lot-size-one production commands premium positioning. Pursue white-label partnerships with established coating converters to bypass multi-year qualification timelines. For Investors and Strategic Acquirers: Aliphatic polyurethane qualification announcements from European production facilities are the leading indicator that supplier consolidation is accelerating. Five-to-ten year viability favors specialized converters with captive resin formulation expertise and embedded OEM quality system relationships. Monitor ECHA enforcement actions and FDA warning letters as inflection signals for acquisition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aliphatic Polyurethane Qualification | REACH Annex XVII compliance secures European automotive supply relationships against reformulation-lagged competitors. |
| Durability Subscription Unbundling | After-sales certification services embed suppliers into German OEM multi-year performance guarantee contracts. |
| Screen-Digital Hybrid Workflow Investment | Converged production captures margin across high-volume automotive programs and short-run medical device customization. |
| Vision-Guided Dispensing Automation | Automated bead placement to 0.1mm tolerance meets Stuttgart-area zero-defect protocols while compressing labor costs. |
| FDA Biocompatibility Re-Certification | Medical device labeling requalification filters commodity converters, creating white space for qualified specialists. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, triangulated with primary interviews across coating chemists, automotive Tier 1 procurement managers, medical device regulatory affairs leads, and label converter operations directors. ECHA REACH substance restriction notifications, EPA VOC emission guidelines, and FDA 510(k) labeling submissions provided compliance trajectory validation. Bottom-up production capacity estimates and top-down end-use demand modeling reconciled volume figures.
Data-stream reconciliation across shipment records, resin import declarations, and OEM specification documents informed the analytical framework. Segmentation dimensions modeled include substrate material, printing technology, application durability tier, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to qualified supplier capacity expansion and end-use program win rates. Shore hardness calibration expertise scarcity and cure-time automation adoption curves served as industry-specific forecast inputs.
Revisions become necessary when REACH enforcement timelines accelerate, FDA biocompatibility requirements expand, or epoxy substitution rates in outdoor marking exceed baseline assumptions. Forecasts reflect documented assumptions regarding aliphatic polyurethane supply qualification success rates and German automotive program retention patterns. Practitioners should monitor ECHA substance restriction amendments and OEM durability guarantee contract renewal rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Screen Print Label Market
Labels
Global Thermal Transfer Label Market
Labels
Stand Alone Label Applicator Market
Labels
Global Waterproof Labels Market
Labels
Global Tamper Evident Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Variable Data Printing Labels Market
Labels
Europe Self Adhesives Label Market
Labels
Canning Labels Market
Labels
Wet Glue Labeling Machines Market
Labels
Sleeve Label Market
Labels
Global Automotive Labels Market
Labels
Time Temperature Indicator Labels Market
Labels
Water Dissolvable Labels Market
Labels
Repositionable Labels Market
Labels
Print Label Market