
 Time Temperature Indicator Labels Market | 2026-2036
Time Temperature Indicator Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Time Temperature Indicator Labels Market Outlook
Pharmaceutical distributors and biologics manufacturers is rotating toward time temperature indicator labels as the fastest-growing buyer archetype in cold chain verification. 3M Company leverages its materials science portfolio to sustain adhesive performance across extreme thermal ranges. CCL Industries anchors North American label supply through specialized pharmaceutical printing capabilities. Sensitech Inc. differentiates via integrated software-hardware platforms that extend beyond passive indication into real-time tracking.
Time temperature indicator labels are adhesive or tag-based devices that undergo irreversible color change or electronic signal generation when cumulative thermal exposure exceeds calibrated thresholds, typically manufactured through microencapsulation of thermochromic dyes or thin-film semiconductor deposition. Their primary commercial purpose is to provide tamper-evident documentation of temperature breach events across pharmaceutical, food, and logistics supply chains. Self-adhesive labels dominate volume due to compatibility with existing packaging lines, while electronic sensors command premium positioning in high-value pharmaceutical lanes where data logging replaces visual inspection. Cold chain management applications represent the deepest margin pool as pharmaceutical shippers absorb higher unit costs for compliance-grade documentation.
The FDA enforces pharmaceutical distribution documentation through the Drug Supply Chain Security Act, compelling serialization and temperature verification at each custody transfer. WHO guidelines on vaccine handling establish international benchmarks that national regulators in Germany through the BfArM and in Japan through PMDA transpose into binding cold chain protocols. EMA's Good Distribution Practice requirements for medicinal products mandate auditable temperature records, directly expanding label attach rates across European pharmaceutical logistics. Stakeholders must monitor regulatory divergence between electronic data logging mandates and passive indicator acceptance as jurisdictions update pharmacopeial standards.

Market Dynamics
Biologics manufacturers are absorbing compliance-grade label costs at three to five times the attach rate of generic pharmaceutical distributors, compressing margin pools toward cold chain verification specialists while passive indicator volumes stagnate.
Growth Catalysts
- FDA Drug Supply Chain Security Act:Serialization mandates at custody transfer points force pharmaceutical distributors to attach tamper-evident temperature documentation, expanding label consumption per shipment.
- Microencapsulated thermochromic dyes:Advances in dye stability across extended thermal ranges enable single-use labels to replace reusable data loggers in last-mile vaccine distribution.
- Germany's pharmaceutical manufacturing clusters:BfArM enforcement of EMA Good Distribution Practice creates concentrated demand for auditable temperature records across Rhine-Ruhr logistics corridors.
Market Restraints
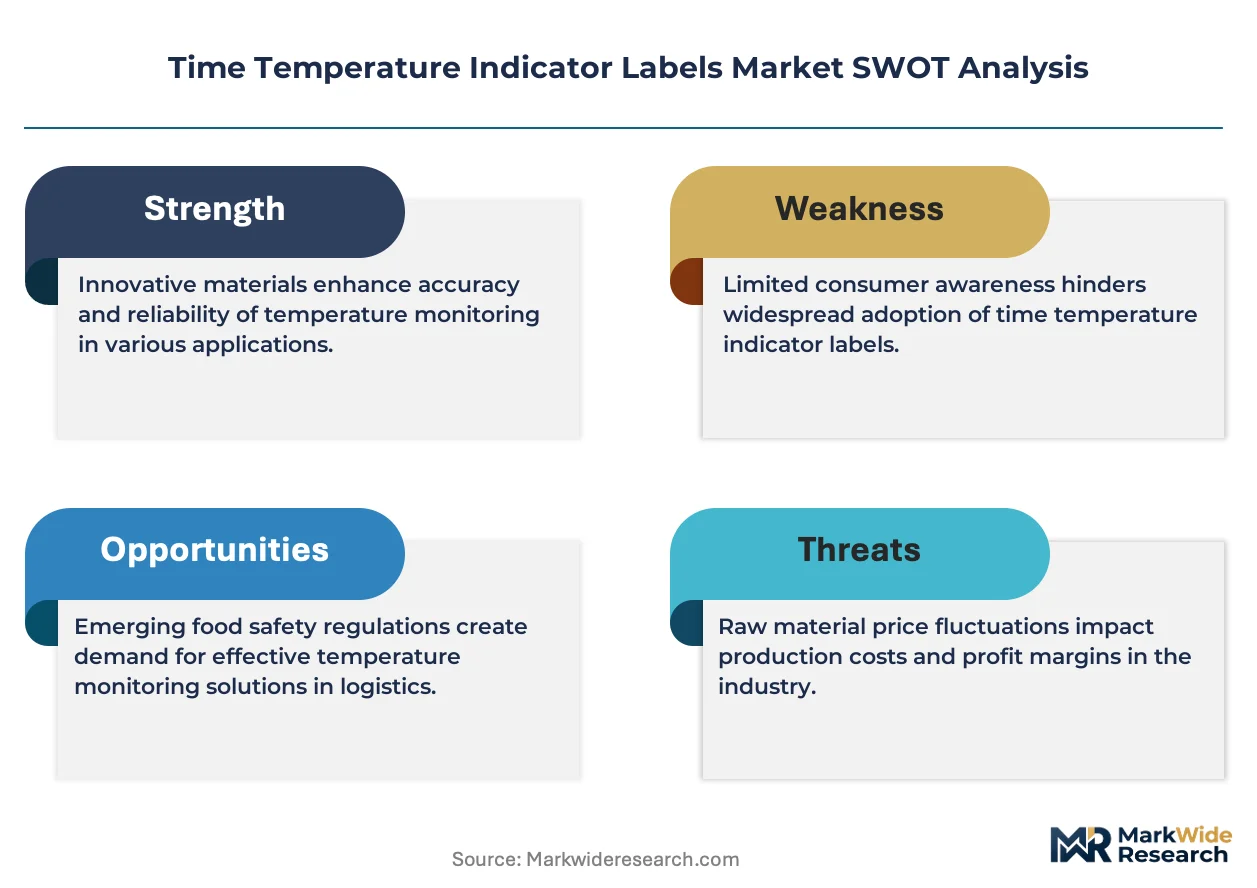
- Adhesive raw material volatility:Acrylic polymer feedstock prices fluctuate with petrochemical markets, squeezing converter margins on self-adhesive label production.
- Thin-film semiconductor deposition:Electronic sensor manufacturing requires specialized capital equipment that concentrates supply among three to four East Asian equipment vendors.
- Passive indicator regulatory friction:WHO guidelines increasingly favor electronic data logging for vaccine shipments, threatening visual-only label acceptance in national immunization programs.
Strategic Opportunities
- Japan's regenerative medicine expansion:PMDA cell therapy approvals are multiplying, creating demand for ultra-low temperature indicators in cryogenic logistics.
- Real-time tracking convergence:Integration of NFC-enabled labels with blockchain custody records opens premium positioning in high-value biologics lanes.
- Direct-to-patient pharmacy channels:Specialty pharmacies shipping temperature-sensitive therapies to homes require consumer-readable breach indicators outside traditional wholesale networks.
Industry Challenges
- Calibration technician scarcity:Electronic sensor production requires thin-film deposition specialists whose training pipelines lag demand expansion.
- Multi-jurisdiction certification timelines:Separate BfArM, PMDA, and FDA validation studies for the same indicator chemistry extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Time Temperature Indicator Labels Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-adhesive Labels, Digital Indicators, Ink-based Indicators, Tag-type Indicators Technology: Thermochromic, Time-Temperature Integrators, Electronic Sensors, Color-changing Inks Application: Food Safety, Pharmaceutical Storage, Logistics Monitoring, Cold Chain Management End User: Healthcare Providers, Food Manufacturers, Logistics Companies, Retailers |
| Companies Covered | Zebra Technologies Corp., CCL Industries, 3M Company, Delta Trak, Temptime Corporation, Sensitech Inc., Avery Dennison, Insignia Technologies, SpotSee, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Time Temperature Indicator Labels Market Strategic Shifts
Active sensing technologies are compressing the boundary between passive indicators and connected devices, forcing label converters to choose between hardware partnerships or margin erosion.
Printed electronics using conductive ink patterns on flexible substrates is displacing conventional microencapsulated dye systems in pharmaceutical cold chain monitoring. Biologics shippers with temperature excursions exceeding $50,000 per pallet are adopting these hybrid formats fastest. The shift is displacing pure-play passive indicator vendors from premium lanes and concentrating margin capture among converters with in-house printed circuit integration.
EMA's updated Good Distribution Practice guidance now explicitly requires time-stamped temperature records for all investigational medicinal products entering European clinical trial supply chains. This tightens documentation standards that previously accepted visual-only indicators for Phase I materials. Germany and the Netherlands are seeing the fastest compliance retrofitting as their clinical logistics hubs handle the highest volume of cross-border trial shipments.
Specialty pharmacies now bundle temperature verification as a patient-facing service rather than treating labels as back-end compliance overhead. This reframes indicator selection around consumer readability and smartphone integration rather than wholesale audit trails. The behavioral shift is most visible in United States oncology and rare disease therapeutic categories where patient self-administration is standard.
Time Temperature Indicator Labels Market Segmentation

Segmentation in time temperature indicator labels reveals divergent margin structures across passive visual formats and electronic data-logging systems. Pharmaceutical cold chain compliance is compressing attach rates toward premium technologies while food safety applications sustain high-volume, lower-unit-cost production.
Product Type:
Premium positioning concentrates in electronic formats where biologics shippers absorb fivefold unit cost multiples over passive alternatives.
- Self-adhesive Labels:Microencapsulated thermochromic dyes on pressure-sensitive acrylic backings dominate pharmaceutical packaging line integration. Demand clusters in Germany's Rhine-Ruhr logistics corridors where BfArM enforcement of EMA Good Distribution Practice mandates tamper-evident documentation at custody transfer points.
- Digital Indicators:Thin-film semiconductor deposition enables NFC-enabled data logging with blockchain custody integration. Japan's PMDA cell therapy approvals are multiplying demand for ultra-low temperature tracking in cryogenic regenerative medicine logistics.
- Ink-based Indicators:Printed conductive patterns on flexible substrates serve cost-sensitive food distribution networks.
- Tag-type Indicators:Suspended formats attach to pallet-level shipments without surface adhesion requirements.
The dominant share belongs to Self-adhesive Labels, while Digital Indicators is closing the gap fastest.
Technology:
Cost tiering separates mature dye chemistry from capital-intensive semiconductor manufacturing with divergent margin profiles.
- Thermochromic:Reversible and irreversible leuco dye systems calibrated to specific thermal thresholds through microencapsulation. FDA Drug Supply Chain Security Act serialization mandates are expanding attach rates across United States pharmaceutical wholesale networks.
- Time-Temperature Integrators:Cumulative exposure measurement via enzymatic or chemical reaction kinetics. WHO vaccine handling guidelines are tightening acceptance standards for visual-only indicators in national immunization programs.
- Electronic Sensors:Real-time temperature logging with cloud connectivity and audit trail generation.
- Color-changing Inks:Consumer-readable breach indication for direct-to-patient pharmacy channels.
Thermochromic systems retain volume leadership, though Electronic Sensors is climbing the fastest as data logging replaces visual inspection in high-value lanes.
Application:
Customer type determines specification intensity, with pharmaceutical shippers demanding calibration certificates that food distributors rarely require.
- Pharmaceutical Storage:Compliance-grade documentation for investigational medicinal products with EMA-mandated time-stamped temperature records. Germany and the Netherlands are seeing the fastest compliance retrofitting as clinical logistics hubs handle cross-border trial shipments.
- Cold Chain Management:Integrated hardware-software platforms extending beyond passive indication into real-time tracking with excursion alerts. United States specialty pharmacies now bundle verification as patient-facing services in oncology and rare disease categories.
- Food Safety:Mass-market indicators for perishable supply chains with lower documentation thresholds.
- Logistics Monitoring:Multi-modal shipment tracking across air, ocean, and ground transportation modes.
Pharmaceutical Storage commands the deepest margin pool, while Cold Chain Management is gaining share fastest through platform integration.
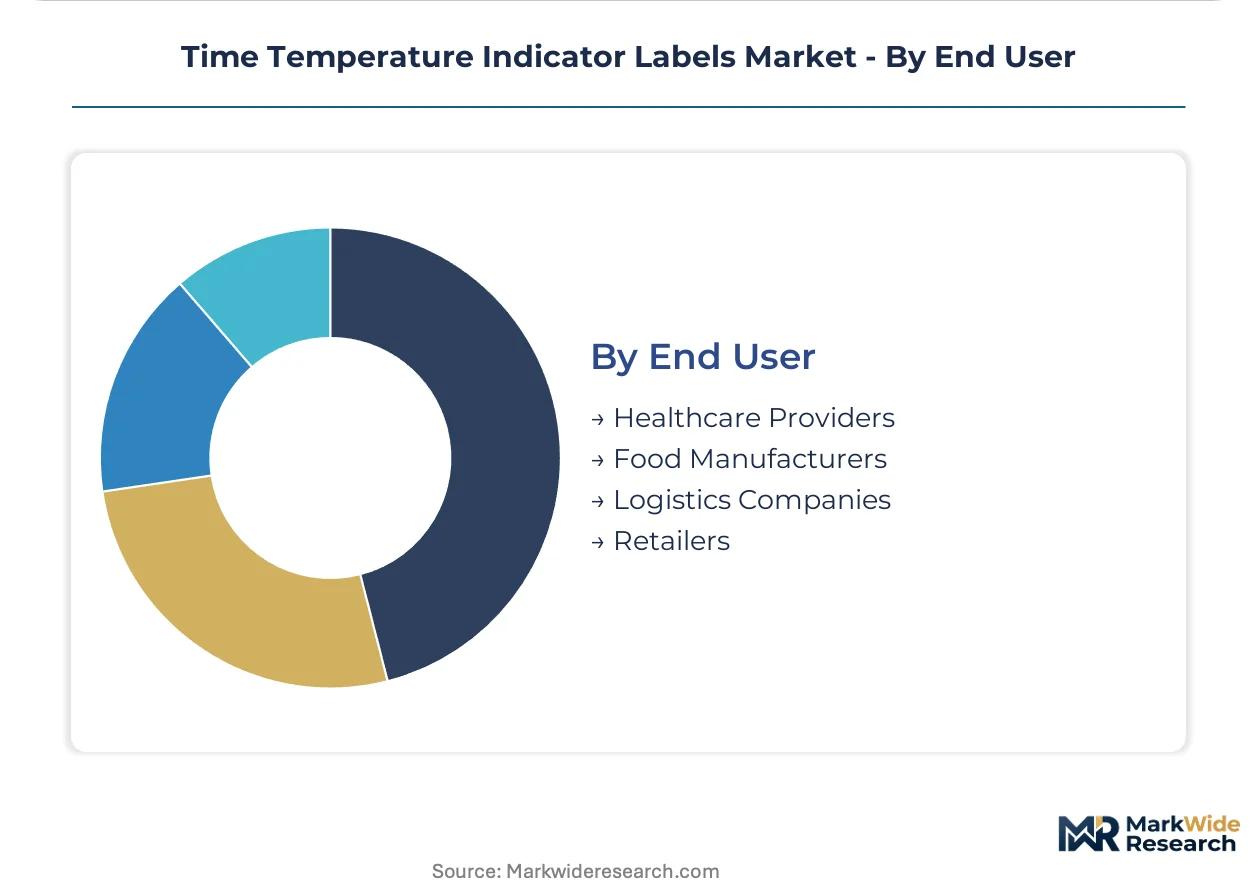
End User:
Procurement authority sits with quality assurance functions in healthcare and supply chain operations in food manufacturing, shaping vendor selection criteria.
- Healthcare Providers:Hospital pharmacy and specialty pharmacy networks requiring patient-readable breach indicators. United States direct-to-patient channels are reframing selection around smartphone integration rather than wholesale audit trails.
- Logistics Companies:Third-party cold chain operators absorbing compliance documentation costs on behalf of pharmaceutical clients. Japan's pharmaceutical manufacturing clusters are concentrating demand among BfArM-validated indicator suppliers.
- Food Manufacturers:Quality control departments specifying cost-optimized visual indicators for domestic distribution.
- Retailers:Private label programs and receiving dock verification protocols for temperature-sensitive merchandise.
Healthcare Providers anchor procurement volume, while Logistics Companies is expanding most quickly through outsourced cold chain services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized adhesive converters and printed electronics fabricators cluster in Germany, the United States, and Japan where pharmaceutical manufacturing density and regulatory enforcement intensity converge. These three markets generate disproportionate demand for compliance-grade temperature documentation as biologics production expands.
United States
FDA Drug Supply Chain Security Act serialization mandates force pharmaceutical distributors to attach tamper-evident temperature documentation at every custody transfer. Specialty pharmacies in oncology and rare disease categories now bundle verification as patient-facing services. The Greater Boston and San Francisco Bay Area biotech corridors concentrate demand for ultra-low temperature indicators in cell therapy logistics.
Germany
BfArM enforcement of EMA Good Distribution Practice creates concentrated demand for auditable temperature records across Rhine-Ruhr logistics corridors. Microencapsulated thermochromic dye converters benefit from proximity to BASF and Merck KGaA chemical feedstock suppliers. The Frankfurt and Munich pharmaceutical manufacturing clusters drive attach rates three to five times higher than generic pharmaceutical distributors.
Japan
PMDA cell therapy approvals are multiplying demand for ultra-low temperature tracking in cryogenic regenerative medicine logistics. METI industrial standards for pharmaceutical cold chain equipment create certification barriers that favor domestic converter partnerships. The Kansai region around Osaka anchors printed electronics manufacturing for NFC-enabled data logging labels.
United Kingdom
EMA-aligned MHRA regulations post-Brexit maintain stringent temperature documentation requirements for investigational medicinal products entering clinical trial supply chains. London and Cambridge biotech clusters generate demand for time-stamped temperature records that previously accepted visual-only indicators. Specialty pharmacy direct-to-patient channels are reframing selection around smartphone integration.
India
CDSCO tightening of cold chain protocols for vaccine distribution is expanding attach rates for single-use temperature indicators in last-mile logistics. The country's national pharmaceutical regulator is transposing WHO guidelines into binding requirements for national immunization programs. Hyderabad and Ahmedabad manufacturing clusters are retrofitting packaging lines for self-adhesive label integration.
Time Temperature Indicator Labels Market Competitive Environment
Concentration sits with diversified materials science conglomerates and specialized pharmaceutical label converters. The market structures around three tiers: premium electronic sensor platforms, mid-tier integrated hardware-software systems, and high-volume passive indicator suppliers. Strategic archetypes include adhesive performance specialists, printed electronics integrators, and cold chain compliance platform providers. Competitive moves center on backward integration into thin-film semiconductor deposition capacity and geographic expansion through distributor partnerships in Asia-Pacific pharmaceutical corridors.
Among North American diversified manufacturers, 3M Company and CCL Industries exemplify contrasting scale strategies. Sensitech Inc. occupies a position bridging passive indication and real-time tracking platforms. These three anchors demonstrate how materials science depth, pharmaceutical printing specialization, and software-hardware integration define viable competitive positioning in compliance-grade temperature documentation.
| Leading Market Players |
|---|
| Zebra Technologies Corp. |
| CCL Industries |
| 3M Company |
| Delta Trak |
| Temptime Corporation |
| Sensitech Inc. |
| Avery Dennison |
| Insignia Technologies |
| SpotSee |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts between pharmaceutical distributors and adhesive converters lock in acrylic polymer feedstock access while freezing unit costs across multi-year compliance mandates. This contract structure concentrates pricing power among German and Japanese suppliers with validated BfArM and PMDA certifications, insulating them from spot-market volatility that squeezes unqualified competitors.
Pricing Analysis
FDA Drug Supply Chain Security Act dictates the pricing tier structure across pharmaceutical cold chain documentation, separating calibration-certified electronic sensors from visual-only passive indicators. Three-tier pricing stratifies across premium data-logging platforms, mid-tier integrated hardware-software systems, and high-volume self-adhesive labels. Cost compression in the passive tier is intensifying because acrylic polymer feedstock prices fluctuate with petrochemical markets. Generic pharmaceutical distributors exhibit the highest price sensitivity, while biologics manufacturers absorb fivefold unit cost multiples for compliance-grade documentation.
Supply Chain Analysis
Thin-film semiconductor deposition equipment manufacturing concentrates supply among three to four East Asian equipment vendors, creating a chokepoint that constrains electronic sensor production scaling. Germany, the United States, and Japan anchor finished label supply through proximity to BASF and Merck KGaA chemical feedstock suppliers. Microencapsulated thermochromic dyes, pressure-sensitive acrylic backings, and NFC chip components constitute critical input dependencies. Single-source vulnerability in semiconductor deposition capital equipment threatens capacity expansion timelines. Distribution runs through pharmaceutical packaging line integrators and specialty pharmacy wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA, EMA, and PMDA validation protocols constructs a defensive moat that favors incumbent converters with existing certification portfolios. Switching costs for pharmaceutical shippers rise with each additional jurisdiction's approval, locking in supplier relationships across decade-long compliance cycles.
For Market Incumbents: Consolidate backward integration into thin-film semiconductor deposition capacity to capture margin pools shifting toward electronic data logging. Deepen captive supply of microencapsulated dye chemistries to defend against printed electronics displacement. The threat of NFC-enabled labels with blockchain integration demands rapid certification investment in Japan's PMDA cell therapy corridors. For New Entrants and Emerging Players: Direct-to-patient pharmacy channel under-service by incumbent wholesale-focused vendors opens white-space targeting around consumer-readable breach indicators with smartphone integration. India's CDSCO tightening of vaccine cold chain protocols represents the most penetrable geography for single-use label attach rate expansion. A go-to-market angle anchored to last-mile logistics partnerships with national immunization programs bypasses entrenched distributor relationships. For Investors and Strategic Acquirers: Capital is best deployed toward printed electronics integrators with in-house flexible circuit fabrication capabilities, as hybrid formats displace pure-play passive indicator vendors from premium pharmaceutical lanes. Long-term viability across the projection horizon hinges on regulatory certification breadth rather than manufacturing scale alone. The signal to watch is WHO guideline updates favoring electronic data logging over visual-only indicators in national immunization programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Deposition | Captures margin pools shifting from passive indicators to electronic sensors in biologics cold chain. |
| PMDA Certification Investment for Cryogenic Indicators | Positions converters for Japan's regenerative medicine expansion in cell therapy logistics. |
| NFC-Blockchain Platform Development | Opens premium positioning in high-value biologics lanes with real-time custody verification. |
| Direct-to-Patient Channel Partnership | Reframes temperature verification as consumer-facing service in specialty pharmacy networks. |
| Multi-Jurisdiction Validation Study Consolidation | Compresses launch cycles currently extended by separate BfArM, PMDA, and FDA approval processes. |
Study Parameters
Initial hypotheses were tested against primary input from pharmaceutical quality assurance directors, cold chain logistics procurement managers, regulatory affairs specialists at biologics manufacturers, and adhesive converter technical R&D leads, then refined through secondary validation. FDA Drug Supply Chain Security Act guidance documents, EMA Good Distribution Practice updates, WHO vaccine handling protocols, and PMDA cell therapy approval records anchored regulatory trajectory assessment. Customs data on acrylic polymer feedstock flows, pharmaceutical packaging machinery import records, and clinical trial logistics expenditure patterns supplied demand-side calibration. Bottom-up attach rate modeling across pharmaceutical, food, and logistics applications was cross-checked against top-down market sizing.
Variance decomposition across product type, technology platform, application intensity, and end-user procurement authority shaped the analytical framework throughout the forecast period. Electronic sensor, thermochromic dye, and time-temperature integrator technology segments were modeled separately with divergent margin assumptions. CAGRs were derived from segmented attach rate projections calibrated to regulatory mandate implementation timelines. Biologics production expansion, vaccine distribution protocol tightening, and regenerative medicine cold chain requirements supplied industry-specific demand inputs.
Material uncertainties — regulatory divergence between electronic data logging mandates and passive indicator acceptance, adhesive raw material price volatility, thin-film deposition equipment supply constraints — sit outside the modeled envelope. Forecasts reflect assumptions about certification timeline compression and pharmaceutical shipper technology adoption curves. Practitioners should keep alternative scenarios live as WHO guideline evolution and national pharmacopeial standard updates reshape indicator acceptance criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
GHS Labels Market
Labels
HAZMAT Labels Market
Labels
Global Label Market
Labels
Pin Feed Labels Market
Labels
Integrated Labeling System Market
Labels
Inventory Tags Market
Labels
Eco-Friendly Labels Market
Labels
Warning Labels and Stickers Market
Labels
Polyester Labels Market
Labels
Stand Alone Label Applicator Market
Labels
Pre-Gummed Labels Market
Labels
Global Metal Detectable Tags and Labels Market
Labels
Syringe Labels Market
Labels
United States Print Label Market
Labels
Repositionable Labels Market
Labels
Glue Applied Automotive Labels Market