
 Die Cut Labels Market | 2026-2036
Die Cut Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Die Cut Labels Market Outlook
Digital printing integration with automated finishing systems is fragmenting traditional die cut label production workflows into shorter-run, on-demand configurations. Avery Dennison Corporation leverages its materials science portfolio to anchor premium adhesive substrate supply chains. 3M Company competes through industrial-grade durability specifications in harsh-environment applications. Resource Label Group specializes in regional flexible packaging partnerships that sustain mid-market share positions.
Die cut labels are precisely engineered adhesive-backed substrates, typically 2-10 mils thick, shaped by steel-rule or rotary dies to exact product contours for seamless surface application. Their primary commercial purpose spans brand identification, regulatory compliance marking, and supply chain track-and-trace functionality across consumer and industrial goods. Pressure-sensitive formulations dominate volume throughput due to versatile substrate compatibility and minimal application equipment requirements, while thermal transfer segments capture higher-margin pharmaceutical serialization work requiring variable data permanence. Shrink sleeve applications are accelerating fastest in beverage containers as contoured packaging designs proliferate beyond traditional cylindrical formats.
FDA DSCSA requirements and EU MDR serialization mandates are forcing pharmaceutical label producers to integrate tamper-evident features and machine-readable authentication layers into standard die cut constructions. EPA guidelines on volatile organic compound emissions from adhesive curing processes are reshaping solvent selection in North American manufacturing operations. REACH compliance in Europe restricts certain plasticizer chemistries in vinyl substrates, redirecting material specification toward polypropylene alternatives. Stakeholders must monitor evolving track-and-trace mandate scope expansions beyond pharmaceuticals into food safety and industrial component provenance systems.
Market Dynamics
Digital printing integration with automated finishing systems is fragmenting traditional die cut label production workflows into shorter-run, on-demand configurations, compressing batch economics and rewiring procurement relationships across pharmaceutical and industrial packaging verticals.
Growth Catalysts
- EU MDR Serialization Mandates:Pharmaceutical track-and-trace requirements are forcing label complexity upgrades across European supply chains, expanding tamper-evident and machine-readable authentication layer specifications.
- Shrink Sleeve Beverage Applications:Contoured packaging designs beyond cylindrical formats are accelerating demand for heat-shrinkable die cut constructions in premium beverage segments.
- Germany's Industrial Packaging Corridor:Concentrated automotive and chemical manufacturing clusters sustain high-volume, specification-grade adhesive label procurement with stringent durability requirements.
Market Restraints
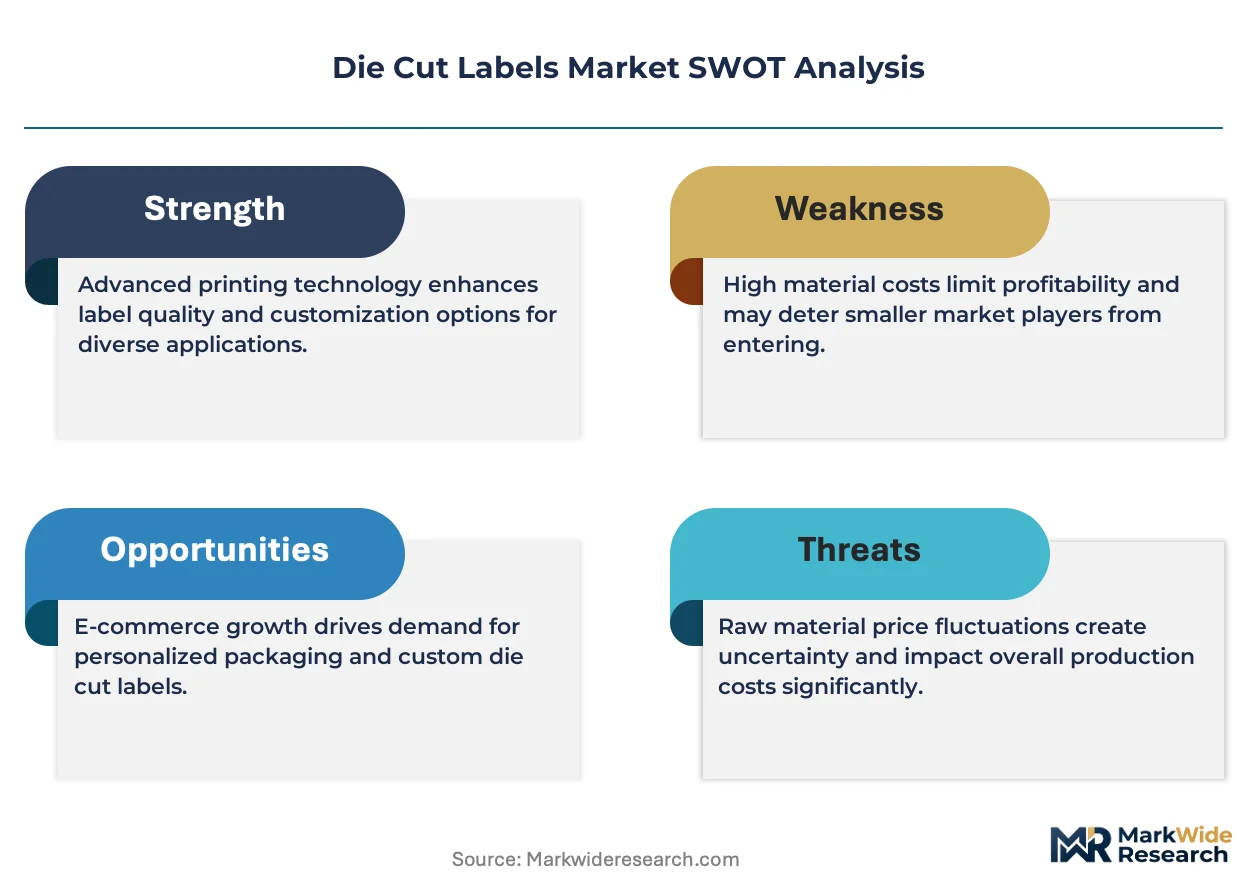
- Adhesive Input Cost Volatility:Petrochemical-derived acrylic and rubber-based adhesive formulations face price instability from crude oil fluctuations, squeezing converter margins on fixed-price contracts.
- REACH Plasticizer Restrictions:ECHA limitations on phthalate chemistries in vinyl substrates are forcing material requalification costs and supply chain redirection toward polypropylene alternatives.
- Digital Substitution Threat:Direct-to-object inkjet marking systems are capturing share in secondary packaging applications previously served by pressure-sensitive die cut labels.
Strategic Opportunities
- Indian Pharmaceutical Export Growth:CDSCO-aligned serialization infrastructure investments by Indian generic drug manufacturers are creating demand for EU MDR-compliant label supply partnerships.
- Food Safety Track-and-Trace Expansion:Anticipated FDA Food Safety Modernization Act scope extensions beyond pharmaceuticals into perishable provenance systems will broaden authentication label applications.
- UV LED Curing Convergence:Energy-curable ink technologies combined with digital printheads are enabling instant-dry, high-resolution variable data printing without thermal substrate distortion.
Industry Challenges
- Variable Data Integration Complexity:Pharmaceutical serialization requirements demand real-time ERP-to-press data pipelines that legacy analog workflow infrastructures struggle to accommodate without substantial middleware investment.
- Specialized Operator Skill Scarcity:Convergence of prepress file preparation, color management, and finishing automation requires hybrid digital-mechanical competencies that traditional flexographic workforces lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Die Cut Labels Market |
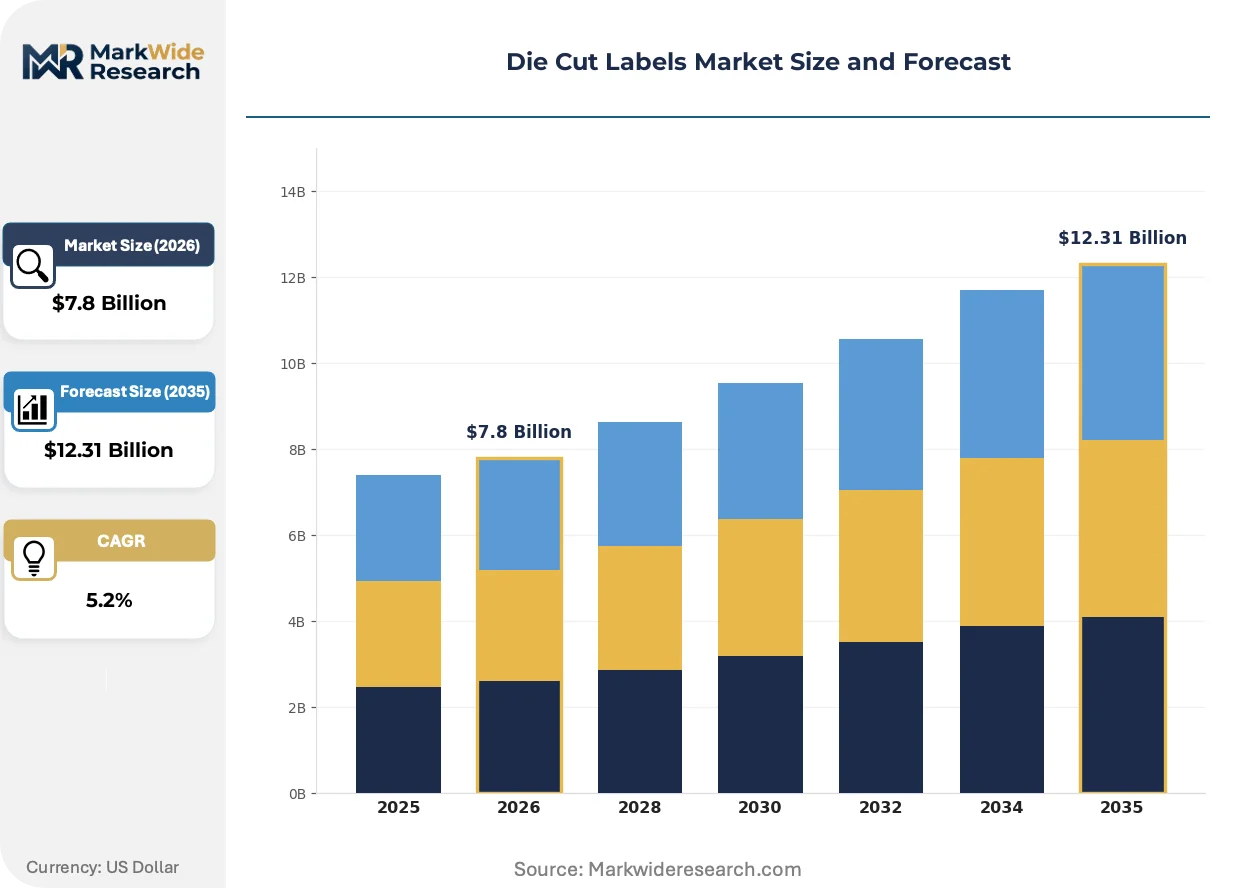
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.31 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Label Type: Pressure-Sensitive, Shrink Sleeve, Thermal Transfer, In-Mold Material: Paper, Polypropylene, Vinyl, Polyester Application: Food Packaging, Industrial Products, Pharmaceuticals, Beverage Containers Finish Type: Matte, Glossy, Transparent, Embossed |
| Companies Covered | Avery Dennison Corporation, Sticker Mule, Resource Label Group, 3M Company, StickerGiant, UPrinting, Grand Rapids Label, Ritrama SpA, ORAFOL Europe GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Die Cut Labels Market Strategic Shifts
Production technology convergence and regulatory authentication mandates are actively rewiring competitive capabilities across the die cut label value chain, favoring converters with integrated digital workflow architectures.
UV-curable inkjet printing systems are migrating from narrow-web label presses into mid-web flexible packaging configurations, enabling pharmaceutical and food converters to merge short-run SKU proliferation with serialized variable data requirements without plate changeover delays. Brand owners in Germany's industrial corridor are adopting these hybrid platforms to compress lead times on regulatory compliance batches.
EPA guidelines on volatile organic compound emissions from adhesive curing processes are reshaping solvent selection across North American manufacturing operations, pressuring converters toward water-based and hot-melt formulations that meet regional air quality standards. California's South Coast Air Quality Management District rules are accelerating this transition among converters supplying the US Southeast logistics hub.
Brand procurement teams are consolidating vendor relationships around converters offering integrated design-to-distribution digital platforms, displacing fragmented spot-buying from multiple regional suppliers. This concentration is most visible among mid-market consumer packaged goods companies in the US Southeast seeking to reduce SKU management overhead across fragmented label specifications.
Die Cut Labels Market Segmentation
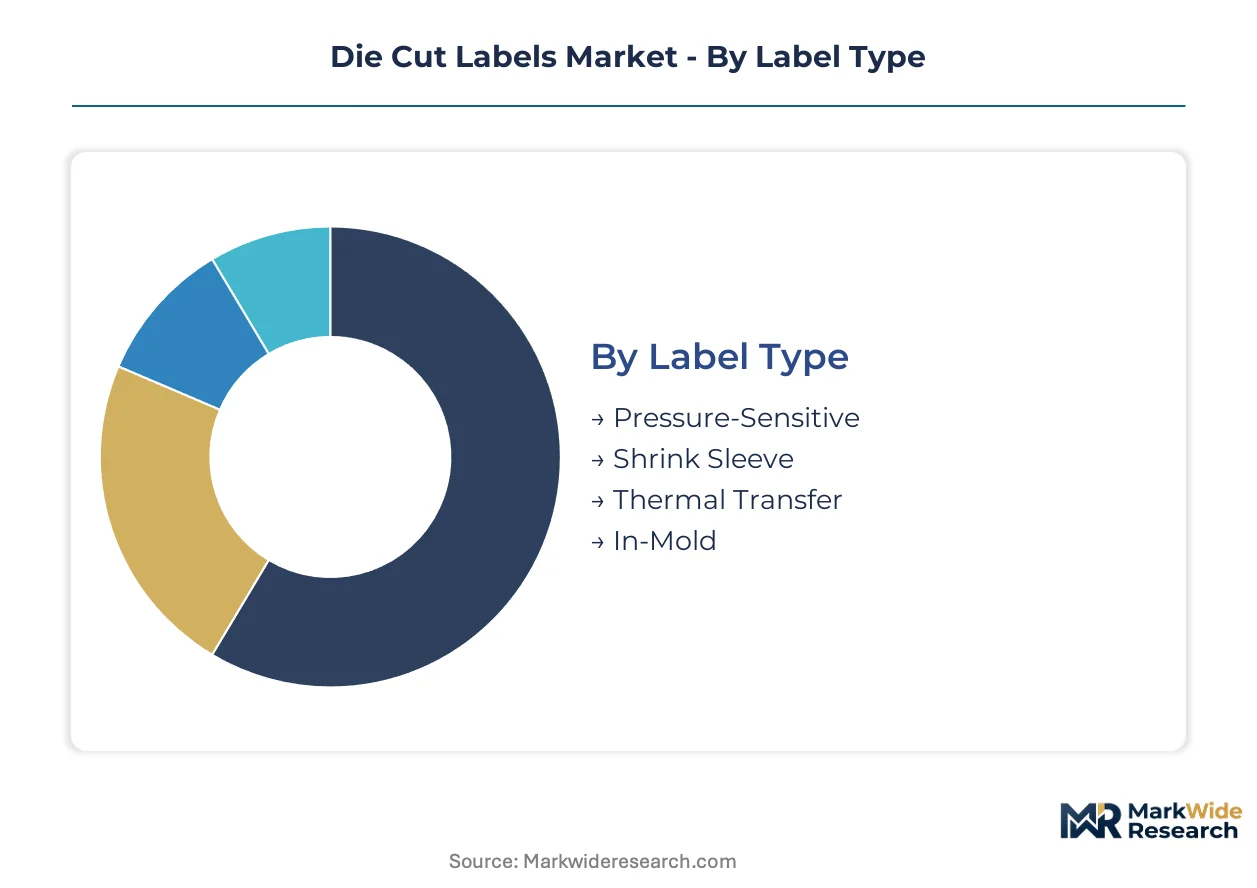
Die cut label procurement patterns diverge sharply across adhesive chemistry, substrate durability, and regulatory authentication requirements. Each segmentation dimension captures distinct margin structures and converter capability thresholds that reshape competitive positioning.
Label Type:
Application method determines equipment investment, run-length economics, and end-use suitability across consumer and industrial verticals.
- Pressure-Sensitive:Acrylic or rubber-based adhesive coatings on release liners enable immediate tack without heat or solvent activation. Food packaging converters in Germany's industrial corridor specify these for high-speed automated application on corrugated secondary packaging.
- Shrink Sleeve:Heat-shrinkable polyester or PVC substrates conform to complex bottle geometries beyond cylindrical formats. Beverage brand owners in the US Southeast logistics hub are expanding SKU proliferation using these for 360-degree decorative coverage with tamper-evident bands.
- Thermal Transfer:Wax-resin or resin ribbons melt onto receptive coatings to produce permanent variable data marks. Pharmaceutical serialization mandates under FDA DSCSA and EU MDR are concentrating procurement among converters with integrated digital print-to-finish workflows.
- In-Mold:Polypropylene labels fuse with injection-molded containers during forming, eliminating post-mold labeling steps. Automotive chemical packaging in Germany specifies these for solvent-resistant permanent identification.
Pressure-Sensitive holds installed capacity. Shrink Sleeve is rotating up the share rankings.
Material:
Substrate selection trades off print receptivity, environmental resistance, and regulatory compliance cost across end-use specifications.
- Paper:Uncoated and coated stocks provide economical print surfaces for short-life consumer goods labels. REACH plasticizer restrictions have redirected some vinyl demand toward paper alternatives in European food packaging applications.
- Polypropylene:Biaxially oriented films deliver moisture resistance and dimensional stability without plasticizer content. Pharmaceutical converters are qualifying these as vinyl replacements to satisfy ECHA compliance requirements.
- Vinyl:Flexible PVC formulations conform to curved surfaces with excellent outdoor durability. Regulatory pressure from REACH phthalate limitations is constraining growth in European markets while sustaining volume in North American industrial applications.
- Polyester:High-tensile films withstand harsh chemical and thermal environments in automotive underhood and industrial component marking. Germany's automotive manufacturing clusters specify these for specification-grade durability.
Polypropylene is climbing the fastest among substrate conversions. Paper retains volume leadership in cost-sensitive segments.
Application:
End-use verticals impose distinct authentication, durability, and aesthetic requirements that filter converter qualification.
- Food Packaging:Direct-contact and secondary labeling for perishables requires migration-compliant adhesives and substrates. Anticipated FDA Food Safety Modernization Act expansions are driving investment in track-and-trace authentication layers.
- Pharmaceuticals:Unit-level serialization, tamper-evidence, and anti-counterfeiting features dominate specification. EU MDR and FDA DSCSA mandates are forcing label complexity upgrades across European and North American supply chains.
- Industrial Products:Chemical drums, automotive components, and electronics demand solvent-resistant, temperature-stable identification. Germany's chemical manufacturing corridor sustains high-volume procurement of specification-grade constructions.
- Beverage Containers:Contoured glass and PET bottles drive heat-shrink sleeve adoption for premium decoration. US Southeast logistics hub distribution centers are consolidating procurement around converters with digital hybrid press capabilities.
Pharmaceuticals commands premium pricing. Beverage Containers is gaining share fastest through shrink sleeve conversion.
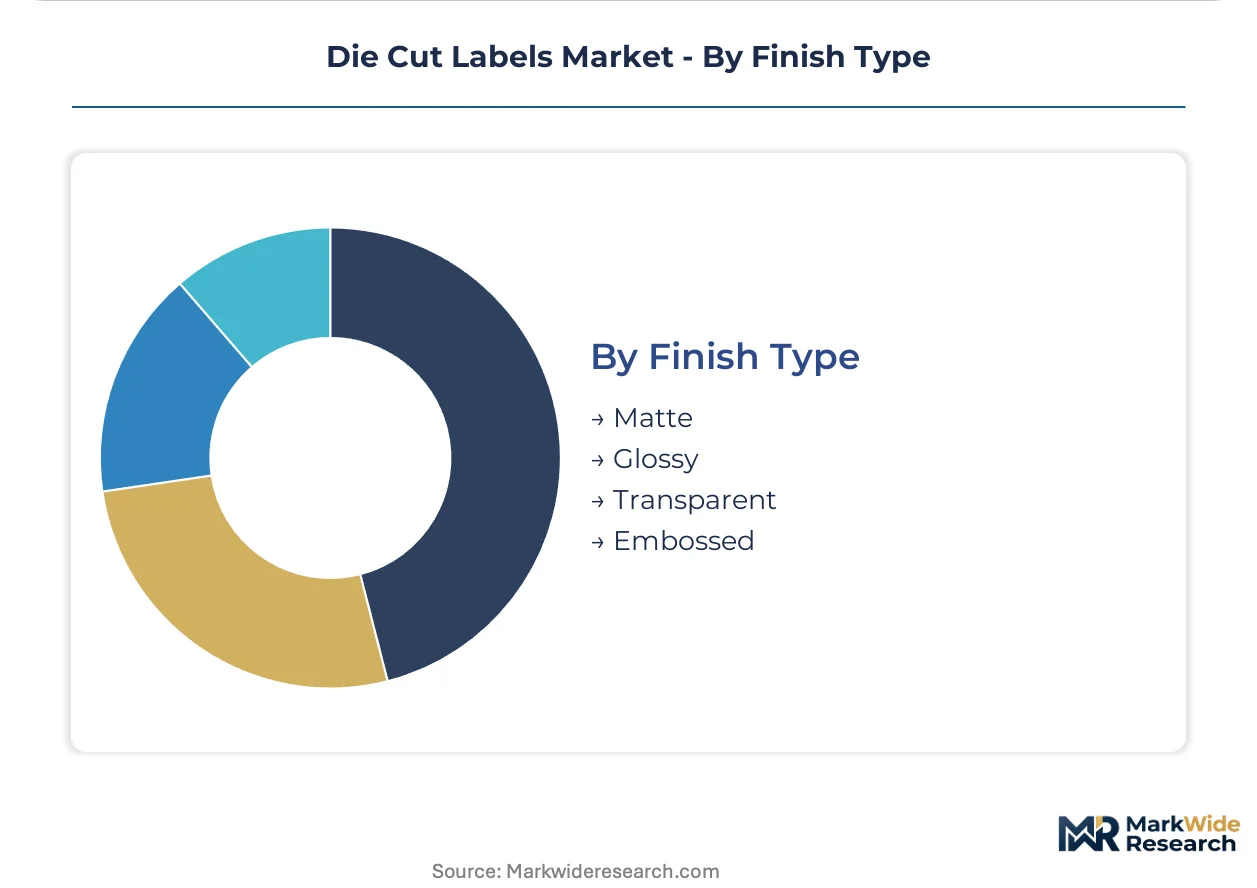
Finish Type:
Surface treatment affects print gloss, scuff resistance, and brand differentiation in crowded retail environments.
- Matte:Non-reflective coatings reduce glare and convey premium sustainability positioning. Craft beverage producers in Germany specify these for artisanal brand differentiation.
- Glossy:High-sheen varnishes maximize color saturation and shelf impact for consumer goods. Mass-market food brands in the US Southeast prioritize these for retail visibility.
- Transparent:Clear films and varnishes reveal underlying container surfaces for no-label look aesthetics. Premium personal care applications are adopting these for minimalist packaging design.
- Embossed:Raised surface patterns provide tactile authentication and luxury signaling. High-end spirits and cosmetics specify these for counterfeiting deterrence and unboxing experience.
Glossy maintains production volume dominance. Matte is ascending fastest on sustainability-aligned brand positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical manufacturers and beverage brand owners concentrate procurement in industrial corridors with dense converter networks and stringent regulatory enforcement. Germany's automotive chemical clusters, the US Southeast logistics hub, and India's pharmaceutical export zones anchor regional demand patterns.
United States
FDA DSCSA serialization mandates and EPA VOC emission guidelines drive label complexity upgrades across pharmaceutical and food packaging supply chains. California's South Coast Air Quality Management District rules accelerate water-based adhesive adoption among converters. The US Southeast logistics hub—spanning Georgia and Tennessee distribution centers—consolidates procurement around digital hybrid press capabilities for beverage SKU proliferation.
Germany
EU MDR pharmaceutical track-and-trace requirements and REACH plasticizer restrictions reshape material specifications toward polypropylene alternatives. ECHA compliance costs filter converter qualification toward integrated digital workflow providers. The industrial packaging corridor in Baden-Württemberg and North Rhine-Westphalia sustains high-volume procurement of specification-grade adhesive labels for automotive and chemical manufacturing.
India
CDSCO-aligned serialization infrastructure investments by generic drug manufacturers create demand for EU MDR-compliant label supply partnerships. Pharmaceutical export growth to regulated markets forces domestic converters to upgrade authentication layer capabilities. Maharashtra and Gujarat pharmaceutical manufacturing clusters drive regional converter consolidation around track-and-trace compliance expertise.
China
NMPA pharmaceutical serialization requirements and dual carbon goals pressure adhesive formulation shifts toward lower-emission curing processes. MIIT industrial standards for food contact materials redirect substrate selection. The Yangtze River Delta converter network adapts digital printing platforms to serve both domestic pharmaceutical serialization and export beverage decoration contracts.
United Kingdom
Post-Brexit regulatory divergence from EU MDR creates parallel compliance pathways for pharmaceutical label converters serving European export markets. MHRA guidance on medical device labeling sustains demand for tamper-evident constructions. The Midlands packaging manufacturing belt concentrates converter investment in hybrid digital-mechanical finishing systems for shortened pharmaceutical batch runs.
Die Cut Labels Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented procurement relationships. The vendor base spans multinational materials science conglomerates, regional flexible packaging partnerships, and digital-native short-run specialists. Three archetypes dominate: substrate-integrated conglomerates with captive adhesive supply, mid-market regional converters with flexible packaging partnerships, and digital-first platforms optimized for e-commerce-enabled short runs. Competitive moves concentrate on M&A-driven geographic expansion and strategic technology licensing for digital finishing integration.
Within the materials-integrated tier, Avery Dennison Corporation and 3M Company anchor premium substrate and industrial-grade durability positioning respectively. Resource Label Group exemplifies the regional partnership model that sustains mid-market share through flexible packaging corridor relationships. These three entities represent distinct capability configurations—substrate science, harsh-environment specifications, and regional logistics integration—that shape procurement segmentation across pharmaceutical, beverage, and industrial verticals.
| Leading Market Players |
|---|
| Avery Dennison Corporation |
| Sticker Mule |
| Resource Label Group |
| 3M Company |
| StickerGiant |
| UPrinting |
| Grand Rapids Label |
| Ritrama SpA |
| ORAFOL Europe GmbH |
| Others |
Value Chain & Pricing Dynamics
Baden-Württemberg's automotive chemical clusters concentrate specification-grade adhesive substrate capacity, feeding converter pricing power downstream into pharmaceutical and industrial procurement negotiations across European supply chains.
Pricing Analysis
Cost-plus contracts with acrylic resin indexation dominate long-term pharmaceutical label agreements, insulating converters from petrochemical volatility while passing through margin compression on fixed-price industrial accounts. Three-tier pricing structure across serialization-grade, standard compliance, and economy unprinted stock reflects authentication complexity and substrate durability tiers. Pricing pressure stems from digital print substitution in secondary packaging applications previously served by pressure-sensitive constructions. Mid-market beverage brand owners exhibit highest price sensitivity, while EU MDR-mandated pharmaceutical serialization commands inelastic demand.
Supply Chain Analysis
Petrochemical feedstocks from Germany, the United States, and China anchor acrylic adhesive and polypropylene film supply, with biaxially oriented film capacity expanding fastest in Asia-Pacific to serve vinyl substitution demand. Converter operations draw from release liner substrates, pressure-sensitive adhesives, and UV-curable ink chemistries as core inputs. Single-source vulnerability concentrates in specialty tamper-evident substrate formulations qualified for FDA DSCSA compliance. Distribution runs through converter-direct relationships with pharmaceutical manufacturers and beverage brand procurement teams, bypassing traditional distribution intermediaries for specification-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Die cut label demand sits in early-cycle expansion as pharmaceutical serialization mandates penetrate Indian and Chinese export infrastructure, creating sustained authentication layer upgrade cycles across generic drug manufacturing clusters.
For Market Incumbents: Insulate margin position through captive adhesive formulation capacity and ERP-to-press digital workflow integration that blocks mid-tier competitors from pharmaceutical qualification. Direct-to-object inkjet marking systems threaten secondary packaging share; defend through shrink sleeve hybrid platform investments in the US Southeast logistics corridor. Backward integration into UV-curable ink chemistry production secures supply continuity for serialization-grade variable data contracts. For New Entrants and Emerging Players: Pursue white-space opportunity in Indian pharmaceutical export serialization partnerships, where CDSCO-aligned infrastructure investments outpace domestic converter authentication capability. Food safety track-and-trace expansion under anticipated FDA scope extensions offers penetrable entry into perishable provenance systems with lower incumbent concentration than pharmaceutical verticals. Lead with digital-native short-run platforms targeting craft beverage SKU proliferation in Germany's industrial corridor. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with integrated digital finishing architectures over analog-flexographic legacy assets facing variable data integration complexity. Five-to-ten year viability hinges on pharmaceutical serialization mandate expansion into food and industrial provenance systems. Acquisition targets should demonstrate hybrid press deployment and ERP integration capabilities; monitor NMPA and CDSCO regulatory alignment announcements as inflection signals for emerging market demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Hybrid Press Deployment | UV LED curing convergence enables instant-dry pharmaceutical serialization without thermal substrate distortion. |
| Backward Integration into Adhesive Chemistry | Captive acrylic formulation capacity insulates margins from petrochemical index volatility. |
| ERP-to-Press Workflow Integration | Real-time variable data pipelines satisfy FDA DSCSA unit-level traceability mandates. |
| Regional Converter Consolidation | Geographic expansion in India's Maharashtra cluster captures CDSCO-aligned export growth. |
| Shrink Sleeve Platform Expansion | Heat-shrinkable constructions address contoured beverage packaging beyond cylindrical formats. |
Study Parameters
A standing panel of label converter operations directors, pharmaceutical packaging procurement managers, beverage brand supply chain leads, and adhesive substrate technical specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA DSCSA guidance documents, EMA MDR implementation reports, ECHA REACH restriction updates, and customs trade data on adhesive substrate flows. Bottom-up capacity assessments at converter facilities triangulated against top-down pharmaceutical serialization mandate penetration models.
Scenario-bracketing framed demand projections across regulatory compliance, digital substitution, and raw material cost volatility pathways. Segmentation modeling spanned label type, substrate material, end-use vertical, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derived from pharmaceutical serialization mandate phase-in schedules, beverage packaging format conversion rates, and industrial durable goods production indices.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories, interest rate environments affecting converter capital expenditure, or trade policy shifts on adhesive substrate tariffs would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement consistency and digital print technology cost curves. Cross-checking against NMPA and CDSCO serialization infrastructure investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Polyester Labels Market
Labels
Printable Tags Market
Labels
Inspection and Inventory Labels Market
Labels
Oxygen Indicator Labels Market
Labels
Booklet Labels Market
Labels
United States Print Label Market
Labels
Multi-Part Labels Market
Labels
BOPP Labels Market
Labels
Wet Glue Labeling Machines Market
Labels
Global in-Mold Labels Market
Labels
Industrial Label Printers Market
Labels
Pre-Gummed Labels Market
Labels
Variable Data Printing Labels Market
Labels
Barcode Label Printer Market
Labels
Global Cryogenic Label Market
Labels
GHS Labels Market