
 North America Self-Adhesive Labels Market | 2026-2036
North America Self-Adhesive Labels Market Size, Share, and Industry Trends Forecast 2026-2036
North America Self-Adhesive Labels Market Insights
California's SB 54 extended producer responsibility mandate is consolidating demand for recyclable and compostable label substrates across the region. Avery Dennison Corporation leverages its materials science portfolio to develop wash-away adhesives that simplify PET container recycling. CCL Industries anchors North American capacity through specialized pharmaceutical and beverage label operations. 3M competes with advanced acrylic adhesive platforms engineered for temperature-variable logistics applications.
Self-adhesive labels comprise pressure-sensitive constructions featuring face stock, adhesive layer, and release liner, with silicone-coated papers or films enabling clean dispensing at speeds exceeding 15,000 labels per hour on rotary application equipment. Their primary commercial purpose spans product identification, regulatory compliance marking, and supply chain traceability across packaged goods industries. Plastic labels lead value contribution due to durability requirements in beverage and personal care segments, while digital printing technology captures the fastest expansion as brands pursue shorter run lengths and variable data personalization. Food and beverage end users command the largest volume share, though healthcare applications generate superior margin pools through serialization and anti-counterfeiting specifications.
The EPA regulates adhesive volatile organic compound emissions under Clean Air Act standards, while FDA oversees indirect food contact compliance for label substrates migrating into packaged edibles. OSHA workplace exposure limits further constrain solvent-based adhesive formulations, accelerating water-based and UV-curable system penetration. State-level packaging extended producer responsibility frameworks, including Oregon and Maine programs, impose material recovery obligations that reshape substrate selection criteria. Stakeholders must monitor evolving state-by-state compliance thresholds and adhesive chemistry registration requirements to sustain market access across fragmented regulatory jurisdictions.
Market Dynamics
California's SB 54 extended producer responsibility mandate is consolidating demand for recyclable and compostable label substrates across the region. The EPA's evolving sustainable packaging guidelines and state-level extended producer responsibility laws are reshaping material specifications across the region.
Growth Catalysts
- State-level EPR mandates:Oregon and Maine packaging extended producer responsibility programs impose material recovery obligations that reshape substrate selection criteria across the region.
- Food and beverage demand:Brands shift toward recyclable and bio-based label substrates as packaging sustainability becomes a purchasing criterion for major retailers.
- Digital printing adoption:Variable data personalization capabilities enable shorter run lengths and mass customization for regional craft beverage producers.
Market Restraints
- Silicone release liner supply concentration:Specialty coated paper and film liner production clusters with limited North American converters, creating input bottlenecks during demand surges.
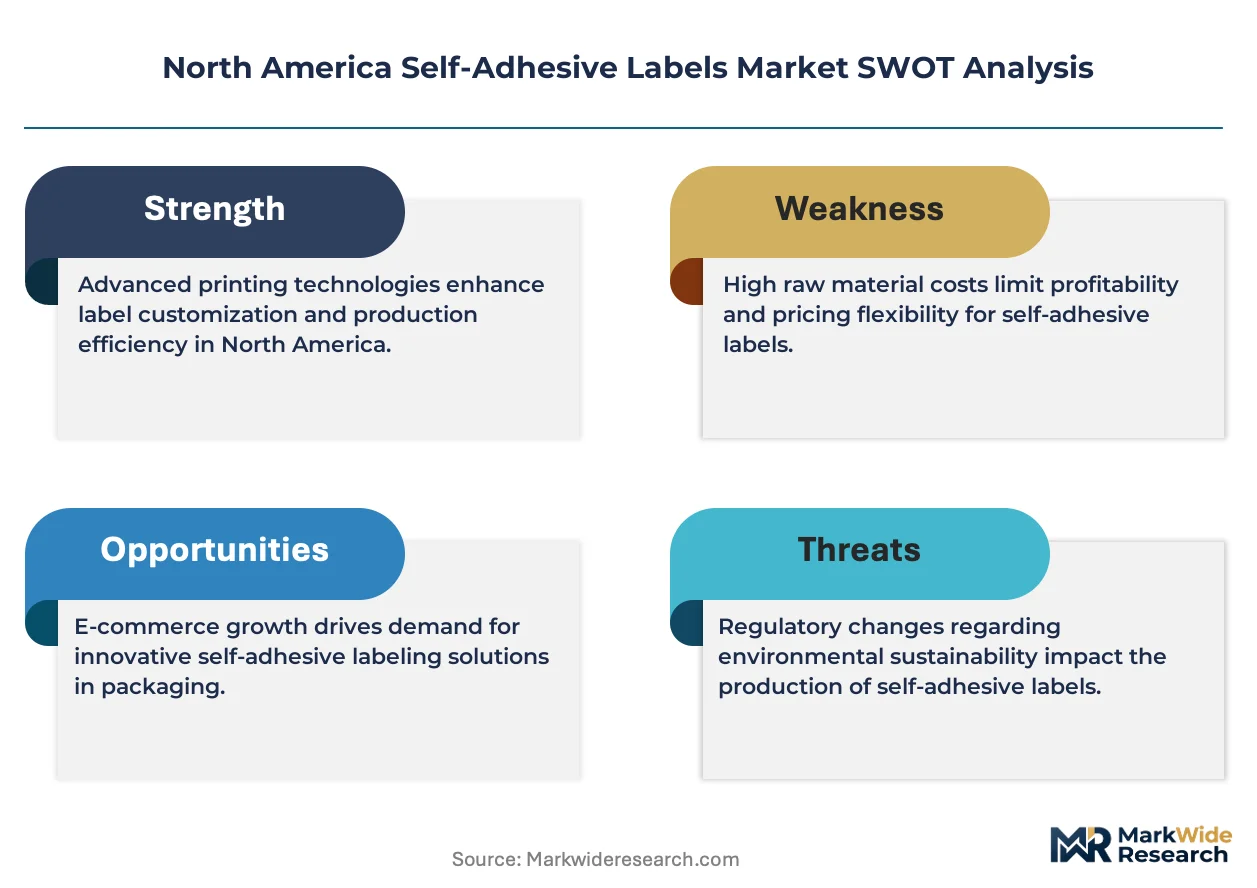
- Adhesive chemistry registration complexity:EPA Clean Air Act volatile organic compound standards and OSHA workplace exposure limits constrain solvent-based formulation options.
- Paper substrate cost volatility:Pulp price fluctuations and energy-intensive coating processes pressure converter margins on standard paper label grades.
Strategic Opportunities
- Wash-away adhesive platforms:PET container recycling simplification creates white space for adhesive technologies that separate cleanly during flotation washing processes.
- Healthcare serialization expansion:FDA drug supply chain security mandates drive demand for track-and-trace labels with integrated authentication features.
- Midwest manufacturing belt proximity:Label converter clustering near Chicago, Detroit, and Milwaukee consumer goods production centers reduces logistics costs for just-in-time delivery.
Industry Challenges
- Multi-jurisdiction compliance navigation:Stakeholders must monitor evolving state-by-state compliance thresholds and adhesive chemistry registration requirements to sustain market access.
- Legacy equipment integration:Rotary application systems operating at 15,000 labels per hour require retrofitting for new substrate thicknesses and adhesive rheologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Self-Adhesive Labels Market |
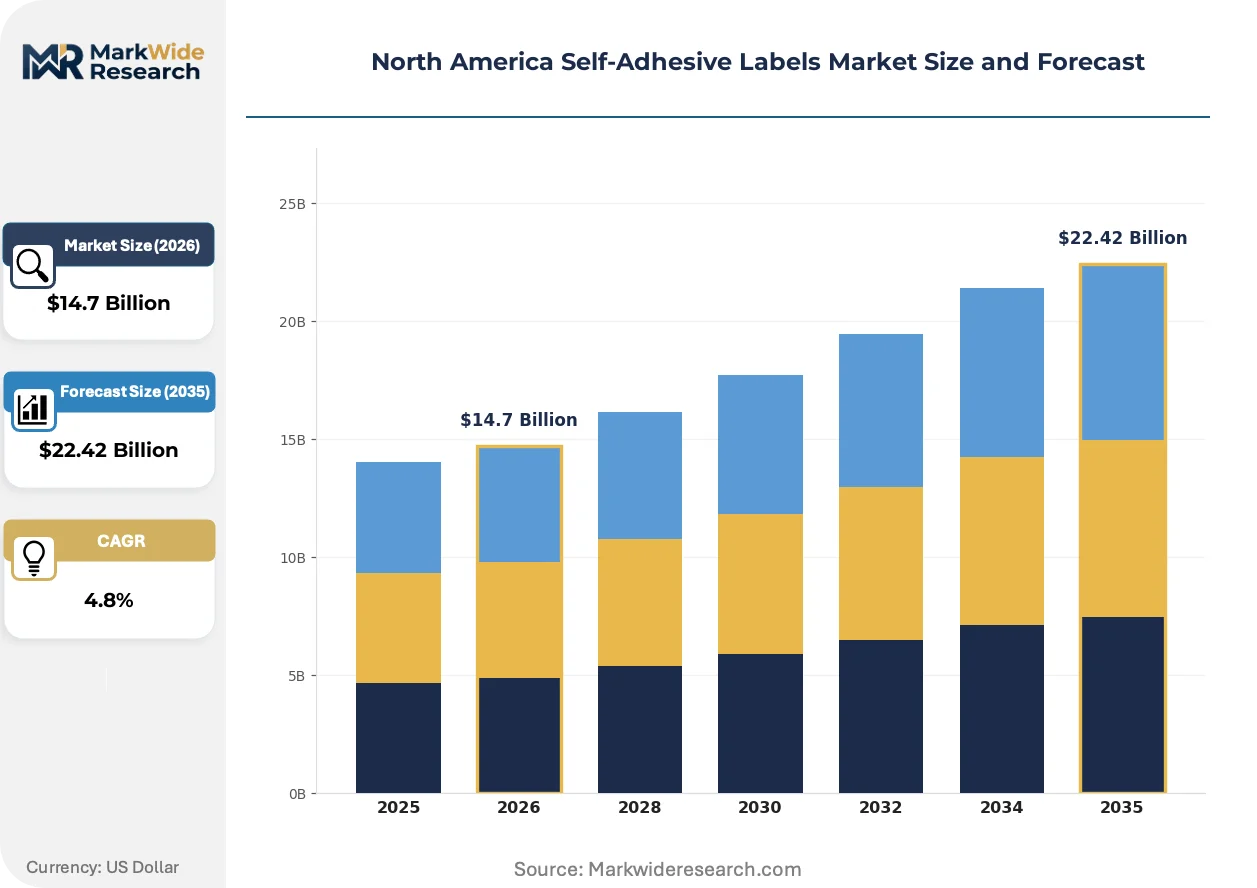
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $22.42 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Paper Labels, Plastic Labels, Vinyl Labels, Specialty Labels End User: Food & Beverage, Healthcare, Retail, Automotive Technology: Digital Printing, Flexographic Printing, Gravure Printing, Offset Printing Application: Packaging, Inventory Management, Product Branding, Shipping |
| Companies Covered | Multi-Color Corporation, UPM, Avery Dennison Corporation, H.B. Fuller Company, DuPont, CCL Industries, LINTEC Corporation, Consolidated Label Co, 3M, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Self-Adhesive Labels Market Trends and Innovations
Digital printing technology is automating production workflows while regulatory pressure on packaging recyclability accelerates material science investment. These forces are compressing run lengths and expanding substrate functionality simultaneously.
Digital inkjet and toner-based printing systems are automating prepress and make-ready processes that previously required manual plate changes and color calibration. Beverage and personal care brands with seasonal SKU proliferation adopt these platforms to reduce minimum order quantities from hundreds of thousands to thousands of labels. This compression of economic run thresholds is automating access to variable data personalization for mid-sized regional brands previously locked out of customization.
EPA Clean Air Act standards on adhesive volatile organic compound emissions are tightening formulation requirements for solvent-based systems. Water-based and UV-curable adhesive chemistries capture share as converters retrofit coating lines to meet compliance thresholds. Food contact applications face the steepest transition costs, as FDA indirect food contact migration testing must validate new adhesive platforms before commercial deployment.
Brand procurement teams now specify recyclability certifications as mandatory bid criteria rather than preferred attributes. This certification-driven preference shift compresses supplier qualification timelines and elevates converters with established wash-away or compostable substrate portfolios. The beverage segment exhibits the most visible transformation, as major retailers demand shelf-ready packaging with third-party verified recycling compatibility.
North America Self-Adhesive Labels Market Segmentation
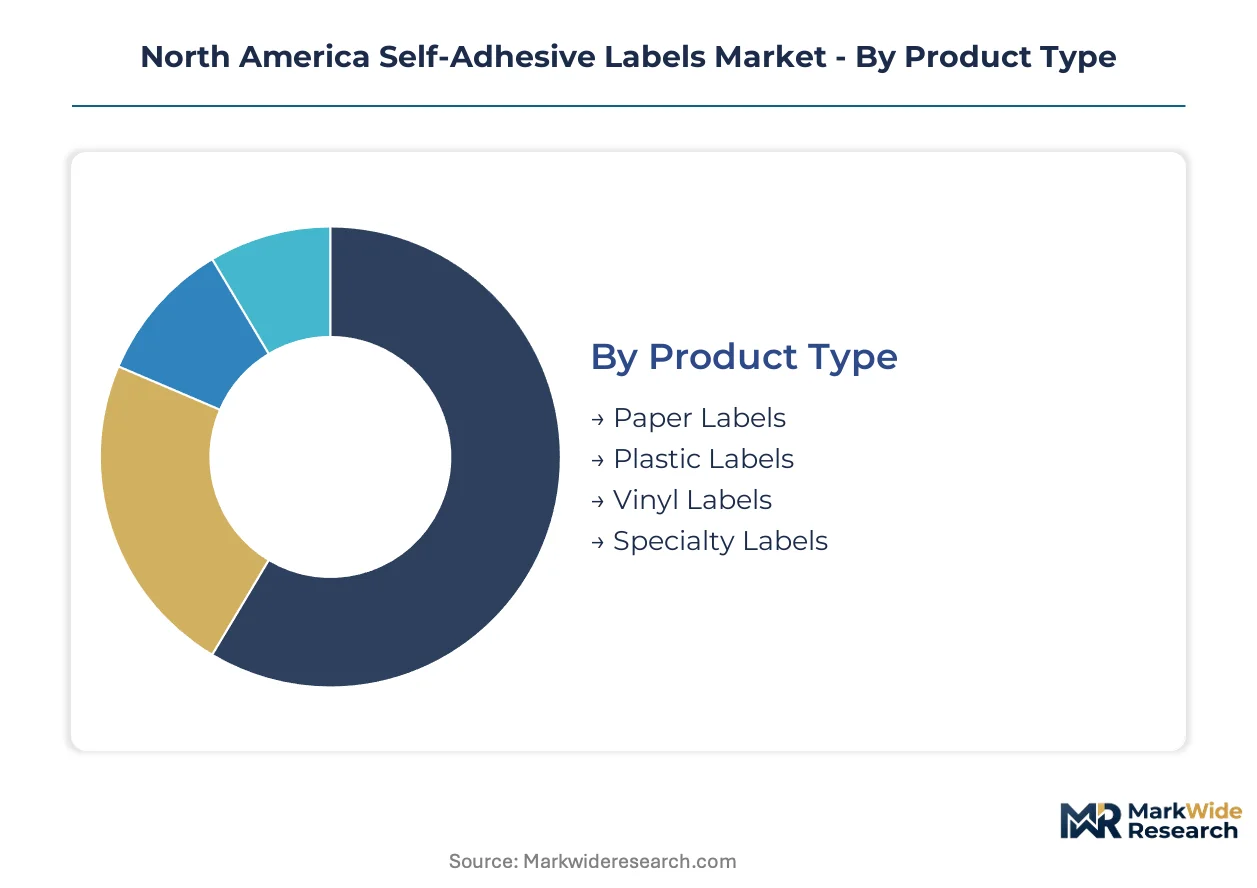
Self-adhesive label procurement decisions hinge on regulatory certification requirements that vary sharply across end-use applications. FDA food contact compliance, EPA volatile organic compound standards, and state-level extended producer responsibility mandates create distinct compliance burdens for each segment category.
Product Type:
FDA indirect food contact migration testing applies most stringently to paper and plastic substrates in food packaging, while specialty labels face OSHA workplace exposure constraints for solvent-based adhesive chemistries.
- Paper Labels:Cellulose-based face stocks with water-based or hot-melt adhesive layers dominate standard consumer goods applications. Demand concentrates in the Midwest manufacturing belt where label converters supply Chicago-area food processors with cost-competitive solutions for dry goods packaging.
- Plastic Labels:Polypropylene and polyethylene constructions deliver moisture resistance and durability for beverage and personal care segments. California's SB 54 recyclability mandates are accelerating demand for mono-material constructions that simplify PET container recycling streams.
- Vinyl Labels:PVC and vinyl ester films provide outdoor durability and chemical resistance for industrial applications.
- Specialty Labels:Holographic, tamper-evident, and temperature-sensitive constructions serve anti-counterfeiting and cold-chain logistics requirements.
Leading the category by volume: Paper Labels. Growing fastest: Plastic Labels.
End User:
Customer procurement power varies dramatically, with healthcare and automotive buyers demanding serialization capabilities while food and beverage purchasers prioritize unit cost reduction.
- Food & Beverage:The largest volume segment spanning packaged goods, craft beverages, and prepared foods. FDA food contact compliance requirements and retailer sustainability scorecards are reshaping substrate specifications toward recyclable and compostable alternatives.
- Healthcare:Pharmaceutical serialization and medical device labeling generate superior margin pools through FDA drug supply chain security mandates. Track-and-trace requirements with integrated authentication features command premium pricing.
- Retail:Private-label and branded consumer goods applications emphasize shelf appeal and variable data personalization for seasonal promotions.
- Automotive:Under-hood and exterior applications demand temperature resistance and chemical stability for parts identification and warranty tracking.
Highest margin concentration: Healthcare. Steepest volume expansion: Food & Beverage.
Technology:
Capital investment thresholds and run-length economics determine technology adoption patterns across converter operations.
- Digital Printing:Inkjet and toner-based systems eliminate plate costs and enable variable data personalization. Regional craft beverage producers in California and the Pacific Northwest adopt these platforms for shorter runs and mass customization.
- Flexographic Printing:Rotary letterpress technology dominates high-volume beverage and food applications with speeds exceeding 15,000 labels per hour.
- Gravure Printing:Cylinder-based systems serve ultra-long runs with consistent color reproduction for national brand campaigns.
- Offset Printing:Lithographic methods retain niche position for premium cosmetic and specialty applications requiring fine detail reproduction.
Widest installed base: Flexographic Printing. Gaining share fastest: Digital Printing.
Application:
Functional requirements dictate adhesive formulation and face stock selection across use cases.
- Packaging:Primary and secondary container labeling accounts for the majority of volume, with wash-away adhesives gaining traction for PET recycling compatibility.
- Inventory Management:Barcode and RFID-enabled labels support warehouse automation and supply chain visibility requirements.
- Product Branding:Premium cosmetic and personal care applications demand tactile finishes and metallic effects for shelf differentiation.
- Shipping:Logistics labels with all-temperature adhesives serve e-commerce fulfillment and parcel distribution networks.
Dominant volume share: Packaging. Fastest technology refresh: Inventory Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North American self-adhesive labels market exhibits a pronounced production-consumption asymmetry. The United States generates the majority of regional demand while Canada and Mexico serve as specialized production nodes with distinct export orientations.
United States
California's SB 54 extended producer responsibility mandate and FDA food contact compliance requirements are consolidating demand for recyclable label substrates. The EPA's Clean Air Act volatile organic compound standards constrain solvent-based adhesive formulations, accelerating water-based and UV-curable system adoption. Midwest manufacturing belt converters near Chicago, Detroit, and Milwaukee supply just-in-time labels to food processors and beverage bottlers.
Canada
Health Canada and PMRA regulate pharmaceutical and food contact label applications with standards harmonized to FDA benchmarks. Ontario and Quebec host specialized converters serving cross-border supply chains into the US Great Lakes region. Toronto-area operations focus on healthcare serialization labels for FDA-compliant drug exports.
Mexico
Nuevo León and the Bajío Region concentrate maquiladora operations producing labels for re-export to US consumer goods manufacturers. Mexico's environmental regulator SEMARNAT enforces evolving adhesive emission standards that align with EPA thresholds. Guadalajara-area converters supply craft beverage brands in the Pacific Northwest through integrated North American logistics networks.
Pacific Northwest
Oregon's packaging extended producer responsibility program imposes material recovery obligations that reshape substrate selection criteria for regional craft beverage producers. Washington State's clean manufacturing standards favor water-based adhesive platforms. Seattle and Portland metro areas cluster digital printing operations serving short-run customization demands.
Southeast
Georgia and Florida distribution hubs serve retail and logistics labeling demand from e-commerce fulfillment networks. State-level workplace safety regulations align with OSHA exposure limits for adhesive handling operations. Atlanta-area converters specialize in inventory management labels with RFID integration for warehouse automation systems.
North America Self-Adhesive Labels Market Competitive Landscape
The competitive structure tilts toward integrated materials science specialists with captive adhesive and substrate capabilities. Tier-one players combine face stock manufacturing, adhesive formulation, and coating operations under unified control. Mid-scale converters compete through geographic proximity to end-use clusters and specialized certification portfolios. Dominant competitive moves include strategic partnerships with beverage brand procurement teams and capacity expansion near Midwest manufacturing belt demand centers.
Within the integrated materials tier, Avery Dennison Corporation and 3M occupy positions defined by proprietary adhesive platforms and broad substrate portfolios. CCL Industries anchors specialized pharmaceutical and beverage label operations with regulatory certification depth. Multi-Color Corporation represents the converter archetype competing through regional production density and vertical integration into pre-press services. These three company types exemplify the strategic segmentation between materials innovators, regulatory specialists, and scale-driven converters.
| Leading Market Players |
|---|
| Multi-Color Corporation |
| UPM |
| Avery Dennison Corporation |
| H.B. Fuller Company |
| DuPont |
| CCL Industries |
| LINTEC Corporation |
| Consolidated Label Co |
| 3M |
| Others |
Pricing and Supply Chain Analysis
Captive adhesive formulation capabilities anchor both supply security and pricing power for integrated converters across the North American self-adhesive labels market. Tier-one players with in-house coating operations command premium positioning against mid-scale competitors dependent on merchant adhesive supply.
Pricing Analysis
Margin tightening in standard paper grades reflects pulp price volatility and energy-intensive coating processes pressuring converter economics. Three-tier pricing structure across premium, standard, and economy levels separates healthcare serialization labels with FDA compliance premiums from commodity food packaging grades. Cost-down pressure on standard paper labels accelerates because major retailers now mandate third-party recyclability certifications as mandatory bid criteria. Healthcare and pharmaceutical buyers exhibit lowest price sensitivity due to regulatory compliance requirements, while food and beverage procurement teams prioritize unit cost reduction above substrate performance attributes.
Supply Chain Analysis
Regional distribution centers in Illinois, Ohio, and Georgia anchor hub-and-spoke patterns serving Midwest manufacturing belt demand clusters. Raw material supply draws from specialty coated paper producers in Wisconsin and Minnesota, silicone release liner manufacturers in South Carolina, and acrylic adhesive compounders in Texas and Louisiana. Single-source vulnerability concentrates in silicone-coated release liner production, where limited North American converter capacity creates input bottlenecks during demand surges. Distribution runs through just-in-time logistics networks linking label converters to Chicago-area food processors and Detroit automotive production facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
California's SB 54 extended producer responsibility mandate is consolidating demand around compliant substrate portfolios, forcing smaller converters without certification depth toward acquisition or exit.
For Market Incumbents: To counter margin compression in commodity paper grades, deepen backward integration into adhesive formulation and secure captive silicone release liner supply agreements. Capacity addition near Pacific Northwest craft beverage clusters captures regional digital printing demand while reducing logistics exposure to Midwest pulp supply volatility. For New Entrants and Emerging Players: E-commerce platform channels offer direct routes to mid-sized regional brands previously locked out of converter minimum order quantities. Healthcare serialization labels with integrated authentication features represent the most penetrable white-space segment, given FDA drug supply chain security mandates and incumbent capacity constraints. A certification-first go-to-market angle accelerates supplier qualification timelines against established competitors. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by integrated materials science specialists seeking geographic density in the Midwest manufacturing belt. Long-term viability favors converters with established wash-away adhesive platforms and compostable substrate portfolios aligned with evolving EPA sustainable packaging guidelines. Watch Oregon and Maine extended producer responsibility program implementation timelines as inflection indicators for substrate specification shifts across regional procurement teams.| Strategic Initiative | Industry Significance |
|---|---|
| Wash-Away Adhesive Platform Development | Avery Dennison's materials science investment simplifies PET container recycling for California SB 54 compliance. |
| Digital Printing Capacity Expansion | Pacific Northwest craft beverage producers adopt inkjet systems for shorter runs and mass customization capabilities. |
| Healthcare Serialization Certification | FDA drug supply chain security mandates drive premium pricing for track-and-trace labels with authentication features. |
| Midwest Manufacturing Belt Proximity | Chicago and Detroit converter clustering reduces logistics costs for just-in-time delivery to food processors. |
| Silicone Release Liner Supply Security | Limited North American converter capacity creates acquisition value for captive coating operations in Wisconsin. |
Research Methodology
Independent corroboration across label converter executives, adhesive formulation specialists, and beverage brand procurement managers underwrites the qualitative findings in this study. Primary fieldwork engaged technical R&D directors at integrated materials science companies, plant managers at Midwest coating operations, and sustainability officers at major retailers. Secondary validation drew from EPA Clean Air Act enforcement data, FDA food contact guidance documents, state-level extended producer responsibility regulatory filings, and customs records tracking silicone release liner import flows. Bottom-up segmentation modeling triangulated against top-down market sizing from industry association production statistics.
Rate-of-change decomposition across product type, end-use application, printing technology, and geographic demand cluster dimensions shaped the analytical framework. CAGRs derived from segment-level growth trajectory analysis incorporating digital printing adoption curves, regulatory compliance transition timelines, and substrate substitution elasticity estimates. Industry-specific forecast inputs included rotary application equipment speed benchmarks and variable data personalization demand indices from regional craft beverage producers.
The model holds under stable EPA and state-level regulatory enforcement intensity; deviation in California SB 54 implementation timelines or Oregon EPR program expansion would shift substrate demand trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Ethical Label Market
Labels
Global QR Code Labels Market
Labels
Global Label Market
Labels
Asia-Pacific Self-Adhesive Labels Market
Labels
Foam Labels Market
Labels
Shipping Label Market
Labels
Wrap Around Labels Market
Labels
Global Resealable Packaging Labels Market
Labels
Holographic Labels Market
Labels
Safety Labels Market
Labels
Global Tamper Evident Labels Market
Labels
Global Print and Apply Labeling and Labeling Equipment Market
Labels
Heat Shrink Sleeve Market
Labels
Thermal Labels Market
Labels
India Print Label Market
Labels
Extended Text Labels Market