
 Solar Refrigerators Market | 2026-2036
Solar Refrigerators Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Refrigerators Market Insights
The EU Green Deal is recalibrating cold-chain infrastructure requirements across European pharmaceutical distribution networks. Dometic Group AB leverages its established RV and marine refrigeration expertise to extend into solar-powered medical transport units. EcoFlow anchors its position through integrated energy storage systems that pair lithium-ion battery packs with DC compressor modules. Sundanzer specializes in ultra-low-energy absorption units purpose-built for off-grid clinics in equatorial regions.
Solar refrigerators are thermally insulated cabinets that utilize photovoltaic-generated electricity to drive vapor-compression, absorption, or thermoelectric cooling cycles, typically maintaining temperatures between 2°C and 8°C for vaccine preservation or sub-freezing conditions for ice production. Compression technology dominates unit shipments due to mature supply chains and coefficient-of-performance advantages in tropical climates. The off-grid installation category captures the fastest expansion as humanitarian organizations and national immunization programs bypass centralized grid dependency entirely. Smart technology integration—remote temperature monitoring, automated defrost, and predictive maintenance algorithms—represents the emerging margin pool as buyers prioritize uptime guarantees over capital cost minimization.
The FDA's vaccine cold-chain guidance, India's CDSCO equipment certification requirements, and the EU's MDR together establish performance baselines that solar refrigerator manufacturers must satisfy for institutional procurement eligibility. WHO prequalification standards further filter market access for products targeting Gavi-funded immunization programs. Stakeholders must monitor evolving battery chemistry regulations and refrigerant phase-down schedules under the Kigali Amendment to anticipate compliance cost trajectories.
Market Dynamics
Off-grid healthcare infrastructure mandates are forcing solar refrigerator manufacturers to integrate predictive maintenance algorithms and remote monitoring capabilities directly into unit specifications, compressing traditional hardware-only procurement cycles.
Growth Catalysts
- WHO prequalification standards:Gavi-funded immunization programs require solar refrigerator compliance, locking in institutional demand across sub-Saharan Africa and South Asia.
- India's CDSCO cold-chain mandates:Pharmaceutical distribution networks must maintain 2°C to 8°C vaccine storage independent of grid reliability, accelerating solar unit adoption.
- Lithium-ion battery cost curves:Integrated DC compressor modules now pair with energy-dense storage at viable price points for rural clinic deployments.
Market Restraints
- Absorption unit supply concentration:Ultra-low-energy cooling systems rely on specialized component manufacturers clustered in Germany and Japan, creating single-source vulnerability.
- Refrigerant phase-down schedules:The Kigali Amendment forces R-134a and R-404A replacement, requiring engineering redesigns before existing certification cycles expire.
- PV panel input volatility:Polysilicon price swings and wafer supply bottlenecks from Chinese manufacturing hubs compress hardware margins unpredictably.
Strategic Opportunities
- Nigeria's rural electrification gaps:National vaccine distribution networks bypass grid infrastructure entirely, creating first-mover advantage for solar cold-chain providers.
- Smart technology convergence:IoT temperature sensors married to satellite connectivity enable real-time cold-chain verification for international health organizations.
- EU Green Deal procurement incentives:European pharmaceutical distributors now weight carbon footprint in vendor selection, favoring solar-powered transport refrigeration.
Industry Challenges
- WHO prequalification timeline compression:Field validation studies in tropical climates require 12-18 months, delaying market entry for redesigned units.
- Legacy grid-tied system integration:Hybrid installations demand electrical engineering capabilities scarce in rural deployment zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Refrigerators Market |
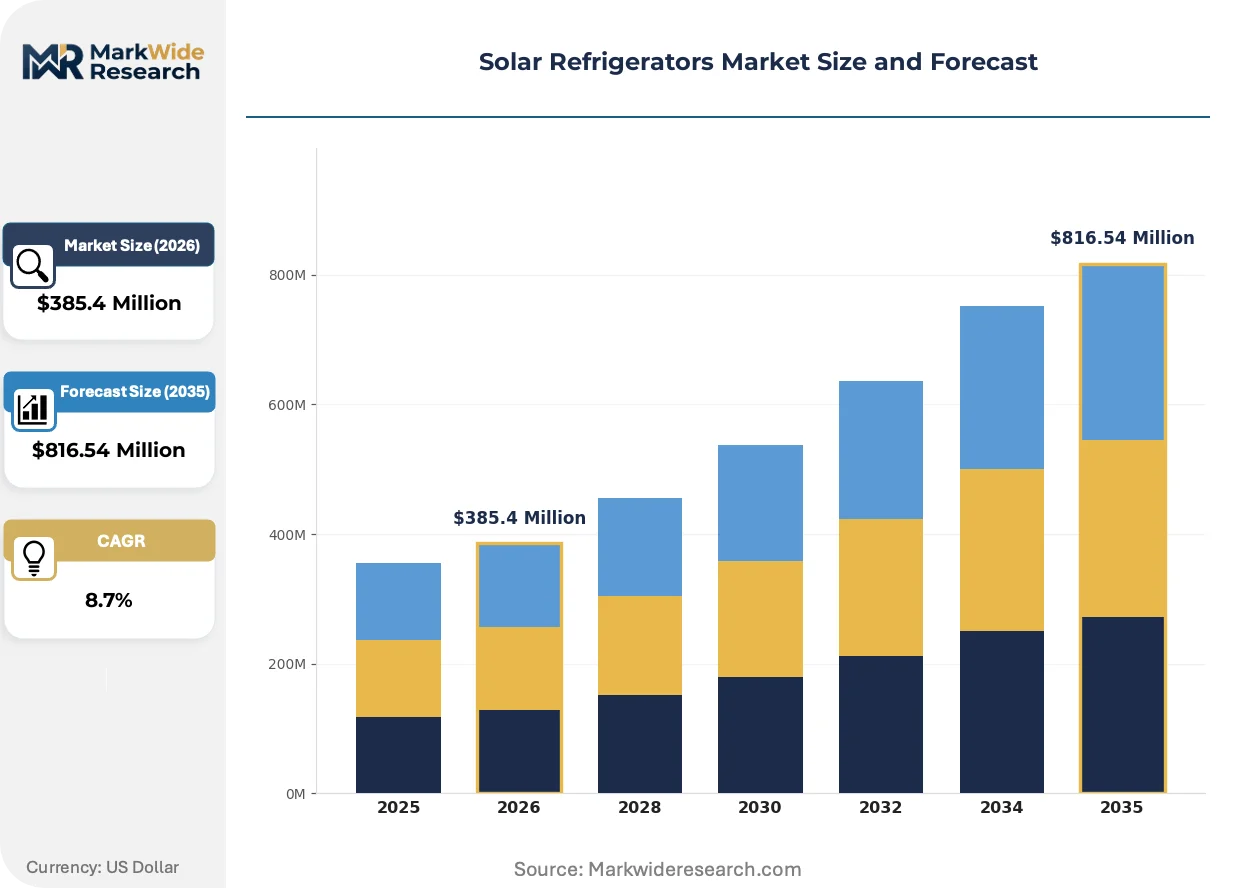
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $816.54 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorption, Compression, Thermoelectric, Hybrid End User: Residential, Commercial, Industrial, Healthcare Installation Type: Portable, Fixed, Built-in, Off-grid Technology: Solar PV, Solar Thermal, Energy Storage, Smart Technology |
| Companies Covered | Sundanzer, EcoFlow, Dometic Group AB, Kyocera Corporation, Viking Cold Solutions, Inc., GoSun, Promethean Power Systems, Unique Appliances Ltd., Aldelano Solar Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Refrigerators Market Trends and Innovations
Remote temperature monitoring platforms are compressing service response times from days to hours. Battery chemistry evolution and predictive analytics are converging to redefine uptime guarantees as the primary competitive differentiator.
DC compressor technology paired with lithium iron phosphate battery packs is decentralizing cold-chain infrastructure ownership. Off-grid clinics in Kenya and Tanzania now deploy standalone units without centralized maintenance contracts. This shift is compressing the addressable market for traditional service-based refrigeration vendors.
The EU's MDR and F-Gas Regulation together mandate refrigerant tracking across pharmaceutical distribution networks. Equipment suppliers must now certify full lifecycle environmental impact, not just operational efficiency. Solar absorption units using ammonia-water cycles are capturing preference in European medical transport applications.
Humanitarian procurement offices now bundle hardware purchase with 10-year uptime guarantees. Gavi and UNICEF tender documents specify predictive maintenance inclusion, displacing capital-expenditure-only bidding. This behavioral pivot concentrates demand among vendors with integrated service platforms, most visible in Nigerian and Kenyan national immunization program tenders.
Solar Refrigerators Market Segmentation
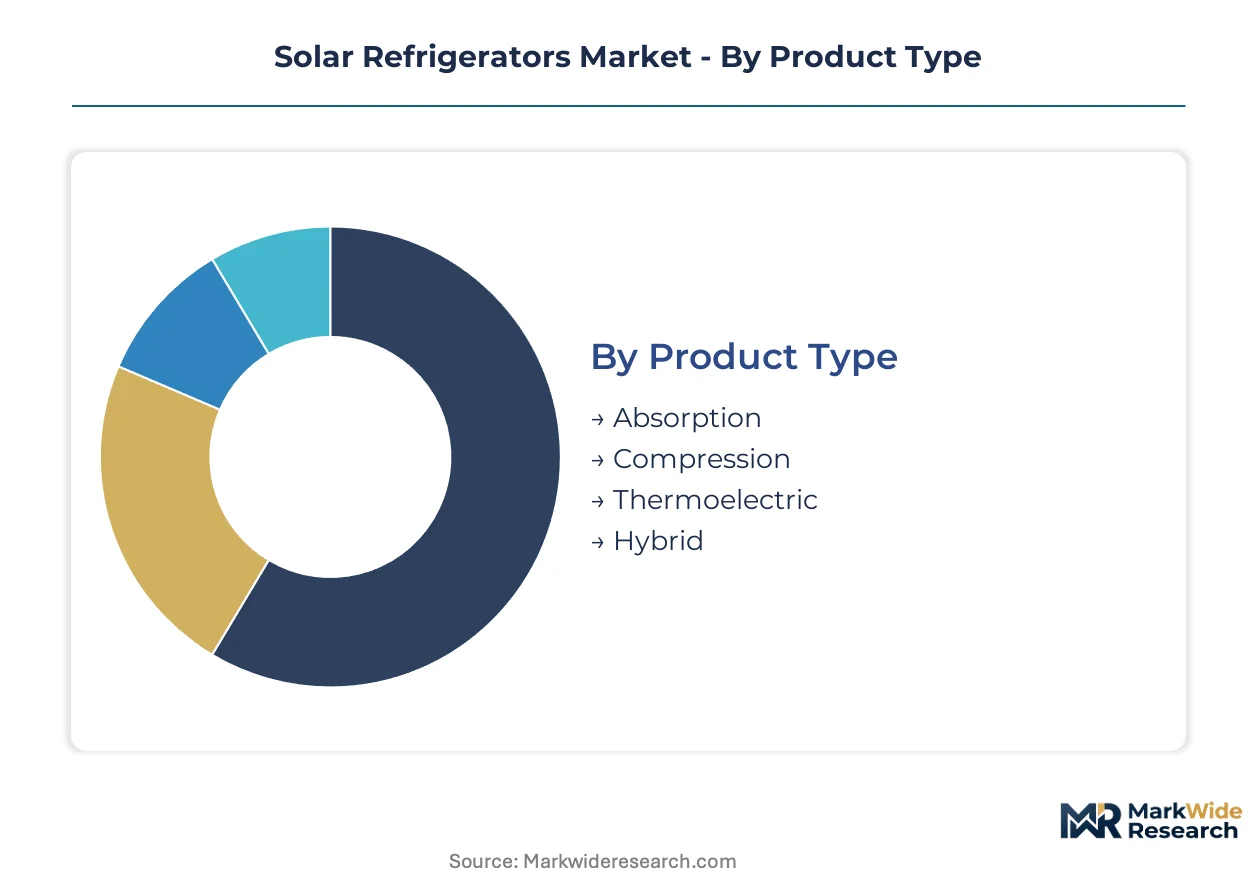
Solar refrigerator procurement varies sharply across use cases, from standardized WHO-prequalified units for immunization programs to custom-engineered systems for pharmaceutical transport. Segmentation reveals where margin pools concentrate and which technology configurations command premium positioning.
Product Type:
Customization intensity spans purpose-built absorption units for equatorial clinics to mass-produced compression systems for residential off-grid deployments.
- Compression:Vapor-compression cycles using DC compressors paired with lithium-ion storage dominate tropical healthcare installations. Nigeria's national vaccine program and Kenya's rural clinic networks specify these units for coefficient-of-performance advantages in high-ambient conditions.
- Absorption:Ammonia-water absorption systems operate without moving parts, achieving ultra-low energy draw for equatorial off-grid clinics. Component supply concentrates in German and Japanese manufacturing clusters, constraining procurement timelines for Gavi-funded programs.
- Thermoelectric:Solid-state Peltier cooling serves portable medical transport where mechanical reliability outweighs efficiency penalties.
- Hybrid:Dual-cycle configurations switch between solar PV and grid power, addressing India's CDSCO mandates for uninterrupted cold-chain integrity.
Most installed capacity flows through Compression. Expansion is steepest in Absorption.
End User:
Price sensitivity and certification requirements diverge across customer categories, from institutional procurement offices to individual household purchasers.
- Healthcare:WHO prequalification and CDSCO certification govern procurement for vaccine storage, with Gavi tenders mandating predictive maintenance inclusion. UN agencies and national immunization programs in sub-Saharan Africa represent the concentrated demand pool.
- Commercial:Pharmaceutical distributors under EU MDR and F-Gas Regulation face carbon footprint disclosure requirements, favoring solar-powered transport refrigeration for last-mile delivery.
- Residential:Rural electrification gaps in Tanzania and Kenya drive household adoption of small-capacity DC units without grid connection.
- Industrial:Cold-chain hubs for agricultural export processing deploy large-scale absorption arrays where grid reliability cannot support temperature-sensitive cargo.
Procurement volume concentrates in Healthcare. Margin expansion is most pronounced in Commercial.
Installation Type:
Deployment flexibility requirements shape engineering specifications from mobile field units to permanent clinic infrastructure.
- Off-grid:Standalone systems with integrated PV arrays and lithium iron phosphate batteries bypass grid dependency entirely. Humanitarian organizations in Nigeria deploy these for rural immunization outreach.
- Portable:Lightweight thermoelectric units with foldable solar panels serve mobile vaccination teams and emergency medical response.
- Fixed:Permanent installations anchor district-level vaccine stores with satellite-linked temperature monitoring for real-time compliance verification.
- Built-in:Custom-integrated cold rooms for pharmaceutical manufacturing facilities under EU MDR environmental impact tracking requirements.
Deployment scale favors Fixed installations. Urgency of need is greatest in Portable.
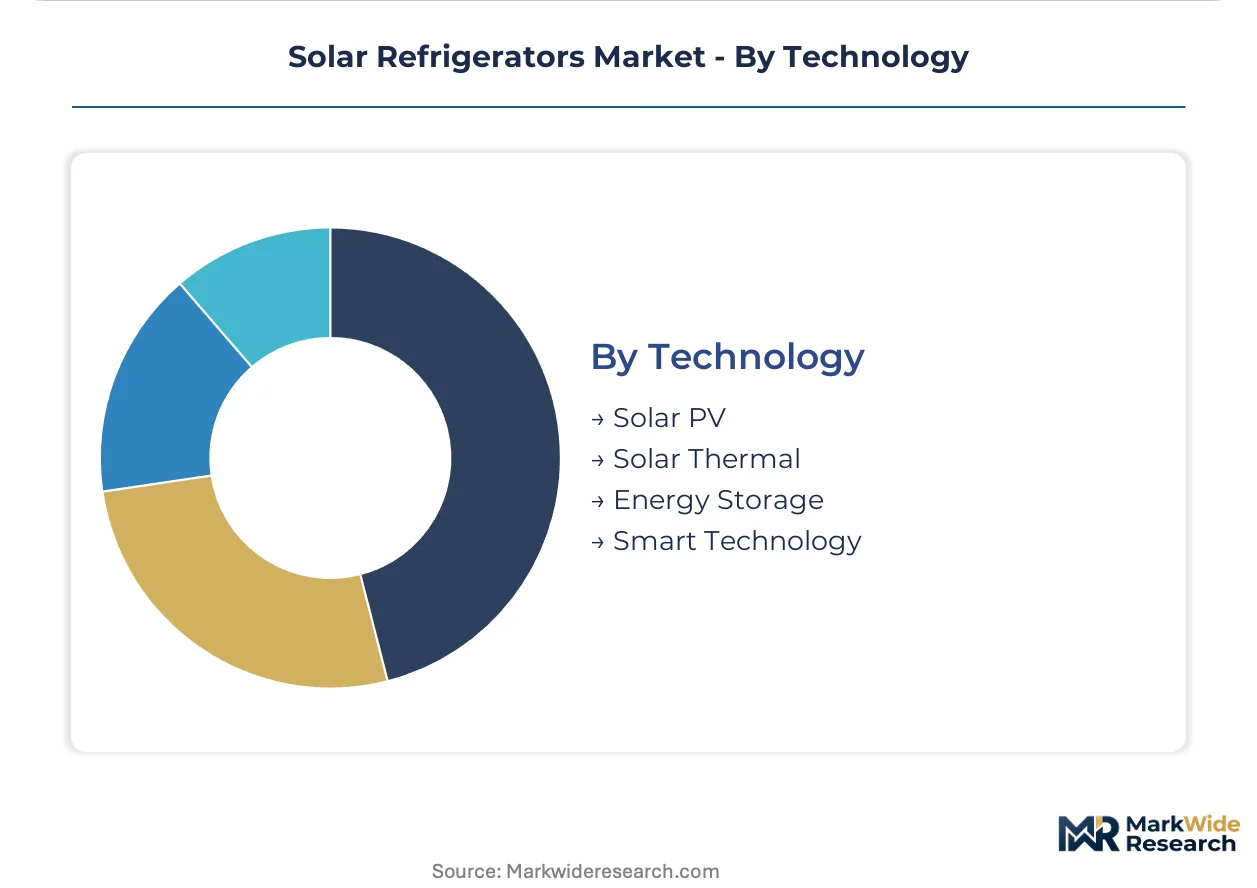
Technology:
System architecture choices determine whether units function as passive hardware or active data nodes within monitored cold-chain networks.
- Smart Technology:IoT temperature sensors with satellite connectivity enable real-time cold-chain verification for international health organizations. Predictive maintenance algorithms compress service response times from days to hours.
- Energy Storage:Lithium-ion and lithium iron phosphate battery packs paired with DC compressor modules decentralize infrastructure ownership, displacing traditional service-based vendor relationships.
- Solar PV:Photovoltaic panels with MPPT charge controllers constitute the primary electricity generation layer for all solar refrigerator categories.
- Solar Thermal:Absorption-cycle activation through evacuated tube collectors serves niche applications in equatorial regions with consistent direct irradiance.
Component value accrues to Smart Technology. Adoption velocity is highest in Energy Storage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Field engineers and cold-chain technicians cluster around Lagos, Nairobi, and Dar es Salaam where immunization programs drive deployment density. Procurement offices in these hubs coordinate WHO prequalification workflows and Gavi tender compliance. Talent scarcity in remote site commissioning creates wage premiums for technicians willing to deploy to rural clinics.
Nigeria
Rural electrification gaps exceed 40% in northern states, forcing the National Primary Health Care Development Agency to specify solar cold-chain units for vaccine outreach. The country's national pharmaceutical regulator mandates temperature documentation for all immunization program procurements. Kano and Kaduna host deployment coordination centers where field validation studies compress WHO prequalification timelines.
Kenya
Off-grid health facilities in Turkana and Marsabit counties order standalone absorption units to bypass diesel generator dependency. Kenya's Pharmacy and Poisons Board enforces cold-chain integrity standards for all Gavi-funded vaccine stores. Nairobi anchors technical service networks that dispatch predictive maintenance crews to remote installations within 48 hours.
India
CDSCO mandates for uninterrupted 2°C to 8°C storage are recalibrating state vaccine depot specifications toward hybrid solar-grid configurations. The national pharmaceutical regulator's equipment certification requirements lock out uncertified suppliers from institutional tenders. Hyderabad and Pune host manufacturing clusters where DC compressor modules integrate with lithium iron phosphate battery packs.
Germany
The EU's MDR and F-Gas Regulation together require lifecycle environmental impact disclosure for pharmaceutical transport refrigeration. ECHA chemical safety standards constrain refrigerant selection for equipment entering European distribution networks. Munich and Stuttgart anchor component manufacturing for ultra-low-energy absorption systems serving equatorial clinic deployments.
United States
FDA vaccine cold-chain guidance shapes procurement specifications for PEPFAR-funded programs operating in sub-Saharan Africa. The agency's temperature monitoring requirements accelerate adoption of satellite-linked IoT sensors in overseas health facility deployments. Atlanta and Washington D.C. concentrate program management offices that coordinate solar refrigerator specifications for international immunization partnerships.
Solar Refrigerators Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the solar refrigerator market. Integrated manufacturers controlling PV panel, battery, and compressor supply chains face modular assemblers sourcing components through distributed procurement networks. The vendor base stratifies into three archetypes: full-stack energy storage specialists, legacy refrigeration incumbents extending product lines, and ultra-low-energy absorption purists. Competitive positioning hardens through WHO prequalification portfolio breadth and predictive maintenance platform maturity.
Among absorption-cycle specialists, Sundanzer exemplifies the ultra-low-energy archetype purpose-built for equatorial off-grid clinics. EcoFlow and Dometic Group AB occupy positions at the integrated-systems end, with the former representing energy storage convergence and the latter anchoring recreational vehicle refrigeration expertise extended into medical transport applications. These three companies illustrate how technology lineage shapes competitive territory.
| Leading Market Players |
|---|
| Sundanzer |
| EcoFlow |
| Dometic Group AB |
| Kyocera Corporation |
| Viking Cold Solutions, Inc. |
| GoSun |
| Promethean Power Systems |
| Unique Appliances Ltd. |
| Aldelano Solar Solutions |
| Others |
Pricing and Supply Chain Analysis
DC compressor integration with lithium iron phosphate battery packs is compressing unit economics while concentrating procurement leverage among integrated energy storage specialists. This technological convergence simultaneously lowers per-unit hardware costs and raises barriers for modular assemblers lacking captive battery supply.
Pricing Analysis
Outcome-based contracting with 10-year uptime guarantees dominates institutional procurement from Gavi and UNICEF. Pricing stratifies across WHO-prequalified premium tiers, CDSCO-certified standard tiers, and uncertified economy tiers for residential off-grid deployments. Cost compression in the economy tier is intensifying because polysilicon price volatility feeds directly into PV panel input costs. National immunization programs show least price sensitivity, while rural household purchasers in Tanzania and Kenya exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing requirements from WHO and Gavi procurement offices mandate qualified suppliers for DC compressors, battery packs, and absorption-cycle components across multiple geographies. Manufacturing concentrates in China for PV panels and lithium-ion cells, Germany for precision absorption components, and India for DC compressor module assembly. The supply chain draws from polysilicon wafers, rare earth elements for compressor motors, and ammonia-water working fluids. Single-source vulnerability in German and Japanese absorption component clusters creates qualification timeline risk. Distribution runs through Lagos, Nairobi, and Dar es Salaam procurement hubs coordinating field validation and rural deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where lithium-ion battery cost curves in China-enabled manufacturing clash against EU MDR carbon-footprint disclosure requirements, creating divergent margin structures across procurement zones.
For Market Incumbents: Acquire predictive maintenance platform capabilities to defend service-embedded contract structures against hardware-only challengers. CDSCO certification investment in India locks out uncertified competitors from state vaccine depot tenders. Backward integration into lithium iron phosphate cell production secures margin control as battery costs dominate unit economics. For New Entrants and Emerging Players: EU Green Deal procurement incentives in Europe open a window for solar-powered transport refrigeration specialization. Nigeria's northern states with 40% rural electrification gaps represent the most penetrable geography for standalone off-grid units. Satellite-linked temperature monitoring bundled with hardware offers differentiated positioning against incumbent service networks. For Investors and Strategic Acquirers: Valuations sit cheapest among component-agnostic modular assemblers lacking WHO prequalification portfolios. Long-term viability hinges on regulatory certification moats widening through Kigali Amendment refrigerant phase-downs and evolving battery chemistry standards. Watch for absorption-cycle component supply consolidation in Germany and Japan as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| WHO Prequalification Expansion | Unlocks Gavi-funded tenders across sub-Saharan African national immunization programs. |
| Predictive Maintenance Platform Development | Compresses service response times from days to hours for remote clinic deployments. |
| Lithium Iron Phosphate Integration | Decentralizes cold-chain ownership by enabling standalone units without grid dependency. |
| EU MDR Carbon Footprint Certification | Qualifies equipment for pharmaceutical distributor procurement under Green Deal incentives. |
| Absorption Cycle Component Sourcing Diversification | Mitigates single-source risk from German and Japanese manufacturing concentration. |
Research Methodology
Bottom-up healthcare deployment modeling reconciled against top-down solar refrigeration manufacturing tracking forms the analytical core. Primary interviews with cold-chain logistics officers, biomedical engineers at rural clinics, Gavi procurement managers, and national immunization program directors combined with secondary validation from WHO prequalification databases, CDSCO equipment certification registries, and customs import records. Triangulation across stakeholder inputs and documentary sources ensures segmentation integrity.
Input-output matrices map DC compressor shipments, battery pack integrations, and PV panel deployments to end-use installations across the projection horizon. Segmentation dimensions include cooling technology type, installation configuration, end-user category, and smart technology integration level. CAGRs derive from unit shipment trajectories weighted by average selling price evolution. Forecast inputs incorporate lithium-ion cost curves, refrigerant phase-down schedules under the Kigali Amendment, and rural electrification gap projections from national development agencies.
Revisions become necessary when WHO prequalification timelines compress further, polysilicon supply disruptions extend beyond Chinese manufacturing hubs, or India's CDSCO mandates expand to additional pharmaceutical distribution tiers. Deviation in battery chemistry safety regulations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Critical Power and Cooling Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Solar-Assisted Heat Pump Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Cooling Tower Rental Market
Cooling Systems
Solar Air Conditioning Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Portable Chiller Market
Cooling Systems
Plate and Frame Heat Exchangers Market
Cooling Systems
Chilled Water System Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Saudi Arabia Desert Air Coolers Market
Cooling Systems
Temporary Power and Cooling Solutions Market
Cooling Systems
Radiant Cooling Systems Market