
 Central Asia Oil and Gas Upstream Market | 2026-2036
Central Asia Oil and Gas Upstream Market Size, Share, and Industry Trends Forecast 2026-2036
Central Asia Oil and Gas Upstream Market Outlook
Advanced chromium steel alloys is consolidating as the preferred metallurgy for sour gas wellheads across Kashagan-type high-pressure reservoirs. KazMunayGas leverages captive steel supply chains to control fabrication costs for its Tengiz expansion program. Chevron Corporation anchors the largest foreign-operated stake in the Tengizchevroil joint venture, sustaining output through staged compression upgrades. Shell PLC competes through deepwater exploration partnerships in the Caspian's Kazakh and Turkmen sectors.
Central Asia oil and gas upstream encompasses exploration, drilling, and production of hydrocarbons from subsurface reservoirs, requiring wellhead ratings exceeding 15,000 psi and hydrogen sulfide-resistant metallurgy for sour service conditions. The primary purpose is extracting crude oil and natural gas for transport to midstream processing and eventual refining into fuels and petrochemicals. Onshore exploration dominates activity volumes across the region, though offshore Caspian blocks carry disproportionate capital intensity and reserve scale. Enhanced Oil Recovery technology leads production-method investments as mature fields in Kazakhstan face natural decline rates. Horizontal well completion is displacing vertical architectures in the Karachaganak field, concentrating drilling service demand.
Kazakhstan's Ministry of Energy and the State Inspectorate for Environment and Technical Safety enforce well construction standards aligned with GB-equivalent pressure vessel codes, while Turkmenistan's national petroleum regulator mandates domestic content thresholds for service contracts. These frameworks shape procurement patterns, requiring operators to source cementing and wireline services from locally registered vendors. Stakeholders must monitor regulatory divergence between Kazakh and Turkmen licensing regimes as field development timelines extend across the forecast horizon.
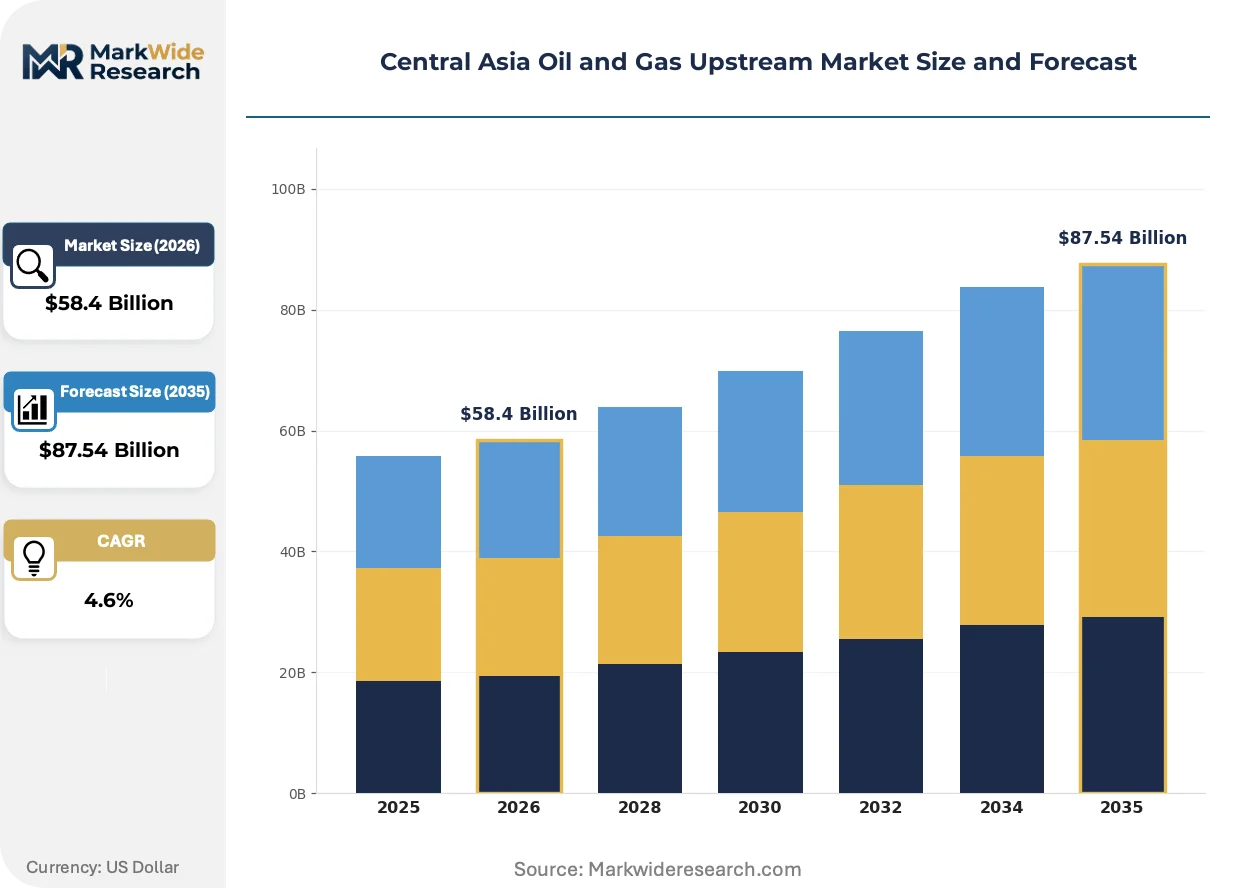
Market Dynamics
Staged compression upgrades across Tengiz-type supergiant fields are forcing capital reallocation toward high-pressure wellhead metallurgy, as operators confront hydrogen sulfide degradation in sour service reservoirs exceeding 15,000 psi ratings.
Growth Catalysts
- Petrochemical feedstock demand:Refinery expansion programs in Kazakhstan and Uzbekistan are pulling incremental crude throughput from upstream clusters. Western Kazakh field operators are prioritizing tie-in infrastructure to capture this demand.
- GB-equivalent pressure vessel codes:Kazakhstan's Ministry of Energy well construction standards are mandating upgraded well integrity systems. Compliance investments are accelerating replacement cycles for aging wellhead infrastructure.
- Enhanced Oil Recovery deployment:Mature onshore fields facing natural decline rates are deploying thermal and gas injection methods. EOR technology adoption is sustaining plateau production across Karachaganak-type carbonate reservoirs.
Market Restraints
- Chromium steel alloy supply concentration:Captive supply chains controlled by national oil companies limit third-party fabricator access to Kashagan-grade metallurgy. Independent service providers face input cost volatility and extended lead times.
- Domestic content thresholds:Turkmenistan's national petroleum regulator mandates local vendor registration for cementing and wireline contracts. Foreign operators encounter procurement friction when sourcing specialized downhole equipment.
- Deepwater capital intensity:Offshore Caspian blocks require disproportionate drilling expenditure relative to onshore analogs. Reserve scale advantages are offset by extended payback periods and technical complexity in high-pressure formations.
Strategic Opportunities
- Horizontal well completion expansion:Karachaganak field operators are displacing vertical architectures with extended-reach laterals. Drilling service demand is concentrating in directional specialists with sour gas expertise.
- Regulatory divergence arbitrage:Licensing timeline differentials between Kazakh and Turkmen regimes create portfolio optimization potential. Operators with cross-border project experience can sequence field development to capture fiscal term variations.
- Digital well monitoring convergence:Integration of fiber-optic sensing with artificial lift systems is enabling real-time reservoir management. Early adopters in the Tengiz cluster are compressing intervention response cycles.
Industry Challenges
- Sour service metallurgy certification:Hydrogen sulfide-resistant alloy qualification timelines extend procurement cycles for critical wellhead components. Operators face schedule risk when sourcing Kashagan-grade equipment under expedited drilling programs.
- Local vendor capability gaps:Cementing and wireline service quality variance across registered Turkmen suppliers requires intensive technical supervision. Field engineering resources are diverted from core reservoir activities to vendor qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Central Asia Oil and Gas Upstream Market |
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $87.54 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Exploration Type: Onshore, Offshore, Shale, Conventional Production Technology: Enhanced Oil Recovery, Steam Injection, Gas Injection, Artificial Lift Well Completion: Horizontal, Vertical, Multilateral, High-Pressure Service Type: Cementing, Drilling, Wireline, Fracturing |
| Companies Covered | PJSC Lukoil Oil Company, Karachaganak Petroleum Operating BV, KazMunayGas, Shell PLC, JSC Turkmengaz, Chevron Corporation, Sinopec Oilfield Service Corporation, National Company QazaqGaz JSC, Gazprom International Limited, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Central Asia Oil and Gas Upstream Market Strategic Shifts
Digitalization of subsurface characterization and modular surface facility design are compressing field development timelines across Central Asia's high-pressure sour gas provinces. Technology adoption patterns diverge between mature onshore brownfields and frontier offshore blocks.
Subsea modularization technology is modularizing production system architecture for deepwater Caspian developments. Kashagan-type high-pressure reservoirs require integrated wellhead-manifold packages that reduce offshore installation vessel time. Operators are compressing project schedules by standardizing module specifications across multiple field phases.
REACH-aligned chemical disclosure requirements are reshaping drilling fluid formulation strategies for operators with European equity partners. Kazakhstan's Ministry of Energy is incorporating EU environmental standards into tender documentation for offshore blocks. Service companies are reformulating synthetic-based mud systems to preempt regulatory friction in cross-border financing structures.
Integrated service contracting is displacing discrete procurement of drilling, completion, and intervention services across Tengiz expansion workscopes. National oil companies are bundling scope to transfer reservoir performance risk to integrated project management providers. This concentration is most visible in western Kazakhstan, where KazMunayGas anchors demand aggregation for supergiant field programs.
Central Asia Oil and Gas Upstream Market Segmentation
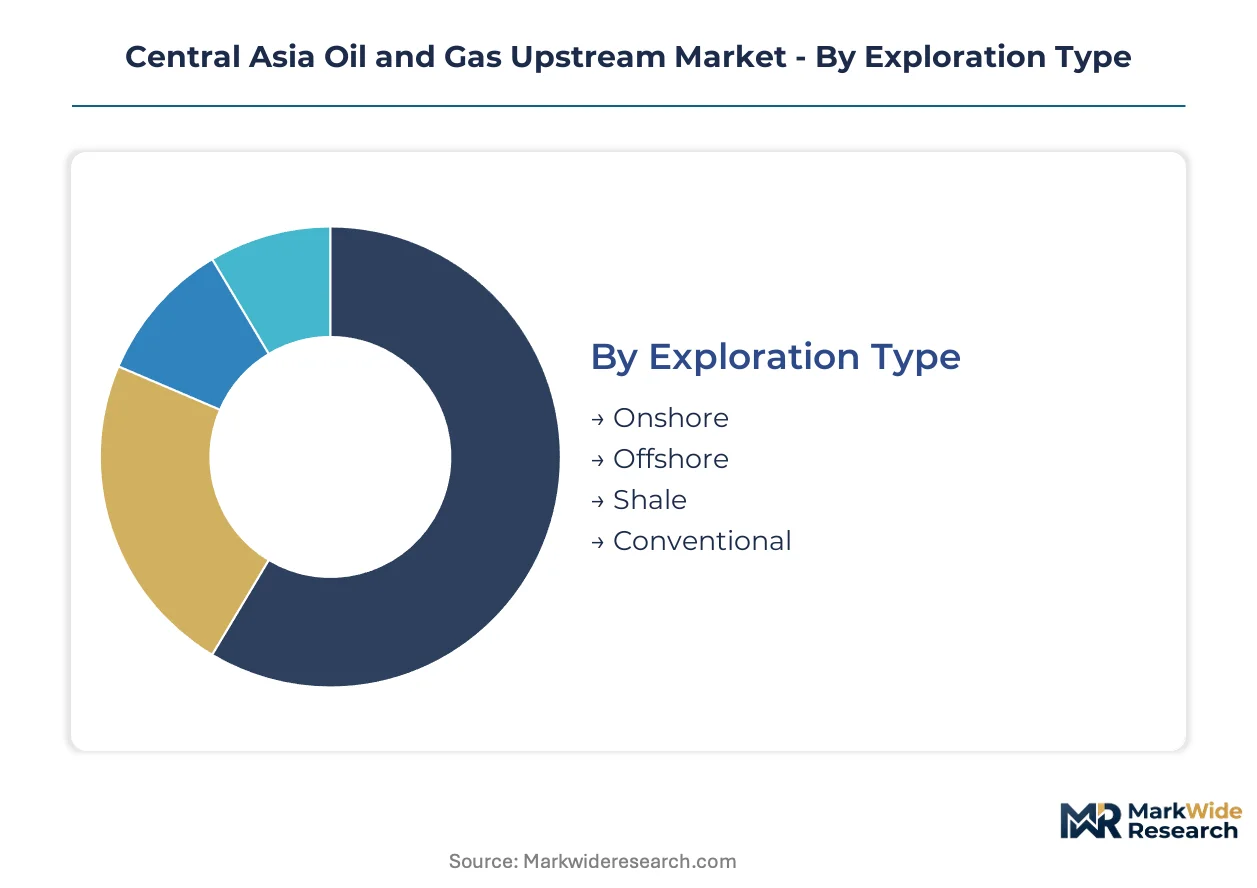
Segmentation reveals how procurement patterns diverge across Central Asia's upstream operations. Kazakhstan's Ministry of Energy certification requirements and Turkmenistan's domestic content mandates reshape competitive positioning within each category.
Exploration Type:
GB-equivalent pressure vessel codes apply differentially across exploration modalities, with offshore blocks facing the most stringent well integrity certification burdens.
- Onshore:Conventional drilling across western Kazakhstan's supergiant fields dominates activity volumes. Tengiz and Karachaganak field clusters anchor demand for high-pressure wellhead systems under Kazakh regulatory oversight.
- Offshore:Caspian shelf developments require integrated subsea packages and extended certification timelines for hydrogen sulfide-resistant metallurgy. Kashagan-type reservoirs force capital concentration toward modular production architecture.
- Shale:Unconventional resource assessment remains limited across Central Asian basins. Exploration permits face additional environmental review under evolving Ministry of Energy standards.
- Conventional:Mature carbonate reservoirs in Uzbekistan's Bukhara-Khiva region sustain baseline production through workover programs. These assets operate under lighter regulatory touch than frontier developments.
Onshore sits at the top of the volume ranking, with Offshore climbing the fastest.
Production Technology:
Cost tier differentiation separates thermal methods from gas injection across Kazakhstan's mature field portfolio.
- Enhanced Oil Recovery:Thermal and gas injection methods sustain plateau production across Karachaganak-type carbonate reservoirs facing natural decline. KazMunayGas prioritizes EOR deployment to maximize recovery factors from brownfield assets.
- Steam Injection:Heavy oil applications in select Kazakh shallow reservoirs require specialized boiler systems and water treatment infrastructure. Capital intensity limits deployment to highest-margin production blocks.
- Gas Injection:Miscible gas flooding dominates Tengiz field pressure maintenance programs. Chevron-operated joint ventures source injection gas from field-associated production.
- Artificial Lift:Progressive cavity and electric submersible pump installations concentrate in Uzbekistan's mature onshore stripper wells. Digital monitoring integration is compressing intervention response cycles.
EOR commands the highest capital allocation per barrel, while Artificial Lift expands most quickly through digital retrofit programs.
Well Completion:
Application-specific architectures separate sour service reservoirs from standard pressure regimes across the Caspian basin.
- Horizontal:Extended-reach laterals displace vertical architectures in Karachaganak field redevelopment. Directional specialists with sour gas expertise capture concentrated drilling service demand.
- Vertical:Straight-hole completions persist in Uzbekistan's conventional sandstone developments and appraisal drilling phases. Lower technical complexity reduces procurement friction under domestic content rules.
- Multilateral:Junction technology enables multiple drainage points from single motherbores in compartmentalized carbonate reservoirs. Deployment concentrates in Tengiz expansion workscopes.
- High-Pressure:Wellhead ratings exceeding 15,000 psi with hydrogen sulfide-resistant metallurgy define Kashagan-type developments. Chromium steel alloy qualification timelines extend procurement cycles for critical components.
Horizontal completions lead in new capital deployment, with High-Pressure systems gaining share fastest through Kashagan-phase development.
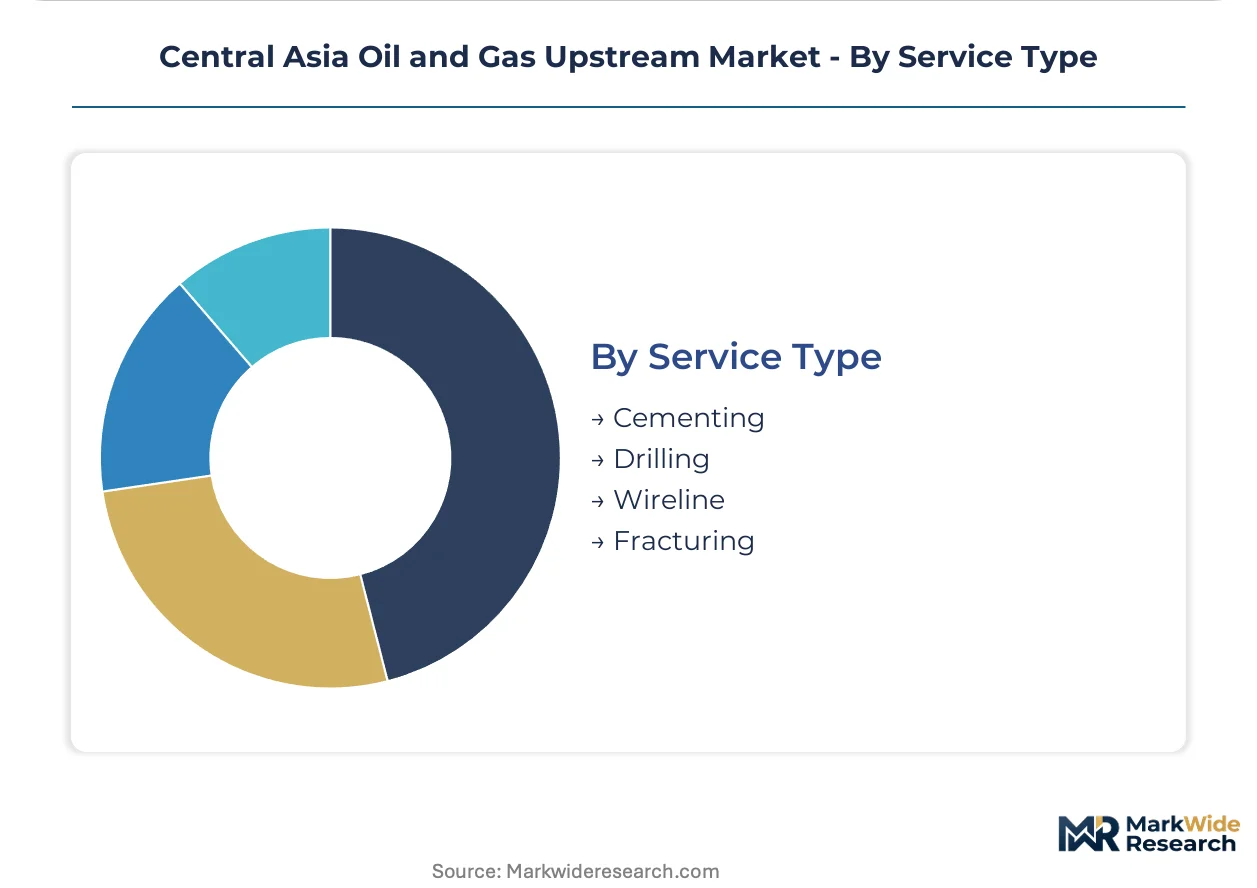
Service Type:
Supply concentration patterns separate cementing and wireline markets from fracturing and drilling services under Turkmenistan's local vendor registration regime.
- Cementing:Zonal isolation and casing cementing services face mandatory domestic content thresholds in Turkmenistan. Quality variance across registered suppliers demands intensive technical supervision.
- Drilling:Integrated project management contracting is displacing discrete procurement across Tengiz expansion programs. KazMunayGas bundles scope to transfer reservoir performance risk to providers.
- Wireline:Logging and perforation services require local vendor registration under Turkmenistan's national petroleum regulator mandates. Foreign operators encounter procurement friction sourcing specialized downhole equipment.
- Fracturing:Stimulation services remain concentrated in Kazakhstan's tight gas and unconventional assessments. Water sourcing constraints and environmental permits limit deployment scale.
Drilling services sit at the top of the volume ranking, with Cementing climbing the fastest under tightening well integrity standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tengiz field cluster anchors upstream capital deployment across Central Asia, with Kazakhstan's western provinces concentrating drilling service demand and wellhead metallurgy procurement.
Kazakhstan
Tengiz and Kashagan supergiants drive wellhead replacement cycles exceeding 15,000 psi ratings. The Ministry of Energy enforces GB-equivalent pressure vessel codes through well construction standards. Atyrau province fabricators supply chromium steel alloys to Tengizchevroil expansion programs.
Uzbekistan
Refinery expansion in Bukhara-Khiva pulls incremental crude from mature carbonate reservoirs. The national petroleum regulator mandates domestic content thresholds for cementing contracts. Surkhandarya basin operators deploy artificial lift systems across stripper well portfolios.
Turkmenistan
Offshore Caspian blocks require integrated subsea packages with extended metallurgy certification timelines. The national petroleum regulator restricts wireline and cementing procurement to locally registered vendors. Balkan province developments concentrate deepwater exploration expenditure.
Azerbaijan
Shah Deniz-type deepwater fields sustain demand for high-pressure sour service completion systems. The State Oil Company of Azerbaijan Republic coordinates offshore licensing through production-sharing agreements. Absheron basin drilling programs anchor regional rig utilization rates.
Central Asia Oil and Gas Upstream Market Competitive Environment
Global majors compete with regional champions across integrated project management contracting, with market structure tiering between scale-driven supermajors and state-backed national oil companies. Chevron Corporation and Shell PLC anchor foreign-operated stakes through production-sharing frameworks. Strategic archetypes separate integrated operators, captive supply chain controllers, and specialized drilling contractors. Dominant competitive moves include backward integration into steel supply chains and bundling of drilling-completion-intervention scope.
Among state-backed operators, KazMunayGas exemplifies captive supply chain control through vertical ownership of metallurgy procurement for Tengiz expansion. Chevron Corporation occupies a position representing scale-driven integrated project execution across supergiant field developments. Shell PLC anchors the deepwater exploration specialist archetype through Caspian offshore partnerships.
| Leading Market Players |
|---|
| PJSC Lukoil Oil Company |
| Karachaganak Petroleum Operating BV |
| KazMunayGas |
| Shell PLC |
| JSC Turkmengaz |
| Chevron Corporation |
| Sinopec Oilfield Service Corporation |
| National Company QazaqGaz JSC |
| Gazprom International Limited |
| Others |
Value Chain & Pricing Dynamics
Staged compression upgrades at Tengiz-type supergiant fields are forcing procurement teams toward hydrogen sulfide-resistant metallurgy that commands premium wellhead ratings, compressing supplier margins as fabricators absorb alloy certification costs while national oil companies leverage captive steel supply chains to control escalation.
Pricing Analysis
Input-cost pass-through from chromium steel alloy volatility defines contract structures across Kashagan-grade procurement cycles. Pricing stratifies across premium hydrogen sulfide-resistant systems, standard pressure-rated wellheads, and economy-tier artificial lift packages. Cost compression in the economy tier is intensifying because Turkmenistan's domestic content mandates force foreign operators toward lower-cost local cementing vendors. National oil companies exhibit lowest price sensitivity due to captive supply chain control, while independent service providers face acute margin pressure from extended lead times.
Supply Chain Analysis
Turkmenistan's domestic content thresholds and Kazakhstan's GB-equivalent pressure vessel codes are reshaping sourcing patterns toward locally registered vendors with constrained technical capabilities. Supply concentrates in Kazakhstan, Uzbekistan, and Russia for chromium steel alloy fabrication, wireline logging equipment, and directional drilling services. Procurement draws from hydrogen sulfide-resistant alloy foundries, high-pressure wellhead component machine shops, and synthetic-based mud chemical formulators. Single-source vulnerability runs through Kazakhstan's captive metallurgy supply chains controlled by KazMunayGas. Distribution runs through integrated project management contractors bundling drilling, completion, and intervention scope.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where well integrity investments are accelerating replacement cycles as Kazakhstan's Ministry of Energy tightens environmental standards and mandates upgraded metallurgy for sour service reservoirs.
For Market Incumbents: To counter input cost volatility in chromium steel alloys, Chevron-operated joint ventures and Shell PLC partnerships should deepen backward integration into alloy supply chains and consolidate drilling service procurement through integrated project management contracts. Capacity addition in Atyrau province fabrication hubs anchors cost control for Tengiz expansion programs. For New Entrants and Emerging Players: Capture white-space opportunity in digital well monitoring convergence, where fiber-optic sensing integration with artificial lift systems remains underpenetrated across Uzbekistan's mature Surkhandarya basin stripper wells. Horizontal well completion expertise in Karachaganak-type sour gas reservoirs offers the most penetrable service segment. Go-to-market positioning should emphasize regulatory divergence arbitrage between Kazakh and Turkmen licensing timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized directional drilling contractors holding sour gas certification and digital reservoir management capabilities. Long-term viability over a multi-year horizon rests on exposure to supergiant field redevelopment cycles rather than frontier exploration. Watch staged compression upgrade announcements at Tengiz and Kashagan as inflection indicators for wellhead replacement demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chromium Steel Supply | KazMunayGas controls fabrication costs for Tengiz expansion through captive Atyrau province foundries. |
| Integrated Project Management Contracting | Bundled drilling-completion-intervention scope transfers reservoir performance risk from national oil companies. |
| Digital Well Monitoring Convergence | Fiber-optic sensing integration compresses intervention response cycles across Tengiz cluster artificial lift systems. |
| Horizontal Well Completion Expansion | Extended-reach laterals displace vertical architectures in Karachaganak field redevelopment, concentrating directional specialist demand. |
| Regulatory Divergence Arbitrage | Cross-border project experience enables operators to sequence field development across Kazakh and Turkmen licensing regimes. |
Study Parameters
Bottom-up well completion and production technology modeling reconciled against top-down drilling service expenditure tracking forms the analytical core of this study. Primary interviews with drilling contractors, wellhead fabrication procurement leads, national oil company project managers, and Ministry of Energy regulatory officials combined with secondary validation from customs trade data, national petroleum regulator filings, EIA energy statistics, and integrated operator capex disclosures. Triangulation across stakeholder perspectives and documentary sources ensures coverage of both procurement decision-making and supply-side capacity constraints.
Historical trendline analysis of wellhead replacement cycles, EOR deployment rates, and horizontal completion penetration established baseline growth trajectories across the projection horizon. The analytical framework models segmentation across exploration type, production technology, well completion architecture, and service category, with additional dimensioning by sour service certification tier. CAGRs derive from regression analysis of capital intensity patterns and regulatory compliance cost trajectories. Forecast inputs include hydrogen sulfide-resistant metallurgy adoption curves and domestic content threshold enforcement intensity.
Regulatory enforcement variance, chromium steel alloy supply disruptions, and petrochemical feedstock demand fluctuations are the dominant revision risks to forecast assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Offshore Oil and Gas
Deep Water Drilling Market
Offshore Oil and Gas
Denmark Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
Oman Oil and Gas Market
Offshore Oil and Gas
South Sudan Oil and Gas Market
Offshore Oil and Gas
Asia-Pacific Offshore Energy Market
Offshore Oil and Gas
Indonesia Oil and Gas Downstream Market
Offshore Oil and Gas
Gulf of Mexico Oil and Gas Market
Offshore Oil and Gas
Ecuador Oil and Gas Downstream Market
Offshore Oil and Gas
Offshore Decommissioning Services Market
Offshore Oil and Gas
Europe Floating Offshore Wind Power Market
Offshore Oil and Gas
United Arab Emirates Oil and Gas Upstream Market
Offshore Oil and Gas
Single Point Anchor Reservoir (SPAR) Market
Offshore Oil and Gas
Brazil Offshore Oil & Gas Upstream Market
Offshore Oil and Gas
Norway Offshore Oil and Gas Decommissioning Market
Offshore Oil and Gas
South Sudan Oil and Gas Downstream Market
Offshore Oil and Gas
Deepwater and Ultra-Deepwater Drilling Market