
 Global Evaporative Cooling Market | 2026-2036
Global Evaporative Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Global Evaporative Cooling Market Foresight
Consolidation among hyperscale data center operators is realigning procurement volumes toward high-efficiency indirect systems. Munters Group AB leverages its engineered air treatment portfolio to sustain premium positioning in server farm deployments. SPX Cooling Technologies anchors North American utility-scale projects through its Marley cooling tower line. Baltimore Aircoil Company differentiates on polymer construction expertise that extends equipment life in corrosive industrial environments.
Evaporative cooling harnesses water evaporation to extract sensible heat from air streams, typically achieving supply temperatures within 70-90% of the ambient wet-bulb depression depending on media saturation efficiency and air velocity. Direct evaporative coolers dominate residential and light commercial segments where first cost sensitivity outweighs precision control requirements. Indirect and two-stage configurations command higher margins in data center and food processing applications where moisture addition must be eliminated. Hybrid coolers are gaining share in warehouses and logistics centers that need seasonal flexibility between evaporative and mechanical cooling modes.
The EPA's AIM Act refrigerant phasedown and the EU F-Gas Regulation are restricting conventional vapor compression options in commercial buildings, expanding addressable market for water-based alternatives. India's BEE mandatory labeling program and updated Energy Conservation Building Code are creating compliance-driven replacement cycles across manufacturing units and agricultural facilities. Stakeholders must monitor evolving wet-bulb design conditions as climate stress tests reshape equipment sizing standards and regional suitability maps.
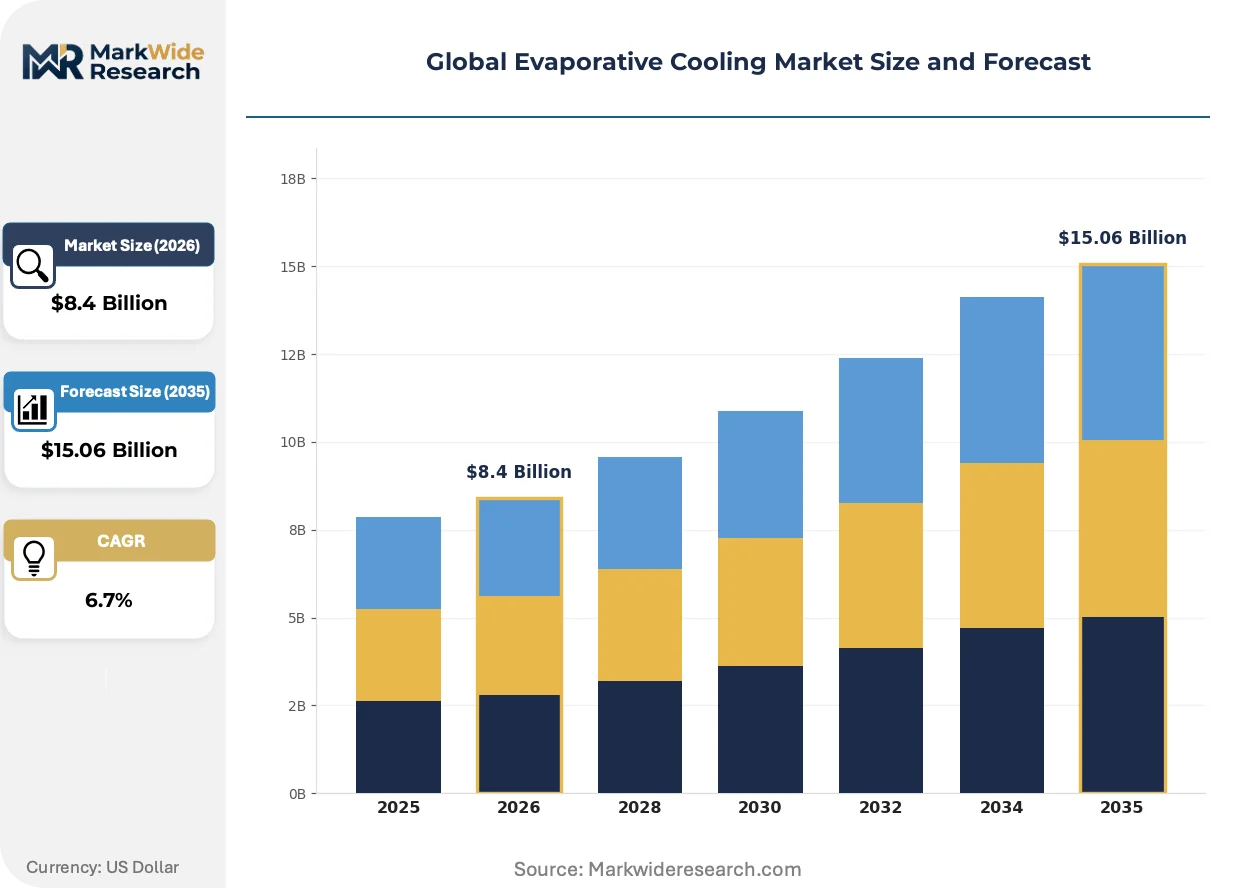
Market Dynamics
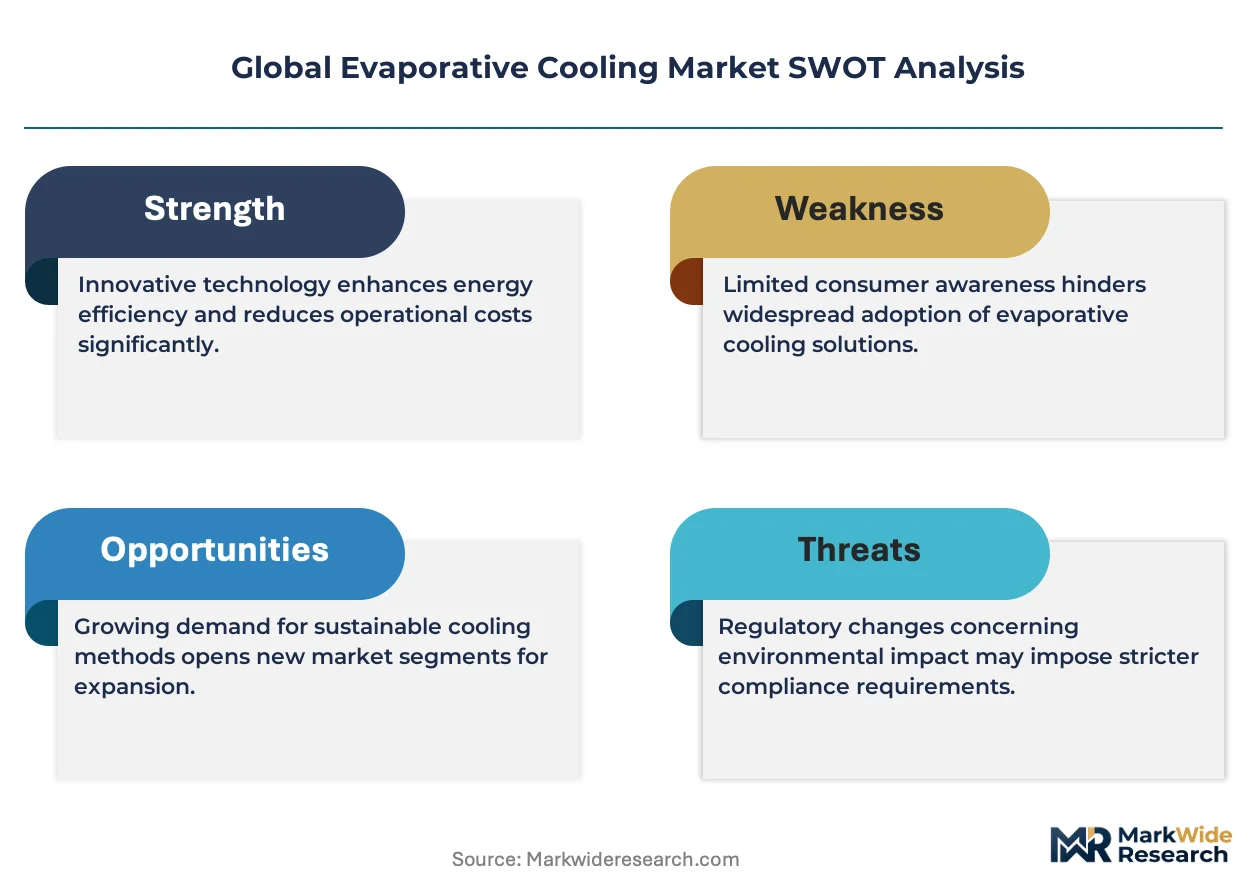
The EPA's AIM Act refrigerant phasedown is redirecting commercial HVAC capital toward water-based cooling architectures, compressing payback periods for indirect evaporative systems against conventional vapor compression across North American data centers and logistics facilities.
Growth Catalysts
- AI Infrastructure Thermal Loads:Hyperscale data center operators in the United States and India are scaling procurement of two-stage evaporative systems to manage heat rejection from GPU clusters exceeding 100kW per rack.
- F-Gas Regulation:The EU F-Gas Regulation's quota reductions on hydrofluorocarbon refrigerants are eliminating conventional chiller options for commercial buildings across Germany and France, expanding addressable market for adiabatic cooling.
- Polymer Media Advancement:Cellulose and engineered polymer wetted surfaces achieving 90% saturation efficiency are extending equipment life in corrosive industrial environments without metallic degradation.
Market Restraints
- Water Scarcity Risk:Evaporative cooling's dependency on continuous water supply creates operational vulnerability in drought-prone regions of Spain and Australia where municipal restrictions intensify during peak cooling seasons.
- Seasonal Performance Limitation:Direct evaporative systems lose effectiveness when ambient wet-bulb temperatures exceed design thresholds, forcing redundant mechanical cooling capacity in humid subtropical climates.
- Mineral Deposition Scaling:Hard water chemistry in the southwestern United States accelerates maintenance cycles and media replacement frequency, elevating total cost of ownership against projected savings.
Strategic Opportunities
- Underpenetrated Southeast Asia:Indonesia and Vietnam's manufacturing expansion lacks mature HVAC infrastructure, creating first-mover advantage for packaged evaporative units in textile and electronics assembly plants.
- Hybrid System Convergence:Integration of evaporative pre-cooling with vapor compression mechanical cooling enables seasonal mode switching, capturing warehouse operators in Japan seeking flexible capital deployment.
- BEE Building Code Enforcement:India's Energy Conservation Building Code mandates for commercial structures are triggering compliance-driven replacement cycles across existing manufacturing units and cold chain logistics centers.
Industry Challenges
- Thermal Engineering Talent Scarcity:Wet-bulb design optimization and psychrometric system sizing require specialized HVAC engineering expertise concentrated in aging workforces across North America and Europe.
- Legacy Control Integration:Building management system interoperability with evaporative cooling controls demands custom protocol bridging, complicating retrofit deployments in existing commercial facilities.
- Climate Data Uncertainty:Shifting wet-bulb design conditions from climate stress tests are forcing equipment oversizing and warranty exposure as historical weather patterns lose predictive validity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Evaporative Cooling Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Direct Evaporative Cooler, Indirect Evaporative Cooler, Two-Stage Evaporative Cooler, Hybrid Cooler Application: Industrial Plants, Commercial Buildings, Warehouses, Data Centers, Agricultural Facilities End User: Manufacturing Units, Logistics Centers, Food Processing Facilities, Server Farms Installation Type: Roof-Mounted, Portable, Wall-Mounted, Ceiling-Mounted |
| Companies Covered | Baltimore Aircoil Company, Inc., SPX Cooling Technologies, Munters Group AB, Condair Group AG, EVAPCO Inc., Delta Cooling Towers Inc., Colt Group Limited, Bonaire, Hessaire Products Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Evaporative Cooling Market Shifts & Advancements
Water treatment chemistry and controls automation are compressing maintenance intervals while expanding evaporative cooling's addressable geography into marginal water-quality regions previously excluded from deployment.
Membrane-based indirect evaporative cooling is consolidating competitive positioning in precision environments. This technology separates wet and dry air streams through vapor-permeable barriers, eliminating moisture addition entirely. Semiconductor cleanroom operators in South Korea and Taiwan are adopting these systems at accelerated pace. The technology is consolidating market share against traditional desiccant dehumidification by halving energy intensity in latent load management.
REACH chemical restrictions and the EU F-Gas Regulation are converging to eliminate conventional refrigerant options across commercial building retrofits. Industrial facility operators in the Netherlands and Belgium face compressed compliance timelines for phasing out high-GWP working fluids. Data center developers in Ireland are responding by specifying adiabatic cooling towers as baseline infrastructure, eliminating refrigerant risk entirely from thermal design.
Equipment-as-a-service contracting is displacing capital purchase in commercial real estate portfolios. Facility management firms in the United Kingdom are unbundling cooling infrastructure from property ownership, transferring operational risk to OEM service arms. This shift concentrates procurement authority with national service networks rather than distributed building operators, favoring suppliers with captive maintenance capabilities and remote monitoring infrastructure.
Global Evaporative Cooling Market Segmentation
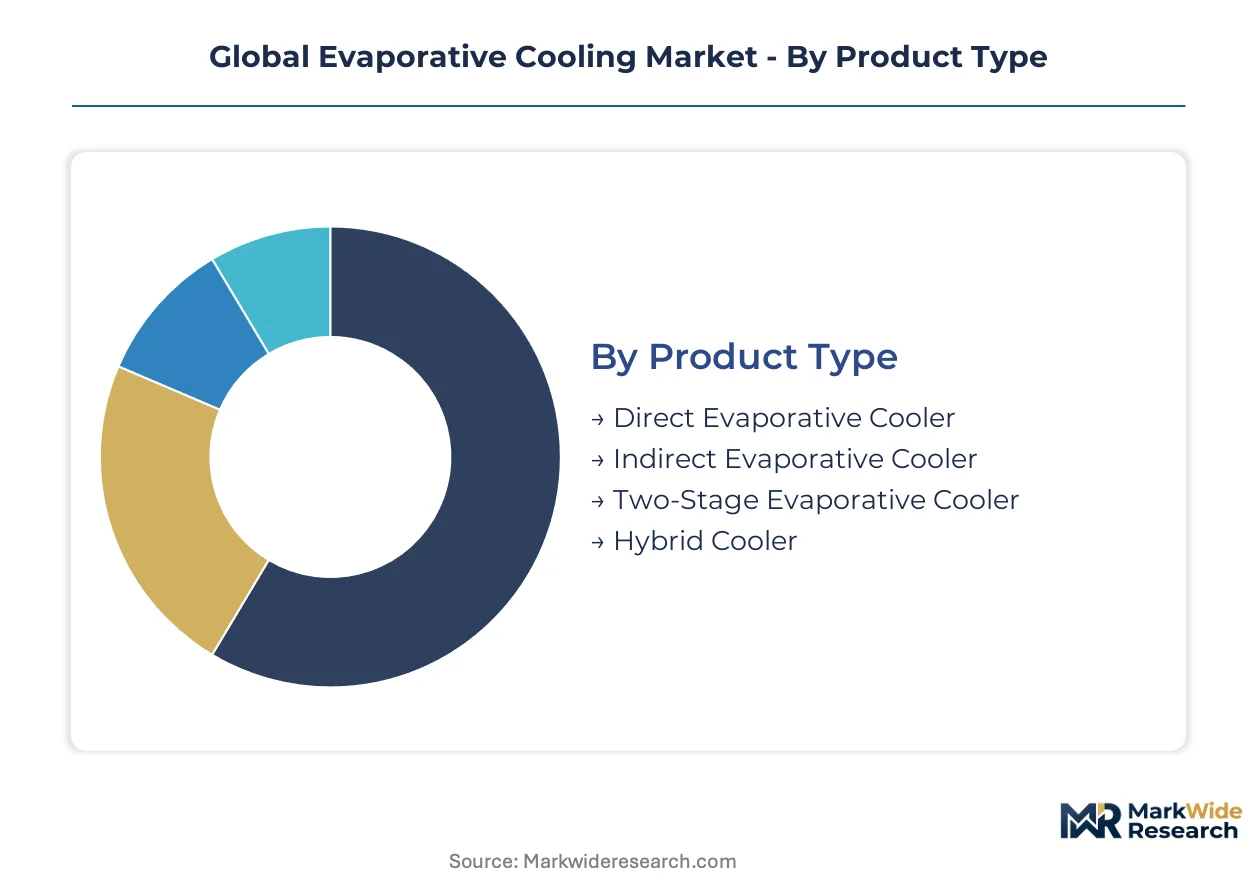
Evaporative cooling segments diverge sharply by precision requirements and first-cost sensitivity. Direct systems dominate residential and light commercial volumes, while indirect and two-stage configurations capture premium margins in controlled environments where moisture addition is prohibited.
Product Type:
Volume concentrates in direct evaporative coolers where low capital cost outweighs precision control needs. Premium positioning belongs to indirect and two-stage systems that eliminate moisture addition entirely.
- Direct Evaporative Cooler:Water-saturated cellulose or rigid media directly contacts supply air, achieving 70-90% wet-bulb depression efficiency. Demand clusters in residential retrofits across Phoenix, Arizona and Delhi, India where dry climates maximize performance and electricity tariffs compress payback periods against vapor compression.
- Indirect Evaporative Cooler:Heat exchangers separate wet and dry air streams, delivering cooled air without humidity addition. Server farm operators in Dublin, Ireland and Singapore specify these systems to maintain ASHRAE thermal envelopes while eliminating refrigerant compliance risk under EU F-Gas Regulation.
- Two-Stage Evaporative Cooler:Combines indirect precooling with direct saturation, achieving sub-wet-bulb supply temperatures. Hyperscale data centers in Ashburn, Virginia deploy these for GPU clusters exceeding 100kW per rack.
- Hybrid Cooler:Integrates evaporative pre-cooling with mechanical compression for seasonal mode switching. Warehouse operators in Japan's Kanto region favor these for flexible capital deployment across variable cooling loads.
Mature deployment sits with Direct Evaporative Cooler. Newer deployment is concentrated in Two-Stage Evaporative Cooler.
Application:
Industrial plants anchor volume through standardized packaged units. Data centers command premium pricing through custom-engineered precision systems.
- Industrial Plants:Heavy manufacturing in Gujarat, India and Texas, United States deploys roof-mounted direct coolers for process ventilation. BEE Energy Conservation Building Code compliance deadlines are accelerating replacement cycles across existing steel and textile facilities.
- Commercial Buildings:Office and retail structures in Madrid, Spain and Melbourne, Australia face municipal water restrictions that constrain evaporative deployment during drought cycles.
- Warehouses:Logistics centers in Rotterdam, Netherlands specify hybrid coolers for seasonal flexibility between evaporative and mechanical modes.
- Data Centers:Hyperscale facilities in Frankfurt, Germany and Mumbai, India are scaling procurement of indirect systems to manage AI infrastructure thermal loads without refrigerant risk.
- Agricultural Facilities:Poultry and dairy operations in California's Central Valley use direct evaporative cooling for livestock barn ventilation.
Deployment density peaks in Data Centers. Fastest expansion is occurring in Warehouses.
End User:
Manufacturing units drive standardized equipment volumes. Server farms require bespoke engineering with extended performance guarantees.
- Manufacturing Units:Automotive and electronics assembly plants in Vietnam and Indonesia specify packaged roof-mounted units for production floor cooling.
- Logistics Centers:Cold chain facilities in India's National Capital Region face BEE mandatory labeling compliance deadlines triggering equipment replacement.
- Food Processing Facilities:Hygiene-critical operations in Belgium and the Netherlands adopt membrane-based indirect systems to eliminate airborne contamination risk.
- Server Farms:Cloud providers in Ireland and Singapore specify adiabatic cooling towers as baseline infrastructure to eliminate refrigerant exposure entirely.
Established penetration sits with Manufacturing Units. Emerging concentration is visible in Server Farms.
Installation Type:
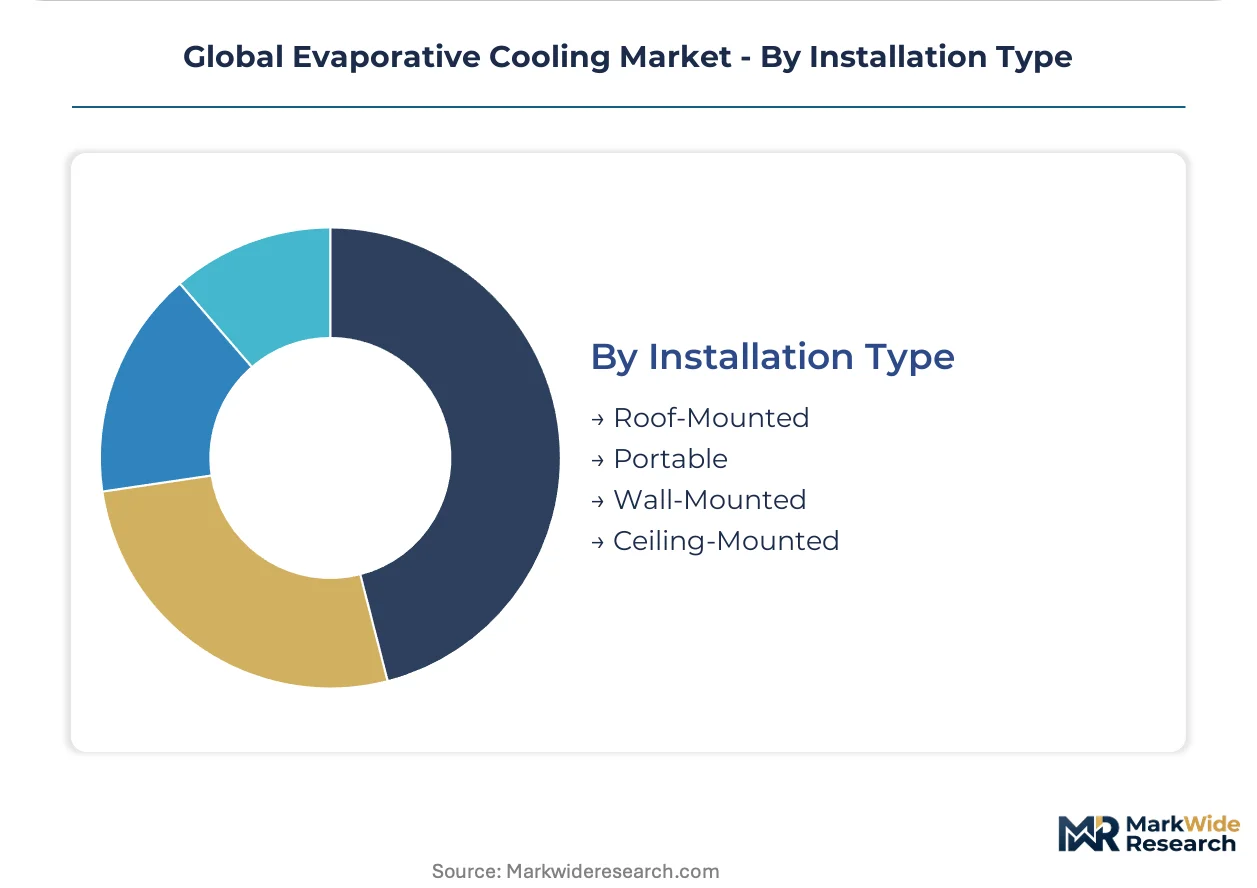
Roof-mounted systems dominate permanent industrial deployment. Portable units serve temporary and supplemental cooling needs.
- Roof-Mounted:Permanent installation on manufacturing and warehouse structures across the United States and India. Polymer construction extends equipment life in corrosive industrial atmospheres.
- Portable:Supplemental and emergency cooling for construction sites and event venues in Australia and Spain where water scarcity limits permanent evaporative infrastructure.
- Wall-Mounted:Space-constrained commercial retrofits in Japan and South Korea where roof structural loading is restricted.
- Ceiling-Mounted:Cleanroom and precision manufacturing environments in Taiwan and South Korea where floor and wall space is fully allocated to production equipment.
Volume concentration rests with Roof-Mounted. Fastest adoption is occurring in Portable configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale data center operators in the United States and India are concentrating procurement volumes for two-stage evaporative systems to manage thermal loads from AI infrastructure exceeding 100kW per rack.
United States
Data center clusters in Ashburn, Virginia and Phoenix, Arizona are scaling deployment of indirect evaporative systems to eliminate refrigerant compliance risk under the EPA's AIM Act. The phasedown of hydrofluorocarbon refrigerants is redirecting commercial HVAC capital toward water-based cooling architectures across logistics facilities in Texas. Manufacturing units in California's Central Valley face hard water chemistry challenges that accelerate maintenance cycles for direct evaporative coolers in agricultural ventilation applications.
Germany
Cloud providers in Frankfurt are specifying adiabatic cooling towers as baseline infrastructure to manage thermal loads without refrigerant exposure under the EU F-Gas Regulation. Industrial facility operators in the Ruhr region face compressed compliance timelines for phasing out high-GWP working fluids. Semiconductor cleanroom operators in Dresden are adopting membrane-based indirect systems to eliminate airborne contamination risk while halving energy intensity.
India
Steel and textile manufacturing in Gujarat and Maharashtra are accelerating equipment replacement cycles to meet BEE Energy Conservation Building Code compliance deadlines. Cold chain logistics centers in Delhi-NCR face mandatory labeling requirements that trigger procurement of packaged evaporative units. Server farm developers in Mumbai are scaling indirect system deployment to manage AI infrastructure thermal loads without mechanical refrigeration.
Singapore
Hyperscale facilities are specifying indirect evaporative coolers to maintain ASHRAE thermal envelopes while eliminating refrigerant compliance risk under tropical wet-bulb conditions. The city-state's data center moratorium has redirected investment toward cooling efficiency retrofits in existing facilities. Precision environment operators are adopting membrane-based systems to manage latent loads in semiconductor packaging operations.
Australia
Municipal water restrictions in Melbourne and Sydney constrain evaporative deployment during drought cycles, forcing hybrid system adoption in warehouse applications. Direct evaporative coolers dominate residential retrofits across Perth and Adelaide where dry climates maximize performance. Mining operations in Western Australia deploy portable units for supplemental cooling where permanent infrastructure faces water scarcity vulnerability.
Global Evaporative Cooling Market Competitive Landscape
North American producers anchor one tier; European specialists hold premium positioning in precision environments. The vendor base concentrates around engineered air treatment portfolios and polymer construction expertise. Three strategic archetypes dominate: full-system integrators with captive maintenance networks, component specialists focused on saturation media and heat exchangers, and regional fabricators serving standardized industrial applications. Competitive moves center on equipment-as-a-service contracting and remote monitoring infrastructure deployment.
Within the full-system integrator tier, Munters Group AB and Baltimore Aircoil Company, Inc. exemplify contrasting geographic anchoring and construction specialization. SPX Cooling Technologies represents the North American utility-scale project archetype through its established cooling tower lineage. These three entities occupy positions that span engineered air treatment, polymer construction expertise, and utility-scale infrastructure respectively.
| Leading Market Players |
|---|
| Baltimore Aircoil Company, Inc. |
| SPX Cooling Technologies |
| Munters Group AB |
| Condair Group AG |
| EVAPCO Inc. |
| Delta Cooling Towers Inc. |
| Colt Group Limited |
| Bonaire |
| Hessaire Products Inc. |
| Others |
Supply & Pricing Matrix
Hyperscale data center procurement consolidation toward indirect and two-stage systems is compressing supplier margins while elevating specification requirements for saturation media and heat exchanger performance. Equipment manufacturers must absorb cellulose and engineered polymer cost volatility or surrender share to integrated rivals with captive component production.
Pricing Analysis
Volume concentrates in direct evaporative coolers where per-unit transactional pricing dominates residential and light commercial procurement. Premium-mid-economy pricing differentiation separates indirect systems with ASHRAE-compliant guarantees from standardized packaged units lacking remote monitoring. Cost compression in direct systems is intensifying because of hard water chemistry maintenance burdens in the southwestern United States. Manufacturing units exhibit highest price sensitivity; server farms prioritize performance guarantees over first cost.
Supply Chain Analysis
Welding and polymer fabrication expertise shortages in Vietnam and Indonesia constrain capacity expansion for corrosion-resistant equipment serving Southeast Asian manufacturing expansion. Component sourcing draws from Chinese cellulose media producers, German heat exchanger specialists, and Indian galvanized steel fabricators. Single-source vulnerability sits with engineered polymer formulations subject to REACH chemical restrictions. Distribution runs through national HVAC service networks consolidating procurement authority under equipment-as-a-service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as OEMs pursue captive saturation media production to secure margin control against raw material volatility.
For Market Incumbents: Cement position by acquiring regional polymer media fabricators in India and Vietnam before competitors lock up supply. Invest in remote monitoring infrastructure to capture equipment-as-a-service contracts displacing capital purchases. Defend against membrane-based indirect system specialists encroaching on semiconductor cleanroom specifications by accelerating R&D in vapor-permeable barrier technology. For New Entrants and Emerging Players: E-commerce platform partnerships offer low-friction entry into residential direct cooler replacement cycles across Phoenix and Delhi. Target Indonesia and Vietnam textile plants lacking mature HVAC infrastructure with packaged roof-mounted units. Position on water treatment integration to differentiate in hard water geographies where maintenance cycles deter incumbent deployment. For Investors and Strategic Acquirers: The window for entry favors mid-cap equipment specialists with captive polymer construction capabilities and established national service networks. Long-term viability hinges on climate adaptation engineering expertise as wet-bulb design conditions shift. Watch BEE enforcement intensity in India's National Capital Region as inflection indicator for compliance-driven replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Media | Captive cellulose and engineered polymer production secures margin control against REACH chemical restriction volatility. |
| Equipment-as-a-Service Launch | Remote monitoring infrastructure transfers operational risk from facility managers to OEM service arms in United Kingdom portfolios. |
| Membrane-Based Indirect System R&D | Vapor-permeable barrier technology halves energy intensity against desiccant dehumidification in South Korean semiconductor cleanrooms. |
| Southeast Asia Manufacturing Footprint | Indonesia and Vietnam plant locations capture first-mover advantage in textile and electronics assembly HVAC deployment. |
| Water Treatment Chemistry Partnership | Controls automation integration expands addressable geography into marginal water-quality regions of Spain and Australia. |
Research Methodology
Document review covered EPA AIM Act implementation guidance, EU F-Gas Regulation quota schedules, and BEE Energy Conservation Building Code amendments, complemented by interviews with data center thermal engineering directors, HVAC procurement managers at hyperscale cloud providers, polymer media manufacturing plant managers, and national service network operations heads. Secondary validation drew from customs trade data, SEC equipment manufacturer filings, and hyperscaler capex disclosures. Bottom-up equipment unit estimates triangulated against top-down cooling infrastructure investment projections.
Market sizing outputs segmented across product type, application, end user, and installation type dimensions over the projection horizon. CAGRs derived from regression analysis against AI infrastructure deployment trajectories, refrigerant phasedown compliance timelines, and building code enforcement intensity. Modeled inputs incorporated wet-bulb design condition shifts from climate stress tests and equipment-as-a-service contract penetration rates.
The model holds under steady regulatory enforcement and stable polymer feedstock availability; deviation in BEE inspection intensity or REACH chemical restriction scope would shift replacement cycle timing and geographic deployment feasibility. Forecasts reflect these base assumptions with acknowledged sensitivity to drought-induced water restriction severity in Australia and Spain. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Air Cooling Corona Discharge Ozone Generator Market
Cooling Systems
Global Transcritical Co2 Systems Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Global Condensing Unit Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Seawater Cooling System Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Heat Pipe Market
Cooling Systems
Global Evaporative Cooler Market
Cooling Systems
Global Chiller Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Process Chillers Market
Cooling Systems
Cryogenic Systems Market