
 Europe Intelligent Pigging Market | 2026-2036
Europe Intelligent Pigging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Intelligent Pigging Market Insights
The EU Green Deal is decoupling pipeline maintenance economics from legacy inspection schedules across Europe. ROSEN Group leverages its electromagnetic sensor portfolio to anchor German and North Sea contract flows. Siemens Energy AG competes through integrated data platforms that link inspection output directly to predictive maintenance systems. Baker Hughes sustains offshore leadership via subsea-capable toolstrings purpose-built for Norwegian and UK deepwater trunk lines.
Europe intelligent pigging deploys self-propelled robotic devices through operational pipelines to detect metal loss, cracks, and geometric anomalies using magnetic flux leakage, ultrasonic, or electromagnetic sensing modalities, typically operating at pressures up to 200 bar and temperatures ranging from sub-zero cryogenic service to elevated thermal conditions. Magnetic flux leakage technology dominates onshore crude and product lines where wall-thickness verification drives regulatory compliance cycles, while ultrasonic inspection captures premium pricing in gas utility networks requiring precise crack sizing for fitness-for-service assessments. End user demand fragments across pipeline operators managing cross-border transmission systems, oil refineries with complex process piping, and gas utilities confronting methane emission accountability.
EMA, ECHA, and national regulators such as Germany's KBA enforce pipeline safety directives that mandate periodic integrity verification and defect response timelines, converting regulatory deadlines into contracted inspection revenue. The EU AI Act introduces algorithmic transparency requirements for automated defect classification systems, reshaping how inspection vendors validate machine-learning outputs for regulatory acceptance. Stakeholders must weigh investment in sensor fusion architectures against the risk of stranded technology if interoperability standards crystallize around competing data formats.
Market Dynamics
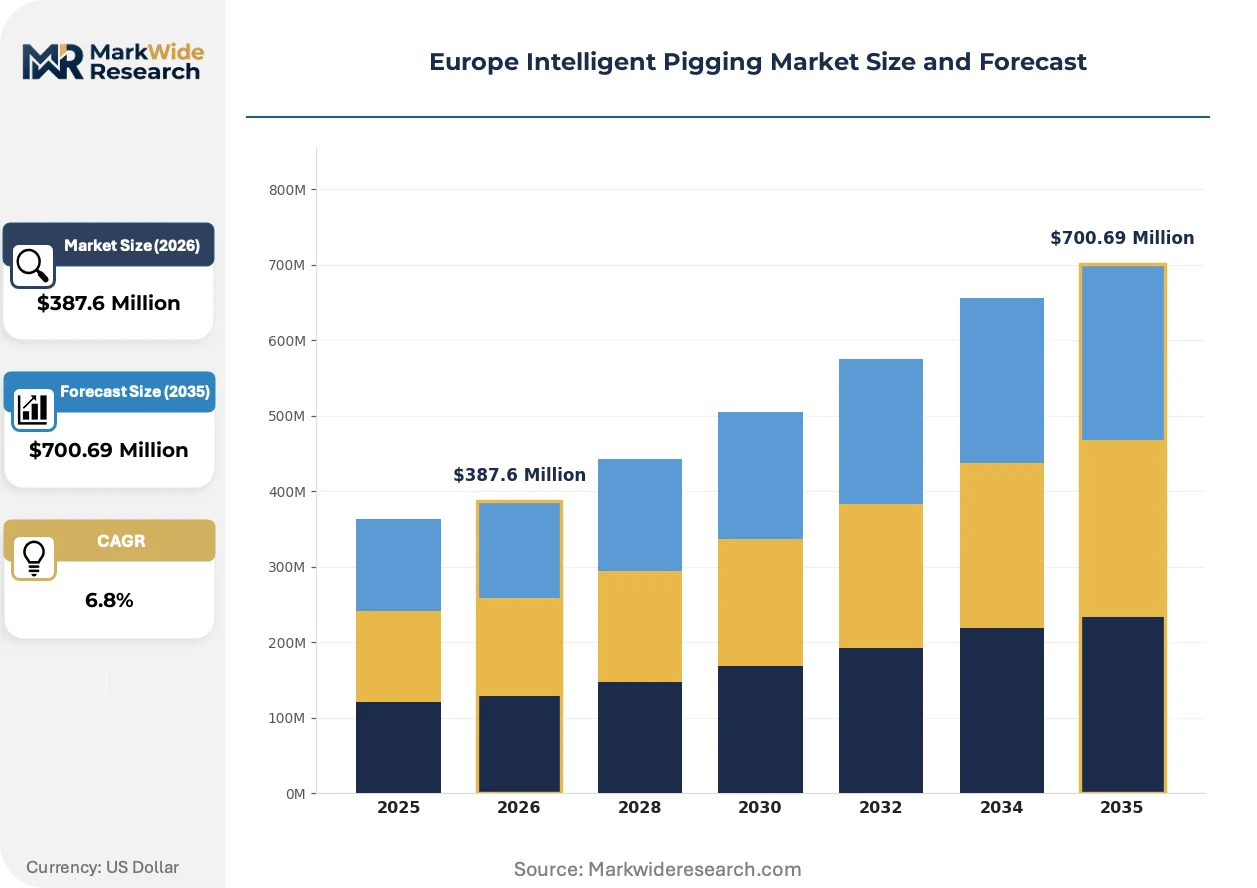
The EU Green Deal and F-Gas Regulation are decoupling pipeline maintenance economics from legacy inspection schedules. Operators now face binding methane emission accountability that converts regulatory deadlines into contracted inspection revenue, while aging North Sea infrastructure demands subsea-capable toolstrings.
Growth Catalysts
- EU Green Deal methane mandates:The framework imposes strict emission caps on gas utilities, forcing continuous integrity verification programs that sustain inspection demand across German and Dutch transmission networks.
- Electromagnetic sensor fusion:Multi-modal detection platforms combining magnetic flux leakage with ultrasonic arrays enable single-pass comprehensive assessment, reducing operational downtime for cross-border pipeline operators.
- North Sea decommissioning wave:Aging offshore trunk lines in Norwegian and UK waters require fitness-for-service reassessments before life-extension decisions, generating specialized deepwater pigging contracts.
Market Restraints
- Specialized alloy input costs:Toolstring bodies require high-grade stainless steel and rare-earth magnetic materials, exposing manufacturers to commodity volatility and extended procurement cycles.
- German supplier concentration:Critical electromagnetic sensor production clusters around Stuttgart and Munich, creating single-source vulnerability for inspection vendors serving Central European networks.
- Ultrasonic temperature limitations:Cryogenic gas service below minus 40 degrees Celsius degrades transducer coupling efficiency, forcing fallback to less precise magnetic methods on Arctic-capable pipelines.
Strategic Opportunities
- Polish and Baltic pipeline expansion:New interconnector projects linking LNG terminals to Central European grids lack established integrity baselines, creating first-mover inspection contracts for qualified vendors.
- EU AI Act algorithmic transparency:Automated defect classification systems face new validation requirements, opening compliance consulting and certified machine-learning training data services.
- Sensor-to-ERP data integration:Direct API connections between inspection platforms and enterprise asset management systems enable predictive maintenance subscriptions, shifting revenue from episodic projects to recurring contracts.
Industry Challenges
- Subsea robotics engineering scarcity:Deepwater toolstring design requires rare cross-training in pressure vessel engineering, autonomous navigation, and marine corrosion science, constraining vendor expansion.
- CE-MDR certification timelines:Electromagnetic inspection tools classified as measuring equipment face extended conformity assessment periods under updated machinery directives, delaying product launches.
- Legacy SCADA integration friction:Brownfield pipelines operate on proprietary data protocols from the 1990s, forcing expensive middleware development to connect modern pigging outputs to operator control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Intelligent Pigging Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Ultrasonic, Magnetic Flux Leakage, Electromagnetic, Acoustic End User: Pipeline Operators, Oil Refineries, Gas Utilities, Chemical Plants Installation: Onshore, Offshore, Network Expansion, Maintenance Operations Service Type: Inspection Services, Data Analysis, Pipe Integrity Assessment, Consultancy |
| Companies Covered | GE Oil & Gas, Enduro Pipeline Services, ROSEN Group, Siemens Energy AG, Aker Solutions ASA, Baker Hughes, NDT Global, Mistras, T.D. Williamson, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Intelligent Pigging Market Trends and Innovations
Pipeline inspection is shifting from scheduled maintenance to continuous condition monitoring. Three developments are compressing the cycle between data capture and operational decision.
Multi-physics sensor platforms are integrating magnetic flux leakage, ultrasonic, and electromagnetic acoustic transducer modalities into unified toolstrings. Norwegian and UK offshore operators are deploying these systems on unpiggable lines via tethered robotic crawlers. The technology is integrating previously separate inspection passes, collapsing weeks of sequential runs into single operational windows and reducing methane venting events.
The EU AI Act introduces algorithmic transparency requirements for automated defect classification systems used in safety-critical infrastructure. Vendors must now document training data provenance and model decision boundaries for regulatory acceptance. German transmission operators are responding by demanding explainable AI modules that flag classification confidence intervals alongside crack sizing outputs.
Asset owners are unbundling inspection data ownership from execution services. Rather than contracting full-scope pigging runs, major utilities now procure raw sensor data and process analytics through separate vendors. This procurement fragmentation is most visible in the Netherlands, where Gasunie and regional operators maintain internal integrity teams that specify data formats and validation protocols, commoditizing field execution while premiumizing data interpretation capabilities.
Europe Intelligent Pigging Market Segmentation
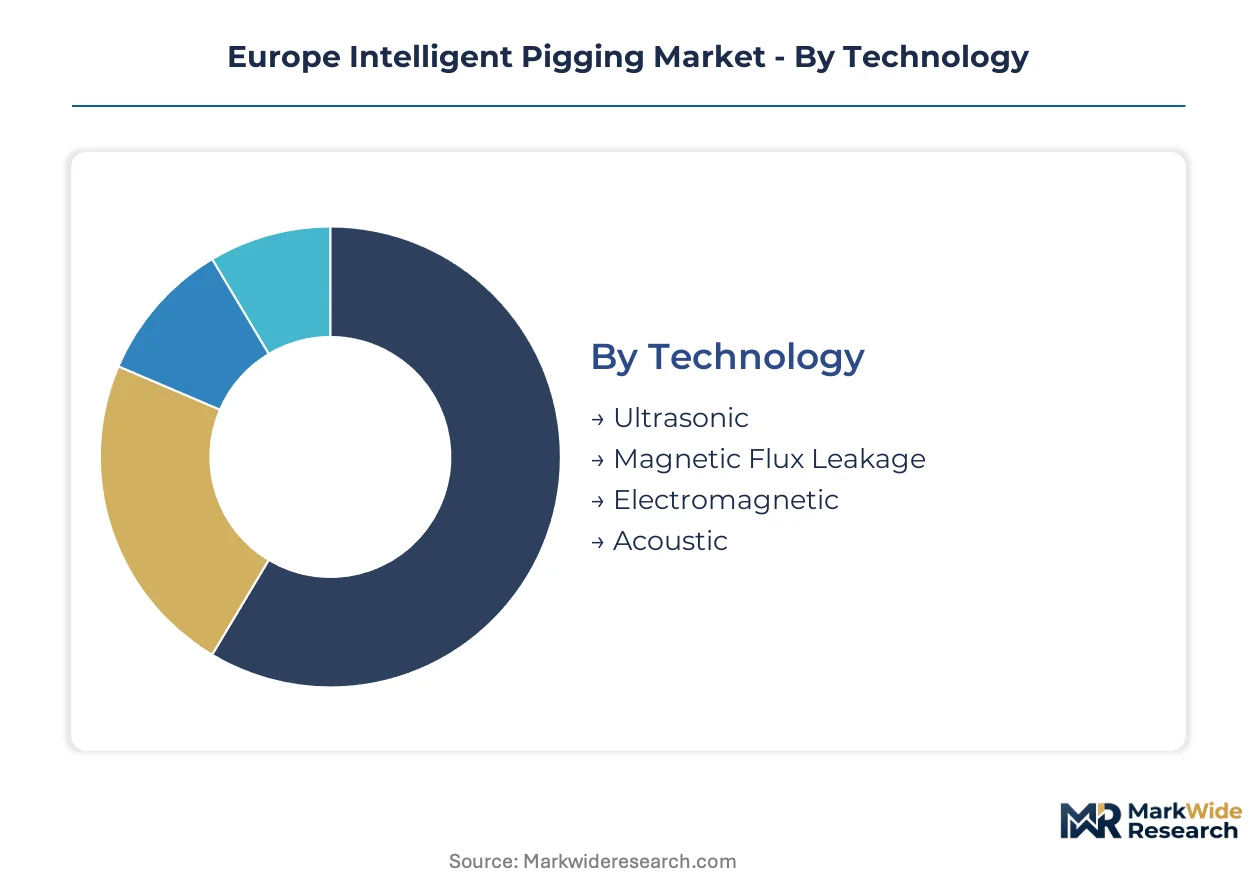
Intelligent pigging procurement patterns in Europe diverge sharply by capital commitment and regulatory exposure. Technology choices determine sensor platform investments, while end-user categories dictate contract structures and compliance urgency.
Technology:
Capital intensity peaks with multi-modal sensor fusion platforms requiring rare-earth magnet arrays and high-frequency ultrasonic transducers.
- Ultrasonic:Piezoelectric transducers emit high-frequency pulses to map wall thickness and crack geometry with sub-millimeter precision. German gas utilities under KBA oversight specify ultrasonic arrays for fitness-for-service assessments on high-pressure methane trunk lines.
- Magnetic Flux Leakage:Saturating magnetic fields detect metal loss anomalies through flux disturbance patterns. This modality dominates North Sea crude pipelines where corrosion monitoring drives regulatory compliance cycles for Norwegian and UK offshore operators.
- Electromagnetic:Eddy-current sensors identify stress-corrosion cracking without direct surface contact. Dutch transmission networks deploy electromagnetic tools for unpiggable pipeline sections where mechanical pigs cannot navigate.
- Acoustic:Passive listening arrays capture leak signatures and flow-induced vibration patterns. This emerging modality serves early-stage methane detection programs under EU Green Deal emission accountability frameworks.
Magnetic Flux Leakage absorbs the bulk of installed capacity; Acoustic is expanding most quickly.
End User:
Contract value scales with pipeline criticality and regulatory scrutiny intensity across operator categories.
- Pipeline Operators:Cross-border transmission system managers procure comprehensive integrity programs spanning multiple sensing modalities. German and Dutch operators face binding methane emission caps that convert inspection schedules into mandated recurring revenue.
- Gas Utilities:Distribution network owners prioritize crack-sizing accuracy for high-consequence area classification. Polish and Baltic utilities expanding LNG interconnector infrastructure represent first-mover contract opportunities lacking established inspection baselines.
- Oil Refineries:Complex process piping networks require geometric anomaly detection for turnaround planning. Refinery demand concentrates in corrosion-prone crude distillation units and catalytic reformer loops.
- Chemical Plants:Specialized alloy piping in ethylene crackers and ammonia synthesis loops demands material-specific inspection protocols. Chemical sector procurement remains episodic, tied to insurance-mandated integrity reassessments.
Pipeline Operators command the largest contract values; Gas Utilities are climbing the fastest on methane accountability mandates.
Installation:
Deployment complexity and tooling requirements fragment procurement economics across operating environments.
- Onshore:Standard bi-directional launcher and receiver configurations support routine inspection cycles on continental pipeline grids. German onshore networks generate continuous demand through operational license conditions requiring corrosion monitoring.
- Offshore:Subsea-capable toolstrings with pressure-rated housings and autonomous navigation systems access deepwater trunk lines. Norwegian and UK North Sea infrastructure approaching decommissioning decisions drives fitness-for-service reassessment contracts.
- Network Expansion:New-build pipelines require baseline integrity surveys before commissioning. Baltic LNG interconnectors and Polish corridor projects lack historical inspection data, creating specification opportunities for qualified vendors.
- Maintenance Operations:Unplanned inspection runs respond to anomaly detection from SCADA monitoring or third-party damage events. Emergency procurement commands premium pricing but unpredictable timing.
Onshore installations retain the deepest installed base; Network Expansion is gaining share fastest on infrastructure buildouts.
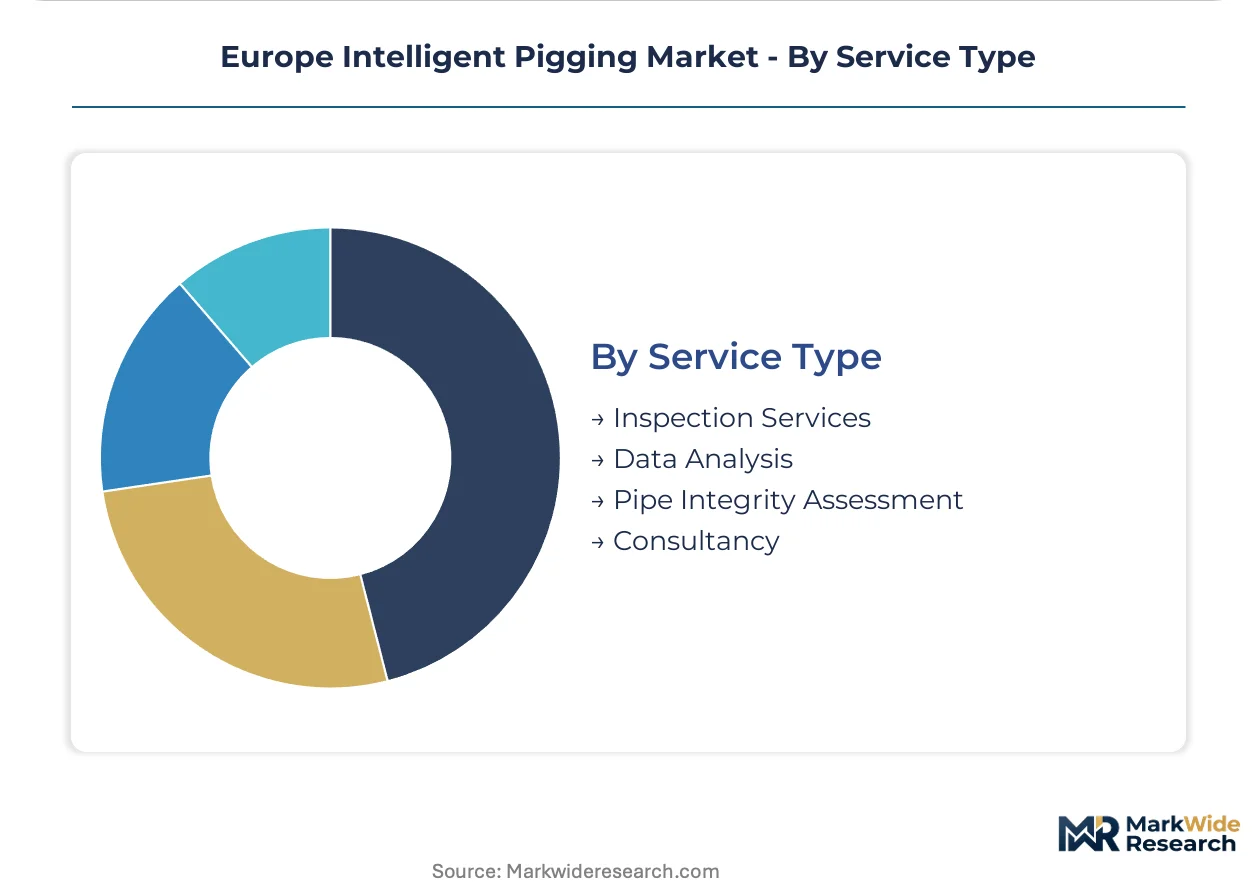
Service Type:
Revenue model evolution is unbundling field execution from data interpretation and advisory functions.
- Inspection Services:Physical pigging runs encompassing tool deployment, tracking, and recovery operations. Field execution is commoditizing as utilities internalize specification authority and data format requirements.
- Data Analysis:Sensor signal processing, defect classification, and severity ranking delivered through cloud platforms. EU AI Act algorithmic transparency requirements are reshaping validation protocols for automated crack-sizing outputs.
- Pipe Integrity Assessment:Fitness-for-service calculations linking inspection findings to remaining life predictions and repair prioritization. This premium service integrates material science expertise with regulatory response timelines.
- Consultancy:Strategic advisory on inspection program design, vendor qualification, and regulatory compliance roadmap development. Consultancy demand is climbing as operators navigate CE-MDR certification complexity for new sensor platforms.
Inspection Services still captures the greatest revenue volume; Data Analysis is expanding most rapidly on predictive maintenance adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
North Sea offshore tax incentives and German industrial zones concentrate intelligent pigging demand across European pipeline corridors. National transmission operators face divergent regulatory timelines and infrastructure maturity profiles.
Germany
The KBA enforces continuous corrosion monitoring for operational license maintenance on high-pressure methane networks. Stuttgart and Munich host critical electromagnetic sensor production clusters serving Central European inspection demand. The national transmission system requires fitness-for-service assessments under binding methane emission caps.
United Kingdom
North Sea decommissioning decisions drive fitness-for-service reassessments on aging offshore trunk lines. The Health and Safety Executive mandates periodic integrity verification with strict defect response timelines. Aberdeen anchors subsea robotics engineering capabilities for deepwater toolstring deployment.
Norway
Offshore operators deploy multi-modal sensor platforms on unpiggable lines via tethered robotic crawlers. Petroleum Safety Authority regulations convert regulatory deadlines into contracted inspection revenue for North Sea infrastructure. Stavanger concentrates subsea engineering expertise for autonomous navigation systems.
Netherlands
Gasunie and regional operators maintain internal integrity teams that specify data formats and validation protocols. The EU Green Deal methane accountability frameworks reshape procurement toward predictive maintenance subscriptions. Rotterdam and Amsterdam host data analytics platforms linking inspection output to enterprise asset management systems.
Poland
New LNG interconnector projects linking Baltic terminals to Central European grids lack established integrity baselines. The country's national energy regulator mandates baseline surveys before pipeline commissioning. Gdańsk and Warsaw corridor projects create first-mover inspection contracts for qualified vendors.
Europe Intelligent Pigging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology and service vectors. Market structure tilts toward consolidation where electromagnetic sensor fusion and subsea capabilities create capability moats. Three archetypes dominate: integrated energy technology conglomerates with inspection divisions, pure-play pipeline integrity specialists, and industrial automation vendors with pigging modules. Competitive positioning hinges on M&A for sensor technology access and strategic partnerships for subsea robotics engineering.
Among Germany-based specialists, ROSEN Group exemplifies the pure-play archetype with concentrated electromagnetic sensor expertise. Siemens Energy AG occupies a position bridging industrial automation and energy infrastructure. Baker Hughes represents the diversified conglomerate model with subsea-capable toolstring portfolios. These three anchors illustrate how geographic clustering around Stuttgart, Munich, and North Sea engineering hubs shapes competitive differentiation.
| Leading Market Players |
|---|
| GE Oil & Gas |
| Enduro Pipeline Services |
| ROSEN Group |
| Siemens Energy AG |
| Aker Solutions ASA |
| Baker Hughes |
| NDT Global |
| Mistras |
| T.D. Williamson |
| Others |
Pricing and Supply Chain Analysis
Cross-border transmission operators concentrated in Germany and the Netherlands anchor procurement volume and enforce project-based contracting with stringent data format specifications. This buyer concentration converts sensor platform differentiation into pricing power for vendors holding CE-MDR certification and electromagnetic fusion capabilities.
Pricing Analysis
Short lead-time premiums dominate contract negotiations as German gas utilities under KBA oversight demand emergency inspection runs within compressed windows to maintain operational licenses. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and after-sales service bundling. Pricing pressure stems from utilities internalizing data analytics capabilities and commoditizing field execution. Small Polish and Baltic utilities expanding LNG interconnectors exhibit highest price sensitivity due to unestablished integrity baselines and capital constraints.
Supply Chain Analysis
Single-source vulnerability sits with rare-earth magnetic material processing concentrated in China and specialized ultrasonic transducer fabrication anchored in Germany and Japan. Toolstring bodies draw from high-grade stainless steel mills in Sweden and Italy. Supply chain risk centers on extended CE-MDR conformity assessment timelines delaying product launches. Distribution runs through direct vendor-operator relationships for subsea-capable systems, with standard onshore tools moving via regional service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
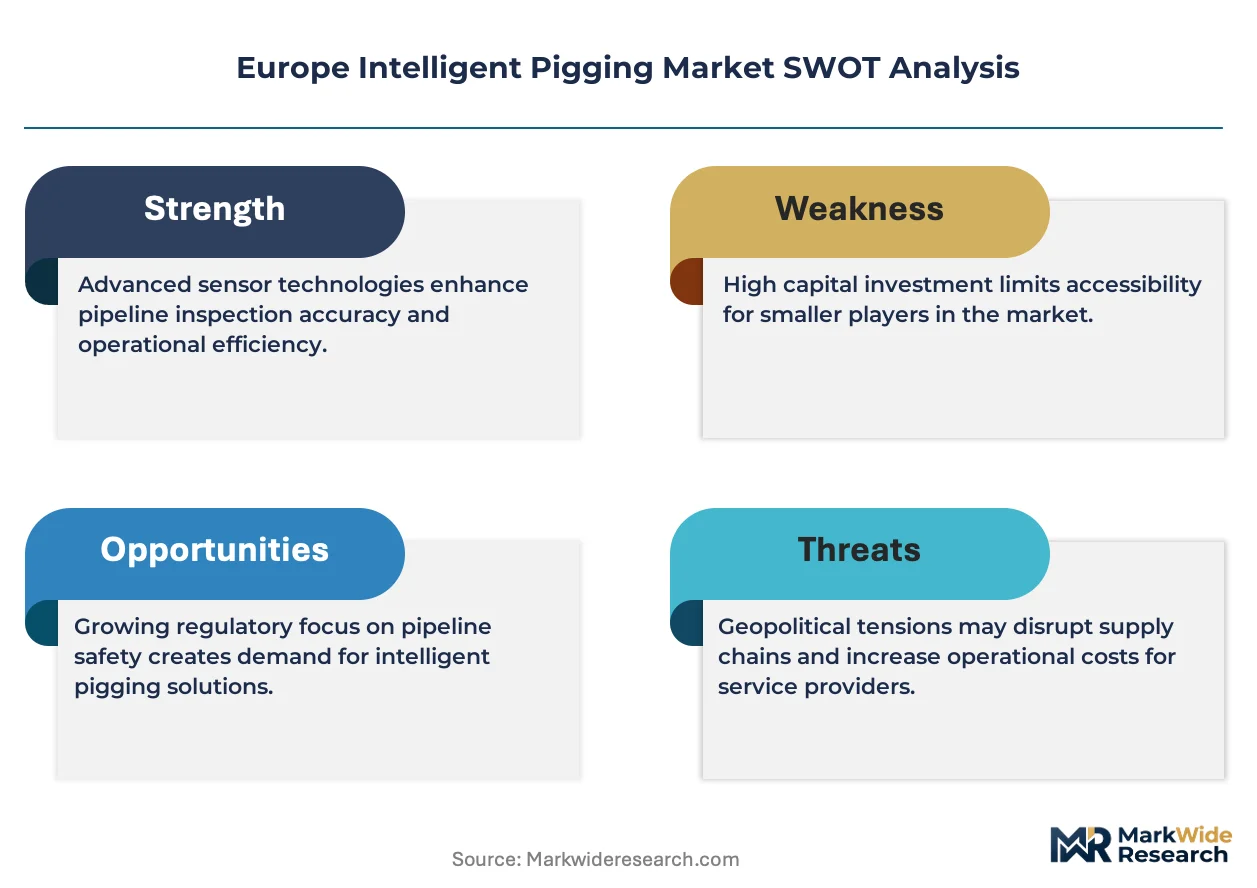
The Europe intelligent pigging market operates as a cost-of-compliance story where EU AI Act algorithmic transparency requirements and CE-MDR certification complexity erect barrier-to-entry moats favoring incumbents with validated machine-learning training data and established regulatory relationships.
For Market Incumbents: Lock in recurring revenue through predictive maintenance subscriptions linking sensor platforms directly to enterprise asset management systems. Deepen backward integration into electromagnetic sensor production to offset Stuttgart and Munich supplier concentration risk. Defend against data analytics commoditization by embedding explainable AI modules that satisfy German transmission operator demands for classification confidence intervals. For New Entrants and Emerging Players: Cloud-based data interpretation services offer the lowest-capital route to contract participation without field execution infrastructure. Polish LNG interconnector projects and Baltic pipeline corridors lack established integrity baselines and represent penetrable white-space. Target consultancy services around EU AI Act compliance validation as utilities seek external expertise for algorithmic transparency documentation. For Investors and Strategic Acquirers: The window for entry favors pure-play sensor technology specialists with electromagnetic fusion capabilities and validated subsea robotics engineering teams. Long-term viability hinges on recurring revenue model transition away from episodic project contracting. Watch for decommissioning timeline acceleration in Norwegian and UK North Sea waters as the signal for specialized deepwater toolstring demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Sensor Fusion Platform Development | Enables single-pass comprehensive assessment collapsing sequential inspection runs for German transmission operators. |
| Predictive Maintenance Subscription Launch | Converts episodic project revenue to recurring contracts through API integration with Gasunie asset management systems. |
| Subsea Robotics Engineering Acquisition | Addresses capability scarcity in deepwater toolstring design for Norwegian and UK North Sea decommissioning decisions. |
| EU AI Act Compliance Certification | Opens algorithmic transparency consulting and certified training data services for automated defect classification systems. |
| Polish-Baltic Corridor First-Mover Contracts | Captures baseline integrity survey specifications for LNG interconnector projects lacking historical inspection data. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with pipeline integrity managers, subsea robotics engineers, regulatory compliance officers, and gas utility procurement leads combined with secondary validation from EMA submissions, KBA inspection directives, EU Green Deal implementation documents, and national transmission operator annual reports. Bottom-up project pipeline assessment triangulated against top-down market sizing from sensor platform shipment data.
Data-stream reconciliation across technology deployment records, contract award announcements, and regulatory compliance timelines shaped the analytical framework. Segmentation dimensions modeled include sensing modality, installation environment, end-user category, and service type across the projection horizon. CAGRs derived from weighted average of vendor guidance, operator capital expenditure plans, and regulatory mandate enforcement schedules. Forecast inputs incorporated North Sea decommissioning timeline probabilities and EU methane emission cap implementation pace.
The model holds under steady regulatory enforcement and continued infrastructure aging assumptions; deviation in CE-MDR certification timeline acceleration or rare-earth material supply disruption would shift vendor capacity and pricing trajectories. Forecasts reflect documented assumptions about inspection frequency mandates and technology substitution rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Workover Rigs Market
Oil & Gas
LNG Bunkering Market
Oil & Gas
Saudi Arabia Liner Hanger System Market
Oil & Gas
Romania Oil and Gas Market
Oil & Gas
US Oil and Gas Analytics Market
Oil & Gas
Global Fracking Fluids and Chemicals Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Romania Oil and Gas Downstream Market
Oil & Gas
India Oil and Gas Midstream Market
Oil & Gas
North America Oil and Gas Electric Submersible Pump Market
Oil & Gas
Global Shale Gas Market
Oil & Gas
Riserless Light Well Intervention Market
Oil & Gas
Africa Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Blockchain in Oil and Gas Market
Oil & Gas
India Natural Gas Market
Oil & Gas
Oil and Gas Fittings Market