
 Low Temperature Radiators Market | 2026-2036
Low Temperature Radiators Market Size, Share, and Industry Trends Forecast 2026-2036
Low Temperature Radiators Market Analysis
China's manufacturing base for aluminum heat exchangers is reconfiguring export flows toward European HVAC supply chains. Mahle GmbH leverages its thermal management heritage to dominate OEM channels for electric vehicle cabin heating. Kelvion Holding anchors industrial process cooling applications with specialized low-temperature coil designs. Rheem Manufacturing Company competes in North American residential replacement cycles through distributor network control.
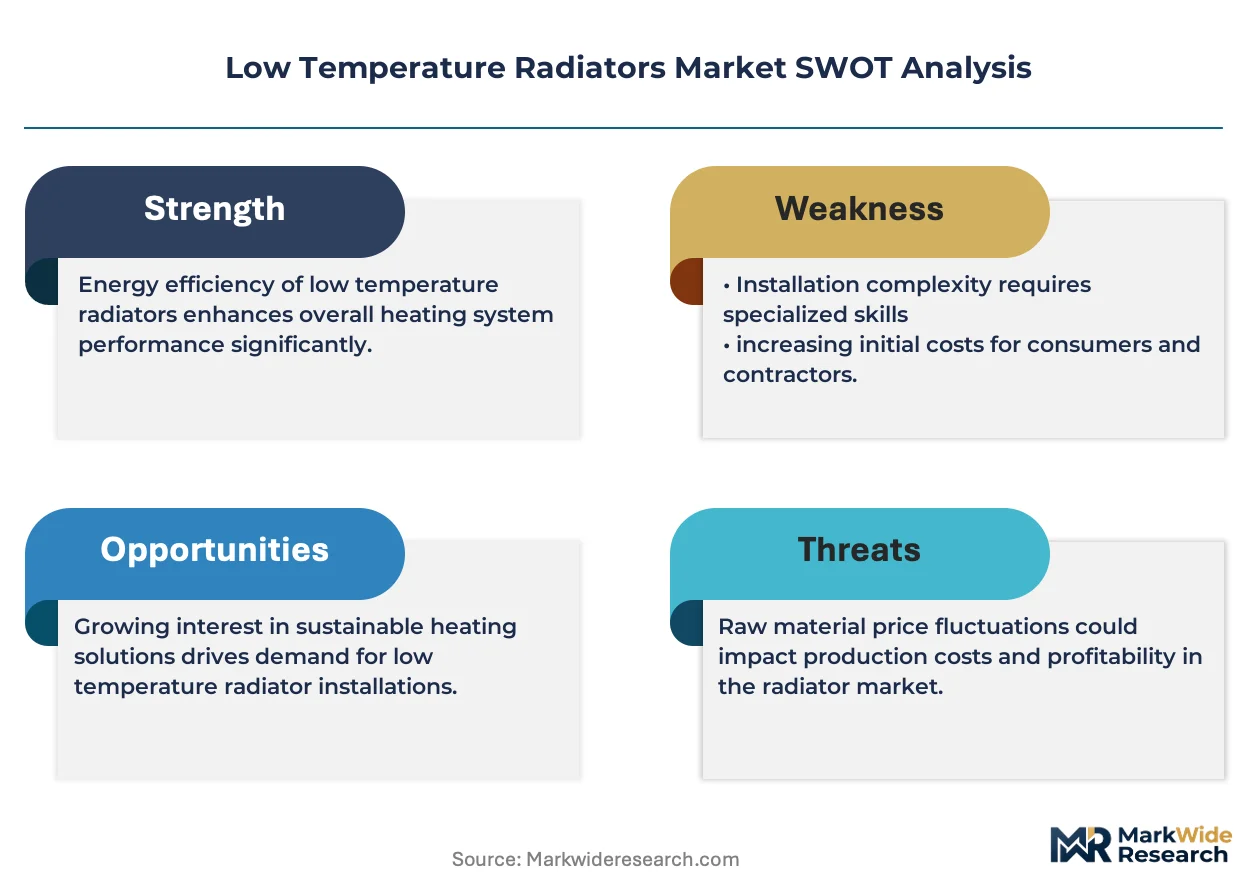
Low temperature radiators are heat emitters engineered to operate with supply water below 45°C, typically constructed from aluminum or steel with enlarged surface areas and optimized convection geometry to compensate for reduced thermal gradients. These systems enable efficient heat pump and condensing boiler integration by maximizing heat output at reduced operating temperatures. Hydronic systems lead the product mix in European renovation markets where existing pipework accommodates retrofits, while electric variants capture fastest growth in new-build residential segments with distributed energy architectures. Panel radiators sustain margin pools through premium powder-coat finishes and modular sizing for architectural specification channels.
The EU Ecodesign Directive mandates minimum efficiency thresholds that disqualify conventional high-temperature radiators from new installations across member states. Germany's Federal Ministry for Economic Affairs enforces Building Energy Act provisions requiring renewable-ready heating equipment in replacement scenarios. Stakeholders must monitor national heat pump subsidy trajectories and local installer capacity constraints to capture replacement-cycle timing across fragmented European building stock.
Market Dynamics
The EU F-Gas Regulation and Germany's Building Energy Act are compressing replacement cycles across European building stock, forcing simultaneous upgrades of heating source and heat emitter in millions of residential retrofits.
Growth Catalysts
- Heat pump compatibility mandates:Germany's Building Energy Act requires renewable-ready heating equipment in all replacement scenarios, mandating low-temperature emitters that operate efficiently below 45°C supply water.
- District heating network expansion:Nordic utilities in Denmark, Sweden, and Finland are lowering distribution temperatures to reduce heat losses, creating pull for enlarged-surface radiators optimized for 35-40°C supply.
- Aluminum extrusion advances:Improved die-casting precision enables thinner fins and higher convection coefficients, closing the thermal output gap between low-temperature and conventional high-temperature systems.
Market Restraints
- Copper and aluminum price volatility:Raw material input costs for heat exchanger cores fluctuate with London Metal Exchange pricing, compressing margins for panel radiator assemblers.
- Installer capacity bottlenecks:Germany's chamber of crafts reports insufficient trained heating technicians to execute mandated retrofit volumes within regulatory timelines.
- Legacy pipework incompatibility:Existing two-pipe systems in pre-1990s European housing stock require hydraulic recalculation and valve upgrades to function with low-temperature differential operation.
Strategic Opportunities
- Netherlands' off-gas grid zones:Municipal bans on new natural gas connections in Amsterdam, Rotterdam, and Utrecht create captive demand for all-electric heating with low-temperature hydronic distribution.
- Building-integrated photovoltaics convergence:Coupling rooftop solar generation with electric heat pumps and smart radiator valves enables zero-operating-cost heating in new-build residential segments.
- France's MaPrimeRénov' subsidy scaling:The national renovation support program now covers emitter replacement when paired with heat pump installation, lowering homeowner capital barriers.
Industry Challenges
- Hydraulic balancing expertise scarcity:Proper commissioning of low-temperature systems requires thermostatic valve characterization and flow temperature optimization skills that conventional gas-boiler installers lack.
- CE marking transition under Ecodesign:Manufacturers must retest product portfolios against updated efficiency metrics by 2027, requiring capital-intensive laboratory certification cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Temperature Radiators Market |
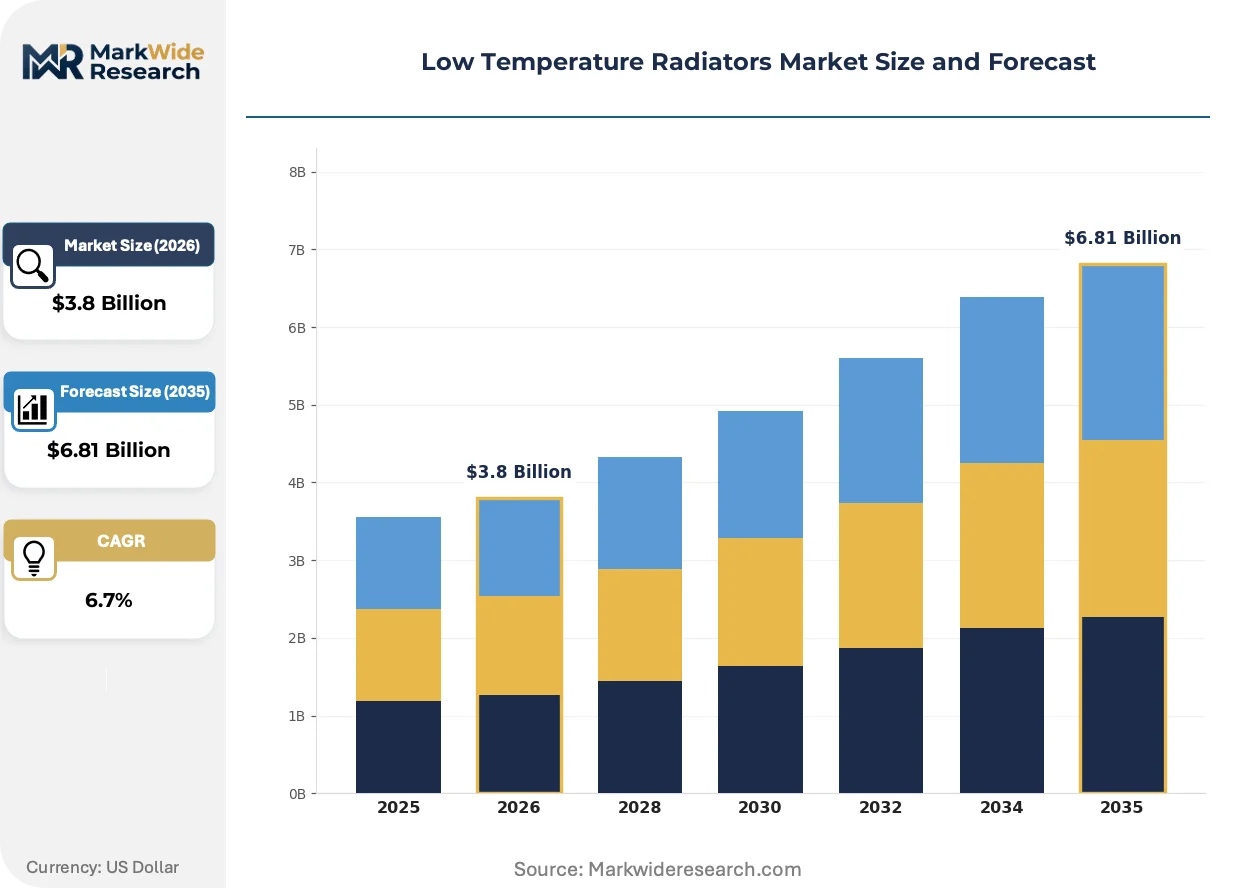
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydronic, Fan Coil, Electric, Panel End User: Residential, Commercial, Industrial, Educational Installation Type: Wall-Mounted, Floor-Standing, Ceiling-Mounted, Integrated Material: Aluminum, Steel, Copper, Plastic |
| Companies Covered | Denso Corporation, Mahle GmbH, Modine Manufacturing Company, Spectra Premium Mobility Solutions, Kelvion Holding, Trane Technologies Company, Rheem Manufacturing Company, Active Radiator, Johnson Controls International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Temperature Radiators Market Emerging Trajectories
Product architecture is converging around thermal response speed and digital controllability as heat pumps replace steady-output gas boilers with cycling compressors. Manufacturers are re-engineering thermal mass and sensor integration to match source behavior.
Microchannel aluminum heat exchangers with sub-millimeter hydraulic diameters are rendering obsolete traditional round-tube-and-fin constructions in residential radiators. Swedish and Finnish HVAC contractors specify these cores for their reduced water volume and faster response to heat pump modulation. The technology is compressing the performance penalty historically associated with low-temperature operation.
The EU F-Gas Regulation's phasedown of high-global-warming-potential refrigerants is accelerating heat pump redesigns that favor lower-temperature lifts. Equipment manufacturers are resizing compressors and expanding evaporators to maintain capacity with reduced temperature differentials. Panel radiator suppliers in Germany and Austria are publishing revised output tables at 35°C mean water temperature to match these source characteristics.
Specification authority is migrating from mechanical contractors to energy consultants and building physics engineers who model whole-system performance. Dutch and Belgian renovation platforms now require documented emitter sizing calculations before subsidy release. This professionalization is elevating technical documentation and selection software to competitive differentiators for radiator brands.
Low Temperature Radiators Market Segmentation
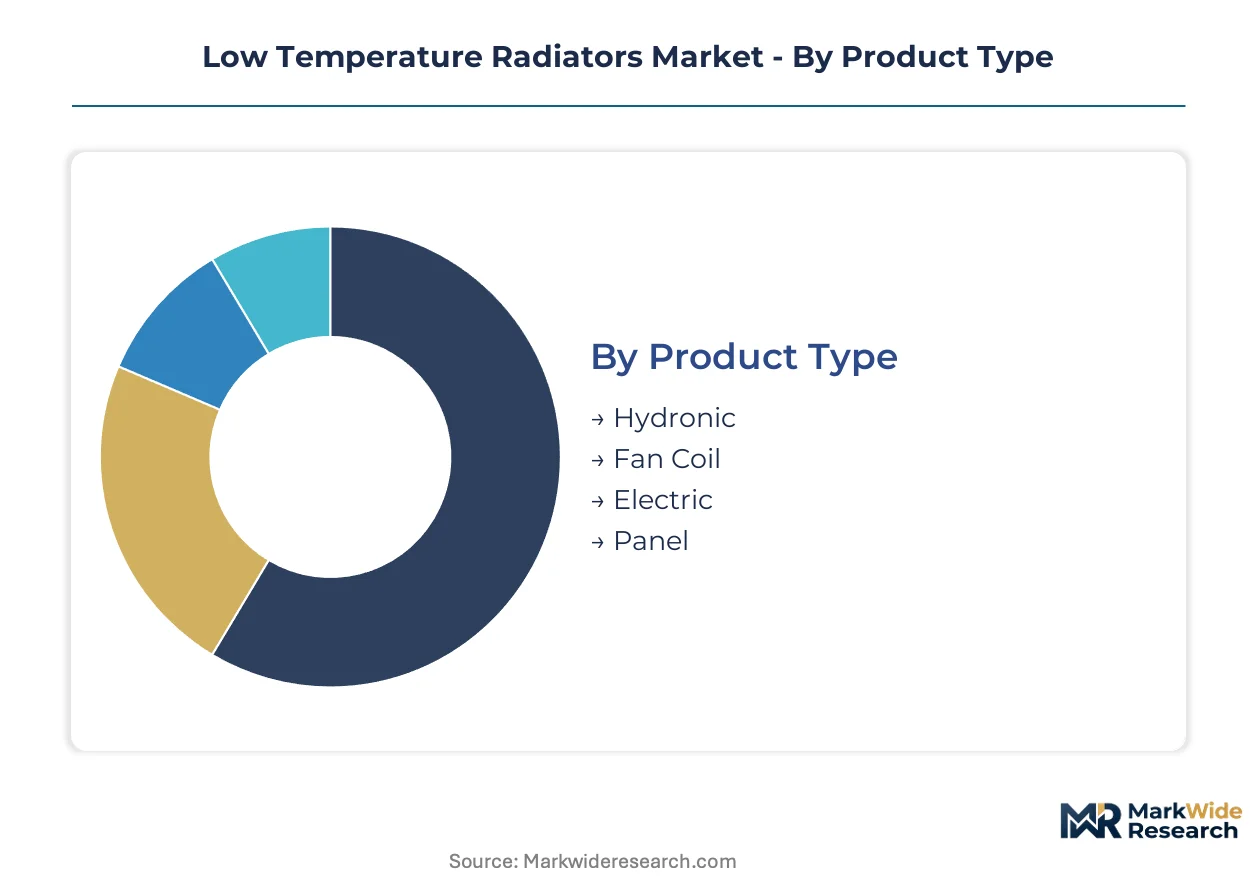
Low temperature radiators serve distinct thermal loads across building archetypes, each imposing unique hydraulic constraints and surface area requirements. Product architecture, installation geometry, and material selection determine compatibility with heat pump supply temperatures and retrofit feasibility. Understanding segment boundaries clarifies where specification authority concentrates and which technical standards govern procurement.
Product Type:
Cost tier separation across product categories reflects water volume, convection geometry, and control sophistication rather than raw material inputs alone.
- Hydronic:Circulating water systems with enlarged fin arrays and low water content cores engineered for 35-45°C supply temperatures. German and Dutch residential retrofits drive specification volumes where existing pipework accommodates emitter replacement without hydraulic redesign.
- Panel:Flat steel or aluminum constructions with convector fins welded to distribution headers, optimized for architectural integration through powder-coat finishes and modular width increments. Scandinavian district heating networks specify these for their rapid thermal response to variable supply temperatures.
- Fan Coil:Forced-air units combining water coils with tangential blowers to boost output at reduced mean water temperatures, common in French commercial renovation where floor space constraints limit radiator footprint.
- Electric:Resistance-element or heat-pump-coupled units with integrated thermostats, capturing new-build residential segments in Netherlands off-gas zones where all-electric heating is mandated.
Hydronic holds installed capacity. Electric is rotating up the share rankings.
End User:
Application context determines thermal load profiles, operating hours, and the economic viability of low-temperature emitter premiums.
- Residential:Single-family and multi-family dwellings where space heating dominates annual energy consumption. Germany's Building Energy Act mandates renewable-ready equipment in replacement scenarios, compressing payback periods for low-temperature retrofits.
- Commercial:Offices, retail, and hospitality with intermittent occupancy patterns requiring rapid response to setpoint changes. Denmark's district heating utilities specify oversized emitters for these loads to accommodate future supply temperature reductions.
- Industrial:Process heating and warehouse applications where radiant asymmetry and air stratification affect worker comfort. Finnish manufacturing facilities integrate low-temperature systems with waste heat recovery circuits.
- Educational:Schools and universities with concentrated occupancy schedules and seasonal shutdowns. Swedish municipal procurement frameworks prioritize lifecycle cost over first cost for these extended-horizon assets.
Residential dominates unit shipments. Commercial is climbing the fastest as Ecodesign enforcement tightens across member states.
Installation Type:
Volume constraints and architectural integration requirements segment the market by mounting geometry and spatial relationship to building fabric.
- Wall-Mounted:Conventional installation behind windows or on external walls, leveraging natural convection currents. Pre-1990s European housing stock predominantly uses this configuration, creating retrofit demand for low-temperature replacements sized to existing brackets.
- Floor-Standing:Freestanding units with integrated feet or plinths, specified where wall construction cannot support radiator weight or where full-height glazing eliminates wall mounting surfaces. Belgian new-build apartments increasingly specify these for aesthetic flexibility.
- Ceiling-Mounted:Suspended emitters exploiting stratification physics for high-bay industrial and atrium spaces. Austrian commercial architects specify these to preserve floor area for tenant fit-out flexibility.
- Integrated:Built-in systems concealed within architectural elements such as window seats or wall recesses. Dutch passive house projects favor these for thermal bridge mitigation and space optimization.
Wall-Mounted holds installed capacity. Integrated is rotating up the share rankings.
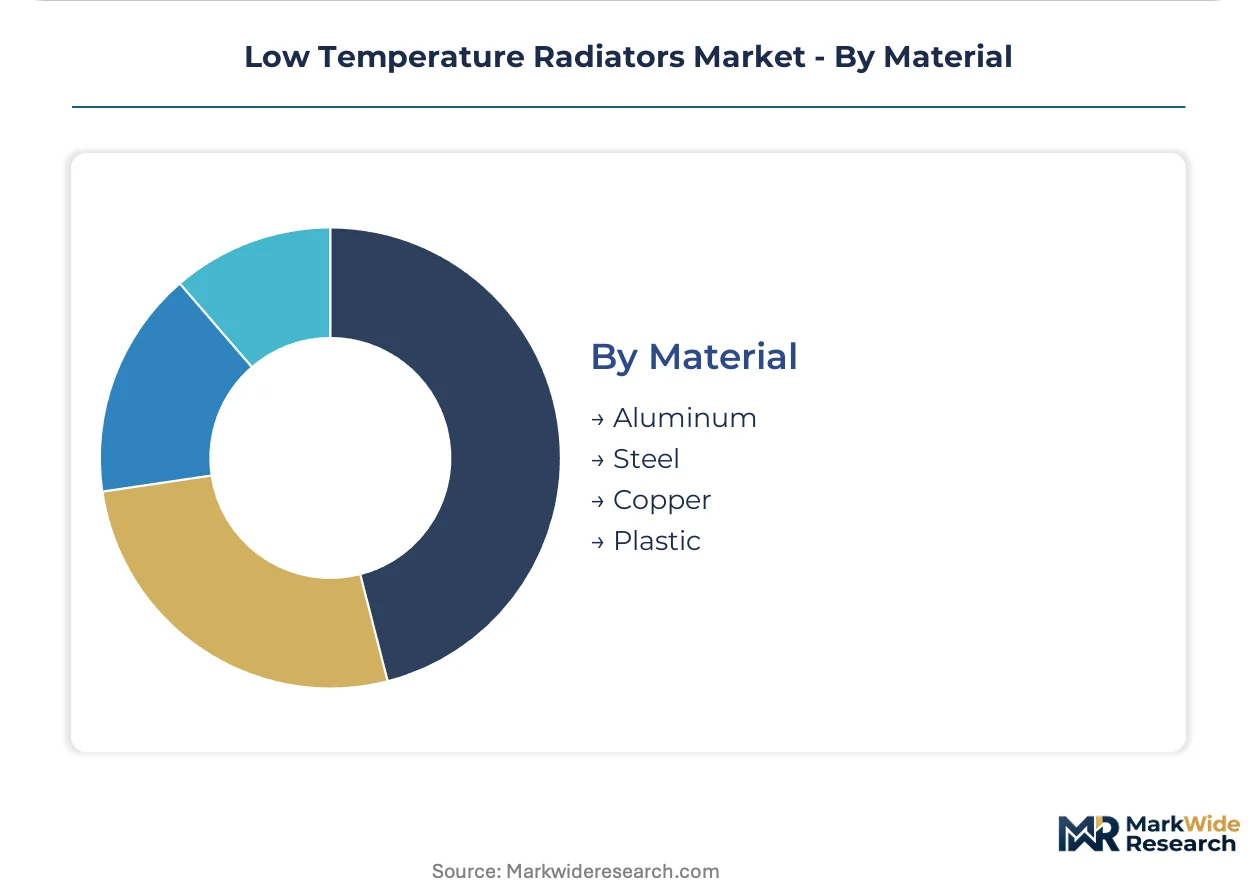
Material:
Margin structure and thermal performance differentiate material categories, with conductivity and corrosion resistance driving specification trade-offs.
- Aluminum:Extruded or die-cast alloys with high thermal conductivity enabling thin-wall constructions and rapid response to heat pump modulation. Chinese manufacturing clusters supply European OEMs with microchannel extrusions for residential panel radiators.
- Steel:Pressed or tubular constructions with superior pressure ratings and durability in closed-loop hydronic systems. German and Italian manufacturers dominate steel panel production for renovation markets.
- Copper:High-conductivity tube-and-fin assemblies for specialized industrial process applications and heritage building restorations where material authenticity is specified.
- Plastic:Polymer-based emitters for aggressive water chemistries or electric resistance heating elements where metallic corrosion is prohibitive. Niche applications in chemical processing facilities and marine environments.
Steel holds installed capacity. Aluminum is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Federal Ministry for Economic Affairs anchors the regulatory framework driving low-temperature radiator adoption through the Building Energy Act. The EU F-Gas Regulation and Ecodesign Directive create harmonized efficiency mandates across member states, while national subsidy programs determine retrofit velocity in fragmented European building stock.
Germany
Residential retrofits in single-family housing dominate volume demand as the Building Energy Act mandates renewable-ready heating equipment in all replacement scenarios. Municipal building authorities in Munich and Hamburg enforce strict compliance timelines for heat pump-compatible emitters. The Ruhr Valley industrial corridor hosts aluminum extrusion facilities supplying microchannel cores to panel radiator assemblers.
Netherlands
Amsterdam, Rotterdam, and Utrecht enforce municipal bans on new natural gas connections, creating captive demand for all-electric hydronic distribution systems. The national heat pump subsidy program covers emitter replacement when paired with renewable heating source installation. Eindhoven's manufacturing ecosystem produces specialized low-temperature coils for residential renovation platforms.
Sweden
Nordic district heating networks in Stockholm, Gothenburg, and Malmö are lowering distribution temperatures to 35-40°C, requiring enlarged-surface radiators optimized for reduced thermal gradients. The Swedish Energy Agency funds building energy renovation programs prioritizing lifecycle cost over first cost. Skåne County municipal procurement frameworks specify rapid-response panel systems for educational and healthcare facilities.
Denmark
Danish utilities in Copenhagen and Aarhus are expanding fourth-generation district heating with supply temperatures below 50°C, pulling demand for thermally responsive emitters. The Danish Energy Agency enforces building code provisions mandating heat pump readiness in new construction and major renovations. Jutland industrial zones host steel panel radiator production serving Scandinavian renovation markets.
France
MaPrimeRénov' national renovation support program now subsidizes emitter replacement when paired with heat pump installation, accelerating residential retrofit adoption. The French Agency for Ecological Transition enforces Ecodesign compliance thresholds for heating equipment in new and existing buildings. Lyon and Grenoble engineering clusters develop selection software tools for energy consultant specification workflows.
Low Temperature Radiators Market Vendor Landscape
Automotive-heritage thermal specialists and dedicated HVAC fabricators split the market across distinct specification channels. The vendor base concentrates among German engineering conglomerates with heat management legacies and North American residential equipment manufacturers with distributor network control. Two strategic archetypes dominate: OEM-integrated thermal system suppliers and independent panel radiator specialists. Competitive moves center on aluminum extrusion capacity expansion and digital selection tool deployment to capture specification authority from energy consultants.
Among automotive-heritage players, Mahle GmbH and Denso Corporation exemplify the OEM-integrated archetype, leveraging thermal management expertise developed in vehicle climate control applications. Kelvion Holding occupies a position within the industrial process cooling specialist tier, while Rheem Manufacturing Company represents the North American residential replacement-cycle channel. Johnson Controls International and Trane Technologies Company sit within the building systems integrator category, bundling emitters with heat pump and control offerings. Active Radiator exemplifies the independent retrofit-focused fabricator archetype serving aftermarket replacement demand.
| Leading Market Players |
|---|
| Denso Corporation |
| Mahle GmbH |
| Modine Manufacturing Company |
| Spectra Premium Mobility Solutions |
| Kelvion Holding |
| Trane Technologies Company |
| Rheem Manufacturing Company |
| Active Radiator |
| Johnson Controls International |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp barge freight corridors carry aluminum extrusions from Chinese manufacturing clusters to German panel radiator assemblers, with cost volatility in this route compressing margins for mid-tier producers while premium brands absorb logistics premiums through powder-coat finish differentiation.
Pricing Analysis
Geographic price spreads of 15-25% separate German-manufactured steel panels from Chinese-origin aluminum systems in European wholesale channels. Three-tier pricing structure across premium architect-specified, standard renovation-grade, and economy new-build levels stratifies the market, with CE marking tier and response-speed certification driving differentiation. Cost compression in the economy tier intensifies because Chinese microchannel extrusion capacity is expanding faster than European retrofit demand. Residential renovation contractors exhibit highest price sensitivity, while energy consultants specifying for passive house projects prioritize thermal performance over unit cost.
Supply Chain Analysis
Primary aluminum feedstock draws from Chinese smelting complexes, Russian ingot flows, and Middle Eastern secondary refining, with extrusion finishing concentrated in Zhejiang province and the Ruhr Valley. Copper tube and brass valve components hinge on Chilean concentrate and German semi-fabricated supply. Single-source vulnerability in Chinese microchannel die-casting creates exposure to export license disruptions. Distribution runs through HVAC wholesale cooperatives in Germany, Netherlands, and Scandinavia, with specification authority migrating to energy consultant platforms requiring documented output calculations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a service-attach opportunity where commissioning software and predictive maintenance subscriptions for smart radiator valves are expanding faster than hardware shipments, as hydraulic balancing expertise scarcity creates recurring revenue pools.
For Market Incumbents: Insulate core panel radiator margins by capturing captive aluminum extrusion capacity in the Ruhr Valley before Chinese export flows reconfigure. Defend specification authority against emerging HVAC-as-a-service platforms by embedding selection software directly into energy consultant workflows. CE marking transition investments by 2027 anchor defensive positioning. For New Entrants and Emerging Players: Pursue Netherlands off-gas zones where municipal gas connection bans create captive demand without incumbent installer relationships. Target French MaPrimeRénov' subsidy channels where emitter replacement is newly eligible alongside heat pump installation. Lead with digital commissioning tools that address hydraulic balancing expertise gaps in Germany's installer shortage. For Investors and Strategic Acquirers: Germany's Building Energy Act 2027 enforcement milestone reshapes the acquisition landscape toward aluminum extrusion specialists with certified low-temperature output tables. Five-to-ten year viability favors targets with backward integration into microchannel die-casting and established energy consultant specification relationships. Monitor heat pump subsidy trajectory volatility as the primary inflection signal for replacement-cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Aluminum Extrusion Capacity Expansion | Ruhr Valley facilities capture microchannel supply before Chinese export reconfiguration reshapes European sourcing. |
| Digital Selection Tool Deployment | Energy consultant platforms in Netherlands and France require documented emitter sizing for subsidy release authorization. |
| Backward Integration into Die-Casting | In-house microchannel production insulates margin pools from London Metal Exchange aluminum volatility. |
| Smart Valve Service Platform Launch | Predictive maintenance subscriptions address hydraulic balancing expertise scarcity in Germany's installer bottleneck. |
| CE Marking Pre-Certification Investment | Early laboratory testing against 2027 Ecodesign efficiency metrics secures product portfolio continuity. |
Methodological Framework
Initial hypotheses were tested against primary input from HVAC system engineers, energy consultant specification leads, heating installer guild representatives, and aluminum extrusion procurement managers, and refined through secondary validation against EU Ecodesign Directive implementation reports, Germany's Federal Ministry for Economic Affairs building energy statistics, Netherlands Enterprise Agency heat pump subsidy disbursement records, and Nordic district heating utility supply temperature disclosures. Bottom-up emitter shipment tallies by product type and installation geometry were triangulated against top-down building stock renovation velocity estimates.
Demand-supply balance framing anchored the analytical framework across the projection horizon, with segmentation modeled across hydronic, panel, fan coil, and electric product architectures, wall-mounted versus integrated installation types, and residential versus commercial end-use contexts. CAGRs were derived from replacement-cycle timing analysis under regulatory mandate scenarios, with heat pump compatibility penetration and district heating network temperature reduction schedules serving as primary volume drivers.
Sensitivities concentrate around German installer capacity constraints, Chinese aluminum export license policy shifts, and heat pump subsidy program continuity across member states. Cross-checking against national building renovation database permit filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Chilled Water System Market
Cooling Systems
Energy Storage Temperature Control Equipment Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Global Scroll and Absorption Chillers Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Cooling Tower Rental Market
Cooling Systems
Absorption Chillers Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Global Air Coolers Market
Cooling Systems
Adaptive Cooling Fan Market
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Global Chiller Market
Cooling Systems
Heat Pump Dryer Market
Cooling Systems
Temperature Controlled Container Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Global Secondary Refrigerants Market