
 Chilled Water Storage System Market | 2026-2036
Chilled Water Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Chilled Water Storage System Market Analysis
Modular tank configurations bundled with controls and insulation packages is rebalancing procurement decisions for large commercial buyers. Carrier Global Corporation leverages its integrated building systems portfolio to anchor multi-site contracts across healthcare and education verticals. Trane Technologies competes through deep specialization in thermal energy storage engineering and district cooling integration.
A chilled water storage system is an insulated vessel or tank array designed to store cooled water, typically between 4°C and 7°C, for later distribution to air handling units or process cooling loops; the primary purpose is load shifting, allowing chillers to operate during off-peak electricity periods while stored capacity handles daytime demand spikes. Thermal energy storage and hybrid storage configurations are capturing margin pools as owners prioritize demand-response revenue and resilience planning over first-cost minimization. Ice storage maintains steady adoption in dense urban districts where footprint constraints favor smaller tank volumes enabled by latent heat storage.
ASHRAE standards govern thermal performance and commissioning protocols, while the EPA regulates refrigerants used in charging systems that feed storage loops, together elevating the technical bar for market entry. The Department of Energy efficiency mandates for federal buildings indirectly stimulate retrofit demand across the installed base. Stakeholders must monitor evolving grid-interconnection tariffs and utility incentive structures that determine payback periods for storage investments.
Market Dynamics
Data center operators are driving a structural shift toward thermal energy storage as peak cooling loads strain grid interconnection capacity, forcing infrastructure planners to prioritize load-shifting assets over incremental chiller expansion.
Growth Catalysts
- Data center thermal loads:Hyperscale facilities in Texas and Arizona are mandating on-site storage to manage coincident peak demand, creating pull-through for large-capacity tank arrays.
- EPA refrigerant phase-downs:The Agency's hydrofluorocarbon management rules are accelerating chiller replacement cycles, bundling storage retrofits into compliance-driven capital plans.
- Utility demand-response tariffs:FERC Order 2222 implementation is enabling behind-the-meter storage assets to capture wholesale market revenues across organized markets.
Market Restraints
- Steel input volatility:Tank fabrication costs swing with hot-rolled coil pricing, compressing margins on fixed-price contracts for regional fabricators.
- Specialized welder scarcity:ASME-certified pressure vessel construction faces bottlenecked labor pools in the Gulf Coast fabrication corridor.
- Ice storage substitution:Latent heat systems capture footprint-constrained projects in dense urban districts, displacing chilled water configurations below 5,000 ton-hours.
Strategic Opportunities
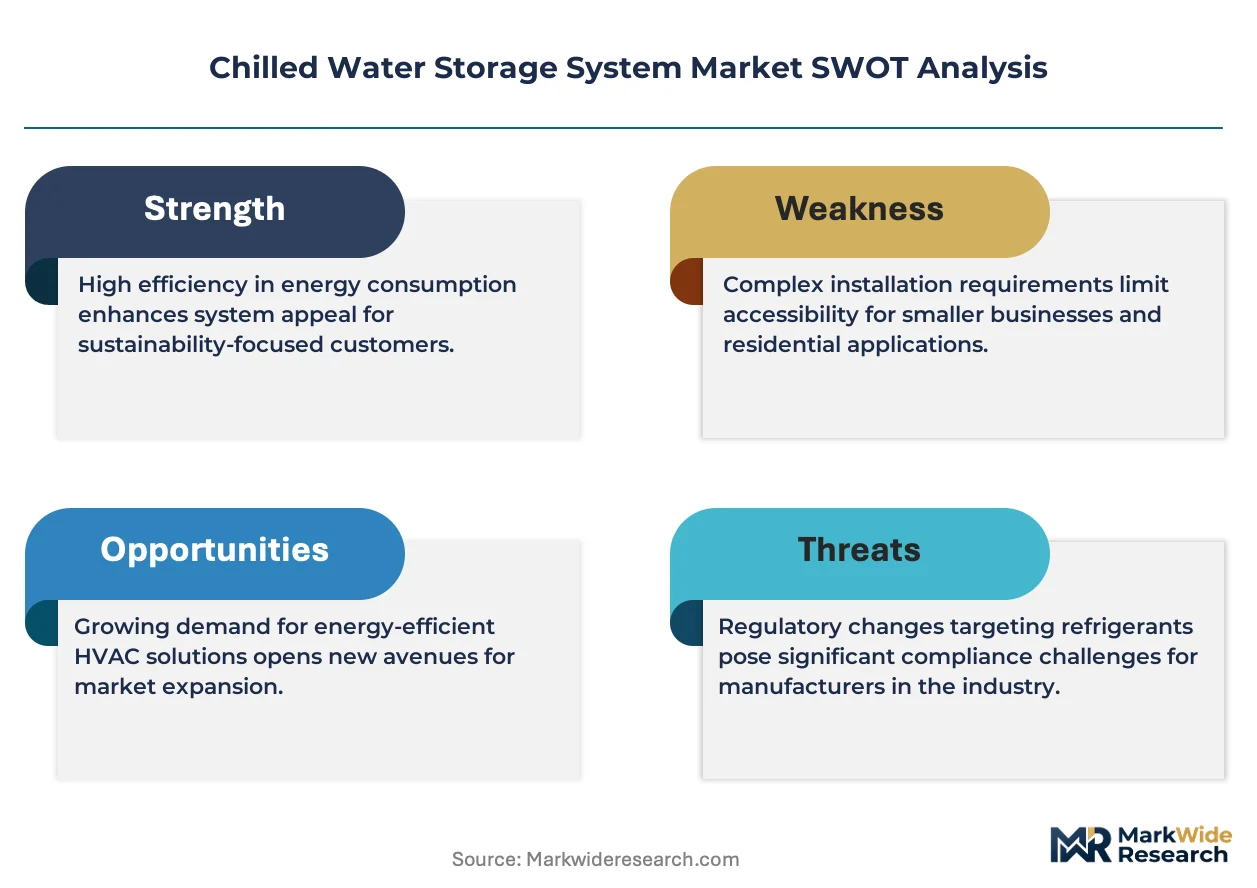
- Healthcare resilience mandates:ASHRAE Standard 170 revisions for hospital emergency cooling are creating retrofit demand across the installed base of aging medical campuses.
- Hybrid storage convergence:Chilled water-ice stratified tanks are opening technical white space for facilities seeking both load-shifting and emergency ride-through capability.
- India commercial construction:Green building certification under IGBC is embedding thermal storage into premium office developments in Bengaluru and Hyderabad.
Industry Challenges
- Commissioning complexity:Thermal performance verification against ASHRAE Standard 90.1 protocols extends project closeout timelines by 8-14 weeks.
- Controls integration:Legacy building automation systems lack native sequencing for storage discharge optimization, requiring middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chilled Water Storage System Market |
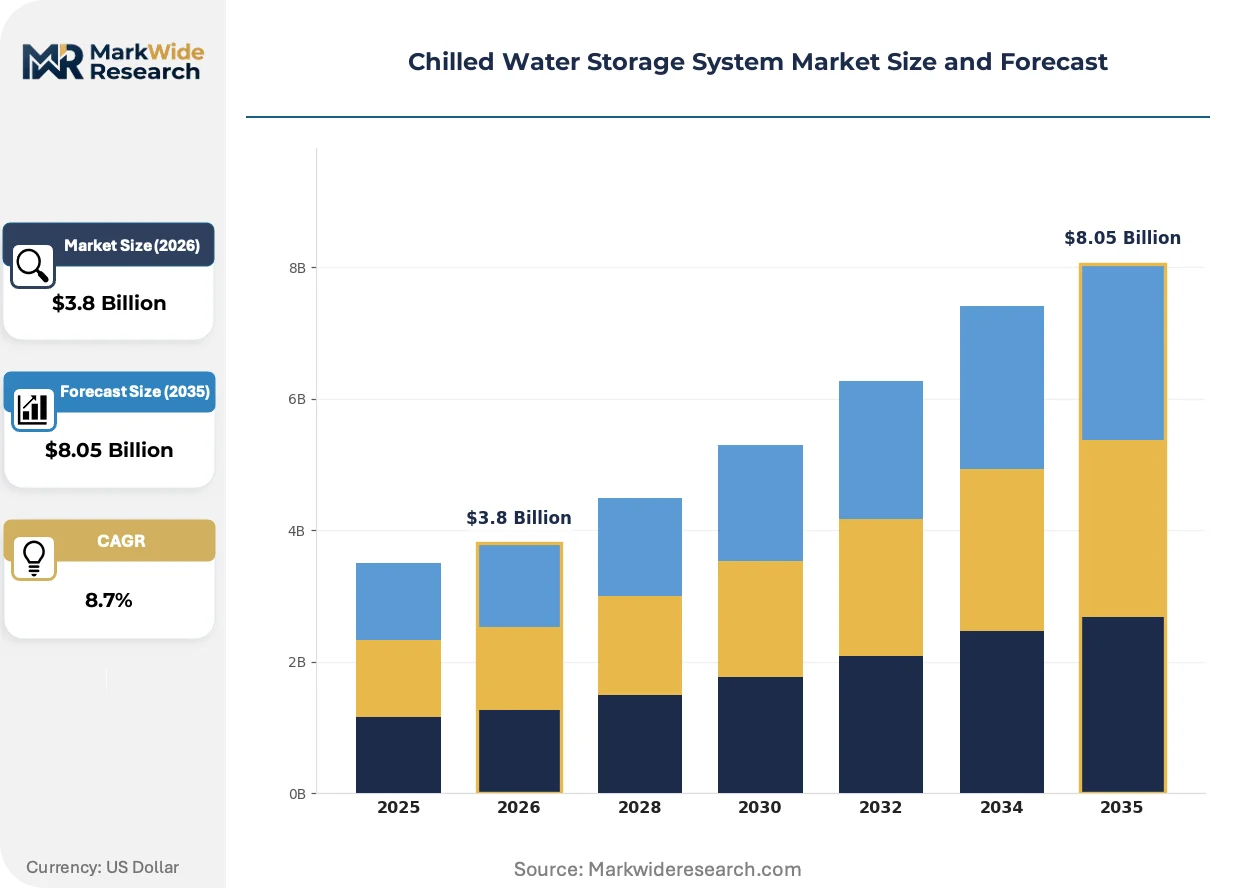
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Ice Storage, Thermal Energy Storage, Chilled Water Tank, Hybrid Storage Application: Commercial Buildings, Industrial Processes, District Cooling, Data Centers Installation Type: New Construction, Retrofit, Modular Systems, Large Scale End User: Hospitality, Education, Healthcare, Manufacturing |
| Companies Covered | Carrier Global Corporation, Trane Technologies, Johnson Controls, Daikin Industries, Ltd., Thermo King Corporation, Baltimore Aircoil Company, Calmac, EVAPCO, Inc., STULZ GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chilled Water Storage System Market Emerging Trajectories
Engineering practice is pivoting from passive storage vessels to intelligent thermal batteries, embedding predictive analytics and grid-interactive controls that transform static infrastructure into revenue-generating assets.
Phase change materials are converging with conventional chilled water architectures to create stratified storage systems that operate across both sensible and latent heat regimes. University campuses and research hospitals are piloting these hybrid configurations to compress tank volumes by 40-60% without sacrificing discharge duration. The technology is converging with district cooling networks in Singapore and the Middle East, enabling smaller mechanical footprints in dense urban districts where land scarcity dominates project economics.
The EU F-Gas Regulation is tightening quotas on hydrofluorocarbon refrigerants used in chiller systems that charge thermal storage loops, forcing equipment planners toward lower-GWP alternatives. Industrial consequence includes extended lead times for compliant chiller packages and accelerated obsolescence of installed base equipment. District cooling operators in Denmark and Sweden are responding with ammonia-based chiller retrofits bundled with expanded storage capacity to maintain system redundancy.
Buying committees are unbundling storage engineering from mechanical contractor scope, engaging specialized thermal storage integrators directly for performance-guaranteed outcomes. General contractors and design-build firms are losing share to niche engineering houses that underwrite thermal performance with liquidated damages clauses. This pattern is most visible in California and New York, where utility incentive programs require third-party measurement and verification protocols that favor independent specialist engagement over traditional trade relationships.
Chilled Water Storage System Market Segmentation
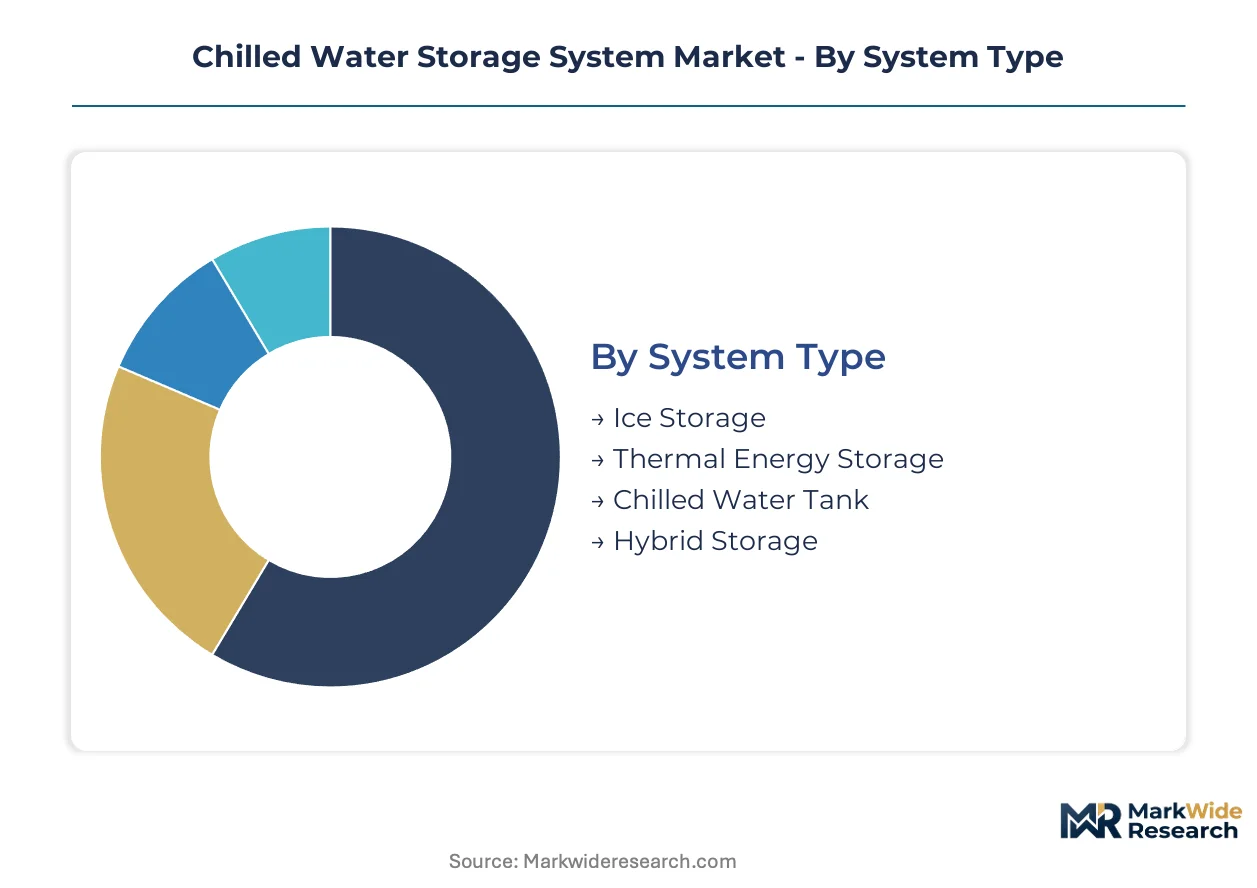
Technology choice in chilled water storage hinges on footprint constraints, discharge duration requirements, and integration complexity with existing chiller plants. Segmentation reveals how infrastructure planners balance first-cost against operational flexibility across divergent facility types.
System Type:
Upgrade cycles favor thermal energy storage retrofits over tank replacement, as existing concrete vessels accommodate new internal heat exchangers without structural demolition.
- Thermal Energy Storage:Sensible heat systems using stratified water columns dominate large-campus and district cooling deployments. Demand concentrates in Texas and Arizona data center clusters where load shifting defers transformer upgrades. Sizing flexibility from 500 to 50,000 ton-hours accommodates phased capital deployment.
- Hybrid Storage:Stratified tanks with embedded phase-change modules compress volumes by 40-60% versus pure water systems. Singapore district cooling networks and Middle Eastern commercial towers specify these configurations where land scarcity dominates project economics. Dual-mode operation enables both demand-response revenue and emergency ride-through.
- Ice Storage:Latent heat systems capture footprint-constrained projects in dense urban districts below 5,000 ton-hours.
- Chilled Water Tank:Conventional insulated vessels retain cost-sensitive education and hospitality retrofits with generous mechanical room space.
Volume placements concentrate in thermal energy storage; the faster expansion belongs to hybrid storage.
Application:
Cooling load profiles determine storage economics, with facilities experiencing sharp daily peaks yielding shortest payback periods.
- Data Centers:Hyperscale facilities generate 24/7 base loads with extreme coincident peaks during thermal batch jobs. Texas and Arizona operators now mandate on-site storage to manage grid interconnection limits. ASHRAE Standard 90.1 compliance drives storage integration into new builds.
- District Cooling:Centralized plants serving multiple buildings achieve scale economies impossible in single-facility deployments. Middle Eastern operators in Dubai and Riyadh pair ammonia chillers with expanded storage to maintain redundancy under EU F-Gas Regulation pressure.
- Commercial Buildings:Office towers and mixed-use developments leverage storage for demand-response tariffs in California and New York.
- Industrial Processes:Pharmaceutical and food processing facilities prioritize thermal stability over load shifting.
Data centers command the highest capacity per installation; district cooling delivers the steepest expansion trajectory as urban density intensifies.
Installation Type:
Project delivery method shapes contractor selection and performance risk allocation.
- Retrofit:Existing mechanical rooms accommodate tank insertion during chiller replacement cycles. Healthcare campuses in California pursue retrofits to satisfy ASHRAE Standard 170 emergency cooling mandates without new construction permits.
- Modular Systems:Factory-built tank segments with integrated insulation reduce field welding requirements. Gulf Coast fabricators facing ASME-certified welder scarcity favor modular approaches to compress schedules.
- New Construction:Greenfield projects embed storage from design inception, optimizing tank geometry and piping runs.
- Large Scale:Custom-engineered field-erected tanks exceed 10,000 ton-hours for district cooling and hyperscale data centers.
Retrofit volumes dominate the installed base refresh; modular systems are climbing fastest as labor constraints bite.
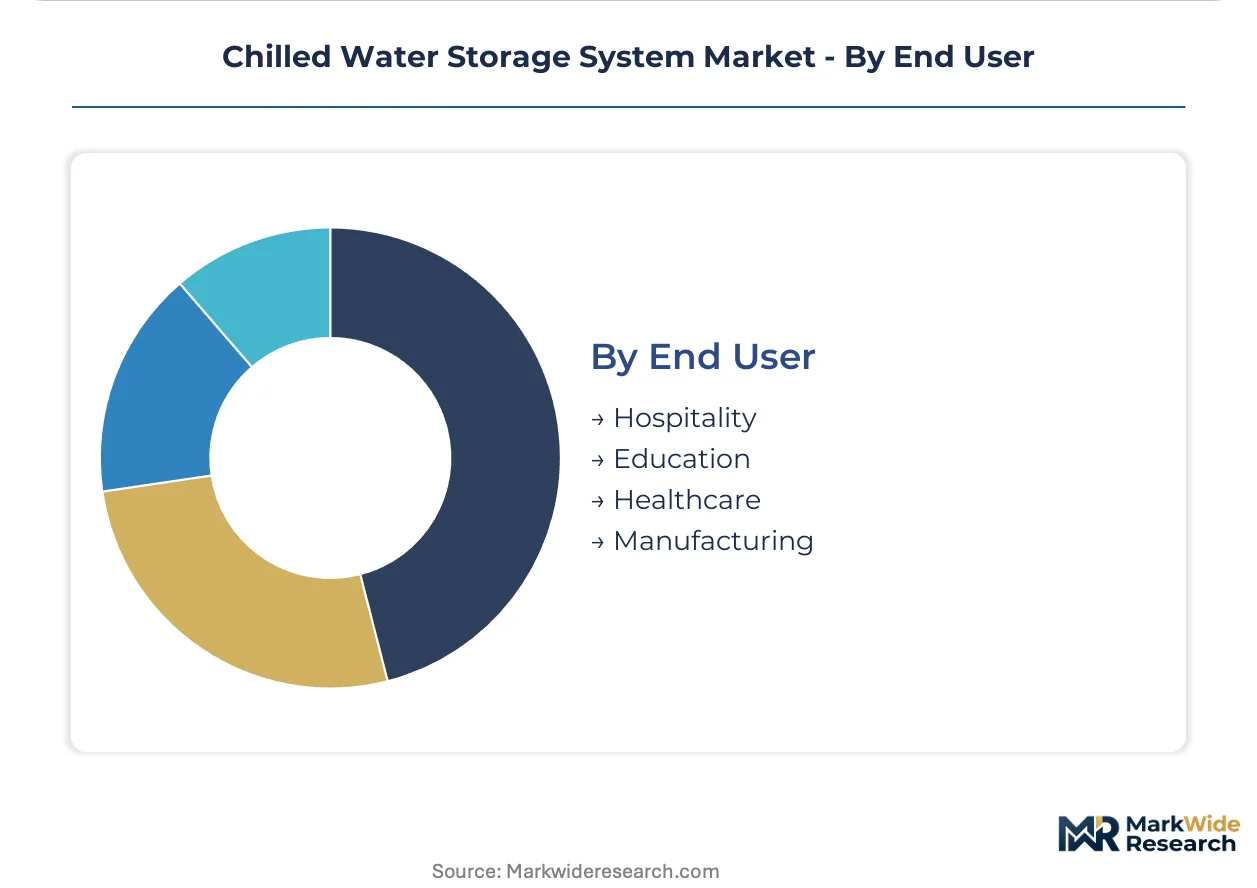
End User:
Regulatory pressure and resilience planning drive divergence in storage adoption across verticals.
- Healthcare:ASHRAE Standard 170 revisions mandate emergency cooling redundancy for hospital surgical suites and isolation rooms. Aging medical campuses in Sun Belt states face compliance-driven capital cycles bundling storage with chiller replacement.
- Education:University campuses pilot hybrid storage configurations to compress mechanical footprints while maintaining discharge duration. District energy systems at public institutions in California leverage FERC Order 2222 revenue streams.
- Hospitality:Hotels and resorts prioritize first-cost minimization, favoring conventional chilled water tanks where space permits.
- Manufacturing:Process cooling stability requirements limit storage adoption to load-shifting ancillary systems.
Healthcare generates the most regulation-driven placements; education offers the fastest-growing adoption curve as sustainability targets harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for chilled water storage systems clusters in the United States and Germany, while consumption concentrates in Sun Belt states, Middle Eastern commercial hubs, and South Asian data center corridors where cooling-degree days and grid constraints intersect.
United States
Hyperscale data center construction in Texas and Arizona mandates on-site thermal storage to manage interconnection limits. EPA refrigerant phase-downs under the AIM Act accelerate chiller replacement cycles that bundle storage retrofits. Dallas-Fort Worth and Phoenix anchor the largest deployment clusters for stratified tank arrays serving cloud computing facilities.
Germany
District cooling networks in Hamburg and Frankfurt prioritize ammonia-based chillers paired with expanded storage under EU F-Gas Regulation pressure. The country's building energy efficiency ordinances embed thermal storage into federal retrofit programs. Bavarian industrial zones pilot hybrid configurations combining sensible and latent heat regimes.
Singapore
Land scarcity drives specification of phase-change hybrid systems that compress tank volumes by 40-60% in Marina Bay and Jurong Lake District developments. The Building and Construction Authority mandates green building certification that embeds thermal storage into premium commercial towers. District cooling operators expand capacity to serve the Greater Southern Waterfront transformation.
India
IGBC green building certification requirements in Bengaluru and Hyderabad embed thermal storage into premium office developments. The Bureau of Energy Efficiency's Perform Achieve and Trade scheme creates compliance-driven demand for load-shifting infrastructure. Telangana's data center policy incentives attract hyperscale operators specifying on-site storage for grid stability.
United Arab Emirates
District cooling operators in Dubai and Abu Dhabi expand storage capacity to maintain redundancy under tightening refrigerant regulations. The Emirates Authority for Standardization and Metrology enforces efficiency mandates for district cooling plant retrofits. Masdar City's integrated energy systems demonstrate advanced thermal storage integration for net-zero commercial developments.
Chilled Water Storage System Market Vendor Landscape
The competitive structure tilts toward integrated building systems providers with multi-site contract execution capabilities. Market concentration remains moderate, with global HVAC conglomerates holding anchor positions alongside specialized thermal storage engineering houses. Two strategic archetypes dominate: full-system integrators leveraging controls and service portfolios, and niche specialists underwriting performance guarantees with liquidated damages clauses. Competitive moves center on vertical integration into tank fabrication and strategic partnerships with district cooling operators.
Among integrated building systems providers, Carrier Global Corporation and Trane Technologies occupy positions spanning healthcare, education, and data center verticals. Carrier leverages its multi-site service infrastructure to anchor performance contracts, while Trane competes through deep specialization in thermal energy storage engineering. Johnson Controls represents the controls-centric archetype, embedding storage optimization into building automation platforms. These three exemplify how procurement unbundling favors entities capable of underwriting thermal performance independently from general contractor scope.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Trane Technologies |
| Johnson Controls |
| Daikin Industries, Ltd. |
| Thermo King Corporation |
| Baltimore Aircoil Company |
| Calmac |
| EVAPCO, Inc. |
| STULZ GmbH |
| Others |
Supply Flow & Price Mechanics
Data center operators mandating ASHRAE Standard 90.1 compliance for new thermal storage installations are compressing supplier margins as specification complexity rises and certified fabrication capacity tightens across the Gulf Coast.
Pricing Analysis
Cost-down pressure on modular tank systems accelerates because ASME-certified welder scarcity in Texas and Louisiana extends delivery timelines and inflates labor premiums. Three-tier pricing structure across performance-guaranteed, standard-specification, and economy-grade levels separates projects by commissioning rigor and liquidated damages clauses. Price differentiation traces to certification tier and volume scale, with healthcare and data center buyers absorbing premiums for third-party verification. Education and hospitality verticals exhibit highest price sensitivity, prioritizing first-cost minimization over operational flexibility.
Supply Chain Analysis
Freight costs for insulated tank segments shipped from Gulf Coast fabricators to Sun Belt data center clusters have become a material line item in project economics. Manufacturing concentrates in the United States, Germany, and Singapore, with steel coil sourcing tethered to domestic mills and European producers. Raw material dependencies span hot-rolled steel, polyurethane insulation, and copper heat exchanger tubing. Single-source vulnerability concentrates in ASME-certified pressure vessel fabrication, where qualified labor pools cannot scale with demand spikes. Distribution runs through specialized thermal storage integrators who displace general contractors in performance-guaranteed engagements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EPA refrigerant phase-downs under the AIM Act and ASHRAE Standard 170 revisions erect technical barriers that favor incumbents with established certification infrastructure and multi-site service networks.
For Market Incumbents: To counter ice storage substitution in footprint-constrained urban districts, deepen engineering specialization in hybrid chilled water-phase change configurations and secure captive supply of phase change material modules through backward integration into specialty chemical sourcing. Anchor multi-site contracts across healthcare verticals by underwriting thermal performance with liquidated damages clauses that emerging players cannot match. For New Entrants and Emerging Players: Begin with district cooling retrofits in Middle Eastern commercial hubs where EU F-Gas Regulation pressure accelerates ammonia chiller replacement cycles and storage expansion demand outpaces incumbent capacity. Target modular system deployments in India where IGBC green building certification creates compliance-driven pull without requiring established US healthcare relationships. Pursue direct engagement with thermal storage integrators rather than general contractors to bypass entrenched procurement channels. For Investors and Strategic Acquirers: The window for entry favors specialized thermal storage engineering houses with performance-guaranteed contract track records and district cooling operator relationships in Singapore and the Middle East. Long-term viability hinges on regulatory tightening trajectory across multiple geographies rather than cyclical construction spend. Monitor FERC Order 2222 implementation pace across organized markets as the signal for demand-response revenue maturation that would revalue storage assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phase Change Materials | Captures margin pools in hybrid storage configurations while securing supply against specialty chemical bottlenecks. |
| Performance-Guaranteed Contracting Model | Displaces general contractors in California and New York where utility incentive programs mandate third-party verification protocols. |
| District Cooling Operator Partnership | Locks in multi-year expansion schedules in Dubai and Riyadh as F-Gas Regulation compliance accelerates retrofit cycles. |
| Modular System Factory Prefabrication | Compresses field schedules in Gulf Coast markets facing ASME-certified welder scarcity and labor cost inflation. |
| Grid-Interactive Controls Platform Development | Enables wholesale market revenue capture under FERC Order 2222 across Texas and Arizona data center deployments. |
Methodological Framework
Independent corroboration across primary interviews with district cooling operators, data center infrastructure planners, and ASME-certified tank fabricators, combined with secondary validation through EPA AIM Act filings, FERC Order 2222 implementation records, and ASHRAE standard revision documentation, underwrites the qualitative findings. Bottom-up triangulation of project-level capacity installations and top-down cross-check against utility incentive program disbursements anchors volume estimates. Conversations with thermal storage integrators in California, Texas, and Singapore provided forward-looking procurement pattern intelligence.
Rate-of-change decomposition across the analysis window segments growth by system type, installation method, end-use vertical, and regional regulatory framework. The analytical framework models technology substitution dynamics between sensible, latent, and hybrid thermal storage configurations. CAGRs derive from installed base refresh cycles, new construction permitting data, and compliance-driven replacement timelines tied to refrigerant phase-down schedules. Forecast inputs incorporate steel price volatility indices and certified welder labor market tightness metrics.
Underlying measurement precision varies by segment; data center and district cooling deployments carry tighter precision than fragmented commercial building retrofits. Forecasts reflect assumptions regarding regulatory implementation pace, utility tariff structure stability, and material input cost normalization. Stakeholders should weight assumptions against their own operating context and local grid interconnection constraints.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cooling Systems
Flue Gas Coolers Market
Cooling Systems
Solar Cold Room Market
Cooling Systems
Global Magnetic Refrigeration Market
Cooling Systems
Industrial Cooling System Market
Cooling Systems
Roll Bond Evaporator Market
Cooling Systems
Evaporative Condensing Unit Market
Cooling Systems
Fluid Coolers Market
Cooling Systems
Marine Cooling Systems Market
Cooling Systems
Evaporative Cooling Tower Market
Cooling Systems
Global Energy Efficient HVAC Systems Market
Cooling Systems
Microchannel Heat Exchanger Market
Cooling Systems
Adiabatic Cooler Market
Cooling Systems
Industrial Radiators Market
Cooling Systems
Europe Air Source Heat Pump Market
Cooling Systems
Industrial Water Cooling System Market
Cooling Systems
Lithium Battery Liquid Cooling Pump Market