
 Li-Ion Pouch Battery Market | 2026-2036
Li-Ion Pouch Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Li-Ion Pouch Battery Market Insights
The EU Battery Regulation is shifting procurement specifications across European automotive supply chains, mandating recycled content thresholds and carbon footprint declarations for cells entering the single market. LG Energy Solution leverages its Polish manufacturing base to preempt compliance timelines for EU-assembled EV platforms. Samsung SDI anchors its premium pouch cell output on silicon-anode R&D pipelines targeting luxury automotive nominations. CATL dominates cylindrical-to-pouch conversion programs with Chinese OEMs seeking pack-level energy density gains.
A Li-Ion Pouch Battery employs layered electrode stacks sealed within flexible aluminum-laminate film enclosures, typically achieving 260-300 Wh/kg gravimetric energy density through stacked or Z-fold winding architectures that maximize active material loading per unit volume. High Energy Pouch variants command the strongest margin pools as automotive OEMs prioritize range extension over cycle-life metrics in premium platform designs. Consumer Electronics demand for Ultra-Thin Pouch configurations sustains volume throughput despite lower per-unit pricing, while Flexible Pouch formats gain traction in wearable medical devices requiring conformal pack geometries.
FDA device-level battery safety guidance and EPA hazardous waste rules for lithium-ion manufacturing byproducts shape product certification pathways and facility siting decisions in the United States. China's GB standards and SAMR compulsory certification requirements govern cell format approvals for domestic EV subsidy eligibility. The EU AI Act and CSRD disclosure mandates will extend traceability obligations from raw material provenance through end-of-life recovery. Stakeholders must monitor how divergent recycling efficiency benchmarks across these jurisdictions reshape cost structures for second-life material reintegration.
Market Dynamics
Automotive OEM platform consolidation around lithium-nickel-manganese-cobalt pouch architectures is compressing prismatic cell procurement timelines and rewiring tier-one supplier qualification protocols across European and North American EV assembly networks.
Growth Catalysts
- EU Battery Regulation recycled content mandates:The framework's carbon footprint declarations and minimum recovery thresholds are forcing cell manufacturers to reconfigure supply chains toward certified secondary material streams.
- Silicon-anode R&D pipelines:Premium automotive nominations for next-generation energy density targets are accelerating pilot-line investments at Korean and Chinese research clusters.
- Chinese domestic recycling infrastructure:MEE dual carbon goals are tightening manufacturing emissions standards and channeling state capital toward closed-loop material recovery facilities.
Market Restraints
- Cobalt price volatility:DRC supply concentration and artisanal mining exposure create unhedgeable input cost swings that compress margin predictability for high-nickel cathode formulations.
- Polish manufacturing bottleneck:LG Energy Solution's sole European gigafactory concentration creates single-source vulnerability for EU-assembled EV platforms facing compliance deadlines.
- Prismatic cell residual demand:Tesla's structural battery pack designs and BYD's blade-cell architectures retain cost advantages in mass-market vehicle segments.
Strategic Opportunities
- Indian PLI scheme localization:Cell manufacturing incentives under the government's production-linked initiative are attracting Korean and Chinese joint ventures seeking tariff-advantaged supply to domestic two-wheeler electrification.
- Wearable medical device flexible formats:FDA device-level battery safety guidance is creating certification moats for conformal pouch geometries in continuous glucose monitoring and cardiac rhythm management applications.
- Solid-state electrolyte convergence:Oxide and sulfide ceramic separator technologies are opening hybrid architecture pathways that retain pouch form-factor flexibility while eliminating thermal runaway risks.
Industry Challenges
- Electrolyte formulation talent scarcity:Experienced solid-state and high-voltage electrolyte chemists command premium compensation in a labor market where Korean and Japanese competitors anchor R&D gravity.
- GB standards certification timelines:SAMR compulsory approval processes for domestic EV subsidy eligibility extend product launch windows by 8-14 months versus unregulated export markets.
- Legacy cylindrical-to-pouch retooling:CATL's conversion programs with Chinese OEMs require welding and winding equipment replacement that strains capital allocation across multi-format production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Li-Ion Pouch Battery Market |
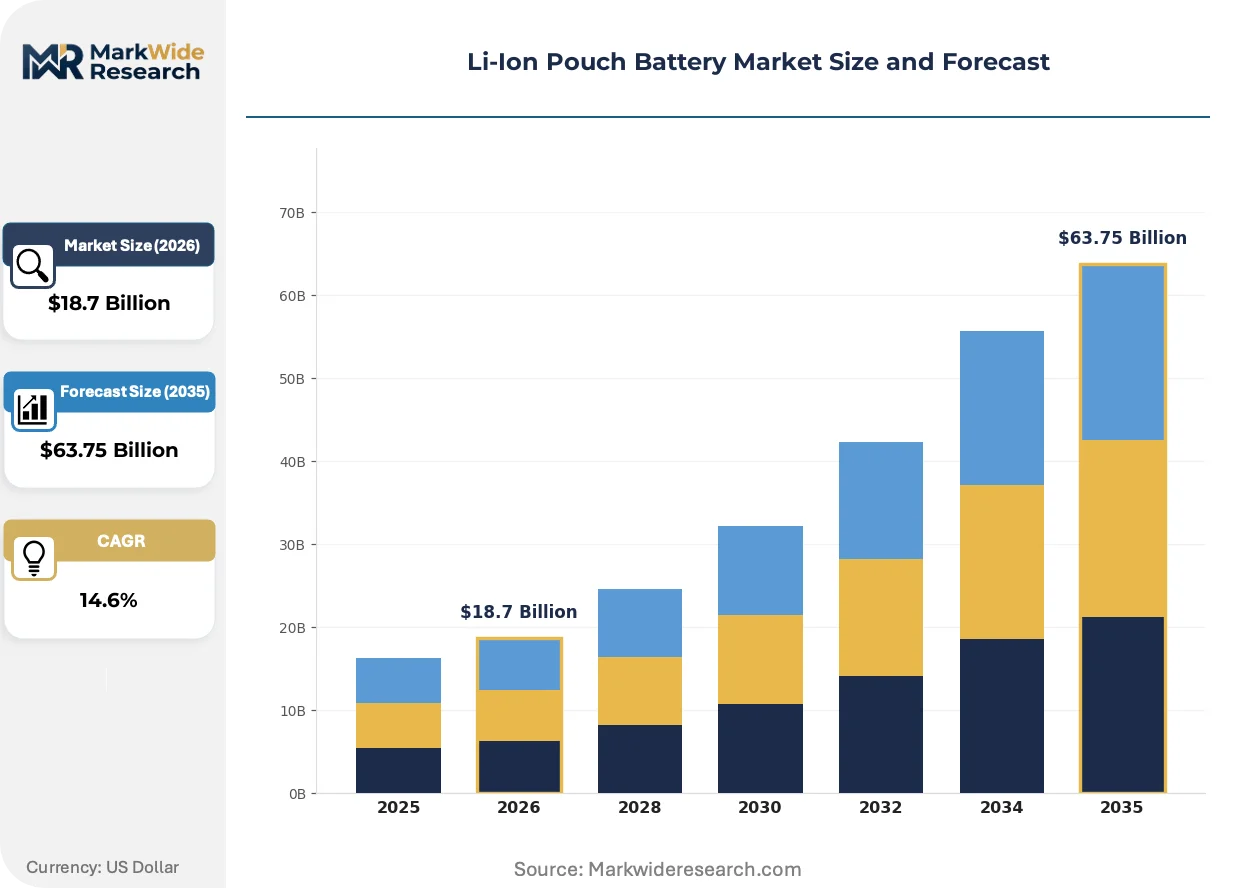
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pouch, High Energy Pouch, Flexible Pouch, Ultra-Thin Pouch End User: Consumer Electronics, Automotive, Energy Storage, Medical Devices Charging Technology: Fast Charging, Wireless Charging, Solar Charging, Standard Charging Capacity: 500 mAh, 1000 mAh, 3000 mAh, 5000 mAh |
| Companies Covered | BYD, Youlchon Chemical, LG Energy Solution, Zijiang New Material, SELEN Science & Technology, CATL, Samsung SDI, Dai Nippon Printing, Resonac Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Li-Ion Pouch Battery Market Trends and Innovations
Electrode stack architectures and sealing technologies are converging toward higher active material loading densities, while regulatory traceability mandates and buyer consolidation are compressing supplier differentiation strategies.
Silicon-graphite composite anodes are consolidating their position as the dominant pathway to 300+ Wh/kg gravimetric targets without sacrificing cycle stability. Korean cell manufacturers are locking in five-year offtake agreements with metallurgical-grade silicon suppliers to secure precursor volumes. This chemistry consolidation is compressing competing lithium-metal and solid-state development timelines by narrowing institutional R&D funding allocation.
CSRD disclosure mandates are extending traceability obligations from raw material provenance through end-of-life recovery across European automotive supply chains. Battery passport requirements under the EU Battery Regulation are forcing cell manufacturers to deploy blockchain-verified chain-of-custody systems by 2027. Premium EV platforms are responding by pre-qualifying suppliers with certified cobalt and lithium hydroxide streams before nomination decisions.
Buyer concentration around vertically integrated OEMs is collapsing the traditional tiered distributor model for automotive cell procurement. Direct platform nominations from Volkswagen, BMW, and Hyundai Motor Group are displacing independent battery trading houses that historically managed spot-market arbitrage. This channel compression is most visible in South Korea, where Samsung SDI and LG Energy Solution have eliminated third-party sales teams for EV-dedicated production lines.
Li-Ion Pouch Battery Market Segmentation
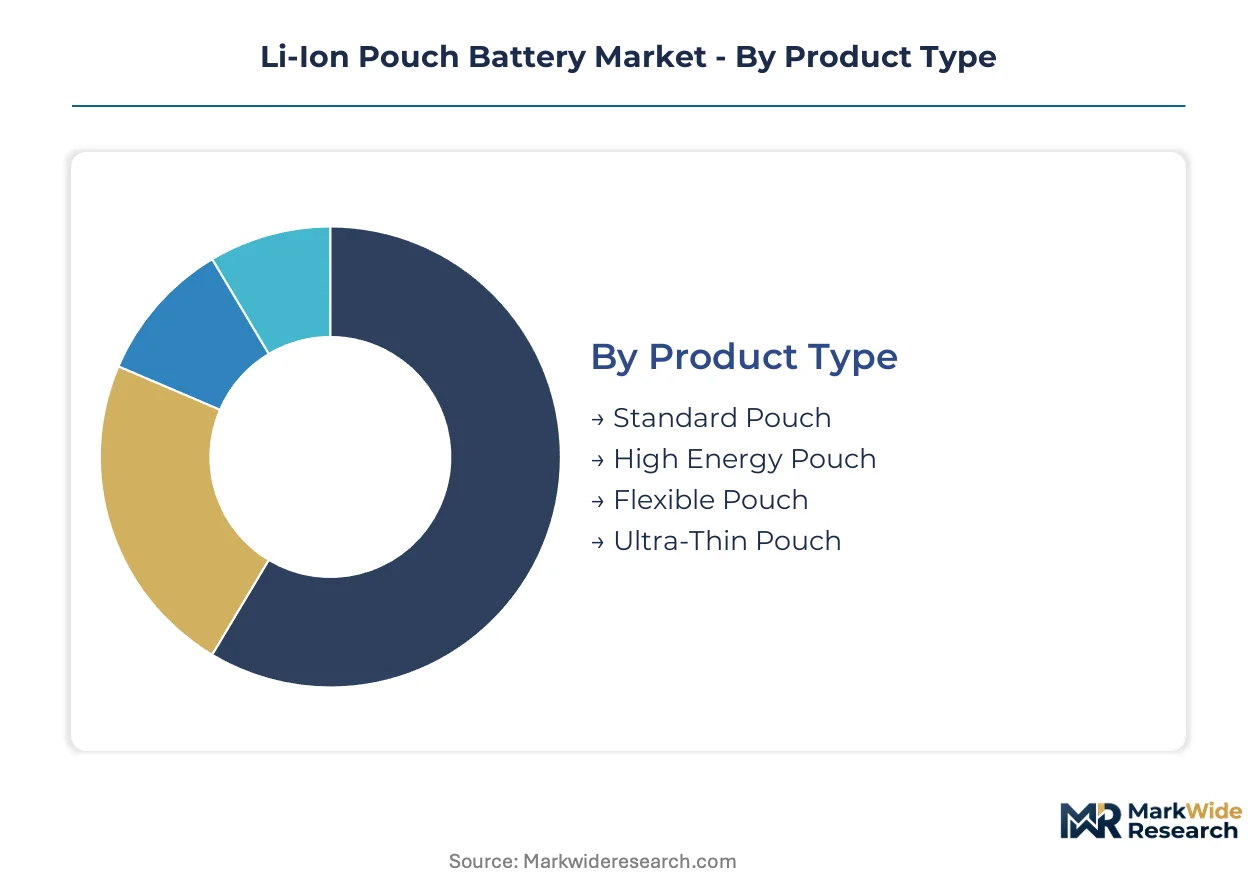
Segmentation in the Li-Ion Pouch Battery Market reveals how cell architectures align with distinct performance thresholds and procurement economics. Each dimension—product format, end-use application, charging interface, and energy storage—creates separate margin pools and qualification barriers.
Product Type:
Upgrade cycles across product tiers accelerate as automotive OEMs retire prismatic formats and consumer electronics brands pursue thinner device profiles.
- High Energy Pouch:Silicon-graphite composite anodes and high-nickel cathode loadings push gravimetric density past 300 Wh/kg. Korean manufacturers anchor pilot-line investments to secure premium automotive nominations from European luxury EV platforms.
- Ultra-Thin Pouch:Sub-3mm Z-fold architectures maximize volumetric efficiency for smartphones and tablets. Samsung SDI and LG Energy Solution dedicate Korean production lines to Apple and Android OEM procurement schedules despite compressed per-unit margins.
- Standard Pouch:Conventional stacked-electrode designs serve mid-range consumer electronics and industrial handheld devices with balanced cycle-life metrics.
- Flexible Pouch:Conformal aluminum-laminate enclosures enable wearable medical devices requiring bend radii under 10mm.
High Energy Pouch sits at the top of the volume ranking, with Flexible Pouch climbing the fastest.
End User:
Cost-tier stratification separates qualification-intensive automotive procurement from high-volume consumer electronics spot purchasing.
- Automotive:Platform nominations from Volkswagen, BMW, and Hyundai Motor Group require cell-level carbon footprint declarations under EU Battery Regulation mandates. Polish and Korean gigafactory output flows directly to North American and European EV assembly plants.
- Consumer Electronics:Smartphone and laptop OEMs prioritize Ultra-Thin Pouch formats with 18-month product refresh cycles driving continuous capacity expansion at Chinese manufacturing bases.
- Medical Devices:FDA device-level battery safety guidance creates certification moats for continuous glucose monitors and cardiac rhythm management systems requiring conformal geometries.
- Energy Storage:Grid-scale and residential battery systems favor High Energy Pouch configurations for modular rack designs with 15-year service life targets.
Automotive commands the steepest expansion trajectory, while Medical Devices offers the most defensible margin structure.
Charging Technology:
Application-specific duty cycles determine which charging interfaces achieve procurement scale across end-use segments.
- Fast Charging:4C-rate capable electrolyte formulations and advanced thermal management enable 10-minute charge windows for premium automotive platforms. Korean cell manufacturers lock in metallurgical-grade silicon offtake agreements to sustain high-rate anode stability.
- Standard Charging:0.5C-1C rate architectures dominate consumer electronics and medical device applications where cycle-life extension outweighs charge-speed priorities.
- Wireless Charging:Qi-compatible coil integration drives demand for standardized pouch dimensions in smartphone and wearable device ecosystems.
- Solar Charging:Low-rate trickle-charge optimization serves off-grid energy storage and remote sensor network deployments with intermittent power availability.
Fast Charging leads absolute volume, with Solar Charging gaining share fastest in off-grid infrastructure builds.
Capacity:
Volume-scale procurement concentrates at mid-range capacities where manufacturing equipment utilization peaks.
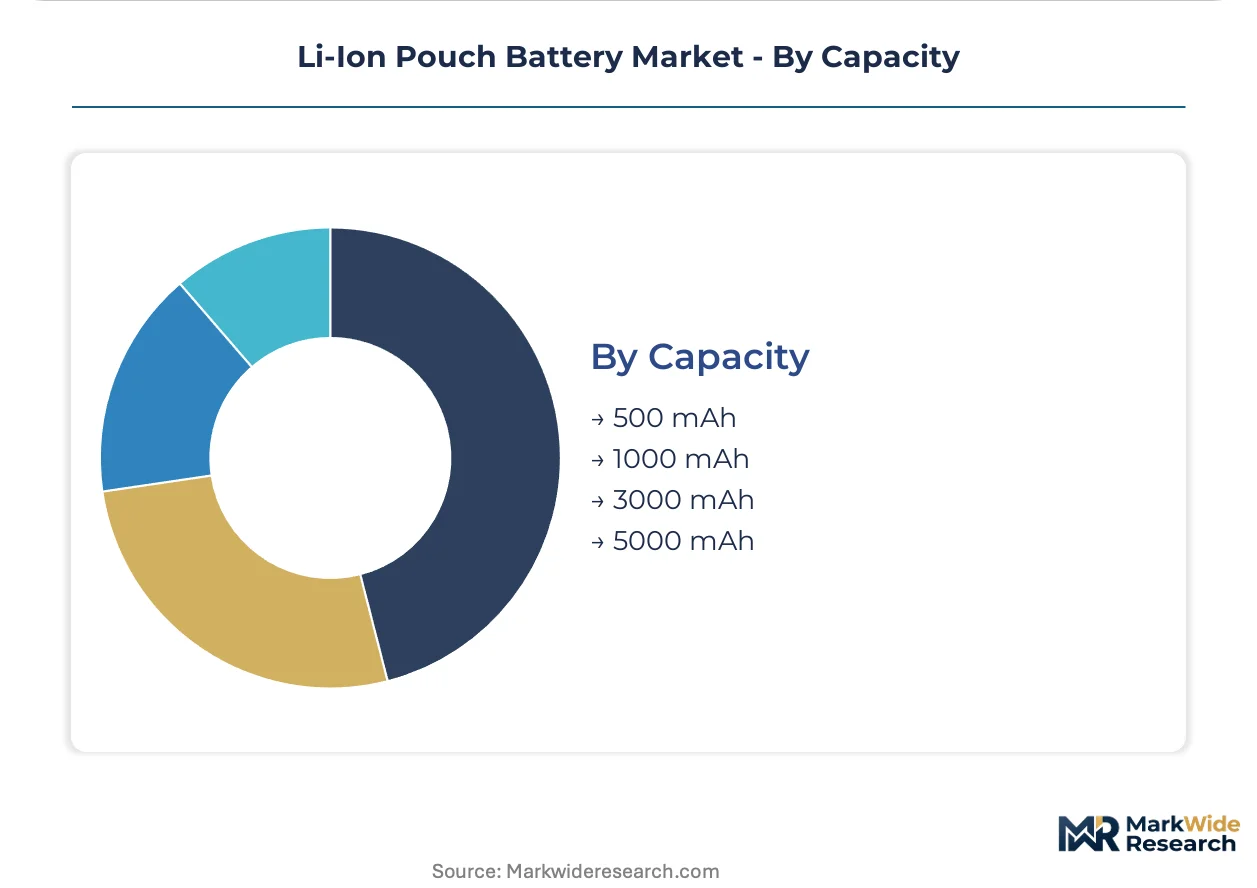
- 3000 mAh:Dominant format for premium smartphones and compact laptops balancing energy density against thermal dissipation constraints. Chinese OEM conversion programs from cylindrical cells channel demand toward this capacity tier.
- 5000 mAh:Emerging standard for gaming smartphones and ultraportable laptops requiring all-day runtime without recharge cycles.
- 1000 mAh:Wearable device and wireless earbud applications where volumetric constraints limit active material loading.
- 500 mAh:Hearing aids, smart rings, and miniaturized medical sensors requiring sub-2g cell mass.
3000 mAh sits at the top of the volume ranking, with 5000 mAh climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pouch cell manufacturing originated in Japanese consumer electronics supply chains during the early 2000s before Korean conglomerates scaled automotive-grade production. Chinese producers now dominate cathode material refining and cell assembly capacity. European regulatory frameworks are reshaping where final pack integration occurs.
China
Domestic EV procurement and energy storage deployment absorb the majority of regional cell output. SAMR compulsory certification under GB standards governs subsidy eligibility for passenger vehicle platforms. The Yangtze River Delta cluster around Shanghai anchors CATL's pilot-line investments for silicon-anode pouch architectures.
South Korea
LG Energy Solution and Samsung SDI supply North American EV assembly plants through direct platform nominations. METI-aligned industrial policy channels state capital toward solid-state electrolyte R&D pipelines. The Gwangju-Ulsan battery corridor concentrates pouch cell output for luxury automotive nominations.
Germany
Volkswagen and BMW procurement teams mandate carbon footprint declarations under EU Battery Regulation timelines. KBA type-approval processes integrate cell-level compliance verification into vehicle homologation. Bavaria hosts pilot recycling facilities testing closed-loop lithium hydroxide recovery from production scrap.
United States
IRA production credits incentivize domestic cell manufacturing joint ventures with Korean partners. EPA hazardous waste rules govern electrolyte formulation facility siting in industrial zones. The Southeast manufacturing belt attracts gigafactory investments serving Detroit Three EV platform launches.
Poland
LG Energy Solution's sole European production base supplies EU-assembled EV platforms facing recycled content mandates. ECHA REACH compliance documentation accompanies cathode active material imports from Asian refiners. Lower Silesia's industrial zones concentrate electrode coating and cell assembly operations.
Li-Ion Pouch Battery Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in the Li-Ion Pouch Battery Market. Korean and Chinese conglomerates anchor automotive supply through captive cathode material refining and in-house separator production. Three archetypes dominate: vertically integrated chemical conglomerates, dedicated cell specialists, and materials-science spinouts from printing and packaging industries. Competitive moves concentrate on silicon-anode pilot-line scaling and direct OEM platform nominations that displace independent battery trading channels.
Among Korean producers, LG Energy Solution and Samsung SDI exemplify the integrated conglomerate archetype with control across separator, electrolyte, and cell assembly operations. CATL represents the Chinese specialist model through cylindrical-to-pouch conversion programs with domestic OEMs. Youlchon Chemical occupies a position within the materials-tier supplier category, anchoring aluminum-laminate film enclosure supply to regional cell manufacturers.
| Leading Market Players |
|---|
| BYD |
| Youlchon Chemical |
| LG Energy Solution |
| Zijiang New Material |
| SELEN Science & Technology |
| CATL |
| Samsung SDI |
| Dai Nippon Printing |
| Resonac Corporation |
| Others |
Pricing and Supply Chain Analysis
European luxury EV platform procurement teams now concentrate annual cell nominations into direct manufacturer relationships, compressing spot-market intermediation and cementing long-term offtake contracting as the dominant pricing mechanism for high-nickel pouch configurations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates silicon-anode automotive nominations from consumer electronics spot purchasing and industrial-grade residual supply. Price differentiation hinges on EU Battery Regulation carbon footprint certification tier and cathode active material purity grade. Cost compression in standard-tier consumer electronics cells is intensifying because Chinese cylindrical-to-pouch conversion programs flood mid-range capacity markets. Automotive OEMs exhibit lowest price sensitivity due to range-performance specifications, while smartphone OEMs negotiate most aggressively on per-unit basis.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Busan, and Shanghai anchor hub-and-spoke patterns for cathode active material and separator film flows. Manufacturing concentrates in China, South Korea, and Poland, with electrode coating and cell assembly feeding from Yangtze River Delta and Gwangju-Ulsan clusters. Raw material dependencies center on metallurgical-grade silicon from Norwegian smelters, lithium hydroxide from Australian spodumene conversion, and cobalt hydroxide from DRC-integrated trading houses. Single-source vulnerability at LG Energy Solution's Polish gigafactory creates EU automotive qualification bottlenecks. Distribution runs through direct OEM platform nominations that displace independent battery trading channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where automotive OEMs now prioritize 300+ Wh/kg energy density specifications over cycle-life metrics, rewarding silicon-anode R&D pipelines with premium platform nominations.
For Market Incumbents: Deploy silicon-anode pilot-line scaling to preempt European luxury EV platform procurement windows. Korean conglomerates must secure metallurgical-grade silicon offtake agreements before Chinese competitors consolidate precursor supply. Solid-state electrolyte R&D pipelines represent the critical defensive moat against lithium-metal substitute technologies. Capacity addition in Poland or alternative EU manufacturing nodes reduces single-source regulatory vulnerability under EU Battery Regulation compliance timelines. For New Entrants and Emerging Players: Capture Indian PLI scheme localization incentives for two-wheeler electrification cell supply, where tariff-advantaged manufacturing offsets Korean and Chinese incumbent scale. Wearable medical device flexible pouch formats offer the most penetrable white-space target, with FDA device-level battery safety guidance creating certification barriers that favor specialized entrants over diversified conglomerates. Go-to-market angle centers on conformal geometry engineering partnerships with continuous glucose monitor and cardiac rhythm management device OEMs. For Investors and Strategic Acquirers: Automotive OEMs are the most active acquirer in this space, pursuing backward integration into cell manufacturing through joint ventures with Korean technology partners. Long-term viability over the next decade hinges on recycled content threshold compliance and carbon footprint declaration capabilities under tightening EU regulatory frameworks. Acquisition target archetype: materials-tier suppliers with aluminum-laminate film enclosure technology and certified secondary material stream access. Signal to watch: SAMR compulsory certification timeline extensions that strain Chinese domestic OEM product launch windows and redirect procurement toward qualified import sources.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon-Anode Pilot-Line Scaling | Korean manufacturers anchor metallurgical-grade silicon offtake to secure European luxury EV nominations. |
| EU Battery Regulation Compliance Investment | Carbon footprint declaration systems and recycled content thresholds reshape Polish and Korean gigafactory qualification protocols. |
| Indian PLI Scheme Localization | Korean and Chinese joint ventures target tariff-advantaged supply to domestic two-wheeler electrification demand. |
| Solid-State Electrolyte R&D Partnership | Oxide and sulfide ceramic separator technologies open hybrid architectures eliminating thermal runaway risks. |
| Direct OEM Platform Nomination | Volkswagen, BMW, and Hyundai Motor Group procurement teams displace independent battery trading houses from automotive channels. |
Research Methodology
Coverage spans China, South Korea, Germany, the United States, and Poland, with primary inputs from each market's battery cluster and regulatory environment. Primary interviews engaged cell manufacturing executives, automotive OEM platform engineers, cathode material procurement leads, and recycling facility operators. Secondary validation drew from SAMR GB standards documentation, EU Battery Regulation implementation guidance, EPA hazardous waste rule filings, and Korean METI industrial policy disclosures. Bottom-up cell capacity and nomination tracking triangulated against top-down automotive production forecasts.
Granularity-level modeling deployed product-type splits across high energy, ultra-thin, standard, and flexible pouch configurations, with end-use segmentation distinguishing automotive platform nominations from consumer electronics spot purchasing. Charging technology and capacity tiers were modeled at the cell-format level. CAGRs were derived from production capacity buildout timelines and OEM nomination schedules. Industry-specific forecast inputs included silicon-anode pilot-line investment trajectories and EU Battery Regulation recycled content mandate phase-in curves.
Raw material price volatility, regulatory certification timeline shifts, and substitute technology breakthrough velocity are the dominant revision risks across the projection horizon. Forecasts reflect documented assumptions regarding cathode chemistry transition rates and automotive platform consolidation patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
US Motive Lead Acid Battery Market
Batteries
Nuclear Battery Sales Market
Batteries
Battery Simulator Market
Batteries
North America Lead Acid Battery Market
Batteries
Power Battery Sealant Market
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
Secondary Battery Market
Batteries
Forklift Battery Market
Batteries
Vanadium Redox Batteries Market
Batteries
Vanadium Redox Flow Batteries (VRFB) Market
Batteries
East Africa Battery Market
Batteries
Nas Battery Market
Batteries
North America Lead-Acid Battery Separator for SLI Applications Market
Batteries
Industrial Battery Charger Market
Batteries
Rear Rack Battery Market
Batteries
High Voltage Air-cooled Battery Compartment Market