
 Automated Power Generation Dispatch Software Market | 2026-2036
Automated Power Generation Dispatch Software Market Size, Share, and Industry Trends Forecast 2026-2036
Automated Power Generation Dispatch Software Market Analytics
Buyer concentration among vertically integrated utilities is hardening across North America and Western Europe, pushing independent software vendors toward deeper enterprise partnerships. Siemens AG leverages its hardware-software bundling strength to anchor long-term dispatch modernization contracts. General Electric Company competes through its digital twin integration for gas turbine fleets. ABB Ltd. specializes in substation automation tie-ins that extend its SCADA footprint into generation control rooms.
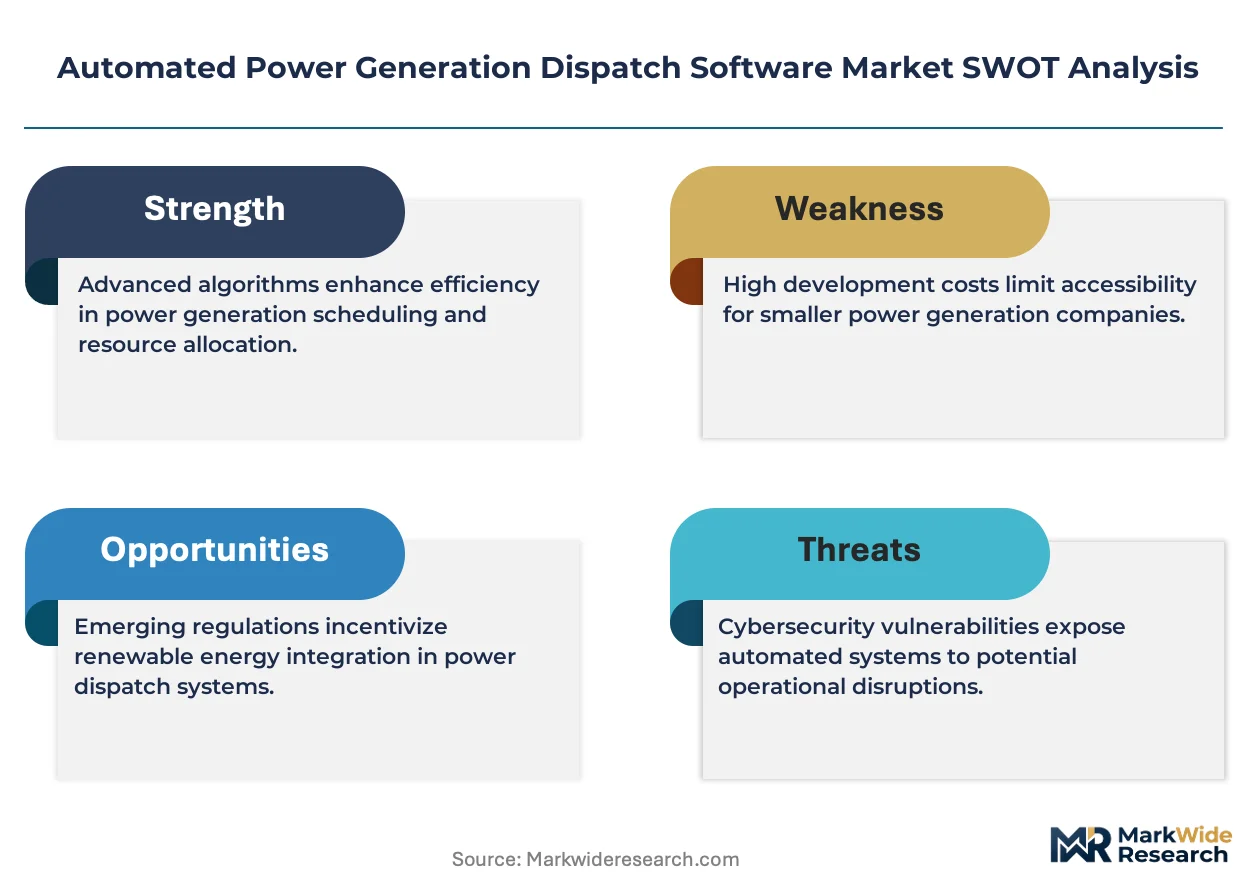
Automated power generation dispatch software coordinates real-time command of electricity sources through economic dispatch algorithms, unit commitment solvers, and frequency regulation protocols that balance supply against fluctuating demand within seconds. The software's primary commercial purpose is minimizing marginal generation cost while maintaining grid stability and reserve margins. Load dispatch platforms dominate current revenue as legacy control centers upgrade from manual protocols, while forecasting tools embedded with machine learning represent the fastest-expanding margin pool as variable renewable penetration rises. Cloud-based deployment architectures are displacing on-premise installations among mid-sized independent power producers seeking operational expenditure flexibility without sacrificing cybersecurity posture.
FERC in the United States mandates wholesale market participation standards for distributed resources, while the EU Green Deal and F-Gas Regulation shape carbon-accounting requirements that dispatch software must embed for compliance. Grid codes issued by national regulators in Germany, the United Kingdom, and Australia now specify sub-second response thresholds that algorithmic dispatch must satisfy. Stakeholders should monitor whether emerging interoperability standards fragment procurement or consolidate vendor ecosystems.
Market Dynamics
Utility procurement is hardening around integrated platform vendors as transmission system operators modernize dispatch centers to manage rising renewable penetration and sub-second response requirements.
Growth Catalysts
- FERC Order 2222:Mandates wholesale market participation standards for distributed energy resources in the United States, forcing utilities to upgrade dispatch software for real-time aggregation capabilities.
- Machine learning forecasting:Embedded predictive algorithms enable operators to anticipate renewable intermittency, reducing curtailment costs and improving reserve margin planning.
- German TSO modernization:Transmission system operators are replacing legacy control centers with automated platforms to manage the country's accelerating wind and solar penetration.
Market Restraints
- SCADA integration costs:Retrofitting existing substation automation infrastructure requires substantial capital outlay, particularly for municipal utilities with constrained IT budgets.
- Cybersecurity certification delays:Grid code compliance timelines in Germany, the United Kingdom, and Australia extend procurement cycles by 12-18 months as vendors await security clearance protocols.
- Specialized talent scarcity:Shortage of power systems engineers with dual expertise in optimization algorithms and grid operations limits deployment velocity for complex implementations.
Strategic Opportunities
- Cloud-native architectures:Mid-sized independent power producers in Texas and California are adopting software-as-a-service dispatch platforms to convert capital expenditure into operational expenditure.
- EU Green Deal carbon accounting:Compliance mandates create embedded software requirements for real-time emissions tracking during economic dispatch decisions.
- Digital twin convergence:Integration of physics-based turbine modeling with dispatch algorithms enables predictive maintenance scheduling that reduces unplanned outage penalties.
Industry Challenges
- Legacy protocol incompatibility:Proprietary communication standards in existing control rooms force costly middleware development for new software deployments.
- Sub-second algorithmic latency:Frequency regulation protocols demand computational response times that strain conventional optimization solver architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automated Power Generation Dispatch Software Market |
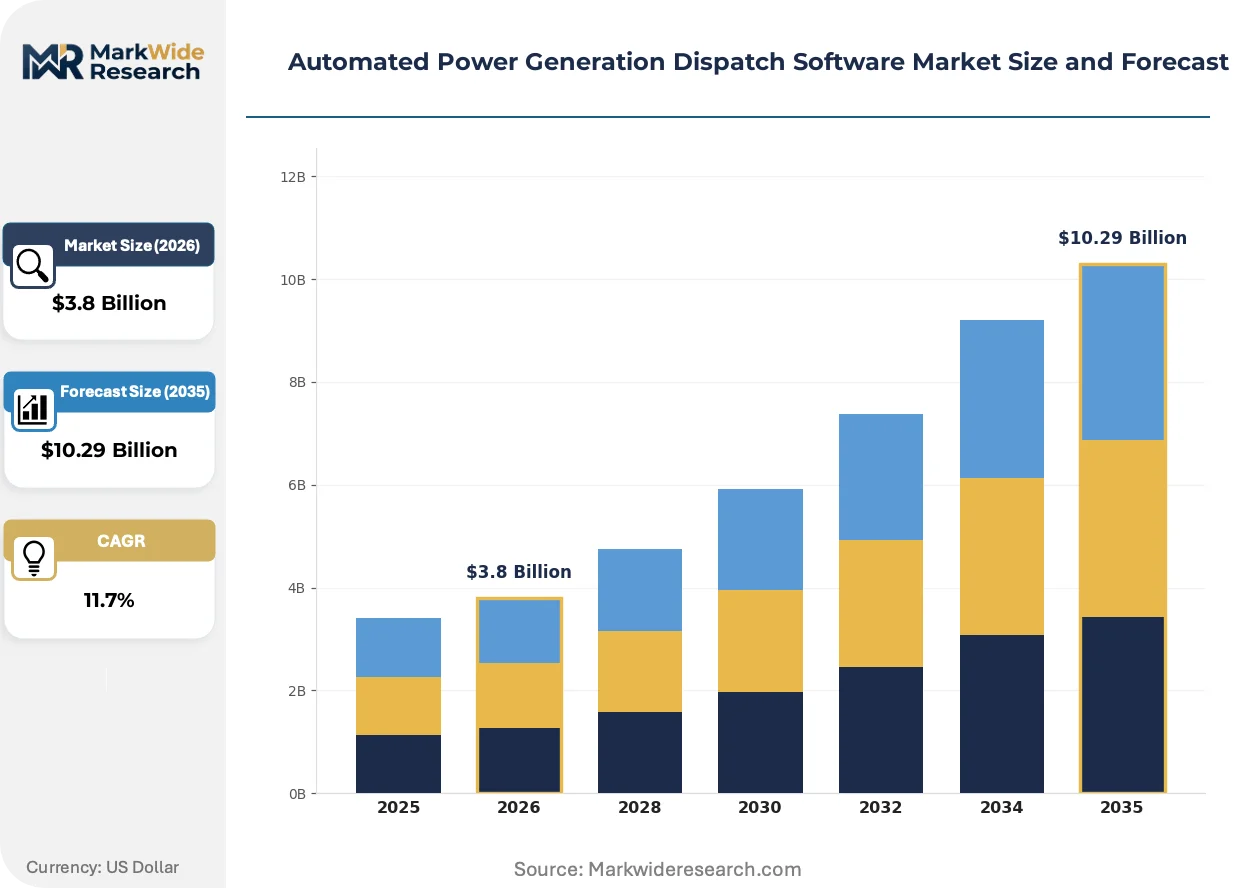
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Load Dispatch, Generation Scheduling, Forecasting Tools, Monitoring Solutions Technology: Artificial Intelligence, Machine Learning, Cloud Computing, Data Analytics End User: Utilities, Independent Power Producers, Renewable Energy Providers, Industrial Users Deployment: On-Premise, Cloud-Based, Hybrid Solutions, Others |
| Companies Covered | ABB Ltd., Siemens AG, Schneider Electric SE, General Electric Company, Emerson Electric Co., Mitsubishi Electric Corporation, Honeywell International Inc., Rockwell Automation, Inc., NR Electric Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automated Power Generation Dispatch Software Market Evolving Landscape
Algorithmic dispatch is absorbing machine learning forecasting, cloud deployment architectures, and carbon-accounting modules as core platform requirements rather than peripheral add-ons.
Machine learning forecasting is absorbing variable renewable uncertainty into day-ahead and real-time dispatch decisions. Independent system operators in California and Texas are deploying neural network models trained on satellite imagery and weather radar to predict solar and wind output with 15-minute granularity. This capability is absorbing the margin compression that renewable intermittency previously imposed on conventional thermal generators.
EU Green Deal carbon-accounting mandates are embedding emissions tracking directly into economic dispatch algorithms. The F-Gas Regulation and national grid codes now require real-time carbon intensity calculations for every generation unit commitment decision. German transmission system operators are retrofitting dispatch platforms to automatically prioritize lower-emission resources during congestion events.
Utility procurement patterns are favoring integrated hardware-software bundles over standalone software licenses. Vertically integrated vendors with captive SCADA and substation automation portfolios are capturing multi-year modernization contracts that independent software vendors cannot match. This concentration is most visible in North America, where regional transmission organizations are consolidating vendor relationships to reduce integration risk.
Automated Power Generation Dispatch Software Market Segmentation
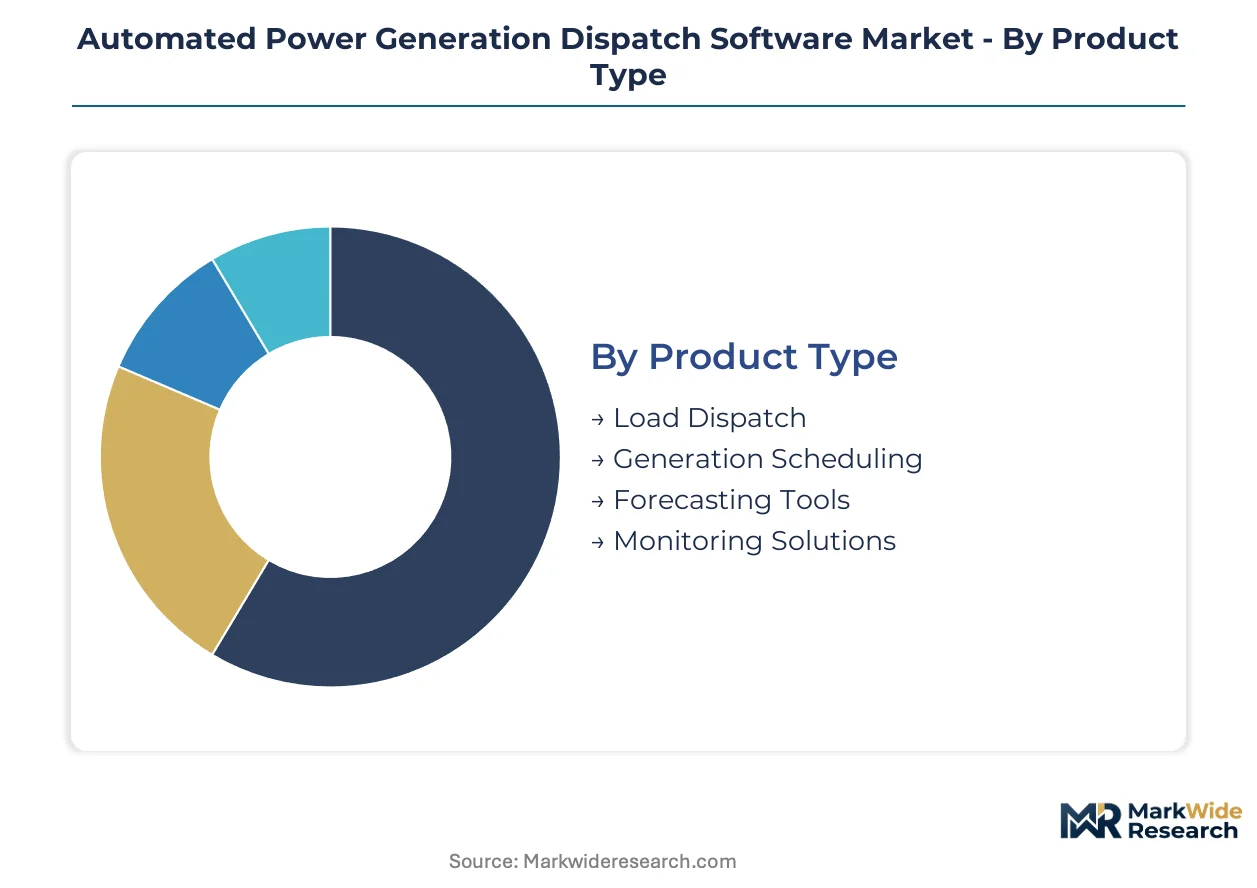
Dispatch software procurement varies sharply by operational scale and regulatory exposure. Capital intensity, integration complexity, and compliance requirements fragment purchasing patterns across buyer categories.
Product Type:
Load dispatch platforms demand the heaviest upfront investment due to control center retrofitting and SCADA integration requirements.
- Load Dispatch:Real-time command systems coordinate unit commitment and economic dispatch across generation fleets. German transmission system operators are modernizing legacy control centers to manage renewable penetration, driving concentrated procurement.
- Forecasting Tools:Predictive algorithms ingest weather data and demand signals to anticipate renewable intermittency. California and Texas independent system operators deploy neural networks trained on satellite imagery, reducing curtailment costs.
- Generation Scheduling:Day-ahead and intraday planning modules optimize maintenance windows and fuel procurement.
- Monitoring Solutions:Telemetry dashboards track unit performance and grid frequency deviations.
Most installed capacity flows through Load Dispatch. Expansion is steepest in Forecasting Tools.
Technology:
Artificial Intelligence applications command premium licensing fees and specialized implementation talent.
- Machine Learning:Neural network architectures predict renewable output with 15-minute granularity. Embedded forecasting algorithms represent the fastest-expanding margin pool as variable penetration rises.
- Cloud Computing:SaaS architectures convert capital expenditure to operational expenditure. Mid-sized independent power producers in Texas and California favor subscription models.
- Artificial Intelligence:Autonomous dispatch agents optimize multi-objective functions including cost, emissions, and reliability.
- Data Analytics:Descriptive and diagnostic tools process historical dispatch records for performance benchmarking.
Machine Learning claims the largest share of new vendor R&D. Cloud Computing is climbing the fastest among mid-market buyers.
End User:
Utilities carry the steepest compliance burden and longest procurement cycles due to regulatory certification requirements.
- Utilities:Vertically integrated transmission system operators and distribution utilities mandate sub-second response thresholds. FERC Order 2222 compels wholesale market participation upgrades.
- Independent Power Producers:Merchant generators prioritize dispatch optimization for energy and ancillary service revenues. Operational expenditure flexibility drives cloud adoption.
- Renewable Energy Providers:Wind and solar asset operators require forecasting integration to minimize imbalance penalties.
- Industrial Users:Cogeneration and behind-the-meter facilities seek automated demand response participation.
Utilities dominate current procurement volume. Renewable Energy Providers are expanding most quickly as aggregation mandates spread.
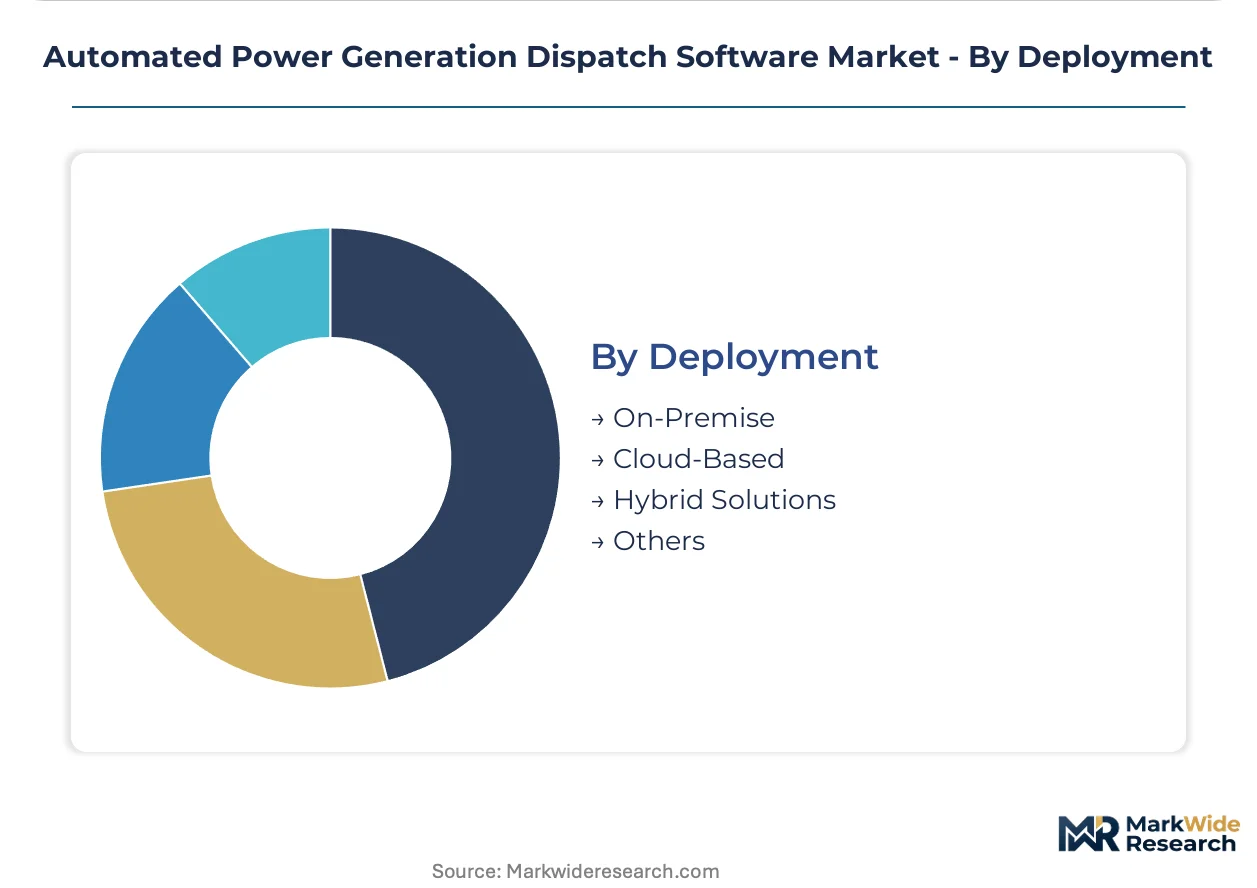
Deployment:
On-premise installations require substantial infrastructure capital and dedicated cybersecurity staffing.
- On-Premise:Air-gapped control systems satisfy critical infrastructure protection mandates. Municipal utilities with constrained IT budgets face extended retrofit timelines.
- Cloud-Based:Managed service models reduce internal systems engineering headcount. Cybersecurity certification delays in Germany and Australia extend procurement cycles.
- Hybrid Solutions:Split architectures isolate real-time control functions while outsourcing analytics workloads.
- Others:Edge computing deployments and containerized microservices for distributed resource aggregation.
On-Premise retains the largest installed base. Cloud-Based deployment is gaining share fastest among independent power producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's transmission system operators are modernizing dispatch centers faster than utilities in France, reflecting sharper renewable penetration pressures and stricter grid code enforcement timelines.
United States
FERC Order 2222 mandates wholesale market participation standards for distributed energy resources, compelling regional transmission organizations to upgrade dispatch software for real-time aggregation. The Inflation Reduction Act accelerates renewable deployment timelines that strain legacy control systems. Texas and California independent system operators in Austin and Sacramento are deploying neural network forecasting to manage solar and wind intermittency.
Germany
Transmission system operators face sub-second response thresholds under national grid codes designed for accelerating wind and solar penetration. The EU Green Deal and F-Gas Regulation embed carbon-accounting requirements directly into economic dispatch algorithms. Dispatch center modernization concentrates in Frankfurt and Hamburg, where operators retrofit platforms to prioritize lower-emission resources during congestion events.
China
Dual carbon goals and provincial renewable integration targets drive state grid corporations toward automated dispatch platforms. MIIT standards shape cybersecurity and data localization requirements for critical infrastructure software. Deployment activity clusters in the Yangtze River Delta and Pearl River Delta, where provincial grid operators manage the world's largest renewable generation fleets.
United Kingdom
Grid codes specify algorithmic latency requirements for frequency regulation that strain conventional optimization architectures. National regulatory frameworks align with EU-derived carbon-accounting mandates despite post-Brexit divergence. London and Edinburgh host transmission system operator control centers where cybersecurity certification delays extend procurement cycles.
Australia
National electricity market rules mandate distributed energy resource aggregation capabilities similar to FERC Order 2222 frameworks. AEMO grid codes enforce sub-second response thresholds for frequency control ancillary services. Dispatch software procurement concentrates in Melbourne and Sydney, where transmission network service providers modernize control rooms for renewable-rich grid zones.
Automated Power Generation Dispatch Software Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across procurement channels, creating a tiered structure where bundled hardware-software offerings command multi-year contracts. Vertically integrated industrial technology groups anchor utility relationships through captive SCADA and substation automation portfolios. Independent software vendors concentrate on cloud-native forecasting modules for mid-sized independent power producers. Dominant competitive moves include strategic partnerships with transmission system operators and portfolio diversification into carbon-accounting compliance modules.
Within the diversified industrial technology tier, Siemens AG and ABB Ltd. represent archetypal bundling strategies that extend hardware footprints into generation control rooms. General Electric Company exemplifies digital twin convergence approaches that integrate physics-based turbine modeling with dispatch algorithms. These three anchors occupy positions where long-term modernization contracts consolidate procurement around integrated platform vendors rather than standalone software licenses.
| Leading Market Players |
|---|
| ABB Ltd. |
| Siemens AG |
| Schneider Electric SE |
| General Electric Company |
| Emerson Electric Co. |
| Mitsubishi Electric Corporation |
| Honeywell International Inc. |
| Rockwell Automation, Inc. |
| NR Electric Co., Ltd |
| Others |
Value Network & Pricing Analysis
Cloud-native deployment architectures are compressing implementation timelines while simultaneously redistributing pricing power toward platform vendors with captive infrastructure stacks. This technology shift forces mid-sized independent power producers to accept subscription-based operational expenditure models that erode traditional perpetual-license margins.
Pricing Analysis
Capacity additions in Texas and California are reshaping price floors for forecasting modules as independent system operators expand neural network deployments. Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation resting on cybersecurity certification grade and SCADA integration depth. Cost compression in mid-market SaaS tiers is intensifying because municipal utilities with constrained IT budgets delay on-premise retrofits. Independent power producers exhibit highest price sensitivity; transmission system operators show least.
Supply Chain Analysis
Dual-sourcing requirements embedded in German and Australian grid codes mandate multi-vendor cybersecurity qualification for critical dispatch infrastructure. Hardware-software bundling concentrates supply relationships in Germany, the United States, and China where vertically integrated industrial technology groups anchor procurement. Raw material dependencies span silicon for edge computing hardware, specialized fiber for control center networking, and rare earth elements for power electronics. Single-source vulnerability around machine learning optimization talent strains deployment velocity. Distribution runs through direct enterprise sales teams for utilities, channel partners for mid-market independent power producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FERC Order 2222 functions as a regulatory compounder, mandating wholesale market participation standards that force sustained dispatch software investment regardless of wholesale price volatility.
For Market Incumbents: Lock in multi-year modernization contracts with transmission system operators by bundling SCADA hardware, substation automation, and carbon-accounting modules. Deepen enterprise partnerships to neutralize cloud-native challengers targeting mid-market independent power producers with subscription economics. Prioritize certification investment in German and Australian cybersecurity protocols to extend procurement cycle advantages.
For New Entrants and Emerging Players: Cloud-native SaaS platforms offer the most penetrable route into Texas and California independent power producer segments where operational expenditure flexibility outweighs integration depth requirements. Target forecasting tool specialization with 15-minute granularity machine learning as the wedge application. Pursue channel partnerships with regional system integrators rather than direct utility sales.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play forecasting specialists lacking captive SCADA footprints. Long-term viability centers on algorithmic latency capabilities for sub-second frequency regulation compliance. Watch for inflection in German TSO procurement acceleration as the demand signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Combines economic dispatch algorithms with SCADA and digital twin modules to anchor utility contracts. |
| Carbon-Accounting Module Development | Embeds EU Green Deal compliance directly into dispatch decisions for German transmission system operators. |
| Cloud-Native Architecture Deployment | Converts capital expenditure to operational expenditure for Texas and California independent power producers. |
| Machine Learning Forecasting Acquisition | Absorbs neural network talent to reduce renewable curtailment costs for California independent system operators. |
| Cybersecurity Certification Investment | Accelerates German and Australian grid code compliance timelines to capture modernization procurement. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, independent power producer project developers, grid operators, and EPC contractors with secondary validation against FERC filings, EIA data, IEA reports, and project development databases. Bottom-up segmentation modeling and top-down market sizing triangulated volume estimates across deployment modes, generation capacity tiers, and regional regulatory frameworks.
Historical reference periods anchored the projection horizon to observable procurement cycles in German transmission system operator modernization and FERC Order 2222 implementation timelines. Segmentation dimensions modeled include product type, technology architecture, end-user category, and deployment mode across the analysis window. CAGRs derived from algorithmic intensity projections and renewable penetration curves. Forecast inputs incorporate machine learning adoption rates and carbon-accounting mandate enforcement schedules.
Cybersecurity certification delays, renewable intermittency forecasting accuracy, and distributed resource aggregation complexity are the dominant revision risks. Forecasts reflect assumptions about regulatory enforcement timelines and technology substitution rates. Deviation in German grid code implementation pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
India Big Data Analytics in Energy Market
Energy Analytics and Software
Canada Big Data Analytics in Energy Market
Energy Analytics and Software
Predictive Maintenance in the Energy Market
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data Analytics in Power Sector Market
Energy Analytics and Software
Netherlands Big Data Analytics in Energy Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Energy As a Service (Eaas) Market
Energy Analytics and Software
Italy Big Data Analytics in Energy Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Japan Big Data Analytics in Energy Market