
 Direct Current Power System Market | 2026-2036
Direct Current Power System Market Size, Share, and Industry Trends Forecast 2026-2036
Direct Current Power System Market Analysis
Market Context
The EU Green Deal is pivoting European data center operators toward native DC power architectures to eliminate conversion losses from AC-DC-AC chains. ABB Ltd. leverages its HVDC portfolio to anchor utility-scale interconnection projects across Scandinavia. Huawei Technologies Co. Ltd. dominates 380V DC rack-level deployments through integrated power module designs. Delta Electronics Inc. specializes in telecom rectifier systems that sustain margins in emerging Asia-Pacific edge computing builds.
Technical Definition and Segment Structure
A direct current power system comprises generation, conversion, storage, and distribution equipment operating at fixed polarity without zero-crossing intervals, typically at 48V, 240V, or 380V nominal for commercial and industrial loads. Voltage-source converter technology leads installed base volumes due to mature IGBT and silicon carbide switching topologies, while modular multilevel architectures capture the fastest growth in offshore renewable interconnection where HVDC submarine cables require precise waveform synthesis. End-user demand concentrates in data centers, where 380V DC bus distribution eliminates double conversion and captures margin pools in hyperscale buildouts exceeding 100MW per campus.
Regulatory Framework
The EU F-Gas Regulation and Ecodesign Directive constrain traditional AC-dependent cooling and power architectures, indirectly accelerating DC-native system certification. In the United States, OSHA electrical safety standards and IEEE 3006.7 DC power guidelines shape product qualification and installation liability. China's GB standards for DC distribution in buildings, administered by SAMR, create market access thresholds for imported conversion equipment. Stakeholders must monitor evolving interoperability standards between regional DC voltage classes before committing to platform-level R&D roadmaps.
Market Dynamics
The elimination of AC-DC conversion losses through native 380V DC bus architectures is restructuring capital allocation across hyperscale data center buildouts, compressing total cost of ownership and redirecting procurement specifications toward integrated power module designs.
Growth Catalysts
- EU Green Deal energy efficiency mandates:Binding carbon reduction targets force facility operators to abandon legacy AC distribution chains and certify native DC infrastructure across new hyperscale campuses.
- Silicon carbide switching topologies:Wide-bandgap semiconductor deployment in voltage-source converters cuts thermal losses and enables higher power density in rack-level power modules.
- Northern Virginia data center cluster:Concentrated corporate net-zero commitments from cloud providers accelerate 380V DC adoption in the world's largest hyperscale corridor.
Market Restraints
- Copper price volatility:Raw material cost swings in conductor cabling compress margins for DC busbar manufacturers serving price-locked utility contracts.
- IGBT supply concentration:Discrete power semiconductor fabrication concentrates in East Asian foundries, exposing converter OEMs to single-source disruption risk.
- OSHA electrical safety compliance:Arc flash protection requirements for DC systems above 300V impose installation cost premiums and qualified technician scarcity.
Strategic Opportunities
- Edge computing in Southeast Asia:Telecom rectifier demand from 5G micro-datacenter rollouts in Indonesia and Vietnam outpaces legacy AC infrastructure refresh cycles.
- GB standards for DC buildings:China's SAMR certification pathway creates first-mover advantage for integrated power module suppliers meeting 240V residential and commercial distribution thresholds.
- Modular multilevel converter convergence:HVDC submarine cable interconnection with offshore wind synthesis opens utility-scale procurement channels beyond data center verticals.
Industry Challenges
- Power electronics engineering scarcity:Specialized magnetics design and thermal management expertise for 380V DC systems commands salary premiums that strain mid-tier OEM hiring.
- IEEE 3006.7 interoperability gaps:Incomplete voltage class harmonization between 240V and 380V DC standards forces platform-level R&D hedging and delays product certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Direct Current Power System Market |
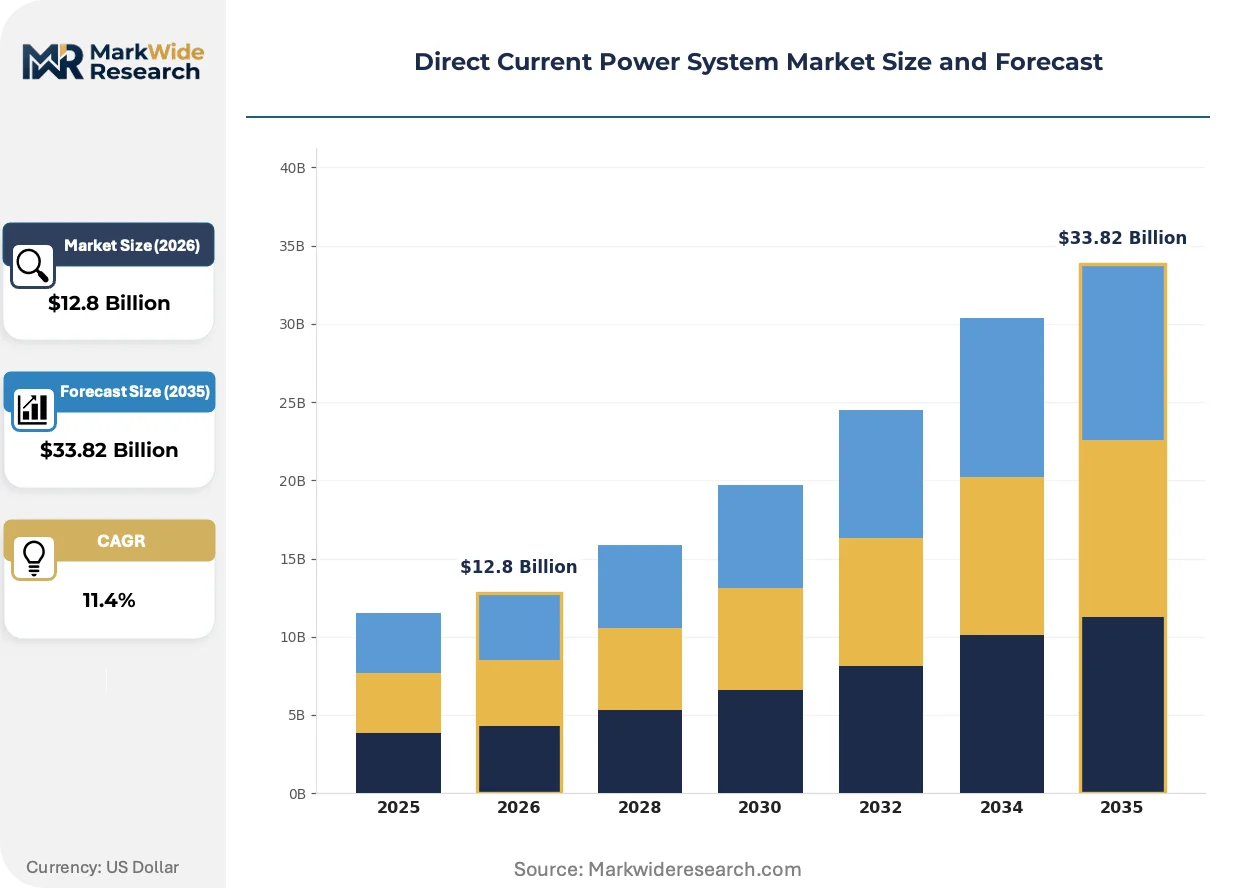
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $33.82 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Converters, Controllers, Inverters, Switchgears Technology: Current-Source, Voltage-Source, Modular Multilevel, Hybrid End User: Telecommunications, Data Centers, Renewable Energy, Industrial Applications Installation: Onshore, Offshore, Indoor, Outdoor |
| Companies Covered | ABB Ltd., Eaton Corp., Huawei Technologies Co. Ltd., Advanced Energy Industries Inc., EnerSys, Delta Electronics Inc., Vertiv Group Corp., Heinzinger electronic GmbH, AEG Power Solutions BV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Direct Current Power System Market Emerging Trajectories
Silicon carbide semiconductor deployment and regulatory pressure on conversion efficiency are compressing technology refresh cycles and forcing architectural bets on unified power distribution platforms.
Integrated rack-level power modules with embedded silicon carbide MOSFETs are unifying rectification, distribution, and battery backup functions into single enclosure designs. Hyperscale operators in Singapore and Frankfurt specify these units for new 100MW-plus campuses. The technology is unifying what were three separate procurement categories—rectifiers, PDUs, and UPS—into single-vendor contracts that compress supplier margins and lock out component specialists.
REACH substance restrictions and the EU F-Gas Regulation are phasing out sulfur hexafluoride insulation in switchgear and high-GWP refrigerants in thermal management. DC-native architectures eliminate the transformer and switchgear count that traditionally relied on SF6-insulated equipment. European data center developers now specify gas-free solid insulation and natural convection cooling to preempt compliance-driven obsolescence.
Long-term power purchase agreements with renewable developers are displacing traditional utility tariff structures for hyperscale operators. Buyers in Northern Virginia and Singapore negotiate 15-20 year contracts that specify DC-coupled solar and storage, bypassing utility AC interconnection queues. This contractual shift forces EPC firms to engineer DC collection buses and battery inverters as standard project components rather than custom add-ons.
Direct Current Power System Market Segmentation
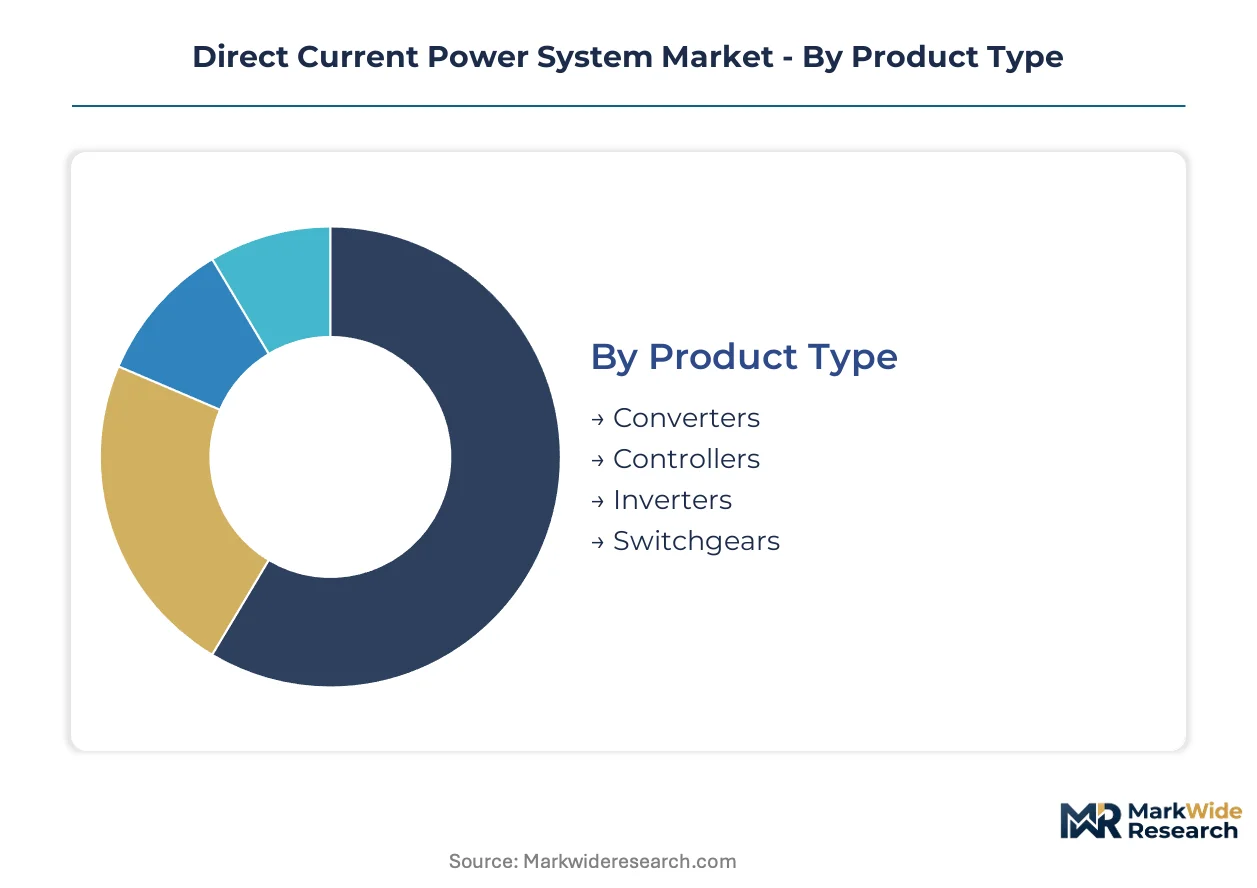
DC power system procurement patterns diverge sharply between mature utility-scale installations and emerging edge computing deployments. Understanding these segment boundaries clarifies where silicon carbide switching investments concentrate versus where legacy IGBT architectures retain cost advantages.
Product Type:
Converters dominate unit volumes while controllers capture the highest gross margins per kilowatt installed.
- Converters:Voltage-source and current-source architectures transform AC grid supply or renewable generation into stable DC bus outputs at 48V, 240V, or 380V nominal. Hyperscale data center operators in Northern Virginia and Singapore specify integrated converter-battery modules that eliminate separate UPS procurement.
- Controllers:Power management units with embedded DSPs govern voltage regulation, load balancing, and fault isolation across distributed DC microgrids. These systems command premium pricing in industrial process control where uptime guarantees exceed 99.999%.
- Inverters:DC-to-AC conversion equipment for grid-tie applications and backup power scenarios.
- Switchgears:Circuit protection and isolation hardware including DC-rated breakers, fuses, and disconnect switches.
Today's leader: Converters. Tomorrow's challenger: Controllers.
Technology:
Voltage-source designs anchor the installed base through mature supply chains, while modular multilevel architectures unlock offshore wind interconnection contracts.
- Voltage-Source:IGBT and silicon carbide MOSFET-based topologies enable precise pulse-width modulation for DC bus regulation. These systems saturate data center and telecom rectifier markets where 380V and 48V standards predominate.
- Modular Multilevel:Stacked subconverter cells synthesize near-sinusoidal waveforms without heavy filtering, enabling HVDC submarine cables exceeding 500kV transmission. Offshore wind developers in the North Sea and Baltic Sea specify these for grid interconnection projects.
- Current-Source:Thyristor-based rectification for high-current industrial drives and electrochemical processing.
- Hybrid:Combined voltage-source and current-source stages for specialized traction and marine propulsion applications.
Voltage-source technology holds the revenue base. Modular multilevel designs are climbing the fastest.
End User:
Data center procurement now exceeds telecom in average project value per megawatt, reversing a decade-long hierarchy.
- Data Centers:Hyperscale facilities exceeding 100MW per campus drive 380V DC bus adoption to eliminate double-conversion losses. Corporate net-zero commitments from cloud providers in Northern Virginia, Frankfurt, and Singapore accelerate native DC architecture certification.
- Telecommunications:5G micro-datacenter and edge node deployments sustain demand for 48V rectifier systems across Southeast Asian markets. Indonesia and Vietnam lead volume growth for outdoor-rated rectifier cabinets.
- Renewable Energy:Solar and battery storage integration requiring DC collection buses and grid-forming inverters.
- Industrial Applications:Manufacturing process power, electric arc furnaces, and electrochemical plants.
Data centers anchor current procurement value. Telecom edge infrastructure is expanding most quickly in unit terms.
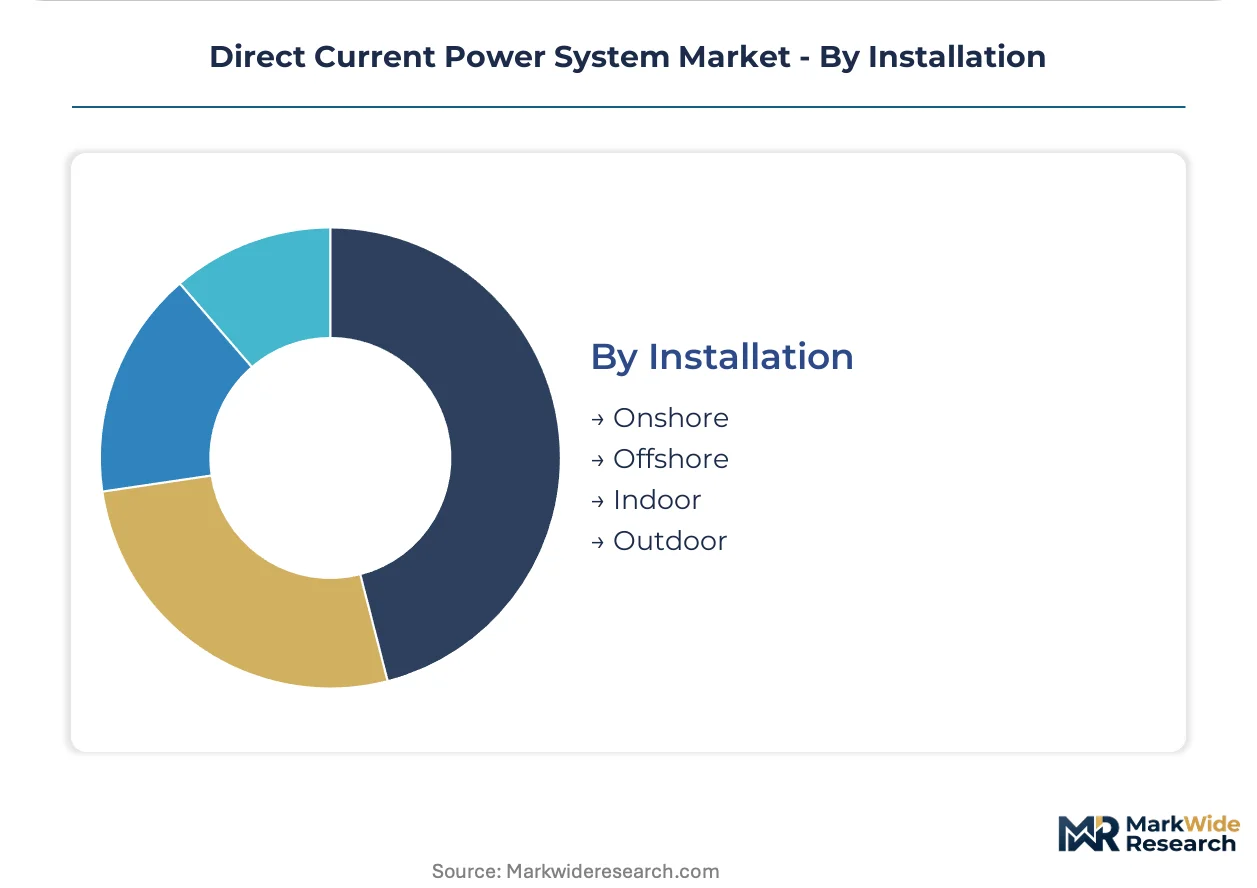
Installation:
Onshore deployment absorbs manufacturing scale advantages, while offshore specifications command engineering premiums for corrosion and vibration resistance.
- Onshore:Ground-mounted converter stations and indoor switchgear rooms constitute the standard delivery model. Utility-scale solar plus storage projects in the United States and China specify containerized onshore DC skids with 20-year operational life.
- Indoor:Climate-controlled environments for sensitive power electronics in data centers and clean manufacturing.
- Offshore:Platform-mounted HVDC converter stations and subsea cable terminations.
- Outdoor:Weather-hardened enclosures for telecom, distribution automation, and remote renewable sites.
Onshore installations dominate capital deployment. Offshore projects are gaining share fastest in HVDC interconnection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DC power systems trace their commercial scale to early 20th-century urban electrification in the United States, where Thomas Edison's Pearl Street Station established the first centralized DC distribution network in Manhattan. This historical lineage anchored American technical leadership before European and Asian markets developed specialized applications for industrial and telecommunications infrastructure.
United States
Hyperscale data center construction in Northern Virginia and Dallas-Fort Worth drives 380V DC procurement for cloud computing campuses. OSHA electrical safety standards and IEEE 3006.7 guidelines shape installation protocols for high-voltage DC bus architectures. Corporate net-zero commitments from cloud providers in Loudoun County accelerate native DC infrastructure certification.
Germany
Industrial automation and automotive electrification sustain demand for precision DC power supplies in manufacturing corridors. The EU Green Deal and Ecodesign Directive mandate energy efficiency thresholds that disadvantage legacy AC conversion chains. Frankfurt's data center cluster leads continental adoption of 380V DC distribution for financial services infrastructure.
China
Massive renewable energy integration and electric vehicle charging networks expand DC distribution requirements across coastal provinces. SAMR-administered GB standards for DC building distribution create certification pathways for domestic and imported conversion equipment. The Yangtze River Delta manufacturing belt concentrates production of silicon carbide power modules for voltage-source converters.
Singapore
Tropical data center operators deploy DC-native architectures to minimize cooling loads from conversion losses in dense urban facilities. The country's national sustainability mandates align with corporate decarbonization timelines from multinational cloud tenants. The Tuas industrial zone hosts experimental 380V DC microgrid deployments for next-generation hyperscale facilities.
India
Telecommunications infrastructure expansion and rural electrification programs sustain 48V rectifier demand across distributed edge networks. The CEA's grid integration standards accommodate DC-coupled solar and storage for industrial microgrids. Karnataka's electronics manufacturing cluster attracts assembly investments for power conversion equipment serving domestic and export markets.
Direct Current Power System Market Vendor Landscape
Premium-margin players sit above commodity-margin players across technology sophistication and application criticality, with integrated power module specialists commanding pricing power in hyperscale data center contracts while rectifier assemblers compete on cost in telecom edge deployments. The vendor base stratifies into three tiers: multinational conglomerates with HVDC and industrial automation portfolios, specialized power electronics firms focused on voltage-source converters, and regional fabricators serving price-sensitive emerging markets. Two dominant competitive moves are reshaping positioning: backward integration into silicon carbide semiconductor sourcing and strategic partnerships with hyperscale data center developers for multi-year supply agreements.
Within the multinational tier, ABB Ltd., Eaton Corp., and Huawei Technologies Co. Ltd. occupy positions that exemplify divergent geographic and technological specializations. ABB's Swiss-Scandinavian heritage anchors its utility-scale HVDC interconnection presence, while Eaton's American incorporation reflects industrial and electrical distribution channel dominance. Huawei's Shenzhen-based structure positions it within integrated power module supply chains for Asian hyperscale deployments. These three entities represent the archetype spectrum from heavy infrastructure project execution to rack-level integrated system design.
| Leading Market Players |
|---|
| ABB Ltd. |
| Eaton Corp. |
| Huawei Technologies Co. Ltd. |
| Advanced Energy Industries Inc. |
| EnerSys |
| Delta Electronics Inc. |
| Vertiv Group Corp. |
| Heinzinger electronic GmbH |
| AEG Power Solutions BV |
| Others |
Supply Flow & Price Mechanics
Performance-tier bifurcation between silicon carbide-enabled integrated modules and legacy IGBT-based rectifiers creates parallel pricing universes that feed distinct supply chain configurations. Premium-tier suppliers in Germany and Switzerland command pricing power through captive semiconductor sourcing, while commodity assemblers in coastal China compete on scale economies for standardized 48V telecom units.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates hyperscale data center contracts from industrial procurement and emerging market telecom deployments. Price differentiation hinges on silicon carbide content and UL/IEC safety certification grade. Cost compression in standard-tier voltage-source converters is intensifying because raw copper busbar expenses outpace contract escalation clauses. Telecom operators in Southeast Asia exhibit highest price sensitivity, while Northern Virginia hyperscale developers prioritize efficiency guarantees over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for integrated power modules, while distributor networks serve fragmented industrial and telecom accounts. Manufacturing gravity centers on China, Germany, and Switzerland for precision magnetics and power semiconductor packaging. Raw material dependencies include copper cathodes, silicon carbide wafers, and rare-earth magnetic materials. Single-source vulnerability concentrates in East Asian foundries fabricating discrete IGBT devices. Distribution runs through authorized system integrators for data center EPC contracts and open-market electronics distributors for replacement components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The direct current power system market compounds steadily as corporate net-zero commitments hardwire efficiency mandates into procurement specifications across hyperscale infrastructure buildouts.
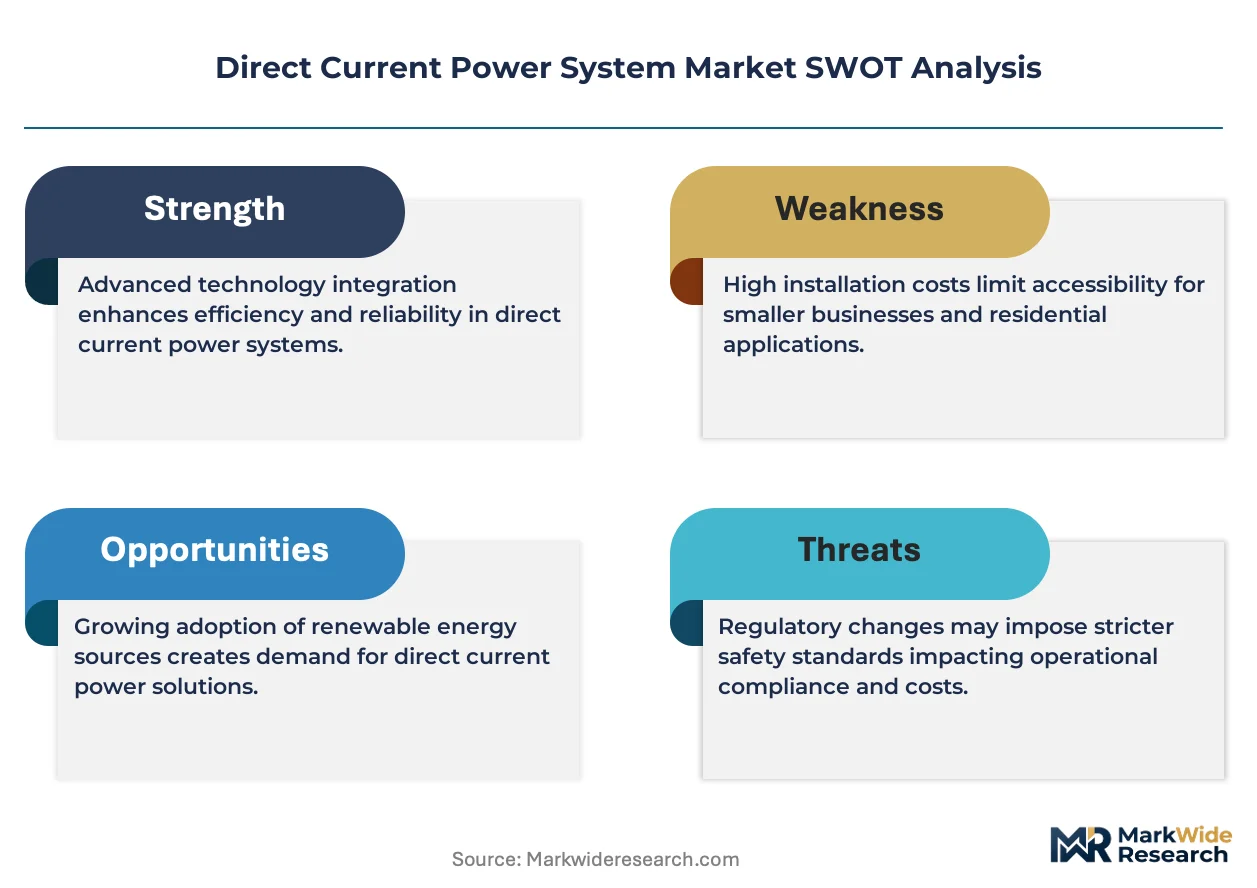
For Market Incumbents: Extend silicon carbide module design leadership through backward integration into wafer sourcing partnerships, neutralizing supply disruption risks from concentrated East Asian foundries. Fortify certification moats by accelerating IEEE 3006.7 compliance roadmaps ahead of voltage standard harmonization, locking out mid-tier competitors from 380V DC hyperscale contracts. For New Entrants and Emerging Players: The EU F-Gas Regulation in Europe opens a window for gas-free solid insulation specialists to capture switchgear replacement cycles as SF6 phaseout deadlines approach. Target China's SAMR certification pathway for 240V building distribution equipment, where domestic incumbents lag in integrated residential-commercial module design. Lead with natural convection cooling architectures that preempt compliance-driven obsolescence in European data center specifications. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized magnetics engineering scarcity strains mid-tier OEM hiring pipelines beyond salary adjustment capacity. Long-term viability favors vertically integrated power module specialists with captive silicon carbide supply arrangements and hyperscale developer relationships spanning multi-year frameworks. Watch for inflection when IEEE publishes finalized 380V DC interoperability standards that eliminate platform-level R&D hedging costs.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Supply Agreement | Captive wafer sourcing from Yangtze River Delta foundries secures converter cost structures against spot market volatility. |
| Hyperscale Developer Partnership | Multi-year supply frameworks with Northern Virginia operators lock in volume commitments across 100MW-plus campus buildouts. |
| EU F-Gas Compliance Certification | Gas-free solid insulation validation enables switchgear procurement in Frankfurt and Scandinavian data center clusters. |
| Modular Multilevel Converter R&D | HVDC submarine cable capability opens North Sea offshore wind interconnection contracts beyond data center verticals. |
| GB Standards Certification Pathway | SAMR approval for 240V building distribution creates first-mover positioning in China's residential-commercial DC microgrid expansion. |
Methodological Framework
Direct dialogue with power electronics engineering directors, hyperscale data center procurement leads, EPC contractor project managers, and SAMR certification specialists grounds qualitative assessments in operational reality. Secondary validation draws from IEEE standards documentation, EU Ecodesign Directive implementation guidance, FERC interconnection filings, and customs data on power semiconductor trade flows. Bottom-up unit economics and top-down macroeconomic drivers undergo iterative reconciliation to ensure segmentation coherence.
Top-down macroeconomic indicators and bottom-up project pipeline tracking converge across the analysis window through multi-scenario stress testing. Segmentation dimensions span product architecture, voltage class, end-use criticality, installation environment, and regional regulatory framework. CAGRs emerge from logistic diffusion modeling of technology substitution rates, with silicon carbide penetration curves and copper price trajectory assumptions serving as primary forecast inputs.
Revisions become necessary when IEEE voltage standard harmonization accelerates, East Asian semiconductor export controls expand, or EU F-Gas phaseout timelines compress. Forecasts reflect documented assumptions regarding technology cost reduction curves and regulatory enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Global Power Line Communication (PLC) Systems Market
Power
China Power Market
Power
Mexico Power EPC Market
Power
Water Turbine Market
Power
Denmark Power Market
Power
Asia-Pacific Turbomachinery Control Systems Market
Power
Sudan Power Market
Power
Residential Micro Inverter Market
Power
Colombia Power Market
Power
Compact Substation Market
Power
Solar Plants Controllers Market
Power
Portugal Power Market
Power
Malaysia Power EPC Market
Power
Gas Freeing Fan Market
Power
Temporary Load Bank Rental Market
Power
Controllable Shunt Reactor for UHV Market