
 Portugal Solar Energy Market | 2026-2036
Portugal Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Portugal Solar Energy Market Analytics
Aftermarket service revenue is tilting from episodic repair contracts toward continuous performance-guarantee agreements as asset owners seek predictable output. EDP Renováveis leverages its Iberian grid integration expertise to sustain long-term O&M contracts across Portuguese solar parks. Iberdrola anchors its position through backward integration into project development and grid connection management. Voltalia competes on distributed generation expertise, occupying the commercial and industrial rooftop segment with standardized installation protocols.
Portugal solar energy encompasses photovoltaic systems that convert sunlight into electricity through silicon-based semiconductor junctions, typically operating at 15-22% conversion efficiency depending on cell architecture, with installations designed for grid injection or behind-the-meter consumption. The technology serves decarbonization mandates, energy cost hedging, and rural electrification objectives across the Portuguese economy. Photovoltaic systems dominate installed capacity, though concentrated solar power retains structural relevance for grid-scale storage coupling in the Alentejo corridor. Agricultural end-use represents the fastest-expanding demand pool as irrigation and processing facilities seek tariff stability. Ground-mounted installations command the majority of megawatt-scale deployment, while floating solar gains traction in Portuguese reservoir environments where land-use conflicts constrain conventional development.
DGEG auction rounds, EU Green Deal alignment requirements, and CE marking standards for electrical equipment collectively shape project eligibility, financing access, and equipment procurement rules for market participants. The national regulator's grid connection queue management directly determines development timelines and capital deployment schedules. Stakeholders must monitor forthcoming capacity auction designs and storage co-location mandates to calibrate project pipelines and partnership strategies.
Market Dynamics
DGEG auction rounds are compressing project development timelines while EU Green Deal alignment requirements reshape equipment procurement rules across Portuguese solar parks. Developers now face simultaneous pressure on grid queue positioning and domestic content thresholds.
Growth Catalysts
- EU Green Deal alignment:CE marking standards and sustainability criteria unlock preferential financing terms for compliant projects, accelerating capital deployment into Alentejo corridor developments.
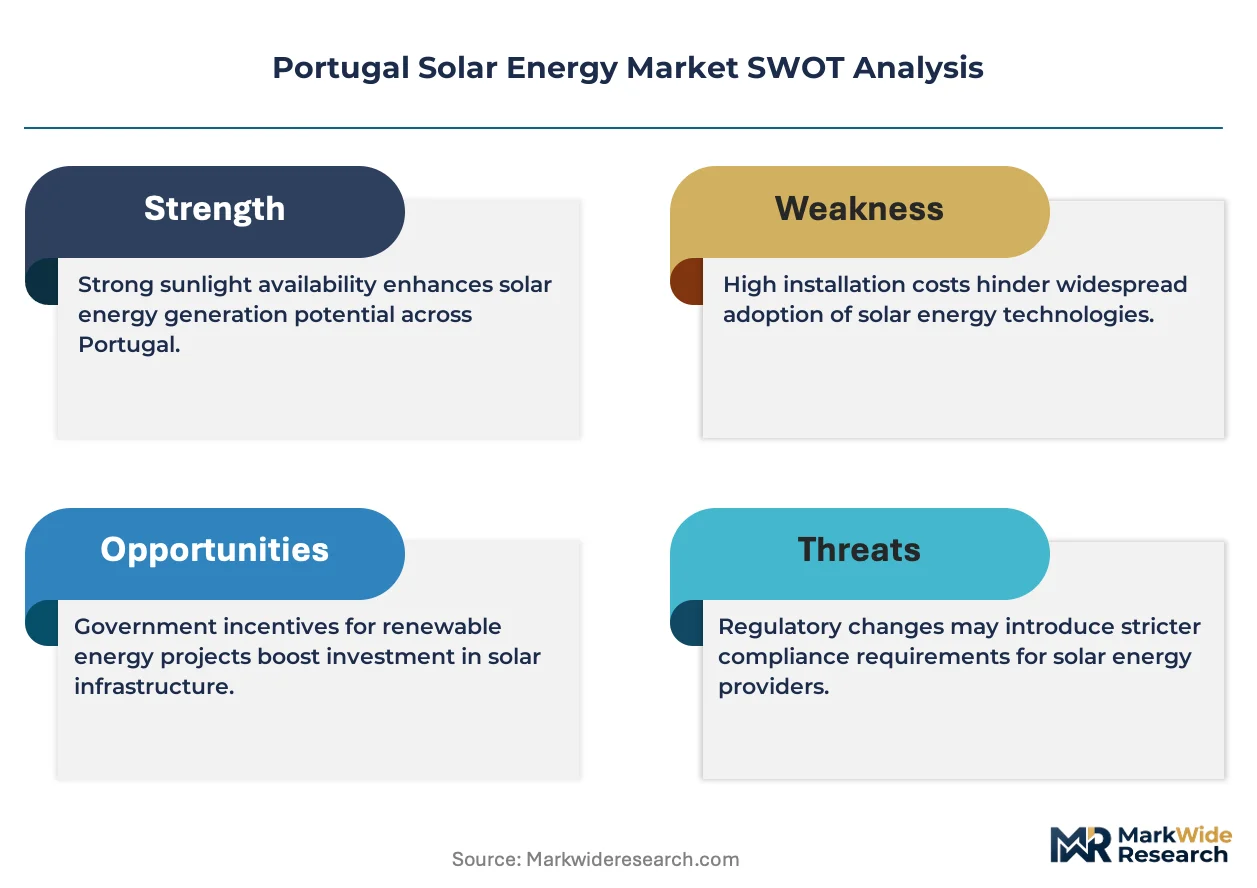
- Agricultural irrigation demand:End-use buyers in farming operations seek tariff stability through behind-the-meter installations, creating predictable offtake for distributed generation developers.
- Alentejo land availability:High irradiance levels combined with expansive rural plots enable ground-mounted utility-scale deployment without land-use conflicts that constrain other European markets.
Market Restraints
- Polysilicon supply concentration:Portuguese developers remain exposed to upstream supply bottlenecks concentrated in Chinese manufacturing clusters, creating input cost volatility and delivery uncertainty.
- Grid connection queue management:DGEG regulatory timelines for transmission access approvals extend capital deployment schedules and compress project IRRs during construction phases.
- Intermittency integration limits:Without co-located storage mandates, solar output variability creates curtailment risk during peak generation periods, constraining merchant revenue streams.
Strategic Opportunities
- Floating solar reservoirs:Portuguese water infrastructure sites offer deployment potential where land availability constraints block conventional ground-mounted development, particularly in Alentejo hydroelectric catchments.
- Cold-chain operation electrification:Food processing and logistics facilities seek renewable energy procurement to meet corporate decarbonization commitments, creating commercial and industrial rooftop demand.
- Storage co-location mandates:Anticipated DGEG auction designs requiring battery coupling will enable hybrid project economics and grid services revenue stacking for early movers.
Industry Challenges
- Grid integration engineering capacity:Portuguese utilities face shortages of specialized inverter and substation technicians capable of managing high-penetration solar interconnection, delaying commissioning schedules.
- Domestic content verification:EU Green Deal origin requirements demand complex supply chain documentation that extends procurement cycles and creates compliance audit exposure for developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portugal Solar Energy Market |
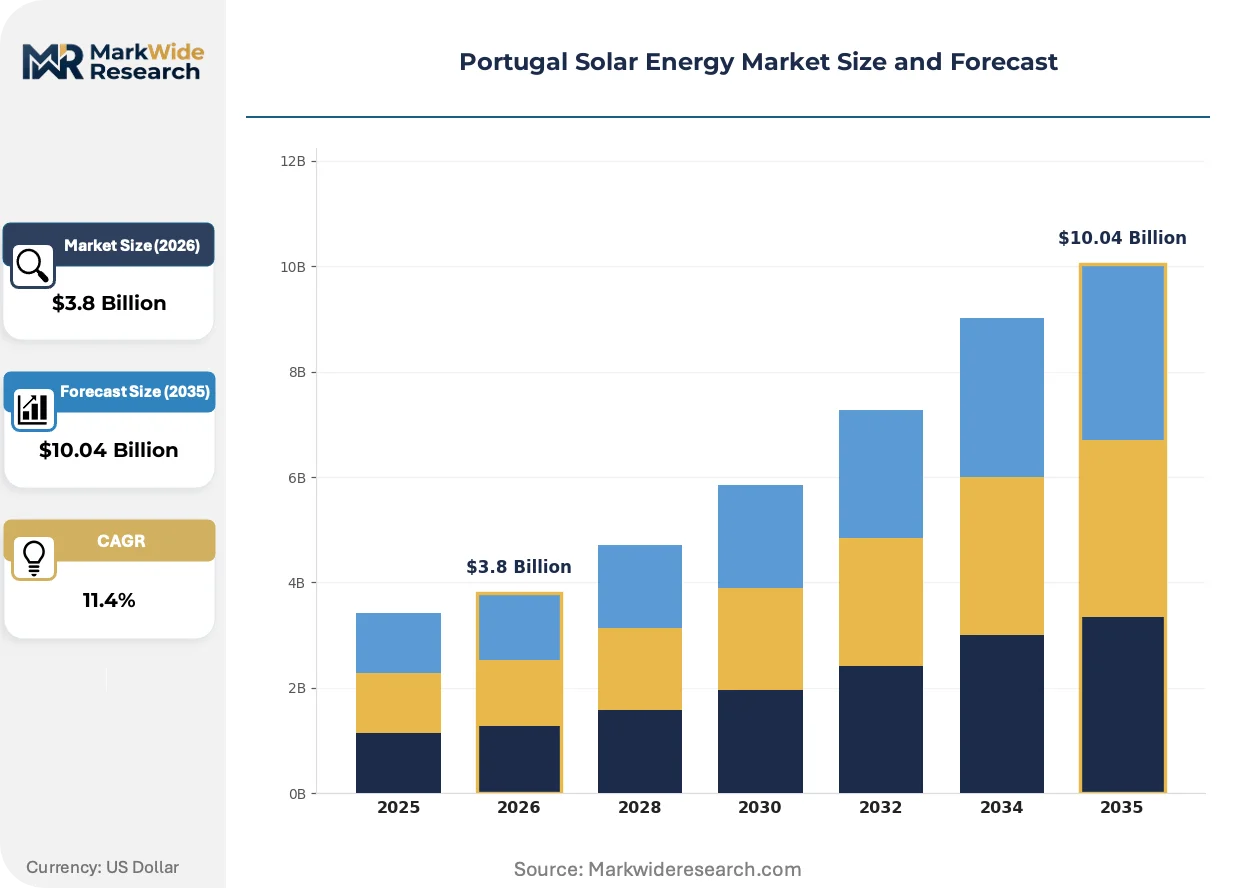
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Systems, Solar Thermal, Concentrated Solar Power, BIPV End User: Residential, Commercial, Industrial, Agricultural Installation Type: Ground-mounted, Roof-mounted, Floating, Building-integrated Service Type: Installation, Maintenance, Consulting, Monitoring |
| Companies Covered | EDP Renováveis, Iberdrola, Voltalia, Greenvolt, Acciona, Sonnedix, Galp, Finerge, R.Power, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portugal Solar Energy Market Evolving Landscape
Bifacial module architectures and floating platform designs are collapsing traditional cost structures while auction mechanisms force faster technology refresh cycles. Portuguese developers must now optimize for dual-sided generation and water-based deployment simultaneously.
Bifacial photovoltaic panels capture reflected irradiance from ground surfaces and albedo effects, boosting effective yield by 10-15% over monofacial equivalents. Agricultural operators in Alentejo are adopting these systems to maximize output per hectare under land-use constraints. The technology is collapsing the historical trade-off between ground coverage ratios and energy density, enabling denser row spacing without clipping losses.
DGEG renewable energy auction frameworks now incorporate grid stability criteria and domestic content thresholds that reshape equipment selection. Developers must balance module efficiency against supply chain documentation burdens to maintain bid competitiveness. The Alentejo utility-scale segment faces the steepest compliance adjustments as connection queue priority ties directly to auction round participation.
Performance-guarantee service contracts are displacing traditional time-and-materials O&M arrangements as asset owners seek predictable output certainty. Long-term yield warranties now bundle remote monitoring, predictive analytics, and corrective maintenance into single fee structures. This shift concentrates most visibly among institutional investors holding Portuguese solar park portfolios who require contracted cash flow visibility for financing covenants.
Portugal Solar Energy Market Segmentation
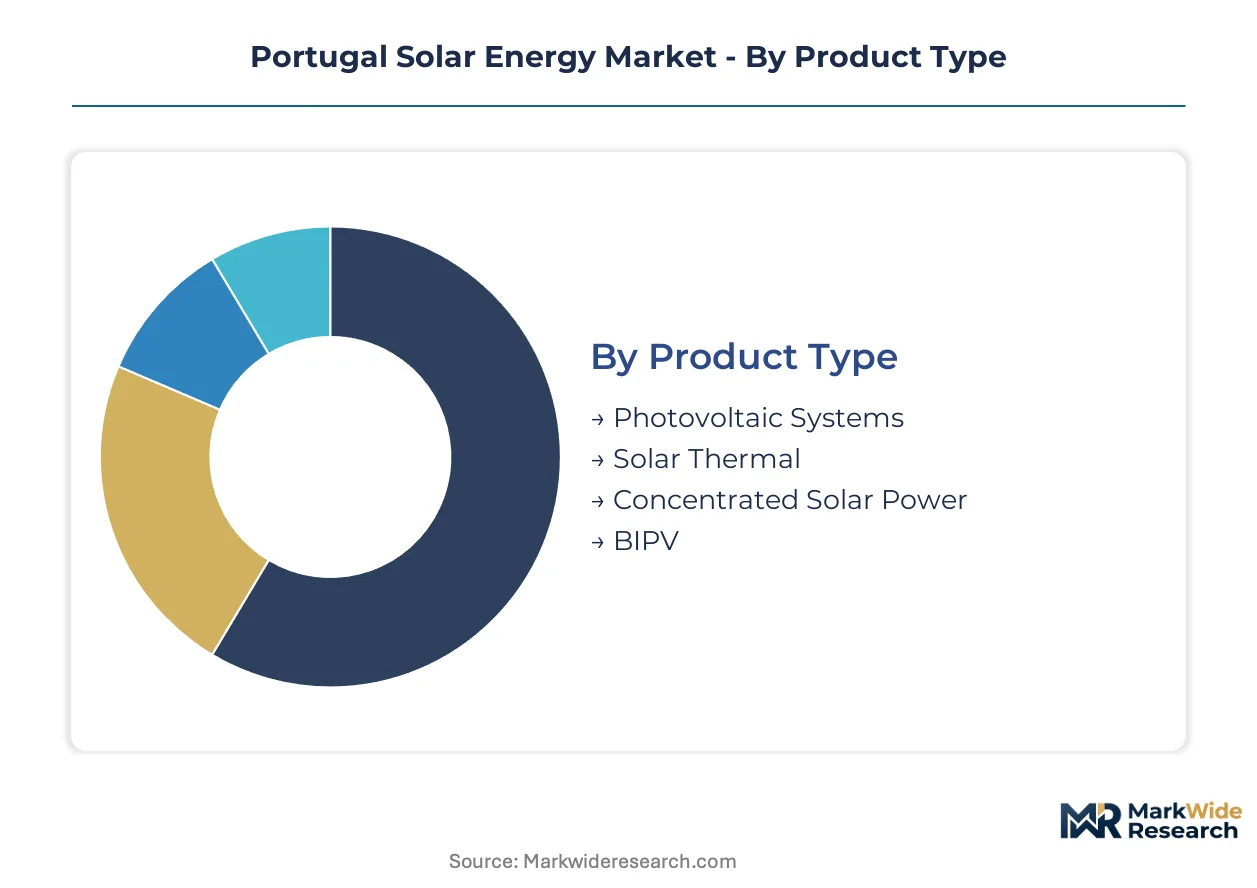
Segmentation in the Portugal solar energy market reveals how technology choice, customer profile, and deployment configuration interact with regulatory frameworks and land constraints. Understanding these divisions illuminates where capital deployment concentrates and where emerging opportunities sit outside current installed capacity patterns.
Product Type:
Technology selection in Portuguese solar deployment tracks directly to grid connection queue positioning and DGEG auction eligibility criteria.
- Photovoltaic Systems:Silicon-based semiconductor junctions operating at 15-22% conversion efficiency dominate Portuguese capacity additions. Alentejo utility-scale developers favor crystalline silicon modules for their bankable performance warranties and established supply chains.
- Solar Thermal:Heat-collection systems using evacuated tube or flat-plate collectors serve residential hot water and industrial process heat applications. Demand clusters in hospitality and food processing facilities seeking decarbonization compliance.
- Concentrated Solar Power:Mirror-based thermal generation with molten salt storage retains structural relevance for grid-scale storage coupling in the Alentejo corridor where high direct normal irradiance supports parabolic trough economics.
- BIPV:Building-integrated photovoltaic systems substitute conventional construction materials while generating electricity. Lisbon and Porto commercial retrofits drive adoption where facade replacement cycles coincide with energy efficiency mandates.
Photovoltaic Systems hold installed capacity. BIPV is rotating up the share rankings.
End User:
Customer type determines financing structure, offtake contract duration, and whether projects connect behind-the-meter or seek grid injection tariffs.
- Residential:Distributed rooftop installations under net-metering arrangements serve single-family homeowners seeking electricity bill reduction. Lisbon metropolitan area and coastal Algarve municipalities concentrate deployment.
- Commercial:Retail, office, and hospitality facilities procure solar through power purchase agreements or direct ownership. Cold-chain logistics operators represent an expanding sub-segment seeking tariff stability.
- Industrial:Manufacturing and processing facilities with high baseload demand deploy multi-megawatt ground-mounted systems. Energy-intensive industries in Setúbal and Aveiro industrial corridors anchor procurement volume.
- Agricultural:Irrigation pumping, cold storage, and processing equipment electrification drives the steepest expansion trajectory among end-use categories. Alentejo farming cooperatives seek behind-the-meter generation to hedge volatile agricultural input costs.
Industrial customers anchor current procurement volume. Agricultural end-use is climbing the fastest.
Installation Type:
Physical deployment configuration responds to land availability constraints, water body access, and building stock characteristics across Portuguese territory.
- Ground-mounted:Utility-scale arrays on dedicated land parcels command the majority of megawatt-scale additions. Alentejo's expansive rural plots and high irradiance levels attract developers without land-use conflicts seen elsewhere in Europe.
- Roof-mounted:Commercial and industrial building rooftops host distributed generation where grid connection infrastructure exists. Porto manufacturing zones and Lisbon logistics parks concentrate this segment.
- Floating:Pontoon-mounted systems on reservoirs gain traction where land availability constraints block conventional development. Alentejo hydroelectric catchments and irrigation reservoirs offer deployment potential.
- Building-integrated:Structural integration into facades and roofing materials serves urban environments with limited conventional rooftop area. Lisbon central business district retrofits drive niche adoption.
Ground-mounted arrays dominate megawatt-scale deployment. Floating solar is rotating up the share rankings.
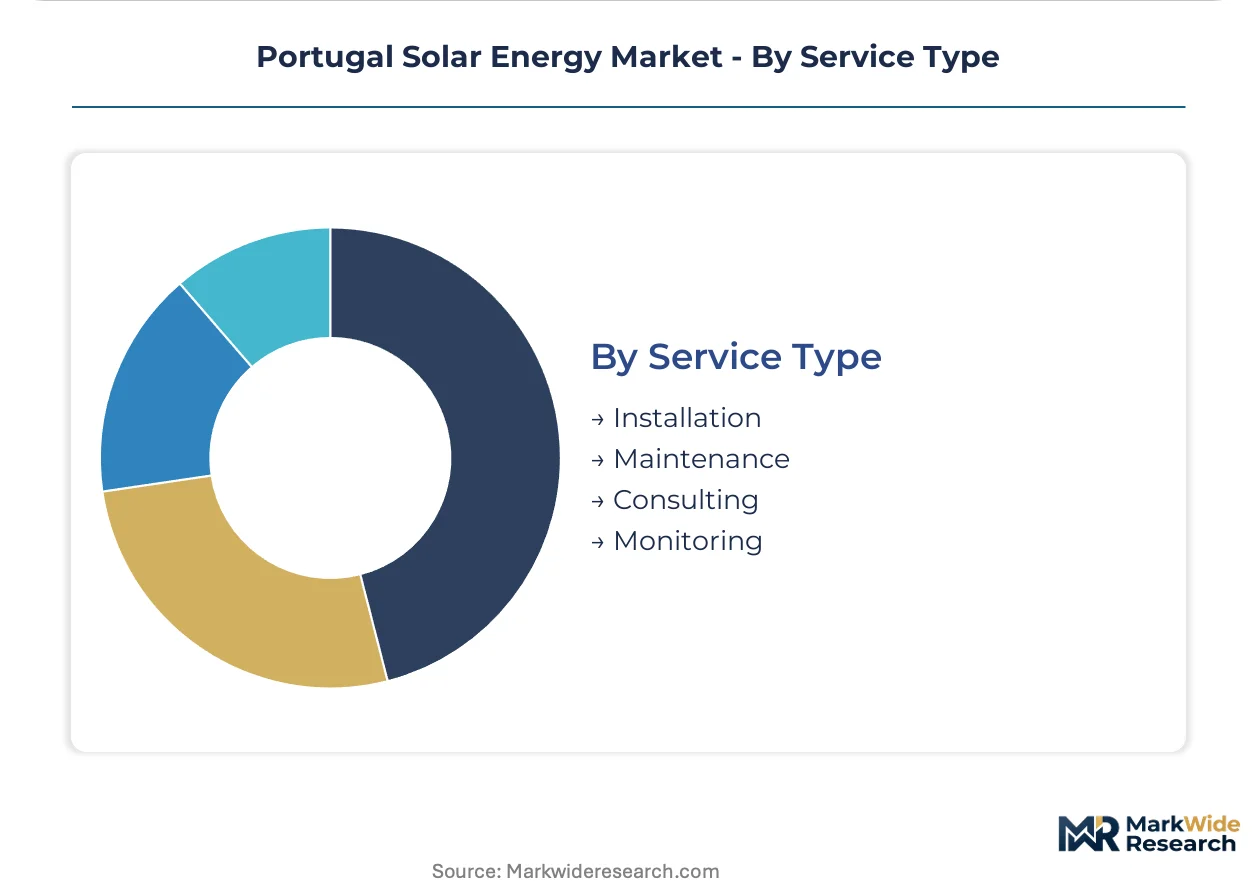
Service Type:
Service revenue models are shifting from transactional project delivery toward continuous performance relationships as asset ownership concentrates among institutional investors.
- Installation:Engineering, procurement, and construction services deliver turnkey project execution. DGEG auction timelines compress development schedules and intensify competition for qualified construction crews.
- Maintenance:Preventive and corrective O&M services preserve generation output and equipment lifetime. Performance-guarantee contracts displace time-and-materials arrangements as asset owners seek predictable cash flows.
- Consulting:Technical advisory, grid connection management, and regulatory compliance support guide developers through DGEG auction participation and permitting processes.
- Monitoring:Remote sensing, predictive analytics, and performance optimization services enable yield warranty fulfillment and insurance compliance for financed projects.
Installation services capture the largest revenue pool. Monitoring is gaining share fastest as digitalization penetrates asset management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive agricultural buyers in Alentejo drive volume procurement, while corporate offtakers in Lisbon and Porto absorb premium tariffs for behind-the-meter certainty. This demand-elasticity split shapes where developers concentrate project pipelines and how DGEG auction participation rates vary across Portuguese territory.
Alentejo
High irradiance levels and expansive rural land availability attract utility-scale ground-mounted deployment. DGEG auction frameworks prioritize grid connection queue positioning for projects in this corridor. Évora and Beja districts concentrate megawatt-scale installations where farming cooperatives seek irrigation electrification.
Lisbon Metropolitan Area
Commercial and industrial rooftop demand clusters around cold-chain logistics and food processing facilities seeking tariff stability. EU Green Deal alignment requirements shape equipment procurement for urban retrofits. The Tagus Valley industrial zone anchors distributed generation deployment with standardized installation protocols.
Porto-North Region
Manufacturing corridors in Aveiro and Braga drive industrial-scale solar procurement for energy-intensive production. CE marking standards and domestic content verification create compliance documentation burdens for developers. The Douro Valley wine processing cooperatives represent an emerging agricultural sub-segment.
Algarve
Tourism and hospitality facilities seek renewable energy procurement to meet corporate decarbonization commitments. Net-metering arrangements support residential rooftop deployment in coastal municipalities. Faro and Portimão concentrate commercial installations where grid infrastructure supports distributed injection.
Central Portugal
Floating solar gains traction in reservoir environments where land-use conflicts constrain conventional development. Coimbra and Castelo Branco districts host pilot deployments on hydroelectric catchments. DGEG regulatory timelines for hybrid storage co-location will determine capital deployment schedules in this sub-region.
Portugal Solar Energy Market Competitive Landscape
Capability concentration sits with grid integration specialists; scale advantage sits with vertically integrated Iberian utilities. The Portuguese solar market structures around three tiers: auction-winning developers with DGEG queue priority, distributed generation specialists with standardized installation protocols, and institutional asset owners seeking performance-guarantee service contracts. Dominant competitive moves include backward integration into project development and strategic partnerships for storage co-location.
Within the utility-scale developer tier, EDP Renováveis and Iberdrola exemplify grid integration capability concentration. EDP Renováveis leverages Iberian interconnection expertise to sustain long-term O&M contracts across Portuguese solar parks. Iberdrola anchors its position through captive project development and grid connection management. Voltalia occupies a distinct position in the distributed generation segment, representing standardized installation protocol specialization for commercial and industrial rooftop deployment.
| Leading Market Players |
|---|
| EDP Renováveis |
| Iberdrola |
| Voltalia |
| Greenvolt |
| Acciona |
| Sonnedix |
| Galp |
| Finerge |
| R.Power |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese polysilicon manufacturing is compressing module prices globally, forcing Portuguese developers to renegotiate EPC contracts while DGEG auction deadlines compress procurement timelines. This utilization-driven price collapse rewards buyers with sourcing flexibility but punishes developers locked into fixed-price agreements.
Pricing Analysis
Performance-guarantee service contracts now drive lifetime value for Portuguese solar asset owners, displacing episodic repair arrangements. Three-tier pricing structure across premium, standard, and economy levels tracks module efficiency ratings and bankability of warranties. Cost compression in crystalline silicon modules is intensifying because Chinese manufacturers are dumping inventory into European markets. Agricultural irrigation cooperatives in Alentejo exhibit the highest price sensitivity, while institutional investors holding Lisbon-area commercial portfolios absorb premium tariffs for yield certainty.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk calculus for Portuguese developers sourcing crystalline silicon modules. Manufacturing concentrates in China, Vietnam, and Malaysia, with Portuguese procurement drawing from Chinese polysilicon, Vietnamese cell assembly, and Malaysian module finishing. Raw material dependencies center on high-purity silicon metal, silver paste for metallization, and aluminum frames. Single-source vulnerability in inverter supply from Chinese manufacturers creates commissioning delays. Distribution runs through Iberian logistics hubs serving EPC contractors with just-in-time delivery to Alentejo construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Portugal solar market sits at a platform-economics inflection where DGEG auction interoperability rules are reshaping developer-aggregator relationships. Grid services stacking and storage co-location mandates are creating new ecosystem entry points beyond pure generation.
For Market Incumbents: Insulate auction queue positioning through captive grid connection management capabilities, as DGEG regulatory timelines increasingly determine project economics. Deepen backward integration into energy storage system procurement to capture hybrid project premiums. Defend against emerging floating solar specialists by securing water body access rights in Alentejo hydroelectric catchments.
For New Entrants and Emerging Players: Establish a beachhead in agricultural behind-the-meter installations where Alentejo farming cooperatives seek tariff stability for irrigation electrification. Target cold-chain logistics facilities in Lisbon's Tagus Valley industrial zone with standardized rooftop deployment protocols. Lead with performance-guarantee service contracts rather than equipment sales to differentiate from incumbent EPC providers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across distributed generation portfolios as modular installation techniques reduce labor costs. Long-term viability favors asset owners with contracted offtake from creditworthy agricultural and industrial end-users. Target acquisition archetypes include regional O&M specialists with DGEG compliance expertise. Watch for inflection when DGEG announces storage co-location mandates in forthcoming auction rounds.
| Strategic Initiative | Industry Significance |
|---|---|
| Storage Co-location Development | DGEG auction designs requiring battery coupling will enable hybrid project economics for early movers. |
| Floating Solar Platform Deployment | Alentejo reservoir access creates differentiated land-use positions where ground-mounted development faces constraints. |
| Performance-Guarantee Service Contracts | Institutional investors holding Portuguese solar portfolios require contracted cash flow visibility for financing covenants. |
| Agricultural Electrification Partnerships | Alentejo farming cooperatives seek behind-the-meter generation to hedge volatile agricultural input costs. |
| Grid Integration Capability Buildout | Portuguese utilities face shortages of specialized inverter technicians capable of managing high-penetration solar interconnection. |
Research Methodology
A spread of perspectives from utility planning officers, IPP project developers, EPC contractors, and grid operators converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation against DGEG auction documentation, EU Green Deal regulatory filings, and Iberian grid operator interconnection data. Bottom-up project pipeline tracking and top-down capacity installation statistics were triangulated to establish baseline market sizing.
Demand-supply balance dynamics across the analysis window were modeled through segmented capacity addition forecasts by technology type, installation configuration, and end-use customer category. Segmentation dimensions included product type, customer profile, deployment configuration, and service revenue model. CAGRs were derived from regression analysis of historical auction outcomes and projected DGEG pipeline releases. Forecast inputs incorporated polysilicon supply elasticity and domestic content threshold compliance costs.
Stress conditions across grid connection queue delays, polysilicon price volatility, and EU Green Deal origin requirement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory continuity and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Thermal Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
Solar Interconnect Ribbon Market
Solar Power Systems
Off Grid Solar Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Solar Carport Market
Solar Power Systems
Denmark Solar Energy Market
Solar Power Systems
Solar Microinverter and Power Optimizer Market
Solar Power Systems
Solar Thermal Power Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Third Generation Solar Cell Sales Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Global Airport Solar Power Market
Solar Power Systems
Global Solar Water Heaters Market
Solar Power Systems
High-Efficiency Solar Modules Market