
 Colombia Solar Energy Market | 2026-2036
Colombia Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Solar Energy Market Outlook
Commercial establishments is redrawing procurement patterns in the Colombia solar energy sector as industrial facilities scale behind-the-meter installations. AES Colombia leverages its utility-scale pipeline to anchor long-term power purchase agreements with mining and manufacturing clients. Celsia competes through distributed generation platforms targeting mid-sized commercial rooftops in Medellín and Cali. Enel Colombia extends its grid-connected project portfolio across the Caribbean coast, capitalizing on transmission access and high irradiance zones.
Colombia solar energy encompasses photovoltaic systems that convert sunlight into electricity through silicon-based cells with typical efficiencies of 18-22%, deployed for grid injection, self-consumption, or rural electrification. Photovoltaic panels dominate capital expenditure allocation, while solar inverters capture disproportionate margin pools due to grid-code compliance requirements and warranty complexity. Grid-connected installations lead volume deployment, though off-grid and hybrid systems are gaining fastest in non-interconnected zones where diesel displacement economics strengthen.
Colombia's Ministry of Mines and Energy, alongside the Energy and Gas Regulatory Commission, shapes market access through net metering rules and renewable energy auction schedules. The National Planning Department coordinates fiscal incentives that reduce project finance costs for qualifying installations. Stakeholders must monitor auction timing, transmission queue positions, and evolving distributed generation regulations to secure offtake contracts and land access before pipeline saturation.
Market Dynamics
The Colombian solar market pivots on distributed generation regulations that reframe who controls electricity production. Law 1715 of 2014 and its enabling decrees created self-generation frameworks allowing commercial and industrial users to offset grid purchases with behind-the-meter installations, shifting capital allocation from centralized utilities to corporate energy managers.
Growth Catalysts
- Net Metering Expansion:The Energy and Gas Regulatory Commission's simplified interconnection rules for systems under 1 MW accelerate rooftop deployment in Bogotá and Medellín commercial zones.
- Non-Interconnected Zones (ZNI):Diesel displacement economics strengthen as hybrid solar-battery systems undercut liquid fuel logistics in Amazonas, Chocó, and La Guajira departments.
- Renewable Energy Auctions:The Ministry of Mines and Energy's long-term contracting mechanisms provide revenue certainty for utility-scale projects seeking project finance.
Market Restraints
- Transmission Queue Congestion:Grid connection delays in the Andean region extend project timelines by 18-36 months as Cundinamarca-Bogotá corridor saturation intensifies.
- Import Dependency:Photovoltaic module supply concentrates in Chinese manufacturing, exposing developers to shipping cost volatility and currency fluctuation risk.
- Land Tenure Complexity:Formalization gaps in rural property registries complicate site acquisition for utility-scale installations in Caribbean coastal departments.
Strategic Opportunities
- Agricultural Irrigation Electrification:Solar-powered pumping systems address diesel dependence in Cauca Valley rice and coffee zones where grid extension remains uneconomical.
- Green Hydrogen Pilots:The National Hydrogen Roadmap positions Atlántico and Bolívar departments for electrolyzer-solar coupling at port industrial clusters.
- Energy Communities:Regulatory frameworks enabling collective self-consumption open municipal-scale aggregation in intermediate cities like Pereira and Bucaramanga.
Industry Challenges
- Specialized Installation Labor:Certified photovoltaic technician shortages constrain deployment velocity as training pipeline output lags permit issuance rates.
- Grid Code Compliance Burden:Inverter synchronization and anti-islanding certification timelines add 4-6 months to commercial project commissioning schedules.
- Legacy Distribution Infrastructure:Radial network configurations in secondary cities limit hosting capacity for distributed generation backflow without transformer upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Solar Energy Market |
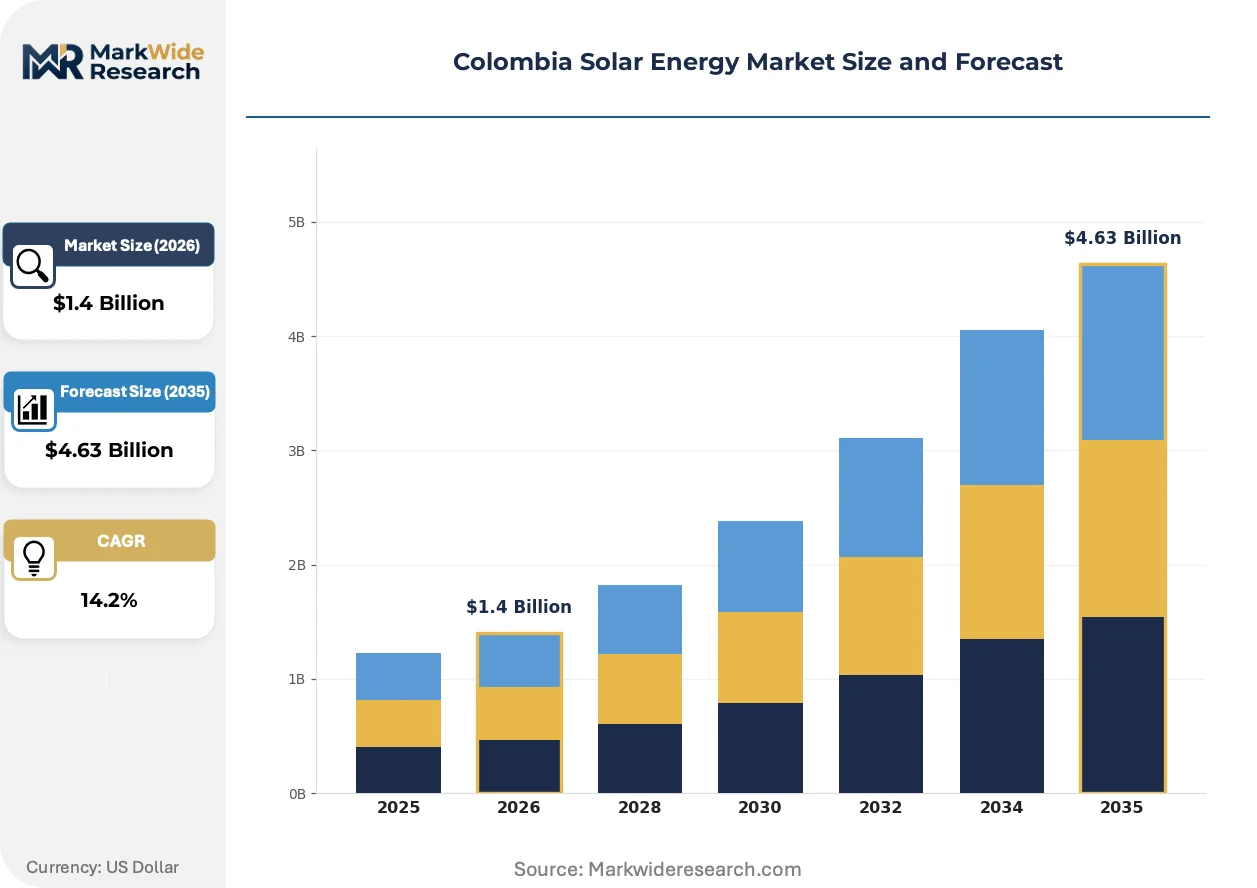
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $4.63 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Solar Inverters, Solar Batteries, Mounting Structures Installation Type: Grid-Connected, Off-Grid, Hybrid Systems, Rooftop Solutions End User: Residential Users, Commercial Establishments, Industrial Facilities, Government Projects Service Type: Installation Services, Maintenance Services, Consulting Services, Financing Solutions |
| Companies Covered | Statkraft, AES Colombia, Enel Colombia, Canadian Solar, Grupo Energía Bogotá, Celsia, Verano Energy, Isagen, Atlas Renewable Energy, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Solar Energy Market Strategic Shifts
Bifacial module technology and string inverter architectures are compressing balance-of-system costs while regulatory experimentation with energy communities opens new ownership structures. These shifts reconfigure competitive advantage around installation speed and local regulatory navigation rather than equipment sourcing alone.
Monocrystalline PERC bifacial modules are decomposing the premium attached to imported European and North American panels by delivering comparable degradation rates at landed cost parity. Large commercial rooftops in Cali and Barranquilla are specifying these units for 20-year power purchase agreements, collapsing the historical tier-one brand price wedge that favored established suppliers.
The Ministry of Mines and Energy's 2023 distributed generation decree modifies net metering caps and self-generation thresholds, forcing developers to restructure project sizing around new regulatory breakpoints. Industrial offtakers in the Cundinamarca-Bogotá corridor are resizing installations to remain under 5 MW limits that preserve simplified interconnection procedures.
Aggregated procurement through energy service companies is displacing direct equipment ownership among mid-sized commercial users. Textile manufacturers in Medellín and food processors in Valle del Cauca now contract operational expenditure models where installers retain asset ownership and sell kilowatt-hours under 10-15 year agreements, transferring performance risk from balance sheets to specialized developers.
Colombia Solar Energy Market Segmentation
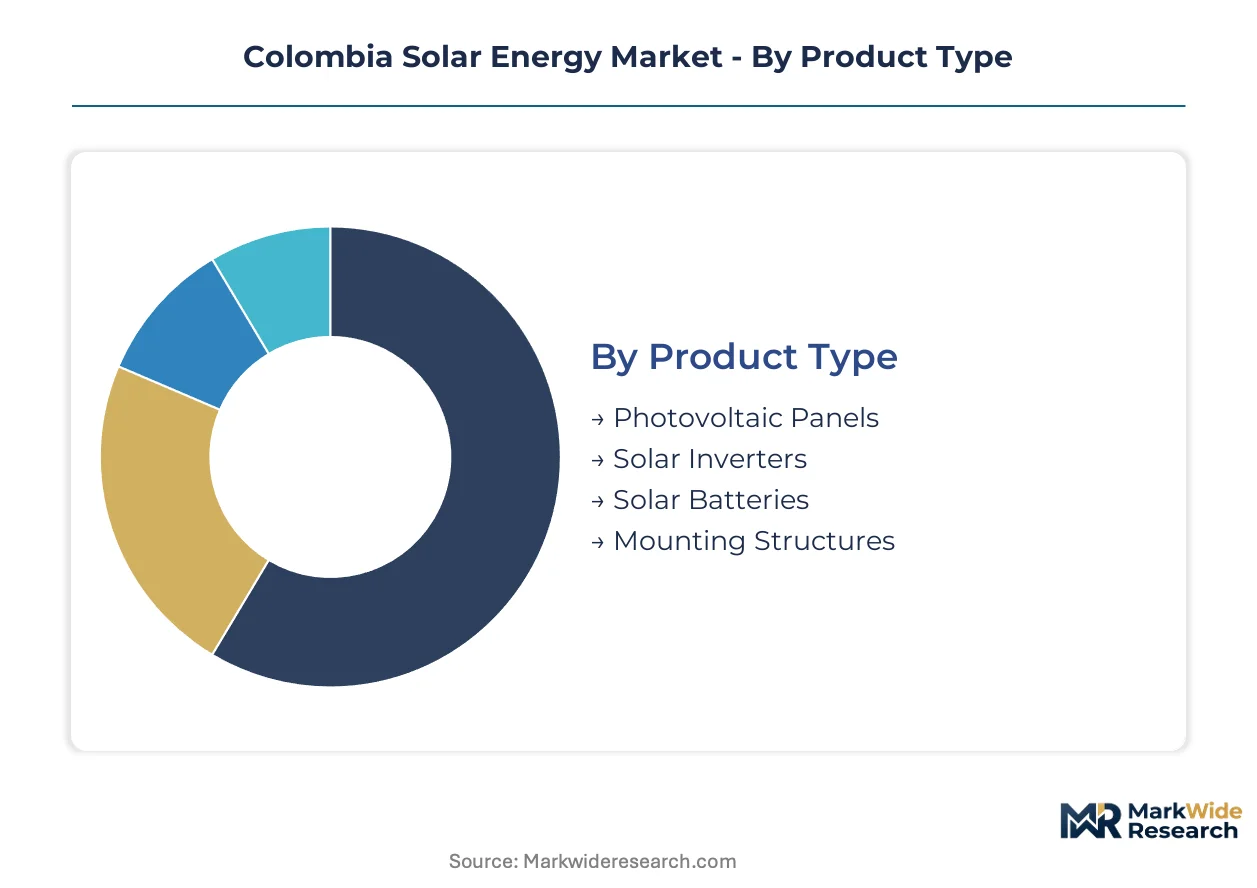
Segmentation in Colombia's solar market reveals how capital allocation shifts between centralized infrastructure and distributed assets. Equipment suppliers and project developers track these divides to position inventory and technical resources where procurement velocity concentrates.
Product Type:
Photovoltaic panels face substitution pressure from integrated solar-storage systems that bundle generation with dispatch capability.
- Photovoltaic Panels:Monocrystalline PERC bifacial modules dominate commercial procurement in Cali and Barranquilla, where 20-year power purchase agreements favor degradation-resistant silicon architectures. Cundinamarca-Bogotá industrial offtakers specify these units for behind-the-meter installations under 5 MW regulatory thresholds.
- Solar Inverters:String and central inverter platforms capture disproportionate margin pools through grid-code compliance requirements and warranty complexity. Anti-islanding certification timelines extend commissioning schedules by 4-6 months in the Andean region.
- Solar Batteries:Lithium-ion storage systems enable diesel displacement in Amazonas, Chocó, and La Guajira non-interconnected zones where hybrid configurations undercut liquid fuel logistics.
- Mounting Structures:Fixed-tilt and tracking systems anchor utility-scale installations across Caribbean coastal departments with high irradiance profiles.
Photovoltaic panels retain volume leadership; solar batteries hold the steepest expansion curve.
Installation Type:
Cost tier differentiation separates capital-intensive grid injection from operational expenditure models favored by mid-sized commercial users.
- Grid-Connected:Utility-scale projects seeking long-term contracting through Ministry of Mines and Energy auctions concentrate in transmission-accessible zones. Revenue certainty mechanisms support project finance for Caribbean coast developments.
- Off-Grid:Standalone systems address electrification gaps where radial network configurations limit hosting capacity. Amazonas and Chocó departments deploy these units for rural community supply.
- Hybrid Systems:Solar-battery coupling strengthens in ZNI territories where diesel displacement economics improve with each fuel price fluctuation. Atlántico and Bolívar port industrial clusters pilot electrolyzer integration under the National Hydrogen Roadmap.
- Rooftop Solutions:Simplified interconnection rules for systems under 1 MW accelerate deployment across Bogotá and Medellín commercial zones. Textile manufacturers and food processors contract energy service company models that transfer performance risk to specialized developers.
Grid-connected installations command the largest capital deployment; hybrid systems are climbing the fastest as battery costs compress.
End User:
Application maturity varies sharply between regulated utility procurement and emergent self-generation frameworks.
- Residential Users:Net metering participation remains constrained by upfront capital requirements and limited financing penetration outside major metropolitan centers.
- Commercial Establishments:Mid-sized rooftops in Medellín and Cali drive distributed generation volume through aggregated procurement and operational expenditure contracts. Law 1715 self-generation frameworks allow grid purchase offsets.
- Industrial Facilities:Mining and manufacturing clients anchor long-term power purchase agreements. Cundinamarca-Bogotá corridor saturation intensifies competition for transmission queue positions.
- Government Projects:Municipal-scale aggregation in Pereira and Bucaramanga tests energy community regulatory frameworks for collective self-consumption.
Industrial facilities anchor revenue concentration; government projects are gaining share fastest as regulatory experimentation opens new procurement channels.
Service Type:
Customer type stratification separates asset owners from performance-risk bearers across the project lifecycle.
- Installation Services:Certified photovoltaic technician shortages constrain deployment velocity as training pipeline output lags permit issuance rates in secondary cities.
- Maintenance Services:Long-term service agreements accompany 10-15 year kilowatt-hour contracts where installers retain asset ownership. Degradation monitoring and inverter replacement schedules protect revenue streams.
- Consulting Services:Regulatory navigation support focuses on auction timing, transmission queue positioning, and distributed generation decree compliance for project resizing.
- Financing Solutions:Project finance structures leverage Ministry of Mines and Energy fiscal incentives that reduce capital costs for qualifying installations.
Installation services capture the largest labor allocation; financing solutions are expanding most quickly as capital markets deepen exposure to renewable asset classes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The SIN (Sistema Interconectado Nacional) transmission backbone underwrites Colombia's solar geography, linking Caribbean irradiance zones to Andean demand centers through 500 kV corridors.
Cundinamarca-Bogotá Corridor
Industrial offtake from cement and steel manufacturers drives capacity deployment across this central region. Law 1715 self-generation frameworks allow grid purchase offsets for facilities under 5 MW thresholds. Zipaquirá and Soacha host the densest concentration of behind-the-meter installations seeking simplified interconnection procedures.
Caribbean Coast
Atlántico and Bolívar departments exploit 5.5+ kWh/m² daily irradiance for utility-scale pipeline development. The Ministry of Mines and Energy's renewable energy auctions provide long-term contracting certainty for projects near Barranquilla's port industrial clusters. Electrolyzer-solar coupling pilots under the National Hydrogen Roadmap concentrate in this zone.
Antioquia
Medellín's textile and apparel manufacturers anchor distributed generation demand through aggregated procurement models. The Energy and Gas Regulatory Commission's net metering rules for sub-1 MW systems accelerate rooftop deployment across the Aburrá Valley. Guarne and Rionegro industrial parks test energy community frameworks for collective self-consumption.
Medellín's textile and apparel manufacturers anchor distributed generation demand through aggregated procurement models. The Energy and Gas Regulatory Commission's net metering rules for sub-1 MW systems accelerate rooftop deployment across the Aburrá Valley. Guarne and Rionegro industrial parks test energy community frameworks for collective self-consumption.
Valle del Cauca
Sugar milling and food processing operations in Palmira and Yumbo contract operational expenditure models transferring performance risk to developers. Celsia's distributed generation platforms target mid-sized commercial rooftops here. The Cauca Valley's agricultural irrigation electrification needs drive solar-powered pumping system pilots.
Non-Interconnected Zones
Amazonas, Chocó, and La Guajira departments deploy hybrid solar-battery configurations where diesel displacement economics strengthen. These territories fall outside SIN coverage, requiring standalone systems for rural community supply. Hybrid configurations undercut liquid fuel logistics in settlements accessible only by river or air.
Colombia Solar Energy Market Competitive Environment
Concentration sits with integrated utilities that combine generation assets with regulated distribution franchises. The competitive structure splits between utility-scale auction participants and distributed generation specialists serving commercial rooftops. Strategic archetypes include: vertically integrated power companies leveraging transmission access, pure-play renewable developers securing land positions, and energy service companies offering operational expenditure contracts. Dominant competitive moves involve auction queue positioning for long-term contracting and aggregated procurement platform construction for mid-market commercial segments.
Among European-headquartered developers, Statkraft anchors the utility-scale pipeline segment through long-term power purchase agreements with industrial offtakers. AES Colombia and Enel Colombia exemplify the integrated utility archetype, combining regulated distribution franchises with renewable generation portfolios. These entities occupy positions spanning auction participation, distributed generation platforms, and grid-connected project development across Caribbean and Andean zones.
| Leading Market Players |
|---|
| Statkraft |
| AES Colombia |
| Enel Colombia |
| Canadian Solar |
| Grupo Energía Bogotá |
| Celsia |
| Verano Energy |
| Isagen |
| Atlas Renewable Energy |
| Others |
Value Chain & Pricing Dynamics
CREG's grid-code certification requirements gate both equipment qualification and price tiering in Colombia's solar sector, forcing developers to absorb compliance premiums or pass them through to offtakers based on interconnection complexity. The regulatory burden compresses margins on sub-1 MW distributed projects while amplifying price spreads between certified and uncertified inverter suppliers.
Pricing Analysis
Volume-discount tiering structures separate utility-scale procurement from commercial rooftop deployment, with projects above 5 MW capturing 15-20% per-watt reductions through aggregated module purchases. Price differentiation rests on CREG certification status and after-sales warranty bundling, with tier-one inverter suppliers commanding premiums for anti-islanding guarantees. Pricing pressure stems from Chinese module oversupply flooding Caribbean port entry points, eroding landed-cost buffers for regional distributors. Mining and cement manufacturers in the Cundinamarca-Bogotá corridor show lowest price sensitivity, prioritizing queue position and commissioning certainty over capital expenditure minimization.
Supply Chain Analysis
Just-in-time inventory strategies dominate among commercial installers in Medellín and Cali, while strategic stockpiling concentrates with utility-scale developers hedging against shipping volatility from Chinese manufacturing hubs. Geographic supply concentration centers on China for photovoltaic modules, South Korea for lithium-ion cells, and Germany for string inverter platforms. Raw material dependencies span polysilicon feedstock, silver metallization paste, and aluminum framing extrusions. Single-source vulnerability in maritime logistics through Cartagena and Barranquilla ports exposes developers to chokepoint risk during peak construction seasons. Distribution runs through specialized EPC contractors who bundle procurement with installation labor and CREG interconnection management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's solar market operates as a substitution defense against diesel generation in non-interconnected zones and grid-purchase offsets in the Andean corridor, with incumbents vulnerable to hybrid storage systems that collapse the economic case for pure-play photovoltaic deployment.
For Market Incumbents: Secure transmission queue positions in the Caribbean coast before saturation extends interconnection timelines beyond 36 months, and deepen backward integration into inverter servicing capabilities to capture recurring revenue streams as equipment margins compress. AES Colombia and Enel Colombia must defend against pure-play renewable developers by leveraging distribution franchise relationships to accelerate commercial customer acquisition in secondary cities. For New Entrants and Emerging Players: Agricultural irrigation electrification in Valle del Cauca represents a service-layer gap where incumbents under-serve diesel-dependent rice and coffee cooperatives with limited technical capacity. Target solar-powered pumping system deployment through equipment-leasing models that transfer performance risk from smallholder farmers to specialized developers, using Celsia's distributed generation platform architecture as a reference for operational expenditure contracting. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across hybrid solar-battery configurations as lithium-ion costs compress, shifting project finance structures toward shorter payback periods and higher leverage tolerance. Acquisition candidates should display established CREG relationships and land optionality in Atlántico or Bolívar departments. The signal to watch is Ministry of Mines and Energy auction schedule density, where accelerated contracting rounds indicate pipeline scarcity and margin expansion for positioned developers.| Strategic Initiative | Industry Significance |
|---|---|
| Power Purchase Agreement Structuring | Long-term contracting with mining clients in Cundinamarca secures project finance and reduces offtake risk. |
| Distributed Generation Platform Buildout | Aggregated procurement models in Medellín and Cali capture mid-market commercial rooftops through operational expenditure offers. |
| Hybrid Storage Integration | Solar-battery coupling in Amazonas and Chocó displaces diesel logistics and opens ZNI territory market share. |
| Grid-Code Certification Investment | CREG compliance capabilities accelerate commissioning timelines and differentiate inverter suppliers in competitive tenders. |
| Energy Community Framework Development | Regulatory experimentation in Pereira and Bucaramanga tests collective self-consumption models for municipal-scale aggregation. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade databases, and project development registries, combining structured interviews with IPP developers, EPC contractors, and utility planning officers at AES Colombia, Celsia, and Enel Colombia with validation against CREG interconnection queue data and Ministry of Mines and Energy auction records. Bottom-up capacity installation tracking triangulates against top-down fiscal incentive disbursement analysis to verify market sizing across grid-connected, off-grid, and hybrid installation categories.
Segmentation dimensions modeled include installation type, end-user application, equipment technology, and service layer, with analytical frameworks projecting capacity deployment and revenue generation across the analysis window. CAGRs derive from regression analysis of historical installation velocity against regulatory milestone timing and macroeconomic variables including currency fluctuation and shipping cost indices. Industry-specific forecast inputs incorporate CREG net metering participation rates and diesel price elasticity in ZNI territories.
Forecasts assume regulatory continuity in CREG interconnection procedures and Ministry of Mines and Energy auction schedules; material policy shifts such as distributed generation cap reductions or import tariff imposition would require re-modeling. Revision becomes warranted when transmission queue congestion in the Cundinamarca-Bogotá corridor extends beyond 48 months or when lithium-ion cell supply disruptions alter hybrid system economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Brazil Solar Energy Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Solar Energy Market
Solar Power Systems
Solar Cell Films Market
Solar Power Systems
Philippines Solar Energy Market
Solar Power Systems
Building Integrated Photovoltaic (BIPV) Market
Solar Power Systems
Solar Transparent Backsheet Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
Thin Film Photovoltaic Modules Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Off-Grid Solar Power Market
Solar Power Systems
India Solar Energy Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Venezuela Solar Energy Market