
 Bifacial Solar Market | 2026-2036
Bifacial Solar Market Size, Share, and Industry Trends Forecast 2026-2036
Bifacial Solar Market Analysis
Utility-scale procurement is realigning toward bifacial modules as developers chase higher energy yield per hectare. JA Solar Technology Co., Ltd. leverages its vertically integrated cell-to-module capacity to dominate glass-glass supply chains. LONGi Solar anchors its competitive position through relentless R&D intensity in monocrystalline bifacial architectures. Trina Solar extends its footprint across floating and agrivoltaic installations where bifacial gain coefficients matter most.
Bifacial solar captures reflected and diffuse light on both front and rear surfaces, typically achieving 5-30% additional energy yield over monofacial equivalents depending on albedo and installation height. Glass-glass modules command structural attention for their superior durability and lower degradation rates in harsh climates. Ground-mounted installations absorb the dominant share of module offtake, while floating bifacial arrays represent the fastest-growing installation category as reservoir and coastal projects multiply. Utility-scale application segments concentrate margin pools through long-term power purchase agreements that reward predictable bifacial performance guarantees.
China's MIIT enforces GB standards that mandate bifacial testing protocols, while the EU Green Deal's carbon border adjustments reshape import competitiveness for non-European module suppliers. India's BIS certification requirements and PLI scheme incentives are tilting domestic manufacturing toward bifacial cell capacity. Stakeholders must monitor how evolving albedo modeling standards and rear-side irradiance measurement protocols affect bankability and project finance terms.
Market Dynamics
Utility-scale developers now prioritize energy yield density over module cost, forcing procurement offices to rewrite technical specifications around bifacial gain coefficients and albedo assumptions rather than upfront capital expenditure.
Growth Catalysts
- China's dual carbon goals:Beijing's 2030 carbon peak mandate accelerates desert solar base deployments where bifacial modules capture reflected irradiance from high-albedo sand.
- Agrivoltaic installations:Dual-use solar arrays over crops exploit elevated mounting and ground reflectivity to boost bifacial harvest factors in France and Japan.
- Glass-glass durability:Extended product warranties and lower degradation rates in harsh climates reduce levelized cost of electricity for 25-year project finance models.
Market Restraints
- Polysilicon input volatility:Raw material price swings compress module margins and delay project commissioning timelines for capital-constrained developers.
- Rear-side irradiance uncertainty:Inconsistent albedo modeling standards across testing laboratories create bankability disputes during project due diligence.
- Monofacial module substitution:Conventional technology retains cost advantages in low-albedo environments and rooftop applications with restricted rear-side exposure.
Strategic Opportunities
- Floating solar arrays:Reservoir and coastal projects exploit water surface reflectivity to maximize bifacial gain coefficients where land constraints block ground-mounted alternatives.
- EU Green Deal carbon border adjustments:Import tariffs on carbon-intensive manufacturing reshape competitiveness for non-European suppliers with cleaner production footprints.
- India's PLI scheme:Domestic manufacturing incentives tilt cell capacity expansion toward bifacial architectures in Rajasthan and Gujarat solar parks.
Industry Challenges
- Rear-side performance certification:Absence of unified IEC standards for bifacial testing protocols forces developers to negotiate custom measurement procedures with each module supplier.
- Installation height optimization:Variable terrain and mounting system tolerances complicate predictive energy modeling and void performance guarantees.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bifacial Solar Market |
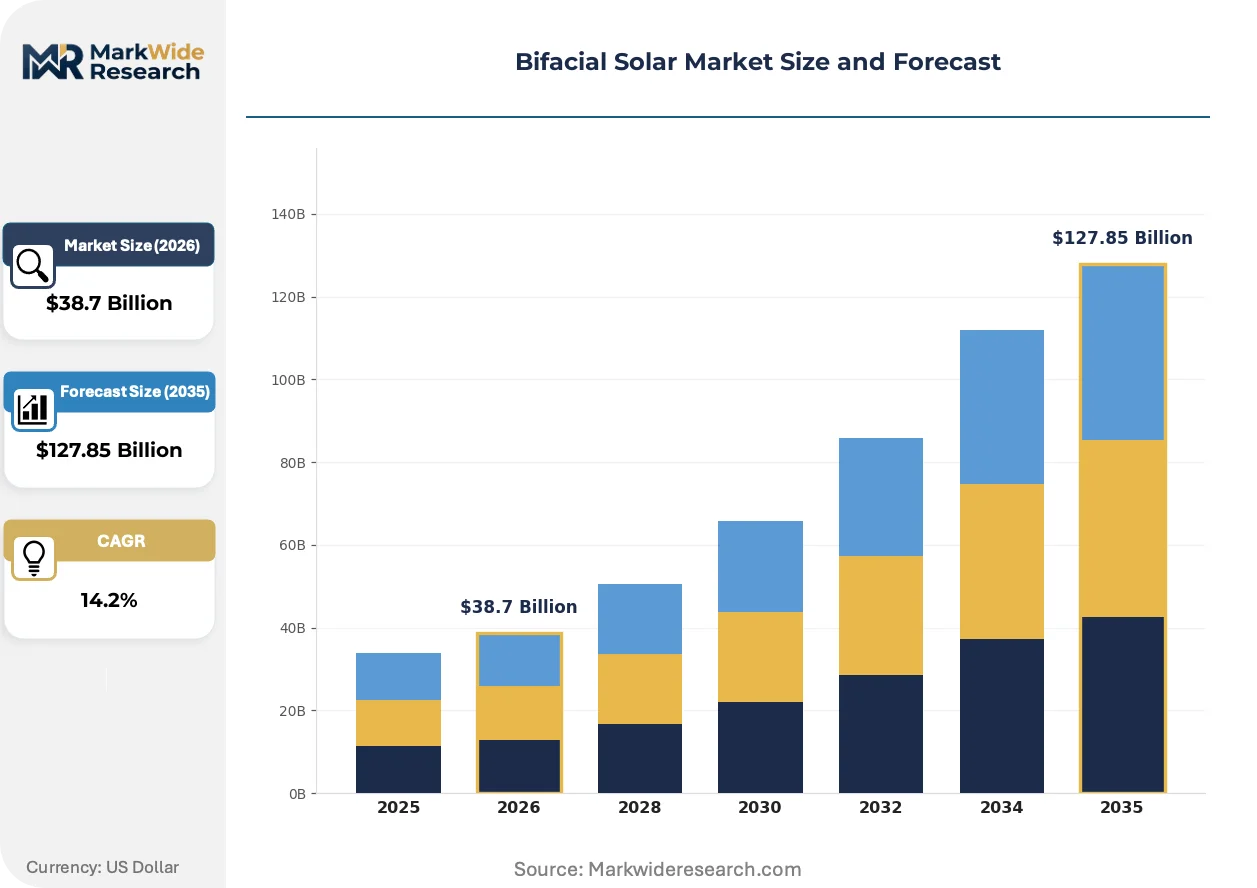
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $127.85 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass-Glass Modules, Glass-Film Modules, Bifacial Monocrystalline, Bifacial Polycrystalline Installation Type: Ground Mounted, Rooftop, Floating, Integrated End User: Utilities, Commercial, Industrial, Residential Application: Utility Scale, Distributed Generation, Off-Grid, Hybrid Systems |
| Companies Covered | JA Solar Technology Co., Ltd., Risen Energy, LONGi Solar, Huasun Energy, Sharp Corporation, Trina Solar, Jinko Solar, Suntech Power, Canadian Solar, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bifacial Solar Market Emerging Trajectories
Module architecture is bifurcating between glass-glass durability and lightweight polymer alternatives as developers weigh degradation rates against structural load limits in floating and rooftop applications.
TOPCon cell metallization is overtaking PERC architectures in new capacity additions. The tunnel oxide passivated contact design reduces rear-side recombination losses critical to bifacial performance. European and Indian module buyers now specify TOPCon in tender documents. This transition is overtaking incumbent cell technologies in procurement specifications before manufacturing cost parity arrives.
China's MIIT enforcement of GB/T 37408 bifacial testing standards tightens quality gates for domestic module shipments. The protocol mandates rear-side irradiance measurement under controlled albedo conditions. Indian developers importing Chinese modules must now verify compliance through BIS certification laboratories. Domestic manufacturers with pre-certified testing capabilities capture procurement preference in state-level solar auctions.
Buyers now unbundle performance guarantees from engineering-procurement-construction contracts. Independent technical advisors verify bifacial gain assumptions before financial close. Project sponsors in Spain and Brazil hire specialized irradiance measurement firms to validate albedo data. This service-layer fragmentation concentrates risk expertise with a narrow pool of accredited consultancies.
Bifacial Solar Market Segmentation
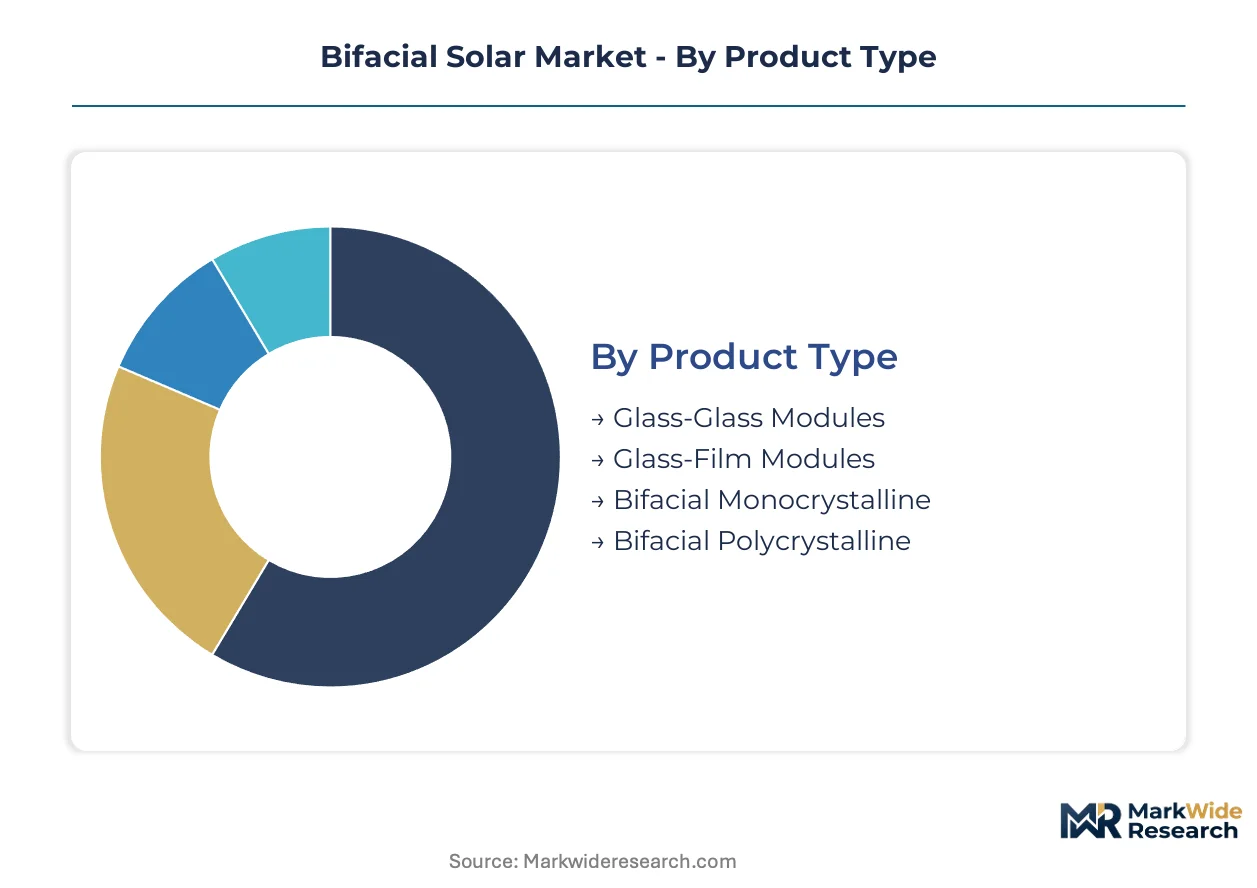
Bifacial solar segmentation reveals how certification burdens, installation constraints, and buyer procurement power reshape competitive positioning across module architectures. Each dimension carries distinct technical standards and financing requirements that determine bankability and project returns.
Product Type:
Glass-glass modules require IEC 61215 and IEC 61730 certification for dual-glass construction, while glass-film alternatives face lighter structural testing protocols. China's MIIT enforces GB/T 37408 bifacial testing standards that mandate rear-side irradiance measurement for all product categories.
- Glass-Glass Modules:Dual-layer tempered glass construction delivers superior mechanical load resistance and moisture ingress protection. Desert solar bases in China's northwest absorb dominant procurement volumes as developers chase 30-year performance warranties and sub-0.4% annual degradation rates.
- Glass-Film Modules:Polymer backsheet alternatives reduce module weight by 15-20% for rooftop applications with structural load constraints. India's Rajasthan solar parks show rising procurement preference where installation labor costs favor lighter handling and faster mounting cycles.
- Bifacial Monocrystalline:Single-crystal silicon architecture achieves highest conversion efficiencies in utility-scale deployments.
- Bifacial Polycrystalline:Multi-crystal construction retains cost competitiveness in price-sensitive distributed generation markets.
Glass-glass modules sit at the top of the volume ranking, with glass-film alternatives climbing the fastest as floating and rooftop applications multiply.
Installation Type:
Ground-mounted arrays concentrate procurement spend through utility-scale power purchase agreements, while floating installations command premium engineering margins due to specialized mooring and corrosion-resistant hardware requirements.
- Ground Mounted:Elevated tracking systems optimize bifacial gain coefficients through controlled row spacing and height-adjustable mounting. China's Qinghai and Xinjiang desert bases deploy gigawatt-scale arrays where high-albedo sand surfaces maximize rear-side energy harvest.
- Floating:Reservoir and coastal installations exploit water surface reflectivity to achieve 20-25% bifacial gains. Japan's Yamakura Dam project and India's Rihand Reservoir demonstrate fastest capacity expansion where land scarcity blocks conventional ground-mounted alternatives.
- Rooftop:Commercial and industrial buildings with parapet walls restrict rear-side exposure and limit bifacial advantage.
- Integrated:Building-integrated photovoltaic applications embed modules into facade and canopy structures with fixed tilt angles.
Ground-mounted systems capture the dominant revenue share, with floating installations gaining share fastest as reservoir projects proliferate across water-stressed regions.
End User:
Utility buyers command procurement scale and technical specification authority, while residential segments face distributed network constraints and interconnection queue delays that compress project timelines.
- Utilities:Centralized procurement offices rewrite technical specifications around bifacial gain coefficients and albedo assumptions rather than upfront capital expenditure. Long-term power purchase agreements in Spain and Brazil reward predictable performance guarantees that favor glass-glass durability.
- Commercial:Corporate offtakers under renewable energy credit mandates prioritize rapid deployment over maximum energy yield density. India's commercial and industrial tariff structures accelerate payback periods for rooftop bifacial installations in Gujarat and Maharashtra.
- Industrial:Heavy manufacturing facilities with flat roof structures and high electricity demand profiles.
- Residential:Homeowner associations and local permitting authorities impose aesthetic and setback restrictions.
Utilities dominate procurement volume, with commercial end users expanding most quickly as corporate renewable energy mandates tighten.
Application:
Utility-scale projects absorb module supply through multi-year procurement frameworks, while hybrid system configurations require inverter and storage co-certification that extends project development timelines.
- Utility Scale:Gigawatt-scale deployments concentrate margin pools through competitive auctions and long-term offtake contracts. India's SECI and NTPC tenders specify bifacial modules with minimum rear-side gain coefficients, while China's state-owned developers consolidate procurement through centralized frameworks.
- Hybrid Systems:Solar-plus-storage configurations optimize dispatchability and grid stability services. Australia's renewable energy zones and California's resource adequacy mandates drive fastest capacity expansion where battery cost declines enable viable merchant revenue stacking.
- Distributed Generation:Behind-the-meter installations serve commercial and industrial load centers without transmission access.
- Off-Grid:Remote mining camps and island microgrids prioritize reliability over levelized cost optimization.
Utility-scale application sits at the top of the volume ranking, with hybrid systems climbing the fastest as storage cost curves enable viable grid services revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's northwest desert solar bases anchor the global bifacial solar market, commanding the dominant share of module deployment and manufacturing capacity. Utility-scale developers in Qinghai and Xinjiang exploit high-albedo sand surfaces to maximize rear-side energy harvest. Regulatory tightening across Beijing, Brussels, and New Delhi is reshaping import competitiveness and domestic manufacturing incentives.
China
Beijing's dual carbon goals drive gigawatt-scale deployments across the Gobi and Tengger deserts where bifacial modules capture reflected irradiance from high-albedo sand surfaces. MIIT enforcement of GB/T 37408 testing standards mandates rear-side irradiance measurement protocols for all domestic module shipments. Qinghai and Xinjiang provinces concentrate manufacturing clusters where state-owned developers consolidate procurement through centralized frameworks.
India
Rajasthan and Gujarat solar parks absorb dominant procurement volumes as developers chase long-term power purchase agreements with bifacial performance guarantees. BIS certification requirements and PLI scheme incentives tilt domestic cell capacity expansion toward bifacial architectures. The state's renewable energy zones in Bhadla and Pavagada demonstrate fastest capacity expansion where high-albedo terrain maximizes rear-side energy yield.
United States
Texas and California utility-scale developers rewrite technical specifications around bifacial gain coefficients rather than upfront capital expenditure. FERC interconnection queue reforms and IRA production tax credits accelerate project commissioning timelines for glass-glass module deployments. The ERCOT grid zone and California's Central Valley concentrate procurement activity where tracking systems optimize bifacial harvest factors.
Germany
Agrivoltaic installations across Bavaria and Baden-Württemberg exploit elevated mounting and ground reflectivity to boost bifacial harvest factors over agricultural land. EU Green Deal carbon border adjustments reshape import competitiveness for non-European module suppliers with cleaner production footprints. The Fraunhofer ISE testing laboratories in Freiburg anchor European certification protocols for rear-side performance validation.
Japan
Reservoir floating solar projects at Yamakura Dam and coastal installations exploit water surface reflectivity to achieve premium bifacial gain coefficients. METI feed-in tariff revisions prioritize energy yield density over module cost in procurement evaluations. Kyushu and Chubu regions demonstrate fastest capacity expansion where land scarcity blocks conventional ground-mounted alternatives.
Bifacial Solar Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers race to capture utility-scale procurement volumes. The vendor base stratifies between vertically integrated cell-to-module producers and specialized glass-glass fabricators. Three archetypes define competitive positioning: scale-driven Chinese conglomerates with captive polysilicon supply, technology-focused specialists in tunnel oxide passivated contact architectures, and regional assemblers serving protected domestic markets. M&A activity and strategic technology licensing agreements concentrate margin pools among firms with pre-certified testing capabilities.
Among Chinese manufacturers, JA Solar Technology Co., Ltd. and LONGi Solar occupy positions within the scale-driven tier, exemplifying backward integration into polysilicon and wafer production. Trina Solar represents the technology-specialist archetype, anchoring competitive positioning through floating and agrivoltaic application expertise. These firms sit within a broader ecosystem where glass-glass durability and TOPCon cell metallization separate premium-tier suppliers from commodity assemblers competing on procurement auction price alone.
| Leading Market Players |
|---|
| JA Solar Technology Co., Ltd. |
| Risen Energy |
| LONGi Solar |
| Huasun Energy |
| Sharp Corporation |
| Trina Solar |
| Jinko Solar |
| Suntech Power |
| Canadian Solar |
| Others |
Supply Flow & Price Mechanics
Utility-scale procurement offices in China and India command dominant pricing power through multi-gigawatt competitive auctions, compressing module margins and forcing manufacturers toward cost-plus contract structures with performance-linked escalators.
Pricing Analysis
Distributor margins in glass-glass module channels absorb 8-12% of landed cost, while direct-to-utility frameworks eliminate intermediaries entirely. Three-tier pricing structure across premium, standard, and economy levels separates TOPCon-certified suppliers from PERC legacy stock and unbranded import alternatives. Pricing pressure stems from polysilicon input volatility and auction-driven procurement in Rajasthan and Qinghai. Distributed generation buyers in commercial rooftop segments exhibit highest price sensitivity, whereas floating solar developers prioritize energy yield density over unit cost.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale buyer demand across China's northwest desert bases, bypassing traditional distribution layers. Manufacturing concentration centers on China, Vietnam, and Malaysia, with polysilicon feedstock drawing from Xinjiang and Inner Mongolia smelters. Module assembly relies on tempered glass from float-glass producers, EVA encapsulant from petrochemical derivatives, and aluminum framing from smelter complexes. Single-source vulnerability in high-purity polysilicon creates procurement risk during energy-intensive production curtailments. Distribution runs through state-owned developer frameworks in China and competitive tender platforms in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's MIIT enforcement of GB/T 37408 bifacial testing standards and the EU Green Deal's carbon border adjustments are accelerating technology transitions and reshaping import competitiveness.
For Market Incumbents: To counter TOPCon cell displacement of PERC architectures, accelerate backward integration into tunnel oxide passivated contact cell capacity and secure pre-certified testing laboratory accreditation through BIS or TÜV Rheinland partnerships. Lock in long-term polysilicon offtake agreements with Xinjiang-based smelters to buffer raw material volatility and defend margin position against commodity assemblers. For New Entrants and Emerging Players: India's PLI scheme in Rajasthan and Gujarat opens a window for domestic cell capacity entry with bifacial architecture specialization. Target floating solar EPC partnerships in Japan's reservoir projects and Brazil's hydroelectric dam complexes where installation expertise gaps create white-space opportunity. Pursue agrivoltaic certification in Germany's Bavaria region to bypass saturated utility-scale procurement channels. For Investors and Strategic Acquirers: State-owned energy developers in China and Middle East sovereign wealth funds are the most active acquirers in this space, consolidating module manufacturing assets with captive project pipelines. Long-term viability hinges on technology differentiation rather than pure scale, favoring targets with TOPCon cell metallization IP and floating solar mooring system integration capabilities. Monitor IEC standard harmonization progress on rear-side irradiance measurement protocols as inflection indicator for bankability premium capture.| Strategic Initiative | Industry Significance |
|---|---|
| TOPCon Cell Capacity Buildout | Tunnel oxide passivated contact architecture reduces rear-side recombination losses critical to bifacial gain coefficients in desert deployments. |
| Glass-Glass Module Certification Program | IEC 61215 dual-glass validation extends product warranties to 30 years, unlocking project finance terms in harsh climate zones. |
| Floating Solar Mooring Partnership | Specialized corrosion-resistant hardware integration captures premium engineering margins in Japan's Yamakura Dam reservoir expansion. |
| Carbon Border Adjustment Compliance | EU Green Deal import tariff alignment reshapes competitiveness for Chinese suppliers with cleaner production footprints. |
| Agrivoltaic Installation Expertise | Elevated mounting systems over agricultural land in France and Germany exploit ground reflectivity for bifacial harvest optimization. |
Methodological Framework
Coverage spans China, India, the United States, Germany, and Japan, with primary inputs from each market triangulated against secondary validation. Primary interviews engaged utility procurement officers, EPC contractors, module manufacturing executives, and grid interconnection specialists across the five core geographies. Secondary sources incorporated MIIT GB standard filings, BIS certification registries, FERC interconnection queue data, EU Green Deal regulatory texts, and IEA solar deployment tracking. Bottom-up module shipment data from regional port customs records reconciled with top-down capacity installation figures from national renewable energy agencies.
Rate-of-change decomposition across the analysis window isolated volume drivers by installation type, cell architecture transition timing, and regulatory enforcement phasing. Segmentation modeling captured product type bifurcation between glass-glass and glass-film constructions, installation category splits across ground-mounted, floating, and rooftop applications, and end-user procurement behavior variations between utilities and commercial offtakers. CAGRs derived from polynomial curve fitting of historical deployment trajectories adjusted for policy discontinuity risks and technology substitution elasticities. Key forecast inputs included albedo modeling standard adoption curves and rear-side performance guarantee penetration rates in project finance documentation.
Revisions become necessary when IEC harmonization on bifacial testing protocols stalls, carbon border adjustment implementation timelines shift, or polysilicon supply disruptions exceed 90-day inventory buffers. Forecasts reflect base-case assumptions regarding MIIT enforcement continuity and PLI scheme renewal probability in India. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Rooftop Solar Photovoltaic (PV) Installation Market
Solar Power Systems
Solar Backsheet Market
Solar Power Systems
Solar PV Module Market
Solar Power Systems
Global Thin Film Solar Cells Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Solar Photovoltaic (PV) Market
Solar Power Systems
Bifacial Solar Module Market
Solar Power Systems
Solar Power Bank Market
Solar Power Systems
Australia Rooftop Solar Market
Solar Power Systems
Portugal Distributed Solar Energy Market
Solar Power Systems
US Solar Tracker Market
Solar Power Systems
Polycrystalline Solar Cell Market
Solar Power Systems
Photovoltaic Mounting System Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
United Arab Emirates Solar Energy Market