
 Philippines Solar Energy Market | 2026-2036
Philippines Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Philippines Solar Energy Market Outlook
Performance-based operations and maintenance contracts is restructuring how solar assets generate recurring revenue in the Philippines. ACEN Corp. leverages its nationwide land-bank to sustain utility-scale development across multiple provinces. Solar Philippines Power Project Holdings anchors domestic module assembly capacity, reducing import dependency for large installations. Vena Energy competes through its experience financing and operating projects under the country's feed-in tariff and auction regimes.
Philippines solar energy encompasses photovoltaic systems that convert sunlight into electricity through semiconductor cells, typically silicon-based modules with conversion efficiencies ranging from 19% to 22% for monocrystalline designs, deployed to displace coal and diesel generation across an archipelago with high electricity tariffs. Photovoltaic modules dominate capital expenditure, while bifacial technology is gaining share in ground-mount applications where albedo reflection boosts yield. The industrial application segment is expanding fastest as factories seek to offset some of the highest power rates in Southeast Asia, whereas off-grid installations serving island communities represent a specialized margin pool with distinct financing structures.
The Department of Energy's Renewable Energy Act implementing rules and the ERC's feed-in tariff framework shape project economics and grid-access rights for developers. BIS-equivalent product certification requirements and the Philippine Grid Code standards enforced by the National Grid Corporation govern equipment eligibility and interconnection protocols. Stakeholders must monitor auction schedule volatility and transmission queue bottlenecks that determine which project pipelines secure offtake certainty.
Market Dynamics
The Department of Energy's Green Energy Auction Program is restructuring competitive procurement for utility-scale solar, compressing margins for developers while accelerating deployment timelines across Luzon's industrial corridor.
Growth Catalysts
- Feed-in Tariff Framework:The ERC's renewable energy pricing mechanism guarantees long-term revenue certainty for qualified projects, attracting institutional capital to utility-scale development.
- Industrial Electrification:Manufacturing facilities in Calabarzon are deploying rooftop photovoltaic systems to offset electricity tariffs that rank among Southeast Asia's highest.
- Bifacial Module Adoption:Ground-mount installations incorporating dual-sided panels are capturing albedo reflection from reflective surfaces, boosting energy yield per hectare.
Market Restraints
- Polysilicon Supply Concentration:Philippine developers remain exposed to input cost volatility from Chinese polysilicon refiners who control upstream crystalline silicon production.
- Transmission Queue Bottlenecks:The National Grid Corporation's interconnection approval timelines extend project commissioning schedules beyond original financial models.
- Diesel Generator Substitution:Off-grid island communities continue relying on liquid fuel backup systems due to storage cost barriers for battery-coupled solar.
Strategic Opportunities
- Visayas Archipelago Expansion:Underpenetrated island provinces present untapped demand for distributed generation serving tourism and fishing cooperatives.
- Agricultural Solar Integration:Agrivoltaic deployments combining photovoltaic canopies with high-value crop cultivation are opening dual-revenue streams for landowners.
- Green Bond Financing:The central bank's sustainable finance framework is channeling institutional capital toward certified renewable infrastructure.
Industry Challenges
- Grid Code Certification Delays:BIS-equivalent testing requirements for inverter and module compliance extend equipment procurement timelines by multiple quarters.
- Specialized Technician Scarcity:The domestic workforce lacks sufficient certified electricians trained to high-voltage direct current installation standards required for utility-scale fields.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Philippines Solar Energy Market |
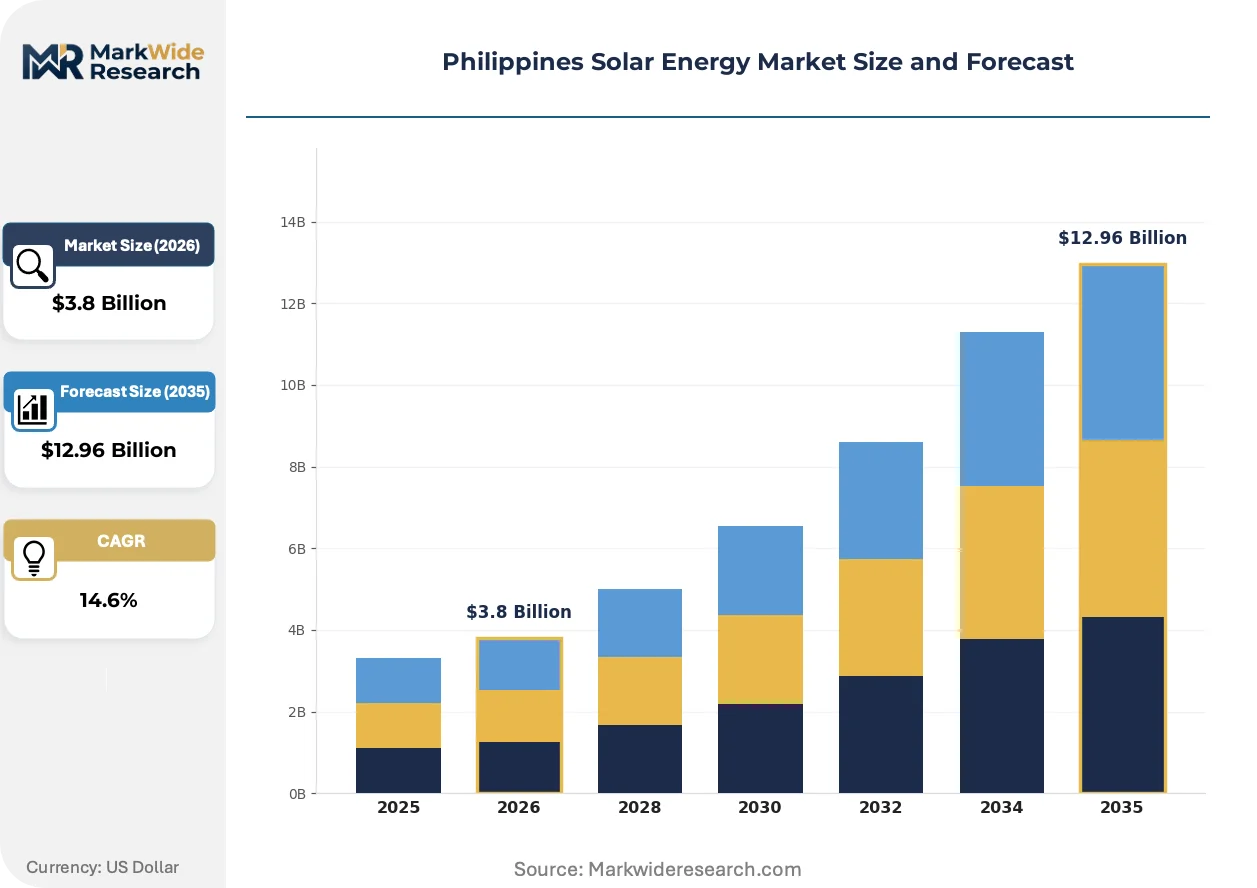
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Modules, Inverters, Mounting Systems, Batteries Application: Residential, Commercial, Industrial, Off-Grid Technology: Monocrystalline, Polycrystalline, Thin Film, Bifacial End User: Utilities, Homeowners, Businesses, Government |
| Companies Covered | Solar Philippines Power Project Holdings, ACEN Corp., Vena Energy, Citicore Power Inc., Aboitiz Power Corp., Meralco PowerGen, San Miguel Corporation, First Gen Corporation, SP New Energy Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Philippines Solar Energy Market Strategic Shifts
Philippine solar deployment is pivoting from subsidy-dependent feed-in tariffs toward merchant and corporate offtake structures, with technology choices and financing models adapting to price exposure.
Monocrystalline PERC technology is absorbing market share from legacy multicrystalline designs as module efficiencies climb toward 22% in commercial applications. Cold-storage operators and semiconductor fabs in Laguna are specifying these higher-conversion panels to maximize generation per limited rooftop area. This efficiency race is compressing viable project sizes and reshaping site selection criteria toward premium irradiance locations.
The Department of Energy's implementing rules for the Renewable Energy Act are mandating competitive auction participation for utility-scale capacity allocation. Developers must now bid strike prices below historical feed-in tariff levels to secure offtake contracts, forcing capital structure optimization and equipment sourcing discipline. Luzon-based independent power producers are responding by consolidating land positions to achieve economies of scale.
Corporate power purchase agreements are displacing traditional utility procurement for industrial offtakers seeking price hedges against volatile spot market rates. Food processing and electronics manufacturing facilities in Batangas are contracting directly with solar developers for behind-the-meter supply or virtual wheeling arrangements. This bilateral contracting trend is most visible in the Calabarzon industrial corridor where tariff sensitivity intersects with sustainability commitments.
Philippines Solar Energy Market Segmentation
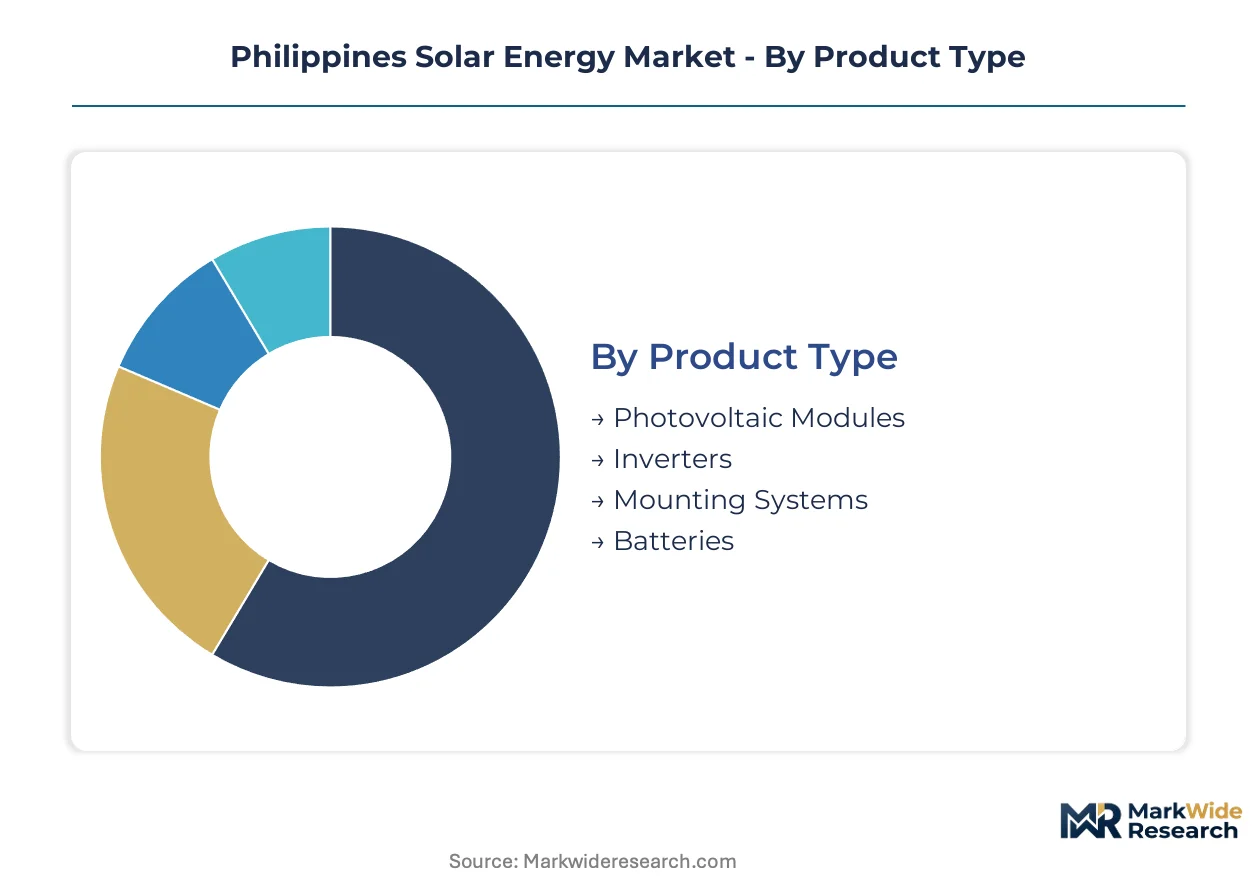
Segmentation in the Philippines solar market reveals how capital allocation and policy incentives concentrate across distinct technology and customer configurations. Equipment choices and offtake structures diverge sharply between grid-connected utility projects and distributed island installations.
Product Type:
Volume deployment concentrates in standardized module and inverter categories, while premium capture sits with integrated storage systems serving reliability-sensitive loads.
- Photovoltaic Modules:Silicon-based semiconductor panels with conversion efficiencies between 19% and 22% for monocrystalline designs dominate capital expenditure in Luzon utility-scale fields. Demand clusters in Batangas and Laguna provinces where industrial offtakers specify high-efficiency units to maximize generation per hectare.
- Inverters:Power electronics converting direct current module output to grid-compliant alternating current, with string and central configurations selected based on project scale. Procurement concentrates among developers bidding the Department of Energy's Green Energy Auction Program where equipment certification delays determine commissioning schedules.
- Mounting Systems:Structural hardware securing panels to rooftops or ground-mount foundations, with fixed-tilt designs prevailing in cost-optimized utility projects across the Calabarzon corridor.
- Batteries:Lithium-ion storage systems enabling dispatchable solar supply, penetrating fastest in off-grid island communities where diesel substitution economics justify premium pricing.
Mature deployment sits with photovoltaic modules and inverters. Newer deployment is concentrated in batteries where financing structures for island microgrids are still standardizing.
Application:
Revenue scale tilts toward industrial and utility-scale installations, while margin structure favors specialized off-grid configurations with captive offtake terms.
- Residential:Distributed rooftop systems serving individual households, typically sub-10 kilowatt installations net-metered against distribution utility bills. Adoption concentrates in Metro Manila subdivisions where homeowners leverage financing from the central bank's sustainable lending framework.
- Commercial:Mid-scale rooftop and ground-mount systems serving retail, hospitality, and logistics facilities. Cold-storage operators in Laguna specify these configurations to offset electricity tariffs ranking among Southeast Asia's highest.
- Industrial:Large-format installations directly supplying manufacturing loads through behind-the-meter or virtual wheeling arrangements. Semiconductor fabs and food processors in Batangas anchor this segment through corporate power purchase agreements displacing traditional utility procurement.
- Off-Grid:Standalone systems serving island communities beyond transmission infrastructure reach, combining solar generation with battery storage and diesel backup. Tourism cooperatives in the Visayas archipelago present untapped demand where storage cost barriers are gradually compressing.
Industrial applications are climbing the fastest as manufacturing facilities seek price hedges against volatile spot market rates. Residential deployment remains constrained by financing access and roof ownership patterns.
Technology:
Efficiency tiering separates premium monocrystalline and bifacial products from legacy polycrystalline and thin-film alternatives.
- Monocrystalline:Single-crystal silicon cells achieving 20-22% conversion efficiency in commercial modules, specified by space-constrained industrial rooftops in Calabarzon. PERC architecture variants are absorbing market share from legacy designs.
- Polycrystalline:Multi-crystal silicon cells with lower efficiency but historical cost advantage, now retreating to price-sensitive distributed applications as monocrystalline manufacturing scales.
- Thin Film:Cadmium-telluride or amorphous silicon layers deposited on flexible substrates, penetrating niche building-integrated applications where weight and form factor override efficiency metrics.
- Bifacial:Dual-sided panels capturing direct irradiance plus ground-reflected albedo, gaining share in ground-mount utility projects across Luzon where reflective surfaces boost yield per hectare.
Polycrystalline deployment represents the most mature installed base. Bifacial configurations are gaining share fastest as developers optimize land-bank productivity.
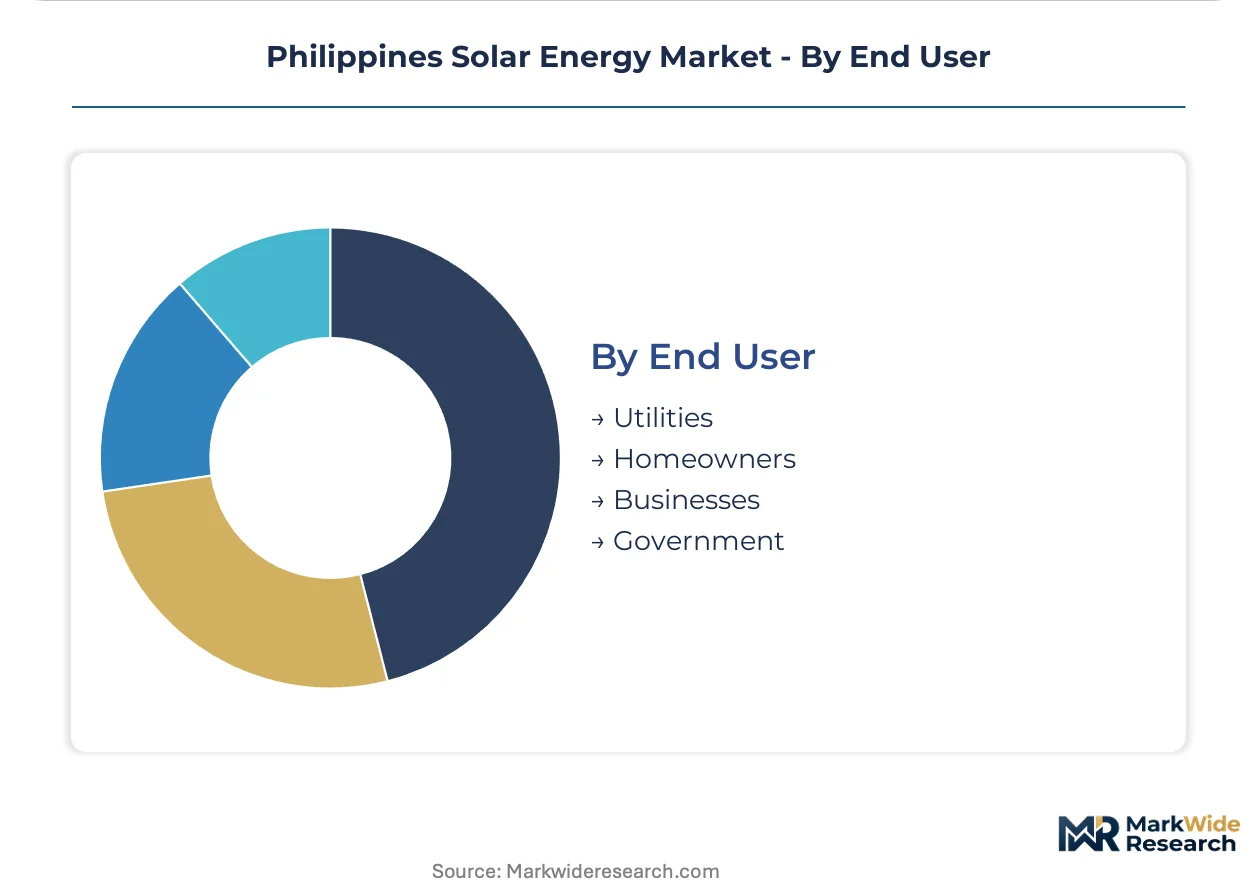
End User:
Procurement authority and offtake certainty distinguish utility-scale developers from distributed customer segments.
- Utilities:Grid operators and independent power producers contracting capacity through the Department of Energy's auction mechanism, with ACEN Corp. and Vena Energy competing for allocation.
- Homeowners:Individual retail customers financing rooftop systems through net metering, concentrated in urban centers with distribution utility interconnection access.
- Businesses:Commercial and industrial entities contracting directly with developers for behind-the-meter supply, with manufacturing facilities in Laguna and Batangas driving bilateral agreement volume.
- Government:Public sector procurement for rural electrification, agricultural solar integration, and municipal facility deployment, channeling development finance toward island provinces.
Utility procurement sits with the most mature auction mechanisms. Business direct contracting is expanding most quickly as corporate sustainability commitments intersect with tariff sensitivity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Philippines generates solar capacity across a production-consumption divide: Luzon hosts most utility-scale installations while demand concentrates in industrial corridors distant from optimal irradiance zones. Sub-regional deployment patterns reflect transmission infrastructure, land availability, and offtake proximity.
Luzon
Industrial load centers in Calabarzon drive demand for utility-scale and distributed solar. The Department of Energy's Green Energy Auction Program channels capacity allocation toward Batangas and Laguna provinces. Semiconductor fabs and cold-storage operators in these provinces contract directly with developers for behind-the-meter supply.
Visayas
Tourism cooperatives and fishing communities create specialized demand for off-grid and battery-coupled systems. The National Grid Corporation's interconnection limitations force island provinces toward distributed generation architectures. Cebu and Iloilo present emerging utility-scale opportunities as transmission backbones expand.
Mindanao
Agricultural solar integration gains traction among banana and pineapple plantation operators seeking dual-revenue land use. The Mindanao grid's isolation from Luzon-Visayas interconnection creates distinct procurement dynamics. Davao del Sur hosts early agrivoltaic pilots combining photovoltaic canopies with high-value crop cultivation.
Metro Manila
Residential rooftop adoption concentrates in subdivisions with net-metering access and sustainable finance availability. The Energy Regulatory Commission's distribution utility interconnection rules shape deployment feasibility. Quezon City and Pasig anchor commercial rooftop activity among retail and logistics facilities.
Philippines Solar Energy Market Competitive Environment
Capital-heavy asset owners compete with development specialists who secure land and permits without owning generation equipment. The market structure tilts toward integrated utilities and independent power producers with balance-sheet capacity to absorb long-dated auction commitments. Three archetypes dominate: nationwide land-bank holders, auction regime specialists, and conglomerate-affiliated gencos. Competitive positioning depends on transmission queue access and offtake contract duration rather than manufacturing scale.
Among Philippine-based developers, Solar Philippines Power Project Holdings and ACEN Corp. occupy positions anchored by land-bank scale and utility relationships. Vena Energy exemplifies the auction-specialist archetype through its experience across feed-in tariff and competitive bidding regimes. These three entities represent distinct capital structure approaches to the Green Energy Auction Program's margin-compressed procurement environment.
| Leading Market Players |
|---|
| Solar Philippines Power Project Holdings |
| ACEN Corp. |
| Vena Energy |
| Citicore Power Inc. |
| Aboitiz Power Corp. |
| Meralco PowerGen |
| San Miguel Corporation |
| First Gen Corporation |
| SP New Energy Corp. |
| Others |
Value Chain & Pricing Dynamics
Bifacial-monocrystalline efficiency premiums against polycrystalline commodity tiers manifest in divergent procurement strategies across Luzon's auction-driven utility sector and Visayas island microgrids. The Department of Energy's Green Energy Auction Program compresses strike-price bids while Chinese polysilicon refiners concentrate upstream crystalline silicon supply, forcing developers to optimize module sourcing against certification timelines and grid-code compliance costs.
Pricing Analysis
Margin tightening in utility-scale segments reflects auction-strike compression below historical feed-in tariff benchmarks as developers bid for Department of Energy capacity allocation. Three-tier pricing structure across premium monocrystalline PERC, standard monocrystalline, and residual polycrystalline inventory tracks conversion efficiency and BIS-equivalent certification status. Industrial offtakers in Calabarzon demonstrate lowest price sensitivity due to tariff hedge priorities, while rural electric cooperatives in the Visayas archipelago face acute budget constraints for battery-coupled systems. Cost-down pressure on polycrystalline modules accelerates because manufacturing scale advantages have shifted entirely to monocrystalline PERC architecture.
Supply Chain Analysis
Polysilicon supply rests on Chinese refiners controlling upstream crystalline silicon production, with module assembly concentrated in China, Southeast Asia, and domestic facilities anchored by Solar Philippines Power Project Holdings. Lithium-ion battery cells, power electronics, and tracking hardware draw from South Korean and Japanese specialty manufacturers. Single-source vulnerability sits with polysilicon price volatility transmitted through long-term module supply contracts. Distribution runs through engineering-procurement-construction contractors bidding National Grid Corporation interconnection queues, with equipment procurement timelines extending multiple quarters due to BIS-equivalent testing requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Philippines solar market remains supply-constrained by transmission queue bottlenecks at the National Grid Corporation, where interconnection approval timelines prop pricing premiums for queue-positioned developers.
For Market Incumbents: Anchor land-bank consolidation in Luzon's Calabarzon corridor to defend against emerging auction specialists bidding strike prices below feed-in tariff historicals. Prioritize backward integration into domestic module assembly capacity to offset Chinese polysilicon price volatility. Secure early-mover positions in agrivoltaic pilots across Mindanao before plantation operators diversify land-use revenue streams. For New Entrants and Emerging Players: Bifacial tracking technology optimized for high-albedo ground-mount sites offers a technology-first wedge against fixed-tilt incumbents constrained by legacy procurement specifications. Target Visayas tourism cooperatives and fishing communities where distributed generation financing structures remain understandardized. Lead with battery-coupled island microgrid proposals leveraging the central bank's sustainable finance framework for development capital access. For Investors and Strategic Acquirers: Exit pathways concentrate in auction-regime specialists with demonstrated strike-price discipline and transmission queue positioning. Long-term viability favors developers with 5-10 year land-lease tenures and corporate power purchase agreement backlogs. Monitor Department of Energy auction schedule volatility as the primary inflection indicator for pipeline valuation compression.| Strategic Initiative | Industry Significance |
|---|---|
| Transmission Queue Positioning | Early interconnection approval at National Grid Corporation secures offtake certainty before auction bid deadlines. |
| Domestic Module Assembly Scale-Up | Captive production capacity reduces import dependency and BIS-equivalent certification timeline exposure. |
| Corporate PPA Origination | Direct bilateral contracts with Batangas semiconductor fabs displace volatile spot market exposure. |
| Agrivoltaic Pilot Development | Dual-revenue land use in Davao del Sur opens plantation operator relationships beyond pure energy offtake. |
| Island Microgrid Financing | Central bank sustainable lending framework channels institutional capital toward Visayas distributed generation. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, combined with primary interviews across utility planning officers, independent power producer project developers, engineering-procurement-construction contractors, National Grid Corporation interconnection specialists, and polysilicon procurement leads. Secondary validation drew from Department of Energy auction announcements, Energy Regulatory Commission feed-in tariff determinations, Philippine Grid Code compliance databases, and import records for photovoltaic module and inverter equipment. Bottom-up project pipeline aggregation and top-down capacity installation tracking provided cross-verification.
Data-stream reconciliation across installation databases, auction award registries, and corporate disclosure filings shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include technology efficiency tier, application scale, end-user procurement authority, and regional grid interconnection status. CAGRs derived from capacity deployment trajectories, auction schedule density, and industrial electricity demand elasticity across the Calabarzon corridor. Forecast inputs incorporated polysilicon price index movements and transmission infrastructure buildout timelines.
Several conditions sit outside the modeled scope, including unannounced regulatory amendments to the Renewable Energy Act implementing rules, force majeure disruptions to Chinese polysilicon supply, and abrupt shifts in central bank sustainable finance eligibility criteria. Forecasts reflect documented assumptions regarding auction participation rates and corporate power purchase agreement execution velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Panel Lights Market
Solar Power Systems
Solar Module Market
Solar Power Systems
Agriculture Solar Water Pumps Market
Solar Power Systems
Solar Shingles Market
Solar Power Systems
Solar Photovoltaic (PV) Panel Market
Solar Power Systems
United Kingdom Photovoltaic Mounting System Market
Solar Power Systems
Switzerland Solar Energy Market
Solar Power Systems
Venezuela Solar Energy Market
Solar Power Systems
Solar Photovoltaic Material Market
Solar Power Systems
Smart Solar Tracker Market
Solar Power Systems
Solar Photovoltaic Modules Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Europe Solar Microinverter Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
New Zealand Solar Energy Market
Solar Power Systems
Thin Film Solar PV Market