
 Europe Soda Ash Market | 2026-2036
Europe Soda Ash Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Soda Ash Market Intelligence
Aftermarket technical service revenue for soda ash handling and dosing systems is fragmenting as buyers internalize maintenance competencies and third-party providers multiply. Solvay leverages its integrated European logistics network to sustain premium positioning in specialty grades. CIECH S.A. anchors its competitive stance through backward integration into salt mining and energy co-generation assets. Tata Chemicals Limited competes on scale economics by operating one of the continent's largest dense soda ash production lines.
Europe soda ash, chemically sodium carbonate (Na₂CO₃) with purity grades ranging from 99.0% to 99.8%, derives primarily from the Solvay ammonia-soda process and natural trona refining; its primary commercial purpose centers on glass melt fluxing, where it lowers silica melting temperatures by 300-400°C and controls thermal expansion coefficients. Dense soda ash commands the dominant volume position across flat glass and container glass applications, while specialty soda ash carries the highest margin concentration due to stringent impurity thresholds in pharmaceutical and food-grade specifications. Light soda ash retains structural importance in detergent formulation, though powder compaction technologies are gradually displacing traditional grades in concentrated laundry products.
The EU Emissions Trading System and REACH chemical registration framework jointly elevate compliance costs for synthetic producers, advantaging natural soda ash sourced from lower-carbon trona deposits. ECHA's evolving classification criteria for sodium carbonate dust exposure are tightening workplace handling standards and reshaping packaging specifications toward sealed bulk systems. Stakeholders must monitor carbon border adjustment implementation timelines and assess whether captive renewable energy integration can preserve cost parity for Solvay-process plants against imported natural material.
Market Dynamics
Carbon border adjustment mechanisms under the EU Green Deal are redirecting capital flows across the European soda ash landscape, advantaging natural trona-based production routes over Solvay-process synthetic capacity.
Growth Catalysts
- Flat glass manufacturing:Automotive and construction sectors across Germany, Italy, and Poland continue absorbing rising dense soda ash volumes for float glass production lines.
- EU Emissions Trading System:Compliance cost differentials are accelerating plant modernization investments, particularly at synthetic production facilities seeking carbon efficiency upgrades.
- Container glass demand:Beverage packaging recyclability mandates under the Packaging and Packaging Waste Regulation are reinforcing domestic glass melt requirements.
Market Restraints
- Energy cost volatility:Natural gas price exposure at Solvay-process plants compresses margin stability against imported natural soda ash from lower-carbon trona deposits.
- Supply concentration risk:Dense soda ash production clusters in Belgium and Poland create geographic vulnerability to single-point logistics disruptions.
- Detergent formulation substitution:Powder compaction technologies and liquid concentrate formats are displacing traditional light soda ash demand in household cleaning applications.
Strategic Opportunities
- Eastern European glass capacity:Underpenetrated container glass manufacturing in Romania and Bulgaria offers expansion corridors for dense soda ash offtake growth.
- Pharmaceutical-grade specialization:REACH-compliant high-purity grades command premium positioning as EMA standards tighten impurity thresholds for sodium carbonate excipients.
- Renewable energy integration:Captive solar and wind power installations at production sites can restore cost parity for synthetic producers against carbon-adjusted imports.
Industry Challenges
- Process engineering expertise:Scarcity of ammonia-soda process specialists constrains operational optimization and technology transfer at legacy production facilities.
- Multi-jurisdictional compliance:Divergent ECHA classification timelines across EU member states complicate unified packaging and handling standard implementation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Soda Ash Market |
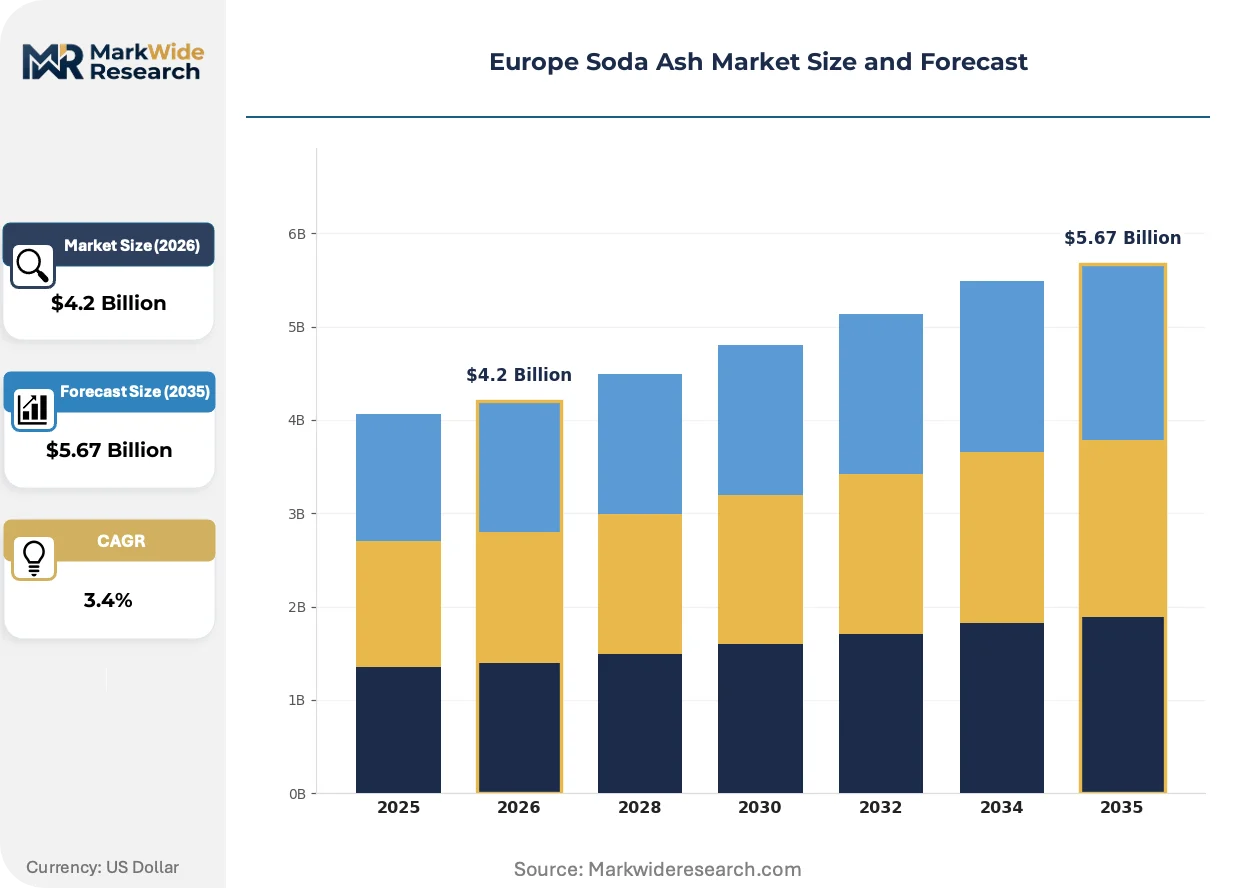
| Market Size in 2026 | $4.2 Billion |
| Market Size in 2035 | $5.67 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Carbonate, Dense Soda Ash, Light Soda Ash, Specialty Soda Ash End User: Glass Manufacturing, Chemical Production, Detergents, Agriculture Application: Flat Glass, Container Glass, Ceramics, Water Treatment Packaging Type: Bulk Bags, Bags, Drums, Containers |
| Companies Covered | Bashkir Soda Company JSC, Tronox Ltd., Solvay, Tata Chemicals Limited, Croda International, BASF SE, CIECH S.A., Zagros Petrochemical Company, We Soda Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Soda Ash Market Strategic Shifts & Innovations
Digital process control systems and closed-loop manufacturing architectures are compressing energy intensity benchmarks while reshaping quality assurance protocols across European soda ash operations.
Advanced process control software is virtualizing traditional manual oversight of Solvay reactor conditions, enabling real-time optimization of ammonia recovery cycles. Container glass producers in Spain and Portugal are deploying these systems fastest, drawn by energy cost reduction targets. This virtualization is compressing the performance gap between synthetic and natural production routes on carbon intensity metrics.
REACH chemical registration frameworks are tightening workplace exposure limits for sodium carbonate dust, mandating sealed bulk handling systems over conventional bagged distribution. ECHA's evolving classification criteria are forcing packaging redesign investments across synthetic production networks. Specialty-grade suppliers serving pharmaceutical and food applications face the steepest compliance timelines.
Glass manufacturers are consolidating supplier relationships around long-term offtake agreements with embedded carbon accounting, displacing spot-market purchasing patterns. This concentration is most visible in Germany's automotive glass cluster, where flat glass producers now prioritize single-source partnerships with verified low-emission credentials. The shift is compressing margins for traders lacking direct production asset backing.
Europe Soda Ash Market Segmentation
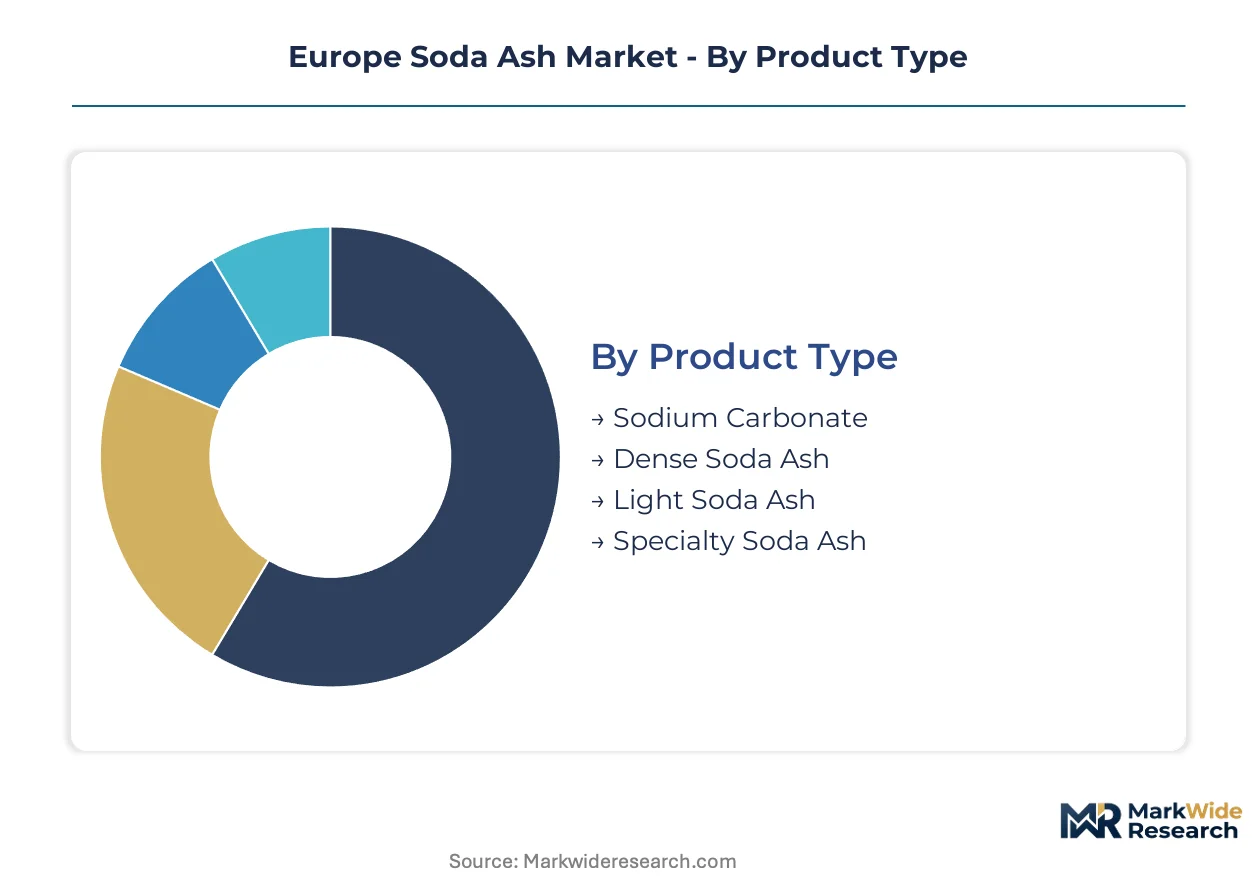
Product differentiation across density grades and purity specifications shapes procurement patterns in European soda ash. Glass manufacturers, chemical processors, and detergent formulators each impose distinct technical requirements that fragment supply contracts and pricing structures.
Product Type:
Density and purity specifications define the use-case spectrum from commodity glass fluxing to precision pharmaceutical applications.
- Dense Soda Ash:Higher bulk density (0.8-1.0 g/cm³) minimizes dust generation and improves flow characteristics in automated glass melt dosing systems. German flat glass plants along the Rhine corridor absorb the largest volumes, driven by automotive windshield production quotas and construction sector float glass demand. REACH compliance on dust exposure limits is accelerating sealed bulk system adoption.
- Light Soda Ash:Lower density (0.5-0.6 g/cm³) and higher porosity enable rapid dissolution in detergent slurry formulations. Polish and Romanian detergent manufacturers remain the primary offtakers, though powder compaction technologies are compressing traditional demand trajectories.
- Sodium Carbonate:Standard industrial grade serves chemical synthesis and water treatment applications with 99.0-99.2% purity thresholds. Italian chemical processors in the Po Valley cluster represent concentrated demand.
- Specialty Soda Ash:Ultra-high purity grades (99.8%+) with controlled heavy metal and chloride specifications serve pharmaceutical excipient and food additive applications. EMA impurity threshold tightening is expanding premium segment boundaries.
The dominant share belongs to Dense Soda Ash, while Specialty Soda Ash is expanding most quickly on regulatory tightening in pharmaceutical supply chains.
End User:
Customer type determines volume scale, contract duration, and technical service intensity across the value chain.
- Glass Manufacturing:Float glass and container glass producers command the largest single-industry offtake, with Belgian and Polish production clusters driving dense soda ash procurement. Long-term offtake agreements with embedded carbon accounting are displacing spot purchasing.
- Chemical Production:Sodium silicate and bicarbonate manufacturers require consistent alkali supply for continuous process operations. German and Dutch chemical corridors anchor regional demand concentration.
- Detergents:Powder and liquid formulation plants source light soda ash for pH adjustment and builder functions. Iberian Peninsula facilities are transitioning fastest to concentrated liquid formats.
- Agriculture:pH correction in soil amendment and animal feed applications represents a price-sensitive fringe segment with seasonal procurement patterns.
Glass Manufacturing holds the volume leadership position, though Chemical Production is climbing the fastest on downstream sodium derivative expansion.
Application:
Process temperature and thermal expansion requirements create distinct specification boundaries across material science applications.
- Flat Glass:Architectural and automotive glazing demand soda ash for silica fluxing at 1400-1500°C melt temperatures. German and Italian automotive glass clusters prioritize verified low-emission supply credentials.
- Container Glass:Beverage bottle and jar production requires controlled thermal expansion coefficients for mechanical durability. Polish and Spanish container plants are consolidating supplier relationships around single-source partnerships.
- Ceramics:Glaze formulation and body fluxing in tile and sanitary ware manufacturing uses lower-purity grades. Italian ceramic districts in Emilia-Romagna represent geographic demand concentration.
- Water Treatment:pH adjustment and softening applications in municipal and industrial water systems favor cost-optimized bulk supply.
Flat Glass commands the premium pricing tier, while Container Glass is gaining share fastest on packaging recyclability mandates under EU regulation.
Packaging Type:
Handling automation and workplace exposure controls are reshaping packaging specifications across distribution channels.
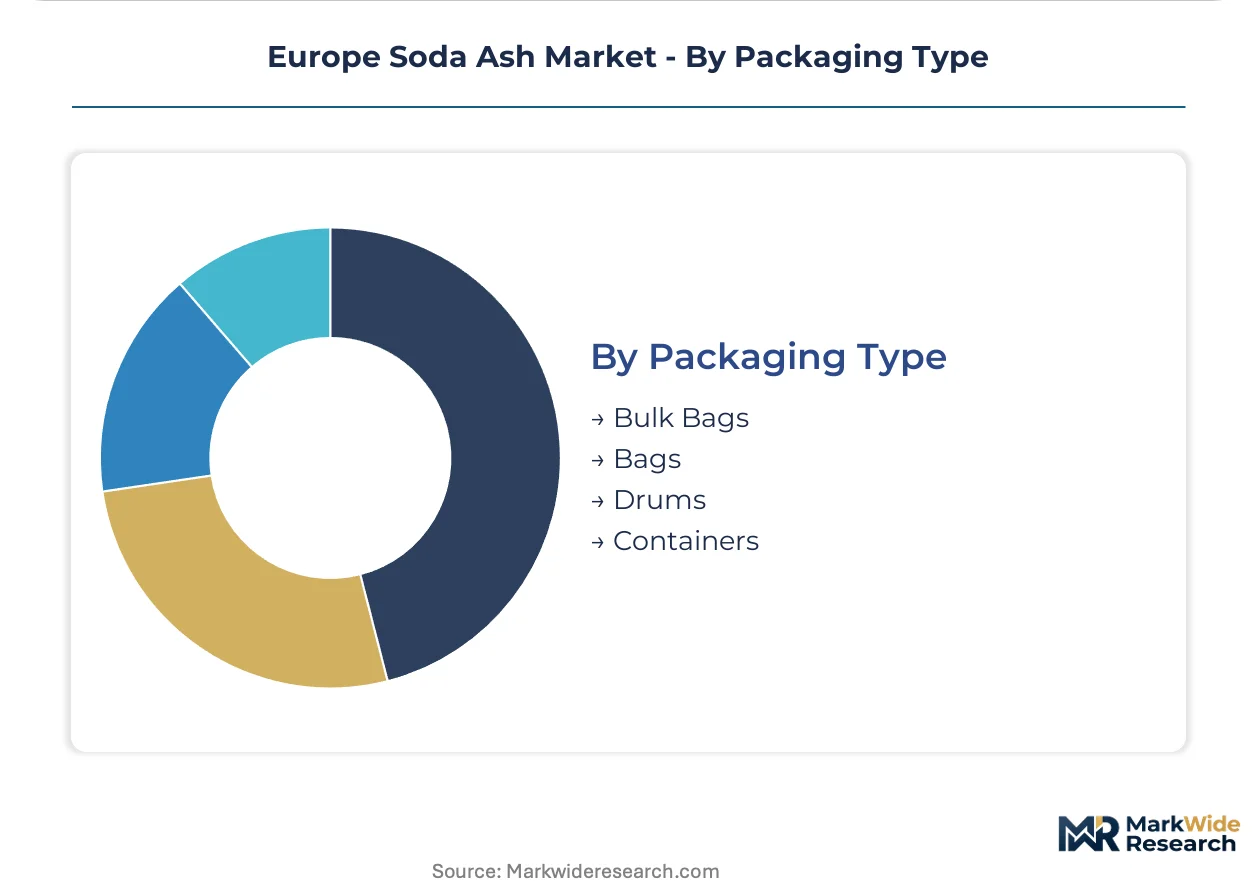
- Bulk Bags:One-tonne flexible intermediate bulk containers dominate glass plant intake, enabling pneumatic conveying and automated dosing. ECHA dust exposure classification tightening is mandating sealed discharge systems.
- Bags:25-50kg multi-wall paper or woven polypropylene sacks serve smaller chemical and detergent processors. REACH workplace handling standards are accelerating packaging redesign investments.
- Drums:Steel or fiber drums contain high-purity specialty grades for pharmaceutical and food applications requiring contamination protection.
- Containers:Intermediate bulk containers and tank trucks serve liquid soda ash solutions and large-volume water treatment applications.
Bulk Bags retain the dominant procurement format, though Bags are losing ground fastest to pneumatic bulk systems in modernized production facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Eastern Europe exhibit the sharpest price elasticity, while German automotive glass producers absorb premium costs for verified low-emission supply. This demand-elasticity contrast shapes regional procurement patterns across the continent.
Germany
Automotive windshield and architectural float glass plants along the Rhine corridor consume dense soda ash volumes well above regional averages. The EU Emissions Trading System compliance costs are accelerating modernization investments at synthetic production facilities. Stuttgart's automotive glass cluster now mandates single-source partnerships with carbon-accounted supply credentials.
Poland
Container glass manufacturing for beverage packaging drives dense soda ash offtake as recyclability mandates tighten under the Packaging and Packaging Waste Regulation. ECHA workplace exposure standards are forcing packaging redesign toward sealed bulk systems. The Silesian industrial basin anchors production concentration with modernized pneumatic conveying infrastructure.
Italy
Flat glass producers serving premium architectural glazing command premium pricing tiers for low-impurity dense grades. REACH chemical registration frameworks are elevating compliance costs for imported synthetic material. The Po Valley chemical processing corridor sustains consistent alkali demand from sodium silicate and bicarbonate manufacturers.
Belgium
Synthetic soda ash production clusters face margin compression from natural gas price volatility against lower-carbon trona imports. The EU Green Deal carbon border adjustment mechanisms are redirecting capital toward emission-reduction retrofits. Antwerp's integrated logistics hub enables premium positioning in specialty-grade distribution.
Spain
Container glass plants are consolidating supplier relationships fastest, displacing spot-market purchasing with long-term offtake agreements. Advanced process control software adoption is compressing energy intensity benchmarks at float glass facilities. Catalan producers lead deployment of virtualized reactor monitoring systems for ammonia recovery optimization.
Europe Soda Ash Market Key Industry Players
Capability concentration sits with integrated European producers commanding specialty-grade margins; scale advantage sits with large-volume synthetic operators. The market structures around three tiers: backward-integrated salt-to-soda ash producers, ammonia-soda process specialists with captive energy assets, and import-dependent traders lacking production backing. Dominant competitive moves include renewable energy integration to restore cost parity and long-term offtake agreements with embedded carbon accounting to lock glass manufacturer relationships.
Within the integrated European tier, Solvay and CIECH S.A. exemplify producers leveraging captive salt mining and energy co-generation infrastructure. Tata Chemicals Limited occupies a position at the scale-driven end with one of the continent's largest dense soda ash production lines. These three anchors illustrate how geographic integration and production scale define competitive positioning under tightening EU carbon regulations.
| Leading Market Players |
|---|
| Bashkir Soda Company JSC |
| Tronox Ltd. |
| Solvay |
| Tata Chemicals Limited |
| Croda International |
| BASF SE |
| CIECH S.A. |
| Zagros Petrochemical Company |
| We Soda Ltd |
| Others |
Cost & Logistics Intelligence
Overcapacity signals from Belgian Solvay-process plants are compressing spot-market premiums and forcing suppliers toward long-term offtake structures. This utilization pressure feeds directly into buyer leverage, as glass manufacturers consolidate procurement around carbon-accounted supply partnerships.
Pricing Analysis
Long-term offtake agreements with embedded carbon accounting now dominate procurement between dense soda ash producers and German automotive glass clusters. Price differentiation separates REACH-compliant specialty grades from standard industrial material, with heavy metal thresholds commanding substantial premiums. Cost compression in synthetic production runs through natural gas price exposure, while Eastern European container glass plants exhibit the sharpest price sensitivity. Belgian and Polish buyers absorb premium costs for verified low-emission credentials.
Supply Chain Analysis
Upstream salt and limestone feedstock availability centers on captive mining assets in Germany, Poland, and Romania. The production network draws from ammonia-soda process specialists and natural trona refiners, with energy co-generation infrastructure anchoring cost structures. Single-source vulnerability concentrates in the Silesian industrial basin, where pneumatic conveying infrastructure creates logistics chokepoints. Distribution runs through Antwerp's integrated logistics hub for specialty-grade distribution and sealed bulk systems for glass plant intake.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against liquid detergent concentrates and powder compaction technologies displacing traditional light soda ash demand. Incumbents must navigate this structural threat while reinforcing carbon-accounted supply relationships.
For Market Incumbents: Insulate core glass manufacturing relationships through captive renewable energy integration at Solvay-process facilities, restoring cost parity against imported natural trona. Deepen backward integration into salt mining assets to secure feedstock autonomy. Carbon border adjustment implementation timelines represent the critical regulatory threat requiring proactive compliance investment. For New Entrants and Emerging Players: Specialty pharmaceutical-grade soda ash with EMA-compliant impurity thresholds represents the most penetrable entry point, as regulatory tightening expands premium segment boundaries. Romanian and Bulgarian container glass manufacturing offers white-space expansion corridors for dense soda ash offtake growth. A certification-first go-to-market approach targeting REACH-compliant high-purity specifications enables margin capture above commodity tiers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across synthetic production retrofits as EU Emissions Trading System compliance costs accelerate. Acquisition targets should display integrated salt-to-soda ash production with captive energy assets and established long-term offtake agreements. The signal to watch is carbon border adjustment implementation pace, which will determine cost parity restoration timelines for domestic synthetic capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Integration | Captive solar and wind installations restore synthetic producer competitiveness against carbon-adjusted trona imports. |
| Backward Integration into Salt Mining | Upstream control over feedstock secures supply autonomy and compresses input cost volatility exposure. |
| Long-term Offtake Agreements | Embedded carbon accounting locks glass manufacturer relationships and displaces spot-market purchasing patterns. |
| Specialty Grade Certification Investment | EMA and REACH compliance enables premium positioning in pharmaceutical excipient applications. |
| Sealed Bulk System Deployment | ECHA dust exposure classification compliance mandates packaging redesign toward pneumatic conveying infrastructure. |
Research Approach
Cross-validation between primary interviews with glass plant procurement directors, chemical processing engineers, and specialty grade quality assurance managers anchors the qualitative findings. Secondary validation draws from ECHA regulatory filings, EU Emissions Trading System compliance disclosures, Cefic chemical industry reports, and customs trade data. Bottom-up volume modeling triangulates against top-down market sizing across density grades and end-use applications.
Calibration against historical capacity utilization rates and carbon intensity benchmarks shapes the analytical framework across the projection horizon. Segmentation dimensions include density grade tier, end-use industry concentration, packaging format adoption, and regional production hub configuration. CAGRs derive from trend extrapolation of flat glass manufacturing expansion and detergent formulation substitution rates, with EU Green Deal implementation pace serving as a key inflection input.
Practitioners should monitor carbon border adjustment mechanism implementation timelines and natural gas price volatility for early signals of forecast revision. Cross-checking against ETS carbon price trajectories and glass manufacturing capacity announcement pipelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Asia-Pacific Lithium Chloride Market
Bulk Chemicals
LAMEA Glacial Acrylic Acid Market
Bulk Chemicals
Chemical Warehousing Market
Bulk Chemicals
Ammonium Carbonate Market
Bulk Chemicals
Chlor Alkali Market
Bulk Chemicals
Asia-Pacific Starch Derivatives Market
Bulk Chemicals
Caprolactam Market
Bulk Chemicals
Europe Castor Oil Market
Bulk Chemicals
Powdered Cellulose Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Aniline Market
Bulk Chemicals
Bio-Succinic Acid Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Sodium Dicyanamide Market
Bulk Chemicals
Global Levulinic Acid Market
Bulk Chemicals
Europe Ammonium Nitrate Market