
 Asia-Pacific Lithium Chloride Market | 2026-2036
Asia-Pacific Lithium Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Lithium Chloride Market Insights
China's dual carbon goals are pivoting lithium chloride demand toward battery-grade purification standards. Jiangxi Ganfeng Lithium leverages integrated brine-to-cathode operations across Jiangxi province. Tianqi Lithium anchors Western Australia's spodumene supply into Chinese conversion facilities. Shenzhen Chengxin Lithium Group specializes in battery-grade salt production for domestic electrolyte manufacturers.
Lithium chloride is an ionic salt with the formula LiCl, typically produced at 99.5% purity for battery applications through solar evaporation of brine or acid leaching of spodumene concentrate; its hygroscopic properties make it essential for moisture control in electrolyte formulations and air treatment systems. Battery Manufacturing dominates volume offtake as cathode and electrolyte producers scale precursor chemical demand. Anhydrous Lithium Chloride commands premium positioning due to stringent moisture specifications in solid-state battery research programs. Direct Sales channels control bulk transactions as integrated battery makers negotiate long-term offtake agreements directly with Qinghai and Sichuan refiners.
China's MEE enforces wastewater discharge limits on lithium refining that elevate capital costs for new Qinghai lake entrants. Australia's TGA and China's NMPA both scrutinize pharmaceutical-grade lithium chloride imports for bipolar disorder treatment formulations. Stakeholders must monitor how Indonesia's emerging nickel-cobalt-lithium industrial corridors reshape regional chemical logistics and offtake contracting norms.
Market Dynamics
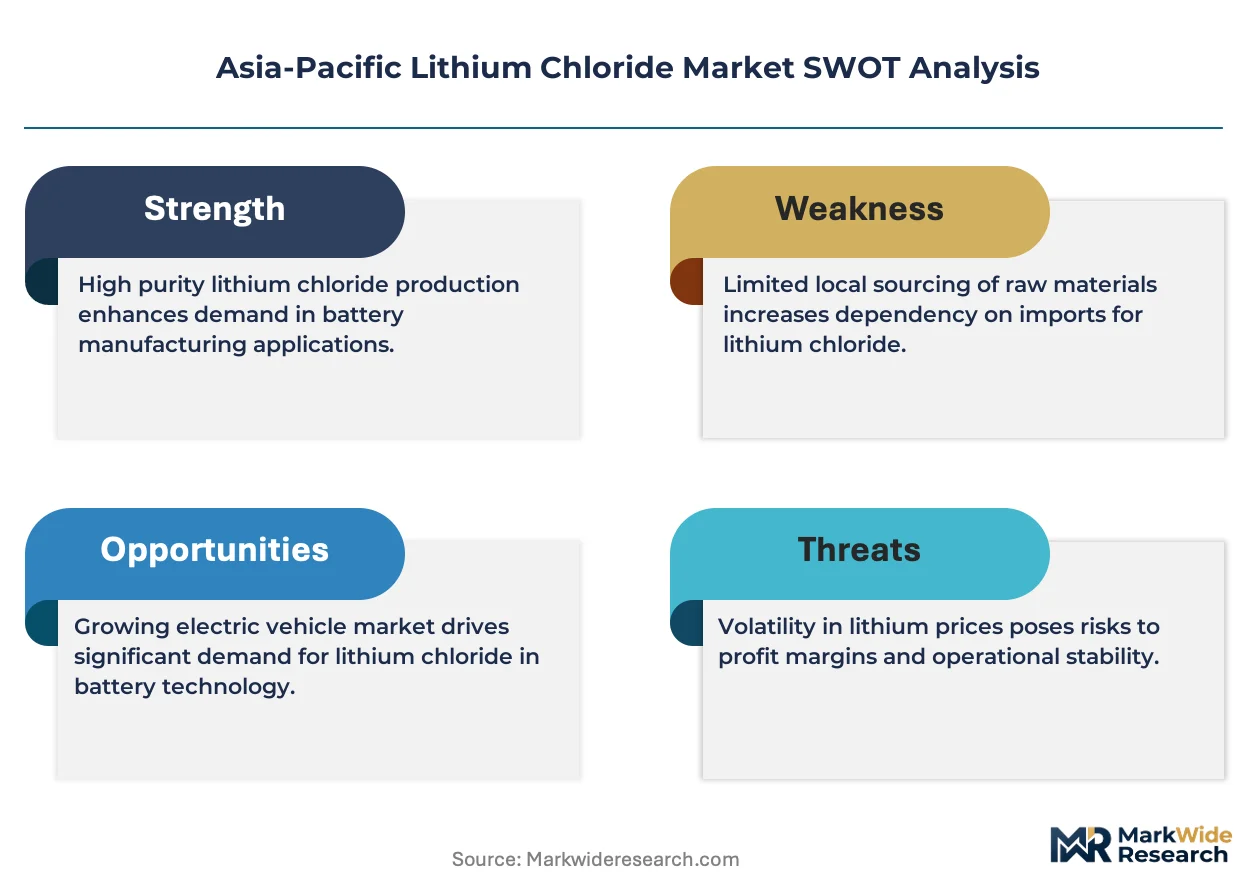
China's dual carbon goals and the Ministry of Ecology and Environment's wastewater discharge mandates are compressing new refinery entry timelines while concentrating capacity among incumbents with compliant lake-bed operations in Qinghai province. Battery-grade purification standards now govern procurement specifications across electrolyte formulators.
Growth Catalysts
- Battery-grade purification standards:China's MIIT mandates 99.5% minimum purity for electrolyte-grade lithium chloride, locking in premium product demand from cathode precursor manufacturers.
- Direct brine extraction:Qinghai salt lake operators deploy solar evaporation arrays that slash acid leaching requirements versus spodumene routes, reducing processing energy intensity.
- Domestic refining investments:Provincial industrial policy in Jiangxi channels capital toward integrated brine-to-cathode corridors that captive upstream chemical output.
Market Restraints
- Qinghai lake concentration risk:Over 60% of regional lithium chloride feedstock originates from three high-altitude brine basins vulnerable to seasonal extraction volatility and water rights disputes.
- Spodumene import dependency:Australian hard rock concentrate supplies face freight cost swings and port congestion that transmit directly to Chinese conversion facility margins.
- Pharmaceutical-grade certification friction:Australia's TGA and China's NMPA impose divergent impurity thresholds for bipolar disorder treatment formulations, fragmenting batch qualification protocols.
Strategic Opportunities
- Indonesia's industrial corridor buildout:Nickel-cobalt-lithium processing parks in Sulawesi and Halmahera create demand for chloride-based precursor chemicals to feed integrated cathode plants.
- Solid-state battery research:Anhydrous lithium chloride specifications below 50 ppm moisture are integrating into sulfide electrolyte development programs at Korean and Japanese cell makers.
- Long-term offtake contracting:Direct sales channels between Qinghai refiners and integrated battery makers are displacing spot market transactions, locking in volume visibility.
Industry Challenges
- Battery-grade certification timelines:Electrolyte manufacturers face 12-18 month qualification cycles with cathode makers, compressing product iteration windows.
- Brine-to-battery integration complexity:Qinghai operators struggle to synchronize seasonal evaporation yields with continuous downstream chemical plant throughput requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Lithium Chloride Market |
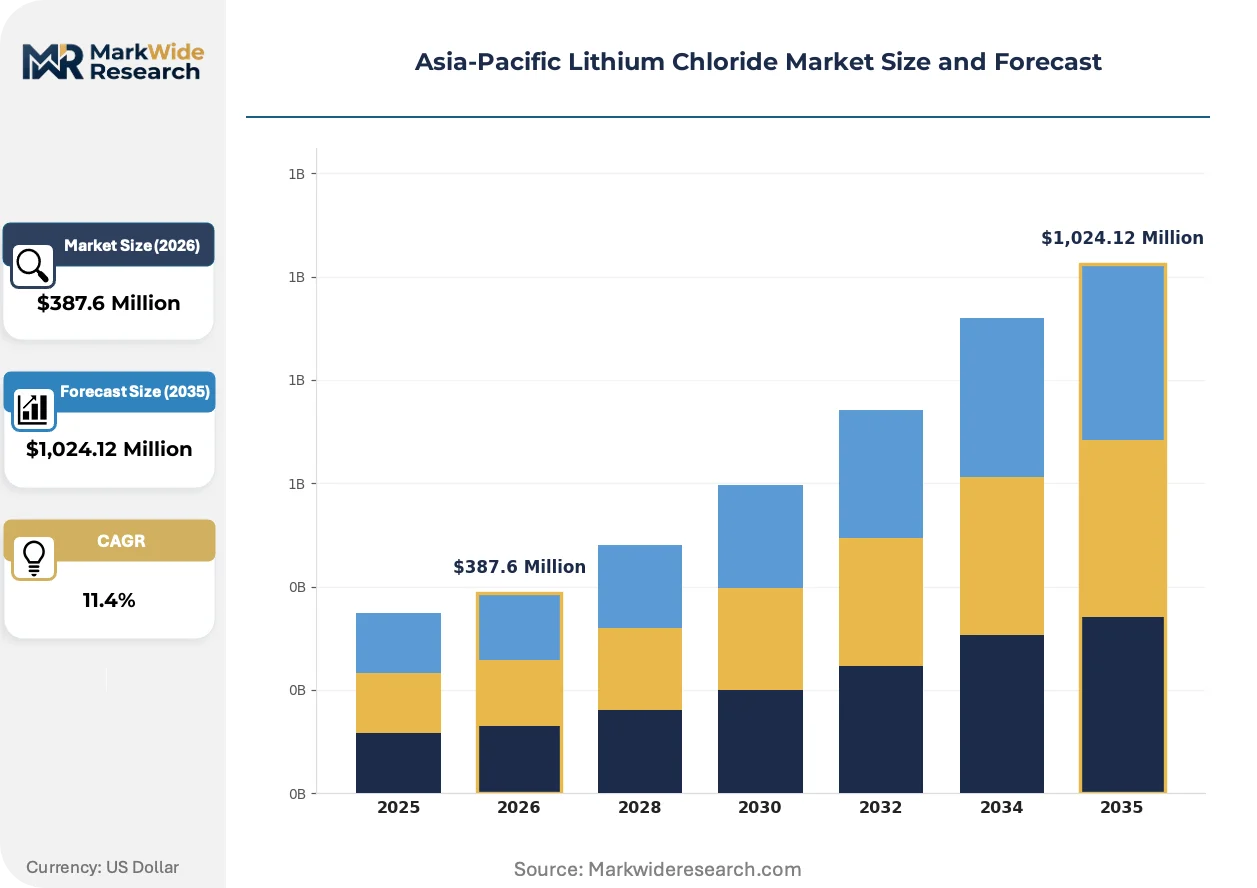
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Battery Manufacturing, Refrigerants, Dehumidifiers, Pharmaceuticals Product Type: Anhydrous Lithium Chloride, Hydrated Lithium Chloride, Lithium Chloride Solution, Lithium Chloride Granules End User: E-Learning Platforms, Automotive Industry, Construction Materials, Chemical Processing Sales Channel: Direct Sales, Online Retail, Distributors, B2B Sales |
| Companies Covered | Jiangxi Ganfeng Lithium, Tianqi Lithium, Shenzhen Chengxin Lithium Group, Nippon Chemical Industrial, Qinghai Chaidamu Xinghua Lithium Salt, Qinghai Zhongke Jiexin, Jiangsu Changjili New Energy Technology, Fengchen Group, Leverton-Clarke, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Lithium Chloride Market Trends and Innovations
Electrolyte chemistry evolution and purification technology advances are compressing product specification bands while regional regulatory divergence fragments compliance architectures. Solid-state research programs and direct refinery-to-cell-maker contracting are restructuring traditional chemical distribution channels.
Membrane-based selective electrodialysis is integrating into Qinghai brine processing trains to bypass lengthy solar evaporation cycles. Tianqi Lithium and Ganfeng Lithium have piloted modular units that reduce lithium chloride crystallization time from 18 months to 90 days. This technology is integrating capital-light expansion pathways for mid-scale lake operators previously blocked by evaporation pond footprint constraints.
China's MEE enforcement of GB 8978 wastewater discharge limits on lithium refining is elevating capital costs for new Qinghai entrants by mandating closed-loop brine management systems. Existing operators with grandfathered evaporation permits face retrofit deadlines that compress free cash flow generation. Battery-grade refiners in Sichuan and Jiangxi are responding by consolidating tailings treatment through third-party industrial park infrastructure.
Direct offtake negotiations between Qinghai chemical refiners and integrated battery makers are displacing multi-tier distributor networks for bulk lithium chloride transactions. Electrolyte formulators in Fujian and Jiangsu now contract 3-5 year volume agreements with named annual price review clauses. This pattern is most visible in China's southeastern battery manufacturing clusters where cathode precursor plants co-locate with cell assembly facilities.
Asia-Pacific Lithium Chloride Market Segmentation
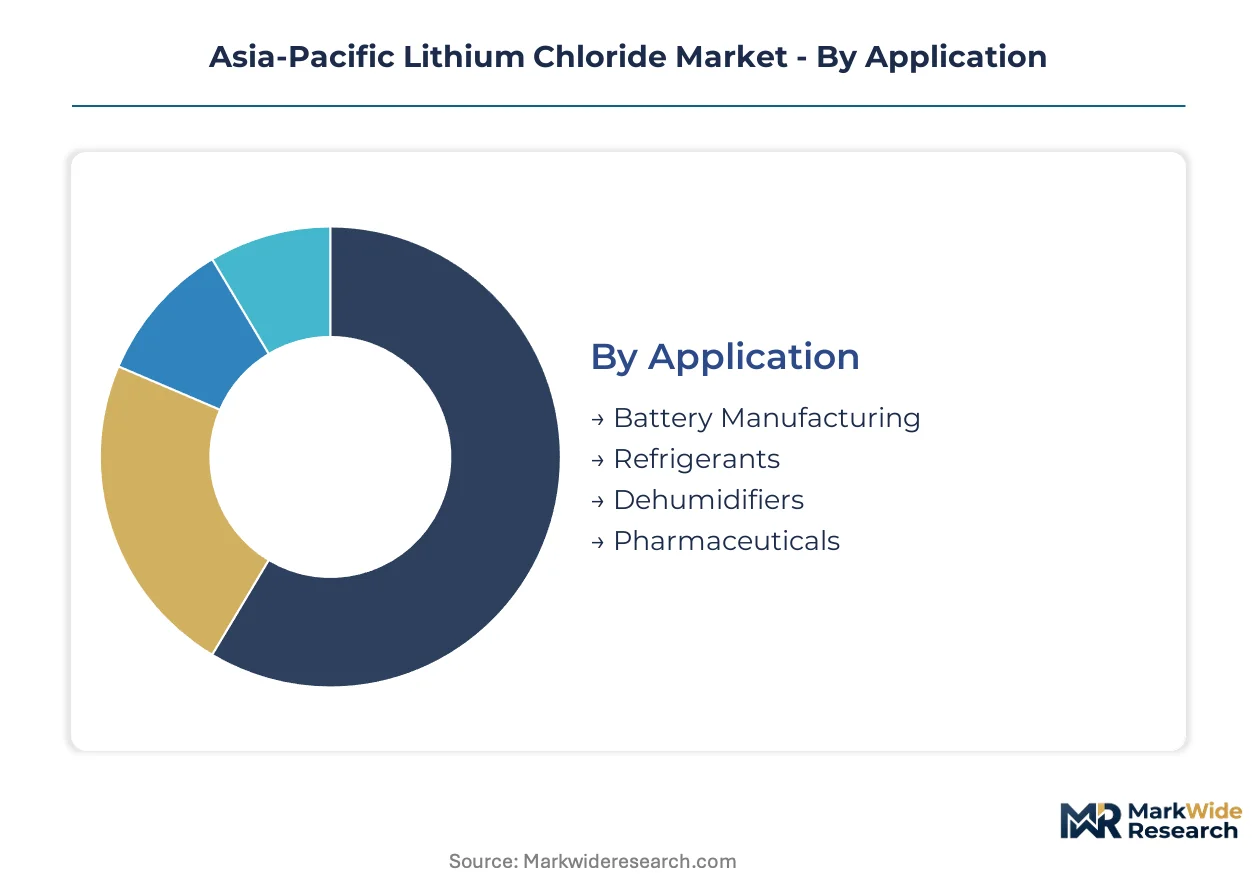
Segmentation in the Asia-Pacific lithium chloride market reveals how purification standards, moisture specifications, and procurement channels fragment demand across battery, pharmaceutical, and industrial applications. Each category exposes distinct margin structures and qualification barriers that shape supplier positioning.
Application:
Customization intensity spans from commodity-grade industrial uses to battery-grade specifications demanding sub-50 ppm impurity thresholds.
- Battery Manufacturing:Electrolyte formulators and cathode precursor producers procure lithium chloride at 99.5% minimum purity per MIIT mandates. Demand concentrates in Fujian and Jiangsu provinces where cell assembly clusters co-locate with chemical conversion facilities.
- Pharmaceuticals:Bipolar disorder treatment formulations require pharmaceutical-grade certification under divergent TGA and NMPA impurity protocols. Australia's TGA and China's NMPA impose non-aligned batch qualification standards that fragment regional supply chains.
- Refrigerants:Industrial absorption cooling systems utilize technical-grade lithium chloride brines with lower purity tolerances.
- Dehumidifiers:Air treatment systems leverage hygroscopic properties for moisture control in controlled atmosphere applications.
Leading the category by volume: Battery Manufacturing. Expanding most quickly: Pharmaceuticals.
Product Type:
Moisture content and physical form determine pricing tiers and end-use accessibility across the specification ladder.
- Anhydrous Lithium Chloride:Sub-50 ppm moisture specifications command premium positioning in solid-state battery research programs at Korean and Japanese cell makers. Korean and Japanese sulfide electrolyte development programs integrate anhydrous grades as critical feedstock.
- Hydrated Lithium Chloride:Crystalline forms with controlled water content serve pharmaceutical and industrial applications where extreme dryness is unnecessary.
- Lithium Chloride Solution:Aqueous preparations facilitate direct injection into electrolyte blending operations without dissolution stages.
- Lithium Chloride Granules:Free-flowing particulate forms optimize handling logistics for bulk industrial consumers.
Dominant by revenue: Anhydrous Lithium Chloride. Steepest expansion trajectory: Lithium Chloride Solution.
End User:
Customer sophistication ranges from price-sensitive commodity buyers to integrated manufacturers demanding captive supply assurances.
- Automotive Industry:Cell makers and OEMs negotiate long-term offtake agreements directly with Qinghai refiners, bypassing distributor markups. Procurement concentrates among integrated battery makers in China's southeastern manufacturing corridors.
- Chemical Processing:Intermediate chemical producers convert lithium chloride into organolithium reagents and specialty salts.
- Construction Materials:Concrete setting accelerators and air-entraining admixtures incorporate technical-grade lithium salts.
- E-Learning Platforms:Laboratory supply procurement for educational institutions represents fragmented, small-volume demand.
Category leader by contract value: Automotive Industry. Gaining share fastest: Chemical Processing.
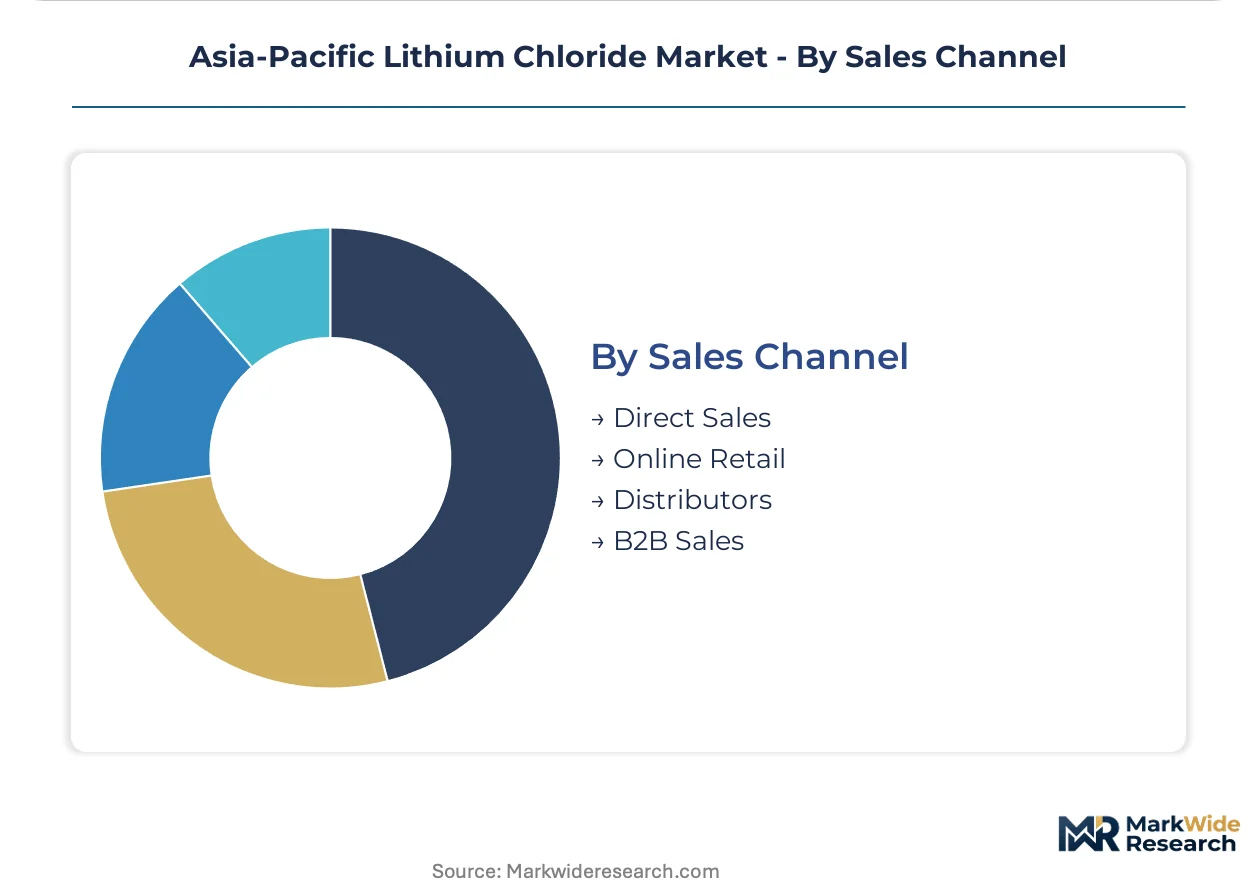
Sales Channel:
Channel selection reflects transaction scale, qualification complexity, and the buyer's integration depth into upstream supply.
- Direct Sales:Qinghai refiners and Jiangxi integrated operators negotiate 3-5 year volume agreements with named annual price review clauses. Fujian and Jiangsu electrolyte formulators lock in volume visibility through direct refinery relationships.
- B2B Sales:Long-term supply contracts with industrial consumers emphasize specification consistency and logistics coordination.
- Distributors:Multi-tier networks serve small and mid-scale consumers lacking procurement scale for direct refinery access.
- Online Retail:E-commerce platforms facilitate laboratory-grade and small-batch transactions for research institutions.
Controlling bulk transactions: Direct Sales. Growing fastest: B2B Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes the majority of Asia-Pacific lithium chloride output while Australia and Chile supply raw spodumene and brine concentrates. Japan and South Korea operate advanced cathode and electrolyte manufacturing without significant domestic lithium extraction.
China
Jiangxi province hosts Ganfeng Lithium's integrated brine-to-cathode operations that convert Qinghai salt lake feedstock into battery-grade chemicals. The MIIT enforces 99.5% minimum purity standards for electrolyte-grade lithium chloride. Qinghai's Chaerhan Salt Lake anchors upstream extraction clusters that supply Sichuan and Jiangxi downstream refiners.
Australia
Greenbushes and Pilbara spodumene mines export hard rock concentrate to Chinese conversion facilities under long-term offtake agreements. The TGA scrutinizes pharmaceutical-grade lithium chloride exports for bipolar disorder formulations. Perth-based logistics hubs coordinate bulk shipments through Port Hedland and Fremantle to Qinghai and Jiangxi processors.
Japan
Osaka and Nagoya electrolyte formulators procure anhydrous lithium chloride for sulfide solid-state battery research programs. METI funding accelerates domestic cell manufacturing capacity without upstream lithium extraction. Kyushu-based chemical processors specialize in ultra-low moisture specifications below 50 ppm for next-generation electrolyte development.
South Korea
Ulsan and Gwangju cathode plants import lithium chloride solution for direct injection into precursor manufacturing. The MFDS maintains pharmaceutical-grade import standards distinct from Chinese NMPA protocols. Seoul Capital Area battery makers negotiate direct refinery relationships with Qinghai operators to bypass distributor markups.
Indonesia
Sulawesi and Halmahera nickel-cobalt-lithium industrial corridors create emerging demand for chloride-based precursor chemicals. The country's national mining regulator oversees export restrictions on unprocessed ores that redirect investment toward integrated refining parks. Morowali Industrial Park hosts cathode plants that source lithium chloride from Chinese and Australian suppliers.
Asia-Pacific Lithium Chloride Market Competitive Landscape
The competitive structure tilts toward integrated brine-to-cathode operators with captive upstream supply. Qinghai salt lake incumbents leverage grandfathered evaporation permits that new entrants cannot replicate under MEE wastewater mandates. Three archetypes dominate: state-affiliated lake operators with mineral rights, private refiners with electrolyte formulator partnerships, and Australian miners with Chinese conversion joint ventures. Capacity expansion and direct long-term offtake contracting constitute the dominant competitive moves.
Among integrated Chinese operators, Jiangxi Ganfeng Lithium and Tianqi Lithium exemplify the brine-to-cathode archetype with upstream mineral rights and downstream chemical processing. Shenzhen Chengxin Lithium Group occupies a position within the specialized battery-grade salt tier serving domestic electrolyte manufacturers. These three entities anchor the competitive landscape through distinct supply chain configurations rather than overlapping market positions.
| Leading Market Players |
|---|
| Jiangxi Ganfeng Lithium |
| Tianqi Lithium |
| Shenzhen Chengxin Lithium Group |
| Nippon Chemical Industrial |
| Qinghai Chaidamu Xinghua Lithium Salt |
| Qinghai Zhongke Jiexin |
| Jiangsu Changjili New Energy Technology |
| Fengchen Group |
| Leverton-Clarke |
| Others |
Pricing and Supply Chain Analysis
China's MEE wastewater discharge mandates gate qualified supply and premium-tier pricing access by forcing retrofit investments on grandfathered Qinghai lake operators while elevating capital barriers for new entrants. Battery-grade certification under MIIT purity standards separates pricing tiers between compliant refiners and technical-grade commodity suppliers.
Pricing Analysis
Yield-based pricing anchors battery-grade lithium chloride contracts, with electrolyte formulators paying premiums tied to cathode precursor manufacturing throughput. Price differentiation separates 99.5% purity certified supply from technical-grade alternatives, with volume scale and direct refinery relationships driving further stratification. Cost compression in hydrated grades is intensifying because Qinghai seasonal yield volatility forces spot market exposure. Chemical processing intermediates prove most price-sensitive, while automotive cell makers absorb premiums for long-term volume visibility.
Supply Chain Analysis
Australian spodumene concentrate, Qinghai salt lake brine, and Chilean lithium carbonate feedstock anchor upstream inputs for Asia-Pacific lithium chloride production. The supply chain draws from Australian hard rock mines, Chinese conversion facilities in Jiangxi and Sichuan, and emerging Indonesian nickel-cobalt-lithium corridors. Single-source vulnerability concentrates in Qinghai's three high-altitude brine basins, where water rights disputes and seasonal extraction swings disrupt continuous chemical plant throughput. Distribution runs through direct refinery-to-cell-maker channels that displace multi-tier distributor networks for bulk transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solid-state battery research programs are displacing liquid electrolyte legacy demand, with anhydrous lithium chloride specifications below 50 ppm moisture becoming the critical feedstock transition.
For Market Incumbents: Anchor backward integration into Qinghai salt lake mineral rights to lock captive upstream supply against emerging Indonesian nickel-cobalt-lithium corridor competition. Invest in membrane-based selective electrodialysis modular units to compress crystallization cycles and defend processing cost position against new entrants with solar evaporation pond constraints. For New Entrants and Emerging Players: The 15-20% price-point gap between premium anhydrous and standard hydrated grades creates entry space for mid-purity battery-grade specialists serving second-tier electrolyte formulators. Target pharmaceutical-grade certification as the most penetrable segment, where divergent TGA and NMPA protocols fragment incumbent batch qualification advantages. Pursue third-party industrial park tailings treatment partnerships to bypass MEE wastewater mandate capital burdens. For Investors and Strategic Acquirers: Direct offtake contract announcements between Qinghai refiners and Korean cell makers are the leading indicator that anhydrous grade demand is accelerating beyond current qualified supply. Frame long-term viability around 5-10 year cathode precursor manufacturing expansion across Southeast Asian industrial corridors. Target acquisition archetypes: state-affiliated lake operators with grandfathered evaporation permits facing retrofit deadlines but holding irreplaceable mineral rights.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Brine Assets | Captive Qinghai salt lake feedstock secures volume visibility against Australian spodumene freight volatility. |
| Membrane Electrodialysis Deployment | Modular units at Tianqi Lithium and Ganfeng Lithium pilots reduce crystallization from 18 months to 90 days. |
| Long-term Offtake Contracting | Direct 3-5 year agreements between Qinghai refiners and Fujian electrolyte formulators displace spot market exposure. |
| Pharmaceutical-grade Certification Investment | Divergent TGA and NMPA impurity thresholds create fragmented batch qualification barriers for regional supply chains. |
| Indonesian Industrial Corridor Partnership | Sulawesi and Halmahera nickel-cobalt-lithium parks demand chloride-based precursors for integrated cathode plants. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Asia-Pacific lithium chloride market assessment. Primary interviews with Qinghai refinery plant managers, electrolyte formulator procurement leads, cathode precursor R&D directors, and Australian spodumene mine operations heads combined with MIIT purity standard documentation, MEE wastewater discharge filings, and China Customs lithium compound export records. Bottom-up volume modeling triangulated against top-down regional chemical demand projections.
Data-stream reconciliation across brine extraction yields, conversion facility throughput, and battery-grade offtake volumes structured the analytical framework. Segmentation dimensions modeled include purity grade tier, moisture specification, end-use application, and regional production hub concentration. CAGRs derived from slope analysis of annual volume trajectories, with specific inputs from solar evaporation cycle timing, membrane technology adoption curves, and direct sales channel penetration rates across the projection horizon.
Inputs from Chinese provincial industrial policy announcements and Korean cell maker sulfide electrolyte development disclosures were available through the study window; gaps in Indonesian nickel-cobalt-lithium corridor operational timelines introduce uncertainty bands around precursor chemical demand timing. Forecasts reflect assumptions on MEE enforcement consistency, Qinghai water rights stability, and solid-state battery research program scale-up commitments. A small set of named triggers—Indonesian export restriction policy shifts, Korean anhydrous grade qualification accelerations, and Qinghai seasonal yield deviations—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
Crude Tall Oil Derivative Market
Bulk Chemicals
Ceric Ammonium Nitrate Market
Bulk Chemicals
Sulfur Market
Bulk Chemicals
India Iodine Market
Bulk Chemicals
Sodium, Potassium, and Calcium Salts Market
Bulk Chemicals
Magnesium Sulfate Market
Bulk Chemicals
Europe Hydrogen Bromide Market
Bulk Chemicals
Isovaleryl Chloride Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Lactic Acid Market
Bulk Chemicals
Calcium Carbonate Market
Bulk Chemicals
Phosphate Rock Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Stilbene Market