
 Ammonium Carbonate Market | 2026-2036
Ammonium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Carbonate Market Analysis
Modular packaging of ammonium carbonate into pre-measured sachets and tablet formats is consolidating buyer choice across artisanal and industrial bakeries. BASF SE leverages its integrated ammonia supply chain to sustain cost leadership in European food-grade distribution. Taixing Dongyu Chemical anchors volume production for Asian agriculture markets through captive urea-to-carbonate conversion. Merck Group differentiates via pharmaceutical-grade certification that commands premium positioning in laboratory reagent channels.
Ammonium carbonate, chemically (NH₄)₂CO₃, decomposes upon heating into ammonia, carbon dioxide, and water vapor, yielding a rapid gas-release profile valued in applications requiring controlled porosity without residual salts. Industrial synthesis proceeds via carbonation of aqueous ammonia under pressurized conditions, yielding crystals that are subsequently dried, milled, or compacted to specification. Powder formulations occupy the dominant share of leavening-agent applications due to dispersibility advantages in dry-mix dough systems, while granule configurations are gaining traction in controlled-release fertilizer blends where soil penetration depth matters. Tablet segments serve niche pharmaceutical and personal-care stabilizer roles where dosing precision outweighs unit-cost sensitivity.
REACH registration requirements in Europe, FDA food-additive specifications under 21 CFR 184.1137 in the United States, and China's GB standards for industrial chemicals collectively elevate purity thresholds and documentation burdens for cross-border suppliers. ECHA substance evaluation protocols are tightening impurity limits for ammonium carbonate used in consumer-facing applications, effectively filtering out non-compliant producers from premium segments. Stakeholders must monitor regulatory divergence between jurisdictions, as diverging maximum-residue and labeling mandates will determine which production configurations remain economically viable across export markets.
Market Dynamics
REACH substance evaluation protocols are filtering non-compliant ammonium carbonate producers from European consumer-facing segments, compressing the supplier base while elevating purity thresholds for cross-border trade.
Growth Catalysts
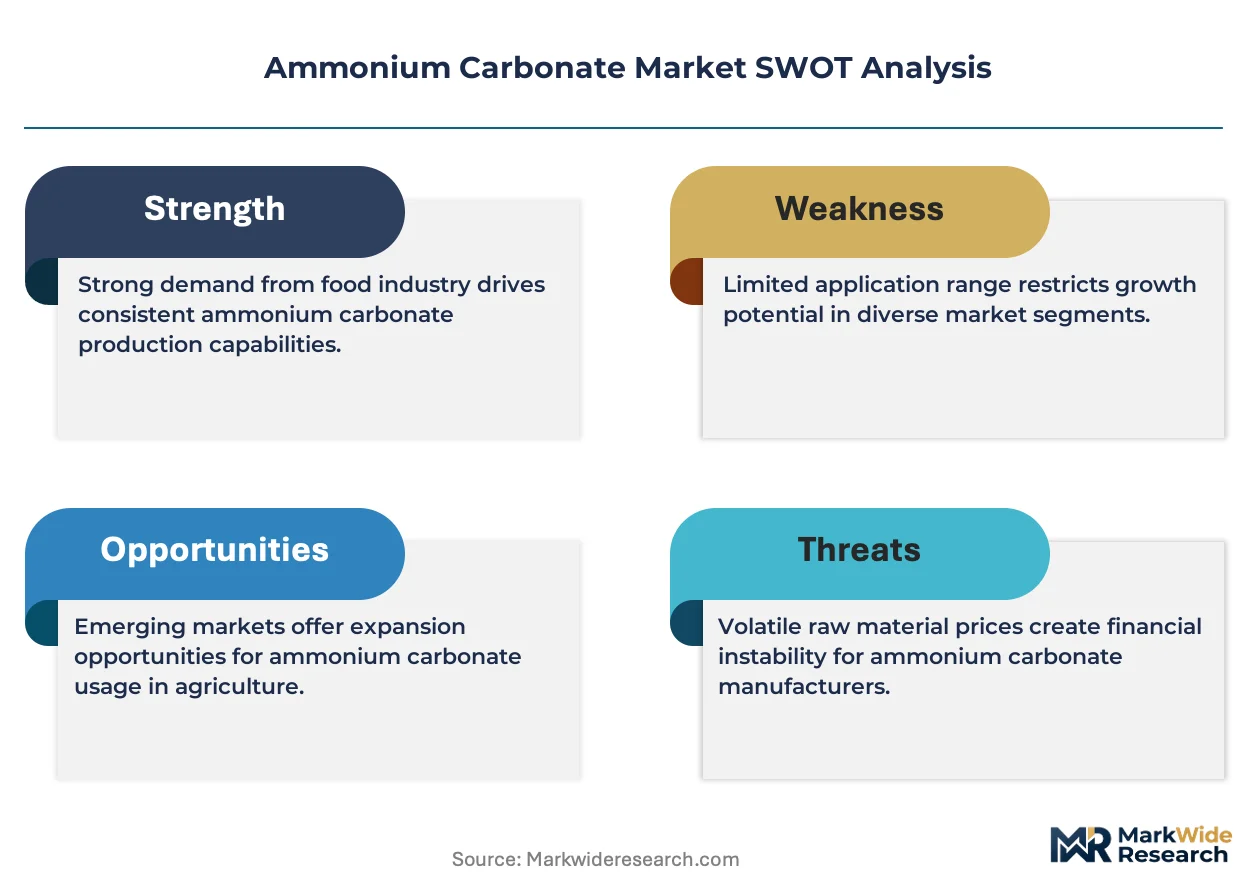
- Food-grade leavening demand:Artisanal and industrial bakeries across Germany, France, and Italy are expanding ammonium carbonate consumption for traditional crisp-baked goods where rapid gas-release profiles outperform alternative agents.
- REACH compliance barriers:ECHA registration requirements are consolidating market share among integrated producers capable of documenting impurity limits below 10 ppm for consumer applications.
- Agrochemical formulation expansion:Controlled-release fertilizer manufacturers in China are incorporating ammonium carbonate granules into nitrogen-stabilized blends for deep soil penetration.
Market Restraints
- Ammonia feedstock volatility:Natural gas price fluctuations directly compress margins for non-integrated producers lacking captive ammonia supply.
- Substitution pressure from sodium bicarbonate:Industrial bakeries in cost-sensitive segments are reformulating toward bicarbonate-based systems where residual salt tolerance permits.
- Transportation classification friction:Ammonium carbonate's hazardous material designation under UN 3077 elevates logistics costs and restricts warehouse co-location with food products.
Strategic Opportunities
- Pharmaceutical-grade certification:Laboratory reagent channels in Switzerland and the United Kingdom command premium positioning for producers achieving pharmacopeial compliance.
- Modular packaging innovation:Pre-measured sachet and tablet formats are opening artisanal bakery segments previously inaccessible to bulk powder distribution.
- Dual carbon policy alignment:China's MEE industrial emissions frameworks are incentivizing carbonate producers with carbon capture integration in ammonia synthesis.
Industry Challenges
- Analytical chemistry talent scarcity:Documentation of ECHA-compliant impurity profiles requires specialized chromatography expertise concentrated among contract laboratories.
- Cross-jurisdictional labeling complexity:Divergent maximum-residue mandates between FDA 21 CFR 184.1137 and China's GB standards force parallel production runs.
- Legacy equipment retrofit costs:Crystallization and drying systems require stainless steel upgrades to meet food-grade surface finish specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Carbonate Market |
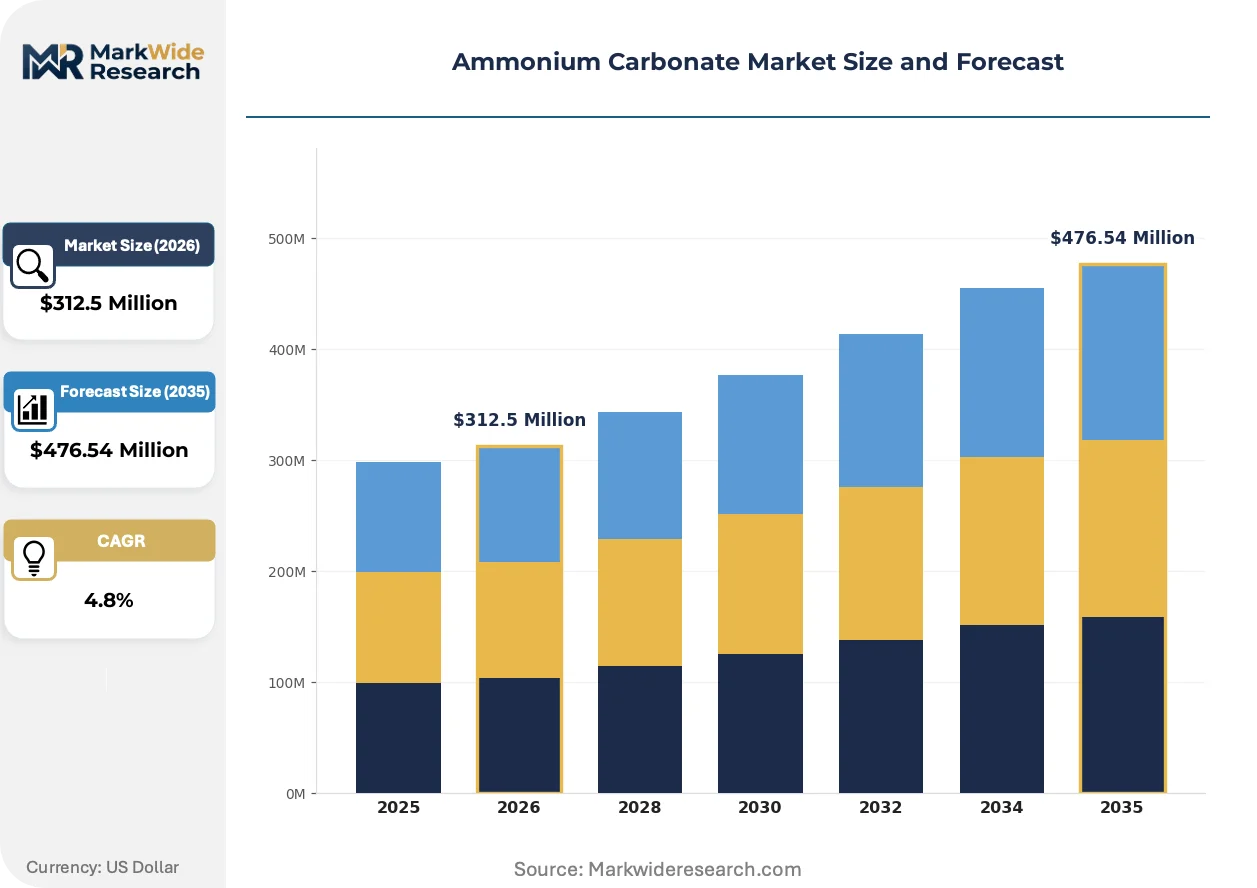
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $476.54 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Granules, Powder, Tablets, Solutions End User: Pharmaceuticals, Food & Beverage, Agriculture, Personal Care Application: Leavening Agent, Fertilizer, Stabilizer, Acid Neutralizer Packaging Type: Bags, Drums, Bulk Containers, Sachets |
| Companies Covered | BASF SE, Thermo Fisher Scientific Inc., Merck Group, Bayer CropScience, Taixing Dongyu Chemical, Shanghai Mingdou Agrochemical Co. Ltd, Honeywell International Inc., Avantor, Syngenta AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Carbonate Market Emerging Trajectories
Continuous carbonation reactor designs and modular dosing systems are compressing batch-to-batch variability while opening new application formats across pharmaceutical and personal care segments.
Continuous carbonation reactor technology is unifying temperature and pressure control across aqueous ammonia feedstocks, eliminating batch-to-batch crystallization variance that previously required extensive post-processing. European food-grade producers are retrofitting legacy pressure vessels with automated pH-loop systems to maintain carbonate-to-bicarbonate ratios within pharmacopeial tolerances. This unifying control architecture is compressing quality-adjusted production costs for mid-scale integrated operators.
ECHA's 2024 updated substance evaluation criteria for ammonium carbonate are tightening heavy metal impurity thresholds in consumer-facing applications, effectively disqualifying producers reliant on industrial-grade ammonia feedstocks. The industrial consequence is a bifurcation between pharmaceutical-certified and technical-grade supply chains with divergent documentation burdens. German and Dutch distributors are responding by consolidating procurement relationships with REACH-registered producers capable of batch-specific certificates of analysis.
Specification-driven procurement is compressing supplier lists among industrial bakeries as quality assurance teams mandate third-party food-safety certification alongside traditional chemical assays. Direct-to-mill sourcing agreements are displacing distributor intermediaries in high-volume leavening-agent contracts across northern European baking clusters. This consolidation is most visible in Belgium and the Netherlands, where integrated milling and baking operations are qualifying single-source ammonium carbonate suppliers for multi-year framework agreements.
Ammonium Carbonate Market Segmentation
Buyer priorities diverge sharply across ammonium carbonate applications. Food-grade purchasers prioritize dispersibility and residual salt profiles, while agrochemical buyers emphasize soil penetration depth and controlled nitrogen release. Pharmaceutical and personal care segments impose the strictest purity documentation burdens, filtering supplier eligibility.
Product Type:
Application-specific performance requirements dictate format selection, with processing characteristics and end-use handling constraints driving procurement decisions.
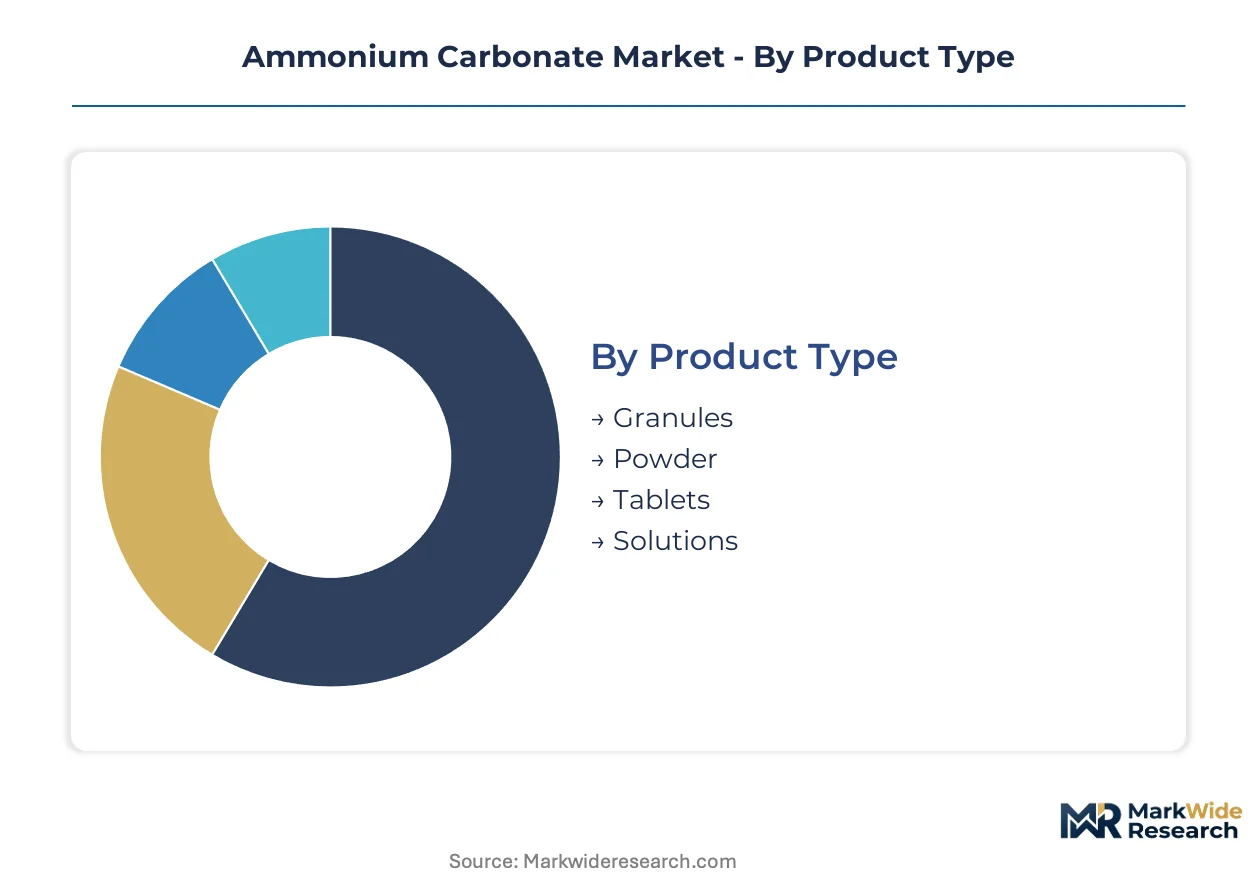
- Powder:Fine particulate structure enables rapid dissolution in dry-mix dough systems. Industrial bakeries across Germany and France specify powder grades for traditional crisp-baked goods where gas-release speed outperforms alternatives. REACH-registered producers dominate supply relationships due to impurity documentation requirements.
- Granules:Compact spherical morphology supports controlled dissolution kinetics in soil applications. Chinese fertilizer manufacturers incorporate granules into nitrogen-stabilized blends for deep penetration in root-zone delivery, with domestic producers anchoring volume supply through captive urea conversion.
- Tablets:Pre-compressed dosing units serve laboratory reagent channels and personal care stabilizer formulations where precision outweighs unit-cost sensitivity.
- Solutions:Aqueous formulations support pharmaceutical manufacturing processes requiring direct liquid-phase integration without dissolution steps.
Volume sits with Powder; growth tilts toward Granules.
End User:
Regulatory certification tiers separate supplier bases, with food-grade and pharmaceutical channels imposing documentation barriers that technical-grade producers cannot surmount.
- Food & Beverage:Leavening-agent specifications under FDA 21 CFR 184.1137 and EFSA food-additive frameworks mandate heavy metal thresholds below 10 ppm. Artisanal and industrial bakeries in Italy and Belgium consolidate procurement around REACH-registered distributors capable of batch-specific certificates.
- Agriculture:Controlled-release fertilizer demand concentrates in China, where MEE industrial emissions frameworks incentivize carbonate producers with carbon capture integration. Domestic agrochemical formulation expansion absorbs volume production from integrated ammonia-carbonate operations.
- Pharmaceuticals:Pharmacopeial compliance requirements in Switzerland and the United Kingdom command premium positioning for laboratory reagent applications.
- Personal Care:Stabilizer applications in cosmetic formulations require cosmetic-grade purity certification under EU Cosmetics Regulation frameworks.
Revenue concentrates in Food & Beverage; margin expansion favors Pharmaceuticals.
Application:
Functional chemistry determines value capture, with reaction kinetics and residual byproduct profiles shaping buyer willingness to pay.
- Leavening Agent:Thermal decomposition yields ammonia, carbon dioxide, and water vapor without residual salts, preserving crisp texture in thin-baked goods. German and Dutch industrial bakeries qualify single-source suppliers for multi-year framework agreements, displacing distributor intermediaries.
- Fertilizer:Nitrogen delivery mechanism integrates into controlled-release blends where soil penetration depth determines agronomic efficacy. Chinese deep-placement application protocols favor granule configurations.
- Stabilizer:pH buffering capacity supports pharmaceutical and personal care formulations requiring precise acidity control.
- Acid Neutralizer:Rapid neutralization kinetics serve industrial chemical processing applications with tolerance for technical-grade purity.
Mature demand anchors Leavening Agent; Fertilizer applications climb the fastest.
Packaging Type:
Handling economics and contamination risk separate bulk from unitized formats, with downstream automation compatibility driving specification divergence.
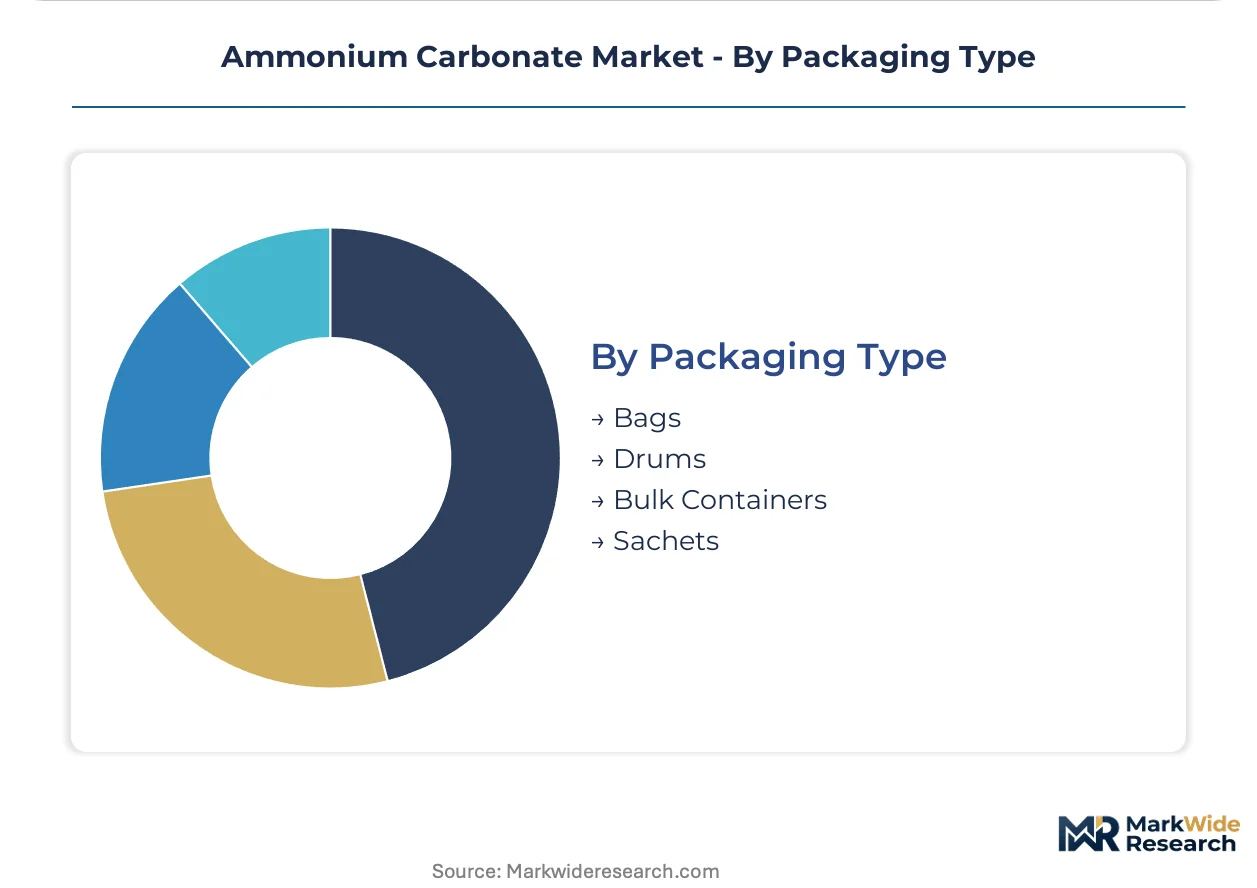
- Bulk Containers:Intermediate bulk handling for high-volume industrial bakeries and fertilizer blenders minimizes per-kilogram packaging cost. Northern European milling clusters favor direct-to-mill sourcing agreements.
- Sachets:Pre-measured unit doses open artisanal bakery segments previously inaccessible to bulk powder distribution, with modular formats consolidating buyer choice across small-scale operations.
- Bags:Standard multi-wall construction serves mid-volume food-grade and technical-grade shipments with established handling infrastructure.
- Drums:Steel containment for pharmaceutical and laboratory reagent grades satisfies UN hazardous material classification requirements with seal integrity assurance.
Shipment value concentrates in Bulk Containers; format innovation centers on Sachets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the bulk of technical-grade material while European food-grade demand outpaces domestic supply, forcing cross-border procurement patterns that concentrate trade flows through Rotterdam and Hamburg.
Germany
Industrial bakeries in Bavaria and North Rhine-Westphalia source REACH-registered ammonium carbonate for traditional crisp-baked goods. ECHA substance evaluation protocols filter non-compliant suppliers from consumer-facing segments. The Cologne-Düsseldorf corridor anchors distribution networks serving artisanal and industrial baking clusters.
China
Fertilizer blenders in Shandong and Jiangsu provinces absorb volume production for deep-placement nitrogen delivery. MEE industrial emissions frameworks incentivize producers with carbon capture integration in ammonia synthesis. The Yangtze River Delta concentrates integrated ammonia-carbonate operations serving domestic agrochemical formulation.
United States
FDA-regulated food additive demand under 21 CFR 184.1137 supports leavening-agent procurement for industrial baking. Natural gas price volatility compresses margins for non-integrated producers lacking captive ammonia supply. Midwest milling operations in Illinois and Ohio consolidate direct-to-mill sourcing agreements.
Belgium
Integrated milling and baking operations in Flanders qualify single-source suppliers for multi-year framework agreements. EFSA food-additive frameworks mandate heavy metal thresholds below 10 ppm. The Port of Antwerp handles bulk import flows for northern European distribution.
Switzerland
Pharmacopeial compliance requirements command premium positioning for laboratory reagent applications. Swissmedic certification separates pharmaceutical-grade from technical-grade supply chains. Basel anchors quality-assured distribution serving Swiss and cross-border research institutions.
Ammonium Carbonate Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across certification tiers. Integrated chemical majors leverage captive ammonia supply chains to sustain cost leadership in food-grade distribution. Three archetypes dominate: ammonia-integrated conglomerates with backward control over feedstock, regional pure-plays serving technical-grade agriculture markets, and pharmaceutical-certified specialists commanding laboratory reagent premiums. Competitive moves center on REACH registration consolidation and modular packaging format innovation.
Within the pharmaceutical-certified tier, Merck Group and Thermo Fisher Scientific Inc. exemplify quality-assured positioning for laboratory channels. Among Asia-based producers, Taixing Dongyu Chemical occupies a position serving volume agriculture markets through integrated urea conversion. At the diversified conglomerate end, BASF SE anchors European food-grade supply through ammonia supply chain integration.
| Leading Market Players |
|---|
| BASF SE |
| Thermo Fisher Scientific Inc. |
| Merck Group |
| Bayer CropScience |
| Taixing Dongyu Chemical |
| Shanghai Mingdou Agrochemical Co. Ltd |
| Honeywell International Inc. |
| Avantor |
| Syngenta AG |
| Others |
Supply Flow & Price Mechanics
Analytical chemistry talent scarcity in the Rhine-Ruhr corridor widens pricing-tier spreads between REACH-certified pharmaceutical grades and technical agriculture grades. Labor-cost differentials for ECHA-compliant impurity documentation compress margins at the premium tier while economy-grade producers in Shandong province exploit lower regulatory compliance burdens.
Pricing Analysis
Cost compression in food-grade ammonium carbonate accelerates as natural gas volatility transmits directly to non-integrated producers lacking captive ammonia supply. Three-tier pricing structure across pharmaceutical-certified, food-grade, and technical-economy levels separates buyers by documentation burden and purity threshold. Price differentiation hinges on REACH registration status and batch-specific certificates of analysis. Industrial bakeries in Belgium and the Netherlands exhibit highest price sensitivity, while Swiss laboratory reagent channels tolerate premium positioning.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg consolidate European import flows from Chinese manufacturing clusters. Supply concentrates in China for technical-grade material, Germany for REACH-registered food grades, and Switzerland for pharmaceutical-certified output. Raw material dependencies rest on ammonia feedstock, carbon dioxide supply, and stainless steel processing equipment. Single-source vulnerability around analytical chemistry contract laboratories elevates documentation risk. Distribution runs through direct-to-mill agreements for northern European milling clusters and distributor networks for artisanal bakery segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ammonium carbonate supply remains constrained by REACH registration bottlenecks, with ECHA substance evaluation protocols filtering non-compliant producers and propping pricing power for certified incumbents.
For Market Incumbents: Cement REACH registration consolidation through acquisition of analytical chemistry contract laboratories facing talent scarcity. Expand carbon capture integration in ammonia synthesis to align with China's MEE industrial emissions frameworks and defend margin position against natural gas volatility. Prioritize modular packaging format innovation in pre-measured sachets to capture artisanal bakery segments.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in pharmaceutical-certified grades offers white-space entry for producers achieving pharmacopeial compliance. Target laboratory reagent channels in Switzerland and the United Kingdom where quality-assured positioning commands tolerance for premium pricing. Pursue go-to-market angles through third-party food-safety certification alongside traditional chemical assays.
For Investors and Strategic Acquirers: Re-rating potential sits with ammonia-integrated conglomerates given carbon policy alignment catalysts in Chinese industrial emissions frameworks. Long-term viability favors producers with backward control over feedstock and documentation capabilities spanning FDA, ECHA, and GB standards. Watch for ECHA impurity threshold tightening as inflection indicator for supplier base consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Supply | Captive feedstock production insulates margin from natural gas volatility in European operations. |
| REACH Registration Consolidation | Acquisition of compliant producers filters non-registered competitors from premium consumer-facing segments. |
| Carbon Capture Integration | Alignment with China's MEE frameworks secures operating licenses in Yangtze River Delta manufacturing clusters. |
| Modular Packaging Innovation | Pre-measured sachet formats open artisanal bakery channels previously inaccessible to bulk distribution. |
| Pharmacopeial Certification Investment | Swissmedic and laboratory reagent compliance commands premium positioning in research institution procurement. |
Methodological Framework
Independent corroboration across primary interviews with plant managers at integrated ammonia-carbonate operations, procurement leads at European industrial bakeries, distribution channel partners in Rotterdam and Hamburg, and technical R&D directors at agrochemical formulators underwrites the qualitative findings. Secondary validation draws from customs and trade data, ECHA substance evaluation protocols, SEC 10-K filings of diversified chemical conglomerates, and Chinese GB standards documentation. Bottom-up volume modeling across powder, granule, tablet, and solution formats triangulates against top-down demand aggregation by end-use industry.
Comparable-period anchoring to historical consumption patterns in food-grade leavening and agrochemical formulation establishes baseline trajectory assumptions across the analysis window. Segmentation dimensions span product type, end-user industry, application function, and packaging format, with regional regulatory cluster as an additional modeled variable. CAGRs derive from slope-log regression against normalized consumption indices, incorporating ammonia feedstock cost curves and REACH compliance diffusion rates as industry-specific forecast inputs.
Inputs from ECHA registration databases and Chinese MEE emissions disclosures were available through the study window; gaps in real-time natural gas price transmission data introduce uncertainty bands around margin compression scenarios. Forecasts reflect documented assumptions regarding regulatory threshold evolution and feedstock cost trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Propionic Anhydride Market
Bulk Chemicals
Global Ammonium Sulphate Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
Heavy Alkyl Benzenes Market
Bulk Chemicals
Bistrifluoromethanesulfonimide Lithium Market
Bulk Chemicals
Sheet Molding and Bulk Molding Compounds Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Polyferric Sulfate Market
Bulk Chemicals
Glacial Methacrylic Acid Market
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Cellulose Powder Market