
 Chlor Alkali Market | 2026-2036
Chlor Alkali Market Size, Share, and Industry Trends Forecast 2026-2036
Chlor Alkali Market Analysis
Chinese chlor-alkali producers is recalibrating capacity allocations toward higher-margin specialty grades. Olin Corporation leverages its integrated Gulf Coast asset base to sustain cost-advantaged chlorine and caustic soda output. Westlake Chemical Corporation anchors its position through captive ethylene and chlorine integration across Texas and Louisiana operations. Tata Chemicals Limited competes on soda ash and chlor-alkali co-production economics at its Mithapur complex.
Chlor alkali denotes the electrochemical production of chlorine gas, caustic soda (sodium hydroxide), and hydrogen via brine electrolysis, typically operating at 3.1–4.0 volts per cell depending on membrane or mercury technology selection. The process yields co-products in fixed stoichiometric ratios, making output flexibility central to profitability across chlorine derivatives and alumina refining applications. Caustic soda dominates value capture in pulp and paper bleaching and bauxite processing, while membrane cell technology leads new capacity additions due to energy efficiency and mercury-phaseout compliance. Chlorine demand in polyvinyl chloride and isocyanate chains sustains margin pools even when caustic soda markets soften.
EPA effluent guidelines and OSHA process safety management standards govern US chlor-alkari facility emissions and worker exposure protocols, while REACH and the EU F-Gas Regulation constrain mercury cell persistence and fluorinated byproduct releases in European operations. China's MEE enforces stricter brine waste discharge limits and accelerates mercury cell replacement timelines. Stakeholders must monitor regulatory divergence between jurisdictions to optimize technology investment sequencing and avoid stranded asset risk from uneven phaseout calendars.
Market Dynamics
Membrane cell technology conversion is compressing the competitive set as mercury-dependent assets face accelerated obsolescence under tightening environmental mandates. This electrochemical transition is redrawing cost curves and forcing capital reallocation across integrated chemical producers.
Growth Catalysts
- EU Green Deal industrial decarbonization mandates:The EU F-Gas Regulation and mercury phaseout timelines are compelling membrane cell retrofits at European chlor-alkali facilities, sustaining equipment demand and technology licensing revenue.
- Water treatment utilities:Municipal pH regulation requirements across North America and Europe are expanding caustic soda offtake from chlor-alkali producers serving public infrastructure networks.
- Coastal chemical clusters in China:Rising chlorine consumption for polyvinyl chloride production at Ningbo and Tianjin chemical parks is anchoring capacity expansion decisions.
Market Restraints
- Energy cost volatility:Electricity constitutes the dominant variable cost in brine electrolysis, and grid price spikes in Germany and the UK have compressed operating margins at European membrane cell facilities.
- Supply concentration in Gulf Coast chlorine:Integrated producers along the Texas-Louisiana corridor control disproportionate merchant chlorine volumes, creating pricing leverage and delivery risk for derivative manufacturers elsewhere.
- Caustic soda-to-chlorine demand imbalance:Fixed stoichiometric co-production ratios force output of one molecule when the other is wanted, stranding inventory when alumina or pulp markets soften independently.
Strategic Opportunities
- High-purity caustic soda for semiconductor etching:Electronic-grade specifications are commanding premium pricing as chip fabrication expands in Taiwan, South Korea, and the southwestern United States.
- Green hydrogen co-production integration:Electrolyzer technology convergence with chlor-alkali cells is enabling hydrogen offtake agreements for ammonia and refining applications.
- India's PLI scheme for chemical manufacturing:Production-linked incentives for specialty chemicals are attracting membrane cell investments to serve domestic caustic soda demand in textiles and soaps.
Industry Challenges
- Mercury cell remediation expertise shortage:Decommissioning and hazardous waste handling requires specialized contractors, and qualified engineering firms are concentrated in Germany and Japan.
- Membrane replacement capex cycles:Ion-exchange membrane refresh intervals demand scheduled downtime and working capital commitments that strain mid-scale operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chlor Alkali Market |
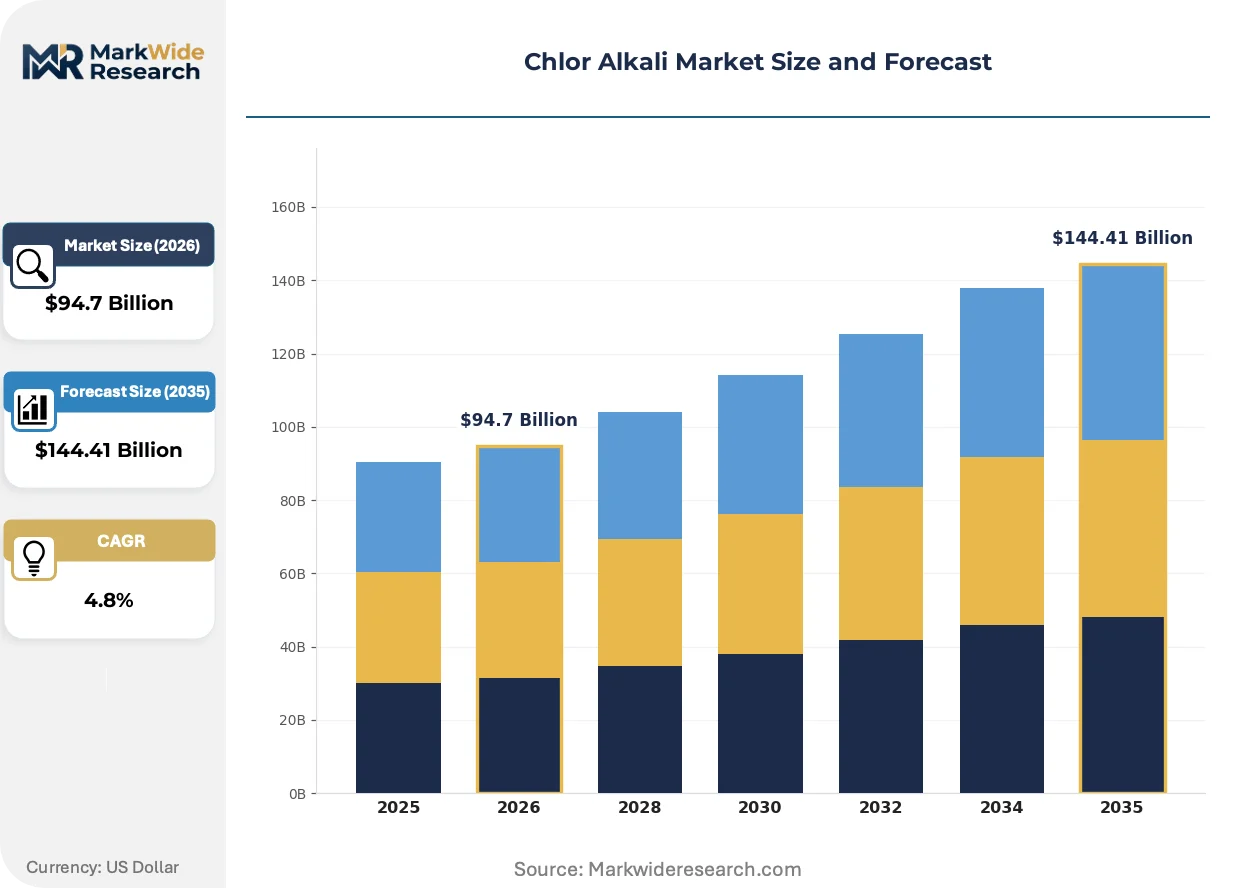
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $144.41 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caustic Soda, Chlorine, Soda Ash, Hydrogen End User: Pulp & Paper, Water Treatment, Chemicals, Textile Technology: Membrane Cell, Diaphragm Cell, Mercury Cell, Ion Exchange Application: Cleaning Agents, Food Processing, Pharmaceuticals, Plastics |
| Companies Covered | Olin Corporation, Westlake Chemical Corporation, Tata Chemicals Limited, Occidental Petroleum Corporation, Formosa Plastics Corporation, Solvay SA, Tosoh Corporation, Xinjiang Zhongtai Chemical Co. Ltd., Hanwha Solutions Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chlor Alkali Market Emerging Trajectories
Electrochemical process intensification and digital cell monitoring are compressing operating envelopes while regulatory chemistry restrictions force feedstock and technology substitutions. These forces are reshaping how producers defend margin pools.
Membrane cell technology is overtaking mercury and diaphragm alternatives in new capacity additions. Pulp and paper bleaching operations in Scandinavia and the southeastern United States are completing conversions ahead of regulatory deadlines. This technology transition is enabling smaller-scale, distributed production economics that erode the historical advantage of mega-complexes.
REACH authorization requirements and the EU F-Gas Regulation are constraining mercury cell persistence and fluorinated byproduct releases. European operators face accelerated asset replacement timelines and higher compliance verification costs. Specialty chlorine derivatives manufacturers in Belgium and the Netherlands are securing alternative supply arrangements ahead of 2025-2027 phaseout milestones.
Long-term offtake contracting is displacing spot market exposure for major caustic soda consumers. Alumina refiners in Australia and pulp mills in Brazil are negotiating five-to-seven-year supply agreements with fixed-volume, indexed-price structures. This procurement pattern shift is most visible in water treatment and mining verticals where input cost predictability outweighs price optimization.
Chlor Alkali Market Segmentation
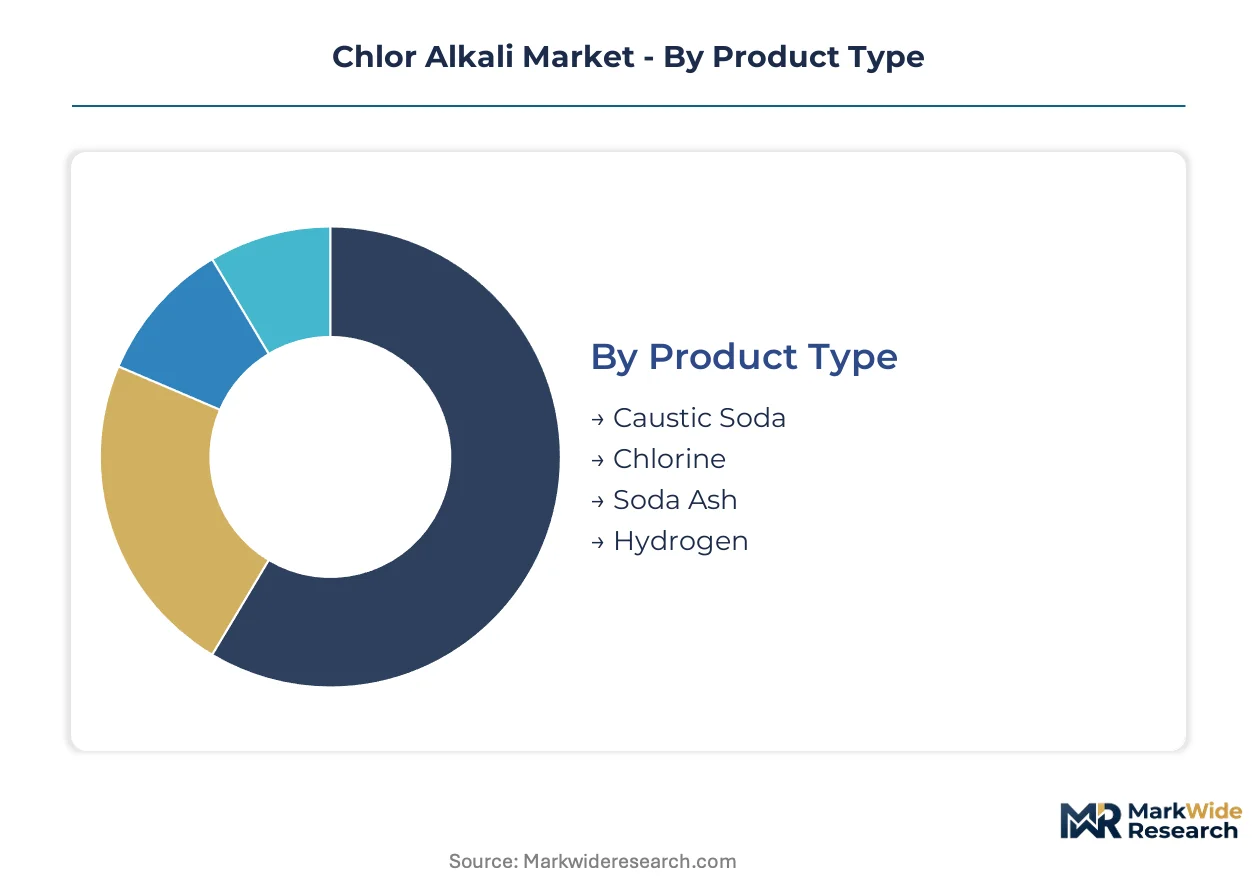
Segmentation in the chlor-alkali sector reveals how fixed stoichiometric co-production ratios create divergent profitability profiles across product lines. Producers must optimize capacity allocation across chlorine derivatives and caustic soda applications where demand cycles rarely synchronize.
Product Type:
Standardization dominates bulk commodity grades while specialty specifications command customization premiums for semiconductor and pharmaceutical purity tiers.
- Caustic Soda:Sodium hydroxide serves as the primary value driver in alumina refining and pulp bleaching, with membrane cell grades capturing premium spreads in bauxite processing across Australian and Guinean operations. Water treatment utilities in Germany and municipal networks across the United States are expanding long-term procurement contracts for 50% concentration material.
- Chlorine:Gaseous chlorine feeds polyvinyl chloride production chains and isocyanate manufacturing, with coastal chemical clusters in China absorbing rising volumes for vinyl chloride monomer synthesis. The fixed co-production ratio with caustic soda creates margin compression when PVC demand softens independently.
- Soda Ash:Synthetic and natural soda ash grades compete in glass manufacturing and detergent formulations, with dense light variants differentiated by bulk density specifications.
- Hydrogen:Byproduct hydrogen from brine electrolysis is gaining offtake traction for ammonia synthesis and petroleum refining applications as electrolyzer technology convergence enables purification upgrades.
Most installed capacity flows through Caustic Soda. Expansion is steepest in Hydrogen as co-production economics improve.
End User:
Volume concentration versus margin dispersion shapes procurement patterns across industrial verticals.
- Pulp & Paper:Scandinavian and southeastern United States bleaching operations are completing membrane cell conversions ahead of regulatory deadlines, driving demand for high-purity caustic soda in kraft pulp processing.
- Water Treatment:Municipal pH regulation requirements across North American and European public infrastructure networks are expanding caustic soda offtake with five-to-seven-year indexed contracting structures.
- Chemicals:Chlorine derivatives manufacturing for solvents, pesticides, and refrigerants consumes merchant chlorine volumes, with pricing leverage concentrated among Gulf Coast integrated producers.
- Textile:Mercerization and dyeing processes in India and Bangladesh absorb standard-grade caustic soda, with PLI scheme incentives attracting domestic membrane cell investments.
Water Treatment commands the steadiest demand profile. Chemicals show the widest margin volatility.
Technology:
Capital intensity and regulatory compliance costs stratify the competitive landscape across electrochemical methods.
- Membrane Cell:Ion-exchange membrane technology leads new capacity additions due to energy efficiency advantages and mercury-phaseout compliance, with European operators accelerating retrofits under EU F-Gas Regulation mandates. The technology enables smaller-scale distributed production economics that erode historical mega-complex advantages.
- Diaphragm Cell:Asbestos-diaphragm alternatives persist in legacy installations where capital constraints delay membrane conversion, particularly in regions with extended regulatory grace periods.
- Mercury Cell:Mercury-dependent assets face accelerated obsolescence under tightening environmental mandates, with China's MEE enforcing stricter phaseout timelines and REACH authorization requirements constraining European persistence.
- Ion Exchange:Emerging electrochemical approaches for specialty chemical production and hydrogen co-capture are attracting pilot investments from integrated producers.
Membrane Cell hosts the dominant installed base. Ion Exchange is climbing the fastest as green hydrogen integration matures.
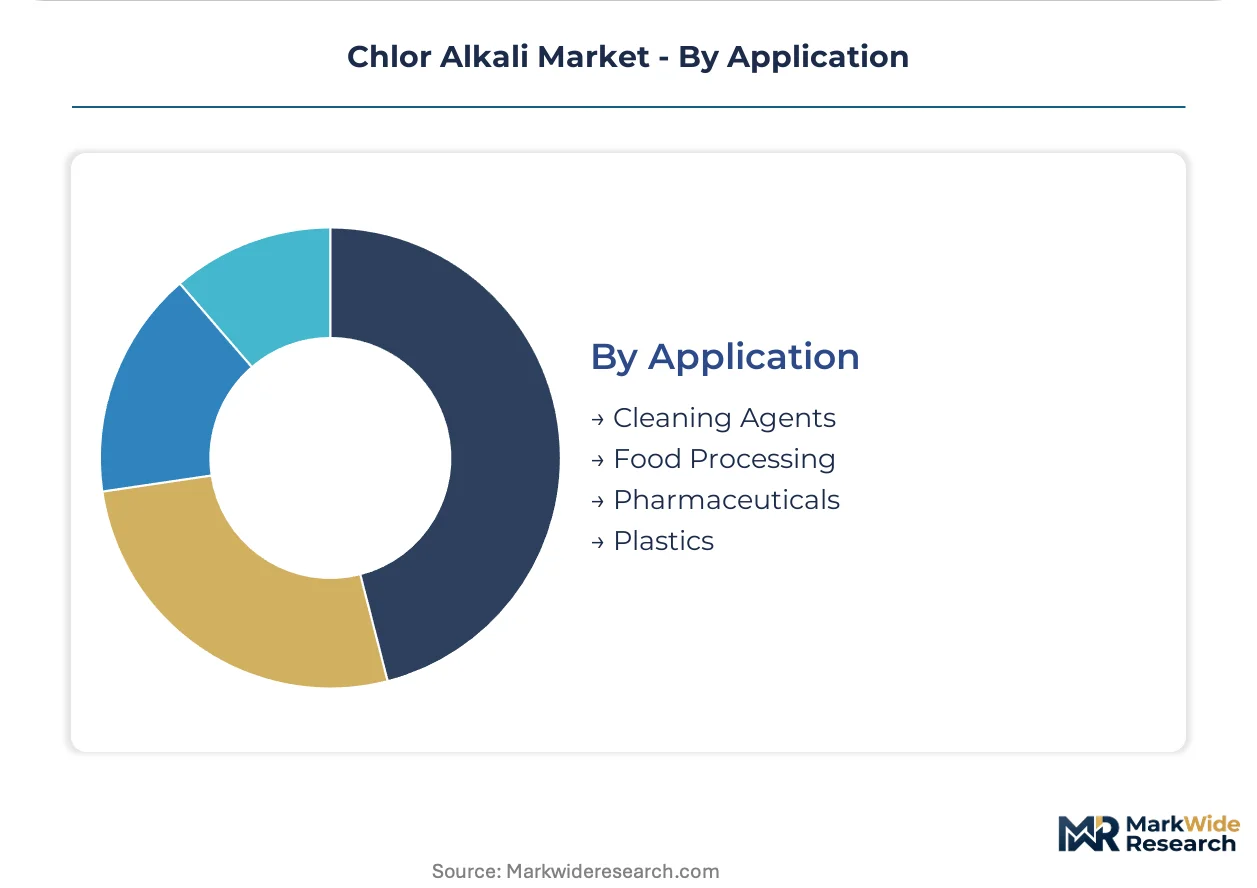
Application:
Specification stringency and certification requirements fragment pricing power across downstream uses.
- Cleaning Agents:Industrial and household detergent formulations consume standard-grade caustic soda, with formulation trends toward concentrated products affecting volume demand.
- Food Processing:FDA and EFSA compliance for food-grade caustic soda in olive curing and cocoa processing commands certification premiums, with purity specifications tightening in European markets.
- Pharmaceuticals:USP-grade material for API synthesis and excipient production requires dedicated production lines and audit trails, limiting qualified supplier pools.
- Plastics:Chlorine consumption for PVC, polycarbonate, and polyurethane precursors anchors volume demand, with construction cycle sensitivity creating demand volatility.
Plastics absorbs the largest chlorine volumes. Pharmaceuticals maintains the tightest supply qualification standards.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between jurisdictions is redirecting capital toward membrane cell retrofits in jurisdictions with accelerated phaseout timelines while preserving legacy capacity where compliance deadlines remain extended. Producers arbitrage these cost-of-compliance gaps through technology licensing and asset relocation strategies.
United States
Water treatment utilities across California and Texas are expanding caustic soda procurement for municipal pH regulation under EPA effluent guidelines. OSHA process safety management standards govern emissions protocols at Gulf Coast facilities. Integrated producers along the Texas-Louisiana corridor leverage captive chlorine-caustic integration to serve polyvinyl chloride manufacturers in Houston and Lake Charles chemical parks.
Germany
Alumina refiners and pulp processors anchor caustic soda demand despite electricity cost volatility compressing membrane cell margins. REACH authorization requirements and the EU F-Gas Regulation are accelerating mercury cell phaseouts in the Rhine-Ruhr industrial belt. Specialty chlorine derivatives manufacturers in Leverkusen and Ludwigshafen are securing alternative supply arrangements ahead of 2025-2027 regulatory milestones.
China
Coastal chemical clusters at Ningbo and Tianjin consume rising chlorine volumes for vinyl chloride monomer synthesis and isocyanate production. The MEE enforces stricter brine waste discharge limits and accelerates mercury cell replacement timelines beyond original schedules. Producers in Shandong and Jiangsu provinces are recalibrating capacity allocations toward higher-margin specialty caustic soda grades for semiconductor and pharmaceutical applications.
India
Textile mercerization and soap manufacturing absorb standard-grade caustic soda volumes across Gujarat and Maharashtra industrial corridors. The PLI scheme for specialty chemicals is attracting membrane cell investments to reduce import dependence. Tata Chemicals Limited anchors domestic supply through co-production economics at its Mithapur complex in Gujarat while newer entrants target Tamil Nadu and Andhra Pradesh for coastal logistics advantages.
Japan
Electronic-grade caustic soda specifications command premium pricing as chip fabrication expands in Kyushu and the Tohoku region. METI energy efficiency standards favor membrane cell technology in capacity renewal decisions. Tosoh Corporation and regional specialists maintain position through high-purity production lines serving pharmaceutical and semiconductor verticals in the Osaka-Kobe industrial zone.
Chlor Alkali Market Vendor Landscape
Gulf Coast producers anchor one tier through integrated chlorine-caustic-hydrogen asset bases; European and Asian specialists hold differentiated positions through technology licensing and specialty grade focus. The competitive set stratifies across three tiers: mega-integrated complexes with captive feedstock control, regional membrane cell operators serving water treatment and alumina verticals, and electronic-grade purity specialists commanding certification premiums. Dominant competitive moves include membrane technology licensing agreements and long-term offtake contracting with municipal utilities and alumina refiners.
Within the integrated producer tier, Olin Corporation and Westlake Chemical Corporation exemplify Gulf Coast asset concentration through Texas and Louisiana operations. Tata Chemicals Limited occupies a position in the co-production economics archetype, leveraging soda ash and chlor-alkali integration at its western India complex. These three anchors represent divergent geographic and structural strategies: US-based coastal integration, Indian subcontinent co-production, and European technology licensing pathways.
| Leading Market Players |
|---|
| Olin Corporation |
| Westlake Chemical Corporation |
| Tata Chemicals Limited |
| Occidental Petroleum Corporation |
| Formosa Plastics Corporation |
| Solvay SA |
| Tosoh Corporation |
| Xinjiang Zhongtai Chemical Co. Ltd. |
| Hanwha Solutions Corporation |
| Others |
Supply Flow & Price Mechanics
Industrial salt and electricity futures indices cascade through chlor-alkali production economics into three distinct pricing tiers: electronic-grade premiums for semiconductor etching, membrane-cell standard grades for alumina and pulp processing, and commodity bulk material for water treatment utilities. Gulf Coast producers leverage captive chlorine-caustic integration to compress delivered costs, while European operators absorb grid price volatility that widens trans-Atlantic spreads.
Pricing Analysis
Direct-to-OEM contracting dominates chlorine offtake to polyvinyl chloride manufacturers, while distributor markups of 8-12% persist in caustic soda sales to fragmented water treatment utilities. Price differentiation rests on membrane cell certification under EU F-Gas Regulation compliance tiers and volume scale commitments from alumina refiners. Cost compression in standard-grade material is intensifying because Chinese coastal clusters are expanding merchant chlorine output. Water treatment municipalities show highest price sensitivity due to indexed procurement budgets, while semiconductor fabs accept premiums for parts-per-billion purity specifications.
Supply Chain Analysis
Dual-sourcing mandates from European specialty chemical manufacturers are accelerating qualification of alternative chlorine suppliers ahead of mercury cell phaseout deadlines. Geographic supply concentration centers on the United States Gulf Coast, coastal China, and Germany's Rhine-Ruhr corridor. Raw material dependencies draw from industrial salt deposits, ion-exchange membranes, and grid electricity. Single-source vulnerability runs through membrane supply where Asahi Kasei and Chemours anchor global production. Distribution runs through pipeline networks for integrated derivatives manufacturers and rail-tank car fleets for merchant caustic soda delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
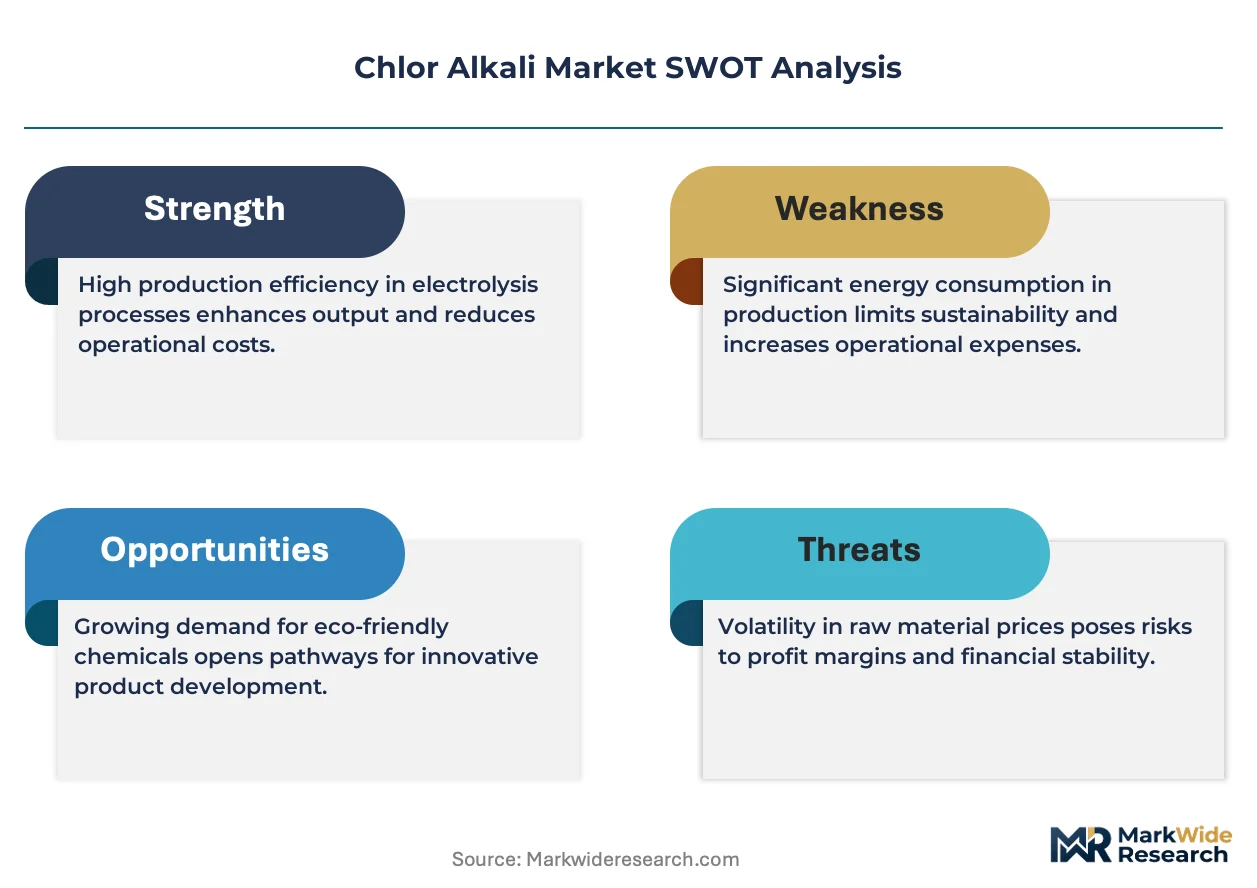
The chlor-alkali market functions as a stable compounder where fixed stoichiometric co-production ratios and regulatory-mandated technology conversions sustain predictable replacement demand cycles.
For Market Incumbents: Anchor position through membrane cell technology licensing to operators facing EU F-Gas Regulation deadlines, capturing equipment and engineering revenue streams. Deepen backward integration into captive salt dome storage and pipeline distribution networks to defend margin pools against merchant market volatility. Prioritize long-term offtake contracting with Australian alumina refiners and Brazilian pulp mills to lock in volume visibility.
For New Entrants and Emerging Players: India's PLI scheme for specialty chemicals opens a window for membrane cell investments targeting textile mercerization and soap manufacturing demand in Gujarat and Maharashtra. Electronic-grade caustic soda for semiconductor fabrication in Taiwan and South Korea presents the most penetrable premium tier, with qualification timelines shorter than pharmaceutical USP-grade pathways. Pursue toll-manufacturing arrangements with established distributors to bypass capital-intensive storage and logistics infrastructure.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-scale membrane cell operators in jurisdictions with extended mercury phaseout grace periods, where regulatory arbitrage sustains cash flow visibility. Five-to-ten-year viability hinges on conversion cost recovery timelines and hydrogen co-production economics. Watch membrane replacement capex cycles as inflection indicators for working capital stress and distressed acquisition opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| Membrane Cell Retrofit | EU F-Gas Regulation compliance sustains equipment demand and technology licensing revenue across European facilities. |
| Long-term Supply Agreement | Indexed five-to-seven-year contracts with Australian alumina refiners reduce spot market exposure and margin volatility. |
| Green Hydrogen Integration | Electrolyzer convergence enables ammonia synthesis offtake agreements and diversifies revenue beyond chlorine derivatives. |
| Electronic-grade Capacity Addition | Parts-per-billion purity production lines command 40-60% premiums from Taiwan and South Korean semiconductor fabs. |
| Backward Integration into Salt | Captive brine supply from underground dome storage compresses variable costs and insulates against industrial salt price spikes. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with chlor-alkali plant managers, procurement leads at alumina refiners and pulp mills, membrane technology licensors, and distribution channel partners with secondary validation from customs trade data, American Chemistry Council and Cefic industry reports, SEC 10-K filings, and EPA effluent compliance records. Bottom-up capacity installation tracking and top-down end-use demand modeling were cross-referenced for triangulation.
Historical reference periods anchored the projection horizon to observed technology conversion cycles, regulatory phaseout timelines, and electricity price volatility patterns across the modeling period. Segmentation dimensions included grade tier (electronic, membrane, commodity), end-use industry (alumina, pulp, water treatment, PVC, semiconductors), technology type, and regional production hub clustering. CAGRs were derived from installed capacity forecasts, operating rate assumptions, and price elasticity estimates for chlorine and caustic soda offtake.
Revisions become necessary when mercury cell phaseout schedules accelerate, grid electricity price spikes exceed historical bands, or membrane supply disruptions constrain technology conversion timelines. Forecasts reflect documented assumptions about regulatory enforcement intensity, trade flow patterns, and derivative demand elasticity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Butyric Acid Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Ethyleneamines Market
Bulk Chemicals
Europe Acetic Acid Market
Bulk Chemicals
Acrylamide Market
Bulk Chemicals
Dextrin Market
Bulk Chemicals
Gluconic Acid Market
Bulk Chemicals
Oxalic Acid Market
Bulk Chemicals
2-Methylfuran Market
Bulk Chemicals
Bromine Market
Bulk Chemicals
Zinc Acetate Market
Bulk Chemicals
Cesium Salts Market
Bulk Chemicals
Zinc Carbonate Market
Bulk Chemicals
Global Bulk Ferroalloys Market
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
North America Potassium Formate Market