
 Global Ammonium Phosphate Market | 2026-2036
Global Ammonium Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ammonium Phosphate Market Foresight
Blended fertilizer bundling is broadening buyer choice across the ammonium phosphate value chain. Nutrien Ltd leverages its integrated potash-phosphate network to control North American distribution channels. Yara International ASA anchors its position through ammonia self-sufficiency and deepwater terminal access. The Mosaic Company competes on Florida phosphate rock extraction scale and sulfuric acid backward integration.
Ammonium phosphate denotes a family of nitrogen-phosphorus compounds produced via the exothermic reaction of phosphoric acid with ammonia, yielding products with N-P-K ratios typically ranging from 11-52-0 to 18-46-0 depending on the ammoniation endpoint. These compounds serve primarily as high-analysis fertilizer sources where both nitrogen and phosphorus availability drive crop yield response. Diammonium phosphate holds the dominant volume position within product type segmentation due to its superior nutrient density and lower production cost per unit P2O5, while technical grade commands premium pricing in flame retardant and industrial applications where purity thresholds exceed agricultural specifications. Food grade ammonium phosphate occupies a narrow but defensible margin pool within the grade segmentation, constrained by CODEX and national food safety certifications that limit supplier qualification.
EPA nutrient management regulations in the United States and REACH chemical registration requirements in Europe shape product formulation standards and cross-border market access for ammonium phosphate derivatives. China's MEE wastewater discharge standards and SAMR fertilizer quality inspections impose additional compliance layers on producers serving Asian agricultural markets. Stakeholders must monitor phosphate rock reserve depletion timelines in Morocco and Jordan alongside ammonia feedstock cost volatility to align capacity investments with sustainable supply security.
Market Dynamics
China's MEE emissions standards and dual carbon goals are forcing phosphate capacity relocation toward cleaner production corridors, compressing supply timelines for agricultural buyers while elevating capital requirements for facility upgrades.
Growth Catalysts
- Brazilian soybean expansion:Cerrado zone clearing and double-cropping intensity drive phosphate consumption density per hectare beyond historical baselines.
- REACH chemical registration pathways:Streamlined dossier approvals for ammonium phosphate derivatives accelerate EU market access for compliant formulations.
- Flame retardant specification tightening:Technical-grade purity thresholds in electronics and construction materials expand addressable premium segments.
Market Restraints
- Phosphate rock reserve concentration:Moroccan and Jordanian state-controlled mining consortia concentrate upstream supply leverage, exposing buyers to sovereign pricing discretion.
- Ammonia feedstock volatility:Natural gas price swings at US Gulf Coast and Middle Eastern production nodes transmit directly into diammonium phosphate variable costs.
- Substitute fertilizer chemistry:Urea-based nitrogen sources and single superphosphate alternatives compete on price in phosphorus-deficient soil applications.
Strategic Opportunities
- India PLI scheme alignment:Domestic fertilizer manufacturing incentives under production-linked investment frameworks attract capacity localization for import substitution.
- Controlled-release coating convergence:Polymer-sulfur encapsulation technologies married to ammonium phosphate cores enable precision agriculture premium capture.
- Deepwater terminal distribution:Direct vessel loading at phosphoric acid production points bypasses intermediate handling, compressing landed costs for Southeast Asian buyers.
Industry Challenges
- Process engineering talent scarcity:Wet-process phosphoric acid expertise and ammonia-plant operations knowledge concentrate among retiring workforce cohorts.
- Sulfuric acid backward integration capex:Captive sulfuric acid production requires metallurgy and environmental control investments that strain mid-tier balance sheets.
- Codex food-grade certification timelines:Multi-year qualification protocols for leavening acid applications constrain supplier pool expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ammonium Phosphate Market |
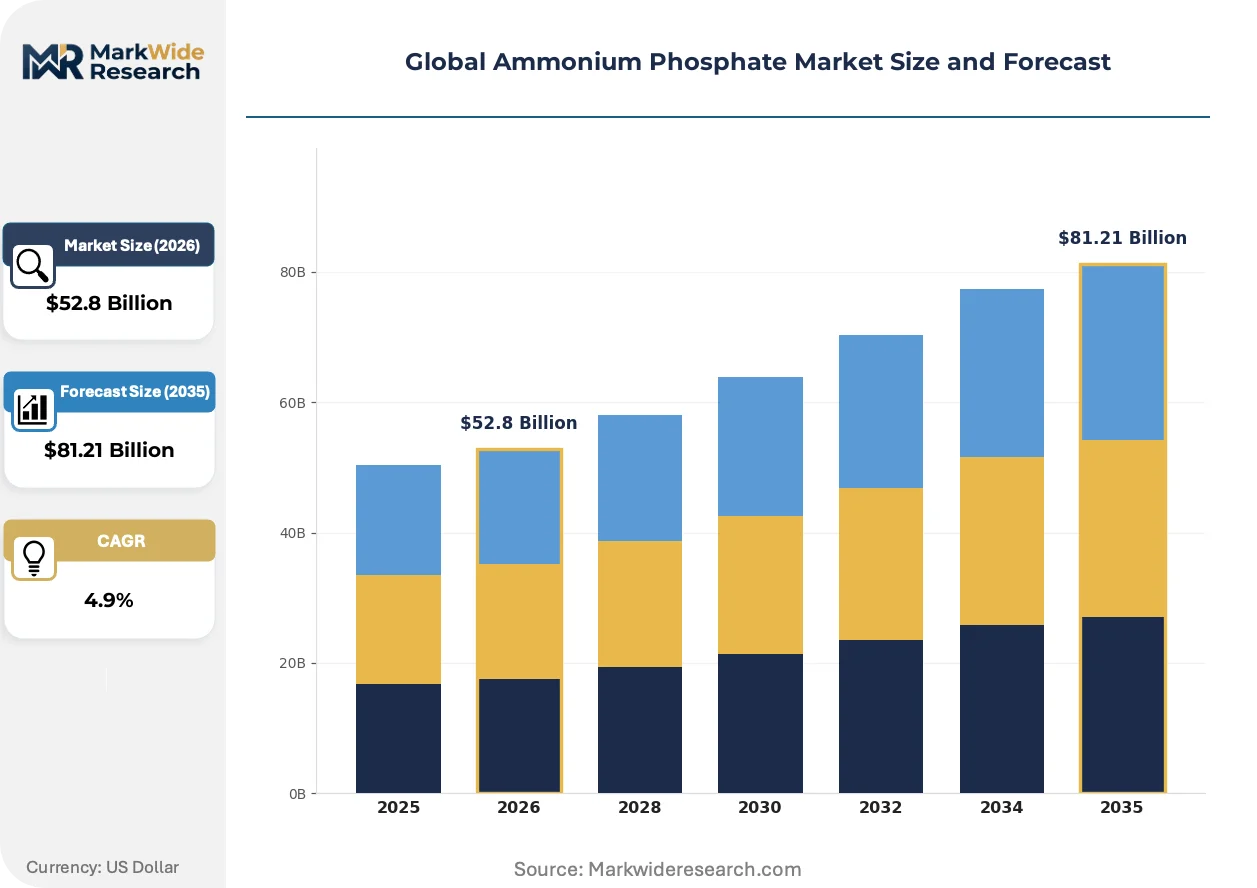
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $81.21 Billion |
| CAGR (2026 – 2036) | 4.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoammonium Phosphate, Diammonium Phosphate, Triple Superphosphate, Rock Phosphate Grade: Technical Grade, Food Grade, Agricultural Grade, Industrial Grade Application: Fertilizers, Flame Retardants, Animal Feed, Detergents, Corrosion Inhibitors End User Industry: Agriculture, Chemical Manufacturing, Animal Husbandry, Water Treatment |
| Companies Covered | Nutrien Ltd, Yara International ASA, The Mosaic Company, OCP Group, PhosAgro, EuroChem Group AG, CF Industries Holdings, ICL Group Ltd, K+S AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ammonium Phosphate Market Shifts & Advancements
Process intensification and regulatory chemistry are compressing traditional production economics while opening margin pools in precision application formats. The competitive frontier is shifting from commodity volume toward formulation specificity and carbon-accounted supply chains.
Membrane filtration and crystallization optimization in phosphoric acid purification is rewriting technical-grade production economics. Electronics and industrial flame retardant manufacturers are adopting these higher-purity streams at accelerating rates. The technology is compressing the cost gap between agricultural and industrial grades, enabling margin migration toward specification-driven buyers.
EPA nutrient management regulations in the United States mandate phosphorus runoff mitigation through enhanced-efficiency fertilizer formulations. Fertilizer blenders must reformulate standard diammonium phosphate grades with stabilizer additives or polymer coatings. Agricultural retailers in the Corn Belt and Mississippi River watershed are restructuring procurement specifications to satisfy total maximum daily load compliance.
Buyer consolidation among North American agricultural cooperatives is compressing distributor tiers and concentrating volume leverage. Direct manufacturer-to-farm-gate contracting is displacing traditional wholesale intermediaries in soybean and corn procurement zones. Brazil's Cerrado and US Midwest grain belts exhibit the most pronounced channel restructuring, with cooperatives demanding carbon-footprint documentation alongside nutrient analysis.
Global Ammonium Phosphate Market Segmentation
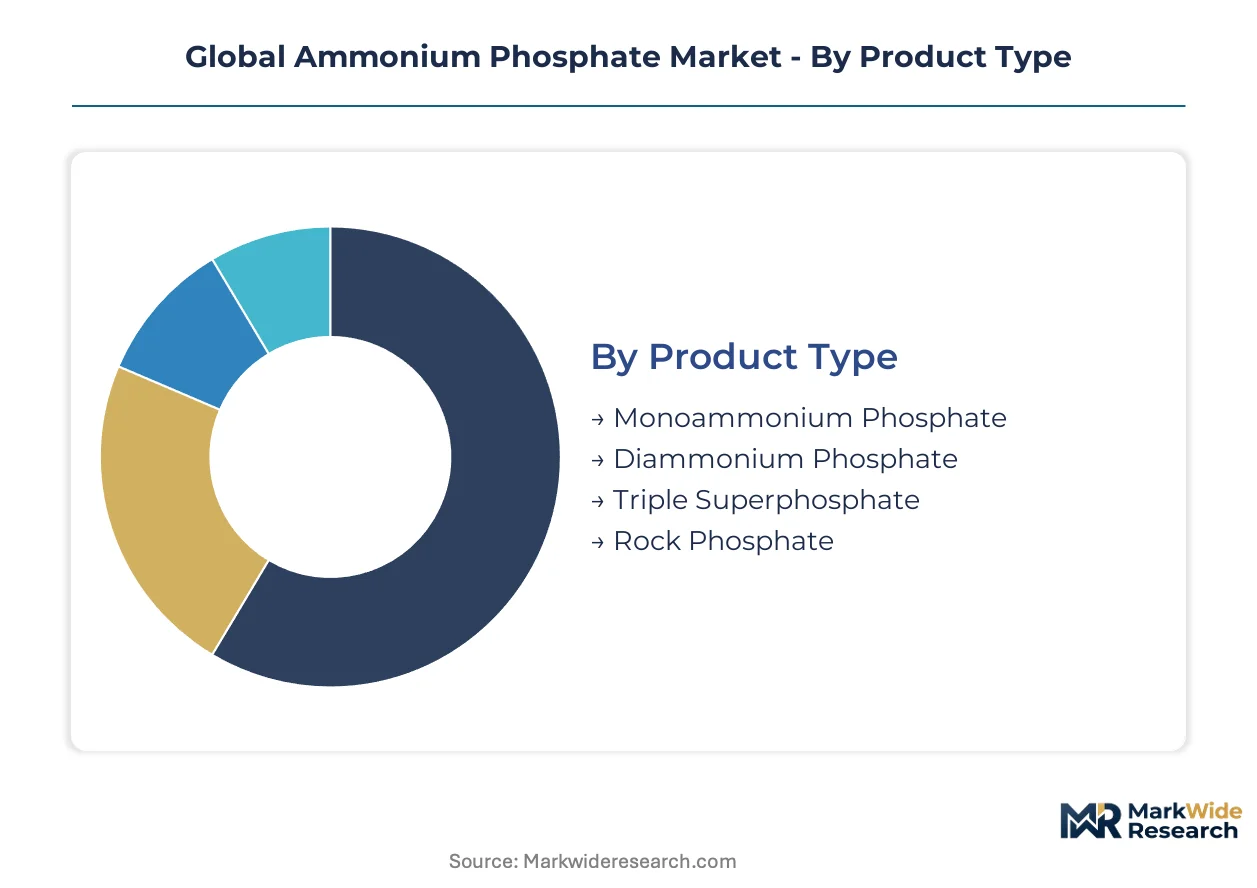
Segmentation in ammonium phosphate markets reveals how nutrient density specifications, purity thresholds, and end-use chemistry requirements partition value capture across the value chain. Product type and grade classifications determine capital intensity and regulatory burden, while application diversity creates margin dispersion between commodity agriculture and specialized industrial formulations.
Product Type:
Supply concentration in diammonium phosphate manufacturing dominates capacity allocation, with production corridors in Florida, Morocco, and China's Guizhou province anchoring global availability.
- Diammonium Phosphate:Contains 18% nitrogen and 46% P2O5, produced via complete neutralization of phosphoric acid with ammonia. Brazilian Cerrado soybean operations and US Corn Belt corn-soy rotations absorb the majority of traded volumes, driven by double-cropping intensity that depletes soil phosphorus rapidly.
- Monoammonium Phosphate:Lower nitrogen content at 11% N with 52% P2O5 concentration, favored in starter fertilizer applications and high-pH soil conditions. North American specialty blenders and controlled-release coating facilities concentrate procurement in this grade for precision agriculture formulations.
- Triple Superphosphate:Produced through phosphoric acid reaction with phosphate rock, yielding 48% P2O5 without nitrogen content. African and Southeast Asian markets lacking ammonia infrastructure favor this product for pure phosphorus supplementation.
- Rock Phosphate:Unprocessed mineral concentrate requiring direct soil application or acidulation, serving organic farming certifications and low-input agricultural systems in sub-Saharan Africa and parts of India.
Today's leader: Diammonium Phosphate. Tomorrow's challenger: Monoammonium Phosphate.
Grade:
Cost tier stratification separates commodity agricultural supply from certified food and technical specifications, with purification steps and analytical testing determining price multiples.
- Agricultural Grade:Standard fertilizer specifications with modest impurity tolerances for heavy metals and moisture. Brazil, India, and the United States account for the bulk of procurement, with EPA nutrient management regulations and India's PLI scheme redirecting formulation requirements toward enhanced-efficiency variants.
- Technical Grade:Elevated purity for electronics flame retardants and industrial catalyst applications, requiring membrane filtration and crystallization optimization. Chinese membrane technology providers and German specialty chemical distributors control qualification pathways for this segment.
- Food Grade:CODEX-compliant leavening acid for baking applications, with multi-year certification protocols limiting supplier pool expansion. North American and European food manufacturers maintain tight qualification standards that constrain new market entrants.
- Industrial Grade:Intermediate purity for water treatment and metal finishing, positioned between agricultural and technical specifications. Municipal water utilities in the United States and EU chemical processors drive steady demand without premium capture.
Agricultural Grade commands current volume leadership. Technical Grade offers the steepest expansion trajectory as electronics manufacturing concentrates in Southeast Asia.
Application:
Application diversity spans soil chemistry, material science, and animal nutrition, with each domain imposing distinct formulation and regulatory requirements.
- Fertilizers:Dominant application combining nitrogen and phosphorus delivery in single-granule or bulk-blend formats. Brazil's Cerrado expansion and India's rice-wheat systems sustain the highest consumption density per hectare globally.
- Flame Retardants:Technical-grade ammonium phosphate intumescence in construction materials and electronics housings. EU REACH registration pathways and tightening fire safety codes in Germany and France accelerate specification adoption.
- Animal Feed:Monocalcium and dicalcium phosphate derivatives for livestock mineral supplementation. US Midwest feed mills and Brazilian integrated poultry operations integrate these inputs into ration formulations.
- Detergents:Phosphate builders in industrial cleaning formulations, declining in household applications due to eutrophication regulations. Remaining demand concentrates in institutional and food-processing sanitation sectors.
- Corrosion Inhibitors:Ammonium polyphosphate derivatives for water treatment and metal protection. Municipal systems in Texas, California, and industrial corridors around Shanghai deploy these chemistries for infrastructure preservation.
Fertilizers anchor present demand. Flame Retardants are climbing the fastest as construction safety codes tighten across developed economies.
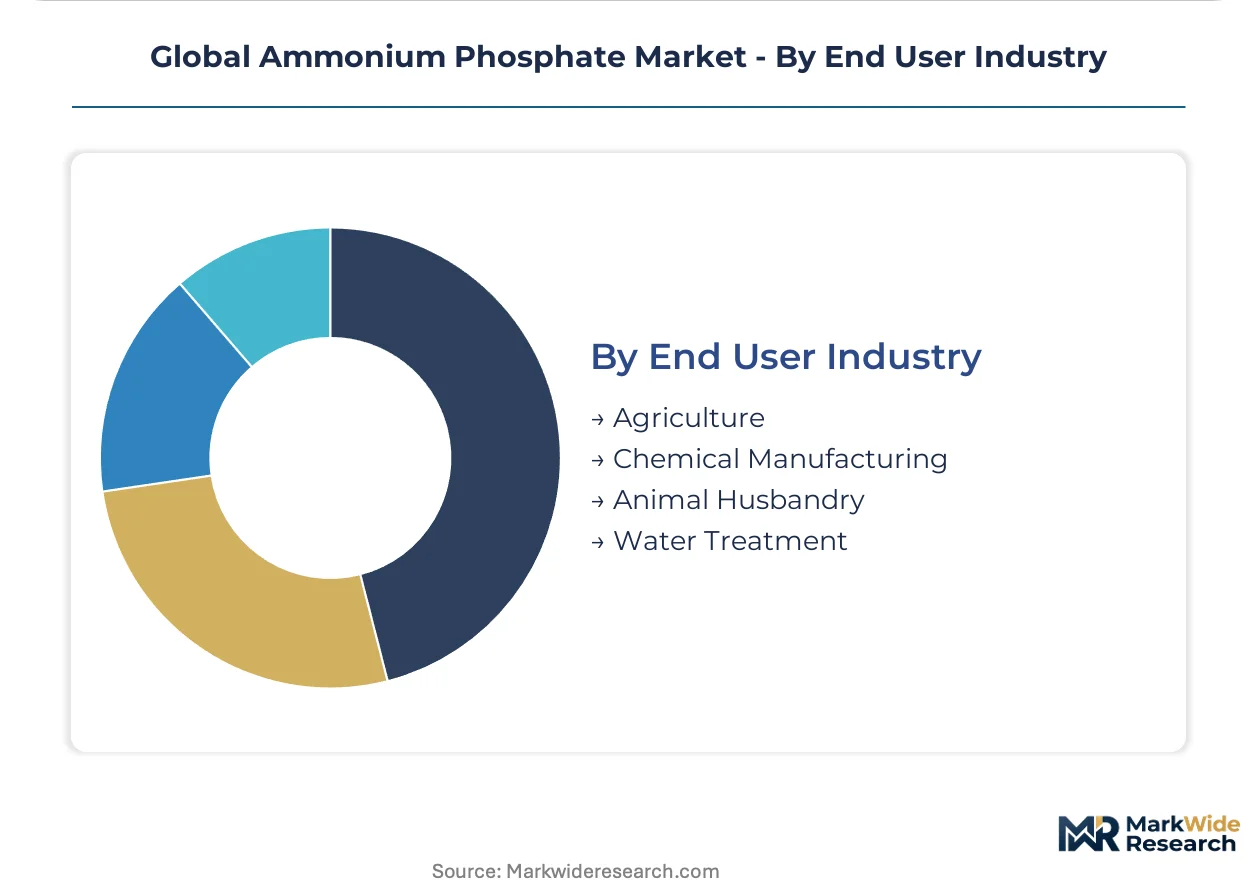
End User Industry:
Customer type segmentation reveals divergent procurement patterns between price-sensitive agricultural cooperatives and specification-driven industrial buyers.
- Agriculture:Grain cooperatives, plantation operators, and government procurement agencies purchasing bulk fertilizer volumes. Direct manufacturer-to-farm-gate contracting is displacing traditional wholesale intermediaries in soybean and corn procurement zones.
- Chemical Manufacturing:Specialty and commodity chemical producers integrating ammonium phosphate as feedstock or process input. German and Chinese chemical clusters maintain the deepest backward integration into phosphoric acid production.
- Animal Husbandry:Integrated livestock operations and independent feed mills sourcing mineral supplements. Vertical coordination between Brazilian meatpackers and phosphate suppliers compresses distributor participation.
- Water Treatment:Municipal utilities and industrial facilities deploying phosphate for corrosion control and lead sequestration. US EPA lead and copper rule revisions drive specification changes in Midwestern and Northeastern systems.
Agriculture retains volume dominance. Chemical Manufacturing is gaining share fastest as industrial phosphate derivatives multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The modern ammonium phosphate industry traces its commercial scale to early 20th-century Tennessee Valley Authority phosphate development in the United States, with production corridors later multiplying across phosphate-rich sedimentary basins in North Africa and China's karst formations.
United States
Florida's Bone Valley phosphate district and Louisiana's ammonia corridor supply the Corn Belt's corn-soy rotation intensity. EPA nutrient management regulations mandate phosphorus runoff mitigation through enhanced-efficiency formulations. Agricultural cooperatives in Iowa and Illinois now demand carbon-footprint documentation alongside nutrient analysis.
China
Guizhou and Yunnan provinces host the country's wet-process phosphoric acid concentration, serving domestic rice-wheat systems and export markets. MEE wastewater discharge standards and dual carbon goals are compressing supply timelines while elevating capital requirements for facility upgrades. Cleaner production corridors in Hubei are absorbing relocated capacity.
Brazil
Mato Grosso and Goiás states in the Cerrado zone drive phosphate consumption density through soybean double-cropping expansion. ANVISA fertilizer quality inspections and state-level environmental licensing impose compliance layers on imported and domestic supply. Port terminals in Paranaguá and Santos are deepening vessel access for direct manufacturer delivery.
Morocco
Khouribga and Youssoufia mining districts anchor OCP Group's phosphate rock extraction scale for downstream ammonium phosphate production. State-controlled mining consortia concentrate upstream supply leverage, exposing buyers to sovereign pricing discretion. Jorf Lasfar industrial complex integrates phosphoric acid, ammonia, and finished fertilizer manufacturing.
India
Gujarat and Andhra Pradesh fertilizer complexes process imported phosphate rock and ammonia for rice-wheat and cotton-producing regions. The PLI scheme's production-linked investment frameworks attract capacity localization for import substitution. SAMR-aligned quality inspections and subsidy reform debates reshape procurement specifications.
Global Ammonium Phosphate Market Competitive Landscape
Premium-margin players sit above commodity-margin players across grade purity and application specificity, with technical-grade and food-grade specialists commanding price multiples over agricultural-grade bulk suppliers. The vendor base stratifies into integrated mining-fertilizer conglomerates, ammonia-self-sufficient nitrogen-phosphorus compounders, and regional blenders dependent on traded intermediates. Three archetypes dominate: phosphate rock owners with captive acid production, ammonia-integrated fertilizer manufacturers with deepwater terminal access, and specialty chemical purifiers serving electronics and food safety certifications. Competitive moves center on sulfuric acid backward integration and controlled-release coating technology licensing.
Within the integrated mining-fertilizer tier, Nutrien Ltd and The Mosaic Company exemplify North American phosphate rock ownership combined with distribution channel control. Yara International ASA occupies a position among ammonia-self-sufficient European compounders leveraging deepwater terminal infrastructure. OCP Group and PhosAgro represent state-linked and privately held mining conglomerates respectively, anchoring Moroccan and Russian supply security narratives for import-dependent buyers.
| Leading Market Players |
|---|
| Nutrien Ltd |
| Yara International ASA |
| The Mosaic Company |
| OCP Group |
| PhosAgro |
| EuroChem Group AG |
| CF Industries Holdings |
| ICL Group Ltd |
| K+S AG |
| Others |
Supply & Pricing Matrix
China's dual carbon goals and MEE emissions standards gate qualified supply and premium-tier pricing access, forcing facility upgrades that compress agricultural-grade margins while elevating technical-grade premiums for compliant producers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CODEX-certified food-grade ammonium phosphate from agricultural bulk and technical specifications for flame retardants. Price differentiation hinges on membrane filtration intensity and REACH registration completeness, with Chinese membrane technology providers capturing margin from purification steps. Pricing pressure stems from ammonia feedstock volatility at US Gulf Coast and Middle Eastern production nodes transmitting directly into diammonium phosphate variable costs. Agricultural cooperatives in Brazil's Cerrado exhibit highest price sensitivity, while electronics manufacturers in Germany and France absorb technical-grade premiums without volume elasticity.
Supply Chain Analysis
Reverse-logistics flows for phosphoric acid purification byproducts and spent catalyst materials from technical-grade production are emerging as cost-recovery channels for Chinese and German specialty chemical operators. Supply concentrates in Morocco's Khouribga mining district, Florida's Bone Valley, and China's Guizhou province, with OCP Group and The Mosaic Company anchoring upstream rock extraction. Raw material dependencies center on phosphate rock concentrate, anhydrous ammonia, and sulfuric acid for wet-process acidulation. Single-source vulnerability from Moroccan state-controlled mining consortia exposes buyers to sovereign pricing discretion. Distribution runs through deepwater terminals at Jorf Lasfar, Paranaguá, and Louisiana's ammonia corridor, bypassing intermediate handling for Southeast Asian and Brazilian buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through controlled-release coating technology premiums and carbon-accounted supply chain certification, with precision agriculture bundling shifting buyer willingness-to-pay toward specification-driven formulations.
For Market Incumbents: Cement sulfuric acid backward integration and captive ammonia supply to defend against feedstock volatility at US Gulf Coast and Middle Eastern nodes. Expand membrane filtration capacity for technical-grade purification serving EU REACH-registered flame retardant specifications. Lock in long-term offtake contracts with Brazilian agricultural cooperatives before channel consolidation completes.
For New Entrants and Emerging Players: Deepwater terminal operators in Southeast Asia present partnership opportunities for direct vessel loading bypassing intermediate handling costs. Target India's PLI scheme-aligned domestic fertilizer manufacturing for import substitution capacity, leveraging SAMR-aligned quality inspection protocols as qualification pathway. Enter through controlled-release coating technology licensing rather than greenfield acid production.
For Investors and Strategic Acquirers: Roll-up economics work for regional blenders dependent on traded intermediates because buyer consolidation among North American agricultural cooperatives is compressing distributor tiers and concentrating volume leverage. Five-to-ten year viability favors ammonia-self-sufficient compounders with deepwater terminal access over pure-play mining operators exposed to phosphate rock reserve depletion timelines. Monitor EPA nutrient management regulation tightening in Mississippi River watershed states as inflection indicator for enhanced-efficiency formulation demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sulfuric Acid | Captive sulfuric acid production at Florida and Moroccan complexes insulates margin from metallurgy cost swings. |
| Membrane Filtration Scale-Up | Chinese and German technology providers compress technical-grade production economics for electronics flame retardant buyers. |
| Controlled-Release Coating Licensing | Polymer-sulfur encapsulation married to ammonium phosphate cores enables precision agriculture premium capture. |
| Deepwater Terminal Expansion | Direct vessel loading at Jorf Lasfar and Paranaguá compresses landed costs for Southeast Asian agricultural buyers. |
| Carbon-Accounted Supply Chain Certification | Midwest agricultural cooperatives now demand carbon-footprint documentation alongside nutrient analysis for procurement compliance. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region combining executive interviews with phosphate plant managers, procurement leads at Brazilian soybean cooperatives, distribution channel partners in Indian fertilizer complexes, and technical R&D directors at German specialty chemical distributors. Secondary validation draws from customs and trade data, OCP Group and Nutrien Ltd SEC filings, MEE wastewater discharge standard publications, and Brazilian ANVISA fertilizer quality inspection records. Bottom-up capacity and demand modeling triangulates against top-down macroeconomic indicators across the analysis window.
Rate-of-change decomposition separates volume growth from price-mix effects across grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived through regression analysis of historical production capacity, feedstock cost trajectories, and regulatory implementation timelines. Industry-specific forecast inputs include phosphate rock reserve depletion curves for Moroccan and Jordanian state-controlled mining consortia, ammonia feedstock cost volatility at US Gulf Coast and Middle Eastern production nodes, and EPA nutrient management regulation adoption rates in Corn Belt and Mississippi River watershed states.
Revisions become necessary when MEE emissions standard enforcement intensifies beyond announced timelines, Brazilian Cerrado clearing regulations tighten, or Moroccan sovereign pricing discretion shifts contract structures. Practitioners should monitor ammonia natural gas price spreads, REACH dossier approval velocities, and agricultural cooperative consolidation announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Benzyl Chloride Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
Global Purified Terephthalic Acid (PTA) Market
Bulk Chemicals
Barite Market
Bulk Chemicals
North America Lime Market
Bulk Chemicals
United States Soda Ash Market
Bulk Chemicals
Benzyl Chloroformate Market
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
Alkali Metal Hydroxides Market
Bulk Chemicals
Europe Quicklime Market
Bulk Chemicals
Zinc L-Pidolate Market
Bulk Chemicals
Calcium Hypophosphite Market
Bulk Chemicals
Lithium Chloride Market
Bulk Chemicals
Sodium Bisulfite Market