
 Ceramic Kilns Market | 2026-2036
Ceramic Kilns Market Size, Share, and Industry Trends Forecast 2026-2036
Ceramic Kilns Market Insights
Digital firing control architecture is reconfiguring how ceramic kilns manage temperature profiles, energy recovery, and batch consistency across production cycles. L&L Kiln Mfg Inc. leverages proprietary electronic control systems to anchor its position in precision firing for technical ceramics. Nabertherm-Kilns sustains engineering leadership through modular furnace designs that serve laboratory and industrial end users across European markets. Skutt competes in the studio-artist segment with user-friendly programmable interfaces that lower operator skill barriers.
Ceramic kilns are thermally insulated enclosures designed to reach controlled temperatures exceeding 1,200°C for sintering, vitrification, and glaze development of clay-based and advanced ceramic materials. Continuous roller kiln systems dominate tiles fabrication due to throughput economics and thermal efficiency, while batch electric kilns retain margin strength in artisanal pottery and educational settings where firing flexibility outweighs scale requirements. Tunnel kiln technology leads sanitaryware production, where extended firing curves and automated pusher systems reduce per-unit energy consumption.
EPA emissions guidelines and EU Green Deal decarbonization targets are forcing gas-fired kiln operators to evaluate electric retrofits or carbon capture add-ons, reshaping capital expenditure priorities for commercial manufacturers. China's MIIT enforces GB standards on industrial furnace efficiency that directly affect kiln import specifications and domestic equipment upgrade cycles. Stakeholders must monitor how dual carbon goals in Asia and evolving F-Gas Regulation thresholds in Europe redirect procurement patterns toward low-emission firing technologies.
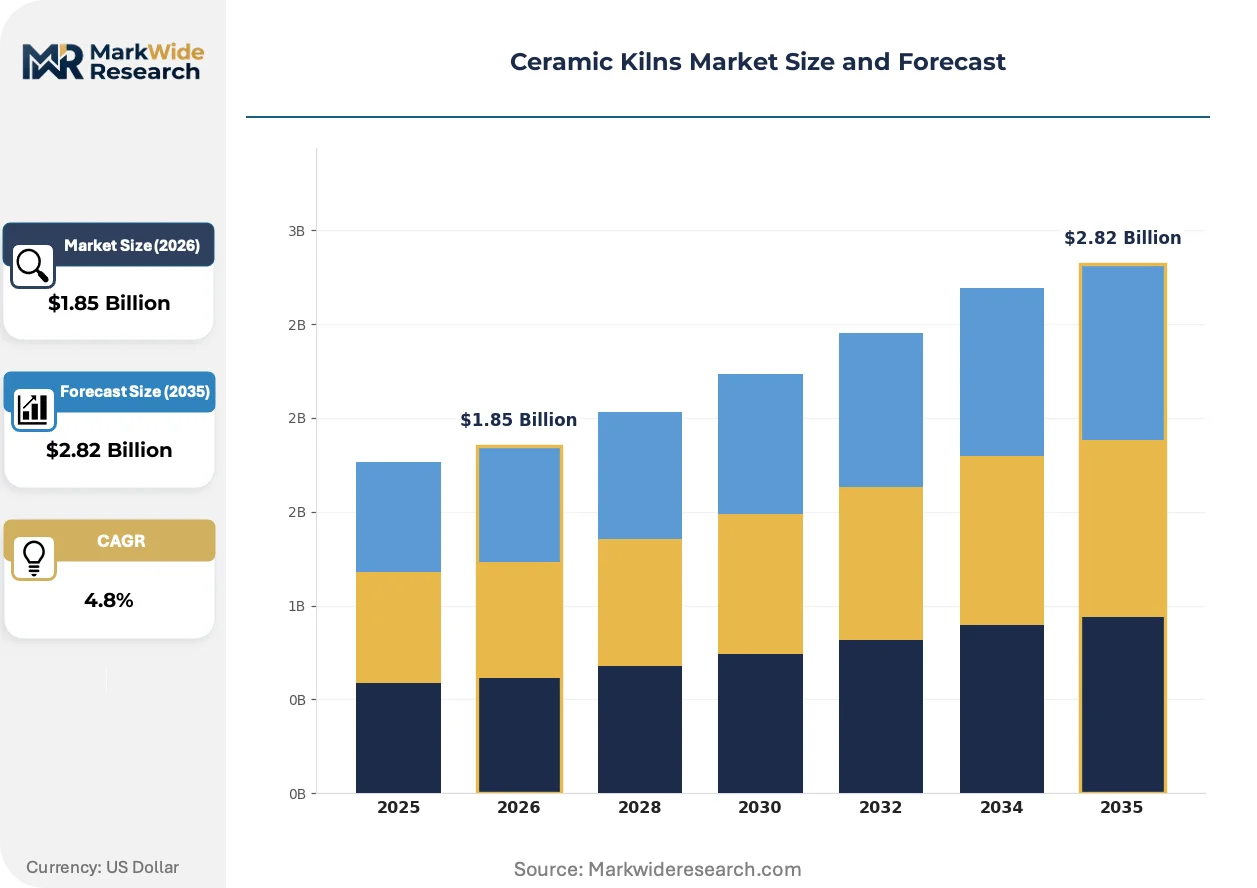
Market Dynamics
EPA emissions guidelines and EU Green Deal decarbonization protocols are forcing gas-fired kiln operators toward electric retrofits and carbon capture add-ons, fundamentally restructuring capital deployment across ceramic manufacturing.
Growth Catalysts
- GB Standards Enforcement:China's MIIT mandates on industrial furnace efficiency accelerate domestic equipment replacement cycles and drive technology import specifications for foreign kiln suppliers.
- Sanitaryware Automation:Tunnel kiln systems with automated pusher mechanisms reduce per-unit energy consumption, attracting investment from large-scale bathroom fixture manufacturers seeking throughput economics.
- Foshan Cluster Density:Ceramic tile production concentration around Foshan and Zibo generates continuous replacement demand and technology upgrade cycles among established operators.
Market Restraints
- Refractory Material Volatility:Sporadic supply constraints and price fluctuations for high-alumina bricks and silicon carbide linings compress margins for kiln fabricators and operators alike.
- Electric Grid Capacity Limits:Industrial zones in Germany, Italy, and parts of the US Midwest face insufficient grid infrastructure to support mass electric kiln conversion without multi-year utility upgrades.
- F-Gas Regulation Thresholds:Evolving EU F-Gas restrictions on fluorinated greenhouse gases complicate cooling system designs for temperature-critical firing processes.
Strategic Opportunities
- India PLI Scheme Alignment:Production-linked incentive frameworks for advanced ceramics and technical materials create procurement pull for precision-controlled batch kiln systems in laboratory and aerospace applications.
- IoT-Enabled Predictive Maintenance:Convergence of thermal sensors, edge computing, and cloud analytics enables kiln-as-a-service business models that unbundle hardware from operational expertise.
- Artisanal Studio Expansion:North American and European hobbyist potter segments show sustained demand for compact programmable electric kilns with user-friendly interfaces that reduce operator training requirements.
Industry Challenges
- Pyrometry Skill Scarcity:Experienced technicians capable of calibrating multi-zone temperature profiles and diagnosing thermal uniformity issues remain in short supply across manufacturing regions.
- Legacy Control Integration:Retrofitting analog kiln infrastructure with digital firing architectures requires custom engineering that extends commissioning timelines and strains technical support capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ceramic Kilns Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.82 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Kiln Type: Electric Kilns, Gas Kilns, Wood-Fired Kilns, Microwave Kilns, Solar Kilns Technology: Batch Kilns, Continuous Kilns, Tunnel Kilns, Roller Kilns, Shuttle Kilns Application: Tableware Manufacturing, Sanitaryware Production, Artisanal Pottery, Tiles Fabrication, Insulator Production End User Industry: Educational Institutions, Industrial Workshops, Artist Studios, Commercial Manufacturers, Research Laboratories |
| Companies Covered | L&L Kiln Mfg Inc., Nabertherm-Kilns, Skutt, Nutec Bickley, Soul Ceramics, Paragon Industries, Olympic Kilns, Cress Mfg. Co., Amaco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ceramic Kilns Market Trends and Innovations
Digital firing architectures and emissions compliance frameworks are compressing traditional equipment lifecycles while opening new service-based revenue streams for kiln technology providers.
Advanced refractory linings incorporating nanostructured ceramics and engineered thermal barriers are collapsing the maintenance intervals and energy loss rates that previously defined kiln operating economics. Tableware manufacturers in Japan and Germany are adopting these materials aggressively, reducing reline frequency from annual to biennial cycles. This compression of downtime windows is reshaping supplier relationships toward long-term refractory service contracts rather than spot material purchases.
EU Green Deal decarbonization targets and companion F-Gas Regulation amendments are mandating phase-outs of high-global-warming-potential cooling agents in kiln auxiliary systems. Industrial ceramic producers in Spain, Italy, and Poland face accelerated capital planning horizons as national implementation timelines diverge from EU baseline schedules. Gas-fired tunnel kiln operators are responding with hybrid electric-gas retrofit designs and pilot carbon capture installations at flagship facilities.
Tableware and tile manufacturers are consolidating procurement authority into centralized technical purchasing functions that negotiate enterprise-wide service agreements spanning multiple production sites. Distributor networks that previously stocked standardized kiln models are ceding ground to direct manufacturer relationships with dedicated application engineering support. This channel compression is most pronounced in China, where Foshan-based tile groups and Zibo sanitaryware clusters negotiate volume commitments in exchange for embedded technical service personnel.
Ceramic Kilns Market Segmentation
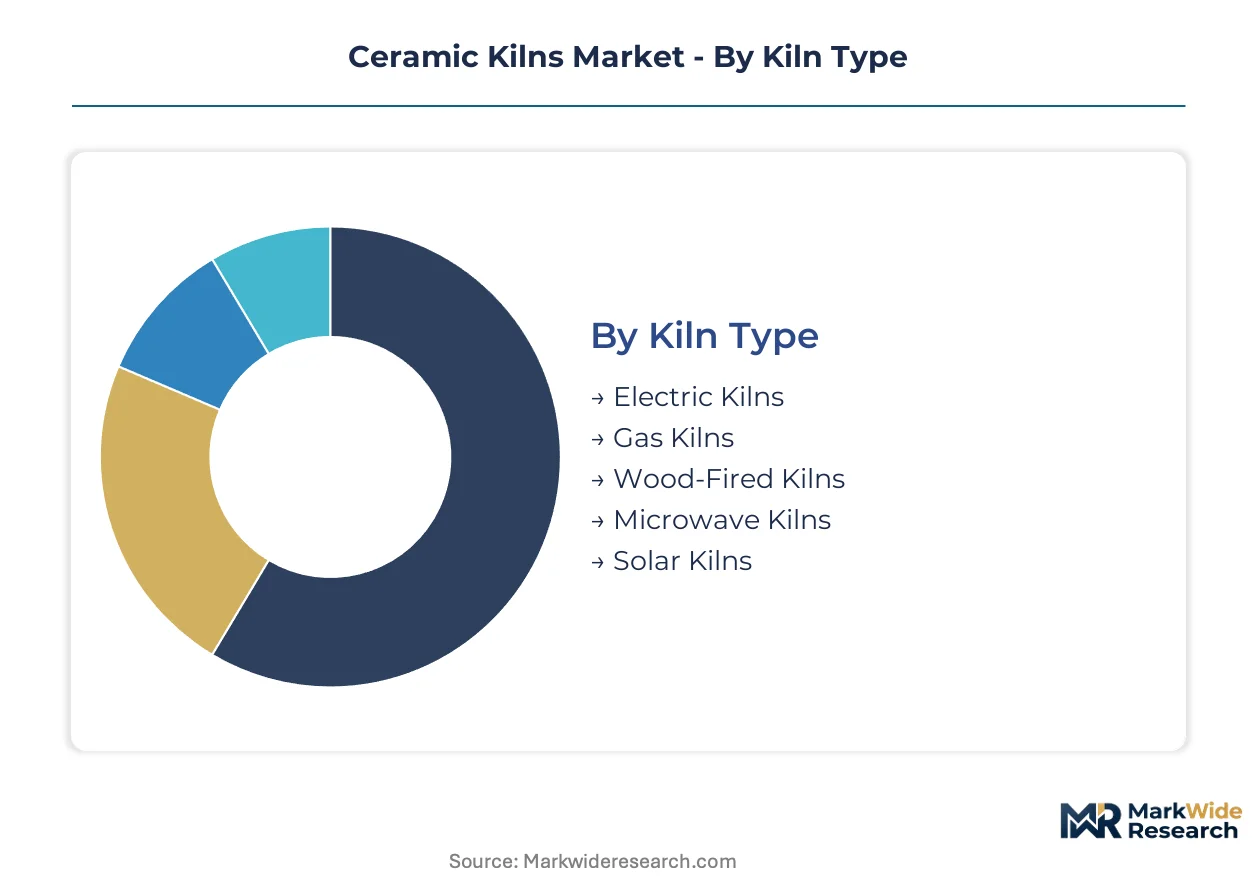
Kiln technology selection dictates thermal efficiency, emissions profile, and capital recovery timelines across ceramic manufacturing operations. Segmentation reveals how firing method, production architecture, and end-use requirements fragment procurement patterns and supplier specialization strategies.
Kiln Type:
Mature electric and gas technologies anchor industrial procurement, while emerging alternatives carve niche positions in sustainability-focused segments.
- Electric Kilns:Resistance-heated chambers deliver precise temperature control with zero direct emissions, making them the default choice for studio artists and educational facilities facing tightening EPA and EU Green Deal protocols. China’s MIIT efficiency mandates and Germany’s grid decarbonization targets are accelerating electric retrofits in Foshan tile clusters and Italian sanitaryware plants.
- Gas Kilns:Combustion-fired systems achieve faster ramp rates and higher peak temperatures for reduction firing effects prized in technical ceramics and traditional tableware. Operators in Spain and Poland face accelerated replacement cycles as national implementations of EU F-Gas Regulation and carbon pricing mechanisms erode the cost advantage of natural gas.
- Wood-Fired Kilns:Traditional combustion architecture produces distinctive flame-path markings for high-end artisanal pottery in Japan and the Pacific Northwest.
- Microwave Kilns:Dielectric heating enables rapid small-batch processing for dental ceramics and jewelry-scale technical applications.
- Solar Kilns:Concentrated thermal collection serves experimental sustainable pottery initiatives in Australia and rural India with unreliable grid access.
Electric kilns retain volume leadership; microwave kilns hold the steepest expansion curve in specialized technical applications.
Technology:
Production scale and thermal mass requirements determine whether batch flexibility or continuous throughput economics dominate equipment selection.
- Continuous Kilns:Unfired ware moves through sequential temperature zones on automated conveyors, minimizing thermal cycling losses that plague batch operations. Foshan tile manufacturers deploy roller-hearth variants to achieve throughput exceeding 15,000 square meters daily per line.
- Tunnel Kilns:Pusher-car systems extend firing curves across 100+ meter lengths for sanitaryware vitrification, with German and Italian OEMs embedding heat recovery stacks that capture 30-40% of exhaust thermal energy for dryer preheating.
- Batch Kilns:Enclosed chamber designs accommodate variable load sizes and experimental glaze formulations for research laboratories and artist studios.
- Roller Kilns:Thin-profile tile firing dominates Chinese export-oriented production with rapid cool zones preventing thermal shock defects.
- Shuttle Kilns:Intermittent car-bottom configurations serve heavy sanitaryware and insulator markets requiring extended soak periods.
Continuous systems dominate volume; tunnel kilns are climbing the fastest in energy-intensive sanitaryware retrofit cycles.
Application:
Surface quality specifications and firing atmosphere requirements fragment kiln procurement across ceramic end-use categories.
- Tiles Fabrication:Roller-hearth continuous kilns achieve rapid firing cycles under 45 minutes for glazed wall and floor tiles, with Foshan and Zibo operators demanding multi-zone temperature profiling to control flatness tolerances within 0.5%.
- Sanitaryware Production:Tunnel kiln systems with 18-24 hour firing curves ensure complete vitrification of thick-walled bathroom fixtures, with Italian manufacturers leading automated glazing robot integration to reduce labor intensity.
- Tableware Manufacturing:Decoration-sensitive firing requires controlled oxidation atmospheres for decal adherence and color stability.
- Artisanal Pottery:Small-batch electric and gas kilns prioritize operator control over throughput economics.
- Insulator Production:High-voltage ceramic components demand precise alumina phase transformation achieved in specialized shuttle kiln configurations.
Tiles fabrication commands the largest installed base; sanitaryware production is gaining share fastest through automation-driven replacement demand.
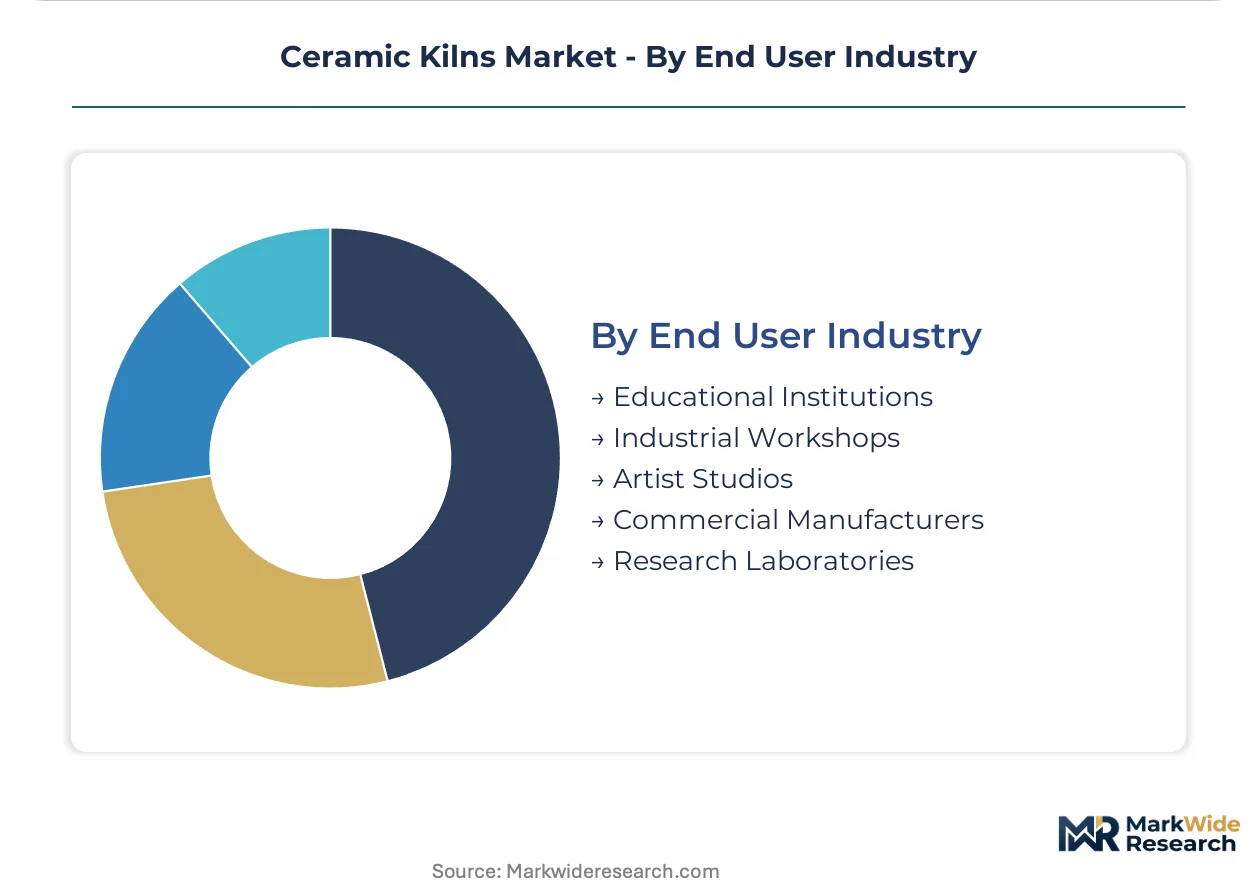
End User Industry:
Capital availability and technical staffing depth create divergent procurement patterns across institutional and commercial buyer categories.
- Commercial Manufacturers:Large-scale tile and sanitaryware producers negotiate enterprise service agreements with embedded technical personnel, consolidating procurement authority into centralized engineering functions that specify IoT-enabled predictive maintenance architectures.
- Artist Studios:North American and European hobbyist segments drive compact programmable electric kiln demand, with user-friendly interfaces reducing pyrometry training requirements for part-time operators.
- Educational Institutions:University and community college ceramics programs prioritize safety interlocks and ventilation integration over firing sophistication.
- Industrial Workshops:Mid-scale tableware and technical ceramic operations balance batch flexibility with semi-automated loading systems.
- Research Laboratories:Precision-controlled batch configurations serve materials science and aerospace ceramic development with atmosphere-controllable environments.
Commercial manufacturers retain volume leadership; artist studios are expanding most quickly through North American hobbyist market penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German kiln fabricators export precision tunnel systems to sanitaryware producers in Italy and Spain, while Chinese equipment dominates tile manufacturing clusters across Southeast Asia and the Middle East.
China
Foshan and Zibo tile clusters drive replacement demand for roller-hearth continuous kilns with multi-zone temperature profiling. MIIT enforces GB standards on industrial furnace efficiency that accelerate domestic upgrade cycles. Zibo sanitaryware manufacturers negotiate volume commitments with embedded technical service personnel from equipment suppliers.
Germany
Grid decarbonization targets and carbon pricing mechanisms push gas-fired operators toward electric retrofits and hybrid systems. The country's national environmental regulator implements EU Green Deal protocols with accelerated national timelines. Tunnel kiln OEMs in North Rhine-Westphalia embed heat recovery stacks capturing exhaust thermal energy for dryer preheating.
Italy
Sanitaryware automation attracts investment from bathroom fixture manufacturers seeking throughput economics through extended firing curves. The national implementation of EU F-Gas Regulation complicates cooling system designs for temperature-critical processes. Sassuolo ceramic tile producers consolidate procurement into centralized technical purchasing functions.
United States
EPA emissions guidelines force commercial manufacturers to evaluate electric retrofits or carbon capture add-ons for existing gas-fired infrastructure. Industrial zones in the Midwest face insufficient grid capacity to support mass electric kiln conversion without multi-year utility upgrades. Pacific Northwest artisanal studios sustain demand for compact programmable electric kilns with user-friendly interfaces.
India
Production-linked incentive frameworks for advanced ceramics create procurement pull for precision-controlled batch kiln systems in laboratory applications. The country's central efficiency authority mandates industrial furnace performance standards affecting import specifications. Morbi tile clusters in Gujarat drive continuous replacement demand amid technology upgrade cycles.
Ceramic Kilns Market Competitive Landscape
On the supply side, the industry is fragmented across specialized fabricators serving distinct thermal processing niches. Tiered competitive positioning separates premium engineering houses from volume-oriented equipment assemblers and regional maintenance providers. Three strategic archetypes dominate: precision control specialists, modular furnace engineers, and studio-artist segment suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players seek geographic coverage and technology access.
Within the precision control tier, L&L Kiln Mfg Inc. and Nabertherm-Kilns occupy positions anchored by proprietary electronic architectures and modular designs respectively. Skutt exemplifies the studio-artist archetype through programmable interfaces that reduce operator skill barriers. These three companies represent distinct competitive vectors spanning industrial, laboratory, and hobbyist end-use segments without overlapping core positioning.
| Leading Market Players |
|---|
| L&L Kiln Mfg Inc. |
| Nabertherm-Kilns |
| Skutt |
| Nutec Bickley |
| Soul Ceramics |
| Paragon Industries |
| Olympic Kilns |
| Cress Mfg. Co. |
| Amaco |
| Others |
Pricing and Supply Chain Analysis
Foshan's roller-hearth kiln manufacturing corridor concentrates capacity for continuous tile firing systems, creating asymmetric pricing power for domestic fabricators serving Southeast Asian export markets. This supply hub density compresses margins for European tunnel kiln suppliers competing on technical ceramics precision, while refractory material volatility propagates cost shocks through liner replacement cycles.
Pricing Analysis
Next-generation IoT-enabled firing controls command substantial premiums over analog legacy systems and basic programmable units. Pricing stratifies across premium, standard, and economy tiers based on thermal sensor density and cloud analytics integration, with certification tier (CE-marked vs non-certified) adding further differentiation. Cost compression in mid-range electric kilns is intensifying because Chinese MIIT efficiency mandates accelerate domestic production scale. Educational institutions and artist studios exhibit highest price sensitivity, while commercial tile manufacturers prioritize total cost of ownership over capital expenditure.
Supply Chain Analysis
EU dual-use export controls on advanced thermal sensor arrays and precision pyrometry components constrain flows to certain Asian manufacturing zones. Kiln fabrication draws from concentrated supply bases in China, Germany, and Italy, with silicon carbide heating elements and high-alumina refractory bricks sourced from Japanese and American specialty ceramic producers. Single-source vulnerability pervades engineered thermal barrier nanomaterials, where patent-protected formulations limit qualified suppliers. Distribution runs through direct manufacturer relationships with embedded technical service personnel, displacing traditional distributor networks in volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across kiln technology tiers creates defendable niches as emissions compliance splits demand between electric retrofit specialists and hybrid-system engineers. The divergence between artisanal studio requirements and industrial automation specifications prevents consolidation into unified product platforms.
For Market Incumbents: Insulate core revenue streams by deepening backward integration into refractory material production, capturing margin otherwise lost to silicon carbide and alumina price volatility. Establish captive service engineering teams within Foshan and Zibo manufacturing clusters to lock out European competitors from replacement cycles. Prioritize GB standards pre-certification for equipment bound for China, as MIIT enforcement tightens import specifications. For New Entrants and Emerging Players: Mid-scale sanitaryware producers in Poland and Spain represent the most penetrable entry point, as accelerated EU F-Gas Regulation implementation forces premature replacement of gas-fired tunnel systems. India's Morbi tile cluster offers secondary expansion potential through PLI scheme alignment for precision batch configurations. Lead with kiln-as-a-service financing models that unbundle hardware capital from operational expertise, reducing procurement committee friction. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance infrastructure play because emissions mandates across EPA, EU Green Deal, and China's dual carbon goals structurally extend equipment replacement cycles while elevating service contract values. Target acquisition profiles emphasize IoT-enabled predictive maintenance platforms with existing embedded relationships at commercial manufacturers. Monitor MIIT enforcement intensity and F-Gas Regulation amendment timelines as inflection indicators for capital deployment pacing.| Strategic Initiative | Industry Significance |
|---|---|
| Refractory Material Backward Integration | Captive supply of silicon carbide elements insulates margins from commodity volatility affecting kiln fabricators. |
| IoT-Enabled Predictive Maintenance Platform | Cloud analytics integration transforms transactional equipment sales into recurring service revenue streams. |
| GB Standards Pre-Certification Program | MIIT compliance alignment accelerates market access for foreign suppliers targeting Chinese tile clusters. |
| Hybrid Electric-Gas Retrofit System Development | EU Green Deal carbon pricing creates immediate demand for transitional firing architectures. |
| Kiln-as-a-Service Financing Model | Unbundled hardware and operational expertise reduces capital barriers for mid-scale sanitaryware producers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade databases, industrial furnace efficiency filings, and ceramic manufacturing association reports. Plant engineers at Foshan tile clusters, procurement leads at Italian sanitaryware OEMs, aftermarket service heads at German tunnel kiln fabricators, and R&D directors at refractory material suppliers provided operational perspective. SEC 10-K disclosures from listed equipment manufacturers, MIIT GB standard enforcement records, and EU ETS carbon price series furnished validation anchors. Bottom-up unit economics and top-down sectoral demand curves underwent iterative reconciliation.
Forecast inputs span kiln type, technology architecture, application segment, and end-user industry classification across the analysis window. Modeled dimensions include firing method differentiation, production scale tier, and regional regulatory cluster alignment. CAGRs derive from installed base turnover rates, replacement cycle compression under emissions mandates, and penetration curves for digital control systems. Refractory material cost trajectories and grid decarbonization timelines inform scenario weighting.
Practitioners should monitor MIIT enforcement intensity, EU F-Gas Regulation amendment schedules, and silicon carbide supply availability for early signals of forecast deviation. Material shifts in China's dual carbon goal implementation pace or German grid capacity expansion timelines would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ceramics
Lithium Zirconate Market
Ceramics
Co-Fired Ceramic Market
Ceramics
Nano Ceramic Coatings Market
Ceramics
Glazed Bricks Market
Ceramics
Southeast Asia Melamine Market
Ceramics
Global High Performance Ceramic Coatings Market
Ceramics
East Africa Ceramic Tiles Market
Ceramics
Global Wollastonite Powder Market
Ceramics
Global Industrial Clay Market
Ceramics
Global Barium Carbonate Market
Ceramics
Alumina Slurry Market
Ceramics
Engineering Ceramics Market
Ceramics
Advanced Structural Ceramics Market
Ceramics
United Kingdom Ceramic Tiles Market
Ceramics
Global Functional Ceramics Market
Ceramics
West Africa Ceramic Tiles Market