
 Aniline Market | 2026-2036
Aniline Market Size, Share, and Industry Trends Forecast 2026-2036
Aniline Market Intelligence
The end-use mix for aniline is shifting, with consumption increasingly tied to polyurethane production for automotive components and insulation, rather than its historical base in dye manufacturing. Wanhua Chemical Group dominates the MDI value chain, giving it significant control over aniline feedstock. BASF SE leverages its integrated Verbund production sites in Europe and Asia to optimize costs. Huntsman Corporation competes through its specialized polyurethane systems and advanced material formulations.
Aniline is an aromatic amine with the chemical formula C6H5NH2, produced mainly through the catalytic hydrogenation of nitrobenzene. It functions as a critical chemical intermediate, with its primary application being the synthesis of methylene diphenyl diisocyanate (MDI). The market's application structure is dominated by MDI production for polyurethane foams in the automotive and construction sectors. Other applications like dye manufacturing and rubber processing constitute mature, slower-growing segments.
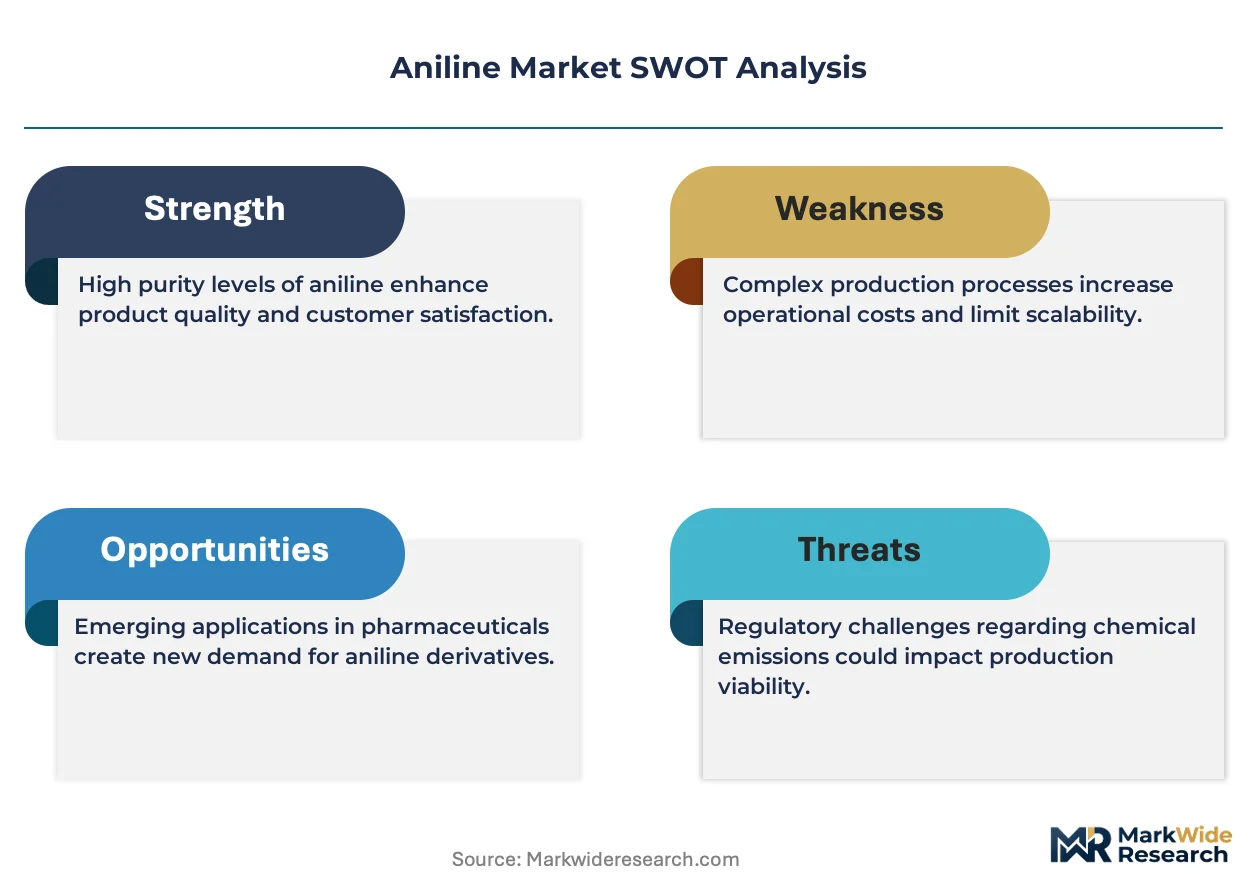
Regulatory oversight from the European Chemicals Agency (ECHA) under REACH and the U.S. EPA imposes strict controls on aniline handling, worker exposure, and emissions. China's Ministry of Ecology and Environment (MEE) mandates cleaner production technologies to meet national environmental targets. Producers must now decide between capacity expansion in established chemistries or investing in bio-based aniline pathways to meet long-term sustainability criteria.
Market Dynamics
The aniline value chain is consolidating around the production of methylene diphenyl diisocyanate (MDI). This structural force links aniline's market fate directly to the capital-intensive polyurethane industry, concentrating production and pricing power in geographies with large-scale, integrated MDI facilities.
Growth Catalysts
- Automotive Sector Demand:Consumption of polyurethane foams and elastomers in automotive components like seating, dashboards, and bumpers requires a steady supply of aniline for MDI synthesis, particularly as manufacturers seek lightweight materials to improve fuel efficiency.
- Energy Efficiency Mandates:Global building codes and standards promoting energy efficiency drive the use of rigid polyurethane foam for insulation. This application directly stimulates demand for aniline as a primary MDI precursor.
- Chinese Industrial Policy:China's dual carbon goals are accelerating investment in modern, large-scale, and more energy-efficient aniline production technologies to support its dominant position in the global MDI market.
Market Restraints
- Feedstock Volatility:The price of aniline is closely tied to its primary precursor, nitrobenzene, which is derived from benzene. Fluctuations in crude oil and aromatics markets create significant input cost volatility for producers.
- Regulatory Compliance Costs:Stringent regulations, such as the EU's REACH framework, impose substantial costs related to chemical registration, handling protocols, and worker exposure monitoring, creating barriers to market entry and operation.
- Substitution Research:Ongoing research and development into bio-based alternatives, such as those derived from glucose or lignin, present a long-term substitution threat to petroleum-based aniline, especially in sustainability-focused applications.
Strategic Opportunities
- Bio-Based Aniline Pathways:Investing in the development and scaling of bio-based production routes offers a significant opportunity for differentiation, allowing producers to meet corporate sustainability goals and appeal to environmentally conscious customers.
- Emerging Market Infrastructure:Growth in construction and manufacturing sectors in regions like Southeast Asia and India represents an opportunity for capacity expansion to serve local demand for polyurethanes, reducing reliance on imports.
- Process Technology Licensing:Companies with proprietary, high-yield, and low-energy catalytic hydrogenation processes can license this technology to new entrants or partners in high-growth regions, creating a new revenue stream.
Industry Challenges
- High Capital Expenditure:The construction of new world-scale aniline and MDI production facilities, or retrofitting existing ones to meet stricter environmental laws from agencies like China's MEE, requires massive capital investment.
- Process Safety Management:Handling highly toxic materials like aniline and nitrobenzene under high pressure and temperature necessitates sophisticated process safety systems and a highly skilled workforce, posing a constant operational challenge.
- Logistical Complexity:The global nature of the aniline supply chain, which involves transporting hazardous materials between continents, creates logistical hurdles and risks related to shipping, storage, and handling compliance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aniline Market |
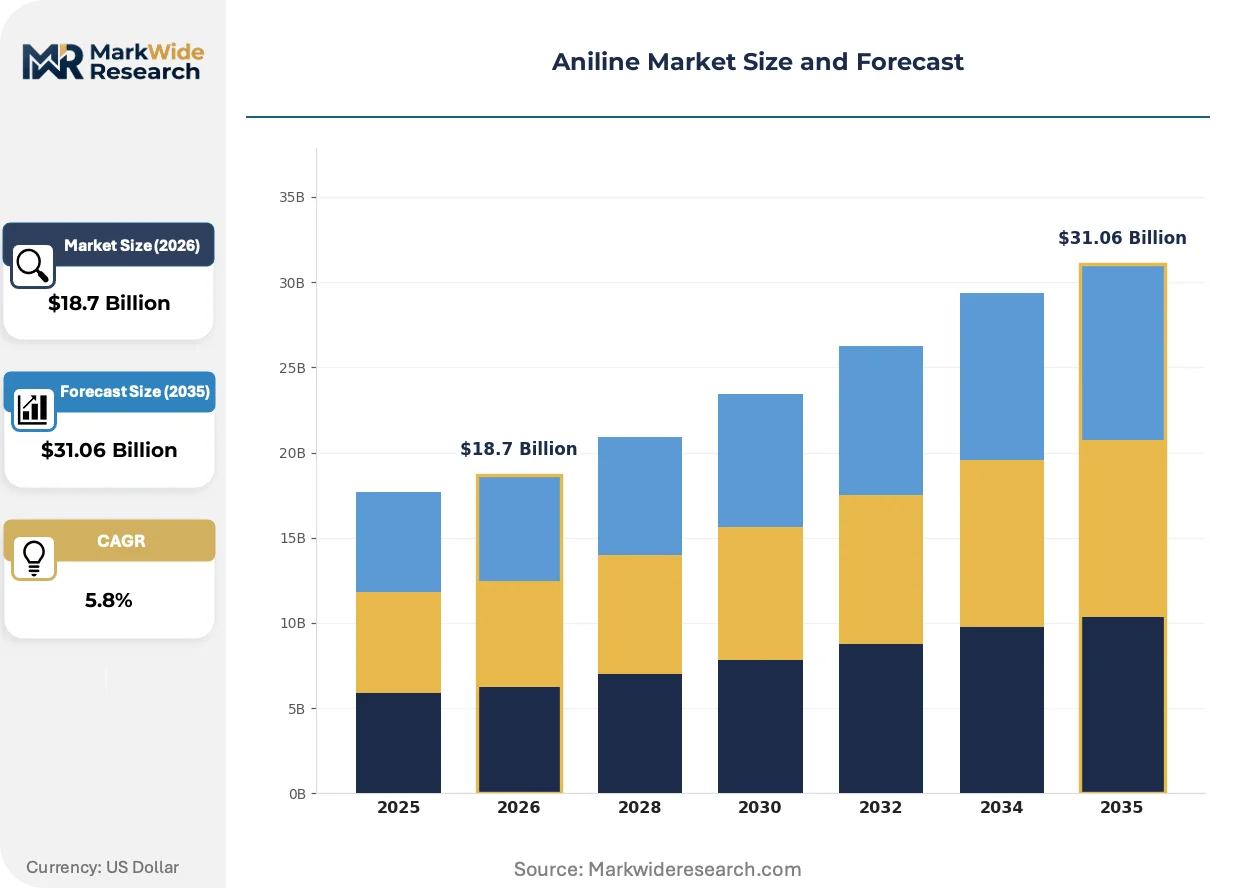
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Para-Aniline, Meta-Aniline, Ortho-Aniline, Aniline Hydrochloride Application: Dye Manufacturing, Rubber Processing, Herbicide Production, Pharmaceutical Intermediates End User Industry: Textile Processing, Automotive Components, Agriculture Chemicals, Drug Formulation Packaging Type: Drums, Bulk Bags, ISO Tanks, Cylinders |
| Companies Covered | Huntsman Corporation, Wanhua Chemical Group Co., Ltd., BASF SE, Tosoh Corporation, Sumitomo Chemical Co., Ltd., Covestro AG, Sinopec, Lanxess, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aniline Market Strategic Shifts & Innovations
The aniline market is defined by a fundamental tension between the immense scale of established petrochemical production and the growing imperative for sustainable chemical synthesis. This dynamic is driving innovation in both process technology and downstream material traceability to meet new environmental and commercial demands.
Research into the electrocatalytic reduction of nitrobenzene offers a novel alternative to conventional high-pressure hydrogenation. Chemical research institutes and advanced materials firms are pioneering this method, which uses electricity to drive the chemical conversion. This development is electrifying the long-term production roadmap by creating a potential pathway to synthesize aniline using renewable energy, decoupling production from fossil fuel-based hydrogen sources.
The European Union's Corporate Sustainability Reporting Directive (CSRD) is compelling a new level of transparency in chemical supply chains. The directive requires large companies to report on their environmental impact, which in turn pressures them to demand detailed sustainability data from their suppliers. The MDI and polyurethane segments are most affected, as downstream customers now require verifiable product carbon footprints for aniline feedstocks.
Downstream customers are increasingly adopting specification-driven sourcing models that prioritize supply chain transparency. This shift moves beyond basic cost and availability, with procurement decisions now incorporating factors like the aniline's production process and its associated carbon footprint data. This trend is most prominent in the automotive and construction sectors in Europe, where OEMs must meet stringent lifecycle emissions targets.
Aniline Market Segmentation
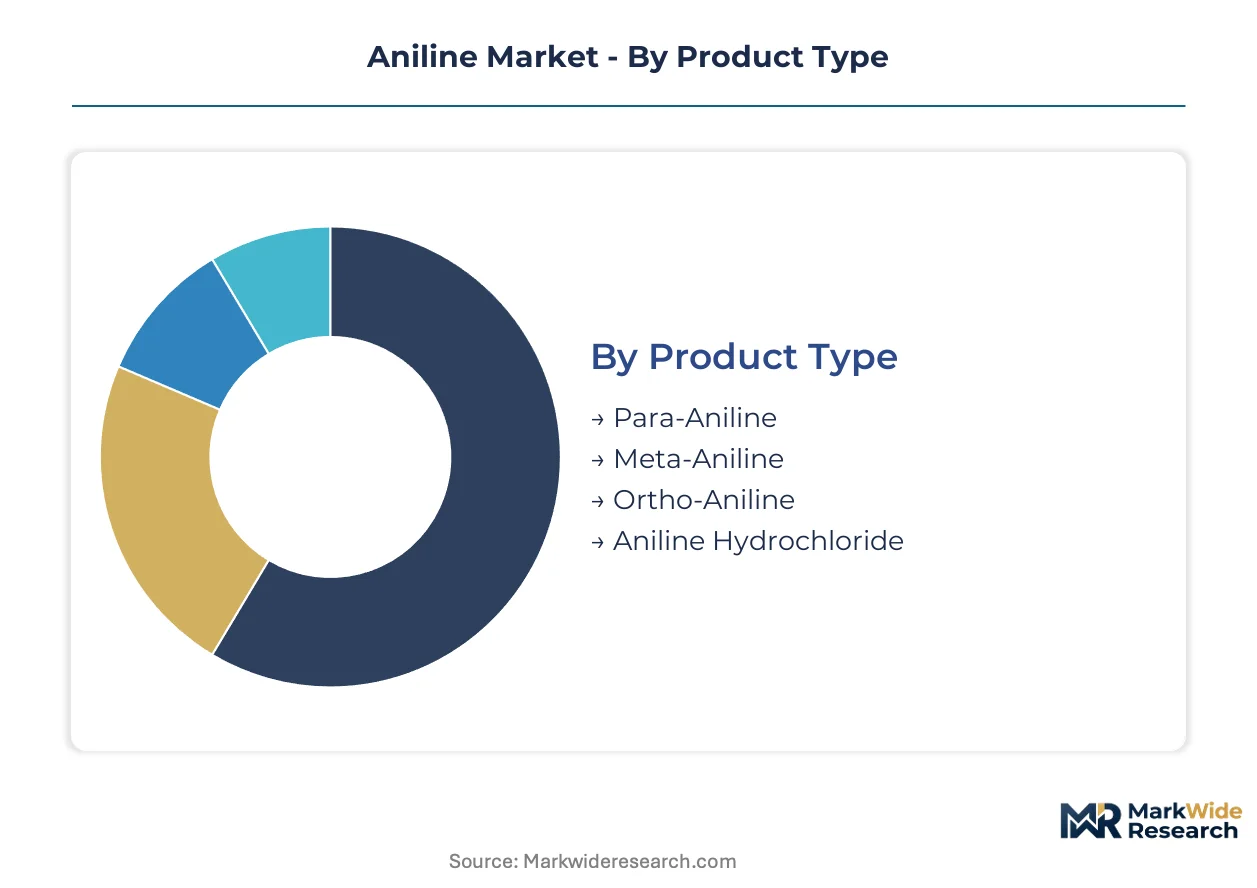
The aniline market structure reflects the diverse chemical properties and industrial requirements for this critical intermediate. Understanding these distinct segments allows producers to align their manufacturing capabilities with specific end-use demands and optimize supply chain strategies.
Product Type:
Aniline's distinct isomeric forms and derivatives offer varied chemical reactivities for downstream synthesis across industries.
- Para-Aniline:This isomer possesses the amino group at the para position, making it crucial for specialized dye intermediates and certain pharmaceutical syntheses. Demand for para-aniline is concentrated in fine chemical manufacturing, where precise molecular structures are required for product efficacy.
- Ortho-Aniline:The ortho isomer features the amino group adjacent to another substituent, enabling its use in specific agrochemical formulations and rubber accelerators. Its demand stems from performance-critical applications in agriculture and material science sectors, particularly in China's expanding chemical industry.
- Meta-Aniline:Meta-aniline, with its amino group positioned differently, finds application in niche chemical processes requiring specific reactivity.
- Aniline Hydrochloride:This salt form of aniline is used where a solid, less volatile form of aniline is preferred for handling and storage.
Para-Aniline leads on scale; Ortho-Aniline leads on momentum.
Application:
The application landscape for aniline demonstrates its versatility as a chemical building block, with varying maturity levels across different industrial uses.
- Dye Manufacturing:Aniline serves as a fundamental precursor for numerous synthetic dyes, including azo dyes, providing colorants for textile, paper, and leather industries. This application represents a mature segment, with demand influenced by global textile production volumes.
- Herbicide Production:Aniline derivatives are essential in synthesizing various herbicides, contributing to crop protection and agricultural productivity. Demand in this segment is influenced by global agricultural practices and the need for effective weed control, particularly in regions like Brazil and India.
- Rubber Processing:Aniline is employed in the production of rubber chemicals, such as accelerators and antioxidants, which enhance rubber's properties and durability.
- Pharmaceutical Intermediates:As a versatile chemical intermediate, aniline is utilized in the synthesis of various pharmaceutical compounds and active ingredients.
Demand for herbicide production is expanding most quickly, while dye manufacturing maintains significant volume.
End User Industry:
Aniline consumption is directly linked to the output and material requirements of several major industrial sectors, each with distinct demand drivers.
- Automotive Components:The automotive industry heavily relies on aniline for the production of MDI, which is then used to create polyurethane foams for seating, interior trim, and lightweight structural parts. Strict fuel efficiency standards and comfort requirements drive consistent demand for these polyurethane materials in Germany and Japan.
- Agriculture Chemicals:This sector utilizes aniline to synthesize various pesticides, herbicides, and fungicides, essential for modern crop management and food security. The expansion of precision agriculture and the need for high-yield crops in countries like India and the United States sustain demand for aniline-based agrochemicals.
- Textile Processing:The textile industry uses aniline derivatives in dye manufacturing, providing a broad spectrum of colors for fabrics.
- Drug Formulation:Aniline functions as a key intermediate in the synthesis of active pharmaceutical ingredients for a range of therapeutic drugs.
The automotive components sector exhibits the steepest expansion trajectory, while agriculture chemicals maintain a substantial consumption base.
Packaging Type:
The packaging of aniline is dictated by logistical efficiency, safety regulations, and the volumes required by industrial customers.
- Drums:Steel or HDPE drums, typically with capacities ranging from 200 to 250 liters, are used for smaller volume shipments to diverse industrial customers. This packaging type is prevalent for regional distribution and for users with moderate consumption requirements, ensuring safe handling in Europe and North America.
- ISO Tanks:These intermodal tank containers are designed for the bulk transport of hazardous liquids, offering high capacity and efficient intercontinental shipping. ISO tanks facilitate the movement of large volumes of aniline between major production hubs in China and consumption centers worldwide.
- Bulk Bags:Also known as Flexible Intermediate Bulk Containers (FIBCs), bulk bags are used for solid forms of aniline derivatives, providing a cost-effective solution for dry chemical transport.
- Cylinders:Smaller cylinders may be used for highly specialized or laboratory-scale requirements, offering precise dispensing for niche applications.
ISO Tanks represent the largest volume segment, while Drums cater to a broad base of smaller-scale customers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta region, with its extensive chemical manufacturing infrastructure, anchors significant aniline production and consumption. This concentration supports the global demand for methylene diphenyl diisocyanate (MDI), primarily for automotive and insulation applications. Regulatory frameworks and industrial policies across key geographies shape investment and operational strategies.
China
China's robust MDI production capacity drives substantial aniline demand for polyurethane foams in automotive and construction sectors. The Ministry of Ecology and Environment (MEE) mandates cleaner production technologies, influencing investment decisions for new facilities. Large-scale MDI facilities in Ningbo are accelerating investment in modern, energy-efficient aniline synthesis processes.
Germany
German automotive manufacturing and stringent energy efficiency mandates for insulation propel aniline demand for MDI synthesis. The EU's REACH framework imposes strict controls on chemical handling and emissions, affecting production practices. BASF's integrated Verbund sites, such as in Ludwigshafen, optimize aniline production and its derivatives for European markets.
United States
United States agriculture chemicals and automotive industries create consistent demand for aniline derivatives. The U.S. Environmental Protection Agency (EPA) enforces rigorous regulations on aniline storage, transport, and worker exposure. Chemical complexes along the Gulf Coast focus on MDI synthesis, serving both domestic and international polyurethane markets.
Japan
Japanese automotive component manufacturing and specialized rubber processing applications sustain a steady demand for aniline. The Ministry of Economy, Trade and Industry (METI) encourages innovation in advanced chemical production processes. Industrial zones in Chiba Prefecture concentrate on integrated petrochemical operations, supporting aniline derivative output.
India
India's expanding agriculture sector and infrastructure development fuel demand for aniline in herbicides and polyurethane insulation. The Production Linked Incentive (PLI) scheme promotes domestic chemical manufacturing capabilities. Gujarat's chemical industrial estates are expanding capacity to meet the growing local demand for agrochemicals and MDI-based products.
Aniline Market Key Industry Players
Capacity expansion dominates the current landscape, driven by the strong linkage between aniline and methylene diphenyl diisocyanate (MDI) production. The market exhibits a consolidated structure, with a few large players controlling significant portions of the MDI value chain. Strategic archetypes include integrated petrochemical conglomerates, specialized polyurethane system providers, and nascent bio-based chemical developers. Key competitive moves involve substantial capital investment in large-scale facilities, upstream control over feedstock, and strategic alliances to explore sustainable pathways.
At the scale-driven end, Wanhua Chemical Group Co., Ltd. exemplifies the strategic importance of extensive MDI production capabilities, anchoring significant aniline consumption within its in-house supply chain. German-based BASF SE represents another integrated chemical giant, leveraging its global network of production sites to optimize cost efficiencies across the aniline-MDI value chain. Huntsman Corporation occupies a position as a specialized provider, focusing on advanced polyurethane systems and material formulations that drive demand for high-performance aniline derivatives.
| Leading Market Players |
|---|
| Huntsman Corporation |
| Wanhua Chemical Group Co., Ltd. |
| BASF SE |
| Tosoh Corporation |
| Sumitomo Chemical Co., Ltd. |
| Covestro AG |
| Sinopec |
| Lanxess |
| Dow |
| Others |
Cost & Logistics Intelligence
The benzene commodity price index, a key precursor for aniline, cascades through the supply chain, directly influencing pricing tiers for MDI producers and smaller industrial buyers. This upstream volatility impacts downstream polyurethane manufacturing costs across automotive and construction sectors.
Pricing Analysis
Input cost pass-through mechanisms remain critical for aniline producers given feedstock volatility. The dominant pricing structure is contract-based long-term offtake for large MDI manufacturers, complemented by commodity spot pricing for smaller volumes. Price differentiation stems from purity grade requirements for specialized applications and the volume scale of purchases. Pricing softness reflects intense competition among integrated players like Wanhua Chemical Group. Large MDI producers exhibit lower price sensitivity due to captive consumption and strategic supply importance, unlike smaller regional buyers.
Supply Chain Analysis
China's dual carbon goals and the EU's REACH framework are reshaping sourcing strategies for aniline, prioritizing cleaner production and verifiable sustainability. Geographic supply concentrates heavily in China, Germany, and the United States, driven by large-scale MDI facilities. The supply chain relies on nitrobenzene and benzene as primary raw materials, with price fluctuations in crude oil markets creating input cost volatility. Logistical complexity for hazardous materials poses a structural risk, particularly for intercontinental transport via ISO tanks. Downstream distribution runs through direct sales to major MDI producers and regional chemical distributors for smaller customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The aniline market is evolving into a late-cycle quality story, driven by stringent lifecycle emissions targets in the automotive and construction sectors. This shift prioritizes sustainable production methods and verifiable product carbon footprints.
For Market Incumbents:
Acquire specialized bio-based aniline technology startups to mitigate long-term substitution threats from petroleum-based alternatives. Invest heavily in electrocatalytic reduction R&D to meet future environmental mandates from agencies like China's MEE and the EU's CSRD. Secure long-term contracts for key feedstocks like benzene to buffer against price volatility. Expand capacity in strategic geographies such as China to reinforce MDI value chain dominance.
For New Entrants and Emerging Players:
The price-point gap between conventional and sustainability-certified aniline offers a clear market entry opportunity. Target niche, high-value applications in automotive or construction where verifiable product carbon footprints command a premium. Focus on developing and licensing proprietary bio-based aniline production pathways, particularly those leveraging renewable energy sources. Penetrate emerging markets in Southeast Asia and India by offering localized production or specialized material formulations.
For Investors and Strategic Acquirers:
Asymmetric upside sits with specialized technology developers possessing proprietary bio-based or electrocatalytic aniline production IP. The long-term viability of the aniline market remains strong due to MDI's critical role, but sustainability will become a non-negotiable value driver. Target companies that offer established intellectual property and a clear path to commercial scale-up for non-petroleum-based aniline. The commercial scale-up of a truly green aniline production facility serves as a key inflection signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Reinforces global MDI supply chain dominance and supports regional demand growth. |
| Green Manufacturing Transition | Addresses regulatory pressures from EU's CSRD and China's MEE for sustainable production. |
| Long-term Nitrobenzene Supply Agreements | Mitigates feedstock price volatility and ensures stable production for MDI manufacturers. |
| Joint Venture for Bio-Based Aniline | Accelerates development of sustainable alternatives, meeting evolving customer and regulatory demands. |
| Process Technology Licensing | Creates new revenue streams by sharing proprietary high-yield, low-energy production methods globally. |
Research Approach
Bottom-up automotive components and construction insulation modeling reconciled against top-down MDI production tracking forms the analytical core of this study. Primary interviews with plant managers at MDI facilities, procurement leads at downstream OEMs, and technical R&D directors for bio-based pathways informed market dynamics. Secondary validation utilized customs/trade data for aniline, ACC/Cefic reports on chemical production, and SEC 10-K filings of major market players. This approach provided a triangulated view of market volume and value.
An input-output matrix correlates aniline production volumes with MDI consumption across the analysis window. Segmentation dimensions included product type, application, end-user industry, packaging format, and regional regulatory frameworks. Compound Annual Growth Rates were derived from historical trends and projected demand elasticity, incorporating forecast inputs such as MDI facility capacity expansions and global automotive production forecasts. The analytical framework projects market evolution across the modeling period.
Caveats apply where geopolitical shifts impacting feedstock supply or accelerated bio-based technology adoption could materially shift the outlook. Forecasts reflect assumptions documented through extensive primary and secondary research. Volatility in crude oil prices or new, more stringent environmental regulations from the EU's REACH framework present specific risk factors. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Potassium Metabisulfite Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
North America Calcium Chloride Market
Bulk Chemicals
Barium Sulfite Market
Bulk Chemicals
Precipitated Barium Sulphate Market
Bulk Chemicals
Sodium Tetraborate Market
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Global Lithium Derivatives Market
Bulk Chemicals
Asia-Pacific Carbon Black Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market
Bulk Chemicals
Europe Gamma Butyrolactone Market
Bulk Chemicals
Global GABA Market
Bulk Chemicals
Potassium Fluoborate Market
Bulk Chemicals
Hydrogen Bromide Market
Bulk Chemicals
Magnesium Lactate Market
Bulk Chemicals
Carbon Disulfide Market