
 Chemical Warehousing Market | 2026-2036
Chemical Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Warehousing Market Analysis
A shift from captive in-house storage toward third-party logistics is pivoting how chemical manufacturers manage working capital and regulatory risk. DHL Supply Chain leverages its global footprint to offer bonded warehousing and customs-integrated inventory solutions. Rinchem specializes in temperature-sensitive and hazardous material handling, sustaining premium positioning through cGMP-compliant facilities. Kuehne + Nagel anchors European chemical logistics through Rotterdam-adjacent tank terminals and multi-modal connectivity.
Chemical warehousing encompasses the engineered storage, handling, and inventory management of hazardous and non-hazardous substances within facilities rated for specific NFPA hazard classes, temperature regimes, and containment specifications. These operations serve as critical nodes in chemical supply chains, ensuring product integrity, regulatory compliance, and just-in-time delivery to downstream manufacturers. Bulk chemicals occupy the largest share of dedicated tank storage capacity, reflecting continuous-process manufacturing and pipeline-fed inbound logistics. Specialty chemicals command higher margins per pallet position due to smaller lot sizes, stricter segregation protocols, and value-added services such as blending and repackaging. Refrigerated storage represents the fastest-expanding segment as biologics and temperature-critical agrochemicals multiply cold-chain requirements.
EPA Risk Management Plan mandates and OSHA Process Safety Management standards shape facility design, emergency response infrastructure, and operator training investments across US chemical warehousing. In Europe, REACH registration obligations and Seveso III directives on major accident hazards dictate secondary containment specifications and site security protocols. Stakeholders must monitor evolving per- and polyfluoroalkyl substances restrictions, as these compound-specific bans could force rapid inventory repositioning and remediation of legacy stock.
Market Dynamics
Specialty chemical manufacturers are accelerating outsourced warehousing adoption to offload EPA Risk Management Plan compliance burdens and free working capital from fixed tank farm assets.
Growth Catalysts
- Seveso III Directives:European major accident hazard regulations mandate upgraded secondary containment and site security, forcing chemical producers toward certified third-party operators with pre-built compliance infrastructure.
- Biologics Cold Chain:Temperature-critical agrochemicals and pharmaceutical intermediates require refrigerated storage expansion, pulling investment into humidity-controlled warehouses with redundant cooling systems.
- US Gulf Coast Concentration:Port-proximate tank farms near Houston and Corpus Christi serve export-oriented petrochemical producers seeking customs-bonded inventory positioning for Latin American and Asian markets.
Market Restraints
- Steel and Containment Material Volatility:Tank construction costs fluctuate with specialty steel alloy pricing, compressing returns on new capacity additions during input price spikes.
- Limited Qualified Labor Pools:Hazmat-certified warehouse operators and process safety engineers concentrate in established petrochemical corridors, constraining facility expansion into secondary markets.
- Per- and Polyfluoroalkyl Substances Bans:Emerging compound-specific restrictions in multiple jurisdictions force rapid inventory repositioning and legacy stock remediation, straining working capital.
Strategic Opportunities
- India Chemical Manufacturing:PLI scheme incentives for specialty chemicals and agrochemicals create demand for temperature-controlled warehousing near Mumbai and Gujarat industrial zones.
- Real-Time Tracking Convergence:IoT sensor networks combined with blockchain documentation enable continuous chain-of-custody verification for high-value specialty chemical shipments.
- Blending and Repackaging Services:Value-added processing within warehouse boundaries captures margin from manufacturers seeking just-in-time formulation adjustments without dedicated plant investment.
Industry Challenges
- cGMP Certification Timelines:Pharmaceutical-grade warehouse qualification under FDA or EMA standards requires 18-24 month validation cycles, delaying revenue generation from new facilities.
- Legacy System Integration:ERP connectivity between manufacturer inventory platforms and third-party warehouse management systems demands custom middleware development, inflating implementation costs.
- Emergency Response Capability Gaps:OSHA Process Safety Management mandates specialized fire suppression and containment infrastructure that many existing facilities lack, requiring substantial retrofit investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Warehousing Market |
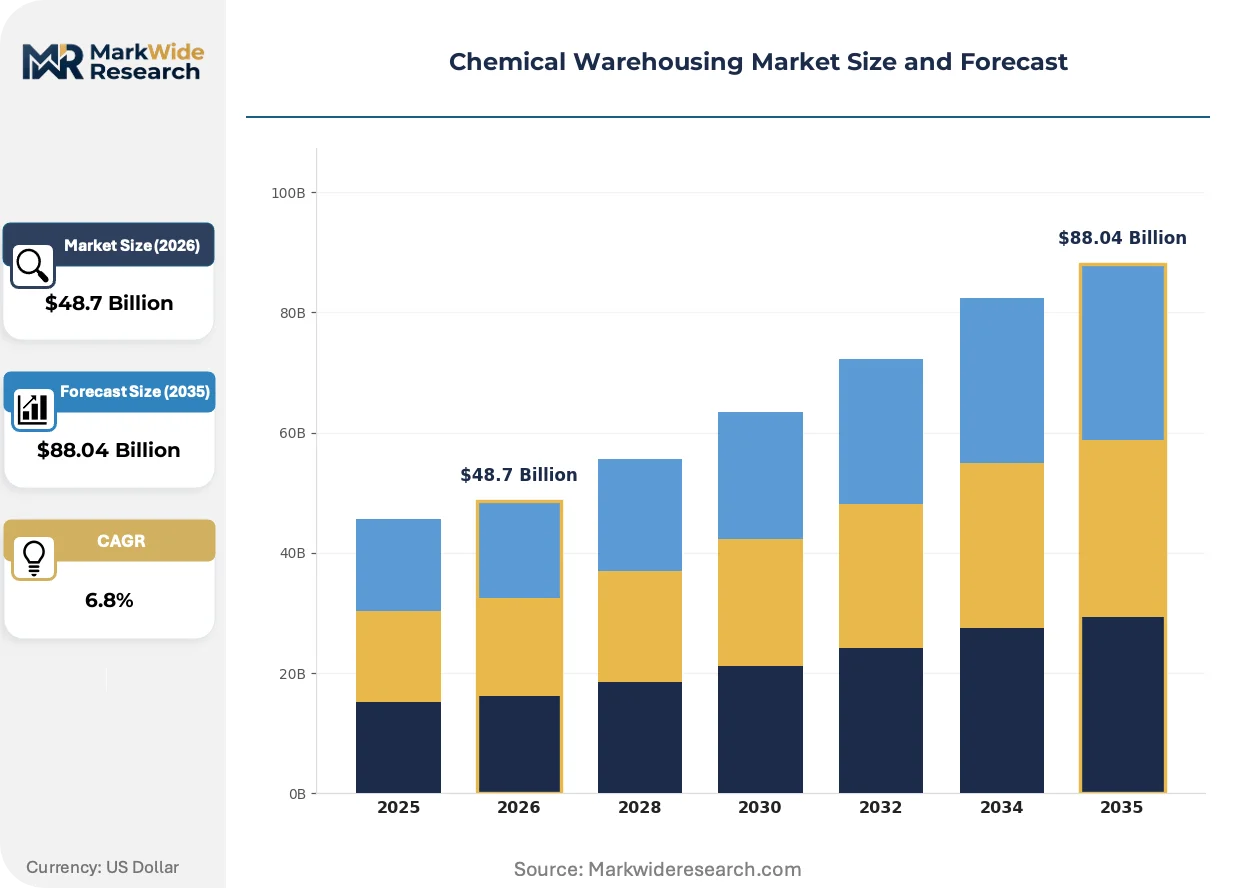
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Chemicals, Specialty Chemicals, Agricultural Chemicals, Petrochemicals End Use Industry: Pharmaceuticals, Agrochemicals, Food & Beverage, Automotive Storage Type: Chemical Tanks, Warehouses, Refrigerated Storage, Dry Storage Distribution Channel: Direct Sales, Distributors, E-commerce, Supply Chain Partners |
| Companies Covered | Rhenus Logistics, Rinchem, DHL Supply Chain, LBC Tank Terminals, CLX Logistics, Kuehne + Nagel, BDP International, Kenan Advantage Group, DSV, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Warehousing Market Emerging Trajectories
Warehouse automation and digital traceability systems are compressing inventory dwell times while elevating compliance documentation standards across hazardous material storage operations.
Automated guided vehicles equipped with explosion-proof ratings are converging with warehouse management software to enable lights-out operation in NFPA Class I hazardous zones. Specialty chemical distributors in Rotterdam and Antwerp terminals deploy these systems to reduce human exposure during high-frequency drum handling. The technology is compressing labor cost structures while tightening lot-level traceability for REACH-mandated substance tracking.
REACH registration obligations are tightening documentation requirements for substance volume tracking and downstream user communication throughout European chemical supply chains. Warehouse operators now embed regulatory reporting modules directly into inventory management platforms to automate SVHC notification triggers. Specialty chemical segments with complex formulation histories face the steepest compliance cost escalation.
Consolidated procurement platforms are displacing fragmented spot-market warehouse contracting among mid-sized chemical manufacturers. Large specialty chemical producers in Germany and the Netherlands now negotiate multi-year capacity reservations with integrated logistics providers, bundling storage, transport, and customs brokerage. This concentration shifts pricing power toward operators with bonded warehouse networks and multi-modal connectivity.
Chemical Warehousing Market Segmentation
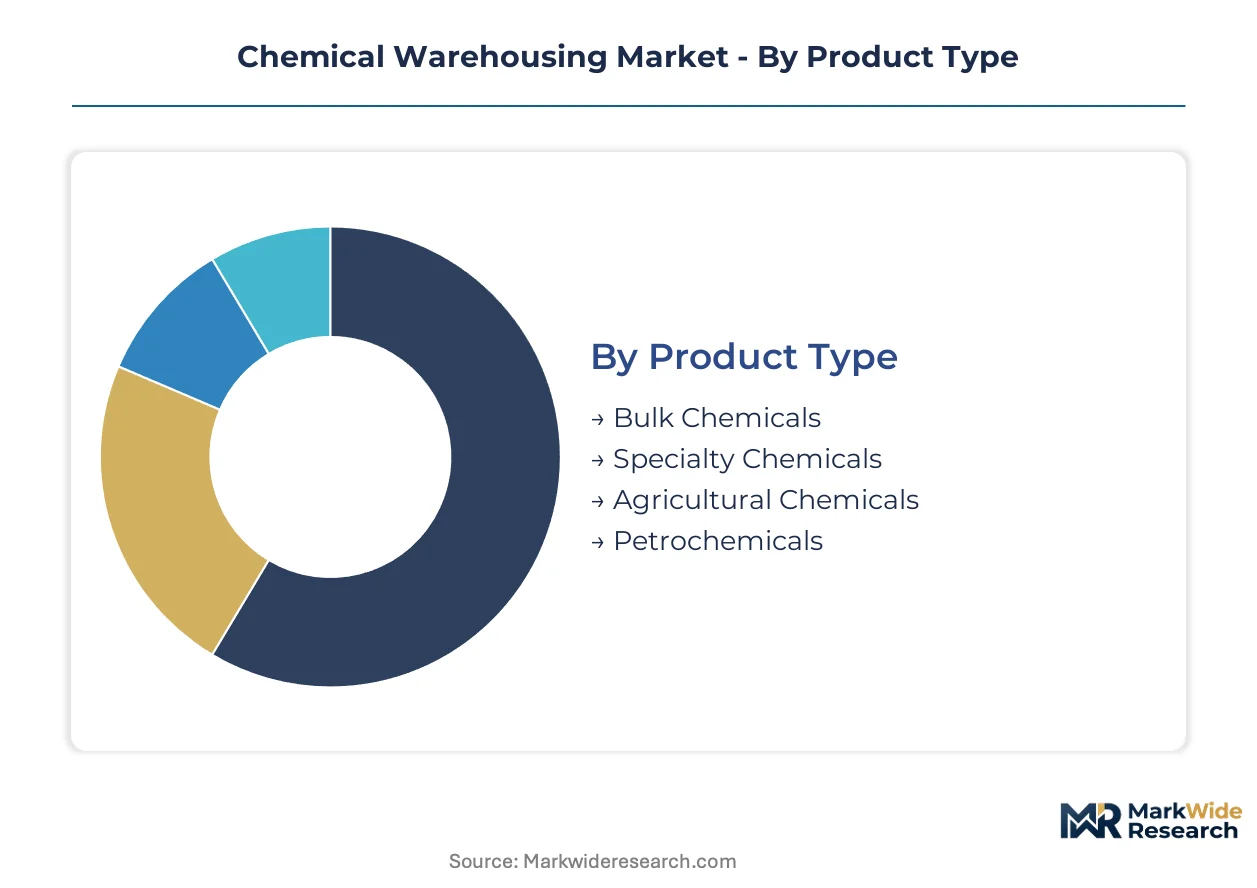
Chemical warehousing segmentation reflects divergent infrastructure requirements across hazard classes, temperature regimes, and custody protocols. Each axis demands specialized capital deployment and shapes operator margin structures differently.
Product Type:
Temperature sensitivity and lot-size economics differentiate chemical storage specifications across product categories.
- Bulk Chemicals:Continuous-process manufacturing feeds pipeline-connected tank farms with single-product dedicated storage. US Gulf Coast facilities near Houston and Corpus Christi anchor capacity for export-oriented ethylene and propylene derivatives.
- Specialty Chemicals:Smaller lot sizes and complex segregation protocols command premium pallet positioning. cGMP-compliant facilities serving pharmaceutical intermediates in New Jersey and Massachusetts sustain 18-24 month qualification cycles that barrier new entrants.
- Agricultural Chemicals:Seasonal demand peaks require surge capacity with EPA Risk Management Plan compliance for ammonia-based formulations. Humidity-controlled warehouses in Iowa and Illinois serve Midwest corn-belt distribution.
- Petrochemicals:Bonded tank terminals enable customs-deferred inventory positioning for Asian and Latin American export markets. Rotterdam-adjacent facilities leverage multi-modal connectivity for European arbitrage.
Mature deployment sits with bulk chemicals. Newer deployment is concentrated in specialty chemicals requiring value-added blending and repackaging services.
End Use Industry:
Regulatory stringency and chain-of-custody requirements segment warehousing demand by downstream application.
- Pharmaceuticals:FDA validation mandates temperature mapping, redundant cooling, and continuous monitoring for active pharmaceutical ingredients. Cold-chain facilities in Pennsylvania and North Carolina cluster near formulation plants.
- Agrochemicals:Temperature-critical biological pesticides and seed treatments expand refrigerated storage requirements. Brazil's São Paulo state and India's Gujarat industrial zones anchor emerging capacity.
- Food & Beverage:Flavor and additive chemicals require food-grade certification with allergen segregation protocols. Midwest distribution hubs serve CPG manufacturers with just-in-time delivery windows.
- Automotive:Paint chemicals, adhesives, and battery electrolytes demand NFPA Class I rated facilities with explosion-proof handling equipment. Detroit-proximate warehouses serve Tier 1 supplier networks.
Established volume concentrates in agrochemicals. Steepest expansion trajectory appears in pharmaceuticals with biologics cold-chain multiplication.
Storage Type:
Containment engineering and environmental controls define facility capital intensity and operating cost structures.
- Chemical Tanks:Above-ground and underground steel tanks with secondary containment serve liquid bulk chemicals. Specialty alloy construction costs fluctuate with nickel and chromium pricing, compressing returns during input spikes.
- Warehouses:Humidity-controlled structures with NFPA-rated segregation accommodate bagged, drummed, and palletized chemicals. Automated guided vehicles with explosion-proof ratings enable lights-out operation in hazardous zones.
- Refrigerated Storage:Redundant cooling systems with temperature validation protocols serve temperature-critical biologics and agrochemicals. Facilities in Netherlands and Singapore anchor intercontinental cold-chain nodes.
- Dry Storage:Ambient warehouses with moisture barriers accommodate stable solid chemicals and intermediates. Lower capital requirements attract fragmented regional operators.
Conventional capacity dominates in dry storage. Investment flow concentrates in refrigerated storage with biopharmaceutical demand acceleration.
Distribution Channel:
Customer scale and service integration requirements segment channel economics and contract structures.
- Direct Sales:Large chemical manufacturers operate captive warehouses or reserve dedicated capacity with third-party operators. Multi-year agreements bundle storage, transport, and customs brokerage.
- Distributors:Independent chemical distributors aggregate fragmented demand across small and mid-sized manufacturers. Rotterdam and Antwerp terminals serve European specialty chemical distribution networks.
- E-commerce:Digital platforms for laboratory chemicals and reagents require small-lot fulfillment with hazardous materials shipping compliance. Limited penetration reflects regulatory complexity.
- Supply Chain Partners:Integrated logistics providers offer bonded warehousing with customs-integrated inventory solutions. Consolidated procurement platforms displace spot-market contracting among mid-sized producers.
Traditional volume rests with direct sales. Channel expansion is gaining share fastest in supply chain partner arrangements with bundled service integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical export corridors and specialty chemical manufacturing clusters concentrate warehousing demand across four distinct national markets. Each geography exhibits unique regulatory pressures and infrastructure investment patterns.
United States
EPA Risk Management Plan mandates and OSHA Process Safety Management standards elevate facility certification requirements for ammonia-based agricultural chemicals and hazardous intermediates. The US Gulf Coast corridor between Houston and Corpus Christi anchors tank farm capacity serving Latin American and Asian export markets. Humidity-controlled warehouses in New Jersey and Massachusetts sustain 18-24 month cGMP qualification cycles for pharmaceutical-grade storage.
Germany
REACH registration obligations and Seveso III directives on major accident hazards dictate secondary containment specifications and site security protocols across chemical logistics networks. The country's national chemical regulator enforces stringent documentation requirements for substance volume tracking. Industrial zones in North Rhine-Westphalia and Bavaria cluster temperature-controlled facilities serving pharmaceutical and agrochemical formulation plants.
Netherlands
Rotterdam-adjacent tank terminals leverage multi-modal connectivity for European arbitrage and bonded customs-deferred inventory positioning. ECHA-mandated SVHC notification triggers are now embedded directly into warehouse management platforms. The Port of Rotterdam chemical logistics corridor anchors cold-chain nodes for temperature-critical biologics and pharmaceutical intermediates.
India
PLI scheme incentives for specialty chemicals and agrochemicals are accelerating demand for temperature-controlled warehousing near Mumbai and Gujarat industrial zones. The country's national pharmaceutical regulator enforces cold-chain validation protocols for biological pesticides and seed treatments. Humidity-controlled facilities in Maharashtra and Gujarat serve export-oriented active pharmaceutical ingredient manufacturers.
Singapore
Strategic positioning as an intercontinental cold-chain hub attracts redundant cooling system investments for biologics and temperature-critical agrochemicals. The country's national environmental agency enforces hazardous materials handling standards for drum storage and repackaging operations. Jurong Island petrochemical complexes anchor bonded warehouse networks serving Southeast Asian distribution.
Chemical Warehousing Market Vendor Landscape
Capacity expansion dominates the current landscape as operators respond to biologics cold-chain multiplication and Seveso III compliance upgrades. The vendor base organizes around three tiers: integrated global logistics networks with bonded warehouse infrastructure, regional specialists in temperature-sensitive and hazardous material handling, and fragmented local operators in ambient dry storage. Strategic archetypes include customs-integrated platform providers, cGMP-certified pharmaceutical-grade specialists, and petrochemical corridor tank terminal operators. Geographic expansion into India and strategic partnerships for IoT-enabled traceability represent the two dominant competitive moves.
Among integrated global networks, DHL Supply Chain and Kuehne + Nagel occupy positions exemplifying customs-bonded infrastructure and multi-modal connectivity archetypes. Rinchem represents the hazardous material and temperature-sensitive specialization tier. These three entities anchor the competitive structure without exhaustively defining it.
| Leading Market Players |
|---|
| Rhenus Logistics |
| Rinchem |
| DHL Supply Chain |
| LBC Tank Terminals |
| CLX Logistics |
| Kuehne + Nagel |
| BDP International |
| Kenan Advantage Group |
| DSV |
| Others |
Supply Flow & Price Mechanics
Hazmat-certified warehouse operators and process safety engineers concentrate along the US Gulf Coast petrochemical corridor, and labor-cost differentials between this talent-dense region and secondary markets widen pricing-tier spreads for cGMP-compliant versus ambient dry storage.
Pricing Analysis
Warranty and emergency-response service bundling separates premium-tier operators from unbundled economy providers. Three-tier pricing structure across premium, standard, and economy levels prevails, with differentiation driven by EPA Risk Management Plan certification grade and after-hours technical support coverage. Cost compression in economy ambient warehousing intensifies because regional operators compete on minimal compliance overhead. Small and mid-sized chemical manufacturers exhibit highest price sensitivity, while pharmaceutical-grade buyers prioritize validation documentation over unit cost.
Supply Chain Analysis
cGMP qualification timelines and Seveso III compliance certification gate facility participation in pharmaceutical and high-hazard chemical storage. Supply concentrates in the United States, Germany, and the Netherlands, with secondary capacity emerging in India. Construction draws from specialty steel alloys, nickel-chromium plating systems, and redundant cooling infrastructure. Single-source vulnerability runs through Rotterdam-adjacent tank terminals for European arbitrage. Distribution runs through integrated logistics providers with bonded warehouse networks and multi-modal connectivity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EPA and Seveso III compliance upgrades is forcing sub-scale operators toward exit or acquisition, rewarding certified third-party platforms with pre-built regulatory infrastructure.
For Market Incumbents: Hedge against specialty steel input volatility through long-term alloy supply agreements with certified foundries. Accelerate cGMP qualification investments in Pennsylvania and North Carolina clusters to capture biologics cold-chain multiplication before 18-24 month validation cycles lock out competitors. Defensive capacity reservations with downstream pharmaceutical manufacturers anchor utilization through demand cyclicality. For New Entrants and Emerging Players: Launch via temperature-controlled warehousing partnerships near Mumbai and Gujarat industrial zones to capture PLI scheme-driven specialty chemical manufacturing. Target agrochemical cold-chain gaps in Brazil's São Paulo state where biological pesticide storage demand outpaces certified facility supply. Pursue IoT-enabled traceability service bundling as differentiated entry wedge against established ambient storage operators. For Investors and Strategic Acquirers: The window for entry favors cGMP-certified regional specialists with validated cold-chain infrastructure and pharmaceutical manufacturer relationships. Long-term viability rests on regulatory moat sustainability through continuous EPA, FDA, and EMA compliance investment. Watch for PFAS ban acceleration as inventory repositioning demand inflection forcing rapid certified capacity absorption.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Biologics cold-chain multiplication in Netherlands and Singapore anchors intercontinental node positioning. |
| Backward Integration | In-house alloy sourcing buffers specialty steel price volatility compressing tank construction returns. |
| Long-term Supply Agreement | Multi-year pharmaceutical manufacturer reservations lock utilization through FDA validation cycle delays. |
| Joint Venture | Rotterdam-adjacent partnerships combine European regulatory expertise with Asian capital deployment. |
| Green Manufacturing Transition | PFAS-free containment system retrofit opens premium positioning as compound-specific bans proliferate. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across plant managers at downstream chemical manufacturers, procurement leads at specialty chemical distributors, EPA compliance officers, and technical R&D directors at containment system suppliers. Bottom-up facility capacity enumeration triangulated against top-down trade flow analysis from USITF and Eurostat databases.
Reconciliation of tank farm utilization rates, warehouse management system adoption curves, and cold-chain investment pipelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include hazard class rating, temperature regime, end-use industry vertical, and regional regulatory cluster. CAGRs derived from facility construction permit trajectories and pharmaceutical manufacturing capacity expansion announcements.
Steel alloy price volatility, PFAS regulatory acceleration, and qualified labor pool constraints are the dominant revision risks to facility deployment timelines. Forecasts reflect documented assumptions on certification cycle durations and trade corridor demand elasticity. A model refresh is warranted upon material change in EPA Risk Management Plan enforcement intensity or ECHA SVHC notification scope expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Hypophosphite Market
Bulk Chemicals
Lysine Market
Bulk Chemicals
Triazine Market
Bulk Chemicals
Hydrochloric Acid Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Styrene Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Asia-Pacific Bitumen Market
Bulk Chemicals
Global Semiconductor Grade Nitric Acid Market
Bulk Chemicals
North America Potassium Permanganate Market
Bulk Chemicals
Middle East Ammonia Market
Bulk Chemicals
Asia-Pacific Ammonia Market
Bulk Chemicals
United States Iodine Market
Bulk Chemicals
Formic Acid Market
Bulk Chemicals
Global Potassium Metabisulfite Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market