
 Europe Limestone Market | 2026-2036
Europe Limestone Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Limestone Market Insights
Multi-source procurement from regional quarries is hardening as cement and steel makers diversify supply away from single-pit dependencies. Carmeuse sustains extensive kiln networks across Belgium and France, securing thermal efficiency advantages in quicklime production. Lhoist Group anchors its European position through deep vertical integration into lime hydration and dolomitic specialties. Schaefer Kalk specializes in ultra-pure calcium carbonate grades for pharmaceutical and food-grade applications, occupying a defensible niche above commodity pricing tiers.
Europe limestone consists primarily of calcium carbonate with variable magnesium content, typically processed through calcination in rotary or vertical kilns at temperatures exceeding 900°C to produce quicklime and hydrated lime for industrial consumers. Crushed limestone dominates construction aggregates for road base and concrete filler, while ground limestone and limestone powder command premium placement in flue gas desulfurization and soil amendment applications where particle size distribution determines reactivity and application efficiency. The water treatment segment is gaining structural importance as municipalities across the region upgrade pH adjustment infrastructure to meet tightened effluent standards.
The EU Emissions Trading System and F-Gas Regulation are pressuring kiln operators to adopt oxy-fuel combustion and carbon capture retrofits, reshaping capital allocation across the value chain. REACH compliance and CE marking requirements for construction aggregates are elevating testing and certification burdens, particularly for cross-border trade within the single market. Stakeholders must track the pace of national transposition for the Industrial Emissions Directive and assess whether emerging carbon removal certifications will unlock new revenue streams for limestone-derived products in hard-to-abate sectors.
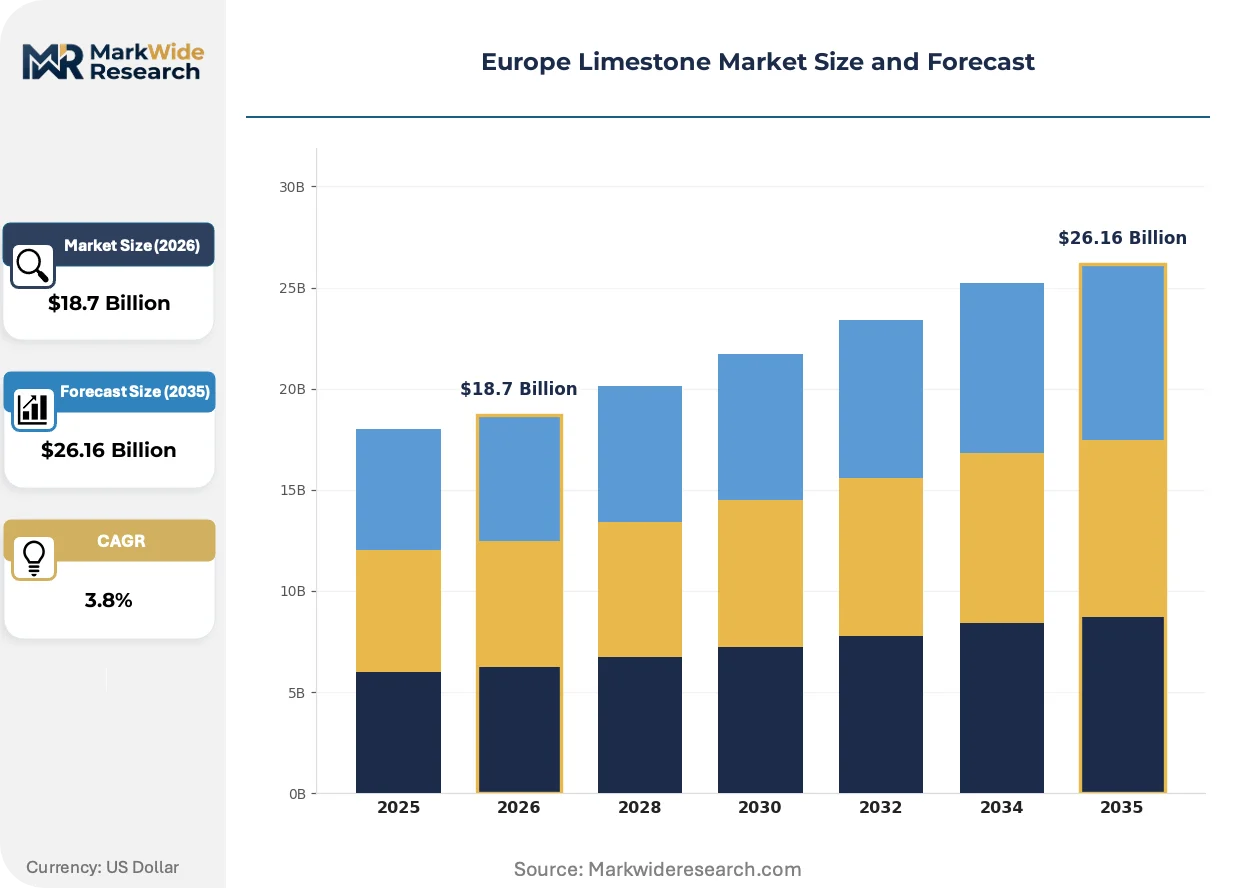
Market Dynamics
The EU Emissions Trading System is compressing margins for kiln operators while simultaneously accelerating capital flows toward carbon capture retrofits and alternative fuel substitution across the European lime value chain.
Growth Catalysts
- EU Green Deal carbon border adjustments:Steel and cement producers are sourcing higher-purity limestone feedstock to reduce process emissions intensity and avoid import tariffs on carbon-intensive materials.
- Flue gas desulfurization upgrades:Coal plant retrofits in Poland and Germany are consuming specialized ground limestone grades with controlled particle size distribution for scrubber efficiency.
- Oxy-fuel combustion adoption:Belgian and French kiln networks are retrofitting burner systems to concentrate CO2 streams for capture, creating pull for refractory-grade limestone with lower silica content.
Market Restraints
- Natural gas price volatility:Kiln fuel costs swing with TTF benchmark movements, forcing operators to idle capacity or absorb margin erosion during winter demand spikes.
- Quarry permitting delays:Environmental impact assessments under the Habitats Directive stretch approval timelines to 4-7 years in Bavaria and Rhineland-Palatinate, constraining reserve replacement.
- Slag and fly ash substitution:Steel industry by-products are displacing limestone in cement clinker production where logistics costs favor local industrial waste streams.
Strategic Opportunities
- Carbon removal certification:Emerging methodologies for limestone-derived carbon capture and storage could unlock revenue streams in voluntary carbon markets for hard-to-abate sectors.
- Eastern European infrastructure buildout:Romanian and Bulgarian road construction programs are absorbing crushed limestone volumes previously directed to Western European markets.
- Pharmaceutical-grade calcium carbonate:Ultra-pure production for antacid and supplement applications commands pricing multiples above commodity construction grades.
Industry Challenges
- Refractory engineer scarcity:Specialized expertise for kiln relining and thermal optimization is retiring faster than vocational programs in France and Germany can replace it.
- CE marking documentation burden:Construction aggregate producers face extended testing protocols for cross-border trade within the single market, stretching quality assurance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Limestone Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $26.16 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crushed Limestone, Ground Limestone, Limestone Powder, Limestone Blocks Application: Construction, Agriculture, Water Treatment, Industrial Processes End User: Construction Companies, Farmers, Municipalities, Manufacturing Industries Distribution Channel: Direct Sales, Online Sales, Retail Outlets, Wholesalers |
| Companies Covered | Cemex SAB de CV, Schaefer Kalk, Carmeuse, Minerals Technologies Inc, Omya AG, Lhoist Group, Imerys, Graymont Limited, Holcim Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Limestone Market Trends and Innovations
Electrification of calcination processes and digital kiln control systems are displacing conventional fuel-fired operations, while regulatory pressure on embodied carbon is reshaping specification standards across construction and industrial end-uses.
Electrothermal calcination using plasma or resistance heating is converging with renewable power purchase agreements to enable zero-process-emission quicklime production. Nordic cement producers are piloting 50 MW-scale installations. This technology is converging with green hydrogen supply chains to eliminate fossil fuel dependence in lime manufacturing entirely.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in industrial refrigeration, indirectly pressuring lime producers to supply higher-reactivity hydrated lime for alternative cooling system chemistry. Chemical processors in the Netherlands and Belgium are reformulating around ammonia and CO2 loops. Food-grade lime specifications are tightening to meet MDR traceability requirements for pharmaceutical excipient applications.
Buyers are consolidating procurement through integrated supply agreements that bundle limestone, logistics, and technical service. Major concrete producers in northern France are locking 5-year offtake contracts with single-quarry operators. This pattern concentrates volume with vertically integrated suppliers capable of guaranteeing specification consistency and carbon footprint documentation under CSRD reporting obligations.
Europe Limestone Market Segmentation
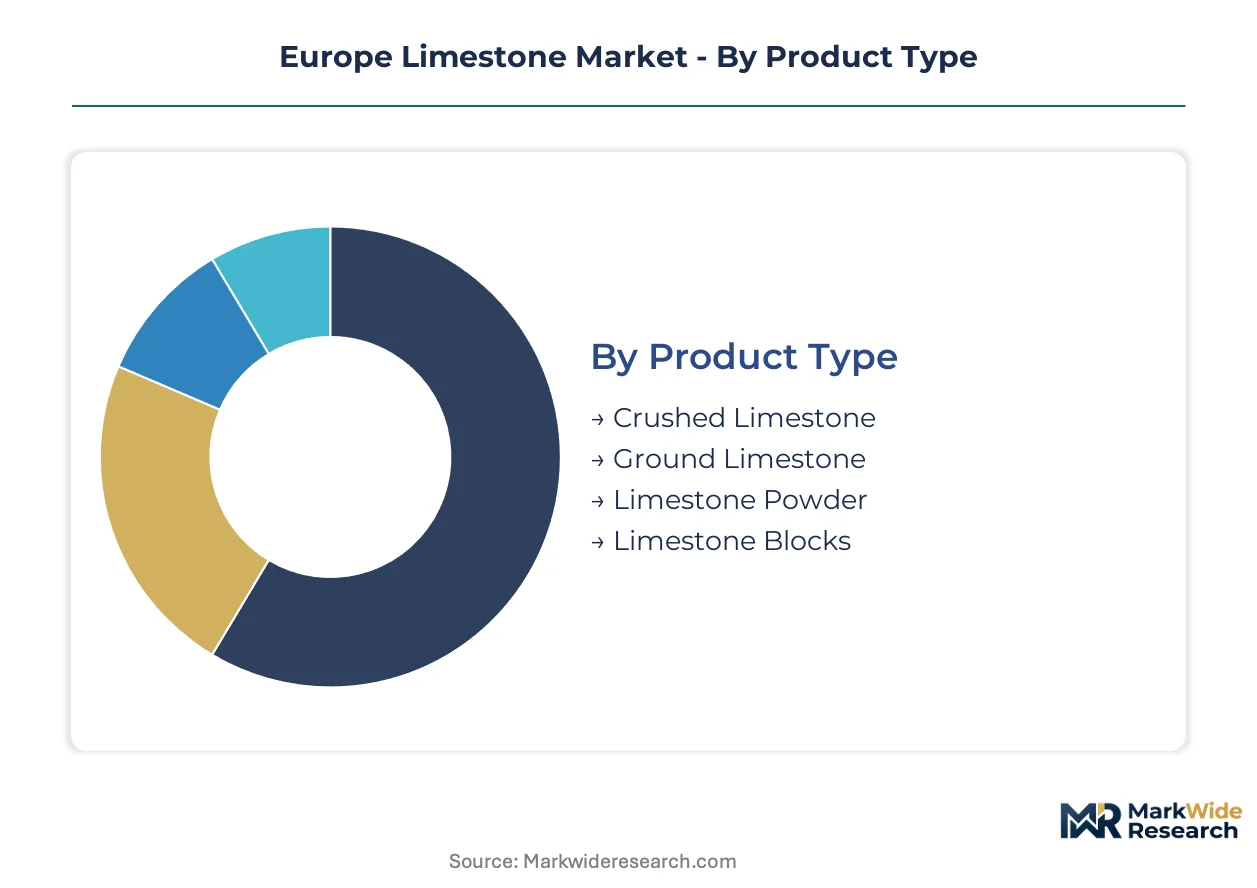
Product form determines handling economics and specification rigor across the Europe limestone value chain. Buyers in construction, agriculture, and industrial processing each impose distinct particle size, purity, and certification requirements that fragment procurement patterns.
Product Type:
Cost tier separates commodity buyers from specification-sensitive industrial consumers.
- Crushed Limestone:Coarse aggregate produced through primary and secondary crushing for road base and concrete filler applications. German and Polish infrastructure contractors absorb the largest volumes, though quarry permitting delays under the Habitats Directive constrain reserve replacement in Bavaria and Rhineland-Palatinate.
- Ground Limestone:Finely milled material with controlled particle size distribution for flue gas desulfurization and soil amendment. Coal plant retrofits in Poland and Germany are pulling specialized grades where reactivity determines scrubber efficiency and agricultural lime effectiveness.
- Limestone Powder:Ultra-fine milling for pharmaceutical excipients, food additives, and high-performance fillers. REACH compliance and MDR traceability requirements tighten documentation burdens for cross-border trade within the single market.
- Limestone Blocks:Dimensional stone for architectural cladding and heritage restoration. Premium pricing reflects extraction selectivity and CE marking certification for construction aggregates.
Volume sits with Crushed Limestone; growth tilts toward Limestone Powder.
Application:
End-use maturity drives margin structure and specification intensity.
- Construction:Road base, concrete aggregate, and cement clinker feedstock consuming the majority of extracted volumes. Eastern European infrastructure buildout in Romania and Bulgaria is absorbing material previously directed westward.
- Agriculture:Soil pH amendment and livestock bedding applications where particle fineness determines dissolution rate and nutrient availability. French and German farmers prioritize logistics proximity over premium grades.
- Water Treatment:Municipal pH adjustment and softening infrastructure upgrades across the region. Tightened effluent standards under the Industrial Emissions Directive are accelerating plant retrofits.
- Industrial Processes:Steel fluxing, glass manufacturing, and chemical processing requiring low-silica, high-calcium feedstock. Oxy-fuel combustion retrofits in Belgian and French kilns are creating pull for refractory-grade limestone.
Margins concentrate in Industrial Processes; expansion is steepest in Water Treatment.
End User:
Procurement scale and technical capability fragment buyer power across the value chain.
- Construction Companies:Large contractors in northern France are consolidating procurement through integrated supply agreements bundling material, logistics, and technical service. CSRD reporting obligations drive demand for carbon footprint documentation.
- Farmers:Fragmented demand across millions of smallholders prioritizing delivered cost over specification consistency. Cooperative purchasing in Germany and Poland aggregates volumes for rail shipment.
- Municipalities:Water treatment infrastructure operators specifying certified grades under EU procurement directives. Extended testing protocols for cross-border trade stretch quality assurance timelines.
- Manufacturing Industries:Steel, cement, and glass producers with captive lime operations or long-term offtake contracts. Carbon border adjustments are pressuring feedstock purity to reduce process emissions intensity.
Contract security favors Manufacturing Industries; price sensitivity peaks with Farmers.
Distribution Channel:
Supply chain configuration aligns with buyer technical requirements and volume scale.
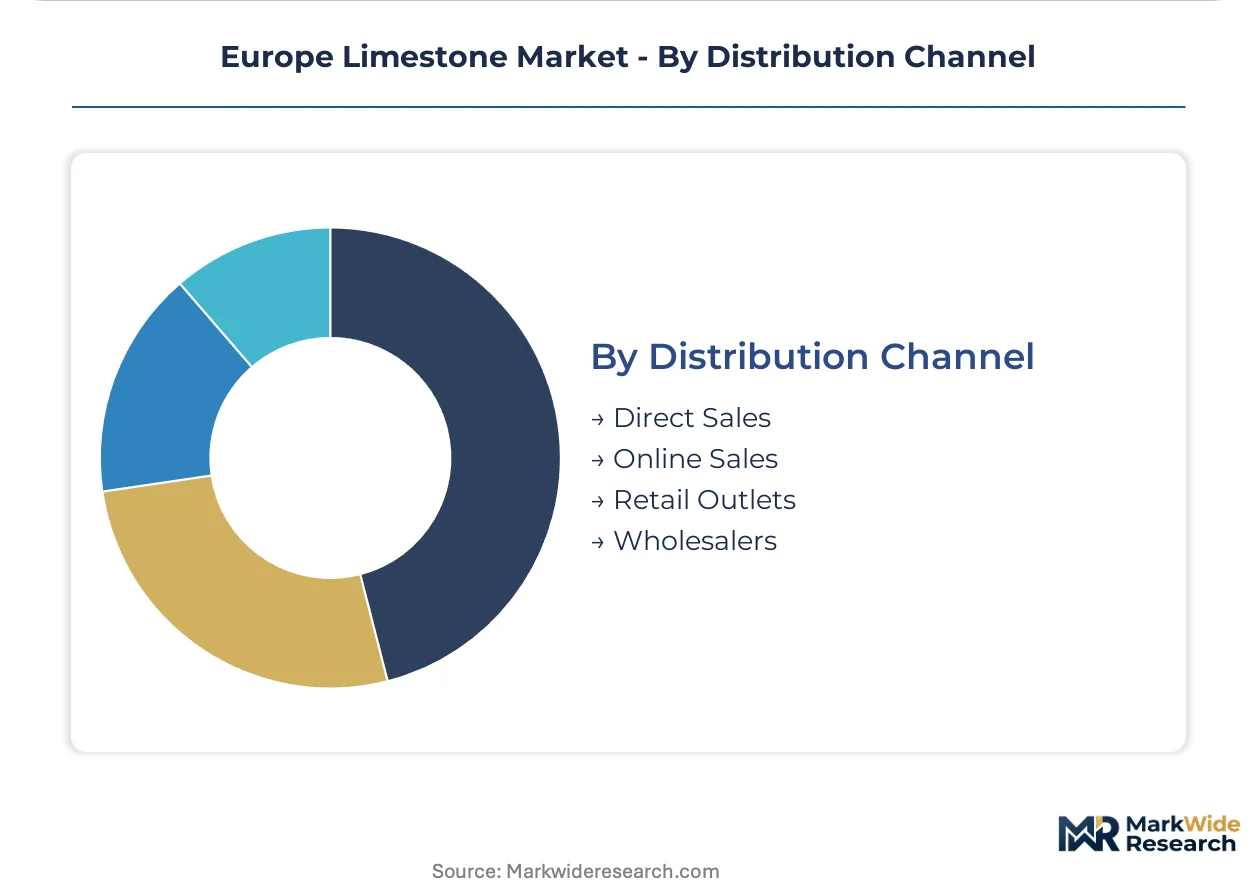
- Direct Sales:Quarry-to-plant arrangements for high-volume industrial consumers. Major concrete producers are locking multi-year contracts with single-quarry operators to guarantee specification consistency.
- Online Sales:Emerging platform for specialty grades and small-lot agricultural lime. Limited penetration reflects bulk logistics constraints and specification verification requirements.
- Retail Outlets:Garden center and farm supply distribution for consumer and smallholder segments. Regional coverage concentrates in France and Germany.
- Wholesalers:Intermediate stocking for construction aggregates and standard agricultural grades. Inventory positions swing with TTF natural gas benchmark movements affecting kiln operating rates.
Volume flows through Direct Sales; channel development targets Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany, Poland, and France absorb the largest limestone volumes for infrastructure and decarbonization projects. Cement and steel producers across these markets are diversifying supply away from single-pit dependencies as EU emissions standards tighten.
Germany
Infrastructure contractors in Bavaria and North Rhine-Westphalia drive crushed limestone consumption for road base and concrete filler. Quarry permitting delays under the Habitats Directive stretch approval timelines to 4-7 years, constraining reserve replacement. The Rhine-Ruhr industrial corridor hosts steel producers sourcing higher-purity feedstock to reduce process emissions intensity under carbon border adjustments.
Poland
Coal plant retrofits in Silesia and Greater Poland consume specialized ground limestone grades for flue gas desulfurization scrubbers. The National Energy and Climate Plan accelerates power sector decarbonization, pulling reactivity-controlled material for SO2 capture. Warsaw-based construction groups are absorbing volumes previously directed westward as Eastern European infrastructure buildout intensifies.
France
Northern French concrete producers lock multi-year offtake contracts bundling material, logistics, and technical service. The EU Green Deal drives cement makers toward integrated supply agreements guaranteeing carbon footprint documentation under CSRD reporting obligations. Lille and Dunkirk anchor quicklime production networks retrofitting oxy-fuel combustion systems for carbon capture concentration.
Belgium
Walloon kiln operators pioneer electrothermal calcination pilots converging with renewable power purchase agreements. The F-Gas Regulation phases down hydrofluorocarbon use, indirectly pressuring hydrated lime supply for alternative cooling chemistry. Antwerp chemical processors reformulate around ammonia and CO2 loops, pulling higher-reactivity grades from regional suppliers.
United Kingdom
Scottish and Northern English water treatment infrastructure upgrades absorb certified limestone for pH adjustment under tightened effluent standards. The Industrial Emissions Directive transposition accelerates municipal plant retrofits. Teesside and Humber industrial clusters source low-silica feedstock for steel fluxing as carbon border mechanisms reshape procurement priorities.
Europe Limestone Market Competitive Landscape
Capacity expansion dominates the current landscape as kiln operators retrofit for oxy-fuel combustion and carbon capture readiness. The market structures around vertically integrated multinationals controlling quarry-to-plant networks, mid-scale regional specialists, and niche purity-grade producers. Three archetypes define positioning: thermal-efficiency leaders optimizing kiln fuel economics, specification masters commanding pharmaceutical and food-grade premiums, and logistics-integrated contractors bundling material with technical service. M&A activity and strategic partnerships concentrate volume with suppliers capable of guaranteeing CSRD-compliant carbon documentation.
Among Belgium-based operators, Carmeuse anchors extensive kiln networks securing thermal efficiency advantages in quicklime production. Lhoist Group exemplifies deep upstream control over lime hydration and dolomitic specialties. Schaefer Kalk occupies a defensible position above commodity pricing tiers through ultra-pure calcium carbonate grades for pharmaceutical and food-grade applications.
| Leading Market Players |
|---|
| Cemex SAB de CV |
| Schaefer Kalk |
| Carmeuse |
| Minerals Technologies Inc |
| Omya AG |
| Lhoist Group |
| Imerys |
| Graymont Limited |
| Holcim Ltd |
| Others |
Pricing and Supply Chain Analysis
The EU Emissions Trading System gates qualified supply for kiln operators and simultaneously restricts premium-tier pricing access to those with verified carbon documentation. Cement and steel producers now bundle carbon footprint certification into procurement specifications, compressing margins for undocumented material while rewarding CSRD-compliant suppliers with contract security.
Pricing Analysis
Volume concentrates in crushed limestone for construction aggregates where spot-market volatility and TTF natural gas benchmark swings compress margins, while pharmaceutical-grade calcium carbonate commands substantial premiums through MDR traceability and REACH compliance. Three-tier pricing structure separates ultra-pure excipient grades from standard industrial lime and unprocessed quarry run. Cost compression in commodity construction tiers is intensifying because slag and fly ash substitution erodes limestone's clinker feedstock share. Farmers exhibit peak price sensitivity through cooperative purchasing aggregators, whereas pharmaceutical formulators absorb premium multiples for certified excipient supply.
Supply Chain Analysis
Single-source vulnerability sits with German and Polish quarry operators facing Habitats Directive permitting timelines stretching to seven years, constraining reserve replacement for Rhine-Ruhr and Silesian industrial corridors. Production draws from Belgian kiln networks, French quicklime operations, and Bavarian crushed stone pits. Refractory-grade limestone with controlled silica content, natural gas for calcination, and specialized grinding media constitute critical input dependencies. Logistics chokepoints at Antwerp chemical terminals and Rhine barge capacity create downstream bottlenecks. Distribution runs through direct quarry-to-plant arrangements for high-volume industrial consumers, with wholesalers holding intermediate inventory positions that swing with fuel cost volatility.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Industrial Emissions Directive transposition creates a compliance moat where permitted kiln capacity becomes a scarce, defensible asset. New quarry approvals under the Habitats Directive now function as barrier-to-entry mechanisms protecting incumbent returns.
For Market Incumbents: Acquire permitted limestone reserves in Bavaria and Rhineland-Palatinate before Habitats Directive timelines extend further. Secure backward integration into captive grinding and classification capacity to guarantee particle size distribution for flue gas desulfurization contracts. Carbon border adjustment documentation requirements threaten operators without verified supply chain traceability, making CSRD-compliant carbon accounting infrastructure a critical defensive lever. For New Entrants and Emerging Players: Electrothermal calcination pilots using renewable power purchase agreements offer technology-first positioning against fossil-fired incumbents. White-space targets concentrate in pharmaceutical-grade calcium carbonate for antacid and supplement applications, where MDR traceability requirements deter commodity producers. Romanian and Bulgarian infrastructure buildout absorbs material previously directed westward, creating geographic entry points through crushed limestone supply to Warsaw-based construction groups. For Investors and Strategic Acquirers: First issuance of carbon removal certification methodologies for limestone-derived carbon capture and storage is the leading indicator that voluntary carbon market revenue streams will materialize for hard-to-abate sector suppliers. Long-term viability favors vertically integrated quarry-to-plant networks with demonstrated oxy-fuel combustion retrofit capability. Acquisition targets should display permitted reserve depth, captive lime hydration capacity, and existing pharmaceutical-grade certification infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Oxy-Fuel Combustion Retrofit | Concentrates CO2 streams for capture at Lille and Dunkirk kiln networks. |
| Carbon Removal Certification | Unlocks voluntary carbon market revenue for Belgian and French operators. |
| Pharmaceutical-Grade Capacity Expansion | Captures premium multiples above commodity construction grades through MDR compliance. |
| Eastern European Quarry Development | Supplies Romanian and Bulgarian road construction absorbing diverted volumes. |
| Integrated Supply Agreement Consolidation | Bundles material, logistics, and technical service for northern French concrete producers. |
Research Methodology
Trade statistics from Eurostat, customs declarations from German and Polish export registries, and SEC filings from listed building materials companies formed the secondary backbone for volume and value estimation. Primary interviews with quarry operations managers, procurement leads at cement and steel producers, technical directors at lime hydration facilities, and municipal water treatment engineers validated extraction rates and specification trends. Bottom-up triangulation across these sources reconciled with top-down macroeconomic indicators for construction and industrial output.
Bottom-up modeling of kiln capacity utilization, quarry extraction rates, and end-use consumption patterns converged with top-down GDP elasticity assumptions for construction and manufacturing investment across the analysis window. Segmentation dimensions included product form, application intensity, end-user procurement scale, and regional regulatory cluster. CAGRs were derived from fitted trend extrapolation adjusted for policy intervention effects, incorporating natural gas price volatility, Habitats Directive permitting velocity, and carbon border adjustment implementation pace as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including unannounced quarry closure orders, breakthroughs in slag chemistry eliminating limestone from clinker production, and abrupt shifts in EU ETS allowance allocation. Forecasts reflect documented assumptions about permitting timelines, fuel cost trajectories, and carbon removal certification adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Minerals
Europe Frac Sand Market
Industrial Minerals
North America Silica Sand Market
Industrial Minerals
Feldspathic Minerals Market
Industrial Minerals
Pyrites Market
Industrial Minerals
Olivine Sand Market
Industrial Minerals
Oman Industrial Salts Market
Industrial Minerals
Nepheline Syenite Market
Industrial Minerals
Limestone Market
Industrial Minerals
Diatomite Mining Market
Industrial Minerals
Global Graphite Market
Industrial Minerals
Dolomite Powder Market
Industrial Minerals
Micronized Salt Market
Industrial Minerals
Europe Feed Minerals Market
Industrial Minerals
Calcined Anthracite Market
Industrial Minerals
United States Feed Minerals Market
Industrial Minerals
Potash Ores Market