
 Bio-Succinic Acid Market | 2026-2036
Bio-Succinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Succinic Acid Market Intelligence
The shift toward high-purity, food-grade bio-succinic acid is rotating the market away from purely industrial applications toward higher-value segments. Major producers like BASF SE leverage extensive chemical manufacturing scale to influence pricing and supply. Corbion N.V. specializes in advanced fermentation processes, differentiating its product portfolio. Mitsubishi Chemical Group Corporation anchors its strategy in downstream applications, particularly in the development of advanced biopolymers.
Bio-succinic acid is a dicarboxylic acid produced through the fermentation of renewable feedstocks like corn starch or sugarcane. This bio-based process yields a platform chemical identical to its petrochemical counterpart, crucial for sustainable chemistry. The plastics application, particularly for producing biodegradable polymers, constitutes the largest demand segment. Concurrently, the cosmetics and food additives applications are expanding rapidly, offering higher margin potential for specialized producers.
Regulations such as the EU’s REACH framework and the US FDA’s guidelines for food contact materials govern market access and product safety. In parallel, China's GB standards and its dual carbon goals create domestic incentives for bio-based chemical production. Future competitiveness hinges on securing low-cost, sustainable feedstock supply chains against a backdrop of fluctuating agricultural commodity prices.
Market Dynamics
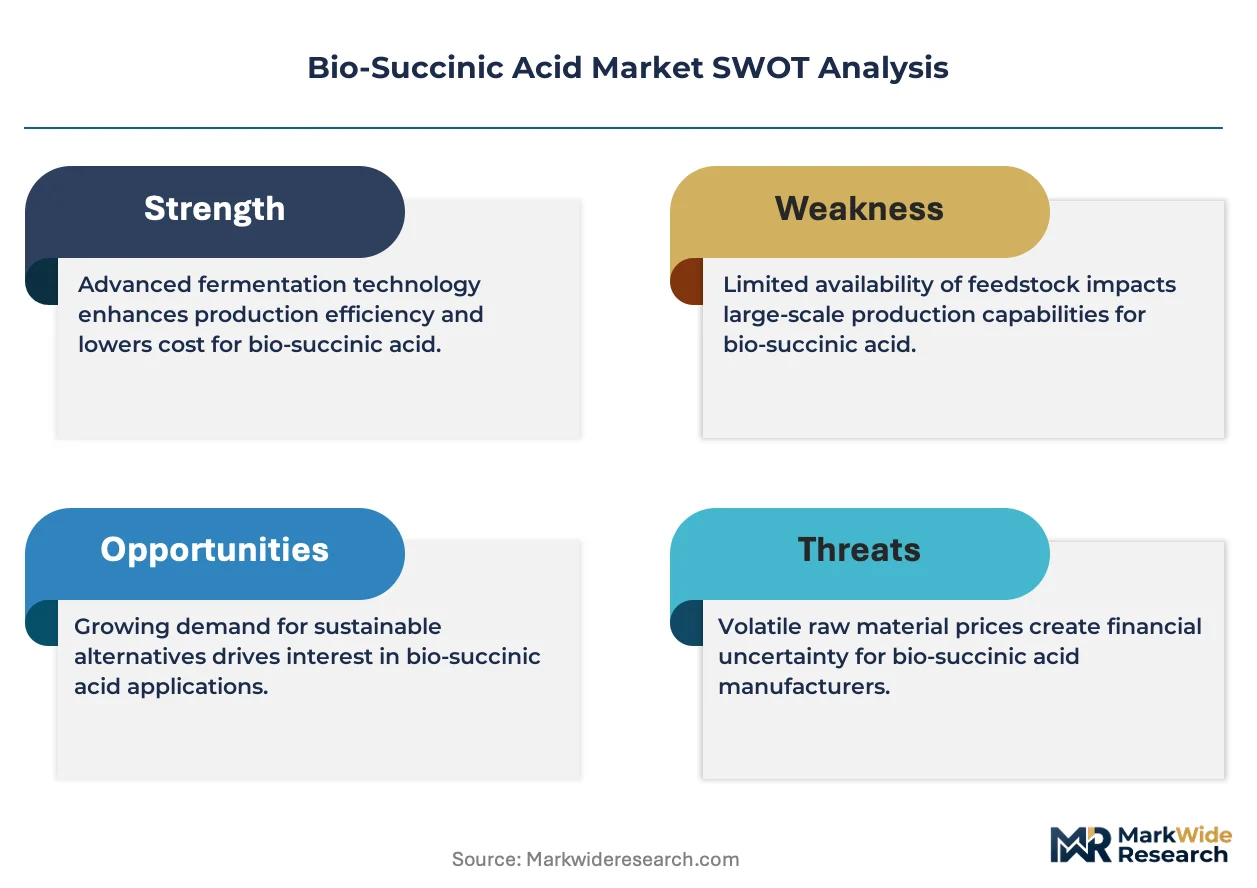
The market's central dynamic is the tension between strong regulatory-driven demand for bio-based chemicals in Europe and North America and the inherent volatility of agricultural feedstock supply chains, which complicates long-term cost and price stability for producers.
Growth Catalysts
- EU Green Deal Incentives:This policy framework accelerates the substitution of petrochemicals in key industrial economies like Germany, directly stimulating demand for bio-succinic acid in the production of biodegradable plastics and coatings.
- Biopolymer Demand:The rapid expansion of the polybutylene succinate (PBS) market for applications in sustainable packaging, agricultural mulch films, and single-use cutlery creates a primary volume driver for bio-succinic acid.
- Advanced Fermentation Processes:Innovations in microbial strain engineering and fermentation technology are improving conversion yields from renewable feedstocks like corn starch, which helps lower the overall manufacturing cost base for producers.
Market Restraints
- Feedstock Price Volatility:Production costs are directly exposed to price fluctuations in agricultural commodities such as sugarcane and corn, creating margin uncertainty and making it difficult to compete with stable petrochemical alternatives.
- Petrochemical Substitution Threat:Fossil-derived succinic acid remains a lower-cost alternative in many industrial applications, particularly in regions without strong carbon pricing or bio-based mandates, limiting market penetration.
- High Purification Costs:Achieving the high-purity grades required for food, pharmaceutical, and cosmetic applications involves energy-intensive separation and purification steps, which adds significant cost and constrains widespread adoption in these segments.
Strategic Opportunities
- High-Margin Cosmetics Applications:The use of bio-succinic acid as a functional ingredient in skincare formulations, acting as a pH adjuster and antimicrobial agent, presents a high-value, fast-growing opportunity outside of bulk industrial uses.
- China's Bio-Based Mandates:The country's dual carbon goals and evolving GB standards for biodegradable materials are creating a large, policy-driven domestic market for bioplastics and their chemical precursors, including bio-succinic acid.
- Waste-to-Chemical Pathways:Developing commercial processes to produce bio-succinic acid from non-food biomass, such as agricultural residue or municipal solid waste, could decouple production costs from volatile food commodity markets.
Industry Challenges
- Biorefinery Scale-Up:The construction of new large-scale fermentation and purification facilities requires substantial capital investment and involves long project timelines and significant commissioning risks for producers aiming to expand capacity.
- Navigating Multi-Regional Compliance:Producers face an operational burden in securing and maintaining compliance across divergent international regulatory systems, such as the EU's REACH framework and the US FDA's food contact substance notifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Succinic Acid Market |
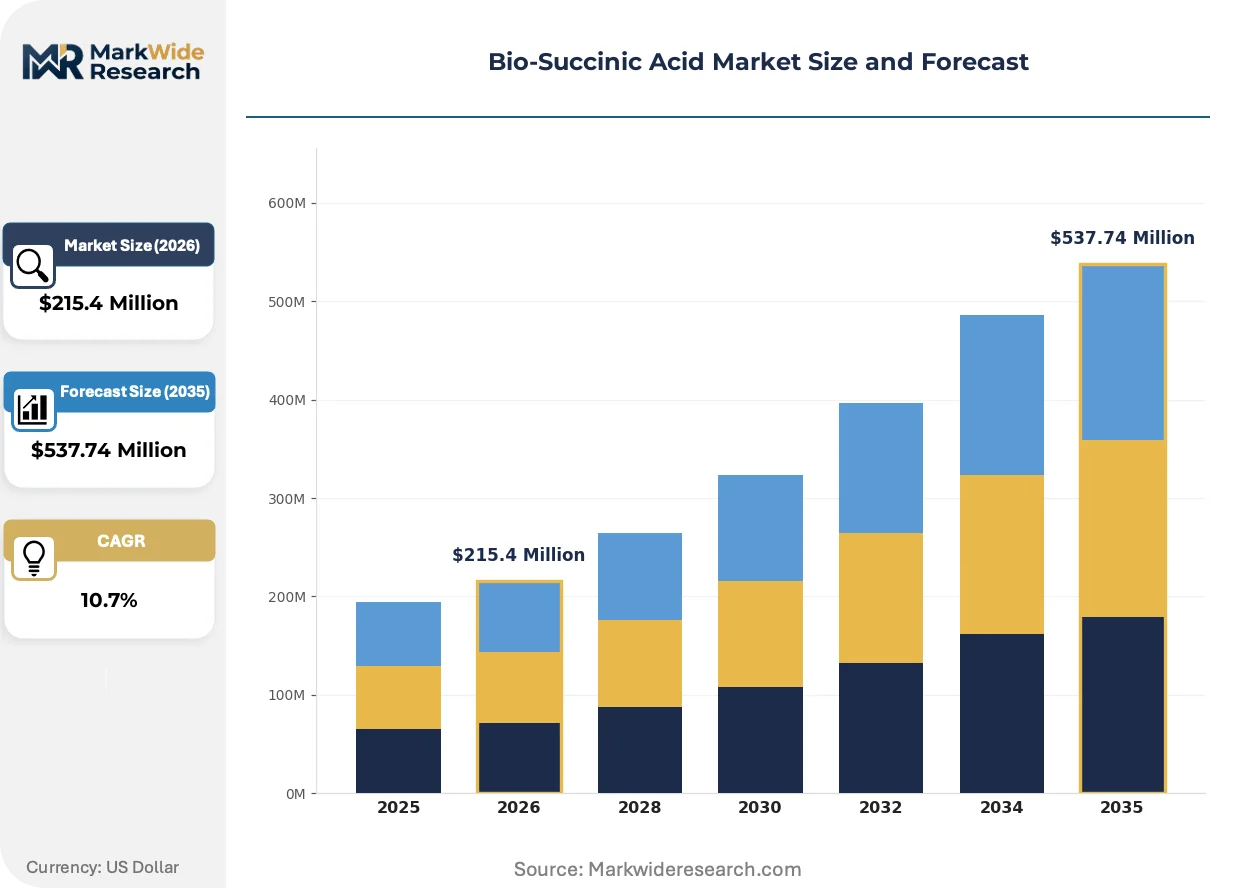
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $537.74 Million |
| CAGR (2026 – 2036) | 10.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-Based, Synthetic, Hybrid, Green Application: Plastics, Cosmetics, Pharmaceuticals, Food Additives End User: Manufacturers, Distributors, Retailers, Chemists Packaging Type: Bottles, Drums, Tanks, Bags |
| Companies Covered | BASF SE, DSM-Firmenich, Roquette Frères, Mitsubishi Chemical Group Corporation, Mitsui & Co., Ltd., Corbion N.V., Nippon Shokubai Co., Ltd., PTT Global Chemical Public Company Limited, Kawasaki Kasei Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Succinic Acid Market Strategic Shifts & Innovations
Specialization toward higher-purity grades is redefining the market's competitive landscape. This pivot moves producers away from competing solely on volume for industrial applications and toward capturing value in regulated end-uses like cosmetics and food additives, where performance and certification matter more than price.
Downstream purification technology, particularly continuous chromatography and advanced membrane filtration, is critical for separating bio-succinic acid from complex fermentation broths. Specialty chemical formulators targeting food-grade and cosmetics applications are rapidly adopting these systems to ensure product consistency and purity. This improved process efficiency is miniaturizing the physical footprint of purification units and reducing the energy intensity per kilogram of finished product.
China's national GB standards for biodegradable materials are becoming increasingly influential on global supply chains. The policy mandates the use of materials like PBS in specific single-use plastic categories, including food service items and agricultural films, creating a direct demand pull. Consequently, plastics converters in industrial provinces such as Zhejiang and Jiangsu are accelerating their qualification of bio-succinic acid suppliers to meet these new requirements.
A significant shift in buyer behavior is evident, as formulators in the personal care industry prioritize ingredients with certified bio-based content and transparent supply chains. This moves procurement decisions beyond unit price to include credentials like USDA BioPreferred or non-GMO project verification. The trend is most visible in North American and European consumer markets, where brand storytelling around sustainability is a key differentiator.
Bio-Succinic Acid Market Segmentation
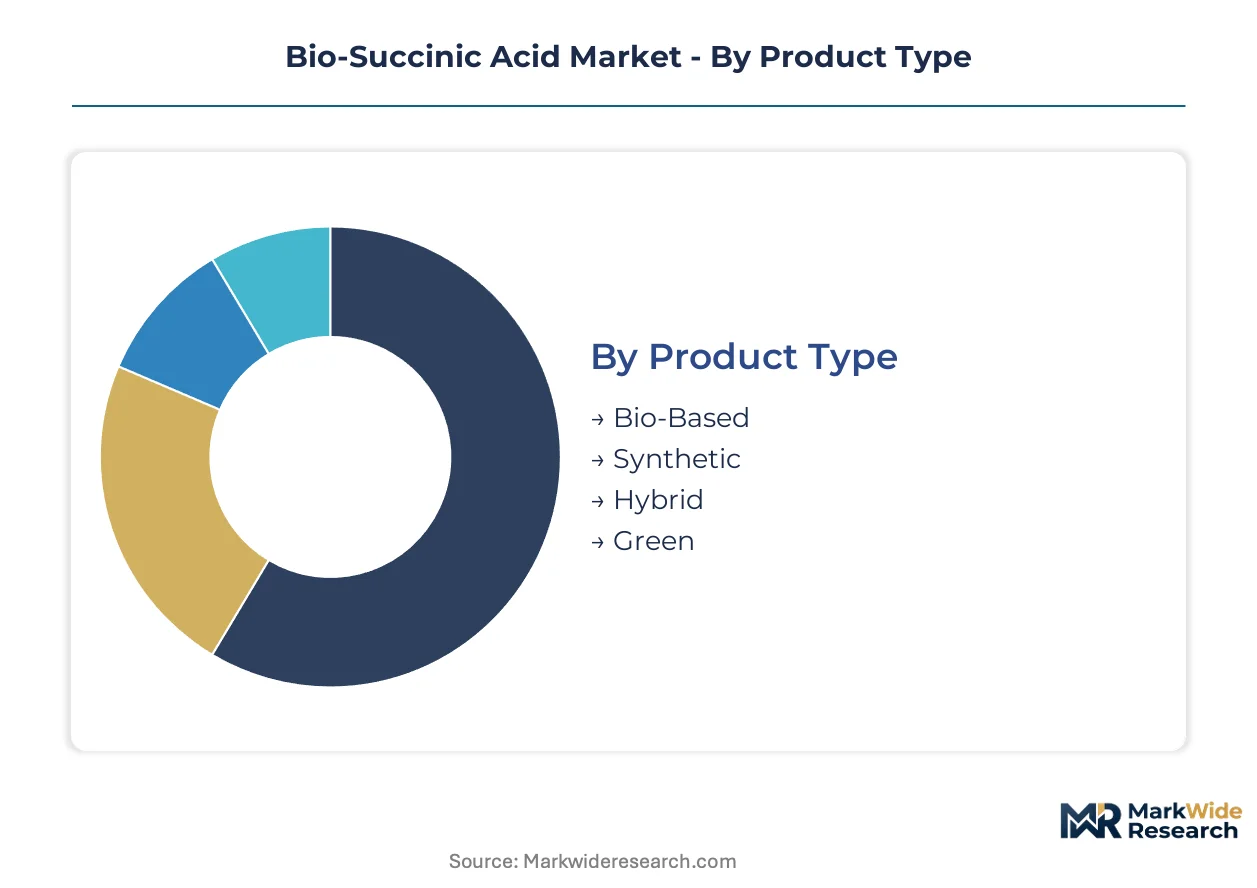
The Bio-Succinic Acid market is analyzed across several dimensions, revealing how product characteristics, end-use sectors, and distribution channels influence demand patterns. Understanding these segments helps producers align their output with specific market needs and regulatory requirements. This granular view highlights areas of concentrated value.
Product Type:
The varied product types of bio-succinic acid exhibit distinct demand profiles, with some grades primarily serving domestic markets while others are designed for international export.
- Bio-Based:Bio-Based succinic acid originates from the fermentation of renewable feedstocks such as corn or sugarcane, providing a sustainable chemical building block. Demand concentrates heavily in European industrial nations like Germany, driven by the EU Green Deal's mandates for biodegradable polymers.
- Synthetic:Synthetic succinic acid, derived from petrochemical processes, remains a cost-effective alternative for industrial applications lacking bio-based mandates.
- Hybrid:Hybrid succinic acid formulations combine bio-based and synthetic components to achieve specific performance profiles or cost efficiencies in niche applications.
- Green:Green succinic acid refers to high-purity, sustainably certified variants often meeting stringent environmental and ethical standards. This type sees strong demand in North American and European cosmetics and food additive sectors, where consumer preference for certified ingredients is high.
Bio-Based succinic acid holds the largest market share; momentum sits with Green succinic acid.
Application:
Applications for bio-succinic acid vary significantly in their volume requirements and market maturity, influencing production scale and distribution strategies.
- Plastics:The plastics application segment primarily utilizes bio-succinic acid as a monomer for producing biodegradable polymers, such as polybutylene succinate (PBS). This segment drives significant volume, particularly for sustainable packaging and agricultural films, supported by China's GB standards and EU directives.
- Cosmetics:Bio-succinic acid functions as a pH adjuster and antimicrobial agent in various skincare formulations, offering a high-value proposition for personal care products. This application commands higher margins within the personal care industry, where certified bio-based content strengthens brand narratives.
- Pharmaceuticals:In pharmaceuticals, bio-succinic acid serves as an excipient or an intermediate in drug synthesis, requiring ultra-high purity grades.
- Food Additives:Food additives leverage bio-succinic acid as a flavor enhancer and acidulant, adhering to strict guidelines like those from the US FDA.
Plastics applications dominate volume; cosmetics and food additives are climbing the fastest.
End User:
End-user segments reflect varying levels of direct consumption and integration within the bio-succinic acid value chain, from primary producers to final product formulators.
- Manufacturers:Manufacturers directly integrate bio-succinic acid into their production processes for creating polymers, resins, and other intermediate chemicals. These large-scale industrial buyers prioritize consistent supply, technical support, and competitive pricing for their high-volume operations.
- Distributors:Distributors manage the supply chain logistics, connecting producers with smaller-scale end-users across diverse regional markets.
- Retailers:Retailers primarily sell finished consumer products containing bio-succinic acid, such as cosmetics or cleaning agents, to the general public.
- Chemists:Chemists in R&D or specialized formulation roles utilize bio-succinic acid for developing new products or optimizing existing chemical processes. They require high-purity grades and comprehensive technical data to support innovation in niche, high-value applications.
Manufacturers dominate direct demand; specialized chemists drive product innovation.
Packaging Type:
The packaging types for bio-succinic acid are dictated by the volume of material required for transport and the specific handling needs of the end-user application.
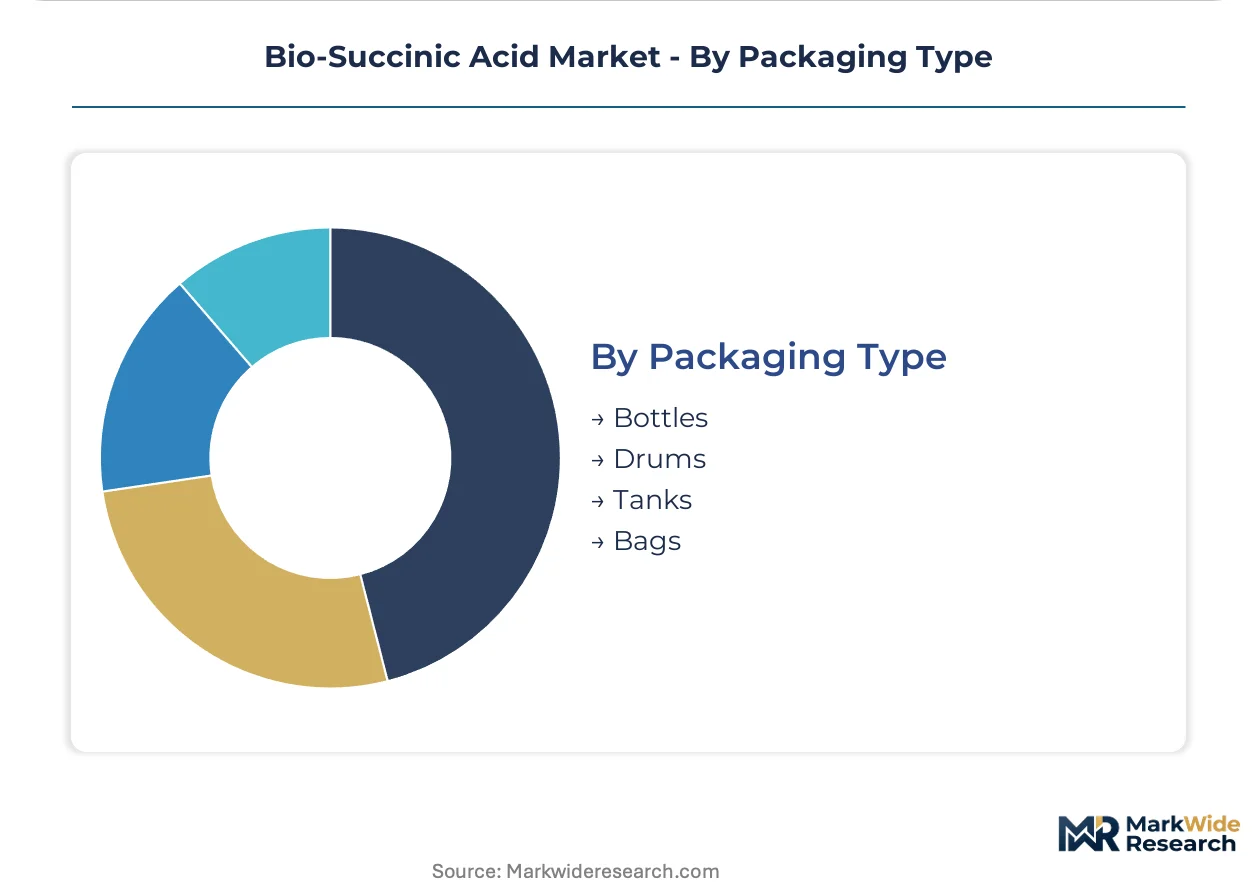
- Bottles:Bottles are used for small volumes of high-purity bio-succinic acid, typically for laboratory research or specialized cosmetic formulations.
- Drums:Drums facilitate the transport of intermediate volumes of bio-succinic acid, commonly used by chemical manufacturers and formulators for industrial applications. This packaging type supports regional distribution networks, providing a balance between bulk efficiency and manageable handling.
- Tanks:Tanks, including ISO tanks and railcars, are employed for bulk transport of bio-succinic acid to large-scale industrial end-users with integrated production facilities. This method is critical for continuous processes in polymer synthesis, optimizing logistics and cost efficiency for high-volume consumers.
- Bags:Bags are utilized for the powdered form of bio-succinic acid, particularly in applications requiring dry solid material.
Tanks serve the largest industrial volumes; smaller formats cater to specialized needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global bio-succinic acid market exhibits a dynamic export-import balance, with European nations driving significant demand for bio-based alternatives. Production centers in Asia and North America often supply these markets, creating complex trade flows. Regulatory incentives in key regions heavily influence these international movements.
Germany
Germany's strong industrial base drives demand for bio-succinic acid in biodegradable plastics and sustainable coatings. The EU Green Deal and REACH framework significantly incentivize the substitution of petrochemicals with bio-based alternatives. Chemical manufacturing hubs in the Rhine-Ruhr region are central to integrating bio-succinic acid into polymer production.
China
China's expanding bioplastics industry creates substantial demand for bio-succinic acid, particularly for polybutylene succinate (PBS). The national GB standards for biodegradable materials, coupled with dual carbon goals, mandate its use in various plastic categories. Plastics converters in industrial provinces like Zhejiang and Jiangsu are rapidly qualifying new bio-succinic acid suppliers.
United States
The United States market exhibits robust demand for high-purity bio-succinic acid in cosmetics and food additive applications. FDA guidelines for food contact materials and USDA BioPreferred certification influence procurement decisions for sustainable ingredients. Personal care formulators in the Northeast corridor increasingly prioritize ingredients with transparent, certified bio-based content.
Netherlands
Netherlands, a key European chemical manufacturing hub, focuses on advanced biopolymers and sustainable chemistry solutions. The EU Green Deal and ECHA regulations promote the integration of bio-based chemicals into industrial processes. Major chemical clusters around Rotterdam are actively developing new downstream applications for bio-succinic acid.
Bio-Succinic Acid Market Key Industry Players
Listed leaders compete with private specialists across the bio-succinic acid value chain, driving innovation and market expansion. The market exhibits a tiered structure, with large chemical conglomerates alongside specialized bio-fermentation firms. Key archetypes include integrated chemical producers leveraging extensive scale, fermentation technology specialists differentiating product portfolios, and downstream application developers focusing on advanced biopolymers. Strategic partnerships and capacity expansions are dominant competitive moves, aiming to secure low-cost feedstock supply and expand market reach into high-value segments.
Among the integrated chemical producers, BASF SE exemplifies a strategy of leveraging extensive chemical manufacturing scale to influence pricing and supply dynamics across various industrial applications. Corbion N.V. represents a specialist in advanced fermentation processes, differentiating its product portfolio through innovative production methods and targeting higher-purity segments. Mitsubishi Chemical Group Corporation occupies a position focused on downstream applications, particularly in the development of advanced biopolymers, anchoring its strategy in material science. These companies collectively demonstrate the varied approaches to market penetration and value capture, from bulk supply to specialized high-value end-uses within the bio-succinic acid industry.
| Leading Market Players |
|---|
| BASF SE |
| DSM-Firmenich |
| Roquette Frères |
| Mitsubishi Chemical Group Corporation |
| Mitsui & Co., Ltd. |
| Corbion N.V. |
| Nippon Shokubai Co., Ltd. |
| PTT Global Chemical Public Company Limited |
| Kawasaki Kasei Chemicals |
| Others |
Cost & Logistics Intelligence
EU Green Deal incentives and US FDA guidelines gate both bio-succinic acid supply qualification and price differentiation simultaneously. These regulatory frameworks drive demand for certified bio-based content, impacting market entry and premium pricing for specialized grades.
Pricing Analysis
Industrial OEM buyers anchor long-term, contract-based pricing for bulk bio-succinic acid. Price differentiation stems from quality grade, with high-purity variants commanding premiums for cosmetics and food additives, and certified content like USDA BioPreferred also influencing value. Pricing softness in industrial segments reflects competition from petrochemical alternatives. Cosmetics and pharmaceutical formulators exhibit lower price sensitivity than large-volume polymer manufacturers.
Supply Chain Analysis
Feedstock availability is a critical chokepoint, with production heavily concentrated in agricultural regions of North America and Asia. The supply chain draws from corn starch and sugarcane, making it vulnerable to agricultural commodity price volatility. China, the Netherlands, and the United States represent key production and processing hubs. Distribution runs through a hybrid model of direct sales to large manufacturers and regional distributors serving specialized formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-succinic acid market represents an early-cycle expansion story, driven by accelerating biopolymer demand and increasing regulatory incentives for bio-based chemicals. This creates significant opportunities across the value chain.
For Market Incumbents: Secure long-term feedstock supply agreements to mitigate agricultural commodity price volatility, a persistent threat to margin stability. Invest in advanced biorefinery capacity, particularly in Europe and China, to meet escalating demand for biodegradable plastics. Develop proprietary purification technologies to achieve ultra-high purity grades required for sensitive applications. Leverage existing chemical manufacturing scale to optimize production costs against emerging competition.
For New Entrants and Emerging Players: Lead with specialized, high-purity bio-succinic acid grades for cosmetics and food additives, where performance and certification matter more than bulk volume. Target underpenetrated regional markets in Southeast Asia or Latin America with strong sustainability narratives. Develop waste-to-chemical pathways to decouple production costs from volatile food commodity markets, offering a unique value proposition. Pursue certification like USDA BioPreferred for market differentiation.
For Investors and Strategic Acquirers: EU Green Deal expansion reshapes the acquisition landscape, favoring companies with proven bio-based production technologies and strong regulatory compliance. The market offers long-term viability over the next decade, driven by sustained demand for sustainable materials. Target specialized fermentation technology firms or biorefinery operators with diverse feedstock capabilities for strategic integration. Practitioners should keep alternative scenarios live as global carbon pricing mechanisms evolve.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | To meet rising demand for polybutylene succinate in China’s packaging sector. |
| Green Manufacturing Transition | To reduce energy intensity in bio-succinic acid purification processes. |
| Long-term Feedstock Agreements | To secure stable corn starch and sugarcane access, mitigating price volatility. |
| Joint Venture with Biopolymer Developers | To accelerate the development of advanced downstream applications for bio-succinic acid. |
| High-Purity Grade Certification | To unlock high-value segments in North American and European cosmetics markets. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EU REACH documents, US FDA guidelines, and China GB standards. This involved in-depth interviews with R&D directors, procurement leads, plant managers, and regulatory affairs specialists across the bio-succinic acid value chain. Data triangulation utilized both bottom-up market sizing and top-down validation approaches.
Segmentation dimensions modeled include product type, application, end-user, packaging type, and regional production hubs, providing a granular market view. Compound annual growth rates (CAGRs) were derived from historical growth trends and future demand projections across the modeling period. Key forecast inputs included feedstock price trends and evolving regulatory policy shifts.
The analysis sits within stated boundaries; outcomes outside significant agricultural commodity shocks or geopolitical trade disruptions would require recalibration. Forecasts reflect assumptions regarding technological advancements and sustained regulatory support for bio-based chemicals. Practitioners should keep alternative scenarios live as global economic conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Sodium Hydroxide Market
Bulk Chemicals
India Lime Market
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Global Concentrated Nitric Acid Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Sodium Bromate Market
Bulk Chemicals
Europe Hydrogen Bromide Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Global Benzaldehyde Market
Bulk Chemicals
United States Iodine Market
Bulk Chemicals
Bromine Market
Bulk Chemicals
India Carbon Black Market
Bulk Chemicals
Global Ammonium Chloride Market
Bulk Chemicals
Europe Titanium Dioxide Market
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Dextrin Market