
 Dimethyl Disulphide (DMDS) Market | 2026-2036
Dimethyl Disulphide (DMDS) Market Size, Share, and Industry Trends Forecast 2026-2036
Dimethyl Disulphide (DMDS) Market Outlook
Petrochemical refining is shifting toward deeper hydrodesulfurization as marine fuel sulfur caps tighten. Arkema S.A. leverages its European manufacturing footprint to serve presulfiding demand. Chevron Phillips Chemical Company anchors North American supply through integrated petrochemical infrastructure. Gaylord Chemical Company, LLC specializes in dimethyl sulfide and DMDS derivatives for specialty chemical markets.
Dimethyl disulphide is an organosulfur compound with the formula CH3SSCH3, a flammable liquid with a characteristic sulfurous odor, manufactured primarily through methanol-thiolation or dimethyl sulfate routes. Its primary commercial purpose is catalyst presulfiding in petroleum refining and as a sulfiding agent in chemical synthesis. Industrial grade DMDS dominates volume consumption in refinery applications where purity thresholds are process-tolerant. Pharmaceutical grade commands premium positioning due to stringent impurity controls for active pharmaceutical ingredient manufacturing. Liquid form leads distribution logistics because of established bulk chemical handling infrastructure.
The EPA regulates DMDS under the Clean Air Act for volatile organic compound emissions in refinery operations. OSHA mandates workplace exposure limits for organosulfur compounds in chemical manufacturing facilities. REACH registration requirements in Europe govern import and production volumes above threshold quantities. Stakeholders must monitor evolving sulfur emission protocols and catalyst technology transitions that could alter presulfiding chemistry requirements.
Market Dynamics
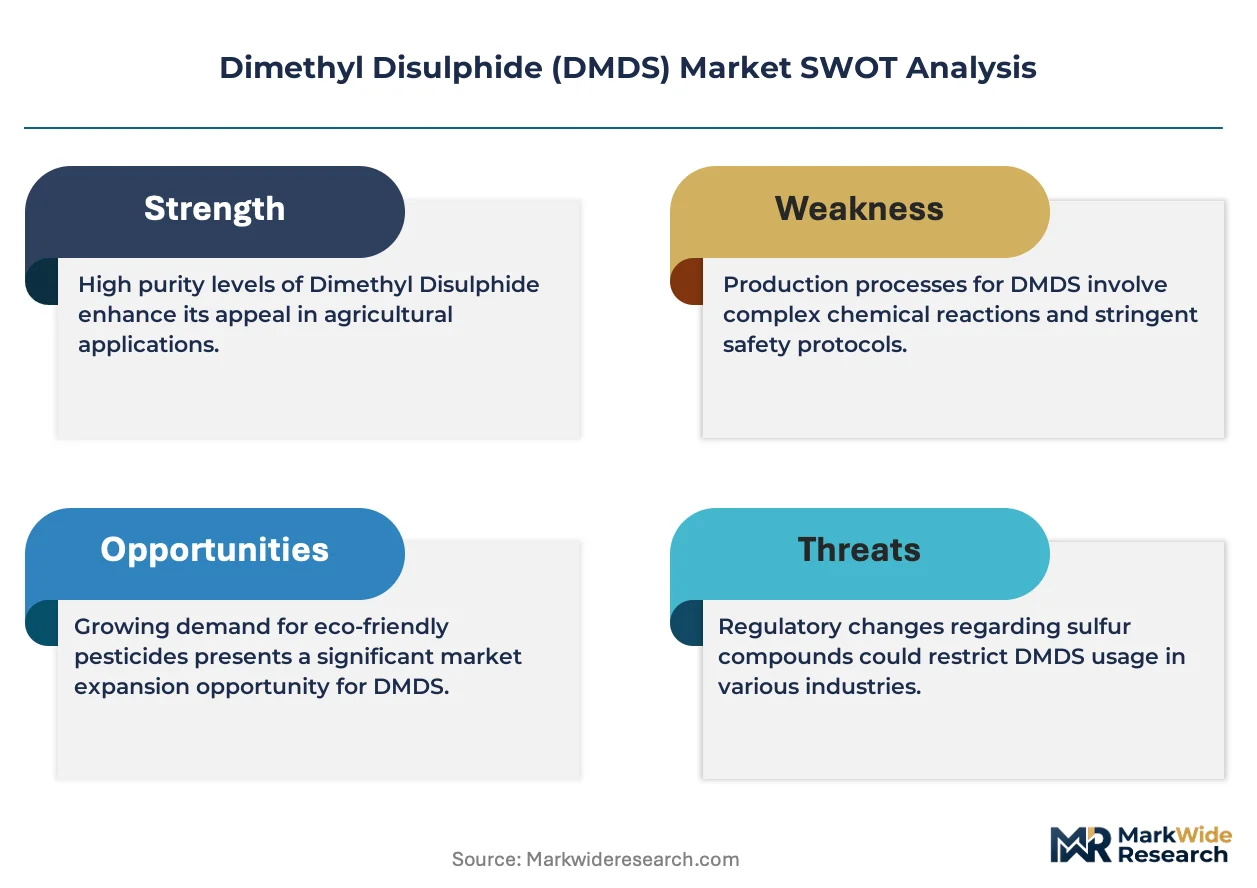
Hydrodesulfurization catalyst presulfiding requirements are intensifying as marine fuel sulfur caps tighten under International Maritime Organization protocols. Refinery operators face simultaneous pressure to process heavier crudes while meeting emission standards, creating structural pull for sulfiding agents.
Growth Catalysts
- IMO 2020 marine fuel sulfur regulations:The 0.5% sulfur cap on bunker fuels forces refiners to upgrade hydrodesulfurization capacity. DMDS serves as the standard presulfiding agent for cobalt-molybdenum and nickel-molybdenum catalyst activation.
- China's dual carbon policy framework:The country's 2030 carbon peak and 2060 neutrality targets accelerate cleaner refinery process adoption. MEE enforcement of sulfur emission standards drives catalyst presulfiding chemical demand.
- Heavy crude processing expansion:Rising Canadian oil sands and Venezuelan heavy crude throughput requires more intensive hydrotreating. DMDS enables effective catalyst sulfidation for high-metal feedstock units.
Market Restraints
- Methanol feedstock volatility:DMDS production relies on methanol-thiolation chemistry. Methanol price swings tied to natural gas and coal economics compress manufacturer margins unpredictably.
- European supply concentration:REACH registration requirements create barriers for new entrants. Arkema's European manufacturing dominance limits supply diversification options for buyers.
- Alternative sulfiding agents:Carbon disulfide and dimethyl sulfide compete for certain presulfiding applications. These substitutes offer lower cost points in price-sensitive refinery procurement.
Strategic Opportunities
- India's refinery capacity expansion:Reliance Industries and Indian Oil Corporation are adding hydrocracking and hydrotreating units. The country's national petroleum regulator emphasizes catalyst efficiency standards.
- Pharmaceutical-grade DMDS certification:Active pharmaceutical ingredient manufacturing requires ultra-low impurity sulfiding agents. CDSCO and FDA compliance create premium pricing tiers.
- Modular refinery deployment:Smaller-scale processing units for stranded gas and remote crude require portable sulfiding solutions. Containerized DMDS delivery systems address this logistics gap.
Industry Challenges
- Organosulfur compound handling expertise:OSHA workplace exposure limits for DMDS require specialized safety protocols. Refinery operators face talent shortages in industrial hygiene and process safety management.
- Catalyst technology transition timing:Next-generation presulfiding chemistries may alter DMDS demand profiles. R&D timelines for non-sulfide activation methods create investment uncertainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dimethyl Disulphide (DMDS) Market |
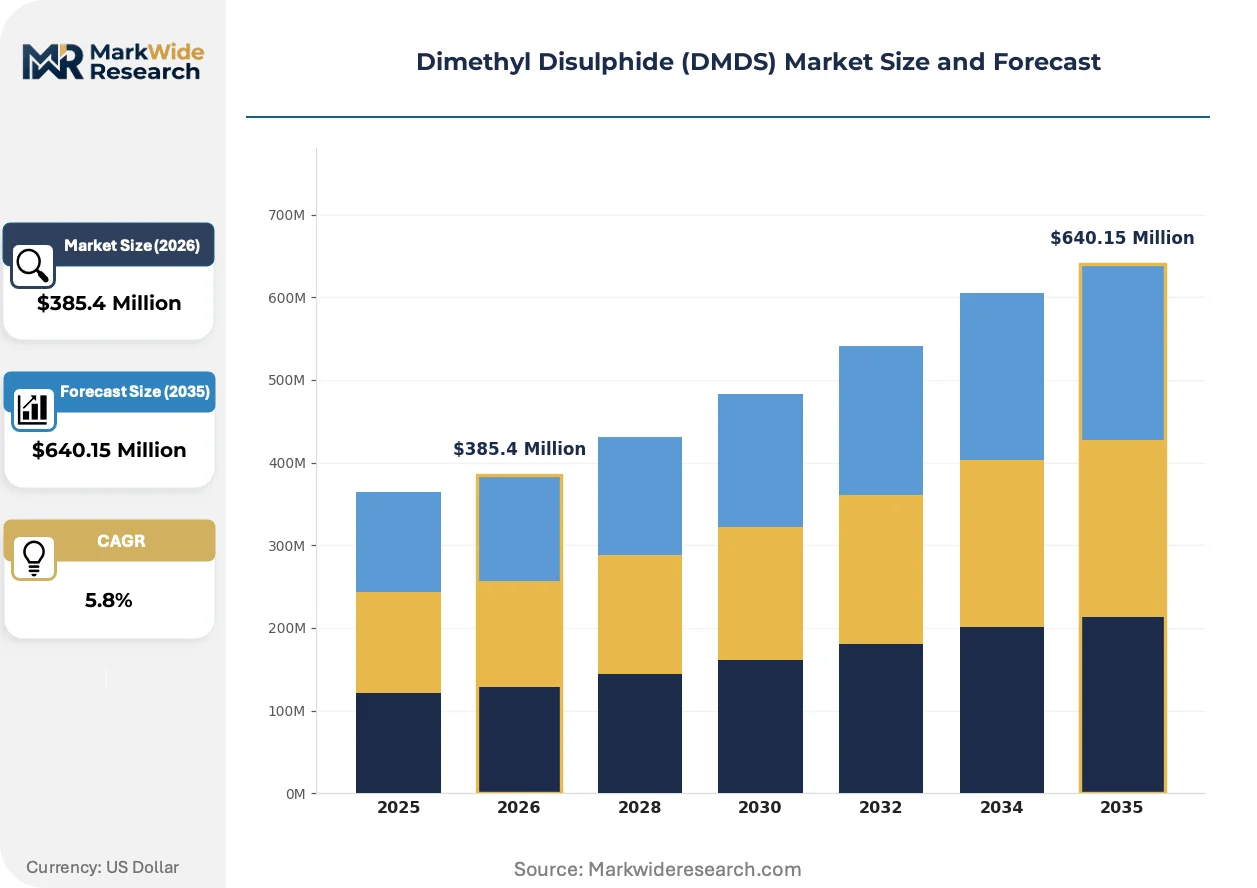
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $640.15 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Agricultural Grade, Food Grade Application: Fumigant, Solvent, Chemical Intermediate, Agrochemical End User: Agriculture, Petrochemical, Pharmaceuticals, Food Processing Form: Liquid, Gas, Solid, Mixture |
| Companies Covered | Arkema S.A., Chevron Phillips Chemical Company, Toray Fine Chemicals Co., Ltd., BASF SE, Gaylord Chemical Company, LLC, Eastman Chemical Company, Huntsman Corporation, Mitsubishi Gas Chemical Company, Inc., Solvay S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dimethyl Disulphide (DMDS) Market Strategic Shifts
Refinery process intensification is compressing catalyst activation windows while raising purity requirements. Three developments are restructuring how sulfiding agents integrate into hydroprocessing operations.
Continuous sulfiding systems are expanding into large-scale hydrotreater operations. These units replace batch-wise DMDS injection with steady-state delivery, improving catalyst bed uniformity. Marathon Petroleum and Phillips 66 have adopted continuous injection at Gulf Coast facilities, reducing activation time by enabling precise sulfur distribution control.
REACH authorization procedures for organosulfur compounds are tightening substance volume tracking across European manufacturing. ECHA's revised registration dossier requirements now mandate extended toxicological data for high-tonnage chemicals. Industrial-grade DMDS producers face compliance cost escalation, pushing some volume toward pharmaceutical-grade certification to capture margin.
Refinery procurement teams are consolidating chemical supplier relationships under master service agreements. Long-term sulfiding agent contracts with technical service bundling are displacing spot market purchases. This pattern concentrates most visibly along the US Gulf Coast, where integrated operators like Chevron Phillips Chemical leverage captive supply infrastructure.
Dimethyl Disulphide (DMDS) Market Segmentation
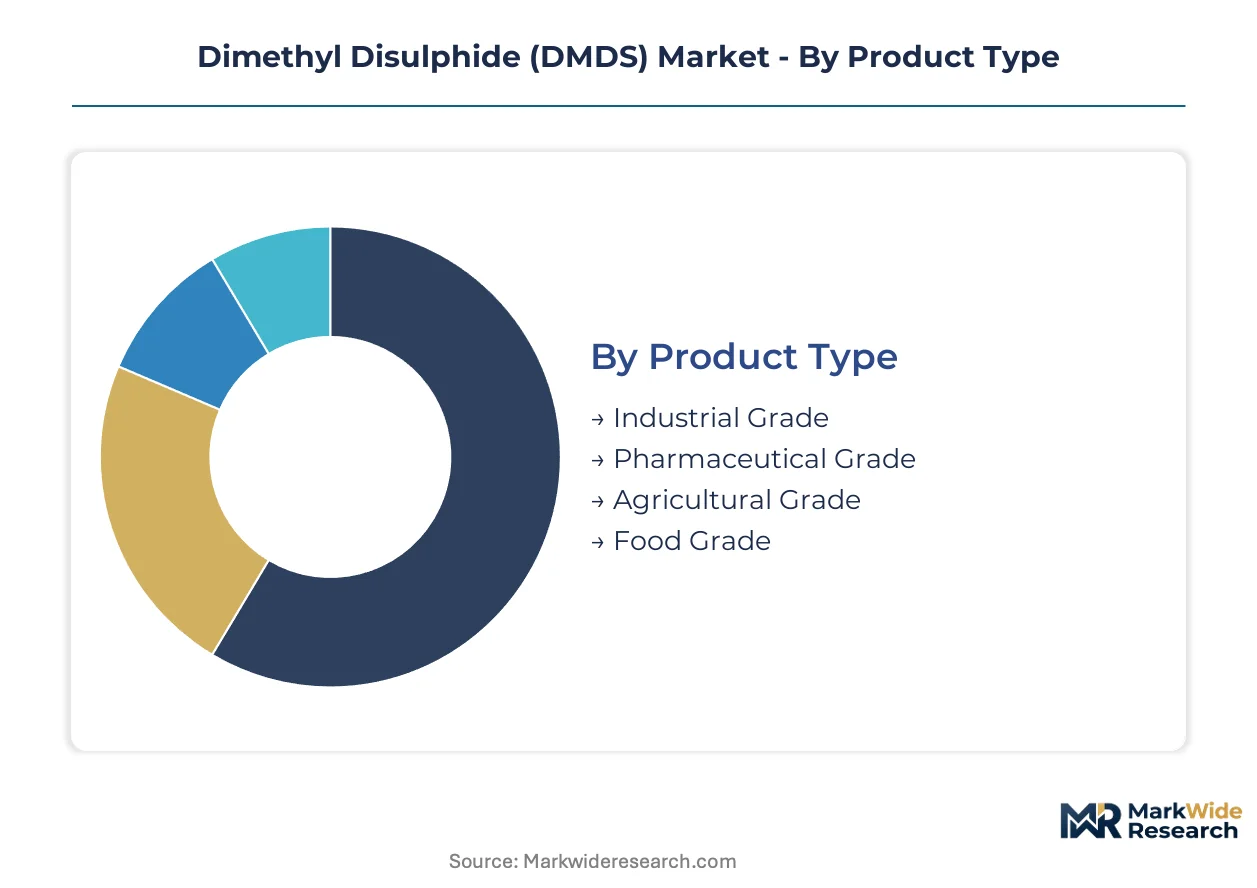
DMDS buyers face divergent purity and handling requirements across refinery, pharmaceutical, and agricultural channels. Segmentation reveals how specification tiers align with regulatory thresholds and process economics in each vertical.
Product Type:
Cost tier separates buyers more than application function, with certification premiums determining procurement budgets.
- Industrial Grade:Process-tolerant purity specifications suit hydrodesulfurization catalyst presulfiding in petroleum refineries. Gulf Coast petrochemical corridors absorb the majority of volumes as IMO marine fuel sulfur caps tighten hydrotreating intensity.
- Pharmaceutical Grade:Ultra-low impurity thresholds meet FDA and EMA standards for active pharmaceutical ingredient synthesis. CDSCO compliance requirements in India and FDA validation protocols in the United States create premium pricing tiers above standard industrial material.
- Agricultural Grade:Intermediate purity positioning serves soil fumigation and pest control applications with balanced cost-performance profiles.
- Food Grade:Stringent contaminant limits align with FSSAI and FDA food contact substance regulations for flavor and additive manufacturing.
Industrial Grade leads volumes today; Pharmaceutical Grade is gaining share fastest.
Application:
Application maturity determines whether DMDS serves as primary chemistry or functional additive.
- Fumigant:Soil sterilization applications in high-value crop agriculture leverage DMDS volatility and broad-spectrum biocidal activity. California's Central Valley and Florida's vegetable belt concentrate demand as methyl bromide phase-out accelerates alternative fumigant adoption.
- Solvent:Organosulfur solvent properties support extraction and reaction media in specialty chemical synthesis. Pharmaceutical manufacturers in Switzerland and Germany specify DMDS for sulfur-containing heterocycle production.
- Chemical Intermediate:Precursor role in thiophane, methionine, and organosulfur polymer manufacturing. Methionine producers in China and France integrate DMDS into animal feed additive supply chains.
- Agrochemical:Active ingredient or formulation component in pesticide and fungicide products. Brazil's soybean belt and India's cotton regions drive seasonal procurement patterns.
Fumigant applications dominate current offtake; Chemical Intermediate demand is climbing the fastest.
End User:
Customer type dictates volume scale and contract structure more than technical specification.
- Agriculture:Seasonal procurement patterns align with planting cycles in temperate and tropical growing regions. Soil fumigation contractors in California, Florida, and Mediterranean Europe schedule bulk deliveries during pre-planting windows.
- Petrochemical:Continuous consumption through catalyst activation cycles and regeneration schedules. United States Gulf Coast refineries operate under long-term supply agreements with integrated chemical producers.
- Pharmaceuticals:Batch-scale purchasing with stringent documentation and audit requirements. Contract manufacturers in India and Ireland qualify suppliers through extended validation protocols.
- Food Processing:Niche flavor and additive applications with intermittent order patterns. Natural and artificial flavor houses in France and the United States specify food-grade material for garlic and onion flavor synthesis.
Petrochemical end users command the largest volumes; Pharmaceutical customers are expanding most quickly.
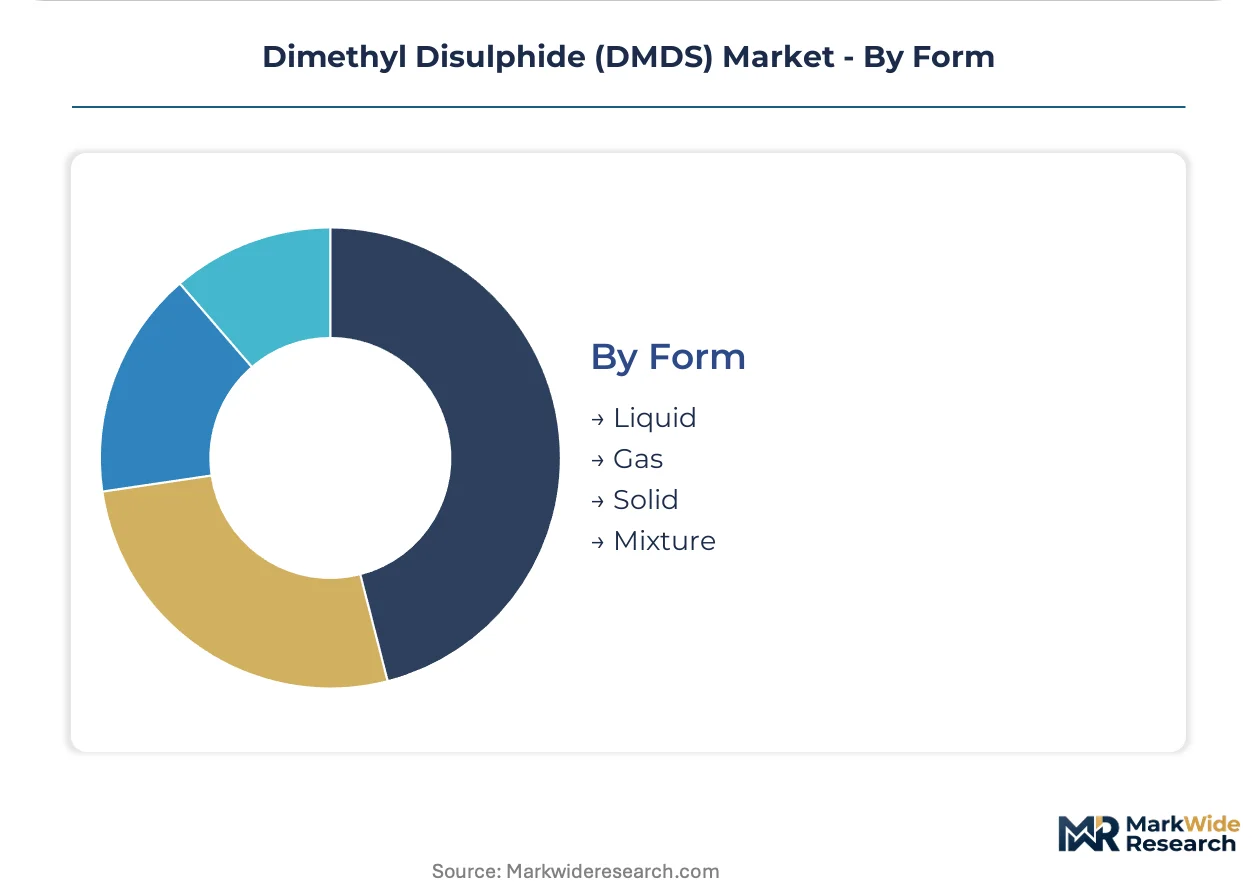
Form:
Physical state determines logistics infrastructure and safety protocol investment.
- Liquid:Standard bulk delivery via rail tank car, ISO tank container, and drum packaging. Established chemical handling infrastructure at refineries and manufacturing sites favors liquid logistics.
- Gas:Vapor-phase sulfiding applications require specialized vaporization and injection equipment. Continuous sulfiding systems at Marathon Petroleum and Phillips 66 facilities process gaseous DMDS for catalyst bed uniformity.
- Solid:Encapsulated or adsorbed formulations for controlled-release agricultural applications. Solid forms reduce handling hazards during field fumigation operations.
- Mixture:Blended formulations with carriers or stabilizers for specific application requirements. Pre-mixed sulfiding solutions simplify refinery catalyst activation procedures.
Liquid form leads volumes today; Gas-phase delivery is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting DMDS production toward jurisdictions with streamlined chemical registration frameworks. Manufacturers face divergent compliance costs across major economies.
United States
Gulf Coast refineries drive catalyst presulfiding demand as IMO marine fuel standards tighten. EPA Clean Air Act enforcement shapes emission control investments. Houston-Beaumont-Port Arthur corridor concentrates hydrodesulfurization capacity expansion.
China
Dual carbon policy targets accelerate cleaner refinery process adoption. MEE sulfur emission standards enforce stricter catalyst efficiency requirements. Shandong and Jiangsu provinces lead petrochemical complex upgrades with integrated sulfiding agent supply chains.
Germany
REACH authorization procedures concentrate European DMDS manufacturing among registered producers. ECHA extended toxicological data requirements raise compliance barriers. Ludwigshafen chemical cluster maintains specialized organosulfur compound production infrastructure.
India
Reliance Industries and Indian Oil Corporation expand hydrocracking capacity. CDSCO pharmaceutical-grade certification creates premium import requirements. Gujarat and Maharashtra refinery corridors attract sulfiding agent distributors.
Saudi Arabia
SABIC and domestic refiners process heavier crudes requiring intensive hydrotreating. The country's national environmental regulator enforces sulfur recovery standards. Jubail Industrial City anchors catalyst chemical demand in the Gulf region.
Dimethyl Disulphide (DMDS) Market Competitive Environment
Capacity expansion dominates the current landscape as integrated petrochemical producers extend sulfiding agent output. The market exhibits moderate consolidation with European and North American incumbents controlling registered production volumes. Two archetypes prevail: diversified chemical conglomerates with captive methanol feedstock, and specialty organosulfur compound houses serving pharmaceutical certification tiers. Geographic expansion into Asian refining corridors and backward integration into methanol supply represent the primary competitive vectors.
Among diversified chemical conglomerates, Arkema S.A. and BASF SE occupy positions anchored by European manufacturing footprints and REACH compliance infrastructure. Chevron Phillips Chemical Company exemplifies the integrated petrochemical archetype with Gulf Coast supply chain proximity to major refinery demand. These three represent distinct strategic postures: European regulatory compliance leadership, North American feedstock integration, and specialty-grade certification capability.
| Leading Market Players |
|---|
| Arkema S.A. |
| Chevron Phillips Chemical Company |
| Toray Fine Chemicals Co., Ltd. |
| BASF SE |
| Gaylord Chemical Company, LLC |
| Eastman Chemical Company |
| Huntsman Corporation |
| Mitsubishi Gas Chemical Company, Inc. |
| Solvay S.A. |
| Others |
Value Chain & Pricing Dynamics
Continuous sulfiding system adoption at Marathon Petroleum and Phillips 66 facilities is compressing catalyst activation windows while simultaneously concentrating procurement power among integrated operators with captive methanol supply, reshaping both unit economics and supplier margin structures across industrial-grade DMDS tiers.
Pricing Analysis
Distributor margins on pharmaceutical-grade certification absorb the widest spreads, while direct-to-refinery contracts for industrial-grade material trade at volume-discounted terms. Price differentiation separates FDA-validated pharmaceutical tiers from process-tolerant refinery grades, with methanol feedstock volatility exerting downward pressure on industrial margins. Spot-market buyers in agricultural fumigation show highest price sensitivity; Gulf Coast petrochemical operators under long-term offtake agreements demonstrate lowest.
Supply Chain Analysis
Direct-to-refinery channels handle continuous sulfiding demand from integrated operators like Chevron Phillips Chemical, while specialty distributors serve pharmaceutical and agricultural segments. Manufacturing concentrates in the United States, France, and China, with methanol-thiolation chemistry drawing from natural gas and coal-derived methanol feedstocks. Single-source vulnerability around Arkema's European REACH-registered capacity creates structural risk. Distribution runs through rail tank car and ISO tank container networks anchored to Gulf Coast petrochemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance cost escalation in Europe against streamlined environmental registration pathways in China creates a geographic-arbitrage opening for capacity relocation and supply contract restructuring.
For Market Incumbents: To counter alternative sulfiding agent substitution by carbon disulfide and dimethyl sulfide, Arkema and BASF should deepen backward integration into methanol supply while securing pharmaceutical-grade certification premiums. Capacity addition in Shandong and Jiangsu provinces addresses China's dual carbon enforcement without European regulatory drag. For New Entrants and Emerging Players: Capture India's refinery capacity expansion at Reliance Industries and Indian Oil Corporation installations, where CDSCO pharmaceutical-grade import requirements create premium positioning unavailable to unregistered suppliers. Modular refinery deployment for stranded gas processing offers a portable-sulfiding go-to-market angle with limited incumbent presence. For Investors and Strategic Acquirers: Valuations sit cheapest among specialty organosulfur compound houses without captive methanol infrastructure, as methanol price volatility compresses standalone margins. Long-term viability hinges on pharmaceutical-grade certification capability and Asian refinery corridor proximity. Watch IMO marine fuel sulfur cap enforcement stringency as the demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methanol Supply | Chevron Phillips Chemical's captive feedstock anchors margin defense against natural gas price swings. |
| Pharmaceutical-Grade Certification Investment | FDA and EMA validation unlocks premium pricing tiers in active pharmaceutical ingredient manufacturing. |
| Long-term Supply Agreement with Refinery Operators | Master service agreements at Marathon Petroleum facilities displace spot market volatility. |
| Joint Venture in Shandong Province | China's MEE sulfur emission standards create localized catalyst chemical demand with regulatory tailwinds. |
| Green Manufacturing Transition | Dual carbon policy alignment in Jiangsu province attracts state-backed petrochemical complex upgrades. |
Study Parameters
Multiple input streams — refinery operations executives, specialty chemical procurement leads, pharmaceutical manufacturing directors, and agricultural fumigation contractors — were reconciled against customs trade data, SEC 10-K filings, ACC petrochemical reports, and ECHA registration dossiers. Bottom-up volume estimates from catalyst consumption rates and top-down market sizing from methanol-thiolation capacity were cross-validated.
Data-stream reconciliation applied grade tier, end-use industry, and regional production hub segmentation across the projection horizon. CAGRs were derived from hydrodesulfurization capacity expansion pipelines and marine fuel sulfur regulation enforcement timelines. Catalyst bed sulfidation intensity per barrel of heavy crude processed served as a primary demand-side input.
Feedstock price volatility, REACH authorization timeline delays, and next-generation catalyst activation chemistry are the dominant revision risks to modeled outputs. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Europe Caustic Potash Market
Bulk Chemicals
Ammonium Thiosulfate Market
Bulk Chemicals
2-Ethylhexanoyl Chloride Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Sodium Hypophosphite Market
Bulk Chemicals
India Chlorine Market
Bulk Chemicals
Global Naphthalene Derivatives Market
Bulk Chemicals
Global Internal Olefins Market
Bulk Chemicals
Ammonium Nitrate Market
Bulk Chemicals
Brassylic Acid Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
Copper (II) Carbonate Basic Market
Bulk Chemicals
Carbonate Market
Bulk Chemicals
Sodium Metasilicate Pentahydrate Market
Bulk Chemicals
Terephthaloyl Chloride (TPC) Market
Bulk Chemicals
Europe Lime Market