
 Caprolactam Market | 2026-2036
Caprolactam Market Size, Share, and Industry Trends Forecast 2026-2036
Caprolactam Market Analysis
Direct supply contracts between caprolactam producers and nylon polymerization facilities is reconfiguring how volume flows through the value chain. BASF SE leverages its integrated Ludwigshafen complex to sustain captive consumption and merchant sales simultaneously. China Petroleum & Chemical Corporation anchors the Asia-Pacific supply base through its massive Shandong and Zhejiang operations. Advansix controls a fully integrated US Gulf Coast chain from phenol feedstock through nylon resin.
Caprolactam is a cyclic amide with the formula (CH₂)₅CONH, produced primarily via the Beckmann rearrangement of cyclohexanone oxime or through toluene-based routes, serving as the essential monomer for nylon-6 polymerization across fiber and engineering resin applications. Nylon production dominates application demand by volume, while engineering plastics captures the most attractive margin pool as automotive and electronics buyers specify higher-performance grades. Caprolactam crystals lead product type shipments for fiber applications, whereas liquid forms gain traction in continuous polymerization systems serving film and industrial yarn segments.
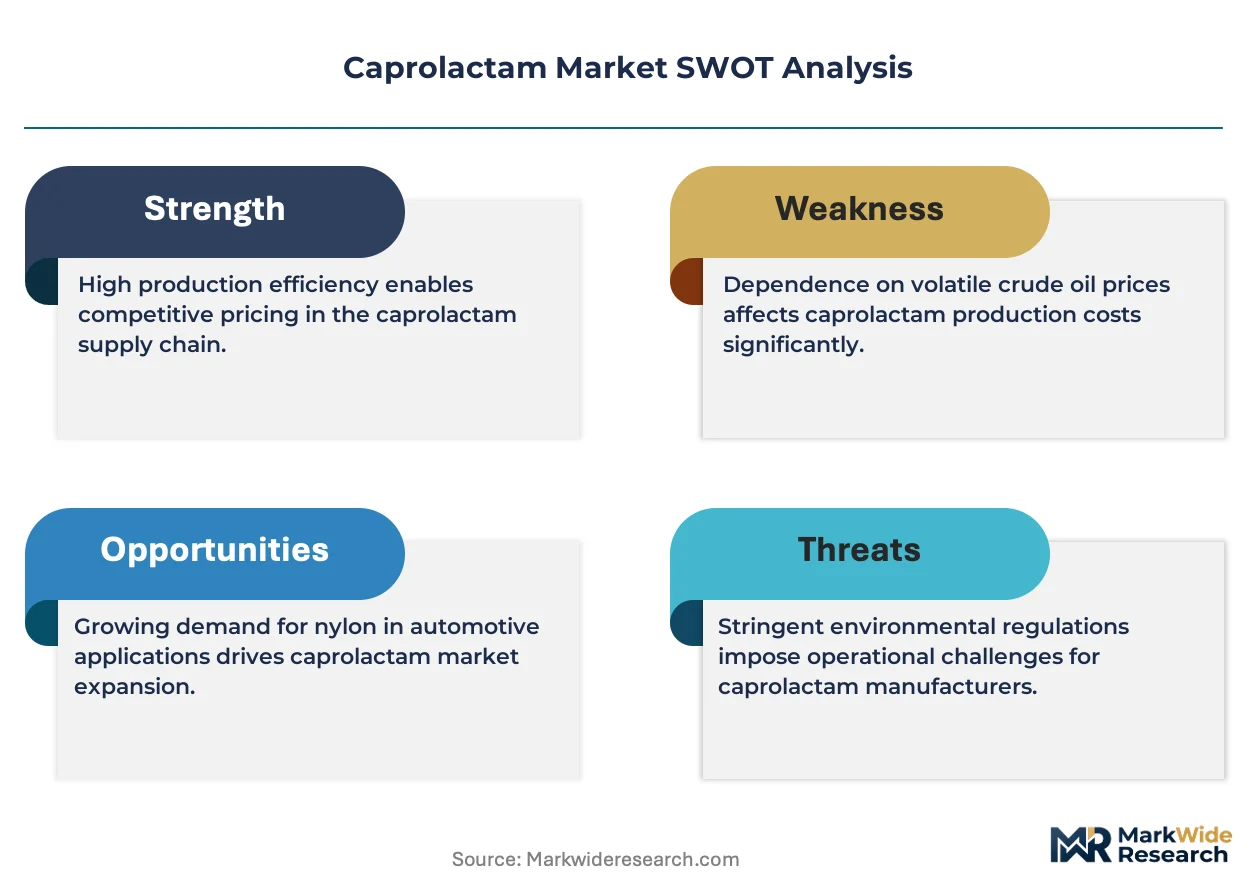
REACH registration requirements in Europe and China's MEE emissions enforcement are elevating capital costs for producers using conventional cyclohexane oxidation routes, advantaging firms with phenol-based or bio-feedstock pathways. The EPA's National Emission Standards for Hazardous Air Pollutants in the US imposes strict benzene and cyclohexane controls on caprolactam manufacturing units. Stakeholders must monitor which regulatory jurisdiction tightens first, as compliance timing will determine competitive repositioning across integrated and merchant supply models.
Market Dynamics
China's dual carbon goals and REACH compliance in Europe are forcing producers to abandon conventional cyclohexane oxidation routes, advantaging phenol-based and bio-feedstock pathways while reshaping capital allocation across integrated and merchant supply models.
Growth Catalysts
- Automotive lightweighting mandates:Fuel efficiency targets in the EU and US are accelerating nylon-6 substitution for metal components in under-the-hood and structural applications.
- MEE emissions enforcement:China's Ministry of Ecology and Environment is shuttering antiquated caprolactam capacity, tightening regional supply and lifting operating rates for compliant producers.
- Continuous polymerization systems:Liquid caprolactam grades are displacing crystalline forms in film and industrial yarn lines, reducing energy intensity in downstream processing.
Market Restraints
- Benzene feedstock volatility:Crude-linked cyclohexane pricing transmits directly to caprolactam cost curves, compressing margins for non-integrated producers during upstream spikes.
- Shandong-Zhejiang supply concentration:Over half of global capacity sits within 500 kilometers in eastern China, exposing buyers to single-region weather, logistics, and policy disruptions.
- Polyamide 66 substitution:Engineering plastics buyers in automotive and electronics can switch to PA66 where heat performance requirements permit, capping nylon-6 pricing power.
Strategic Opportunities
- Bio-based feedstock pathways:Fermentation-derived caprolactam from renewable sugars is approaching pilot scale, offering premium positioning for EU and US brands facing Scope 3 pressure.
- India's PLI scheme for textiles:Production-linked incentives for technical textiles are attracting polymerization investments that will require merchant caprolactam supply.
- Direct-to-polymer contracts:Bypassing traditional distributor layers through long-term offtake agreements with nylon fiber and resin producers is capturing margin previously lost to intermediaries.
Industry Challenges
- Beckmann rearrangement expertise scarcity:The specialized chemical engineering talent required to operate and optimize cyclohexanone oxime conversion is concentrated among a shrinking cohort of veterans.
- Legacy ammonia plant integration:Retrofitting older facilities to meet MEE and EPA National Emission Standards for Hazardous Air Pollutants requirements demands capital outlays that strain mid-scale balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Caprolactam Market |
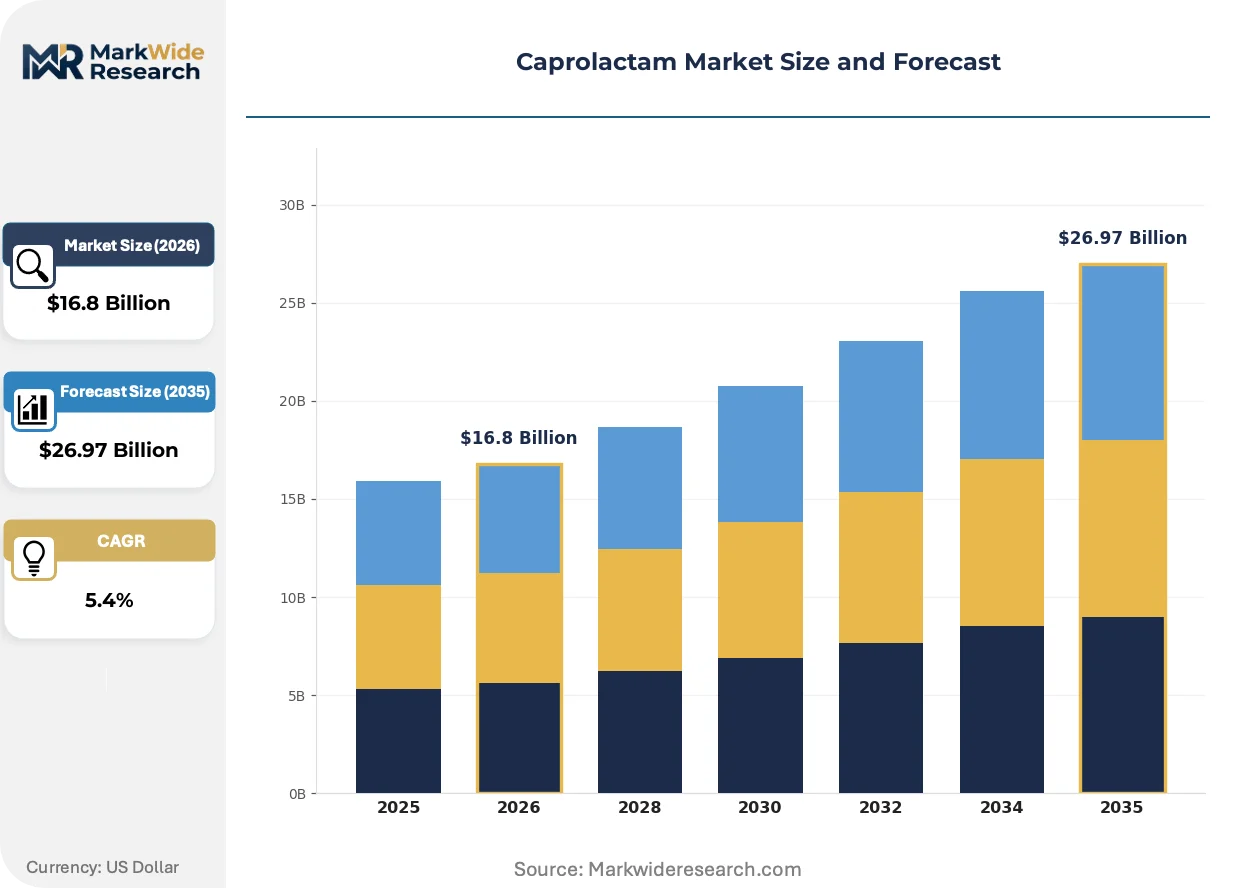
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $26.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caprolactam Crystals, Caprolactam Liquid, Caprolactam Granules, Caprolactam Powder Application: Nylon Production, Textile Manufacturing, Coatings, Engineering Plastics End User: Automotive Sector, Consumer Goods, Electronics, Aerospace Distribution Channel: Direct Sales, Online Distributors, Specialty Stores, Wholesalers |
| Companies Covered | BASF SE, China Petroleum & Chemical Corporation, Honeywell International Inc., LANXESS, UBE Corporation, DSM, Toray Industries, Sumitomo Chemical Company Limited, Advansix, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Caprolactam Market Emerging Trajectories
Process intensification and feedstock diversification are compressing the viable technology set, while regulatory differentiation between geographies is fragmenting competitive strategy rather than harmonizing it.
Enzymatic caprolactam synthesis from renewable feedstocks is rendering obsolete energy-intensive Beckmann rearrangement routes for specialty grades. European automotive suppliers and Japanese fiber producers are piloting bio-based certificates at 15-20% price premiums. This pathway is rendering obsolete the carbon intensity advantage that phenol-based producers held over cyclohexane oxidation rivals.
REACH registration requirements and China's dual carbon goals are elevating capital costs for conventional producers while exempting bio-routes from carbon border adjustments. The EU's Carbon Border Adjustment Mechanism will layer import costs on Middle Eastern and Asian shipments from 2026. Engineering resin compounders in Germany and France are qualifying alternative suppliers ahead of compliance deadlines.
Automotive Tier-1s are consolidating resin procurement through central casting contracts rather than plant-level spot buying. This concentration is disintermediating regional distributors and favoring producers with certified quality management systems and continent-spanning logistics networks. The shift is most pronounced in Germany and the US Southeast where nylon-6 consumption clusters around transmission and engine component manufacturing.
Caprolactam Market Segmentation
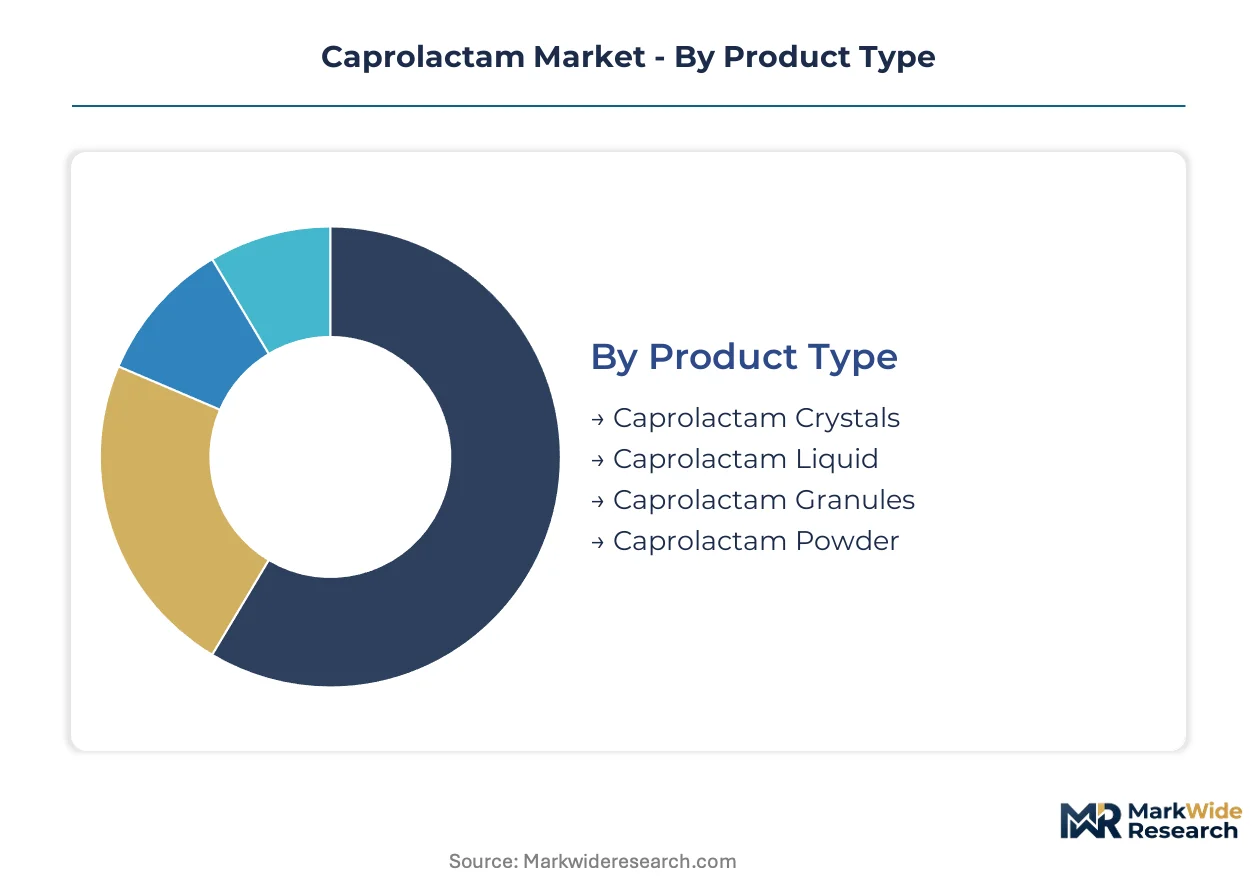
Segmentation in the caprolactam market reveals how product form, application intensity, and channel economics create distinct margin pools. Buyers prioritize specification purity for fiber spinning versus handling efficiency for continuous polymerization, while regulatory pressure on Scope 3 emissions is fragmenting end-user procurement criteria.
Product Type:
Use-case spectrum spans batch polymerization requiring solid-phase handling through to automated liquid injection systems serving high-throughput film lines.
- Caprolactam Crystals:Solid-phase material with specified melting point range serves conventional batch polymerization in fiber-grade nylon production. Textile manufacturers in Shandong and Zhejiang provinces specify crystalline forms for compatibility with legacy spinning equipment.
- Caprolactam Liquid:Molten monomer delivered in heated tank trucks eliminates solidification energy costs in downstream processing. Automotive resin compounders in Germany and the US Southeast are migrating to liquid delivery to support continuous polymerization systems.
- Caprolactam Granules:Pelletized solid offers intermediate handling characteristics for mid-scale polymerization facilities lacking liquid storage infrastructure.
- Caprolactam Powder:Fine particulate grade addresses specialty coating applications requiring rapid dissolution kinetics.
The dominant share belongs to Caprolactam Crystals, while Caprolactam Liquid is closing the gap fastest.
Application:
Cost tier differentiation separates commodity fiber volumes from engineering resin premiums, with coating applications occupying a narrow specialty niche.
- Nylon Production:Polymerization into nylon-6 fiber and resin accounts for the overwhelming majority of monomer offtake. Caprolactam specification for textile-grade polymerization tolerates higher impurity levels than engineering resin grades, creating a two-tier pricing structure.
- Engineering Plastics:High-viscosity nylon-6 compounds for under-the-hood automotive components command the most attractive margin pool. Heat-stabilized grades for transmission and engine bay applications in EU and US manufacturing clusters require certified low-oligomer caprolactam feedstock.
- Textile Manufacturing:Direct fiber spinning bypasses discrete polymer chip production, concentrating demand in integrated chemical-textile complexes.
- Coatings:Solvent-borne and powder coating formulations utilize caprolactam as a reactive diluent and corrosion inhibitor in marine and industrial protective applications.
Nylon Production retains volume leadership, though Engineering Plastics delivers the steepest expansion trajectory as lightweighting mandates intensify.
End User:
Customer type fragmentation reflects divergent technical requirements, with automotive procurement centralization contrasting against electronics spot-buying patterns.
- Automotive Sector:Tier-1 resin compounders specify heat-stabilized and glass-filled nylon-6 grades for powertrain and structural components. Central casting contracts from German and US Southeast manufacturing clusters are consolidating supplier relationships around certified quality management systems.
- Electronics:Connector and housing manufacturers demand flame-retardant nylon-6 compounds with precise dimensional stability for surface-mount assembly processes.
- Consumer Goods:Appliance and sporting equipment producers utilize standard-grade nylon-6 for cost-sensitive applications with moderate thermal and mechanical requirements.
- Aerospace:Interior component manufacturers specify certified low-fume emission grades meeting FAA and EASA fire-smoke-toxicity standards.
Automotive Sector holds the dominant procurement position, while Electronics is expanding most quickly on connector miniaturization trends.
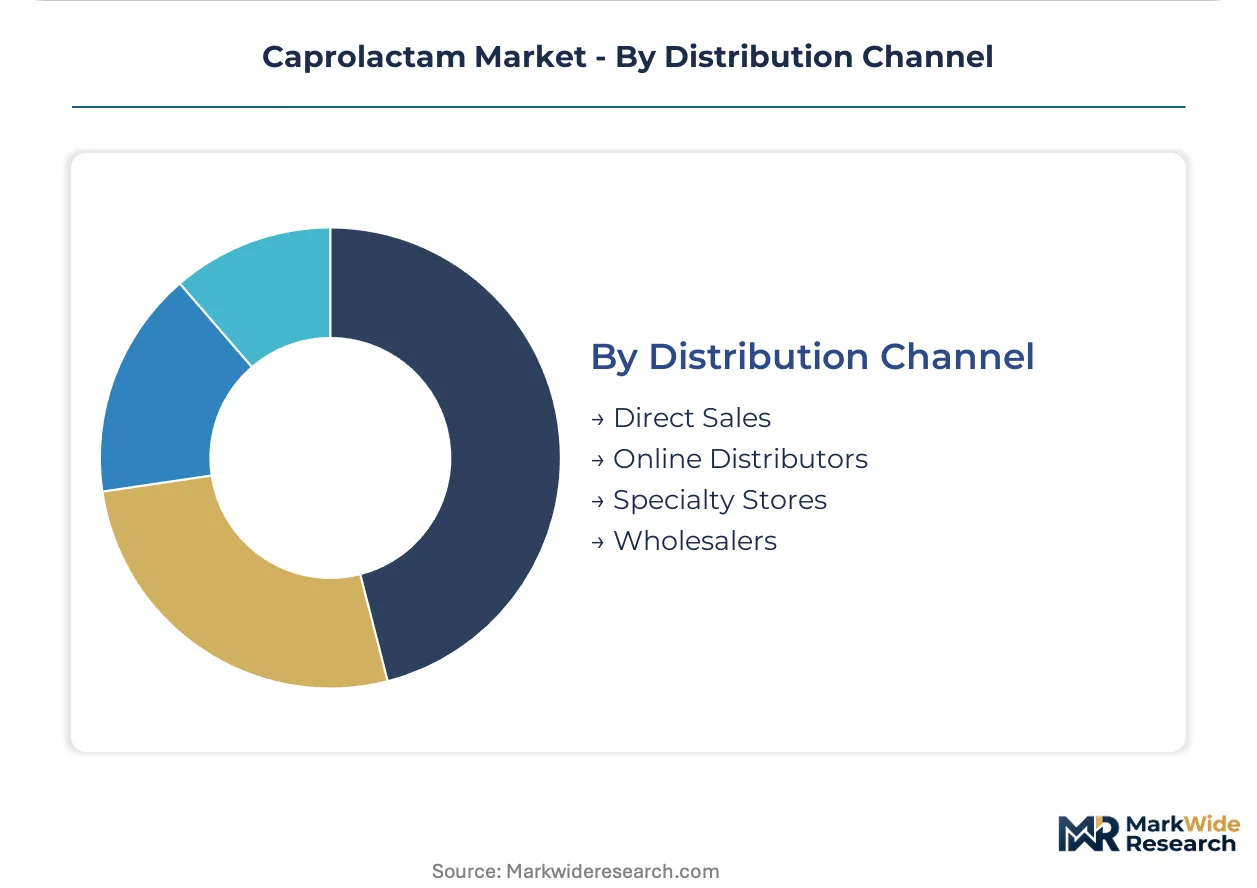
Distribution Channel:
Supply concentration in eastern China is compressing logistics economics for traditional wholesaler networks while favoring direct producer relationships.
- Direct Sales:Long-term offtake agreements between caprolactam producers and nylon polymerization facilities eliminate distributor margins. BASF's Ludwigshafen complex and Sinopec's Shandong operations leverage captive integration and merchant direct sales simultaneously.
- Wholesalers:Regional distributors serve fragmented textile processors lacking volume scale for direct contracting, though their role is eroding as procurement centralizes.
- Online Distributors:Digital platforms are emerging for spot purchases and specialty grade sourcing in fragmented end-user segments.
- Specialty Stores:Niche channels serve laboratory and pilot-scale buyers requiring packaged quantities with certificate of analysis documentation.
Direct Sales commands the dominant volume flow, while Online Distributors are gaining share fastest among small and mid-scale processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement in China is shuttering antiquated capacity and lifting operating rates for compliant producers across the Shandong-Zhejiang corridor. Regional regulatory divergence is fragmenting competitive strategy rather than harmonizing it.
China
Automotive lightweighting mandates and technical textile expansion drive monomer consumption in the Yangtze River Delta. MEE emissions standards are forcing cyclohexane oxidation closures while phenol-based and bio-feedstock routes gain capital allocation priority. Sinopec's Shandong and Zhejiang operations anchor the majority of global manufacturing capacity within a 500-kilometer radius.
Germany
Engineering resin compounders in Bavaria and North Rhine-Westphalia specify heat-stabilized nylon-6 grades for powertrain components. REACH registration requirements and the EU Carbon Border Adjustment Mechanism elevate compliance costs for conventional imports. BASF's Ludwigshafen complex sustains captive consumption and merchant sales through integrated phenol-to-resin operations.
United States
Automotive Tier-1s in the Southeast and Midwest are consolidating resin procurement through central casting contracts. EPA National Emission Standards for Hazardous Air Pollutants impose strict benzene and cyclohexane controls on manufacturing units. Advansix controls a fully integrated Gulf Coast chain from phenol feedstock through nylon resin.
India
Production-linked incentives for technical textiles under the PLI scheme are attracting polymerization investments requiring merchant caprolactam supply. BIS certification requirements are tightening specification standards for imported monomer grades. Gujarat and Maharashtra industrial corridors are emerging as downstream nylon fiber manufacturing clusters.
Japan
Connector miniaturization trends in electronics and high-performance fiber applications sustain specialty grade demand. METI industrial standards and corporate Scope 3 pressure are accelerating bio-based certificate pilot programs. Toray Industries and UBE Corporation anchor domestic supply through integrated chemical complexes in the Kansai and Chubu regions.
Caprolactam Market Vendor Landscape
Vertically integrated petrochemical conglomerates and specialty chemical specialists split the market into distinct capability tiers. The structure favors producers with captive feedstock positions and certified quality management systems. Three archetypes dominate: integrated oil majors with phenol-to-resin chains, Asian state-affiliated producers with massive scale advantages, and regional specialists with technical service depth. Capacity rationalization and direct-to-polymer contracting represent the dominant competitive moves reshaping margin capture.
Among European-based integrated producers, BASF SE and LANXESS exemplify the petrochemical conglomerate archetype with complex-level integration and merchant market presence. DSM occupies a position within the specialty tier, representing the transition toward bio-based feedstock pathways and premium positioning for Scope 3-conscious buyers. These anchors illustrate how regulatory differentiation between geographies is fragmenting competitive strategy rather than standardizing it.
| Leading Market Players |
|---|
| BASF SE |
| China Petroleum & Chemical Corporation |
| Honeywell International Inc. |
| LANXESS |
| UBE Corporation |
| DSM |
| Toray Industries |
| Sumitomo Chemical Company Limited |
| Advansix |
| Others |
Supply Flow & Price Mechanics
Shandong-Zhejiang corridor capacity dynamics translate directly into downstream pricing power for compliant producers as MEE enforcement shutters antiquated cyclohexane oxidation units. Phenol-based and bio-feedstock routes command premium positioning against conventional imports facing carbon border adjustments.
Pricing Analysis
East Asian liquid caprolactam grades trade at persistent discounts to European crystalline forms due to freight differentials and specification purity gaps. Contract-based long-term offtake agreements dominate volume flows, with price differentiation anchored in certification grade and vertical integration depth. Cost compression in textile-grade tiers is intensifying because Shandong-Zhejiang supply concentration exposes buyers to single-region logistics disruptions. Automotive resin compounders exhibit lowest price sensitivity, while fragmented textile processors in India and Southeast Asia absorb margin pressure fastest.
Supply Chain Analysis
Export-control regimes on advanced Beckmann rearrangement catalysts limit technology transfer to emerging producers, preserving incumbent process expertise advantages. China, Germany, and the United States anchor global manufacturing, with raw material dependencies centering on benzene, phenol, and ammonia feedstocks. Single-source vulnerability concentrates in the 500-kilometer Shandong-Zhejiang radius where weather and policy disruptions propagate rapidly. Distribution runs through direct producer-to-polymer contracts that disintermediate traditional wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Caprolactam incumbents must navigate polyamide 66 substitution threats in automotive heat-performance applications where buyers can switch polymer grades. Defending market position requires building moats around process expertise and regulatory compliance rather than commodity scale alone.
For Market Incumbents: Build certification moats around REACH registration and MEE compliance that bio-feedstock routes already satisfy. Secure backward integration into phenol feedstock to insulate margins from benzene volatility. Capture channel control through direct-to-polymer contracts that lock in automotive Tier-1 resin compounders before PA66 substitution accelerates. For New Entrants and Emerging Players: Establish a beachhead in India's technical textiles segment where PLI scheme investments create merchant caprolactam demand without incumbent supply relationships. Target bio-based certificate positioning for EU and Japanese buyers facing Scope 3 pressure. Lead with fermentation-derived feedstock pathways that bypass Beckmann rearrangement expertise barriers entirely. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive phenol-to-resin chains and long-term automotive offtake agreements. Five-to-ten year viability favors firms with demonstrated MEE compliance and liquid-grade delivery infrastructure. Watch bio-based pilot scale achievements as the inflection signal for premium pricing acceptance.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Feedstock | Advansix and BASF Ludwigshafen operations demonstrate margin insulation from crude-linked benzene spikes. |
| Green Manufacturing Transition | Fermentation-derived caprolactam from renewable sugars captures EU Carbon Border Adjustment Mechanism exemptions. |
| Long-term Supply Agreement | Direct contracts with automotive Tier-1s in Germany and US Southeast consolidate procurement around certified quality systems. |
| Capacity Expansion | Sinopec Shandong-Zhejiang additions must demonstrate MEE compliance to avoid stranded asset risk. |
| Joint Venture | India's PLI scheme attracts polymerization investments requiring merchant caprolactam partnerships with Gujarat-Maharashtra clusters. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade data, ACC and Cefic industry reports, SEC 10-K filings, and MEE enforcement disclosures. Plant managers, procurement leads at nylon polymerization facilities, distribution channel partners, and technical R&D directors provided operational perspective. Bottom-up capacity and utilization estimates triangulated against top-down consumption models derived from automotive production and textile fiber databases.
Forecast inputs span grade tier, end-use industry, packaging format, and regional production hub segmentation across the analysis window. CAGRs were derived from elasticity modeling against automotive lightweighting mandates and MEE capacity closure schedules. Continuous polymerization adoption rates and bio-feedstock pathway commercialization timelines informed scenario boundaries.
Stress conditions across benzene price volatility, MEE enforcement intensity, and PA66 substitution elasticity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory compliance timing and feedstock route economics. Material shifts in EU Carbon Border Adjustment Mechanism implementation or breakthrough bio-based scale achievements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Mexico Caustic Soda Market
Bulk Chemicals
Acetyl Tributyl Citrate Market
Bulk Chemicals
Vacuum Salts Market
Bulk Chemicals
Soda Ash Market
Bulk Chemicals
Isophorone Market
Bulk Chemicals
Zinc Gluconate Granules Market
Bulk Chemicals
Chlorotoluenes Market
Bulk Chemicals
Picric Acid Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Atrazine Market
Bulk Chemicals
Triazine Market
Bulk Chemicals
Potassium Cryolite Market
Bulk Chemicals
Aluminum Chloride Hexahydrate Market
Bulk Chemicals
Rubidium Bromide Market
Bulk Chemicals
Magnesium Citrate Market