
 LAMEA Glacial Acrylic Acid Market | 2026-2036
LAMEA Glacial Acrylic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Glacial Acrylic Acid Market Insights
The capital-intensity divergence between integrated petrochemical complexes and standalone refiners is bifurcating competitive dynamics across the LAMEA region. BASF SE leverages its integrated Ludwigshafen-derived process know-how through its PETRONAS joint venture in Malaysia. Sasol anchors its position via coal-to-chemicals backward integration at Secunda, yielding captive acrylic acid feedstock. Dow Inc competes through Gulf Coast technology transfer to its regional operations.
Glacial acrylic acid is a purified form of acrylic acid containing less than 0.3% water, produced via two-stage crystallization or melt crystallization of crude acrylic acid, serving primarily as a monomer precursor for superabsorbent polymers and acrylate esters. Industrial grade product dominates volume flows into paints and adhesives manufacturing across the LAMEA construction sector. Pharmaceutical grade commands premium positioning amid tightening healthcare procurement standards. Direct sales channels control bulk transactions to automotive coatings producers, while distributor networks manage fragmented textile mill demand.
South Africa's Department of Trade, Industry and Competition enforces BIS-aligned chemical import standards, while Saudi Arabia's SASO mandates conformity assessment for acrylic acid derivatives entering construction supply chains. Brazil's ANVISA pharmaceutical-grade registration requirements create market access barriers for non-compliant suppliers. Stakeholders must monitor evolving national chemical inventories and alignment with OECD test guidelines to sustain cross-border product registration validity.
Market Dynamics
Capital-intensity divergence between integrated petrochemical complexes and standalone refiners is bifurcating competitive dynamics across the LAMEA region, with backward integration becoming the decisive margin defense mechanism for volume players.
Growth Catalysts
- Water treatment polymer demand:Municipal and industrial wastewater infrastructure expansion in the Middle East is accelerating superabsorbent polymer consumption for flocculation and sludge dewatering applications.
- REACH-aligned chemical safety protocols:South Africa's adoption of European-equivalent registration standards is formalizing product specifications and creating compliance-based demand for pharmaceutical-grade glacial acrylic acid.
- Jubail Industrial City concentration:Saudi Arabia's petrochemical corridor integration is enabling captive feedstock access and reducing logistics costs for acrylate ester producers serving regional coatings manufacturers.
Market Restraints
- Propylene feedstock volatility:Crude oil price swings transmit directly to naphtha-cracker economics, compressing margins for non-integrated acrylic acid producers lacking captive olefin supply.
- Import dependency concentration:Standalone refiners in Brazil and Argentina remain exposed to Asian and US Gulf Coast supply disruptions, with limited regional buffer stock capacity.
- Biobased acrylic acid substitution:Fermentation-derived 3-hydroxypropionic acid routes are achieving pilot-scale viability for superabsorbent polymer feedstock, threatening fossil-based volume growth.
Strategic Opportunities
- Underpenetrated Nigerian market:West Africa's paints and coatings sector lacks localized glacial acrylic acid production, creating first-mover advantage for distributors establishing blending facilities in Lagos.
- Construction chemical certification mandates:SASO conformity assessment requirements for acrylic acid derivatives are generating premium positioning for pre-certified suppliers in Saudi building supply chains.
- Melt crystallization technology convergence:Integration of dynamic crystallization control with membrane pervaporation is reducing energy intensity for high-purity glacial acrylic acid production below conventional two-stage methods.
Industry Challenges
- Process control specialist scarcity:Crystallization operations engineering expertise concentrates in European and East Asian technical institutes, complicating staffing for new LAMEA production assets.
- ANVISA registration timeline compression:Brazil's pharmaceutical-grade chemical approval cycles extend 18-24 months, delaying market entry for specialty-grade suppliers targeting healthcare procurement channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Glacial Acrylic Acid Market |
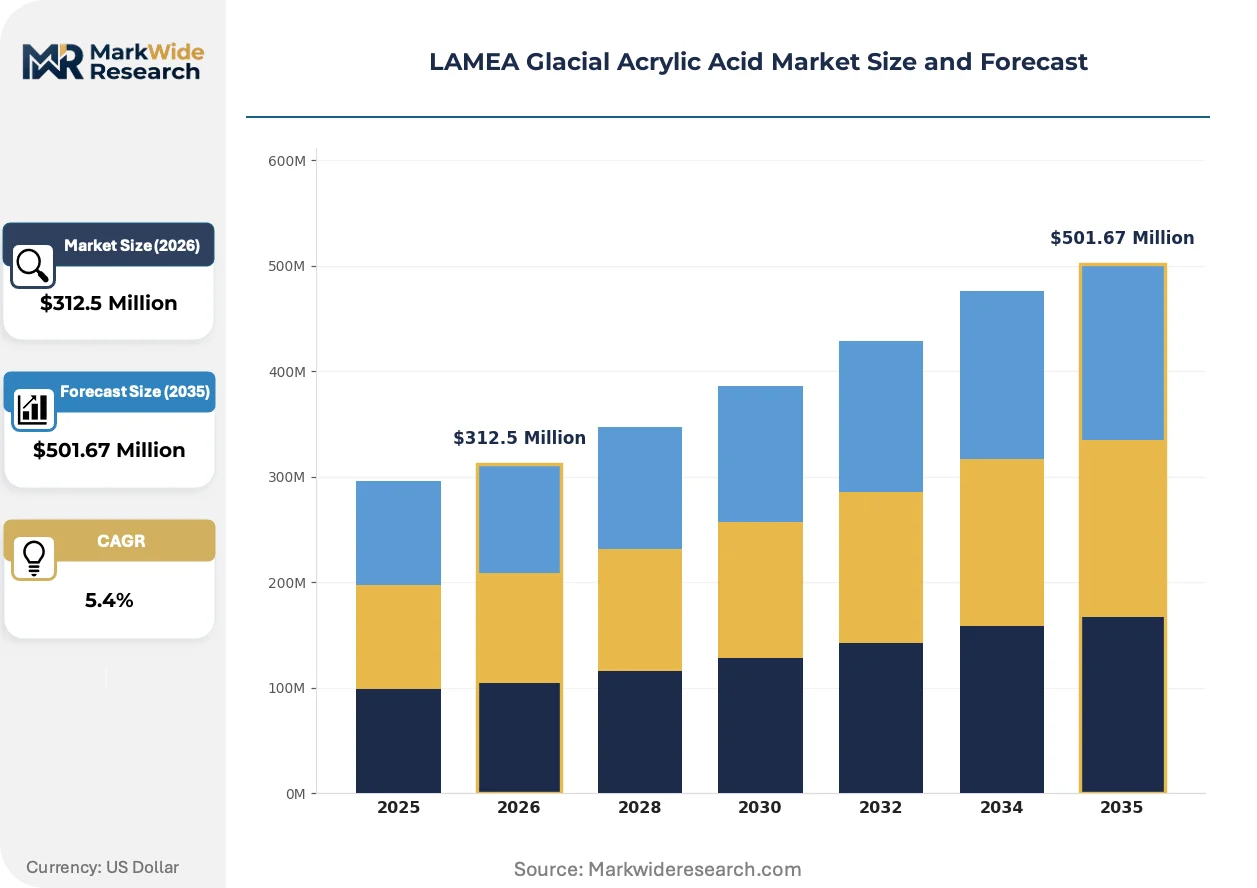
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $501.67 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Cosmetic Grade, Food Grade, Pharmaceutical Grade Application: Paints, Adhesives, Coatings, Textiles End User: Construction, Automotive, Consumer Goods, Healthcare Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | BASF SE, Dow Inc, Sasol, Nippon Shokubai Co Ltd, Mitsubishi Chemical Holdings Corporation, Tasnee, Arkema, Formosa Plastics Corporation, BASF PETRONAS Chemicals Sdn. Bhd., Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Glacial Acrylic Acid Market Trends and Innovations
Melt crystallization process intensification is compressing energy requirements and purity thresholds simultaneously, while regulatory alignment pressures and buyer consolidation are restructuring commercial relationships across the value chain.
Advanced dynamic crystallization control systems are miniaturizing. Superabsorbent polymer producers in the Middle East are adopting these compact purification units to achieve pharmaceutical-grade specifications without dedicated standalone facilities. This technology is miniaturizing the capital barrier between industrial-grade and high-purity production, enabling mid-scale players to contest premium segments previously reserved for integrated majors.
South Africa's Department of Trade, Industry and Competition enforces BIS-aligned chemical import standards that mirror Indian technical specifications. Industrial-grade glacial acrylic acid shipments now require pre-shipment testing and certificate of conformity documentation. Paints and adhesives manufacturers in Johannesburg and Durban are consolidating supplier bases to reduce compliance administration burden, favoring distributors with established certification management capabilities.
Buyer concentration among automotive coatings producers is compressing contract negotiation cycles. Direct sales channels serving OEM-tier suppliers in Morocco and Egypt are displacing traditional distributor relationships for volume transactions above 500 metric tons annually. This consolidation is most visible in the Maghreb region, where Renault-Nissan and Stellantis supplier qualification programs are mandating single-source glacial acrylic acid procurement to simplify supply chain audit trails.
LAMEA Glacial Acrylic Acid Market Segmentation
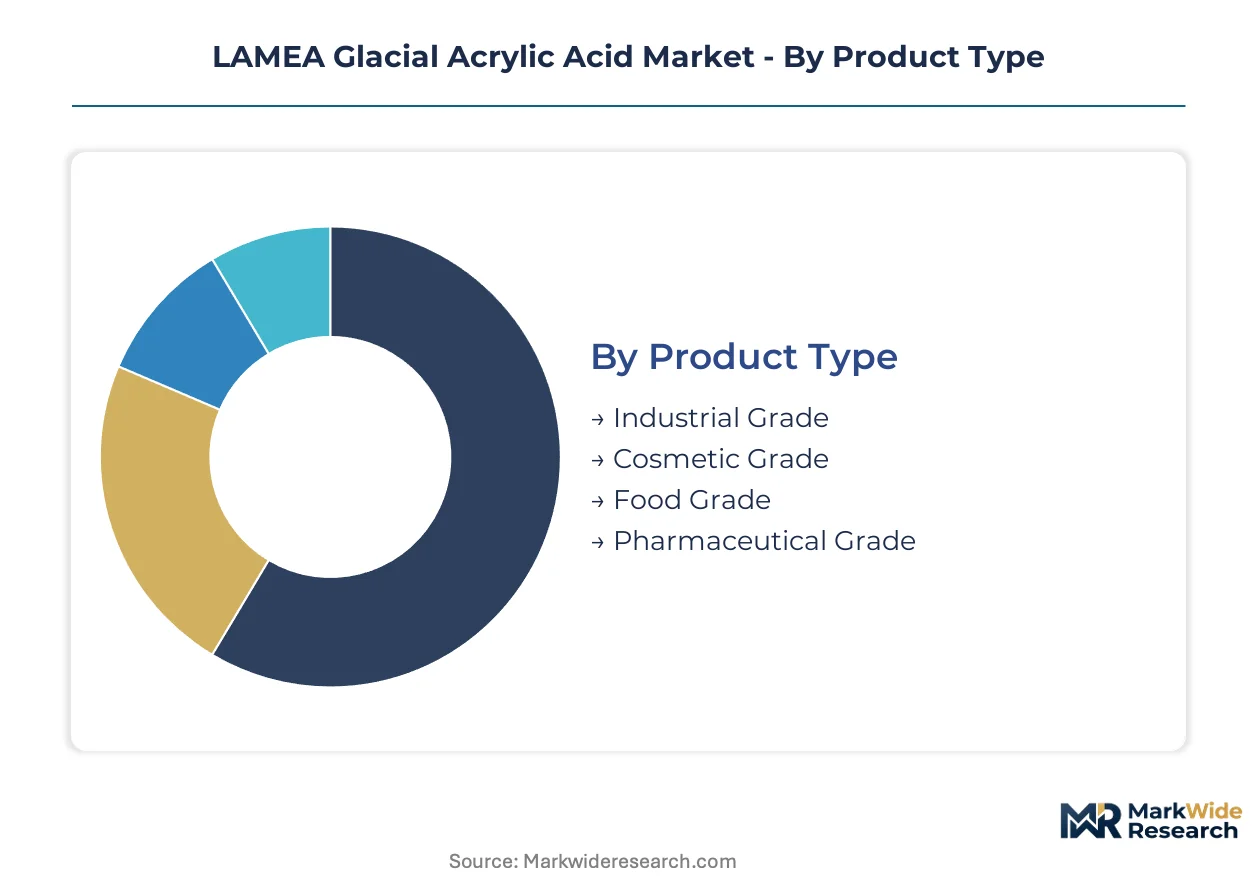
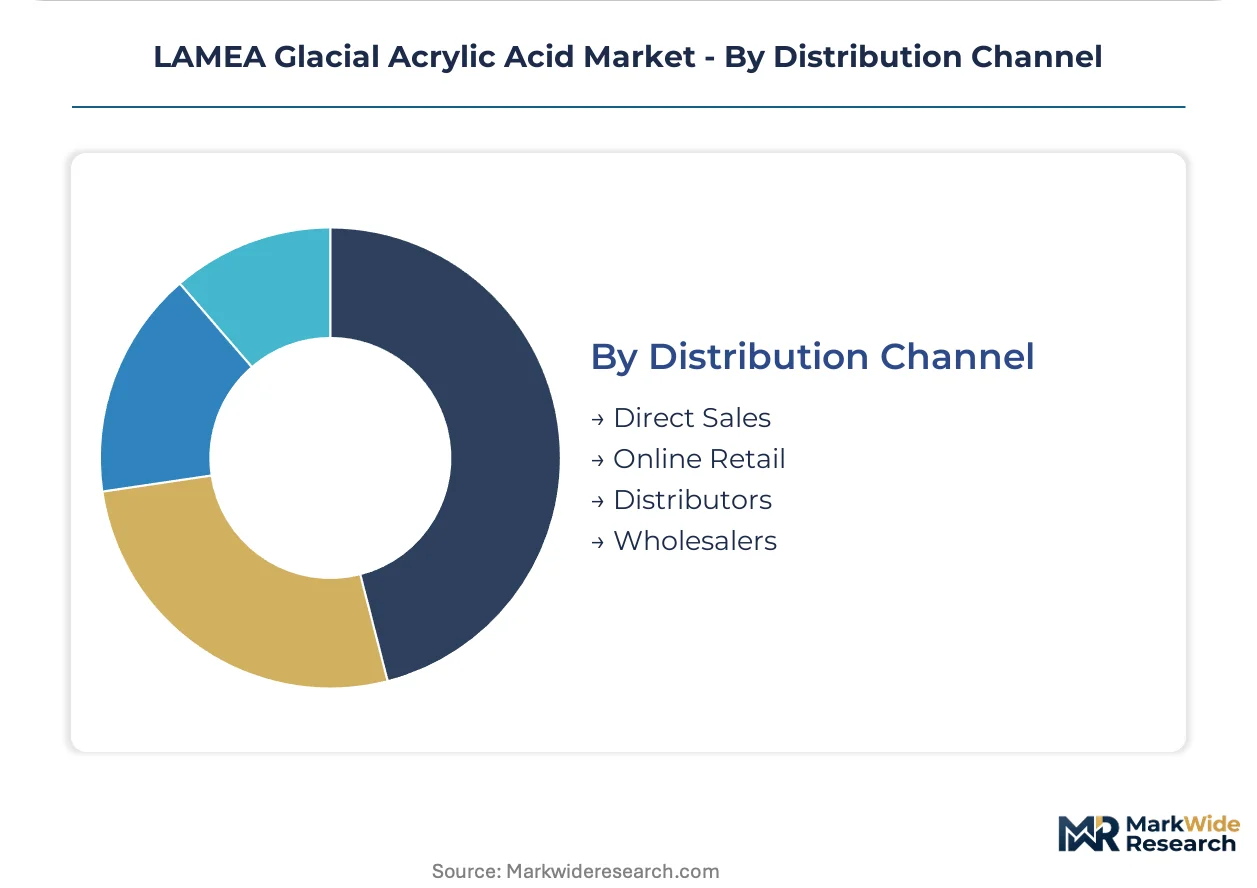
Channel configuration in the LAMEA glacial acrylic acid market diverges sharply between bulk industrial flows and specialty-grade transactions. Understanding which segments route through direct sales versus distributor networks determines procurement strategy and margin capture for suppliers targeting this fragmented regional landscape.
Product Type:
Industrial-grade volumes move predominantly through direct sales channels to large coatings manufacturers, while pharmaceutical and cosmetic grades rely on specialized distributors with certification management capabilities.
- Industrial Grade:Contains higher water content tolerance up to 0.3% and serves as the workhorse feedstock for acrylate ester production. Demand concentrates in Saudi Arabia's Jubail Industrial City corridor, where integrated petrochemical complexes supply captive consumption for regional paints and adhesives manufacturing.
- Pharmaceutical Grade:Achieves purity thresholds exceeding 99.5% through advanced melt crystallization, commanding substantial premiums over standard specifications. South Africa's adoption of REACH-aligned protocols through its Department of Trade, Industry and Competition is formalizing procurement standards for healthcare applications in Johannesburg and Cape Town hospital supply chains.
- Cosmetic Grade:Meets stringent heavy metal and residual monomer limits for personal care polymer applications. Brazilian formulators in São Paulo's cosmetics cluster source through ANVISA-registered distributors to satisfy registration requirements.
- Food Grade:Complies with migration limits for indirect food contact applications in packaging adhesives. Limited regional production capacity forces reliance on import channels serving North African processing facilities.
Industrial Grade dominates installed base. Pharmaceutical Grade is where expansion concentrates.
Application:
Margin structure varies dramatically across applications, with coatings commanding premium positioning through SASO certification requirements while textiles operate on thinner spreads.
- Coatings:Automotive OEM specifications in Morocco and Egypt mandate single-source procurement above 500 metric tons annually, compressing negotiation cycles and favoring direct supplier relationships. Renault-Nissan and Stellantis qualification programs in the Maghreb region are consolidating vendor bases.
- Adhesives:Construction-grade formulations for Saudi building supply chains require SASO conformity assessment documentation, creating barrier-to-entry advantages for pre-certified suppliers. Johannesburg and Durban manufacturers are consolidating supplier bases to reduce compliance administration burden.
- Paints:Decorative and protective coatings for Nigeria's underpenetrated West African market present first-mover opportunities for distributors establishing blending facilities in Lagos.
- Textiles:Sizing and finishing applications for fabric processing generate fragmented demand managed through regional distributor networks with established mill relationships.
Coatings command premium positioning. Adhesives present the steepest expansion trajectory amid infrastructure buildout.
End User:
Customer concentration patterns dictate channel selection, with automotive and construction favoring direct engagement while consumer goods and healthcare fragment across intermediary layers.
- Construction:Saudi Arabia's petrochemical corridor integration enables captive feedstock access for large-scale acrylate ester producers serving regional building supply chains. Direct sales channels control these volume relationships.
- Automotive:OEM-tier supplier qualification programs in North Africa mandate simplified supply chain audit trails, displacing traditional distributor relationships for qualified volume transactions.
- Healthcare:Pharmaceutical-grade registration requirements through ANVISA in Brazil extend approval cycles to 18-24 months, delaying market entry and concentrating procurement among established compliant suppliers.
- Consumer Goods:Superabsorbent polymer demand for personal care products fragments across mid-scale processors, with distributor networks managing smaller lot sizes and technical service requirements.
Construction anchors volume flows. Healthcare is climbing the fastest on regulatory formalization.
Distribution Channel:
Channel economics reflect shipment scale and technical service intensity, with crystallization operations engineering expertise scarcity complicating direct model expansion.
- Direct Sales:Controls bulk transactions above 500 metric tons annually to integrated coatings producers and automotive OEM-tier suppliers. Crystallization operations engineering expertise concentrates in European and East Asian technical institutes, complicating staffing for new LAMEA production assets seeking to serve this channel.
- Distributors:Manages fragmented textile mill demand and smaller healthcare procurement channels with certification management capabilities. South Africa's BIS-aligned import standards favor distributors with established pre-shipment testing and documentation workflows.
- Wholesalers:Serves spot market requirements and inventory buffering for standalone refiners lacking captive olefin supply.
- Online Retail:Captures laboratory-scale and research quantities with limited current penetration in industrial bulk procurement.
Direct Sales dominates transaction value. Distributors are gaining share fastest on compliance complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Africa's pharmaceutical channels exhibit the lowest price elasticity due to REACH-aligned compliance requirements, while Brazilian construction formulators remain highly sensitive to feedstock cost swings. This demand-elasticity contrast shapes procurement patterns across the LAMEA region.
Saudi Arabia
Water treatment polymer demand from municipal infrastructure expansion drives consumption growth. SASO mandates conformity assessment for acrylic acid derivatives entering construction supply chains. Jubail Industrial City concentrates integrated petrochemical capacity, enabling captive feedstock access for regional acrylate ester producers.
South Africa
Pharmaceutical-grade procurement formalizes through healthcare supply chain standardization. The Department of Trade, Industry and Competition enforces BIS-aligned chemical import standards with pre-shipment testing requirements. Johannesburg and Durban manufacturers consolidate supplier bases to reduce compliance administration burden.
Brazil
Construction-grade adhesives and paints absorb industrial-grade volumes amid infrastructure buildout. ANVISA pharmaceutical-grade registration requirements extend approval cycles to 18-24 months, creating market access barriers. São Paulo's cosmetics cluster sources cosmetic-grade material through registered distributors.
United Arab Emirates
Superabsorbent polymer demand accelerates for personal care product manufacturing. MOHAP pharmaceutical oversight influences import documentation requirements for healthcare applications. Dubai and Abu Dhabi logistics hubs facilitate re-export flows to underpenetrated West African markets.
Nigeria
Paints and coatings sector expansion creates first-mover opportunities for distributor-established blending facilities. National chemical inventory development lags regional peers, complicating cross-border registration validity. Lagos anchors West African demand concentration with limited localized production capacity.
LAMEA Glacial Acrylic Acid Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the LAMEA glacial acrylic acid market. European and East Asian integrated majors command advanced melt crystallization process know-how, while regional petrochemical players leverage captive olefin supply for margin defense. Three archetypes dominate: integrated global majors with technology licensing capabilities, regional petrochemical conglomerates with backward integration into feedstock, and specialty distributors with certification management infrastructure. Competitive dynamics center on strategic partnerships for technology transfer and capacity expansion in high-growth corridors.
Among European-anchored integrated majors, BASF SE exemplifies technology-led positioning through its Ludwigshafen-derived process expertise. Dow Inc represents North American technology transfer models serving regional operations. Sasol occupies a distinctive position as a coal-to-chemicals backward integrated producer at Secunda, yielding captive acrylic acid feedstock unavailable to naphtha-dependent competitors.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc |
| Sasol |
| Nippon Shokubai Co Ltd |
| Mitsubishi Chemical Holdings Corporation |
| Tasnee |
| Arkema |
| Formosa Plastics Corporation |
| BASF PETRONAS Chemicals Sdn. Bhd. |
| Others |
Pricing and Supply Chain Analysis
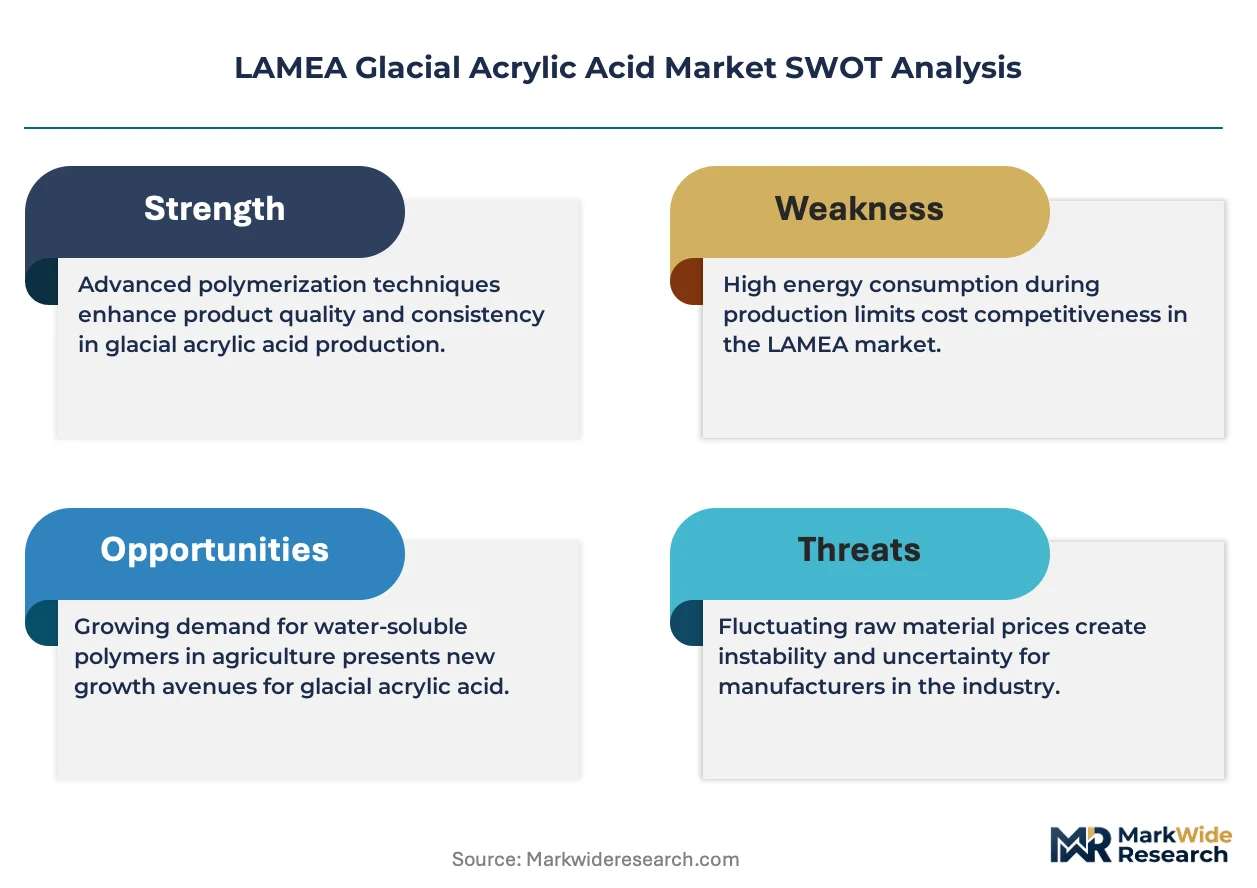
Sixty-to-ninety-day inventory cycles at Jubail Industrial City complexes concentrate pricing power among backward-integrated producers, while standalone refiners absorb propylene volatility through spot-market exposure. This lead-time asymmetry stratifies margin capture across the LAMEA glacial acrylic acid value chain.
Pricing Analysis
After-sales technical service contracts and crystallization process optimization packages now drive lifetime value beyond base chemical offtake. Three-tier pricing structure across pharmaceutical, industrial, and cosmetic grade levels segments buyers by purity threshold and certification burden. Pricing pressure stems from biobased 3-hydroxypropionic acid pilot routes achieving fermentation-scale viability for superabsorbent polymer feedstock. Brazilian construction formulators exhibit highest price sensitivity to naphtha-cracker input swings, while South African pharmaceutical channels show lowest elasticity under REACH-aligned compliance mandates.
Supply Chain Analysis
Strait of Hormuz transit underwrites feedstock security for Saudi Arabia's Jubail corridor, concentrating regional supply gravity in the Gulf. Production draws from Saudi Arabia, South Africa, and Malaysia, with propylene, naphtha, and coal-derived syngas as primary input anchors. Single-source vulnerability pervades Brazilian and Argentine standalone refiners lacking captive olefin supply. Distribution runs through direct sales channels for bulk coatings transactions above 500 metric tons annually, while distributor networks manage fragmented textile and healthcare procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service attach rates for crystallization process optimization and SASO certification management are expanding faster than base chemical volumes, reframing this market as a recurring-revenue opportunity beyond commodity offtake.
For Market Incumbents: Fortify margin position through captive feedstock expansion at Secunda-scale coal-to-chemicals complexes and melt crystallization technology licensing to mid-scale Middle Eastern producers. Biobased substitution threats from fermentation-derived routes demand accelerated R&D in dynamic crystallization control systems to preserve premium-grade positioning.
For New Entrants and Emerging Players: Anchor in Nigeria's underpenetrated West African paints sector through Lagos-based blending facilities with pre-positioned inventory buffers. Construction chemical certification mandates in Saudi Arabia present white-space entry via SASO-registered distributor partnerships, bypassing integrated major dominance in direct sales channels.
For Investors and Strategic Acquirers: Carve-out targets emerge from European petrochemical parents divesting non-core acrylic acid assets amid portfolio decarbonization pressures. Mid-scale distributors with ANVISA-registered infrastructure in Brazil and BIS-aligned certification capabilities in South Africa represent acquisition archetypes with defensive moats. Watch biobased acrylic acid cost-parity milestones as inflection signals for fossil-based volume erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Olefin Supply | Secunda-style coal-to-chemicals complexes insulate margins from naphtha volatility. |
| Melt Crystallization Technology Licensing | European process know-how transfer unlocks premium-grade production for Gulf partners. |
| SASO Certification Pre-Positioning | Pre-certified suppliers capture Saudi construction chemical premium positioning. |
| ANVISA-Registered Distribution Infrastructure | Brazilian pharmaceutical-grade registration creates 18-24 month competitive moats. |
| Biobased Acrylic Acid R&D Partnerships | Fermentation-derived route pilots threaten fossil-based volume growth trajectories. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, with plant managers at Jubail Industrial City complexes, procurement leads at Moroccan automotive coatings OEMs, and technical R&D directors at superabsorbent polymer producers contributing operational data. Secondary validation drew from Saudi customs and trade statistics, SEC 10-K disclosures from integrated petrochemical majors, and OECD chemical inventory alignment documentation. Bottom-up capacity and consumption estimates were triangulated against top-down macroeconomic drivers.
Across the analysis window, forecasts reflect segmented modeling across grade tier, end-use industry, and regional production hub dimensions. CAGRs were derived from elasticity-adjusted consumption trajectories incorporating propylene feedstock cost scenarios and regulatory alignment timelines. Crystallization technology adoption curves and biobased substitution threat velocities served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under base assumptions of sustained naphtha-cracker economics and stable regulatory alignment timelines; material deviation in crude oil volatility or REACH-equivalent protocol expansion would warrant model refresh. Practitioners should keep alternative scenarios live as biobased acrylic acid cost-parity and Gulf petrochemical capacity expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Global Boric Acid Market
Bulk Chemicals
Bio Based Paraxylene Market
Bulk Chemicals
Sodium Molybdate Market
Bulk Chemicals
Global Linear Alpha Olefins Market
Bulk Chemicals
Sodium Bisulfite Market
Bulk Chemicals
Muconic Acid Market
Bulk Chemicals
Methyl Chloroform Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Putty Powder Market
Bulk Chemicals
Lignosulfonates Market
Bulk Chemicals
Hydrated Lime Market
Bulk Chemicals
Cesium Hydroxide Market
Bulk Chemicals
Granular Urea Market
Bulk Chemicals
Calcium Hydrogen Sulphite Market
Bulk Chemicals
Global Levulinic Acid Market
Bulk Chemicals
Chloroacetophenone Market