
 Neodecanoyl Chloride Market | 2026-2036
Neodecanoyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
Neodecanoyl Chloride Market Analytics
Specialty chemical distribution through regional distributors and direct mill supply contracts is fragmenting as buyers seek shorter lead times and certified lot traceability. BASF SE leverages its integrated European production network to sustain captive supply advantages for pharmaceutical-grade material. CABB Group anchors North American availability through chlorination technology leadership at its German and US sites. Merck KGaA differentiates via ultra-high-purity packaging protocols that serve life-science end users with stringent contamination thresholds.
Neodecanoyl chloride is a branched C10 acyl chloride synthesized via thionyl chloride or phosgene-mediated chlorination of neodecanoic acid, with purity grades ranging from technical to greater than 99 percent for pharmaceutical applications. The compound functions primarily as an acylation reagent and intermediate for esterification routes producing plasticizers, surfactants, and agrochemical actives. Liquid formulations dominate volume throughput due to ease of handling in continuous chemical processes, while powder grades command premium positioning in pharmaceutical sector applications where moisture exclusion determines shelf stability. Intermediates and plasticizers represent the fastest-growing application clusters, driven by agrochemical suppliers and plastics manufacturers seeking branched-chain modifiers with enhanced thermal stability.
REACH registration requirements in Europe and EPA Toxic Substances Control Act reporting in the United States impose escalating compliance burdens on importers and domestic producers, effectively filtering smaller traders from commercial supply chains. China's SAMR-administered chemical substance registration framework now mandates new-data submission for imported acyl chlorides, extending approval timelines and favoring producers with established local testing partnerships. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate specification mismatches that could disrupt cross-border formulation supply.
Market Dynamics
REACH compliance deadlines and China's SAMR registration mandates are compressing supplier qualification timelines, forcing buyers to consolidate procurement around certified producers with established testing partnerships.
Growth Catalysts
- Agrochemical intermediate demand:Branched-chain acyl chlorides enable synthesis of thermally stable pesticide actives. East China's chemical manufacturing belt consumes bulk volumes for captive production of herbicide and fungicide precursors.
- REACH registration completion:European downstream formulators now specify pharmaceutical-grade purity thresholds above 99 percent, creating specification premiums for compliant acyl chloride suppliers.
- Plasticizer formulation shifts:Neodecanoyl esters deliver enhanced thermal stability in PVC compounds. Plastics manufacturers in Germany and the United States are substituting linear-chain alternatives with branched C10 modifiers.
Market Restraints
- Thionyl chloride input volatility:Sulfur and chlorine feedstock price swings compress margins for chlorination-based producers. Technical-grade material faces acute cost pressure during sulfur supply disruptions.
- Phosgene route regulatory friction:EPA Toxic Substances Control Act reporting and OSHA process safety mandates impose fixed compliance burdens. Smaller chlorination specialists lack capital to sustain dual-route production flexibility.
- Linear acyl chloride substitution:Decanoyl chloride from palm kernel fatty acid streams offers lower unit economics in surfactant applications. Cost-sensitive detergent formulators in Southeast Asia default to linear-chain alternatives.
Strategic Opportunities
- Pharmaceutical-grade packaging protocols:Ultra-high-purity powder grades command shelf-stability premiums in life-science applications. Moisture-exclusion packaging innovations open specialty distribution channels.
- India agrochemical formulation growth:CDSCO registration pathways for imported acyl chlorides remain underpenetrated. Domestic pesticide producers seek branched-chain intermediates for export-oriented actives.
- Continuous flow chlorination technology:Microreactor systems reduce phosgene inventory and improve heat transfer. Technology convergence between process intensification and automated quality control enables smaller-batch pharmaceutical supply.
Industry Challenges
- Analytical chemist scarcity:Gas chromatography and Karl Fischer titration expertise for acyl chloride purity verification is concentrated at legacy chlorination sites. New market entrants face recruitment bottlenecks for QC laboratory staffing.
- SAMR approval timeline compression:China's new-data submission requirements for imported acyl chlorides extend registration cycles. Importers without established local testing partnerships face 18-month qualification delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neodecanoyl Chloride Market |
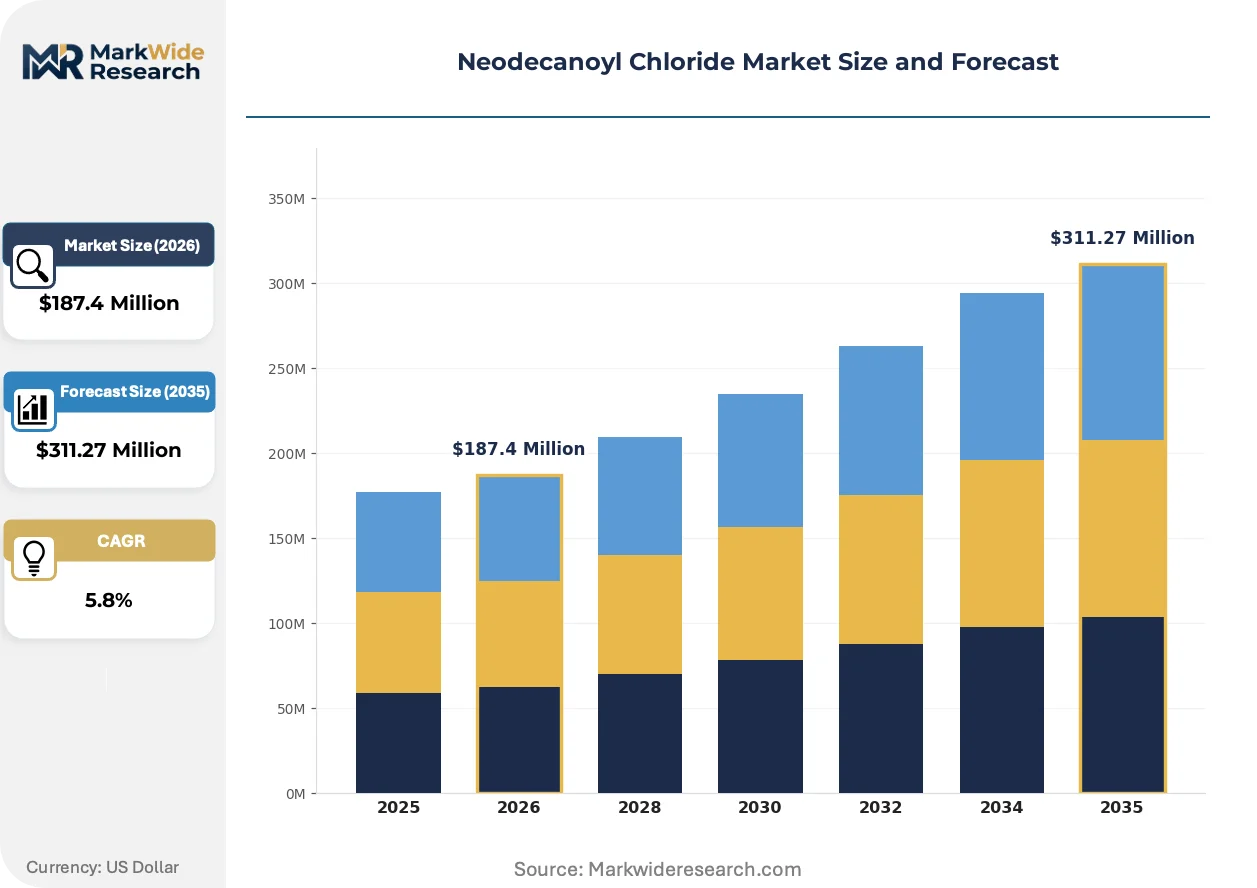
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Powder, Viscous End User: Chemical Industry, Pharmaceutical Sector, Agrochemical Suppliers, Plastics Manufacturers Application: Solvents, Intermediates, Plasticizers, Surfactants Packing Type: Drums, Bags, Cylinders, Containers |
| Companies Covered | BASF SE, CABB Group, Merck KGaA, Tokyo Chemical Industry Co., Ltd., Alfa Aesar, Hangzhou Dayangchem, Pingyuan Xinda Chemical, VanDeMark, J&H Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neodecanoyl Chloride Market Evolving Landscape
Process analytical technology and automated batch release systems are compressing quality assurance cycles. Regulatory divergence between jurisdictions is fragmenting specification standards.
Continuous flow microreactor chlorination is digitizing production control in acyl chloride synthesis. Pharmaceutical-grade suppliers in Germany and Switzerland are adopting real-time infrared monitoring to reduce batch-to-batch variability. This technology is digitizing quality documentation, enabling electronic batch records that satisfy FDA and EMA audit requirements without manual transcription.
REACH substance evaluation under the 2024-2026 rolling action plan is tightening impurity thresholds for acyl chlorides used in cosmetic and pharmaceutical intermediates. Downstream formulators must now demonstrate sub-ppm levels of residual thionyl chloride decomposition products. European surfactant producers are responding by dual-sourcing from REACH-registered suppliers with dedicated pharmaceutical-grade production lines.
Certified lot traceability is displacing spot-market purchasing in specialty chemical distribution. Agrochemical and plastics manufacturers in China's Yangtze River Delta now require chain-of-custody documentation from neodecanoic acid feedstock through final chlorination. This behavioral shift concentrates procurement around integrated producers with captive acid supply, marginalizing traders without backward integration into fatty acid refining.
Neodecanoyl Chloride Market Segmentation
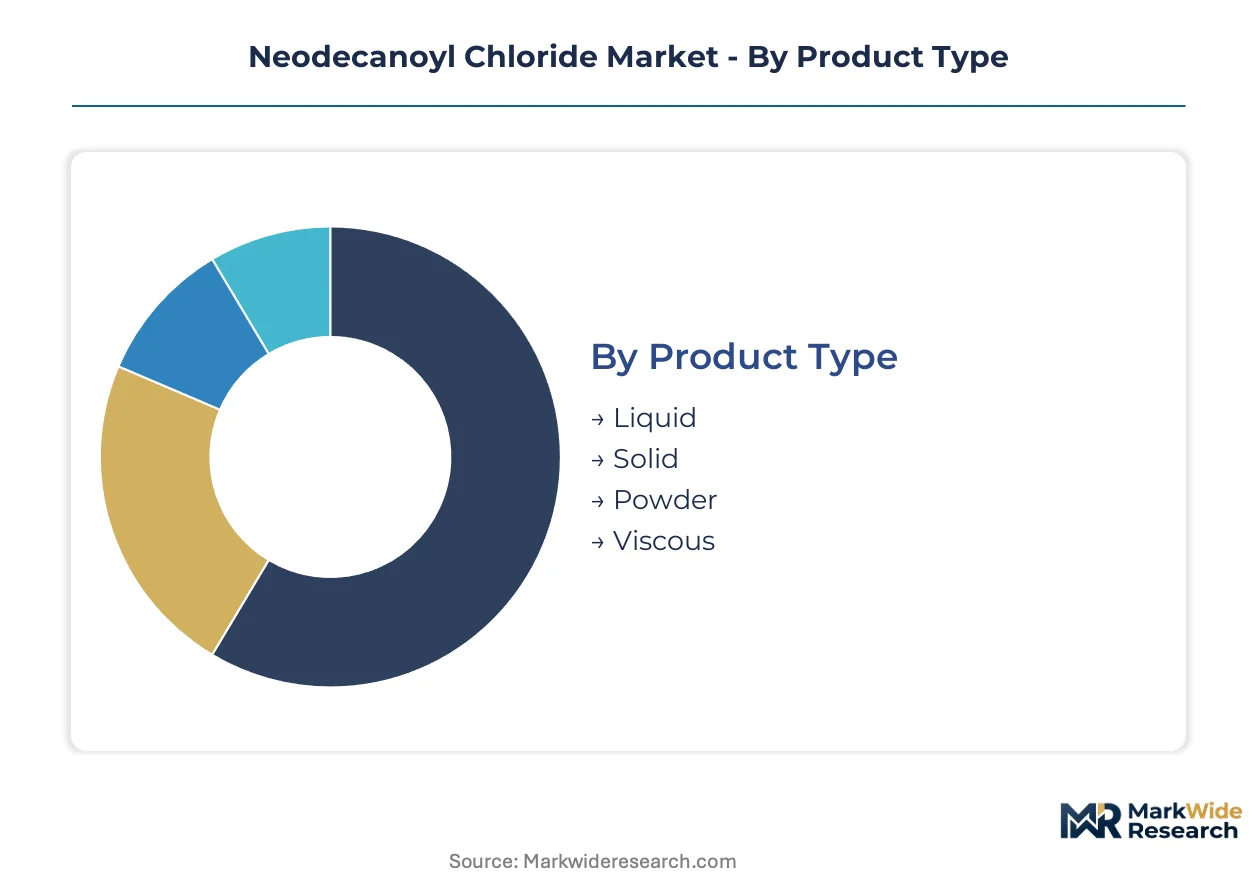
Neodecanoyl chloride exhibits divergent specification requirements across its end-use spectrum, with pharmaceutical and agrochemical applications imposing fundamentally different purity, handling, and documentation standards on suppliers. Segmentation clarity enables procurement teams to match formulation needs against certified production capabilities without over-specification penalties.
Product Type:
Mature liquid formulations dominate commercial throughput, while powder and solid grades occupy emerging niches with premium positioning.
- Liquid:Standard liquid grades facilitate continuous feed in chlorination and esterification processes. Agrochemical manufacturers in East China's chemical manufacturing belt consume bulk liquid volumes for captive herbicide intermediate production, prioritizing handling efficiency over ultra-high purity.
- Powder:Powder formulations undergo additional drying and milling to achieve moisture content below 0.1 percent. Pharmaceutical sector buyers in Germany specify powder grades for acylation reactions where water exclusion determines shelf stability and reaction yield consistency.
- Solid:Solid neodecanoyl chloride offers intermediate handling characteristics between liquid and powder states. Specialty chemical distributors stock solid grades for customers lacking powder handling infrastructure.
- Viscous:Viscous variants retain residual solvent or plasticizer content from incomplete purification. Technical-grade purchasers accept viscous material for cost-sensitive surfactant synthesis.
Liquid retains volume leadership; powder holds the steepest expansion curve.
End User:
Customer type segmentation reveals a cost-to-compliance gradient, with commodity chemical buyers at one pole and validated pharmaceutical suppliers at the other.
- Chemical Industry:General chemical processors employ neodecanoyl chloride as a versatile acylation reagent across multiple synthesis routes. REACH-registered European producers supply this segment with technical-grade material certified for industrial use.
- Agrochemical Suppliers:Branched-chain acyl chlorides enable thermally stable pesticide active synthesis. East China's integrated agrochemical producers consume captive volumes for export-oriented herbicide and fungicide precursors, driving specification convergence around sulfur and chlorine impurity thresholds.
- Pharmaceutical Sector:Pharmaceutical applications demand greater than 99 percent purity with sub-ppm residual thionyl chloride documentation. FDA and EMA audit requirements force suppliers to maintain dedicated pharmaceutical-grade production lines with electronic batch records.
- Plastics Manufacturers:PVC compounders substitute linear-chain plasticizers with neodecanoyl esters for enhanced thermal stability. German and United States plastics producers lead this formulation shift, sourcing through direct mill supply contracts rather than distributors.
Chemical Industry retains volume leadership; Agrochemical Suppliers hold the steepest expansion curve.
Application:
Application segmentation tracks the compound's functional versatility from process solvent to structural building block in downstream molecules.
- Intermediates:Intermediate applications dominate value capture, with neodecanoyl chloride serving as a acylation building block for complex agrochemical and pharmaceutical actives. CDSCO registration pathways in India remain underpenetrated for this application, creating expansion opportunity.
- Plasticizers:Neodecanoyl esters deliver superior thermal stability in flexible PVC compounds. German automotive cable manufacturers specify branched C10 plasticizers for under-hood applications exceeding linear-chain alternatives.
- Solvents:Solvent applications exploit the compound's polar aprotic characteristics in specialized reaction media. This segment contracts as greener solvent alternatives gain regulatory preference under EU Green Deal objectives.
- Surfactants:Surfactant synthesis employs neodecanoyl chloride for branched-chain ester surfactants with foaming control properties. Southeast Asian detergent formulators increasingly substitute linear decanoyl chloride from palm kernel fatty acids on cost grounds.
Intermediates retain volume leadership; Plasticizers gain share fastest.
Packing Type:
Packaging segmentation reflects divergent supply chain configurations, from bulk tanker integration to laboratory-scale cylinder distribution.
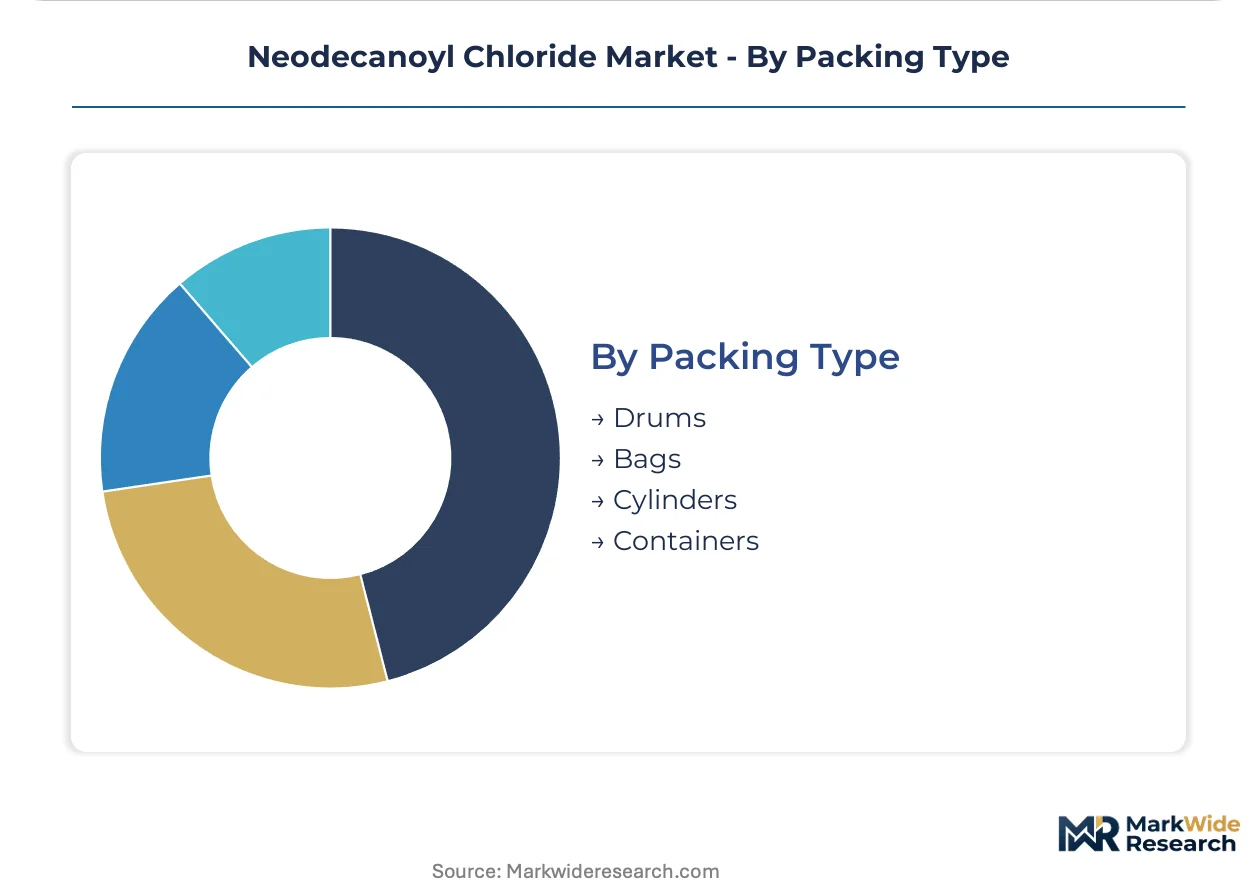
- Drums:Steel and HDPE drums constitute the standard liquid handling format for chemical industry and agrochemical procurement. German distributors maintain drum stockpiles at Rotterdam and Hamburg port facilities to compress lead times for European formulators.
- Cylinders:Cylinders with inert gas blankets serve pharmaceutical and life-science customers requiring moisture exclusion during dispensing. Merck KGaA's ultra-high-purity packaging protocols center on specialized cylinder designs with nitrogen padding.
- Containers:Intermediate bulk containers enable continuous process feeding at integrated manufacturing sites. China's Yangtze River Delta agrochemical producers favor container delivery for captive consumption.
- Bags:Multi-layer laminated bags package powder grades with desiccant inclusion. Shelf-stability premiums for bagged powder open specialty distribution channels to pharmaceutical compounders lacking bulk handling systems.
Drums retain volume leadership; Cylinders gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German pharmaceutical-grade suppliers command 15-20% price premiums over East Chinese technical-grade producers, yet Yangtze River Delta agrochemical manufacturers absorb this asymmetry through captive backward integration into fatty acid feedstocks.
China
East China's chemical manufacturing belt dominates global consumption volume, with integrated agrochemical producers in Jiangsu and Zhejiang provinces consuming captive neodecanoyl chloride for herbicide and fungicide intermediate synthesis. SAMR-administered chemical substance registration now mandates new-data submission for imported acyl chlorides, extending approval timelines and favoring domestic producers with established local testing partnerships. Shanghai and Ningbo port clusters serve as consolidation points for drum and container shipments to Southeast Asian surfactant formulators.
Germany
Specialty chemical manufacturers in North Rhine-Westphalia and Bavaria sustain procurement leadership for pharmaceutical-grade material exceeding 99% purity thresholds. REACH substance evaluation under the 2024-2026 rolling action plan tightens impurity specifications for cosmetic and pharmaceutical intermediates, forcing downstream formulators to demonstrate sub-ppm residual thionyl chloride documentation. BASF SE leverages its integrated Ludwigshafen production network to maintain captive supply advantages for life-science end users.
United States
Plastics manufacturers in Texas and Louisiana substitute linear-chain plasticizers with neodecanoyl esters for enhanced thermal stability in automotive cable compounds. EPA Toxic Substances Control Act reporting and OSHA process safety mandates impose fixed compliance burdens on phosgene-route chlorination, filtering smaller traders from commercial supply chains. CABB Group anchors North American availability through chlorination technology leadership at its German and US sites.
India
Domestic pesticide producers in Gujarat and Maharashtra seek branched-chain intermediates for export-oriented agrochemical actives, yet CDSCO registration pathways for imported acyl chlorides remain underpenetrated. Bureau of Indian Standards certification requirements for specialty chemicals create procedural friction for first-time entrants. Ankleshwar and Vapi industrial corridors concentrate formulation activity for herbicide precursors destined to Latin American markets.
Japan
Pharmaceutical and fine-chemical manufacturers in Osaka and Tokyo metropolitan areas source ultra-high-purity grades for acylation reactions requiring moisture exclusion. METI-administered chemical substance regulations align with REACH impurity thresholds, enabling seamless cross-certification for European export formulations. Kansai region distributors maintain cylinder inventories with nitrogen padding for life-science customers lacking bulk handling infrastructure.
Neodecanoyl Chloride Market Competitive Landscape
Vertically integrated chemical conglomerates and specialty chlorination specialists split the market into captive-supply and merchant-sale domains. Consolidation pressure concentrates procurement around producers with backward integration into neodecanoic acid feedstocks, marginalizing traders without fatty acid refining capabilities. Three archetypes dominate: integrated petrochemical majors with multi-site chlorination networks; mid-cap specialists with dedicated pharmaceutical-grade production lines; and regional Chinese producers serving cost-sensitive surfactant applications. Competitive moves center on REACH registration completion and continuous flow microreactor technology licensing.
Among European-based integrated producers, BASF SE exemplifies the captive-supply archetype through its Ludwigshafen production network, while CABB Group occupies the chlorination-technology leadership position across German and North American sites. Merck KGaA represents the ultra-high-purity tier through specialized packaging protocols serving life-science end users with stringent contamination thresholds.
| Leading Market Players |
|---|
| BASF SE |
| CABB Group |
| Merck KGaA |
| Tokyo Chemical Industry Co., Ltd. |
| Alfa Aesar |
| Hangzhou Dayangchem |
| Pingyuan Xinda Chemical |
| VanDeMark |
| J&H Chemical |
| Others |
Value Network & Pricing Analysis
Thionyl chloride feedstock volatility compresses margins for chlorination-based producers while simultaneously widening price spreads between technical and pharmaceutical-grade material, forcing buyers to consolidate procurement around integrated suppliers with captive acid supply.
Pricing Analysis
Configured-to-order pricing for pharmaceutical-grade powder grades commands substantial premiums over standard liquid formulations. Three-tier pricing structure across premium, standard, and economy levels separates greater than 99 percent purity material with sub-ppm documentation from technical-grade bulk supply. Price differentiation rests on certification grade and volume scale, with REACH-registered producers capturing specification premiums. Cost compression in technical-grade segments is intensifying because sulfur supply disruptions squeeze chlorination margins. Agrochemical manufacturers in East China exhibit highest price sensitivity, while German pharmaceutical formulators accept premium positioning for audit-compliant material.
Supply Chain Analysis
Neodecanoic acid feedstock availability anchors supply chain configuration, with production gravity centering on Germany, China, and the United States. Raw material dependencies encompass sulfur and chlorine for chlorination routes, plus thionyl chloride or phosgene as chlorinating agents. Distribution runs through regional distributors and direct mill supply contracts, fragmenting as buyers demand certified lot traceability. Single-source vulnerability emerges from concentrated neodecanoic acid refining capacity, exposing downstream formulators to feedstock disruption.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical-grade packaging protocols represent a service-attach opportunity, with moisture-exclusion cylinder innovations and nitrogen-padding systems expanding faster than commodity liquid volumes.
For Market Incumbents: Entrench position through backward integration into neodecanoic acid feedstocks and dedicated pharmaceutical-grade production lines with electronic batch records. Linear acyl chloride substitution from palm kernel fatty acids threatens surfactant market share, demanding certification investment in REACH-registered purity tiers to defend specification premiums. For New Entrants and Emerging Players: Build out microreactor-based continuous flow chlorination capabilities to serve smaller-batch pharmaceutical demand with reduced phosgene inventory. India's CDSCO registration pathways for imported acyl chlorides remain underpenetrated for agrochemical intermediate applications, offering white-space entry through local testing partnerships and Bureau of Indian Standards certification. For Investors and Strategic Acquirers: Chlorination-technology specialists with established SAMR testing partnerships in China present compelling acquisition targets for long-term viability across the projection horizon. Monitor SAMR approval timeline compression as an inflection indicator, with 18-month qualification delays for importers without local partnerships signaling consolidation pressure toward domestic producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Neodecanoic Acid | Captive feedstock supply secures margin control against sulfur volatility for German and Chinese producers. |
| Continuous Flow Microreactor Deployment | Process intensification reduces phosgene inventory while enabling FDA-compliant electronic batch records. |
| Pharmaceutical-Grade Packaging Protocol Development | Merck KGaA's nitrogen-padded cylinder designs open specialty distribution channels with shelf-stability premiums. |
| CDSCO Registration Pathway Establishment | First-mover certification in India captures agrochemical intermediate demand from Gujarat pesticide producers. |
| REACH Registration Completion | Sub-ppm impurity documentation satisfies EMA audit requirements for cosmetic and pharmaceutical downstream formulators. |
Research Methodology
The analysis maps liquid, powder, solid, and viscous product grades, each validated through procurement leads at agrochemical manufacturers, pharmaceutical formulators, plastics compounders, and specialty chemical distributors. Primary interviews with plant managers, downstream OEM procurement heads, distribution channel partners, and technical R&D directors combined with secondary validation from customs/trade data, Cefic industry reports, SEC 10-K filings, and SAMR registration databases. Bottom-up volume triangulation against top-down value estimates ensures cross-verification of segment splits.
Assumptions around REACH compliance deadlines, SAMR registration timelines, and thionyl chloride feedstock availability were held fixed across the modeling period, with sulfur price volatility and phosgene route regulatory friction treated as scenario variables. Segmentation dimensions modeled encompass grade tier, end-use industry, packaging format, and regional production hub. CAGRs were derived through regression analysis of historical volume trends against projected formulation shifts in plasticizer and agrochemical applications.
Stress conditions across sulfur supply disruptions, SAMR approval timeline extensions, and linear acyl chloride substitution rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions, with regulatory divergence across REACH, EPA TSCA, and SAMR frameworks representing primary revision risks. Cross-checking against Cefic chemical production benchmarks and CDSCO import registration data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Trimethyl Pentanediol Monoisobutyrate Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Global Hexyl Cinnamal Market
Oleochemicals
Caprylic/Capric Triglyceride Market
Oleochemicals
US Esters Market
Oleochemicals
Stearoyl Lactylates Market
Oleochemicals
Diisostearyl Fumarate Market
Oleochemicals
Global Methyl Ester Ethoxylate Market
Oleochemicals
White Mineral Oil Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Global Specialty Oleochemicals Market
Oleochemicals
Petrolatum Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Cetyl Esters Market
Oleochemicals
Isobutyl Stearate Market