
 Asia-Pacific Starch Derivatives Market | 2026-2036
Asia-Pacific Starch Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Starch Derivatives Market Outlook
Aftermarket technical service revenue for modified starch blending equipment is reshaping margin distribution across the value chain. Cargill leverages its integrated supply chain from Thai tapioca sourcing to regional formulation labs. Ingredion sustains technology leadership in specialty dextrin production for pharmaceutical binding applications. Japan Corn Starch anchors premium positioning through JIS-certified manufacturing protocols serving domestic food manufacturers.
Asia-Pacific starch derivatives comprise chemically, physically, or enzymatically altered starch products with modified viscosity, gelatinization temperature, or digestibility profiles, produced through acid hydrolysis, oxidation, or cross-linking processes for industrial thickening, binding, and stabilizing functions. Modified starch commands the dominant value share as food manufacturers substitute synthetic hydrocolloids in processed sauces and ready meals. Native starch competes on cost in animal feed compounding where livestock producers prioritize energy density over functional modification. Starch syrup segments face margin compression from alternative sweetener competition in beverage applications.
FSSAI labeling requirements in India, China's GB standards for food additive purity, and Japan's METI chemical substance management framework collectively tighten product specifications and documentation burdens. Compliance costs favor scaled producers with dedicated regulatory affairs teams over regional traders. Stakeholders must monitor evolving pharmaceutical-grade certification requirements across multiple national pharmacopeias to secure long-term supply contracts with drug companies.
Market Dynamics
Clean-label reformulation mandates from India's FSSAI and China's GB standards are compressing synthetic hydrocolloid demand while accelerating native and modified starch substitution across processed food manufacturing.
Growth Catalysts
- Pharmaceutical-Grade Dextrin Demand:Domestic drug manufacturers in China are expanding excipient procurement for tablet binding applications. This consumption pull concentrates in oral solid dosage formulations where dextrin replaces synthetic polymers.
- FSSAI Labeling Mandates:India's food additive disclosure requirements are forcing reformulation toward native starch alternatives. Processed sauce and ready meal manufacturers prioritize ingredient transparency to maintain shelf positioning.
- Tapioca Supply Chain Integration:Thai cassava processors are securing long-term contracts with regional formulation labs. This upstream control ensures consistent modified starch viscosity profiles for Southeast Asian food exporters.
Market Restraints
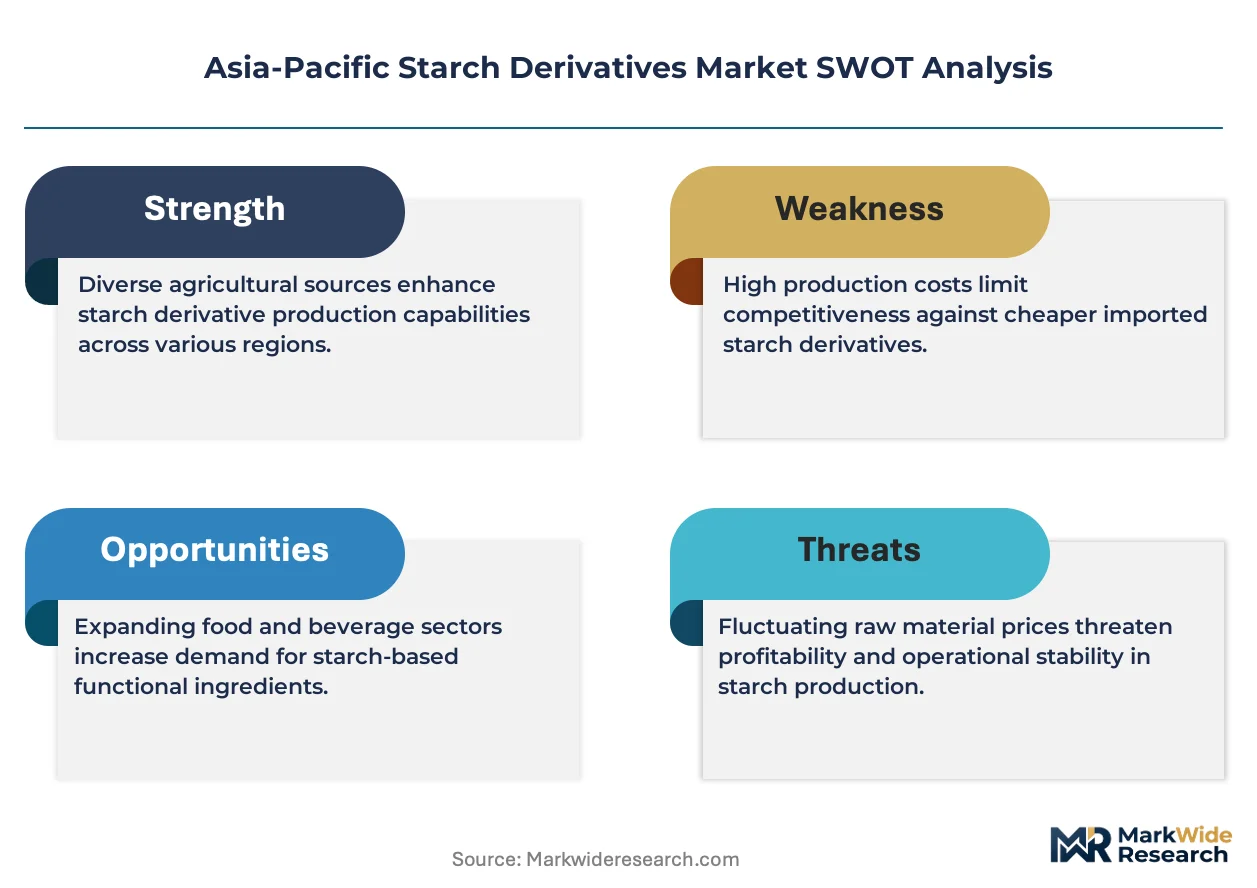
- Cassava Price Volatility:Thai tapioca chip export demand fluctuates with Chinese ethanol policy shifts. Starch derivative producers face margin compression when feedstock costs spike without corresponding formula price adjustment mechanisms.
- Pharmaceutical Certification Burden:Multiple national pharmacopeias require separate documentation for excipient-grade materials. Small and mid-scale producers lack dedicated regulatory affairs teams to manage Japan PMDA, China NMPA, and India CDSCO submissions simultaneously.
- Alternative Sweetener Displacement:High-fructose corn syrup faces substitution by stevia and monk fruit extracts in beverage applications. Starch syrup segments experience volume attrition in carbonated and still drink formulations.
Strategic Opportunities
- Vietnam Processed Food Expansion:Foreign direct investment in ASEAN manufacturing hubs is creating localized modified starch demand. Multinational sauce and convenience meal producers seek regional suppliers to reduce import dependency.
- Enzymatic Conversion Technology:Novel amylase systems enable lower-temperature starch processing with reduced energy inputs. Food manufacturers in Japan and South Korea pilot these systems to meet corporate carbon reduction targets.
- PLI Scheme Alignment:India's production-linked incentive framework for food processing supports domestic starch derivative capacity expansion. Eligible producers gain cost advantages in export markets through subsidized capital expenditure.
Industry Challenges
- Cross-Functional Technical Talent Scarcity:Formulation chemists with simultaneous expertise in enzymatic modification and pharmaceutical excipient compliance command premium compensation. Regional producers struggle to retain staff against multinational laboratory networks.
- Legacy Equipment Retrofit Costs:Acid hydrolysis reactors require corrosion-resistant lining replacement to meet evolving GB standards for food additive purity. Capital deployment timelines extend 18-24 months for compliance upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Starch Derivatives Market |
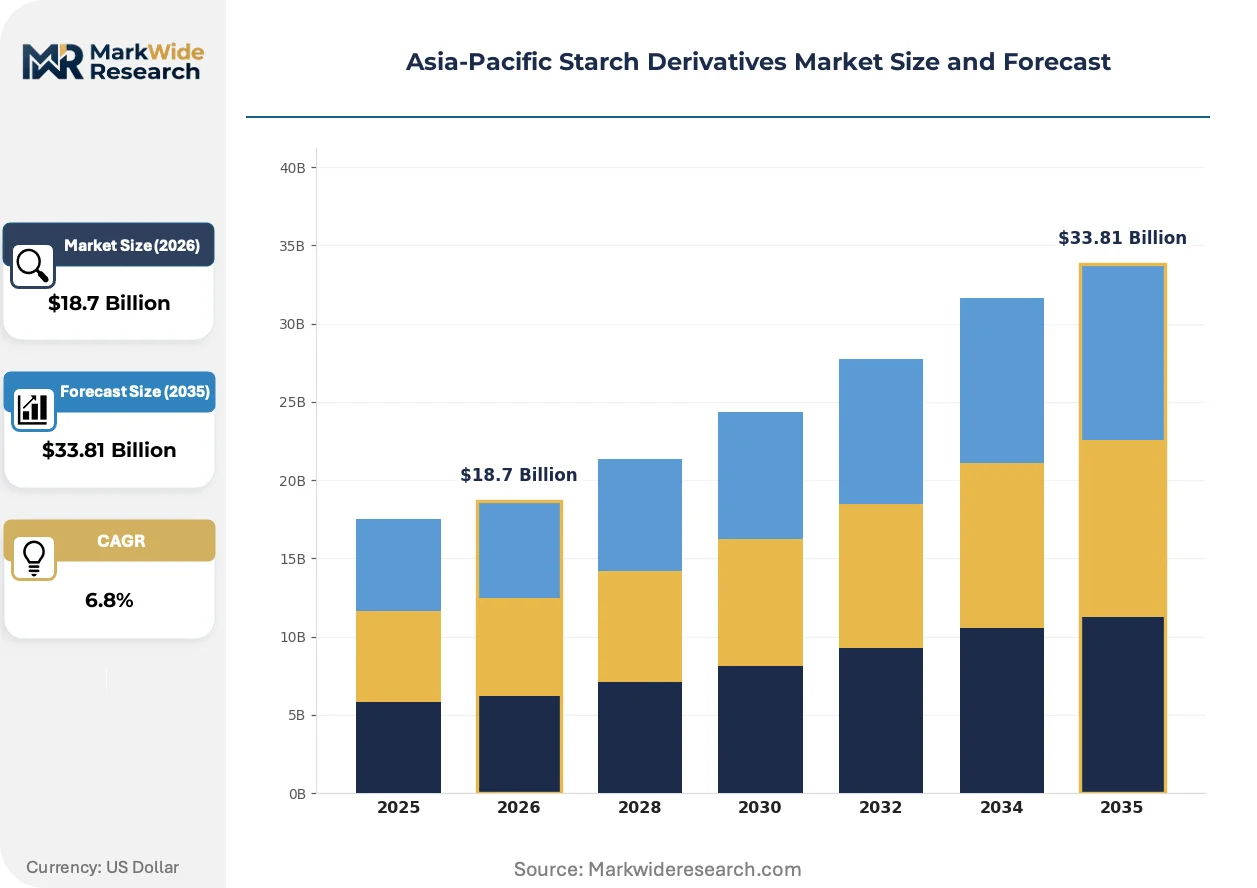
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modified Starch, Native Starch, Starch Syrup, Dextrins Application: Food & Beverage, Pharmaceuticals, Personal Care, Animal Feed End User: Food Manufacturers, Drug Companies, Cosmetic Brands, Livestock Producers Distribution Channel: Online Retail, Specialty Stores, Direct Sales, Wholesalers |
| Companies Covered | AGRANA, Manildra Group, Cargill, Gulshan Polyols, Japan Corn Starch, Ingredion, Angel Starch and Food, Sukhjit Starch & Chemicals, Tate & Lyle, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Starch Derivatives Market Strategic Shifts
Enzymatic processing advances and regulatory disclosure tightening are restructuring competitive advantage toward producers with integrated formulation capabilities and certified manufacturing protocols.
Dual-enzyme hydrolysis systems combining alpha-amylase and glucoamylase are collapsing traditional acid-thinning processes in modified starch production. Japanese and South Korean food manufacturers adopt these systems to achieve precise viscosity control with reduced chemical residue risk. The technology is collapsing capital requirements for small-batch specialty starch production while compressing batch cycle times from 12 hours to 4 hours.
China's GB 2760 food additive purity standards and Japan's METI chemical substance management framework are tightening residual solvent limits in pharmaceutical-grade dextrin. Manufacturers must install additional purification stages including activated carbon filtration and vacuum drying. Excipient producers serving domestic drug companies in Shanghai and Osaka face the steepest compliance cost escalation.
Ingredient disclosure preferences are compressing synthetic hydrocolloid procurement cycles across Southeast Asian retail channels. Clean-label ready meal producers in Thailand and Indonesia now specify native starch or minimally modified alternatives in supplier qualification documents. This specification shift concentrates in premium supermarket tiers where consumer panel scrutiny drives formulation transparency.
Asia-Pacific Starch Derivatives Market Segmentation
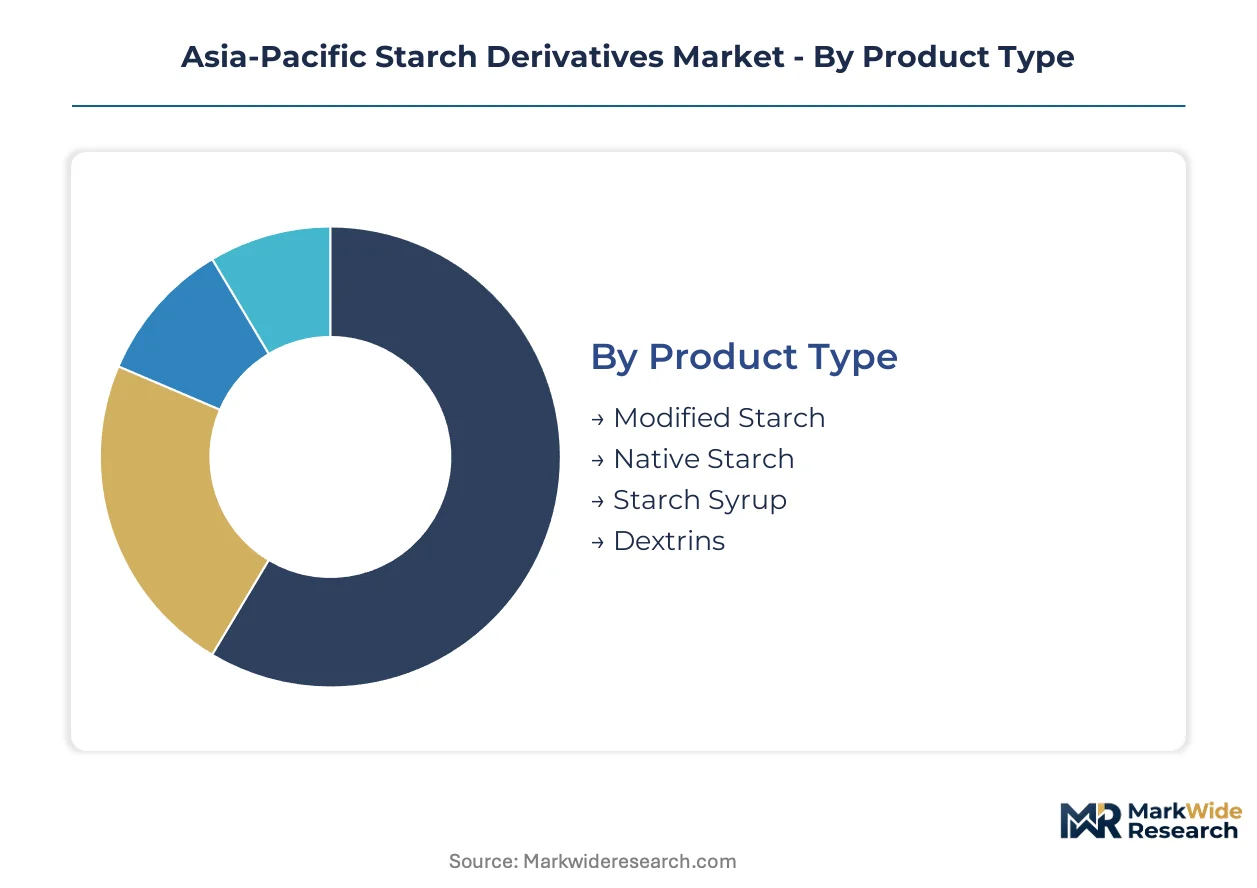
Starch derivative procurement patterns diverge sharply across product grades and end-use specifications. Pharmaceutical excipients command purity premiums that food-grade materials cannot capture, while feed applications prioritize caloric density over functional modification.
Product Type:
Cost tier stratification separates commodity native starch from premium modified and pharmaceutical-grade derivatives.
- Modified Starch:Chemically or physically altered to achieve specific viscosity, gelatinization temperature, or freeze-thaw stability profiles. Southeast Asian sauce and ready meal manufacturers in Thailand and Indonesia are expanding procurement for clean-label reformulations that displace synthetic hydrocolloids under tightening FSSAI and GB disclosure mandates.
- Native Starch:Unmodified starch extracted directly from corn, cassava, or potato sources without structural alteration. Indian livestock producers and Southeast Asian feed compounders concentrate procurement here, prioritizing energy density per unit cost over functional performance in ration formulations.
- Starch Syrup:Hydrolyzed starch products serving sweetener and humectant functions across beverage and confectionery applications.
- Dextrins:Low-molecular-weight carbohydrate polymers produced through controlled starch hydrolysis, with pharmaceutical-grade variants requiring residual solvent documentation for China NMPA and Japan PMDA submissions.
Modified starch commands the established base. The steepest expansion runs through pharmaceutical-grade dextrin serving domestic drug manufacturers.
Application:
End-use specifications create divergent purity and documentation requirements across regulated industries.
- Food & Beverage:Processed sauce, ready meal, and beverage applications requiring viscosity modification, texture stabilization, or fat replacement. Reformulation activity concentrates in India and China as FSSAI labeling mandates and GB 2760 purity standards compress synthetic additive tolerance.
- Pharmaceuticals:Tablet binding, disintegration control, and excipient functions demanding pharmacopeia compliance across multiple national standards. Domestic drug companies in Shanghai and Osaka are expanding excipient procurement for oral solid dosage formulations.
- Personal Care:Film-forming and viscosity-building applications in cosmetic and topical formulations.
- Animal Feed:Energy supplementation in livestock and aquaculture rations where cost per megajoule dominates supplier selection.
Food and beverage applications anchor volume demand. Pharmaceutical applications are climbing fastest on excipient-grade certification requirements.
End User:
Customer type determines procurement sophistication, with multinational formulators demanding integrated technical service that regional traders cannot supply.
- Food Manufacturers:Multinational sauce, convenience meal, and beverage producers operating Southeast Asian manufacturing hubs. These buyers prioritize regional supplier qualification to reduce import dependency and secure formulation lab support for clean-label transitions.
- Drug Companies:Domestic pharmaceutical manufacturers in China and Japan requiring excipient-grade dextrin with full pharmacopeia documentation. Procurement teams manage simultaneous NMPA, PMDA, and CDSCO submission requirements.
- Cosmetic Brands:Personal care formulators seeking film-forming starches for skin and hair applications.
- Livestock Producers:Feed compounders and integrated animal operations prioritizing native starch for caloric density in ration formulations.
Food manufacturers represent the volume anchor. Drug companies are expanding procurement most aggressively on domestic pharmaceutical production growth.
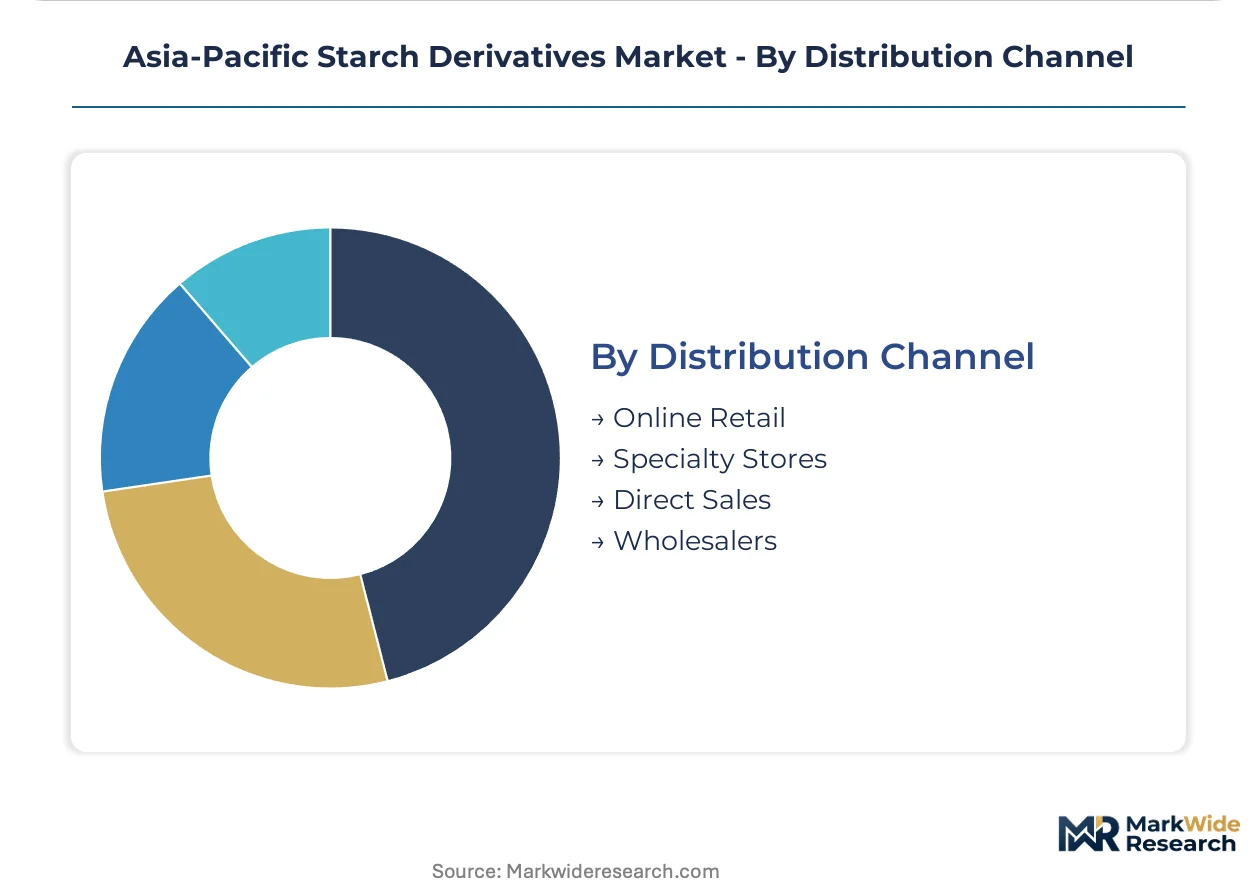
Distribution Channel:
Supply concentration varies by customer scale and technical service requirements.
- Direct Sales:Long-term supply contracts between starch derivative producers and multinational food or pharmaceutical manufacturers. These relationships embed technical service agreements for formulation support and regulatory documentation.
- Wholesalers:Regional distributors serving mid-scale food processors and feed compounders with standardized product grades and shorter procurement cycles.
- Specialty Stores:Niche channels for small-batch or certified organic starch derivatives targeting premium food manufacturers.
- Online Retail:Emerging procurement path for small-scale cosmetic brands and research quantities, though pharmaceutical and large food volumes remain offline.
Direct sales channels capture the premium tier. Wholesalers are gaining share fastest among mid-scale regional processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across the Asia-Pacific region diverge sharply by end-use priority. China and Japan concentrate pharmaceutical-grade procurement, while India and Southeast Asian markets prioritize cost-optimized feed and food applications.
China
Domestic drug manufacturers in Shanghai and Beijing are expanding excipient-grade dextrin procurement for oral solid dosage formulations. GB standards for food additive purity are tightening residual solvent limits, forcing purification stage upgrades. The Yangtze River Delta cluster hosts concentrated modified starch production serving both pharmaceutical and processed food exporters.
India
Livestock producers in Gujarat and Maharashtra prioritize native starch for caloric density in poultry and dairy rations. FSSAI labeling mandates on food additive disclosure are accelerating reformulation toward clean-label alternatives in processed sauce manufacturing. The National Capital Region anchors formulation lab activity supporting multinational food manufacturers.
Japan
Osaka-based pharmaceutical manufacturers demand JIS-certified excipient grades with full PMDA documentation for tablet binding applications. METI chemical substance management frameworks are elevating manufacturing protocol requirements. The Kansai industrial corridor maintains premium positioning through certified production facilities serving domestic drug companies.
Thailand
Cassava processors in the Central Plains are securing long-term supply contracts with regional formulation labs for modified starch viscosity consistency. Thai tapioca chip export demand fluctuates with Chinese ethanol policy shifts, creating feedstock price volatility. Bangkok anchors technical service networks for Southeast Asian food exporters.
Vietnam
Foreign direct investment in Ho Chi Minh City and Hanoi manufacturing hubs is generating localized modified starch demand for sauce and convenience meal production. Multinational producers seek regional suppliers to reduce import dependency from Thai sources. The Mekong Delta supplies raw cassava feedstock to domestic processors.
Asia-Pacific Starch Derivatives Market Competitive Environment
Capability concentration sits with integrated multinationals; scale advantage sits with regional processors anchored to raw material sources. The vendor base stratifies across three tiers: global suppliers with formulation lab networks, mid-scale regional producers with captive tapioca supply, and commodity traders serving price-sensitive feed applications. Dominant competitive moves include backward integration into Thai cassava sourcing and enzymatic technology licensing for reduced-energy processing systems.
Within the integrated multinational tier, Cargill, Ingredion, and Japan Corn Starch occupy positions defined by supply chain control and certification depth. Cargill exemplifies upstream integration from Thai tapioca sourcing through regional formulation labs. Ingredion represents technology leadership in specialty dextrin production for pharmaceutical applications. Japan Corn Starch anchors premium-tier positioning through JIS-certified manufacturing protocols serving domestic food and drug manufacturers.
| Leading Market Players |
|---|
| AGRANA |
| Manildra Group |
| Cargill |
| Gulshan Polyols |
| Japan Corn Starch |
| Ingredion |
| Angel Starch and Food |
| Sukhjit Starch & Chemicals |
| Tate & Lyle |
| Others |
Value Chain & Pricing Dynamics
The Central Plains cassava processing cluster in Thailand translates raw material dominance into pricing leverage over Southeast Asian food manufacturers seeking viscosity-consistent modified starch. When Thai tapioca chip export demand spikes on Chinese ethanol policy shifts, derivative producers face feedstock cost surges that compress margins without immediate formula price adjustment mechanisms.
Pricing Analysis
Long-term offtake contracts between Thai cassava processors and regional formulation labs anchor pricing stability for multinational food manufacturers, while spot procurement serves mid-scale Indian feed compounders prioritizing cost over consistency. Pharmaceutical-grade dextrin draws premium-mid-economy pricing differentiation based on residual solvent documentation depth for NMPA versus PMDA submissions. Pricing pressure stems from alternative sweetener displacement in beverage applications where stevia and monk fruit extracts erode starch syrup volumes. Livestock producers in Gujarat and Maharashtra exhibit highest price sensitivity, prioritizing energy density per unit cost; drug companies in Shanghai and Osaka show lowest sensitivity, accepting purity premiums for excipient-grade certification.
Supply Chain Analysis
Export-control regimes on enzymatic conversion technology from Japanese and South Korean equipment suppliers limit processing efficiency gains for regional producers outside licensing networks. Raw material flows concentrate in Thailand, India, and Vietnam, with cassava chip and corn starch feedstocks drawing from agricultural harvest cycles. Supply chain risk centers on single-source vulnerability when Thai tapioca processors face simultaneous domestic ethanol and export starch derivative demand surges. Distribution runs through direct sales channels for pharmaceutical and multinational food accounts, with wholesalers gaining share among mid-scale regional processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized formulation chemists commanding premium compensation for simultaneous enzymatic modification and pharmaceutical excipient compliance expertise represent the critical scarcity constraining regional producer expansion.
For Market Incumbents: Entrench through backward integration into Thai cassava sourcing and captive enzymatic technology licensing to defend against multinational laboratory networks poaching technical talent. Prioritize JIS and GB 2760 certification investments to maintain premium positioning as METI and SAMR tighten residual solvent documentation requirements. For New Entrants and Emerging Players: Pursue Vietnam's processed food manufacturing expansion as the most penetrable geography, where foreign direct investment in Ho Chi Minh City and Hanoi generates localized modified starch demand currently served by Thai imports. Target enzymatic conversion system pilot partnerships with Japanese and South Korean food manufacturers seeking carbon reduction compliance. For Investors and Strategic Acquirers: Long-term, this sits as a certification-depth play because pharmaceutical-grade dextrin procurement by domestic drug companies in China and Japan concentrates on producers with simultaneous NMPA, PMDA, and CDSCO submission capabilities. Watch enzymatic processing technology licensing agreements as the signal indicating which regional producers can collapse batch cycle times and capture specialty starch margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cassava Sourcing | Thai processors securing long-term contracts gain feedstock cost predictability against ethanol policy volatility. |
| Enzymatic Conversion Technology Licensing | Japanese and South Korean equipment suppliers enable regional producers to meet corporate carbon reduction targets. |
| Pharmaceutical-Grade Certification Investment | Producers achieving NMPA and PMDA documentation depth capture excipient premiums from Shanghai and Osaka drug companies. |
| Regional Formulation Lab Expansion | Vietnam-based technical service networks reduce import dependency for multinational sauce and convenience meal producers. |
| Clean-Label Reformulation Partnership | Suppliers supporting FSSAI and GB 2760 compliance displace synthetic hydrocolloids in Southeast Asian retail channels. |
Study Parameters
A spread of perspectives from starch processing plant managers, procurement leads at multinational food manufacturers, pharmaceutical regulatory affairs directors, and Thai cassava cooperative representatives converged on the working assumptions. Primary fieldwork combined with secondary validation from customs and trade data, FSSAI additive disclosure filings, NMPA excipient registration databases, and GB standards documentation. Bottom-up capacity assessments across Thai, Indian, and Vietnamese processing facilities triangulated against top-down demand modeling from food, pharmaceutical, and feed end-use segments.
Demand-supply-balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning product grade tier, end-use application, and regional regulatory cluster. CAGRs emerged from iterative convergence of capacity expansion timelines, feedstock price trajectory assumptions, and substitution elasticity estimates for synthetic hydrocolloids. Industry-specific inputs included enzymatic technology adoption curves and pharmaceutical certification backlog durations.
Sensitivities concentrate around Thai tapioca chip export demand fluctuations, FSSAI labeling mandate enforcement intensity, and enzymatic processing technology licensing accessibility. Forecasts reflect documented assumptions on feedstock cost pass-through mechanisms and regulatory documentation burden escalation. Material shifts in Chinese ethanol policy or METI chemical substance management framework revisions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
North America N-Hexane Market
Bulk Chemicals
Vinyl Cyclohexane Market
Bulk Chemicals
Calcium Lactate Market
Bulk Chemicals
Isopentane Market
Bulk Chemicals
Butachlor Market
Bulk Chemicals
Sodium Tungstate Dihydrate Market
Bulk Chemicals
North America Starch Derivatives Market
Bulk Chemicals
Tributyl Citrate Market
Bulk Chemicals
Dimethyl Disulphide (DMDS) Market
Bulk Chemicals
Germany Propylene Glycol Market
Bulk Chemicals
Europe Methyl Acrylate Market
Bulk Chemicals
Global Phosphoric Acid Market
Bulk Chemicals
United States Calcium Carbonate Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Copper Sulphate Market
Bulk Chemicals
Propionaldehyde Market