
 Global Levulinic Acid Market | 2026-2036
Global Levulinic Acid Market Size, Share, and Industry Trends Forecast 2026-2036
Global Levulinic Acid Market Foresight
Pharmaceutical-grade levulinic acid is bifurcating the competitive landscape as buyers tighten purity thresholds for high-value derivatives. GFBiochemicals leverages its commercial biorefinery footprint in Italy to anchor European supply security. Biofine Technology LLC specializes in acid-catalysis reactor design that sustains cost advantages at scale. DuPont de Nemours navigates multi-industry demand by extending its specialty chemicals portfolio into bio-based platform molecules.
Levulinic acid is a C5 organic acid synthesized from hexose dehydration, typically featuring a keto group at the gamma position and a carboxylic acid terminus, with industrial production favoring sulfuric acid catalysis of biomass-derived carbohydrates at controlled temperature and pressure to yield platform chemicals for solvents, plasticizers, and fuel oxygenates. Industrial grade currently dominates volume throughput due to established offtake from chemical manufacturing, while pharmaceutical grade captures disproportionate margin pools as purity certifications command price premiums from personal care producers. The biorefinery process segment is expanding fastest as integrated crop-to-chemical configurations reduce feedstock logistics costs for agrochemical companies.
EPA bio-preferred program standards and REACH registration requirements in Europe are tightening disclosure thresholds for petrochemical-derived intermediates, redirecting procurement budgets toward certified bio-based levulinic acid. FDA food-contact substance notifications and EFSA novel food assessments further delineate grade-specific market access corridors for animal feed additive applications. Stakeholders must monitor evolving biorefinery carbon intensity accounting methodologies to preserve eligibility under emerging green procurement frameworks.
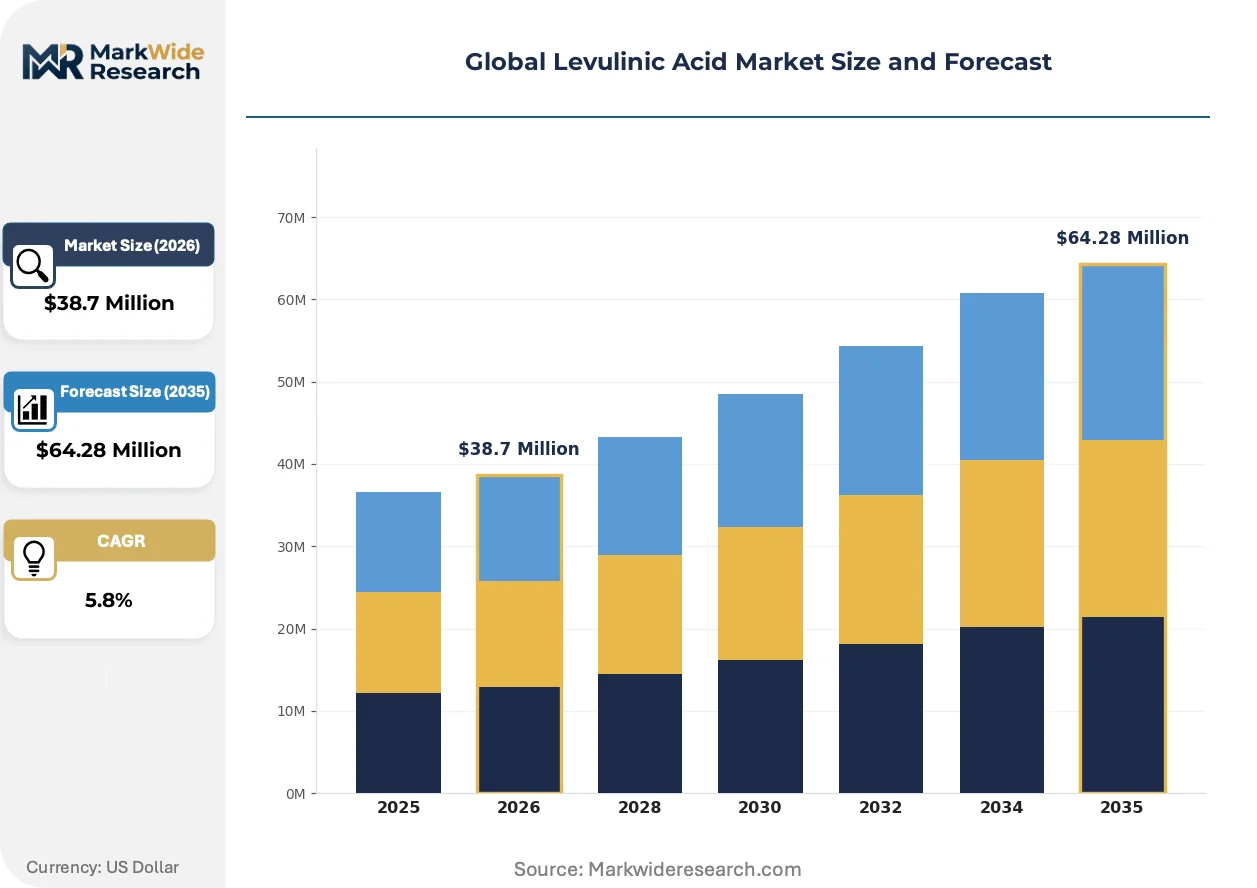
Market Dynamics
Pharmaceutical-grade purity thresholds are bifurcating the levulinic acid market as biofuel producers and personal care formulators impose certification requirements that industrial-grade suppliers cannot meet. This specification divergence is compressing margins for commodity producers while creating premium capture opportunities for biorefinery operators with integrated purification capabilities.
Growth Catalysts
- EU Green Deal bio-based mandates:Brussels' binding targets for renewable feedstocks in transport fuels are redirecting procurement budgets toward certified levulinic acid for fuel oxygenate applications.
- Cellulosic feedstock processing:Second-generation biorefinery technology unlocking agricultural residue streams is reducing raw material costs for platform chemical production in the US Corn Belt.
- Personal care certification requirements:EFSA novel food assessments and FDA food-contact substance notifications are creating preferential market access corridors for pharmaceutical-grade material in animal feed additives.
Market Restraints
- Sulfuric acid input volatility:Concentrated acid procurement costs fluctuate with sulfur commodity markets, squeezing conversion economics for acid-catalysis reactor operators.
- Biorefinery supply concentration:Commercial-scale production clusters in Italy and Germany create geographic vulnerability for European offtake agreements.
- Petrochemical substitution persistence:Fossil-derived adipic acid and succinic acid retain cost advantages in plasticizer applications where bio-based premiums are not mandated.
Strategic Opportunities
- India specialty chemical demand:BIS certification pathways for bio-based platform molecules remain underdeveloped, offering first-mover positioning for pharmaceutical-grade suppliers.
- Agrochemical integrated formulations:Crop-to-chemical biorefinery configurations are reducing logistics costs for herbicide intermediate producers seeking captive levulinic acid supply.
- REACH registration tailwinds:ECHA disclosure threshold tightening for petrochemical intermediates is redirecting formulation R&D budgets toward bio-based alternatives with established safety dossiers.
Industry Challenges
- Bioprocess engineering talent scarcity:Skilled operators for continuous acid-catalysis reactor systems command wage premiums that inflate operating expenditures for new market entrants.
- Pharmaceutical-grade certification timelines:FDA cGMP facility inspections and EMA active substance master file approvals extend market access timelines by 18-24 months for greenfield producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Levulinic Acid Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $64.28 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Food Grade, Pharmaceutical Grade, Cosmetic Grade Application: Plasticizers, Solvents, Fuel Additives, Agricultural Chemicals, Animal Feed Additives Manufacturing Process: Acid Catalysis, Enzymatic Conversion, Biorefinery Process, Hydrothermal Process End User Industry: Chemical Manufacturing, Personal Care Producers, Biofuel Producers, Agrochemical Companies |
| Companies Covered | Biofine Technology LLC, Avantium, GFBiochemicals, DuPont de Nemours, Eastman Chemical Company, Zibo Changlin Chemical, NXTLEVVEL Biochem, Segetis, Hebei Yanuo Bioscience, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Levulinic Acid Market Shifts & Advancements
Process intensification and regulatory disclosure requirements are reshaping competitive positioning in levulinic acid production. Technology developers are prioritizing modular reactor designs that reduce capital deployment risk, while downstream formulators are consolidating supplier relationships around certified biorefinery partners.
Continuous flow acid-catalysis reactor technology is fragmenting the traditional batch-processing paradigm in levulinic acid manufacturing. Specialty chemical producers in Germany and the Netherlands are adopting these systems to reduce thermal degradation losses during hexose dehydration. The technology is fragmenting equipment vendor relationships as incumbent stirred-tank suppliers lose share to microreactor engineering specialists.
EPA bio-preferred program standards are tightening disclosure thresholds for federal procurement of bio-based intermediates. US government purchasing guidelines now require third-party certification for platform chemicals used in solvent and plasticizer applications. Federal supply contractors are responding by qualifying pharmaceutical-grade levulinic acid despite industrial-grade availability at lower unit cost.
Buyer consolidation among agrochemical formulators is compressing supplier qualification cycles and extending contract durations. Multinational crop protection companies are reducing approved vendor lists from twelve to three levulinic acid sources, favoring biorefinery operators with integrated hexose supply chains. This concentration is most visible in the US Midwest, where seed-chemical integration has created captive demand for platform molecule intermediates.
Global Levulinic Acid Market Segmentation
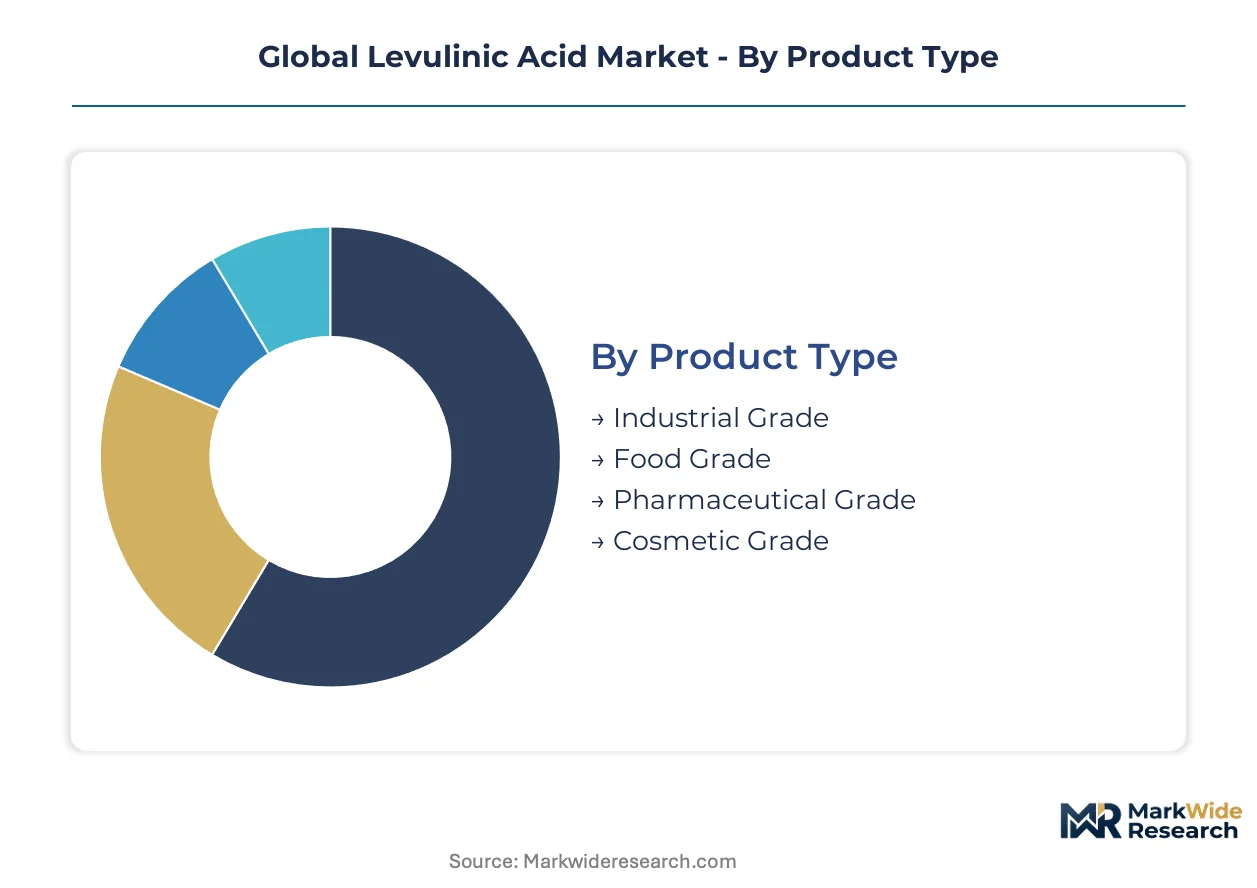
Levulinic acid specifications diverge sharply across regulatory jurisdictions, with FDA food-contact notifications and REACH registration requirements creating distinct market access corridors. Grade-specific purity thresholds determine eligibility for fuel oxygenates, personal care formulations, and animal feed applications.
Product Type:
REACH registration and FDA cGMP certification requirements bifurcate procurement budgets between commodity and premium grades.
- Industrial Grade:Sulfuric acid-catalyzed production yields 95-98% purity material for solvent and plasticizer manufacturing. Chemical manufacturers in Germany and the US Midwest absorb the majority of volume for adipic acid replacement applications.
- Pharmaceutical Grade:Purification to 99.5%+ purity via crystallization or chromatography satisfies EMA active substance master file requirements. Personal care producers in France and Switzerland command price premiums for certified bio-based platform molecules.
- Food Grade:EFSA novel food assessments and FDA food-contact substance notifications govern animal feed additive applications.
- Cosmetic Grade:ISO 16128 natural origin certification supports preservative and pH adjuster formulations.
Industrial grade handles the majority of throughput; pharmaceutical grade is gaining share fastest on margin expansion.
Application:
End-use demand concentrates where bio-based mandates override petrochemical cost advantages.
- Plasticizers:Levulinic acid esters displace phthalates in PVC compounding for medical devices and food packaging. EU Green Deal bio-based procurement targets redirect German automotive supplier budgets toward certified alternatives.
- Fuel Additives:Ethers and esters function as oxygenates in gasoline blending. Italian biofuel producers leverage GFBiochemicals' commercial biorefinery output to meet Brussels' renewable transport fuel quotas.
- Solvents:Dipolar aprotic solvent applications in electronics cleaning face competition from petrochemical NMP.
- Agricultural Chemicals:Herbicide intermediates and plant growth regulators consume platform molecule derivatives.
- Animal Feed Additives:Sodium levulinate preservative applications require pharmaceutical-grade certification for EU market access.
Fuel additives and plasticizers together dominate volume offtake; fuel additives are climbing the fastest on regulatory tailwinds.
Manufacturing Process:
Process selection determines capital intensity, feedstock flexibility, and carbon intensity accounting eligibility.
- Biorefinery Process:Integrated crop-to-chemical configurations process lignocellulosic agricultural residues. Agrochemical companies in the US Corn Belt reduce logistics costs through captive hexose supply chains.
- Acid Catalysis:Concentrated sulfuric acid dehydration of C6 sugars operates at 150-200°C with continuous reactor designs. Biofine Technology LLC's reactor engineering sustains cost leadership for commodity-grade output.
- Enzymatic Conversion:Cellulase cocktails hydrolyze biomass under milder conditions, reducing thermal degradation losses.
- Hydrothermal Process:Subcritical water treatment avoids acid input costs but requires corrosion-resistant reactor metallurgy.
Acid catalysis handles the majority of throughput; biorefinery process is expanding most quickly on integrated feedstock economics.
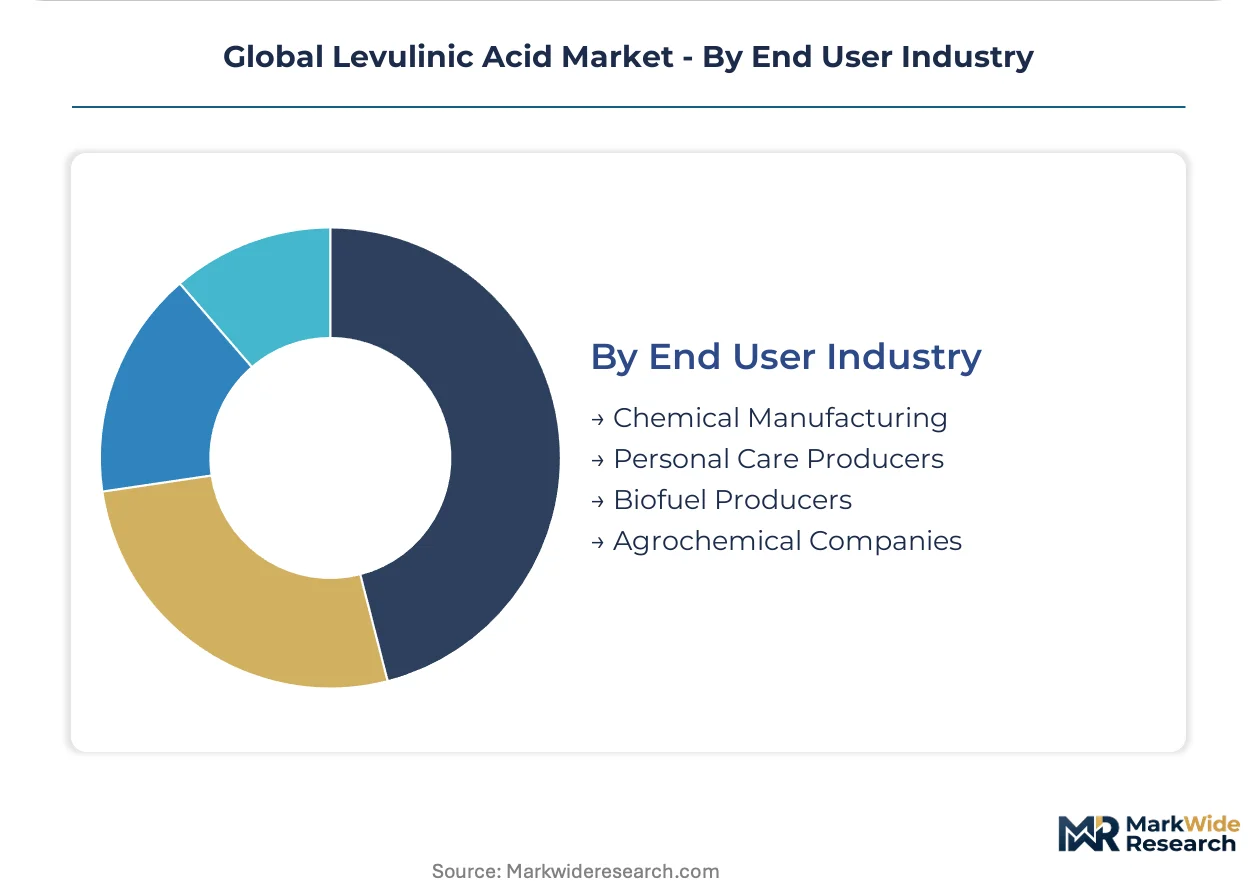
End User Industry:
Customer consolidation and supplier qualification cycles favor biorefinery operators with integrated purification capabilities.
- Chemical Manufacturing:Commodity solvent and plasticizer producers prioritize unit cost over certification. German adipic acid replacement applications absorb industrial-grade volume at thin margins.
- Biofuel Producers:EU renewable fuel mandates require mass-balance certification for oxygenate feedstocks. Italian and German blenders qualify pharmaceutical-grade material despite industrial-grade availability.
- Personal Care Producers:ISO 16128 and ECOCERT natural origin standards drive specification tightening for preservative applications.
- Agrochemical Companies:Seed-chemical integration in the US Midwest creates captive demand for herbicide intermediates.
Chemical manufacturing handles the majority of throughput; biofuel producers are gaining share fastest on mandate-driven procurement redirection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial-scale biorefinery capacity clusters in Italy and Germany, creating geographic concentration that exposes European offtake agreements to single-source vulnerability. Procurement managers in biofuel and agrochemical sectors are diversifying supplier relationships across North American and Asian production nodes to mitigate this risk.
Germany
Industrial-grade levulinic acid demand from adipic acid replacement applications anchors chemical manufacturing throughput in the Rhine-Ruhr industrial corridor. ECHA REACH registration requirements tighten disclosure thresholds for petrochemical-derived intermediates, redirecting formulation R&D budgets toward certified bio-based alternatives. The KBA and federal environment ministry coordinate enforcement of EU Green Deal bio-based mandates for transport fuel applications.
United States
Cellulosic feedstock processing in the Corn Belt unlocks agricultural residue streams for second-generation biorefinery operations. EPA bio-preferred program standards now require third-party certification for platform chemicals used in federal solvent and plasticizer procurement. Seed-chemical integration across Iowa and Illinois creates captive demand for herbicide intermediates from integrated crop-to-chemical configurations.
Italy
GFBiochemicals operates commercial-scale biorefinery facilities that supply pharmaceutical-grade material to EU biofuel producers meeting renewable transport fuel quotas. EFSA novel food assessments govern animal feed additive applications requiring certified purity thresholds. The Po Valley chemical cluster concentrates acid-catalysis reactor capacity for commodity-grade output serving Mediterranean plasticizer markets.
China
Sulfuric acid-catalyzed production from dedicated chemical manufacturers feeds industrial-grade demand across Asia-Pacific solvent and plasticizer applications. MIIT industrial policy guidance under dual carbon goals incentivizes biomass-derived platform molecule development. The Yangtze River Delta chemical corridor hosts concentrated acid-catalysis reactor capacity serving domestic adipic acid replacement demand.
India
Specialty chemical demand for pharmaceutical-grade levulinic acid remains underpenetrated as BIS certification pathways for bio-based platform molecules stay underdeveloped. CDSCO and FSSAI regulatory frameworks for food-contact and feed additive applications create compliance barriers for uncertified imports. Maharashtra and Gujarat chemical parks attract first-mover positioning from international suppliers seeking early-mover advantage in emerging certification corridors.
Global Levulinic Acid Market Competitive Landscape
Concentration sits with integrated biorefinery operators and acid-catalysis technology licensors that control commercial-scale production nodes. The vendor base splits between commodity-grade producers competing on unit cost and pharmaceutical-grade specialists capturing certification-driven price premiums. Three archetypes dominate: crop-to-chemical biorefinery integrators, acid-catalysis reactor engineering specialists, and diversified specialty chemical portfolios extending into bio-based platform molecules. Capacity expansion and strategic technology licensing represent the dominant competitive moves as new entrants seek to bypass 18-24 month pharmaceutical-grade certification timelines.
Among North American technology developers, Biofine Technology LLC exemplifies the acid-catalysis reactor engineering archetype with continuous flow system designs. GFBiochemicals anchors the integrated biorefinery tier through its Italian commercial production footprint. DuPont de Nemours occupies a position within diversified specialty chemical portfolios extending into bio-based platform molecules. These three represent distinct strategic postures without implying specific market share or operational claims.
| Leading Market Players |
|---|
| Biofine Technology LLC |
| Avantium |
| GFBiochemicals |
| DuPont de Nemours |
| Eastman Chemical Company |
| Zibo Changlin Chemical |
| NXTLEVVEL Biochem |
| Segetis |
| Hebei Yanuo Bioscience |
| Others |
Supply & Pricing Matrix
REACH registration and FDA cGMP certification regimes gate both supply qualification and price differentiation simultaneously, forcing buyers to pay certification premiums or accept restricted market access. Pharmaceutical-grade levulinic acid commands substantial premiums over industrial-grade material because EMA active substance master file requirements and EPA bio-preferred standards create non-substitutable procurement corridors for fuel oxygenate and personal care applications.
Pricing Analysis
REACH and FDA cGMP requirements dictate the pricing tier structure across the levulinic acid market. Three-tier pricing separates pharmaceutical-grade from industrial-grade from food-grade material, with certification level and volume scale as the primary differentiation drivers. Cost compression in industrial-grade supply is intensifying because sulfuric acid input volatility squeezes acid-catalysis reactor operators. Chemical manufacturers in Germany exhibit the highest price sensitivity, while personal care producers in Switzerland and France show the least.
Supply Chain Analysis
Italy and Germany anchor commercial-scale biorefinery production for pharmaceutical-grade levulinic acid, while China and the US concentrate acid-catalysis capacity for industrial-grade output. The supply chain draws from lignocellulosic agricultural residues, concentrated sulfuric acid, and crystallization purification equipment as critical inputs. Single-source vulnerability concentrates risk around GFBiochemicals' Italian facilities and the Po Valley chemical cluster. Distribution runs through long-term offtake agreements with qualified biorefinery partners rather than spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Levulinic acid incumbents face a substitution defense against fossil-derived adipic acid and succinic acid, which retain cost advantages in plasticizer applications wherever bio-based procurement mandates do not apply. Incumbents must navigate this threat through certification moats and captive feedstock integration.
For Market Incumbents: Secure pharmaceutical-grade certification pipelines to defend against petrochemical substitution in plasticizer markets. Expand backward integration into cellulosic feedstock processing in the US Corn Belt to reduce logistics cost exposure. GFBiochemicals demonstrates how Italian biorefinery anchoring creates supplier consolidation leverage against emerging acid-catalysis competitors. For New Entrants and Emerging Players: Lead with BIS certification pathway development in India, where specialty chemical demand for pharmaceutical-grade material remains underpenetrated. Target agrochemical integrated formulations in the US Midwest, where seed-chemical integration creates captive demand for herbicide intermediates. A go-to-market angle emphasizing REACH-registered bio-based alternatives with established safety dossiers bypasses incumbent certification timelines. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed acid-catalysis technology licensors seeking exit liquidity after commercial-scale validation. The five-to-ten-year viability window favors acquisition targets with integrated crop-to-chemical configurations and existing EMA active substance master files. The signal to watch is tightening ECHA disclosure thresholds for petrochemical intermediates, which would accelerate procurement budget redirection toward certified biorefinery operators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Corn Belt agrochemical companies reduce logistics costs through captive hexose supply chains. |
| Pharmaceutical-Grade Certification Investment | EMA active substance master file approvals unlock premium capture in EU biofuel oxygenate markets. |
| Continuous Flow Reactor Technology Licensing | Biofine Technology LLC's acid-catalysis designs sustain cost leadership for commodity-grade output. |
| Long-term Supply Agreement with Biofuel Producers | Italian blenders qualify pharmaceutical-grade material to meet Brussels' renewable transport fuel quotas. |
| Joint Venture for Indian Market Entry | Maharashtra and Gujarat chemical parks attract first-mover positioning in underdeveloped BIS certification corridors. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted to construct this analysis, combining structured interviews with biorefinery plant managers, procurement leads at agrochemical and personal care formulators, distribution channel partners, and technical R&D directors with secondary validation. Sources included customs and trade data, Cefic and ACC industry reports, SEC 10-K filings from diversified chemical portfolios, ECHA REACH registration databases, and EPA bio-preferred program certification records. Bottom-up capacity estimates and top-down demand segmentation were triangulated to reconcile volume figures.
Across the analysis window, the forecasting framework models grade tier, end-use industry, manufacturing process technology, and regional production hub as primary segmentation dimensions. CAGRs were derived through regression analysis of historical capacity expansion patterns against regulatory mandate implementation timelines. Industry-specific inputs include EFSA novel food assessment approval trajectories and sulfur commodity price volatility indices affecting acid-catalysis conversion economics.
Forecasts assume regulatory continuity in REACH, FDA cGMP, and EPA bio-preferred regimes; material policy shifts would require re-modeling. Specific risks that could revise projections include sulfuric acid supply disruptions, biorefinery carbon intensity accounting methodology changes, and accelerated petrochemical substitution in non-mandated plasticizer markets. Recalibration cycles align with material shifts in EU Green Deal enforcement intensity and ECHA disclosure threshold revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Furandicarboxylic Acid Market
Bulk Chemicals
Global Purified Terephthalic Acid (PTA) Market
Bulk Chemicals
Sodium Bromide Market
Bulk Chemicals
Isovaleryl Chloride Market
Bulk Chemicals
Global Phosphoric Acid Market
Bulk Chemicals
Calcium Bromide Market
Bulk Chemicals
Natural Thickener Market
Bulk Chemicals
Palmitic Acid Market
Bulk Chemicals
Global Hexamethylenediamine Market
Bulk Chemicals
Aluminum Nitrate Nonahydrate Market
Bulk Chemicals
Aluminum Sulfate Market
Bulk Chemicals
Europe Caustic Soda Market
Bulk Chemicals
Triazine Market
Bulk Chemicals
Paraxylene(PX) Market
Bulk Chemicals
Phenylalanine Market
Bulk Chemicals
Thiodiglycol Market