
 Europe Castor Oil Market | 2026-2036
Europe Castor Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Castor Oil Market Intelligence
Petrochemical-derived emollients in European personal care is pivoting toward castor oil alternatives as brands reformulate for biodegradability credentials. Arkema leverages its polymer science heritage to anchor specialty castor derivatives for engineering plastics. Gustav Heess competes through refined pharmaceutical-grade oil output from German extraction facilities. Alberdingk Boley GmbH specializes in waterborne coating binders that incorporate dehydrated castor oil chemistry for furniture and automotive finishes.
Castor oil comprises triglycerides with ricinoleic acid occupying roughly 90 percent of fatty acid content, extracted through cold-pressing or solvent extraction of Ricinus communis seeds for lubrication, cosmetic emolliency, and polymer precursors. Natural castor oil retains dominance in European pharmaceutical and food-grade applications where unmodified purity satisfies pharmacopeia standards. Hydrogenated castor oil commands premium positioning in cosmetics as a viscosity modifier and emulsion stabilizer for lipsticks and creams. Dehydrated castor oil serves industrial coatings with oxidative polymerization properties that replace alkyd resins in solvent-reduced formulations.
REACH registration requirements govern chemical safety documentation for castor oil derivatives sold above one tonne annually, while the EU Green Deal pushes bio-based content thresholds in public procurement. ECHA substance evaluation protocols shape impurity limits for cosmetic and pharmaceutical grades, filtering non-compliant suppliers from premium segments. Stakeholders must monitor evolving F-Gas Regulation amendments that could expand castor oil's role as a biodegradable compressor lubricant alternative.
Market Dynamics
REACH compliance deadlines and the EU Green Deal's bio-based procurement mandates are compressing substitution timelines for petrochemical emollients across European personal care and industrial coatings.
Growth Catalysts
- EU Green Deal procurement thresholds:Public tenders now mandate minimum bio-based content, forcing coatings and cosmetics formulators to specify castor-derived binders and emollients.
- Pharmaceutical-grade cold-pressing:German extraction facilities are expanding capacity to meet EMA pharmacopeia purity standards for laxative and excipient applications.
- Frankfurt-Ludwigshafen industrial clustering:Chemical processing infrastructure concentration enables just-in-time hydrogenated castor oil delivery to cosmetics compounders.
Market Restraints
- Indian seed supply concentration:Over 85 percent of global castor bean cultivation sits in Gujarat, exposing European processors to monsoon yield volatility and export duty fluctuations.
- Hydrogenation energy costs:Catalytic hydrogenation of castor oil requires sustained high-pressure hydrogen, tying margin stability to natural gas pricing in German industrial parks.
- Alkyd resin substitution resistance:Coatings formulators in Southern Europe retain solvent-borne alkyd formulations where VOC regulations remain less stringent than REACH-driven Northern markets.
Strategic Opportunities
- Polish coatings manufacturing expansion:Waterborne furniture finish production near Wrocław lacks qualified dehydrated castor oil suppliers, creating first-mover positioning for REACH-registered entrants.
- F-Gas Regulation compressor lubricants:Amendments expanding biodegradable lubricant mandates open industrial refrigeration and HVAC maintenance channels for formulated castor esters.
- Pharmaceutical excipient certification:EMA's tightened elemental impurity limits favor European-extracted grades over import-dependent competitors in tablet and capsule applications.
Industry Challenges
- Ricin detection protocol standardization:Batch testing for residual toxin in pharmaceutical grades lacks harmonized EMA-EDQM methodology, delaying release timelines.
- Cold-press capacity retrofitting:Solvent extraction lines require stainless steel replacement and nitrogen blanketing systems to achieve food-grade certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Castor Oil Market |
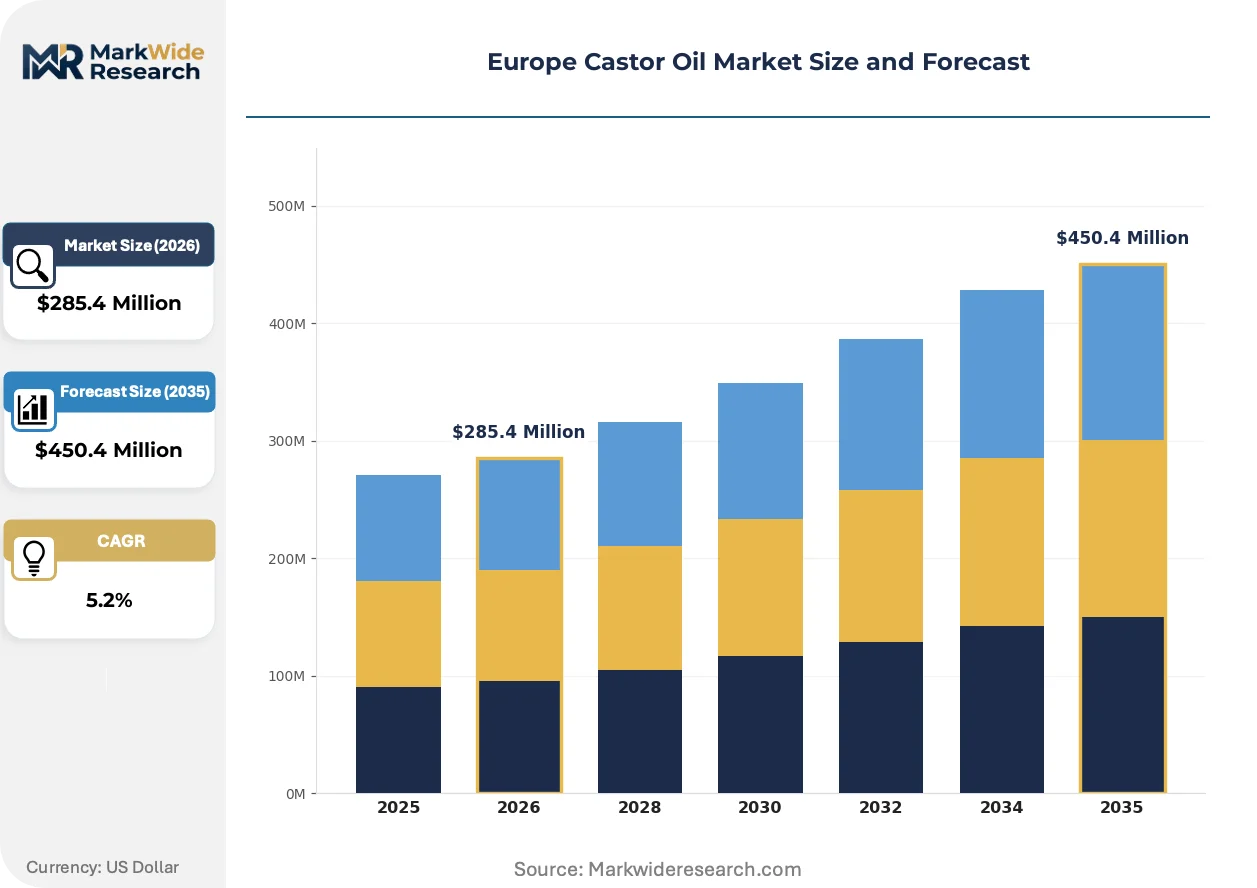
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $450.4 Million |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Castor Oil, Hydrogenated Castor Oil, Dehydrated Castor Oil, Ricinoleic Acid End User: Cosmetics, Pharmaceuticals, Food Industry, Lubricants Application: Industrial Products, Personal Care, Plastics, Coatings Distribution Channel: Online Sales, Specialty Stores, Wholesale Distributors, Direct Sales |
| Companies Covered | Gokul Agro Resources, Taj Agro, Castor, Arkema, Alberdingk Boley GmbH, Vertellus, N K Proteins, Gustav Heess, Jayant Agro-Organics, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Castor Oil Market Strategic Shifts & Innovations
Process intensification and regulatory precision are fragmenting traditional commodity trading patterns, pushing value capture toward specialty derivative production and certified supply chains.
Supercritical CO2 extraction is modularizing castor oil purification for mid-scale pharmaceutical processors. German equipment suppliers now offer skid-mounted 500-liter units that bypass hexane solvent handling permits. This distributed processing architecture is compressing capital barriers for regional compounders seeking EMA-compliant excipient sourcing.
REACH substance evaluation protocols are tightening impurity disclosure thresholds for cosmetic-grade ricinoleic acid derivatives. ECHA's 2024 updated guidance demands full supply chain contaminant mapping down to 0.1 percent w/w. Northern European personal care brands are responding by qualifying single-origin German extraction batches over blended Mediterranean supplies.
Long-term offtake contracting is displacing spot purchasing among coatings binders buyers. Automotive OEMs in Stuttgart and Munich now require 36-month dehydrated castor oil supply commitments with fixed ricinoleic acid content specifications. This preference compression is marginalizing traders lacking backward integration into seed crushing or hydrogenation assets.
Europe Castor Oil Market Segmentation
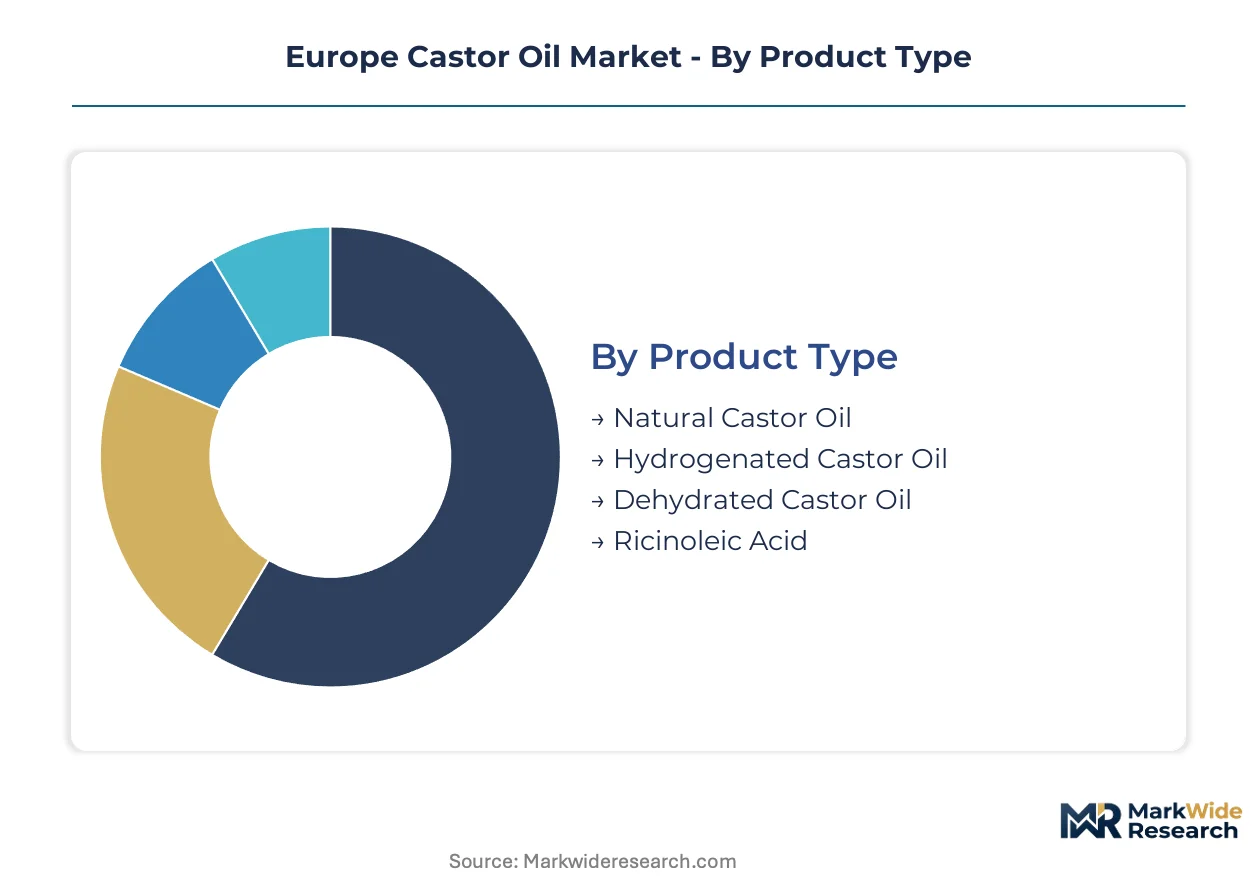
Castor oil derivatives exhibit divergent value capture depending on processing intensity and certification requirements. Segmentation reveals how hydrogenation and dehydration chemistries command premium positioning against commodity natural grades.
Product Type:
Customization intensity spans from unrefined natural oils to engineered hydrogenated derivatives requiring catalytic infrastructure.
- Natural Castor Oil:Cold-pressed triglyceride oil retaining ricinoleic acid integrity for pharmaceutical laxative and food additive applications. German extraction facilities near Stuttgart concentrate supply for EMA pharmacopeia compliance, though Indian import dependency constrains margin stability.
- Hydrogenated Castor Oil:Catalytically hardened wax-like derivative functioning as viscosity modifier and emulsion stabilizer in lipstick and cream formulations. Cosmetics compounders in Frankfurt-Ludwigshafen clusters source this grade for REACH-registered personal care lines, with hydrogen feedstock costs tied to German industrial gas pricing.
- Dehydrated Castor Oil:Thermally processed variant with conjugated double bonds enabling oxidative polymerization for alkyd resin replacement in waterborne coatings.
- Ricinoleic Acid:Fractionated fatty acid precursor for polymer intermediates and specialty ester synthesis.
Leading the category by volume: Natural Castor Oil. Expanding most quickly: Hydrogenated Castor Oil.
End User:
Regulatory stringency varies sharply across end-use segments, with pharmaceutical and food applications demanding EMA documentation that cosmetics and lubricants escape.
- Cosmetics:Formulators leverage hydrogenated grades for texture engineering in color cosmetics and skincare, driven by EU Green Deal bio-based procurement mandates for public-sector personal care tenders.
- Pharmaceuticals:Laxative and excipient applications require cold-pressed natural oil meeting EDQM monograph purity standards, with German processors expanding stainless steel cold-press capacity to displace import reliance.
- Food Industry:Food additive and flavoring applications governed by EFSA purity specifications for residual ricin and solvent limits.
- Lubricants:Biodegradable compressor and hydraulic fluids positioned for F-Gas Regulation amendment compliance in industrial refrigeration systems.
Cosmetics generates the highest value per tonne. Pharmaceuticals demonstrates the steepest certification barrier escalation.
Application:
Application segmentation tracks the migration from solvent-borne industrial formulations toward waterborne and bio-based alternatives.
- Industrial Products:Lubricant and grease formulations for machinery and automotive applications.
- Personal Care:Emollient and surfactant applications across skincare, haircare, and color cosmetics.
- Plastics:Polyamide 11 and polyurethane precursor chemistry leveraging ricinoleic acid derivatives.
- Coatings:Dehydrated castor oil serves as binder replacement in furniture and automotive finishes, with Polish manufacturing expansion near Wrocław creating supply gaps for REACH-registered dehydrated grades.
Coatings exhibits the fastest formulation switching. Personal Care sustains the most stable offtake contracting.
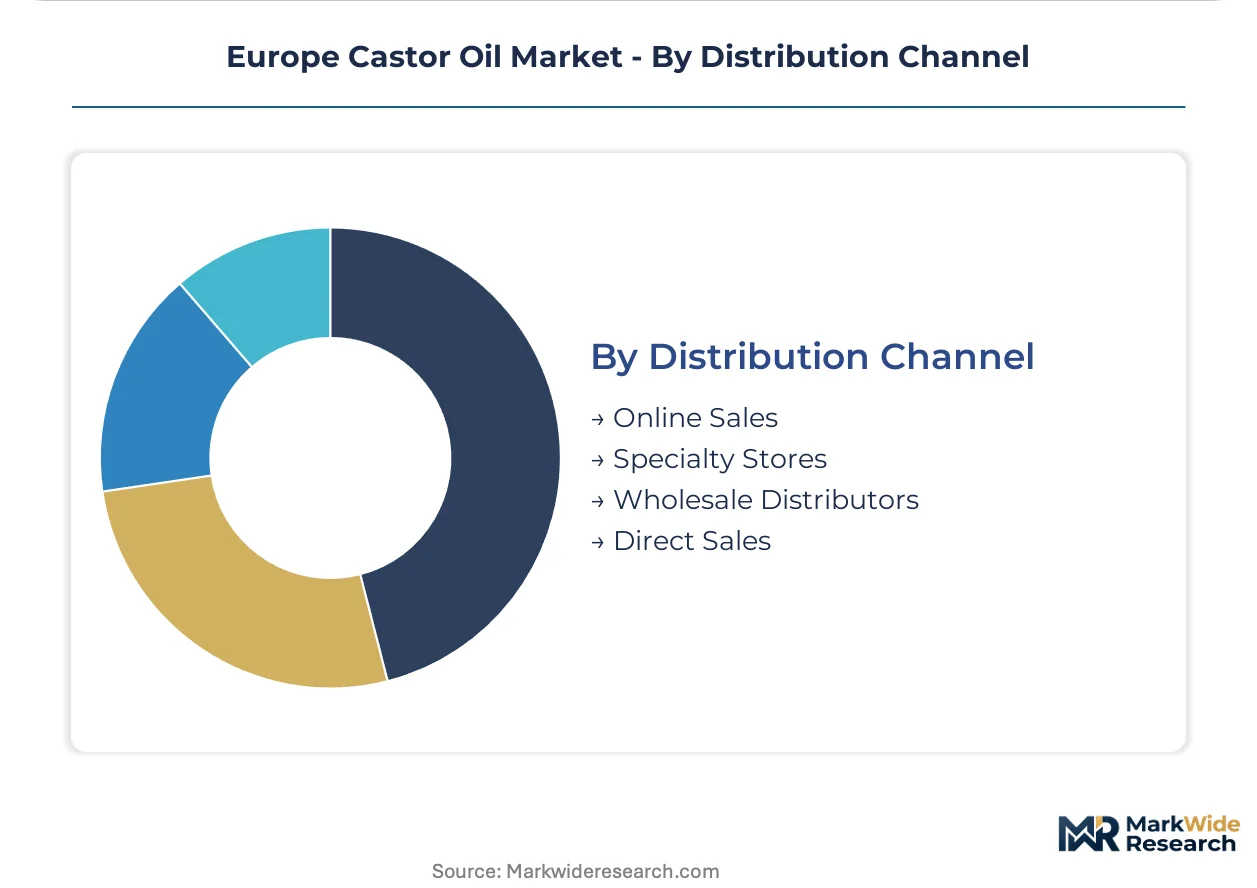
Distribution Channel:
Channel selection reflects order scale and technical service requirements, with bulk industrial buyers bypassing intermediaries.
- Online Sales:Small-volume cosmetic ingredient and DIY pharmaceutical grade purchases.
- Specialty Stores:Regional compounder supply for mid-tier coatings and personal care formulators.
- Wholesale Distributors:Aggregated supply for Southern European coatings manufacturers lacking direct processor relationships.
- Direct Sales:Long-term offtake agreements dominate automotive OEM coatings binders procurement, with Stuttgart and Munich manufacturers mandating 36-month supply commitments with fixed ricinoleic acid specifications.
Direct Sales commands the largest transaction values. Online Sales shows the fastest channel growth rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones around Frankfurt and Ludwigshafen concentrate hydrogenation capacity for cosmetics-grade derivatives. REACH registration clusters in these zones attract compounders seeking just-in-time delivery. Bio-based procurement mandates under the EU Green Deal accelerate regional capacity allocation toward certified supply chains.
Germany
Frankfurt-Ludwigshafen chemical parks host catalytic hydrogenation infrastructure for castor wax production. ECHA substance evaluation protocols drive impurity disclosure investments among local processors. Stuttgart extraction facilities expand cold-press capacity to meet EMA pharmacopeia standards for pharmaceutical applications.
France
Cosmetics formulators in the Île-de-France region specify hydrogenated grades for lipstick and cream emulsion stability. ANSM guidance on elemental impurities shapes certification requirements for pharmaceutical-grade imports. Arkema anchors polymer derivative production near Lyon for engineering plastics feedstocks.
Italy
Lombardy-based coatings manufacturers trial dehydrated castor oil in waterborne furniture finishes. REACH compliance deadlines compress reformulation timelines for solvent-borne alkyd replacements. Northern industrial clusters near Milan source refined grades through German wholesale channels.
Poland
Wrocław furniture manufacturing expansion creates supply gaps for REACH-registered dehydrated grades. EU Green Deal bio-based procurement thresholds apply to public-sector coating tenders. Domestic compounders lack qualified local suppliers, opening first-mover positioning for registered entrants.
Netherlands
Rotterdam port infrastructure handles bulk natural oil imports for redistribution across Benelux coatings markets. EFSA purity specifications govern food-grade additive applications among Dutch processors. Randstad logistics hubs enable just-in-time delivery to German hydrogenation facilities.
Europe Castor Oil Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with derivative producers commanding premium positioning against commodity traders. Hydrogenation and dehydration capabilities create tiered supply structures where catalytic infrastructure owners capture value from cosmetics and coatings formulators. Three archetypes dominate: integrated seed-to-derivative processors, toll hydrogenation operators, and regional refining specialists. Capacity expansion and REACH registration acquisition represent the dominant competitive moves, with players securing ECHA compliance ahead of substance evaluation deadlines.
Within the integrated processor tier, Arkema and Alberdingk Boley GmbH exemplify specialty derivative positioning. Arkema occupies a position anchored in polymer science heritage for engineering plastics applications. Alberdingk Boley GmbH represents waterborne coating binder specialization through German extraction infrastructure. Gustav Heess sits within the pharmaceutical-grade refining archetype, with German facility ownership supporting EMA pharmacopeia compliance positioning.
| Leading Market Players |
|---|
| Gokul Agro Resources |
| Taj Agro |
| Castor |
| Arkema |
| Alberdingk Boley GmbH |
| Vertellus |
| N K Proteins |
| Gustav Heess |
| Jayant Agro-Organics |
| Others |
Cost & Logistics Intelligence
Automotive OEM coatings buyers in Stuttgart and Munich concentrate procurement power through 36-month offtake agreements, forcing contract-based pricing models that penalize spot-market volatility. This buyer concentration compresses margin flexibility for processors lacking backward integration into hydrogenation assets.
Pricing Analysis
Short lead-time premiums dominate dehydrated castor oil transactions for Polish furniture manufacturers near Wrocław, where qualified REACH-registered suppliers command pricing stratification across premium, standard, and economy tiers. Certification grade and volume scale drive price differentiation, with EMA pharmacopeia compliance adding substantial premiums over industrial grades. Cost compression in hydrogenated wax production is intensifying because German industrial gas pricing volatility feeds directly into catalytic hydrogenation economics. Coatings compounders show highest price sensitivity due to alkyd resin substitution alternatives, while pharmaceutical excipient buyers absorb premiums for EDQM monograph compliance.
Supply Chain Analysis
Castor bean supply rests on Indian cultivation concentrated in Gujarat, Brazilian secondary production, and minimal European experimental plots. Seed crushing, solvent extraction, and catalytic hydrogenation form the critical processing dependencies. Single-source vulnerability in Gujarat monsoon-dependent yields exposes European processors to export duty fluctuations and crop failure risk. Distribution runs through Rotterdam bulk handling for natural oil, with Frankfurt-Ludwigshafen chemical parks hosting derivative production for just-in-time cosmetics delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration deadlines and ECHA substance evaluation protocols are consolidating supplier tiers, eliminating non-compliant traders from premium derivative segments. This regulatory pressure forces weaker processors toward commodity natural oil trading or exit.
For Market Incumbents: Anchor hydrogenation capacity in Frankfurt-Ludwigshafen chemical parks to defend against toll-operator competition. Secure EMA pharmacopeia certification for Stuttgart extraction facilities before EDQM tightens elemental impurity limits. Backward integration into seed crushing assets mitigates Indian supply concentration risk. For New Entrants and Emerging Players: Polish coatings distributors represent the most penetrable channel partner type for REACH-registered dehydrated castor oil supply. Target Wrocław furniture manufacturing clusters where qualified local suppliers remain absent. Position through technical service partnerships with mid-tier formulators lacking direct processor relationships. For Investors and Strategic Acquirers: The window for entry favors German hydrogenation asset owners with ECHA registration portfolios. Five-to-ten year viability hinges on EU Green Deal procurement threshold expansion. Watch F-Gas Regulation amendment timing as inflection indicator for compressor lubricant demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Registration Acquisition | ECHA compliance ahead of substance evaluation deadlines secures premium segment access. |
| Backward Integration into Seed Crushing | Captive supply of raw castor beans reduces Gujarat monsoon exposure. |
| Hydrogenation Capacity Expansion | Frankfurt-Ludwigshafen cluster infrastructure supports cosmetics-grade wax output scaling. |
| Long-term Supply Agreement | Automotive OEM coatings binders procurement mandates 36-month commitment structures. |
| Joint Venture | Polish compounder partnerships unlock Wrocław furniture finish manufacturing expansion. |
Research Approach
Trade databases, ECHA registration filings, and EU procurement records formed the secondary backbone, cross-referenced against primary interviews with hydrogenation plant managers, coatings procurement leads at automotive OEMs, cosmetics formulator R&D directors, and Rotterdam bulk commodity traders. Bottom-up and top-down triangulation validated volume estimates across derivative grades.
Bottom-up modeling tracked individual processor capacities and offtake contract coverage, while top-down analysis calibrated against EU Green Deal bio-based procurement thresholds across the analysis window. Segmentation dimensions included product type, end-use industry, application format, and regional production hub. CAGRs derived from weighted capacity expansion timelines and substitution elasticity assumptions for petrochemical emollient displacement.
Caveats apply where Indian export policy shifts or EMA ricin detection protocol standardization delays could materially shift the outlook. Forecasts embed assumptions about REACH enforcement consistency and hydrogen feedstock cost stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
PAG Base Stock Market
Bulk Chemicals
Potassium Chlorate Market
Bulk Chemicals
Sodium Carbonate Market
Bulk Chemicals
Potassium Sulphate Market
Bulk Chemicals
Global Sodium Lactate Market
Bulk Chemicals
Sodium Tetraborate Market
Bulk Chemicals
Global Acrolein Market
Bulk Chemicals
Thiodiglycol Market
Bulk Chemicals
Sodium Sulfide Market
Bulk Chemicals
Cobalt Acetate Crystals Market
Bulk Chemicals
Caproic Acid Market
Bulk Chemicals
Bulk Molding Compounds Market
Bulk Chemicals
Mercaptan Market
Bulk Chemicals
Benzyl Acetate Market
Bulk Chemicals
Pyridine Market
Bulk Chemicals
Dimethyl Terephthalate (DMT) Market