
 Soda Ash Market | 2026-2036
Soda Ash Market Size, Share, and Industry Trends Forecast 2026-2036
Soda Ash Market Intelligence
A divergence in capital intensity between natural trona mining and synthetic production methods is reorganizing the competitive landscape. Companies like Ciner Group and WE Soda leverage access to vast, low-cost natural trona reserves in the United States and Turkey. In contrast, Solvay sustains its market position through advanced synthetic process technologies and a strong European distribution network. Tata Chemicals navigates this dynamic by operating both natural and synthetic production facilities across multiple continents.
Soda ash, chemically known as sodium carbonate (Na2CO3), is an inorganic compound produced either through the Solvay process or by refining natural trona ore. It serves as a primary alkaline chemical in numerous industrial applications, acting as a fluxing agent in glassmaking and a pH regulator. Dense soda ash, required for flat and container glass, constitutes the largest product segment by volume. While glass manufacturing dominates end-use, the chemical processing sector provides a stable demand base for its use in producing silicates and phosphates.
Regulatory frameworks established by the US EPA and the EU's ECHA directly impact soda ash production, particularly concerning emissions and chemical safety. In China, MEE enforcement of environmental standards for synthetic plants influences regional supply availability and production costs. The evolving cost differential between energy-intensive synthetic processes and natural trona mining under expanding carbon regulations remains a critical strategic variable for all producers.
Market Dynamics
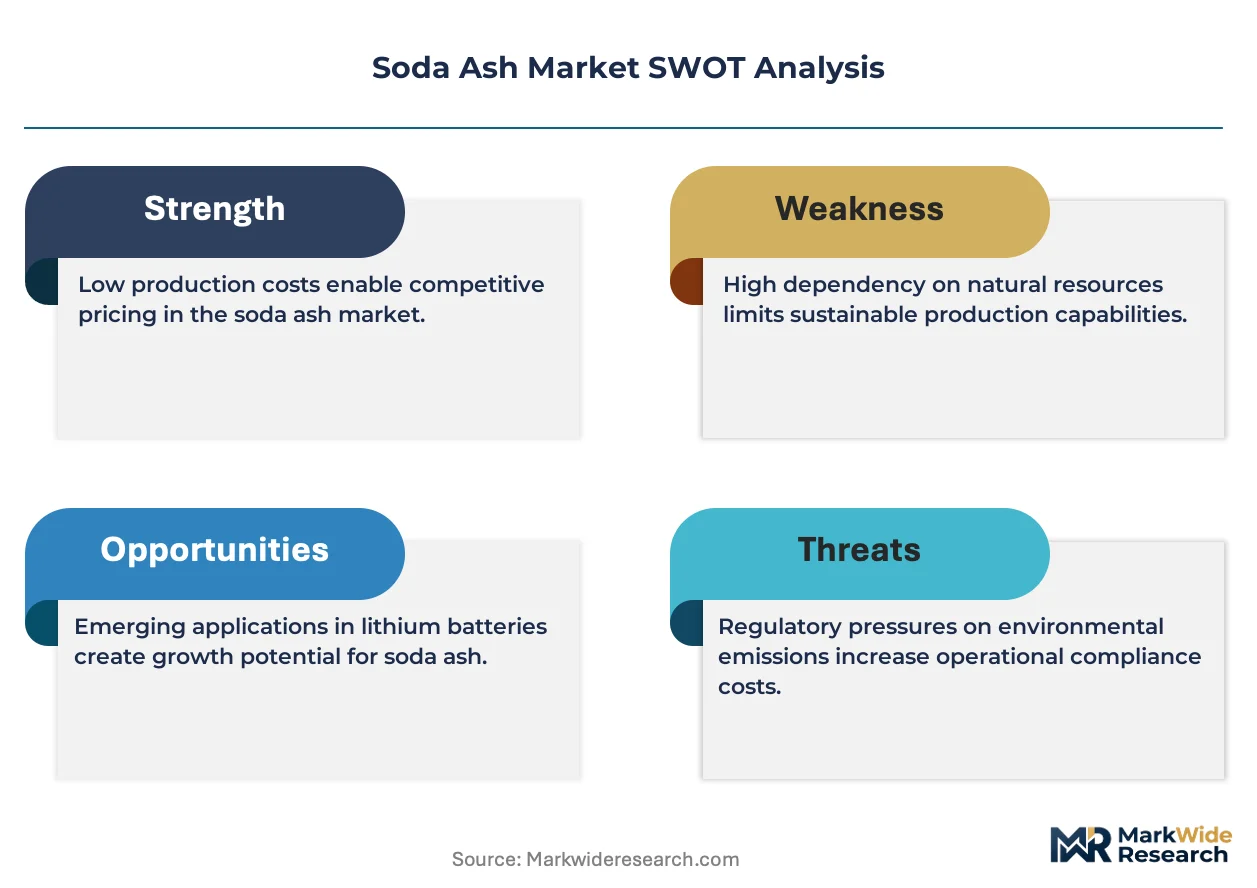
The primary structural force shaping the soda ash market is the widening operational and cost divergence between natural trona mining and energy-intensive synthetic production, a gap amplified by global carbon regulations and volatile energy markets.
Growth Catalysts
- Solar Glass Manufacturing:Demand for flat glass in solar panel production, driven by government-backed renewable energy initiatives and targets in the US, Europe, and China, provides a significant growth vector.
- Chinese Industrial Policy:China's dual carbon goals are compelling synthetic soda ash producers to invest in energy-efficient technologies and process upgrades, stimulating capital investment and modernizing regional production capacity.
- Chemical Sector Demand:Consistent consumption in the manufacturing of sodium silicates, phosphates, and other specialty chemicals for detergents and industrial cleaners creates a stable, high-volume demand base.
Market Restraints
- Energy Cost Volatility:Synthetic production via the Solvay process is highly sensitive to fluctuations in natural gas and coke prices, creating margin pressure and cost uncertainty for producers without access to natural trona.
- Geographic Supply Concentration:The world's economically viable trona reserves are heavily concentrated in the United States and Turkey, exposing the global supply chain to regional geopolitical risks and logistical bottlenecks.
- Environmental Compliance Costs:Regulations from the US EPA and the EU's ECHA impose stringent limits on emissions and waste disposal for synthetic plants, increasing operational expenses and capital requirements for compliance.
Strategic Opportunities
- Battery Materials Production:The growing need for lithium carbonate in electric vehicle batteries presents an opportunity for soda ash as a key reagent in the refining and purification process, linking the market to e-mobility growth.
- Carbon Capture Integration:Synthetic producers can retrofit facilities with carbon capture, utilization, and storage (CCUS) technology to meet emissions standards under frameworks like the EU Green Deal and potentially create new revenue streams.
- Emerging Market Industrialization:Rising industrial activity and consumer goods demand in Southeast Asia and Africa are creating new demand centers for glass, detergents, and chemicals, offering expansion opportunities for suppliers.
Industry Challenges
- Capital-Intensive Expansion:Developing new trona mining operations or constructing modern, large-scale synthetic plants requires substantial upfront capital investment, creating high barriers to entry and long lead times for new capacity.
- Logistical Complexity:Managing the global transportation of a high-volume, relatively low-value bulk chemical from concentrated production hubs to a dispersed global customer base presents significant logistical and cost challenges.
- Extended Permitting Cycles:Securing environmental and operational permits for new mining projects or synthetic facilities is a lengthy and complex process, often delaying the response to supply-demand imbalances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Soda Ash Market |
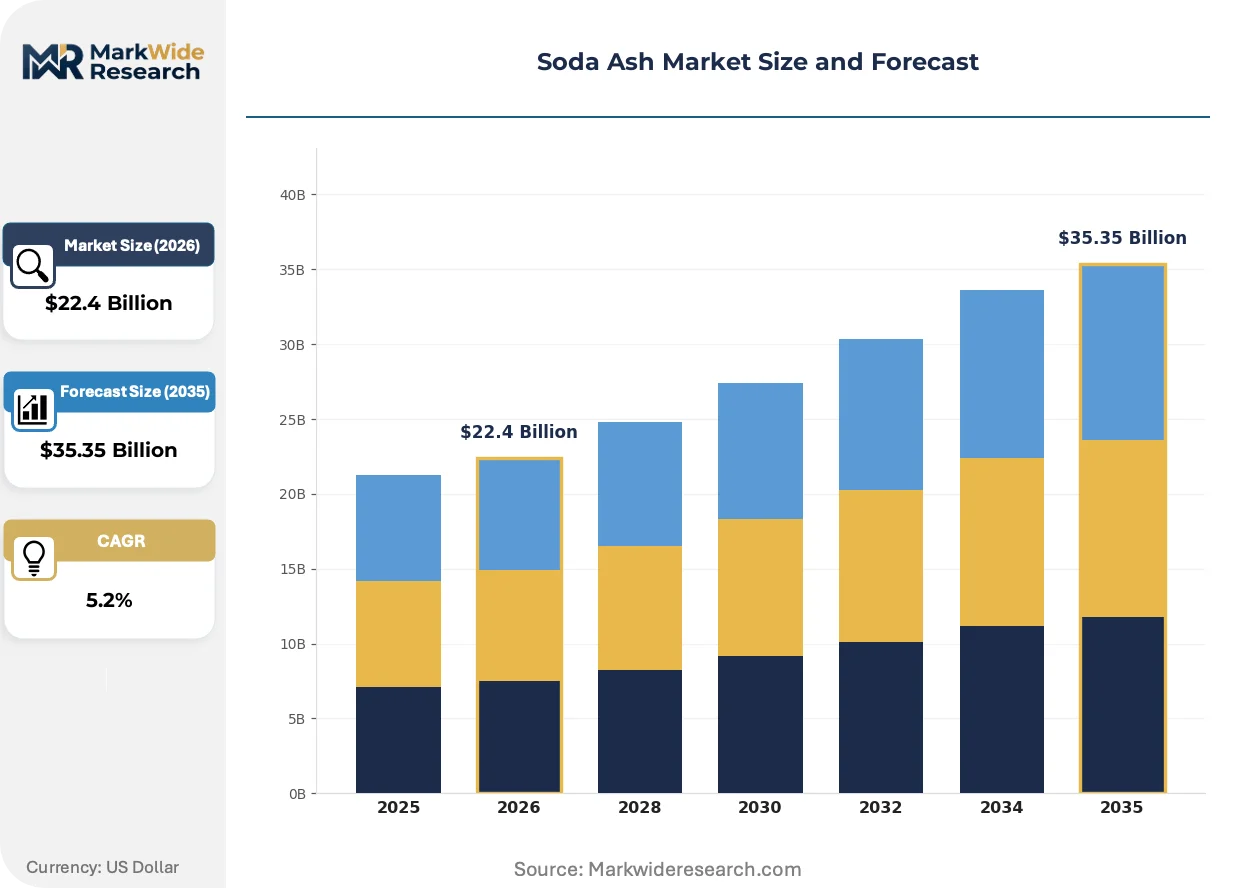
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $35.35 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Soda Ash, Dense Soda Ash, Solvay Soda Ash, Synthetic Soda Ash End Use Industry: Glass Manufacturing, Detergents Production, Chemical Processing, Water Treatment, Textile Processing Application: pH Control, Neutralization Agent, Bicarbonate Industry, Baking Powder Industry, Carbonated Beverages Packaging Type: Bulk Bags, Paper Bags, Jumbo Bags, Small Sacks |
| Companies Covered | Ciner Group, NIRMA, Solvay, Olin Corporation, Shandong Haihua Group Co., Ltd., Şişecam, WE Soda, DCW Ltd., Tata Chemicals Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Soda Ash Market Strategic Shifts & Innovations
Production economics are being redefined by a concerted push toward sustainability and process efficiency. This shift is driven by a combination of stringent environmental regulations and a clear demand signal from end-users for materials with a lower carbon footprint.
Process Intensification in Synthetic Production
Advanced purification and crystallization techniques are being developed to improve the efficiency of the Solvay process. Chemical manufacturers are adopting these innovations to reduce energy inputs, water consumption, and waste outputs per ton of soda ash produced. This focus on efficiency is displacing older, less-optimized synthetic production lines that carry a larger environmental and operational cost burden.
Carbon-Adjusted Trade Mechanisms
The European Union's Carbon Border Adjustment Mechanism (CBAM) is a pivotal policy shift impacting global trade flows. The regulation imposes a levy on carbon-intensive imports, including chemicals, to align their cost with domestically produced goods under the EU's Emissions Trading System. This policy most affects non-EU producers exporting to the region, creating a direct financial incentive to adopt lower-carbon production methods to maintain market access.
Demand for Supply Chain Transparency
End-users in consumer-facing industries are increasingly prioritizing materials with certified and traceable environmental credentials. This shift leads to procurement decisions favoring soda ash suppliers who can provide verified Environmental Product Declarations (EPDs) documenting a lower carbon footprint. The trend is most prominent in the European and North American container glass sectors, where brands use sustainable sourcing as a market differentiator.
Soda Ash Market Segmentation
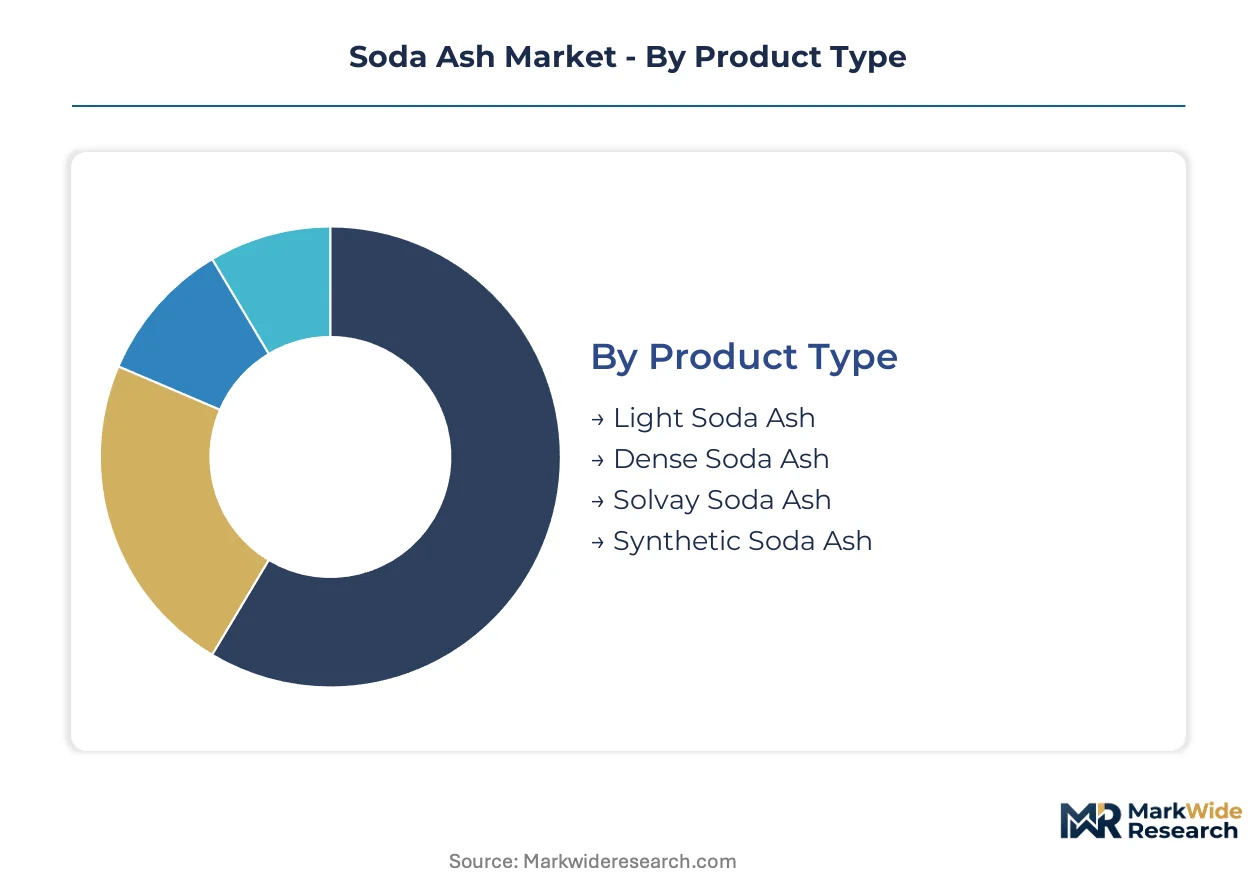
The soda ash market's segmentation reveals the diverse forms and applications of this fundamental industrial chemical. Understanding these distinct segments helps producers align their output with specific end-user requirements and regional demand patterns. Each segment presents unique challenges and opportunities for market participants.
Product Type:
The geographic concentration of production methods significantly influences the availability and trade flows of different soda ash product types.
- Light Soda Ash:This fine, white powder serves primarily in detergent formulations and specialty chemical production. Its lighter density makes it suitable for applications where rapid dissolution is beneficial.
- Dense Soda Ash:This granular, heavier form of sodium carbonate is essential for glass manufacturing due to its higher bulk density and lower dust generation. Demand for dense soda ash concentrates heavily within China's industrial provinces, driven by both domestic glass and chemical processing sectors.
- Solvay Soda Ash:Produced via the energy-intensive Solvay process, this synthetic form represents a significant portion of global supply, particularly in regions without natural trona reserves. It faces increasing cost pressures from volatile energy markets and expanding carbon regulations.
- Synthetic Soda Ash:This category encompasses all soda ash produced through chemical processes, including the Solvay method, rather than from natural trona. Its production is influenced by regional energy costs and environmental compliance standards, particularly in Europe and China.
Dense Soda Ash holds the largest share; momentum sits with Synthetic Soda Ash due to process innovation.
End Use Industry:
The soda ash market exhibits broad application diversity across various industrial sectors, each with distinct consumption profiles and growth drivers.
- Glass Manufacturing:This sector remains the largest consumer of dense soda ash, primarily for producing flat glass, container glass, and specialty glass for solar panels. Government-backed renewable energy initiatives in the US, Europe, and China provide a significant growth vector for this segment.
- Detergents Production:Soda ash serves as a builder and pH regulator in detergent formulations, enhancing cleaning efficiency and water softening. Consistent consumption in the manufacturing of sodium silicates and phosphates creates a stable demand base.
- Chemical Processing:This segment utilizes soda ash as a key raw material for producing a wide array of chemicals, including sodium silicates, sodium phosphates, and sodium bicarbonate. The sector provides a stable demand base for its use in producing silicates and phosphates.
- Water Treatment:Soda ash helps adjust pH levels and remove heavy metals and hardness from water in municipal and industrial treatment facilities. Environmental regulations drive consistent demand for this essential chemical.
- Textile Processing:In the textile industry, soda ash is used in dyeing, scouring, and bleaching processes to maintain alkaline conditions. This application supports fabric preparation and finishing.
Glass Manufacturing accounts for the largest volume; Chemical Processing exhibits steady consumption patterns.
Application:
Specific applications contribute varying volumes to the overall soda ash market, reflecting their industrial scale and necessity.
- pH Control:Soda ash is widely employed as an alkaline agent to adjust and maintain pH levels in various industrial processes, including water treatment and chemical reactions. This fundamental function underpins demand across multiple sectors.
- Neutralization Agent:Industries use soda ash to neutralize acidic waste streams and byproducts, ensuring environmental compliance and process safety. Its effectiveness as a neutralizer is critical in chemical and manufacturing operations.
- Bicarbonate Industry:Soda ash serves as a primary raw material for producing sodium bicarbonate, which finds use in food, pharmaceuticals, and animal feed. This segment links soda ash demand to consumer product manufacturing.
- Baking Powder Industry:As a precursor to sodium bicarbonate, soda ash indirectly supports the baking powder industry, providing leavening agents for food production. Food safety standards influence demand in this area.
- Carbonated Beverages:Soda ash is used in the production of sodium bicarbonate, which is then used as a carbonating agent in various soft drinks. This application connects soda ash to the consumer beverage market.
pH Control represents the largest functional use; Neutralization Agent applications are expanding most quickly.
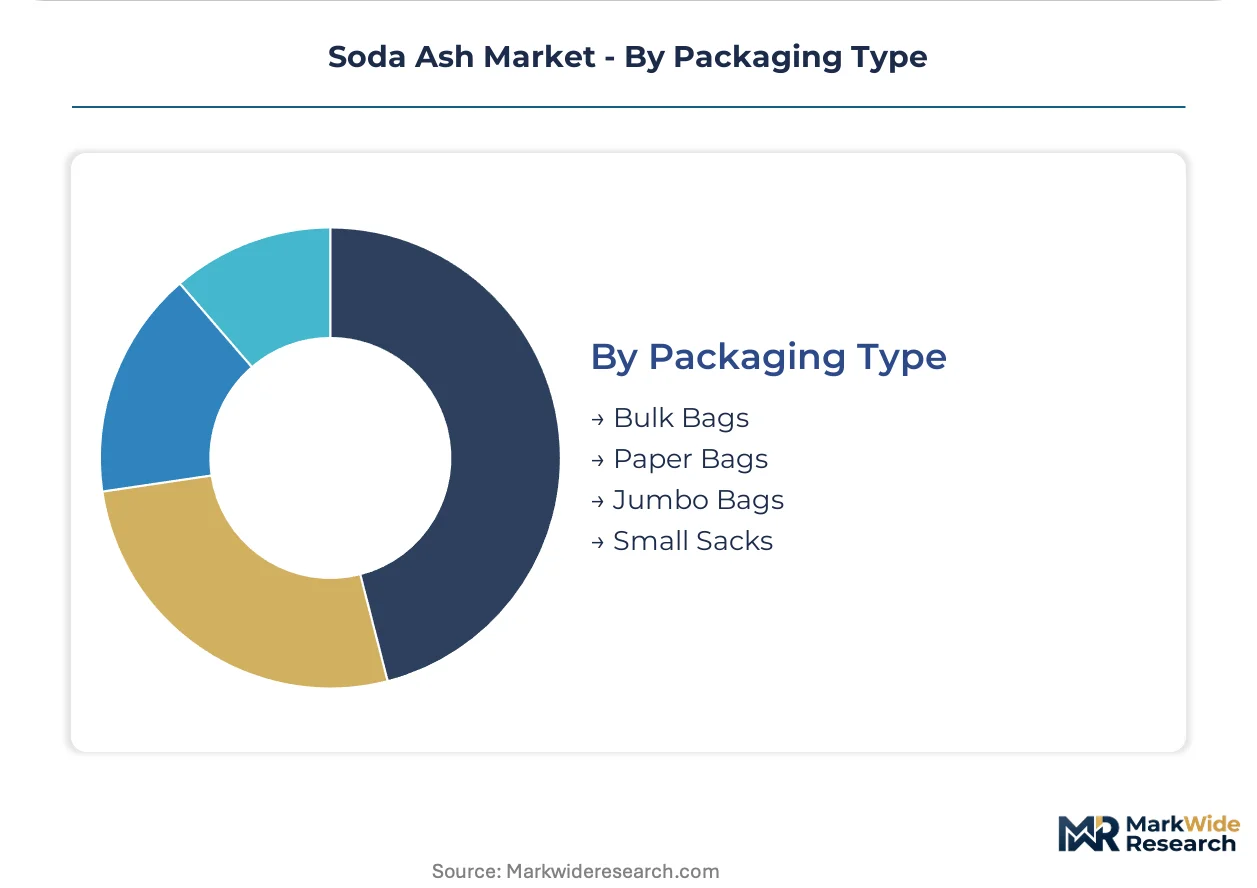
Packaging Type:
The choice of packaging type for soda ash often depends on the customer's operational scale, logistical capabilities, and storage infrastructure.
- Bulk Bags:These large, flexible containers, typically holding 500 kg to 2,000 kg, are preferred by large industrial users for efficient handling and reduced packaging waste. Bulk bags facilitate cost-effective transportation for high-volume customers.
- Paper Bags:Smaller quantities of soda ash are often packaged in multi-ply paper bags, suitable for smaller industrial applications or distribution to diverse end-users. These bags offer convenience for manual handling and smaller batch processing.
- Jumbo Bags:Even larger than standard bulk bags, jumbo bags can hold several tons of soda ash, catering to very high-volume industrial consumers with specialized material handling equipment. They optimize logistics for major manufacturing plants.
- Small Sacks:These are typically 25 kg or 50 kg bags, used for smaller-scale industrial applications, retail distribution, or where precise dosing is required. Small sacks provide flexibility for diverse customer needs.
Bulk Bags dominate industrial distribution; Jumbo Bags are gaining share fastest among major consumers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The soda ash market exhibits varied consumption patterns globally, with China's industrial provinces heavily focused on domestic glass and chemical processing sectors. Other regions demonstrate distinct preferences for natural trona or synthetic production methods based on resource availability and regulatory frameworks.
China
Demand for dense soda ash in China's industrial provinces remains robust, primarily driven by glass manufacturing for solar panels. The Ministry of Ecology and Environment (MEE) enforces stringent environmental standards for synthetic plants, influencing regional supply availability. Industrial clusters in Jiangsu and Shandong provinces continue to modernize production capacity with energy-efficient technologies.
United States
The United States leverages vast, low-cost natural trona reserves, primarily for glass manufacturing and chemical processing. The US Environmental Protection Agency (EPA) regulates emissions from industrial operations, impacting both natural and synthetic producers. The Green River Basin in Wyoming serves as the world's largest natural trona mining hub, supporting global supply chains.
Turkey
Turkey is a significant producer of natural trona, with companies like WE Soda supplying global markets, particularly Europe. Exports to the European Union are increasingly influenced by the EU's Carbon Border Adjustment Mechanism (CBAM). Production facilities near Ankara capitalize on extensive trona deposits, offering a cost advantage to international buyers.
Germany
Germany primarily relies on synthetic soda ash production to meet demand from its advanced chemical processing and glass manufacturing industries. The European Union's ECHA regulations impose strict chemical safety and environmental compliance standards on producers. Chemical parks in the Rhine-Ruhr area focus on process intensification to reduce energy consumption and waste outputs.
India
India's industrialization drives significant soda ash consumption in detergents, glass, and chemical manufacturing sectors. The Bureau of Indian Standards (BIS) sets quality benchmarks for industrial chemicals, ensuring product consistency. Gujarat's industrial clusters, including those around Vadodara and Dahej, are experiencing growth in both domestic production and import reliance.
Soda Ash Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive structure of the soda ash market. This tiered landscape includes diversified chemical giants, natural trona mining specialists, and regional synthetic producers. Capacity expansion, particularly in natural trona operations, and investments in energy-efficient synthetic technologies represent dominant competitive moves.
Within the natural trona segment, Ciner Group exemplifies players leveraging extensive reserves for cost-effective production and global distribution. Solvay occupies a position among advanced synthetic producers, relying on proprietary process technologies and strong European networks. Tata Chemicals Ltd. represents the diversified approach, operating both natural and synthetic facilities across multiple continents to serve varied regional demands.
| Leading Market Players |
|---|
| Ciner Group |
| NIRMA |
| Solvay |
| Olin Corporation |
| Shandong Haihua Group Co., Ltd. |
| Şişecam |
| WE Soda |
| DCW Ltd. |
| Tata Chemicals Ltd. |
| Others |
Cost & Logistics Intelligence
The European Union's Carbon Border Adjustment Mechanism (CBAM) gates supply qualification for European markets and influences price differentiation for imported soda ash. This policy creates a direct financial incentive for lower-carbon production methods.
Pricing Analysis
Long-term offtake agreements characterize a significant portion of soda ash transactions, particularly for high-volume industrial consumers. Price differentiation stems from volume scale and the source of production, favoring natural trona for its lower operational cost base. Pricing pressure stems from volatile energy costs, which disproportionately impact synthetic producers. Glass manufacturers are highly price-sensitive buyers, while specialty chemical producers often prioritize consistent supply and specific purity grades.
Supply Chain Analysis
The United States and Turkey anchor global natural trona production, supplying a substantial portion of the world's dense soda ash to diverse markets. The supply chain draws from key raw materials like limestone and salt for synthetic processes, or naturally occurring trona ore. Geographic concentration in trona reserves creates single-source vulnerability and potential logistical chokepoints for global buyers. Distribution runs through a network of bulk carriers and specialized logistics providers to dispersed industrial end-users across continents.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The soda ash market is experiencing a shift in buyer power, driven by consolidation among large glass manufacturers. This trend increases procurement leverage for major end-users, affecting producer margins.
For Market Incumbents:Compound existing advantages by investing in energy-efficient synthetic process technologies to mitigate volatile energy costs. Expand natural trona mining capacity in the United States to counter rising production costs for synthetic soda ash. This protects against emerging lower-cost synthetic alternatives. Leverage strong European distribution networks as a key lever for market access and stability.
For New Entrants and Emerging Players:Environmental Product Declarations (EPDs) fast-track market entry for sustainable soda ash producers targeting eco-conscious buyers. Target underserved regional markets in Southeast Asia with smaller-scale, localized synthetic production facilities. Focus on specialty chemical applications requiring specific purity grades. A direct-to-customer sales model can build early market share.
For Investors and Strategic Acquirers:Secondary-cycle assets sit with regional synthetic producers facing environmental compliance costs, offering potential for strategic acquisition. Long-term viability rests on securing low-cost energy inputs or access to natural trona reserves. Target mid-sized synthetic plants with carbon capture integration potential. The signal to watch is the sustained increase in carbon credit prices, impacting operational expenses.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion (Natural Trona) | Secures long-term, low-cost raw material supply for global glass manufacturing. |
| Green Manufacturing Transition | Reduces carbon footprint for synthetic producers, gaining access to EU markets under CBAM. |
| Long-term Supply Agreements | Provides demand stability and mitigates price volatility for both producers and industrial buyers. |
| Carbon Capture Integration | Transforms synthetic production facilities into lower-emission operations, enhancing environmental compliance. |
| Regional Distribution Network Optimization | Improves logistical efficiency and reduces transportation costs for bulk chemical delivery to end-users. |
Research Approach
The analysis maps dense soda ash and synthetic soda ash segments, each validated through extensive primary interviews with chemical plant managers and procurement leads. Secondary validation utilized customs data, industry association reports, and company 10-K filings. This approach combined bottom-up data aggregation with top-down market sizing for robust triangulation across the value chain.
Quantitative outputs underwent rigorous consistency checks against external economic indicators and historical trade volumes. The analytical framework modeled segmentation across product type, end-use industry, packaging format, and regional production hubs. Compound Annual Growth Rates were derived through regression analysis and expert consensus. Key forecast inputs included global glass production rates and regional energy price projections.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in energy price volatility and new trona reserve discoveries. Forecasts reflect these documented assumptions. Recalibration cycles align with material shifts in global trade policies or major capacity additions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Asia-Pacific Quicklime Market
Bulk Chemicals
Sodium Hydrogen Sulphite Market
Bulk Chemicals
Europe Calcium Nitrate Market
Bulk Chemicals
Fine Hydrate Market
Bulk Chemicals
Magnesium Nitrate Hexahydrate Market
Bulk Chemicals
Global Ammonium Phosphate Market
Bulk Chemicals
Europic Chloride Market
Bulk Chemicals
Magnesium Carbonate Market
Bulk Chemicals
Metallurgical Coke Market
Bulk Chemicals
Triammonium Citrate Market
Bulk Chemicals
Electronic Batio3 Powder Market
Bulk Chemicals
Cyclohexylamine Market
Bulk Chemicals
Glacial Acrylic Acid (GAA) Market
Bulk Chemicals
Global Bio Based Platform Chemicals Market
Bulk Chemicals
Phosphorus and Derivatives Market
Bulk Chemicals
Glacial Methacrylic Acid Market