
 Europe Polyolefin Foam Market | 2026-2036
Europe Polyolefin Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polyolefin Foam Market Intelligence
REACH is shifting the cost-of-entry calculus for polyolefin foam producers serving European automotive and construction clients. TotalEnergies leverages its integrated petrochemical platform to secure feedstock cost advantages across the value chain. BASF SE anchors its position through specialized catalyst technologies that enable tailored molecular architectures. Zotefoams plc differentiates via nitrogen-expanded autoclave processes that yield ultra-low density grades for aerospace and medical cushioning.
Europe polyolefin foam comprises thermoplastic cellular structures manufactured from polyethylene and polypropylene resins through extrusion, autoclave, or chemical foaming processes, with densities typically ranging from 15 to 200 kg/m³ depending on end-use requirements. These materials deliver energy absorption, thermal insulation, and chemical resistance for automotive interior panels, protective packaging, and building envelope systems. Expanded polypropylene dominates volume in automotive bumper cores and seat structures due to its exceptional resilience and recyclability profile. Extruded polyethylene leads cushioning and surface protection applications where cost efficiency and moisture resistance prove decisive. Cross-linked polyethylene commands premium positioning in construction insulation and soundproofing where dimensional stability under thermal cycling justifies higher material costs.
The EU F-Gas Regulation and CE marking requirements under the Construction Products Regulation shape product development roadmaps and market access conditions for insulation-grade foams. ECHA substance restriction proposals on persistent organic pollutants are forcing reformulation of certain chemical blowing agents, accelerating migration toward physical foaming technologies. EMA compliance frameworks indirectly influence medical packaging specifications where polyolefin foams serve as sterile barrier components. Stakeholders must monitor the interplay between the EU Green Deal's recyclability mandates and the technical performance thresholds that OEMs enforce in automotive qualification protocols.
Market Dynamics
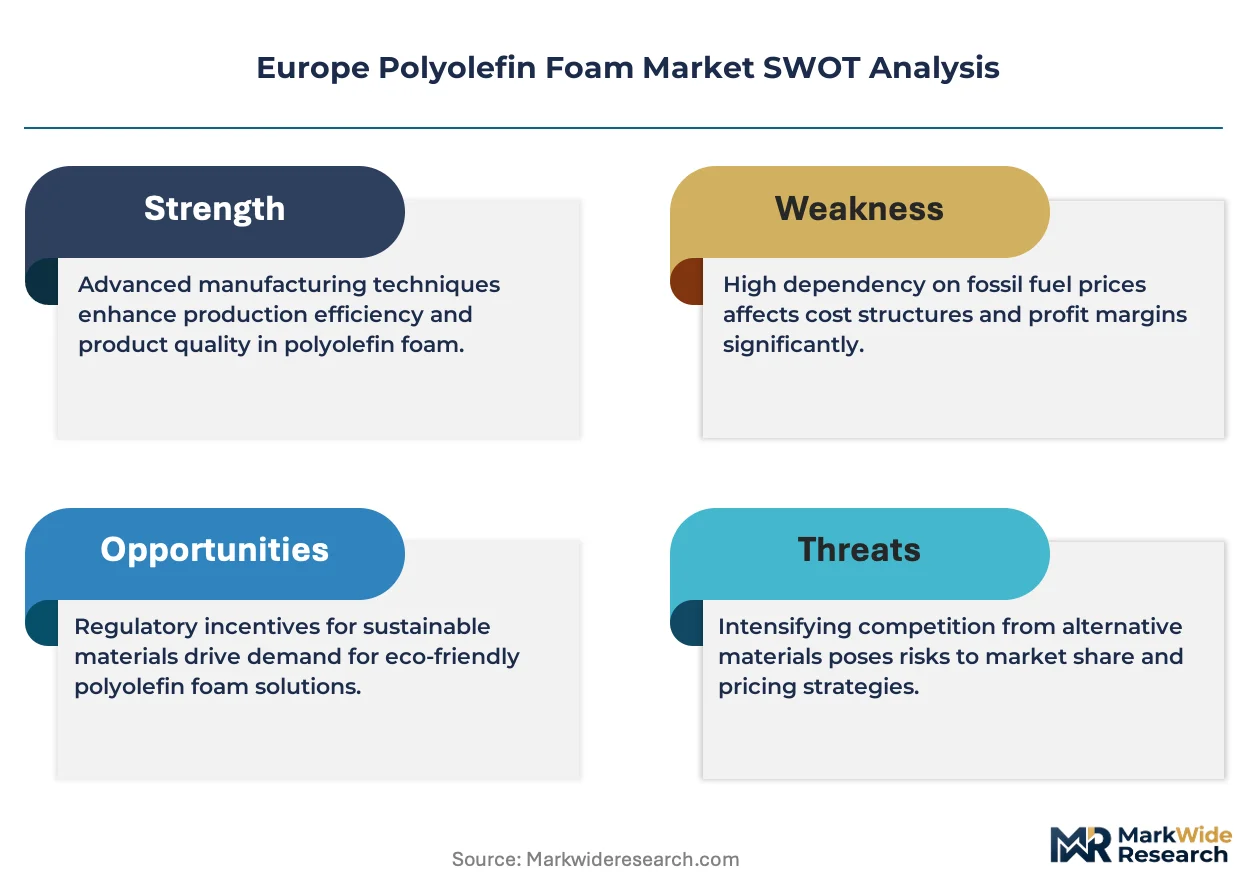
REACH substance restrictions on persistent organic pollutants are compressing formulation choices for European polyolefin foam producers, forcing migration toward physical nitrogen-based foaming systems and away from legacy chemical blowing agents.
Growth Catalysts
- Automotive lightweighting mandates:Germany's KBA and France's environmental agency enforce CO2 reduction targets that accelerate expanded polypropylene adoption in bumper cores and seat structures.
- EU Green Deal recyclability requirements:The circular economy action plan redirects R&D spending toward bio-based polyolefin formulations that maintain performance thresholds.
- Physical foaming technology maturation:Nitrogen-expanded autoclave processes now yield ultra-low density grades for aerospace cushioning and medical barrier applications.
Market Restraints
- Feedstock cost volatility:Naphtha and propylene price swings squeeze margin structures for non-integrated foam converters lacking captive cracker output.
- ECHA substance restriction timelines:Uncertainty around formaldehyde-releasing agent classifications delays capital commitment for new extrusion lines.
- Alternative material substitution:Bio-based polyurethane foams capture share in premium automotive interior segments where OEMs prioritize carbon footprint reduction.
Strategic Opportunities
- Eastern European manufacturing expansion:Poland and Czech Republic offer labor cost advantages for packaging-grade extruded polyethylene serving German automotive suppliers.
- Medical packaging certification demand:EMA compliance frameworks for sterile barrier systems create premium positioning for cross-linked polyethylene foam grades.
- Building envelope retrofit programs:F-Gas Regulation phase-down drives specification of low-GWP insulation foams in Benelux renovation markets.
Industry Challenges
- Autoclave nitrogen process expertise scarcity:Specialized reactor engineering talent concentrates at a handful of technical institutes in Germany and the Netherlands.
- CE marking timeline compression:Construction Products Regulation testing protocols for fire reaction classification extend product qualification cycles by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polyolefin Foam Market |
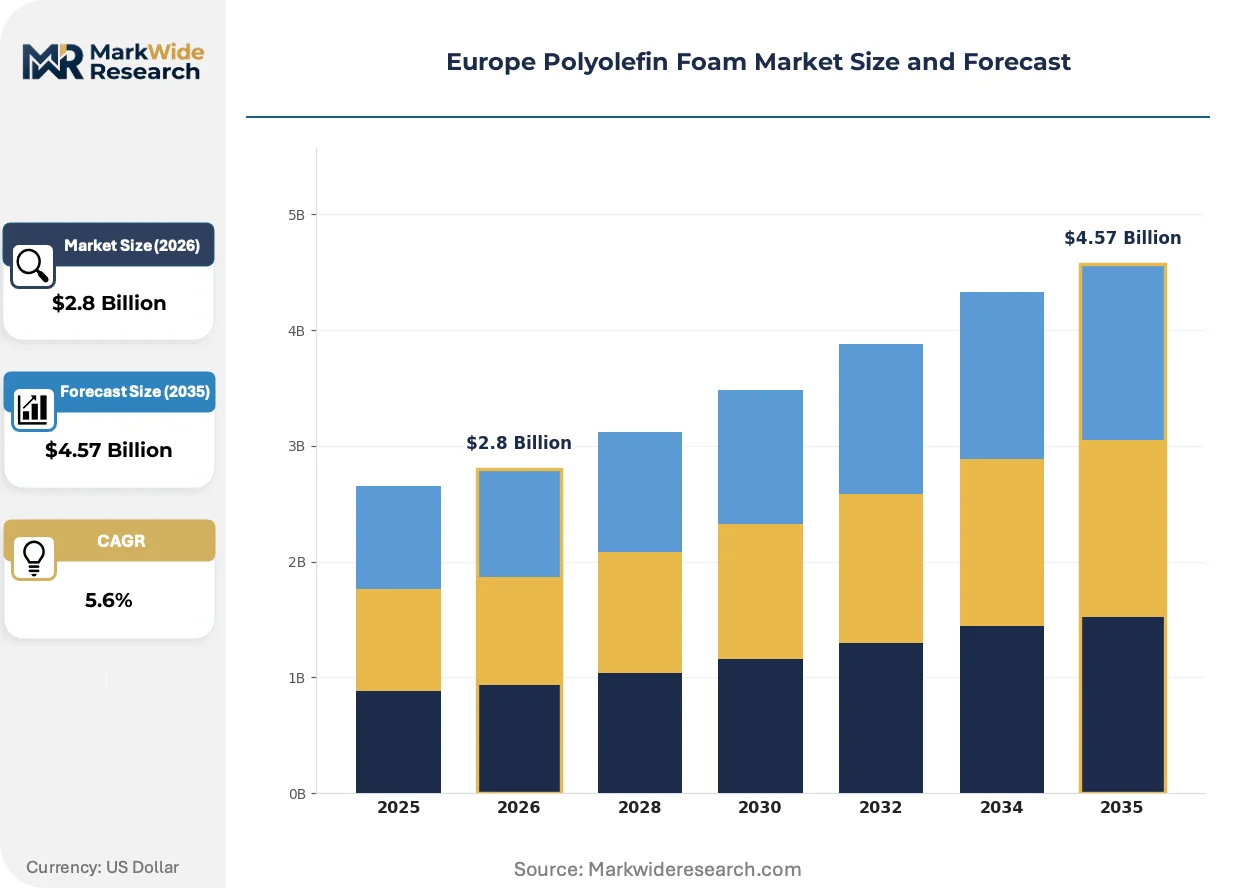
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expanded Polypropylene, Extruded Polyethylene, Cross-Linked Polyethylene, Flexible Polyethylene End Use Industry: Automotive, Packaging, Construction, Consumer Goods Form: Sheets, Rolls, Blocks, Custom Shapes Application: Insulation, Cushioning, Soundproofing, Surface Protection |
| Companies Covered | Sekisui Alveo, TotalEnergies, BASF SE, SABIC, DOW INC, Armacell International S.A., Arkema Group, Zotefoams plc, Borealis AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polyolefin Foam Market Strategic Shifts & Innovations
Physical foaming systems are displacing chemical alternatives across European production lines, while regulatory pressure on blowing agents and recyclability mandates reshape formulation roadmaps and capital allocation priorities.
Nitrogen-expanded autoclave technology is absorbing the technical requirements previously served by chemical blowing agents in aerospace and medical cushioning applications. Tier-1 automotive suppliers in Germany's Baden-Württemberg corridor specify these ultra-low density grades for interior panels where resilience and weight reduction converge. The shift is absorbing premium pricing power from conventional extruded polyethylene converters unable to replicate density control precision.
REACH restriction proposals on halogenated flame retardants are forcing reformulation of construction-grade cross-linked polyethylene foams. The ECHA regulatory pipeline now targets additive packages common in building insulation, compelling producers to validate phosphorus-based alternatives through extended fire reaction testing. Nordic markets and German federal states with stricter Bauaufsicht requirements face the steepest compliance cost escalations.
Automotive OEMs now mandate recycled content thresholds in foam component specifications. Procurement teams at German and French manufacturers require third-party mass-balance certification for expanded polypropylene used in seat structures and bumper cores. The specification shift is concentrating supply relationships toward converters with integrated mechanical recycling capabilities or secured offtake from chemical recycling joint ventures.
Europe Polyolefin Foam Market Segmentation
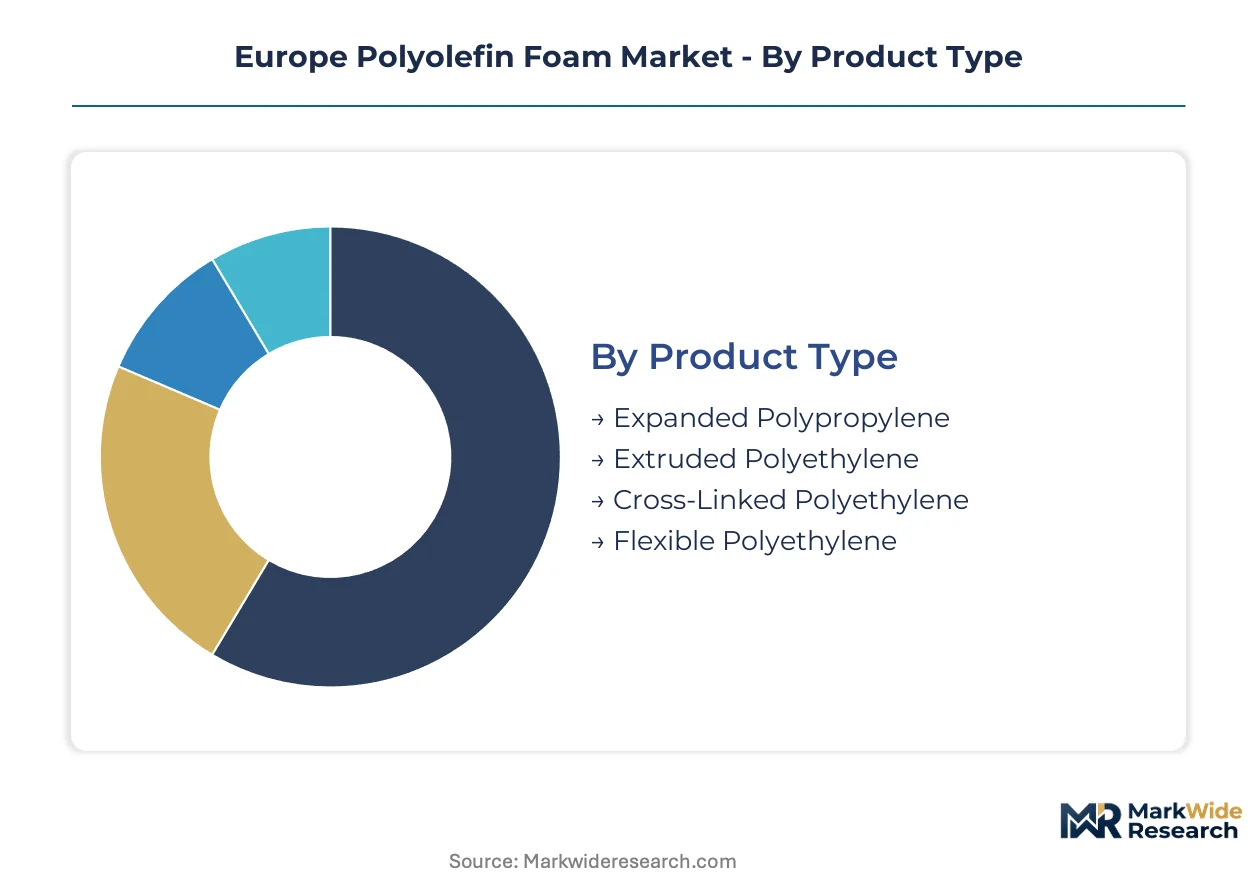
Polyolefin foam specifications diverge sharply across European end-uses, with automotive qualification protocols and construction fire ratings imposing incompatible technical thresholds on shared resin platforms. Upgrade cycles in automotive lightweighting and building energy retrofits are redirecting volume toward higher-performance grades that command material substitution premiums.
Product Type:
Replacement cycles in automotive seating and bumper systems are accelerating specification shifts toward grades that balance resilience with recycled content mandates.
- Expanded Polypropylene:Nitrogen-expanded cellular structures with closed-cell morphology deliver exceptional energy return and thermal stability. German and French automotive OEMs specify this grade for bumper cores and seat structures where KBA-enforced CO2 reduction targets prioritize weight reduction alongside recyclability certification.
- Extruded Polyethylene:Continuous foam sheets manufactured through tandem extrusion lines offer cost-efficient moisture resistance and surface protection. Benelux packaging converters favor this grade for protective dunnage serving German automotive suppliers, though margin compression from feedstock volatility constrains expansion.
- Cross-Linked Polyethylene:Irradiated or chemically cross-linked structures provide dimensional stability under thermal cycling for construction insulation.
- Flexible Polyethylene:Low-density open-cell variants serve consumer goods cushioning where softness and conformability outweigh structural rigidity requirements.
Expanded Polypropylene sits at the top of the volume ranking, with Cross-Linked Polyethylene climbing the fastest on F-Gas Regulation-driven building envelope retrofits.
End Use Industry:
Cost tier stratification separates specification-intensive automotive and medical applications from price-sensitive packaging segments where converter consolidation pressures margins.
- Automotive:Tier-1 suppliers in Baden-Württemberg and Île-de-France specify expanded polypropylene for interior panels and structural components. EU Green Deal recyclability mandates now require third-party mass-balance certification, concentrating supply relationships toward converters with integrated mechanical recycling capabilities.
- Construction:Cross-linked polyethylene dominates building envelope insulation where CE marking under the Construction Products Regulation mandates extended fire reaction classification testing. Nordic markets and German federal states with stricter Bauaufsicht requirements face steepest compliance cost escalations from REACH proposals on halogenated flame retardants.
- Packaging:Extruded polyethylene sheets and rolls serve protective dunnage for electronics and industrial equipment.
- Consumer Goods:Flexible polyethylene blocks and custom shapes address sporting equipment and furniture cushioning.
Automotive generates the highest value per kilogram, while Construction expands most quickly on renovation stimulus programs.
Form:
Supply concentration in nitrogen-autoclave reactor capacity favors block and custom shape producers serving aerospace and medical barrier applications.
- Sheets:Flat extruded or compression-molded panels serve surface protection and laminating substrates.
- Rolls:Continuous wound foam enables automated packaging line integration and reduces material handling labor.
- Blocks:Bun-stock formats from autoclave or slab-stock processes allow CNC machining and custom fabrication. Zotefoams plc and specialized German converters leverage nitrogen-expanded autoclave expertise to serve aerospace cushioning and EMA-compliant medical barrier specifications.
- Custom Shapes:Thermoformed or die-cut components match complex automotive interior geometries.
Sheets and Rolls dominate packaging tonnage, with Custom Shapes gaining share fastest on automotive interior panel complexity.
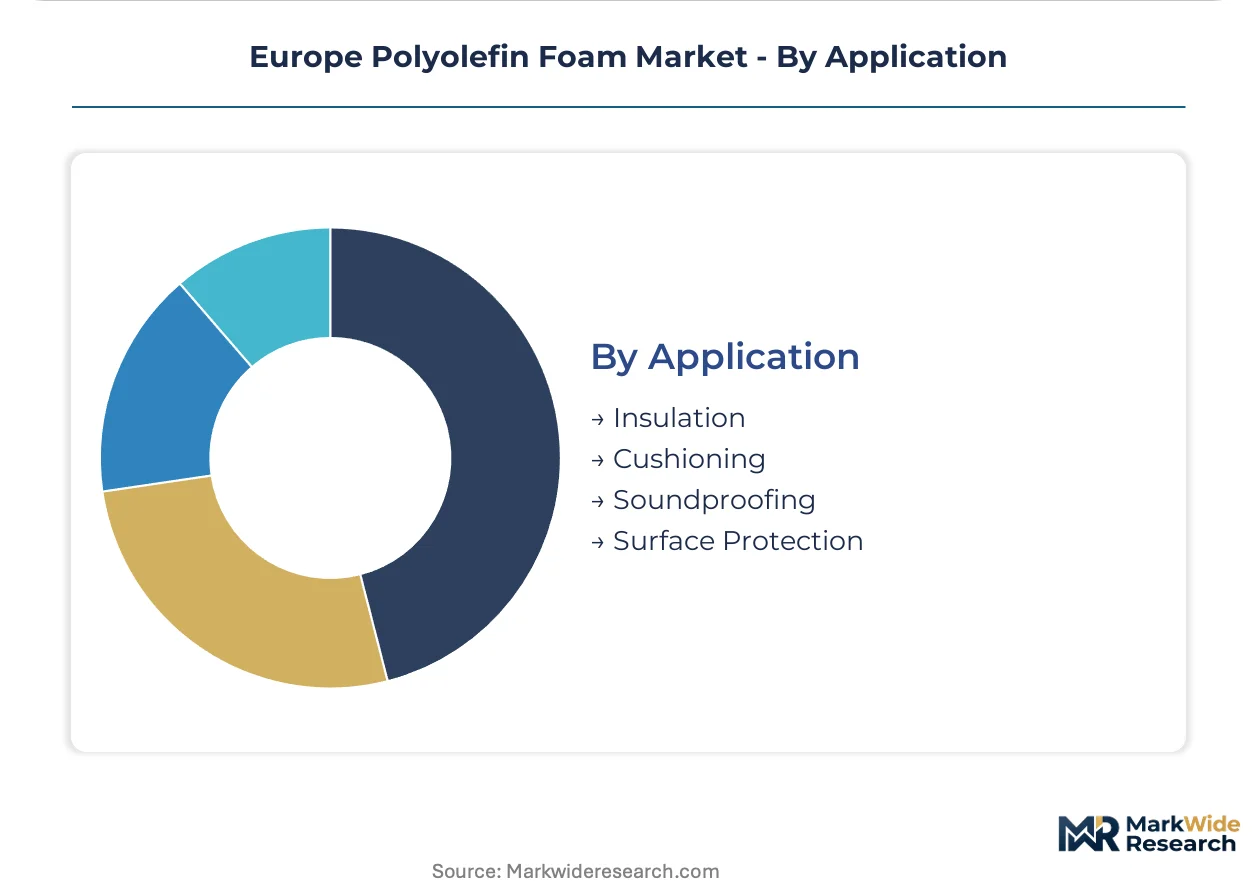
Application:
Application selection tracks end-use performance thresholds, with thermal and acoustic specifications in construction diverging from impact absorption requirements in automotive.
- Insulation:Cross-linked polyethylene blocks and sheets deliver thermal resistance for building envelopes. F-Gas Regulation phase-down drives specification of low-GWP foam alternatives in Benelux renovation markets, though CE marking timeline compression extends qualification cycles.
- Cushioning:Expanded polypropylene and flexible polyethylene grades absorb impact energy across automotive seating, medical packaging, and consumer goods. EMA compliance frameworks for sterile barrier systems create premium positioning for nitrogen-expanded grades with ultra-low density control.
- Soundproofing:Multi-layer foam laminates address NVH reduction in automotive cabins and building partition systems.
- Surface Protection:Extruded polyethylene sheets and rolls prevent abrasion during manufacturing and logistics.
Cushioning commands the broadest cross-industry demand, with Insulation posting the steepest expansion trajectory on building energy retrofit mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineering traditions established polyolefin foam manufacturing scale in the 1960s, with Baden-Württemberg autoclave expertise later diffusing to Benelux packaging corridors and French automotive supply chains.
Germany
KBA-enforced CO2 reduction targets accelerate expanded polypropylene adoption in bumper cores and seat structures across Stuttgart's automotive cluster. REACH substance restrictions on persistent organic pollutants compress formulation choices for foam producers serving OEM qualification protocols. Nitrogen-expanded autoclave expertise concentrates in Baden-Württemberg technical institutes supplying Tier-1 suppliers.
France
Île-de-France automotive OEMs mandate third-party mass-balance certification for recycled content in interior panel specifications. The EU Green Deal's circular economy action plan redirects R&D spending toward bio-based polyolefin formulations maintaining performance thresholds. Lyon-based packaging converters serve aerospace cushioning demand through nitrogen-expanded grades.
Netherlands
Benelux renovation markets drive specification of low-GWP insulation foams under F-Gas Regulation phase-down schedules. ECHA regulatory pipelines target halogenated flame retardants common in building insulation, compelling producers to validate phosphorus-based alternatives. Rotterdam-area extrusion lines supply protective dunnage to German automotive suppliers.
Poland
Labor cost advantages attract packaging-grade extruded polyethylene capacity serving German automotive supply chains. CE marking timeline compression under Construction Products Regulation extends product qualification cycles for insulation-grade foams. Warsaw-region converters expand block and custom shape fabrication for medical barrier applications.
Belgium
Antwerp's petrochemical hub provides feedstock cost advantages for integrated foam converters with captive cracker access. EMA compliance frameworks for sterile barrier systems create premium positioning for cross-linked polyethylene grades. Flanders-based producers leverage nitrogen-autoclave reactor capacity for aerospace cushioning specifications.
Europe Polyolefin Foam Market Key Industry Players
The competitive structure tilts toward integrated petrochemical majors controlling resin supply and specialized autoclave operators commanding premium density precision. Tier-1 automotive qualification requirements concentrate supply relationships among converters with mechanical recycling capabilities or chemical recycling joint venture offtake. Three archetypes dominate: integrated resin-to-foam majors, nitrogen-autoclave specialists, and regional extrusion converters. Competitive moves center on backward integration into feedstock and technology licensing for physical foaming systems.
Among integrated petrochemical platforms, TotalEnergies and BASF SE exemplify resin-cost advantage strategies, while Zotefoams plc occupies the specialist tier for ultra-low density nitrogen-expanded grades. These three anchors represent divergent capability investments: captive cracker economics, catalyst technology control, and autoclave reactor engineering precision respectively.
| Leading Market Players |
|---|
| Sekisui Alveo |
| TotalEnergies |
| BASF SE |
| SABIC |
| DOW INC |
| Armacell International S.A. |
| Arkema Group |
| Zotefoams plc |
| Borealis AG |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between EMA-compliant medical barrier foams and commodity packaging grades manifests in both pricing premiums and supply chain configurations across European production networks. Nitrogen-expanded autoclave capacity commands material substitution premiums while extruded polyethylene converters face margin compression from feedstock volatility.
Pricing Analysis
Bundled certification and technical service packages separate premium nitrogen-autoclave grades from unbundled commodity extruded polyethylene sheets sold on per-kilogram spot terms. Three-tier pricing structure across EMA-certified medical, CE-marked construction, and standard packaging grades reflects divergent compliance investment recovery timelines. Pricing pressure stems from naphtha and propylene cost swings squeezing non-integrated converters lacking captive cracker output. Tier-1 automotive procurement teams exhibit lowest price sensitivity where KBA-enforced CO2 targets prioritize weight reduction over material cost.
Supply Chain Analysis
Propylene feedstock rests on integrated petrochemical platforms concentrated in Germany, Belgium, and the Netherlands. Naphtha and natural gas liquids serve as primary raw material inputs alongside nitrogen gas for physical foaming systems. Single-source vulnerability concentrates in Baden-Württemberg autoclave engineering expertise. Distribution runs through converter-direct relationships with Tier-1 automotive suppliers and packaging distributors serving Benelux industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European polyolefin foam has entered a late-cycle quality phase where specification-intensive automotive and medical segments reward certification-capable producers. OEM procurement teams now mandate third-party mass-balance certification for expanded polypropylene in seat structures and bumper cores.
For Market Incumbents: Acquire nitrogen-autoclave reactor engineering capabilities to defend premium positioning against physical foaming technology diffusion. Secure backward integration into mechanical recycling streams or chemical recycling joint venture offtake to meet EU Green Deal recyclability mandates. Expand CE marking fire reaction testing capacity to compress qualification cycles for cross-linked polyethylene insulation grades. For New Entrants and Emerging Players: Begin with packaging-grade extruded polyethylene production in Poland and Czech Republic where labor cost advantages serve German automotive supply chains. Target medical barrier applications where EMA compliance frameworks create premium positioning for cross-linked polyethylene foam grades. Establish distributor relationships with Rotterdam-area logistics hubs serving Benelux renovation markets. For Investors and Strategic Acquirers: Consolidation pressure builds where autoclave nitrogen process expertise concentrates at a handful of technical institutes in Germany and the Netherlands. Five-to-ten year viability favors converters with integrated mechanical recycling capabilities or secured chemical recycling offtake. Target acquisition archetype: regional extrusion converters with CE marking infrastructure and automotive qualification relationships. Watch F-Gas Regulation phase-down schedules as inflection indicator for low-GWP insulation foam demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Recycling | Secures mass-balance certification feedstock for EU Green Deal compliance. |
| Nitrogen-Autoclave Capacity Expansion | Captures premium positioning in aerospace cushioning and medical barrier specifications. |
| CE Marking Fire Testing Investment | Compresses qualification cycles for cross-linked polyethylene construction insulation. |
| Eastern European Manufacturing Footprint | Exploits labor cost advantages for packaging-grade extruded polyethylene serving German OEMs. |
| Phosphorus-Based Flame Retardant Reformulation | Anticipates ECHA restriction proposals on halogenated additives in building insulation. |
Research Approach
Multiple input streams — executive interviews with Tier-1 automotive procurement directors, technical discussions with nitrogen-autoclave process engineers, and validation sessions with EMA regulatory affairs specialists — were reconciled against customs trade data, Cefic polyolefin reports, and SEC filings from integrated petrochemical majors. Bottom-up volume modeling across product type, end-use industry, and form segments was cross-checked against top-down demand estimates from automotive production databases and building renovation stimulus disclosures.
Historical volume trajectories were cross-referenced against panel input from plant managers at Benelux extrusion facilities and procurement leads at German automotive suppliers. Segmentation dimensions modeled include foam grade tier, end-use industry qualification protocol, regional production hub, and certification status. CAGRs were derived from elasticity-adjusted demand projections incorporating REACH substance restriction timelines and F-Gas Regulation phase-down schedules. Forecast inputs incorporated KBA-enforced CO2 reduction targets and EU Green Deal circular economy action plan implementation pacing.
Several conditions sit outside the modeled scope, including formaldehyde-releasing agent classification uncertainty, alternative bio-based polyurethane substitution rates, and geopolitical disruption to naphtha feedstock flows. Forecasts reflect documented assumptions about physical foaming technology maturation and ECHA regulatory pipeline progression. A small set of named triggers warrants ongoing watch: EMA guidance updates on sterile barrier materials, Bauaufsicht enforcement tightening in German federal states, and chemical recycling joint venture commissioning timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Polypropylene Powder Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Europe Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Bisphenol a Market
Polymers & Resins
Bio-Based PVC Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Medical Grade Liquid Crystal Polymer Market
Polymers & Resins
Bio-Based Epoxy Resin Market
Polymers & Resins
Global Alpha Olefins Market
Polymers & Resins
Vinyl Acetate Monomer (VAM) Market
Polymers & Resins
Paste PVC Resin Market