
 Bio-Based PVC Market | 2026-2036
Bio-Based PVC Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based PVC Market Analytics
Premium-grade rigid PVC formulations certified for medical and automotive tubing is unwinding legacy petroleum-dependent supply chains. INEOS Group Limited leverages its European chlor-alkali network to sustain integrated bio-ethylene oxide feedstock access. Solvay SA anchors its position through specialty plasticizer R&D intensity in Belgium and France. Shin-Etsu Chemical Co., Ltd. dominates Asian high-purity resin output for semiconductor cleanroom applications.
Bio-based PVC substitutes conventional polyvinyl chloride by incorporating ethanol-derived ethylene or plant-based plasticizers such as epoxidized soybean oil, achieving comparable Shore hardness and tensile strength for extrusion and calendering processes. Its primary purpose centers on reducing cradle-to-gate carbon intensity in durable goods without retrofitting existing extrusion infrastructure. Flexible PVC commands the broadest addressable footprint due to flooring and cable jacketing volume, yet rigid PVC captures superior margin pools in medical device and potable water pipe segments where phthalate-free certification commands price premiums. Foam PVC remains a nascent growth vector constrained by cell-structure uniformity challenges in bio-plasticizer blends.
The EU Green Deal and REACH framework restrict phthalate plasticizer migration limits, directly elevating bio-based formulation premiums in European medical and toy applications. EPA guidelines under the Toxic Substances Control Act shape US vinyl chloride monomer emissions thresholds, influencing bio-ethylene pathway economics versus conventional naphtha cracking. FDA device master file requirements for blood-contact tubing create compliance moats around validated bio-PVC compounders. Stakeholders must monitor feedstock certification integrity as mass-balance accounting standards diverge between ISCC PLUS and RSB protocols.
Market Dynamics
REACH phthalate restrictions and EU Green Deal carbon-accounting mandates are forcing compounders to revalidate entire formulation libraries around bio-attributed feedstock certification, compressing legacy petroleum-PVC margins while opening premium pricing tiers for ISCC PLUS-verified resins.
Growth Catalysts
- REACH Migration Limits:ECHA's tightened phthalate thresholds in medical devices and toys elevate bio-plasticizer formulations to compliance-mandatory status, capturing price premiums in European tubing and flooring segments.
- Automotive Cable Sheathing:German OEMs are integrating bio-based PVC into high-voltage cable jackets to meet Scope 3 reduction targets, creating validated demand pools that compounders must qualify for through extended homologation cycles.
- Mass-Balance Certification:ISCC PLUS and RSB protocol adoption is accelerating as brand owners demand chain-of-custody documentation for sustainability reporting under CSRD requirements.
Market Restraints
- Bio-Ethylene Cost Volatility:Brazilian sugarcane ethanol pricing swings and US corn harvest variability transmit directly to bio-ethylene oxide feedstock economics, constraining margin stability for European chlor-alkali integrated producers.
- Asian High-Purity Concentration:Semiconductor-grade resin output clusters in Japan and South Korea, creating supply vulnerability for medical device compounders requiring sub-ppm ionic contamination specifications.
- Cell-Structure Uniformity:Foam PVC applications remain technically constrained by bio-plasticizer blend incompatibility with nucleating agents, limiting penetration into lightweight construction panels.
Strategic Opportunities
- Underpenetrated US Medical Tubing:FDA device master file validation gaps for bio-PVC compounders create first-mover advantages in blood-contact applications where phthalate-free specifications are tightening.
- Epoxidized Soybean Oil Convergence:Agricultural plasticizer supply chains are merging with chlor-alkali networks through backward integration into oilseed crushing, capturing margin pools previously lost to merchant plasticizer suppliers.
- IRA Clean Manufacturing Credits:US bio-based chemical production incentives under the Inflation Reduction Act are repositioning domestic ethylene oxide economics versus naphtha-cracking alternatives.
Industry Challenges
- Homologation Timeline Compression:Automotive OEM validation cycles for cable sheathing now demand 18-month accelerated aging protocols that bio-formulations struggle to complete ahead of model-year deadlines.
- Mass-Balance Audit Fragmentation:Divergent ISCC PLUS and RSB accounting standards create dual-certification burdens for compounders serving both European medical device and US flooring customers.
- Extrusion Parameter Reconfiguration:Bio-plasticizer thermal stability profiles require screw-design modifications and temperature-zone recalibration that legacy extrusion houses resist deploying across mixed feedstock operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based PVC Market |
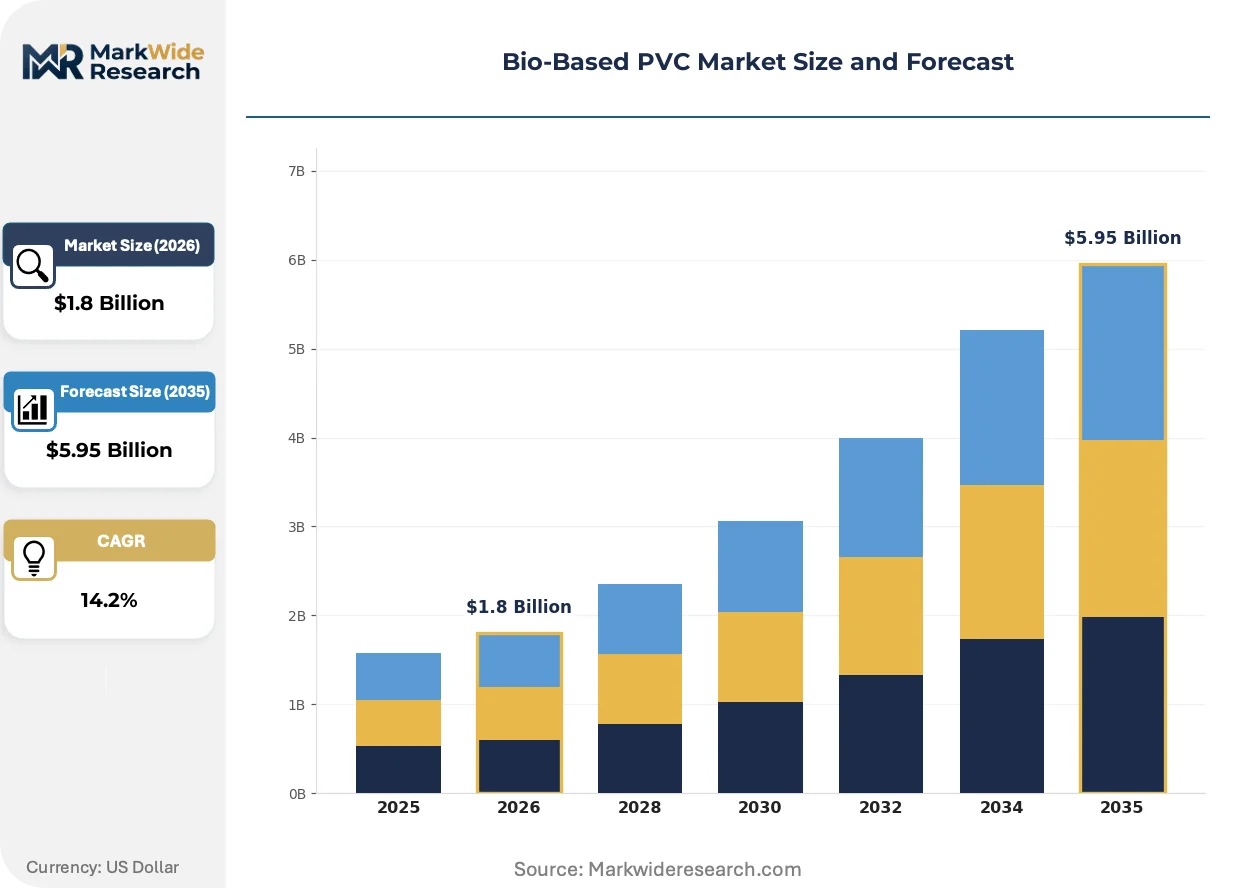
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible PVC, Rigid PVC, Foam PVC, Others End User: Construction, Automotive, Consumables, Packaging Application: Flooring, Pipes, Cables, Medical Devices Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | INEOS Group Limited, Formosa Plastics Corporation, Solvay SA, Vinnolit GmbH, Shin-Etsu Chemical Co., Ltd., Westlake Chemical Corporation, Arkema SA, Covestro AG, The Dow Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based PVC Market Evolving Landscape
Formulation chemistry, regulatory accounting, and procurement validation protocols are simultaneously evolving, compressing the window between laboratory certification and commercial-scale deployment for bio-attributed compounds.
Epoxidized soybean oil plasticizer systems are supplanting DINP and DEHP in European medical tubing and flooring applications. German automotive cable manufacturers are adopting these formulations at pilot scale ahead of 2027 model-year specifications. This substitution is compressing legacy phthalate compounder margins while opening premium tiers for verified bio-attributed supply chains.
EU Green Deal carbon-border adjustment mechanisms and REACH authorization sunset clauses are tightening together, forcing non-European resin suppliers to obtain ISCC PLUS certification for market access. Industrial consequence includes mandatory third-party audit costs that smaller compounders cannot absorb. Medical device and toy segments are responding by consolidating supplier panels around pre-certified integrated producers.
Buyer certification requirements are displacing spot-market purchasing in construction and automotive cable procurement. Tier-1 contractors and OEMs now mandate chain-of-custody documentation from resin to finished article, eliminating merchant compounders without validated mass-balance systems. This pattern is most visible in German automotive supply chains and Benelux flooring distribution networks.
Bio-Based PVC Market Segmentation
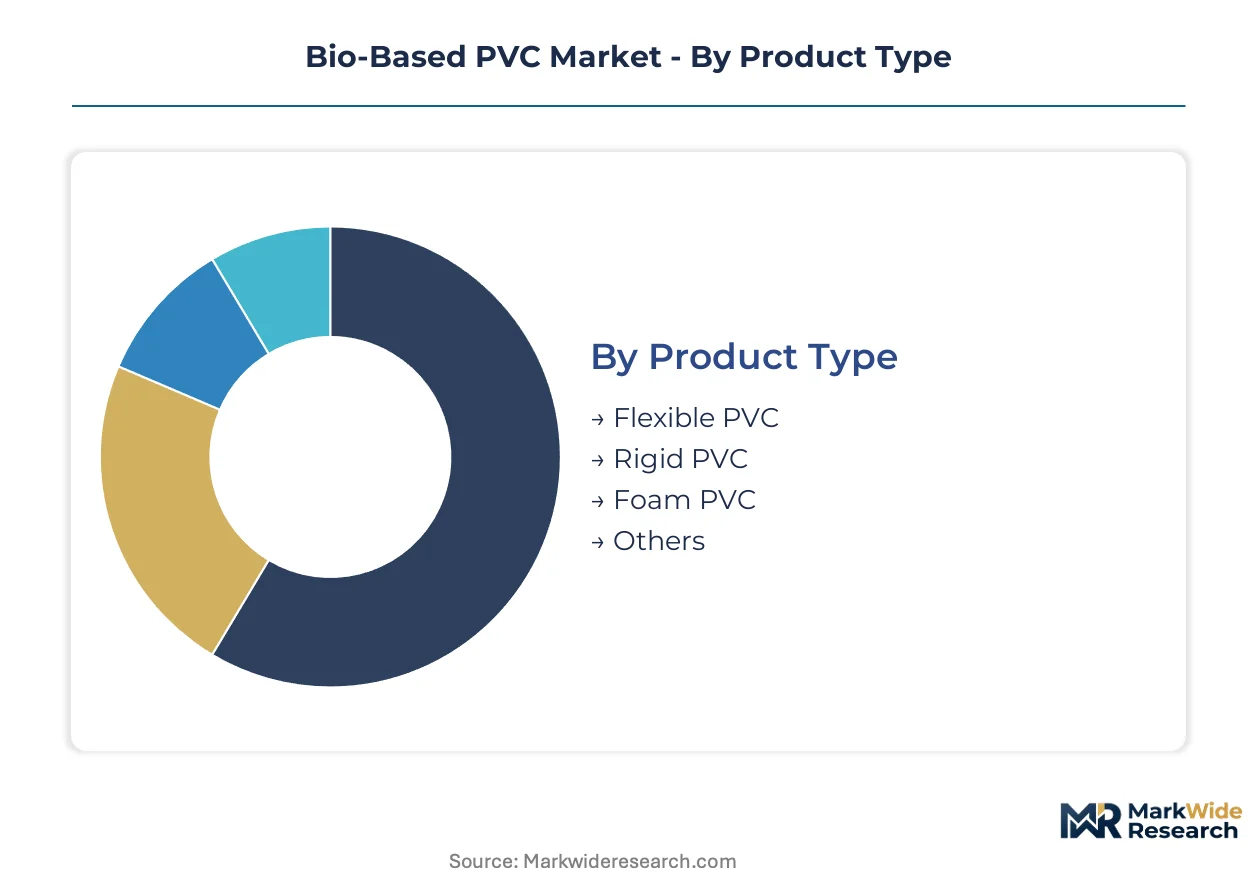
Segmentation in bio-based PVC reveals how regulatory pressure and carbon-accounting requirements fragment demand across material grades and end-use specifications. Each dimension exposes distinct margin structures and certification burdens that compounders must navigate.
Product Type:
REACH phthalate migration limits and EU Green Deal carbon-border adjustments split the market into compliance-mandatory versus discretionary substitution tiers.
- Flexible PVC:Incorporates epoxidized soybean oil and other bio-plasticizers to replace DINP and DEHP in flooring and cable jacketing. German automotive OEMs and Benelux flooring distributors now mandate ISCC PLUS certification for volume procurement, compressing spot-market participation.
- Rigid PVC:Formulated with bio-attributed ethylene for pipe and medical tubing applications where phthalate-free specifications command validation premiums. Construction sector procurement in Germany and medical device manufacturing clusters in Belgium concentrate demand for premium-grade resin.
- Foam PVC:Faces cell-structure uniformity constraints when bio-plasticizer blends interact with nucleating agents, limiting penetration into lightweight construction panels.
- Others:Includes specialty compounded grades for semiconductor cleanroom and blood-contact applications requiring sub-ppm ionic contamination control.
Flexible PVC handles the majority of throughput; Rigid PVC is expanding most quickly on share as medical and potable water specifications tighten.
End User:
Carbon intensity disclosure requirements and Scope 3 reduction targets concentrate procurement validation efforts across durable goods manufacturers.
- Construction:Rigid bio-based PVC pipe procurement is accelerating as German and Dutch builders seek lower-carbon alternatives for potable water and drainage infrastructure. ECHA REACH compliance mandates now exclude legacy phthalate formulations from public tender specifications.
- Automotive:German OEMs are integrating bio-based PVC into high-voltage cable sheathing to meet Scope 3 reduction targets, creating validated demand pools that require 18-month accelerated aging protocols for homologation.
- Consumables:Medical device and toy segments respond to tightened phthalate thresholds by consolidating supplier panels around pre-certified integrated producers with validated mass-balance systems.
- Packaging:Remains a discretionary substitution segment where cost parity with conventional PVC constrains penetration outside premium brand owner specifications.
Construction absorbs the greatest volume tonnage; Automotive is climbing the fastest as cable jacketing specifications proliferate across EV platforms.
Application:
Performance certification requirements and contact-safety standards stratify addressable markets by validation burden and price realization.
- Flooring:Epoxidized soybean oil plasticizer systems are supplanting phthalates in European commercial and residential vinyl flooring. Benelux distribution networks now demand chain-of-custody documentation from resin to finished article.
- Pipes:Rigid bio-based PVC captures superior margin pools in potable water segments where KBA and DVGW certification requirements exclude non-compliant compounders.
- Cables:High-voltage automotive cable sheathing specifications in Germany are adopting bio-based formulations at pilot scale ahead of model-year deadlines.
- Medical Devices:FDA device master file requirements for blood-contact tubing create compliance moats around validated bio-PVC compounders, with first-mover advantages accruing to pre-qualified suppliers.
Flooring generates the broadest revenue base; Medical Devices is gaining share fastest as phthalate-free specifications harden across regulatory jurisdictions.
Distribution Channel:
Chain-of-custody documentation requirements are restructuring procurement relationships away from spot-market intermediation toward validated direct partnerships.
- Direct Sales:Tier-1 automotive OEMs and medical device manufacturers now mandate direct relationships with ISCC PLUS-certified integrated producers to satisfy CSRD sustainability reporting requirements.
- Distributors:Benelux and German flooring distribution networks are consolidating around distributors with validated mass-balance audit capabilities, eliminating merchant compounders without certification.
- Online Retail:Serves small-volume specialty compound procurement for R&D and pilot-scale formulation development.
- Others:Includes toll-compounding arrangements and consignment inventory programs for construction sector contractors.
Direct Sales commands the dominant share of premium-grade volume; Distributors is expanding most rapidly as mass-balance certification becomes a table-stake requirement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in bio-based PVC track chlor-alkali integration and bio-ethylene oxide feedstock availability. Germany and the United States run structural surpluses in specialty compounded grades. Asian markets depend on high-purity resin imports for medical and semiconductor applications.
Germany
Automotive cable sheathing specifications from BMW and Volkswagen drive bio-based PVC procurement for high-voltage EV platforms. ECHA REACH authorization sunset clauses exclude legacy phthalate formulations from public tender eligibility. The Ruhr industrial corridor hosts integrated chlor-alkali producers with ISCC PLUS-certified mass-balance systems.
United States
Medical device manufacturers in Minnesota and Massachusetts seek FDA-validated bio-PVC compounders for blood-contact tubing applications. EPA Toxic Substances Control Act guidelines on vinyl chloride monomer emissions favor bio-ethylene pathway economics. The Gulf Coast petrochemical corridor anchors domestic ethylene oxide capacity with backward integration into agricultural feedstock processing.
Belgium
Specialty plasticizer R&D intensity concentrates around Antwerp port logistics for epoxidized soybean oil import and formulation. EU Green Deal carbon-border adjustment mechanisms require third-party audit documentation for all resin imports. The Flanders chemical cluster maintains validated supply chains for Benelux flooring distributors demanding chain-of-custody certification.
Japan
Semiconductor cleanroom applications require sub-ppm ionic contamination specifications that concentrate high-purity resin output in Osaka and Tokyo industrial zones. METI dual carbon goals accelerate bio-attributed feedstock verification requirements for electronics-grade materials. Kyushu chemical producers face supply vulnerability as medical device compounders seek alternative qualified sources.
Brazil
Sugarcane ethanol pricing volatility transmits directly to bio-ethylene oxide economics for export-oriented chlor-alkali operations. ANVISA pharmaceutical-grade polymer regulations create compliance moats around validated compounders serving Latin American medical markets. São Paulo state crushing facilities merge agricultural plasticizer supply chains with downstream resin production.
Bio-Based PVC Market Competitive Landscape
Concentration sits with integrated chlor-alkali producers possessing captive bio-ethylene oxide feedstock access and mass-balance certification infrastructure. The vendor base stratifies across three tiers: multinational petrochemical conglomerates with European chlor-alkali networks, Asian high-purity resin specialists serving semiconductor applications, and regional compounders focused on construction and flooring segments. Strategic moves center on backward integration into agricultural feedstock processing and extended homologation partnerships with automotive OEMs for cable sheathing validation.
Among European integrated producers, INEOS Group Limited and Solvay SA exemplify the chlor-alkali-network archetype with mass-balance certification capabilities. Shin-Etsu Chemical Co., Ltd. occupies a position representing Asian high-purity specialization for medical and electronics-grade applications. These three entities anchor the competitive structure through divergent feedstock integration models and end-market validation depth.
| Leading Market Players |
|---|
| INEOS Group Limited |
| Formosa Plastics Corporation |
| Solvay SA |
| Vinnolit GmbH |
| Shin-Etsu Chemical Co., Ltd. |
| Westlake Chemical Corporation |
| Arkema SA |
| Covestro AG |
| The Dow Chemical Company |
| Others |
Value Network & Pricing Analysis
Chlor-alkali scale economies in the Ruhr corridor and US Gulf Coast establish minimum efficient scale thresholds that filter out sub-integrated compounders and compress spot-market participation. These capacity-utilization dynamics concentrate pricing power among ISCC PLUS-certified producers while forcing merchant compounders toward contract-based offtake arrangements with automotive OEMs and medical device manufacturers.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in bio-based PVC procurement. Certification grade and volume scale drive price differentiation, with ISCC PLUS-verified resins commanding substantial premiums over uncertified alternatives. Cost compression in the standard tier is intensifying because Brazilian sugarcane ethanol volatility transmits directly to bio-ethylene oxide economics. Construction contractors exhibit the highest price sensitivity due to tender-based procurement, while medical device manufacturers remain least sensitive given FDA validation moats and phthalate-free compliance mandates.
Supply Chain Analysis
Just-in-time inventory strategies dominate automotive cable sheathing procurement, while medical tubing compounders maintain strategic stockpiles of high-purity resin to hedge against Japanese supply disruptions. Production concentrates in Germany, the United States, and Japan, with each node serving distinct specification tiers. Feedstock dependencies draw from Brazilian sugarcane ethanol, US corn-derived bio-ethylene, and Asian high-purity VCM imports. Single-source vulnerability clusters around semiconductor-grade resin output in Osaka and Tokyo industrial zones. Distribution runs through validated direct partnerships with Tier-1 OEMs rather than spot-market intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-based PVC incumbents face substitution pressure from bio-polyolefin cable jacketing and thermoplastic elastomer tubing formulations that bypass chlor-alkali infrastructure entirely. Defense of position requires preemptive consolidation of mass-balance certification capabilities and accelerated homologation partnerships before alternative materials capture automotive validation cycles.
For Market Incumbents: Shield market position by securing backward integration into agricultural feedstock processing in São Paulo state and Minnesota corn-belt regions, eliminating exposure to merchant bio-ethylene price volatility. Accelerate ISCC PLUS and RSB dual-certification investments to preempt regulatory divergence between European and North American accounting standards. Consolidate supplier panels around pre-certified integrated producers before bio-polyolefin compounders achieve automotive OEM validation. For New Entrants and Emerging Players: Anchor in underpenetrated US medical tubing applications where FDA device master file validation gaps create first-mover advantages for blood-contact bio-PVC compounders. Target toll-compounding arrangements with construction sector contractors seeking REACH-compliant rigid pipe formulations for German and Dutch public infrastructure tenders. Pursue epoxidized soybean oil backward integration through oilseed crushing partnerships to capture margin pools previously lost to merchant plasticizer suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated chlor-alkali producers with captive bio-ethylene oxide feedstock and validated mass-balance systems serving automotive OEM direct contracts. Long-term viability across the analysis window rests on homologation depth with German cable manufacturers and FDA validation status for medical applications. Acquisition targets should demonstrate existing ISCC PLUS certification and active automotive OEM validation programs. The signal to watch is accelerated aging protocol completion rates relative to model-year deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | São Paulo sugarcane crushing and US corn processing capture margin pools from merchant bio-ethylene suppliers. |
| Dual Certification Investment | ISCC PLUS and RSB protocols preempt regulatory divergence between ECHA REACH and EPA emission frameworks. |
| Automotive Homologation Partnership | BMW and Volkswagen cable sheathing validation creates 18-month competitive moats against bio-polyolefin substitutes. |
| Medical Device FDA Validation | Device master file pre-qualification locks in blood-contact tubing procurement before phthalate-free mandates harden. |
| Mass-Balance Audit Infrastructure | Third-party documentation capabilities satisfy CSRD chain-of-custody requirements for Tier-1 OEM direct sales. |
Research Methodology
Initial hypotheses were tested against primary input from chlor-alkali plant managers, automotive OEM procurement leads, medical device regulatory affairs directors, and Benelux flooring distribution channel partners and refined through secondary validation. Trade data from Eurostat and USITC, ECHA REACH authorization databases, SEC 10-K filings from disclosed petrochemical producers, and ISCC PLUS certification registries provided quantitative anchors. Bottom-up resin throughput estimates triangulated against top-down end-use consumption models across construction, automotive, and medical segments.
Variance decomposition across the projection horizon isolates feedstock price volatility, regulatory authorization timelines, and homologation completion rates as primary uncertainty sources. Segmentation dimensions include product type tier, end-use industry, application specification, and distribution channel structure. CAGRs derive from fitted growth curves applied to validated base-year estimates, with bio-ethylene oxide economics and plasticizer substitution elasticities serving as key forecast inputs.
Material uncertainties — Brazilian ethanol pricing swings, ECHA authorization sunset clause timing, and automotive OEM platform standardization decisions — sit outside the modeled envelope. Forecasts reflect assumptions regarding sustained REACH enforcement and ISCC PLUS adoption trajectories. Revision becomes warranted when bio-polyolejin substitution rates in cable applications cross validation thresholds at major German OEMs.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
PET Foam Market
Polymers & Resins
Germany Polymer Emulsion Market
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Polyamide 11 & 12 Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Polycarbonate Resin Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market