
 Natural Oil Polyols (NOP) Market | 2026-2036
Natural Oil Polyols (NOP) Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Oil Polyols (NOP) Market Analysis
Automotive OEMs is unwinding legacy reliance on furniture and bedding buyers as the fastest-growing buyer archetype for natural oil polyols. Cargill Incorporated anchors its position through captive oilseed crushing and downstream polyol conversion across North American supply chains. BASF SE competes on polymerization technology leadership, sustaining R&D intensity in high-performance rigid foam formulations. Stepan Company differentiates through specialty esterification expertise, occupying niche positions in coatings-grade biopolyols.
Natural oil polyols are hydroxyl-functionalized derivatives of vegetable oils—primarily soybean, castor, and palm—typically exhibiting hydroxyl values between 50 and 200 mg KOH/g and molecular weights ranging from 1,000 to 3,000 g/mol, manufactured through epoxidation-ring opening or transesterification pathways to serve as renewable feedstocks for polyurethane synthesis. Polyether polyols dominate current volume owing to mature processing infrastructure and broad compatibility with isocyanate systems, while biopolyols represent the fastest-expanding category as biochemical processes achieve cost parity with chemical synthesis in flexible foam applications. Coatings applications command premium positioning due to stringent volatile organic compound regulations, whereas rigid foam growth ties directly to construction energy-efficiency codes.
EPA bio-preferred procurement standards and REACH substance restrictions in Europe jointly elevate compliance costs for petroleum-based alternatives, redirecting formulation investments toward NOP platforms. FDA food-contact material guidelines and OSHA workplace exposure limits further constrain conventional polyol handling, broadening NOP adoption in consumer goods molding. Stakeholders must monitor evolving bio-content certification schemes and isocyanate pairing compatibility to secure formulation lock-in before specification cycles harden at major OEMs.
Market Dynamics
Automotive OEM sustainability mandates are compressing specification cycles for bio-based polyurethane feedstocks, forcing tier-one seating suppliers to validate natural oil polyol formulations ahead of traditional petroleum-derived alternatives.
Growth Catalysts
- REACH substance restrictions:ECHA's tightening limits on aromatic amines in polyurethane foams redirect formulation investments toward vegetable-oil-derived polyols in European automotive and construction applications.
- Construction energy-efficiency codes:Germany's EnEV standards and comparable building thermal-performance mandates in China drive rigid foam specification for insulation panels using high-functionality NOP grades.
- Epoxidation-ring opening technology:Advanced catalytic pathways for soybean and castor oil modification are achieving cost parity with petrochemical polyols in flexible foam production at North American processing facilities.
Market Restraints
- Oilseed price volatility:Soybean and palm oil commodity swings transmit directly to NOP feedstock costs, compressing margin stability for formulators lacking backward integration into crushing operations.
- Isocyanate pairing constraints:Natural oil polyols exhibit narrower compatibility windows with aromatic isocyanates versus polyether alternatives, limiting substitution rates in high-performance rigid foam systems.
- Regional supply concentration:Over 60 percent of global castor oil production originates in Gujarat, India, creating geographic single-point vulnerability for suppliers dependent on this feedstock stream.
Strategic Opportunities
- Brazilian construction cluster expansion:São Paulo and Rio de Janeiro metro regions are driving polyurethane insulation demand under national energy-efficiency building codes, creating import-substitution potential for local NOP production.
- Coatings-grade biopolyol white space:Low-VOC decorative and industrial coatings represent underpenetrated application territory where specialty esterification expertise commands 15-25 percent formulation premiums.
- USDA BioPreferred federal procurement:Federal agency purchasing mandates for biobased products create guaranteed offtake volume for NOP-certified suppliers in US government construction and furnishing contracts.
Industry Challenges
- Bio-content certification complexity:ASTM D6866 radiocarbon testing and competing European biobased content schemes impose 6-12 month validation timelines that delay OEM specification lock-in.
- Polyol-isocyanate formulation requalification:Automotive seating suppliers face 18-24 month OEM validation cycles when switching from incumbent polyether systems to NOP-based alternatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Oil Polyols (NOP) Market |
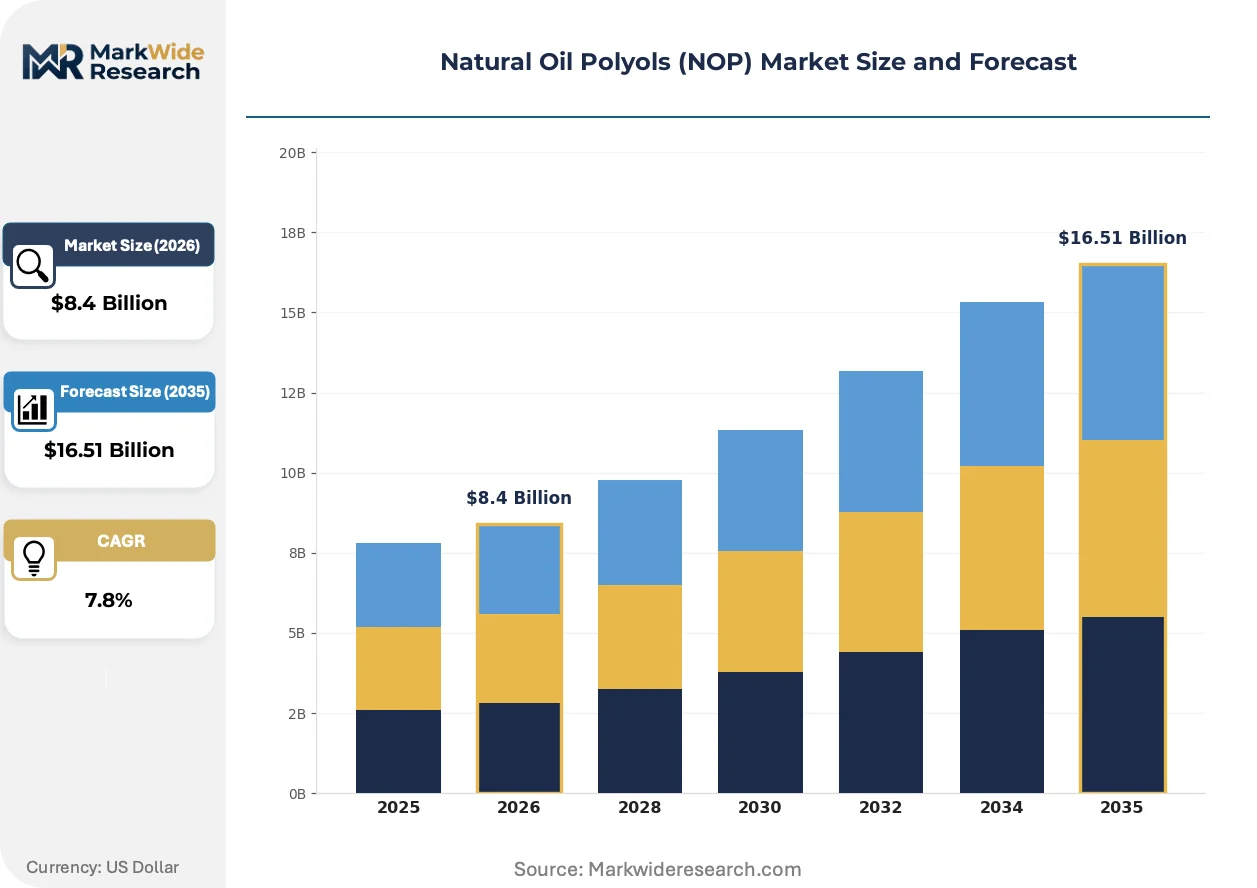
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $16.51 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyether, Polyester, Biopolyols, Oleochemicals Application: Flexible Foam, Rigid Foam, Coatings, Adhesives End User: Automotive, Construction, Furniture, Consumer Goods Technology: Chemical Synthesis, Biochemical Processes, Polymerization, Esterification |
| Companies Covered | Croda International PLC, Stepan Company, Cargill Incorporated, Mitsui Chemicals, Inc., Elevance Renewable Sciences Inc., BASF SE, Oléon-Novance (Avril), Emery Oleochemicals, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Oil Polyols (NOP) Market Emerging Trajectories
Process intensification and regulatory alignment are reshaping how vegetable-oil feedstocks compete with petrochemical routes, with technology fragmentation creating parallel supply tiers rather than consolidated substitution.
Next-generation transesterification catalysts are fragmenting the technical landscape between enzymatic and heterogeneous chemical pathways. Tier-one automotive suppliers in Germany and China are piloting both routes simultaneously. The resulting process diversity is fragmenting equipment vendor relationships and fragmenting technical service requirements across regional supply bases.
EPA's expanded BioPreferred labeling requirements and ECHA's microplastic restriction proposals are jointly elevating scrutiny of synthetic polymer feedstocks. European coatings formulators face reformulation deadlines that compress R&D timelines. The construction insulation segment is responding fastest, with German rigid foam producers accelerating NOP qualification programs ahead of 2027 building code revisions.
Automotive seating buyers are consolidating supplier relationships around vertically integrated oilseed-to-polyol producers capable of certifying chain-of-custody bio-content. Tier-one procurement teams in Detroit and Stuttgart are displacing multi-source commodity purchasing with sole-source partnership models. Brazil and China show the most visible concentration, where local crushing capacity determines supplier selection criteria.
Natural Oil Polyols (NOP) Market Segmentation
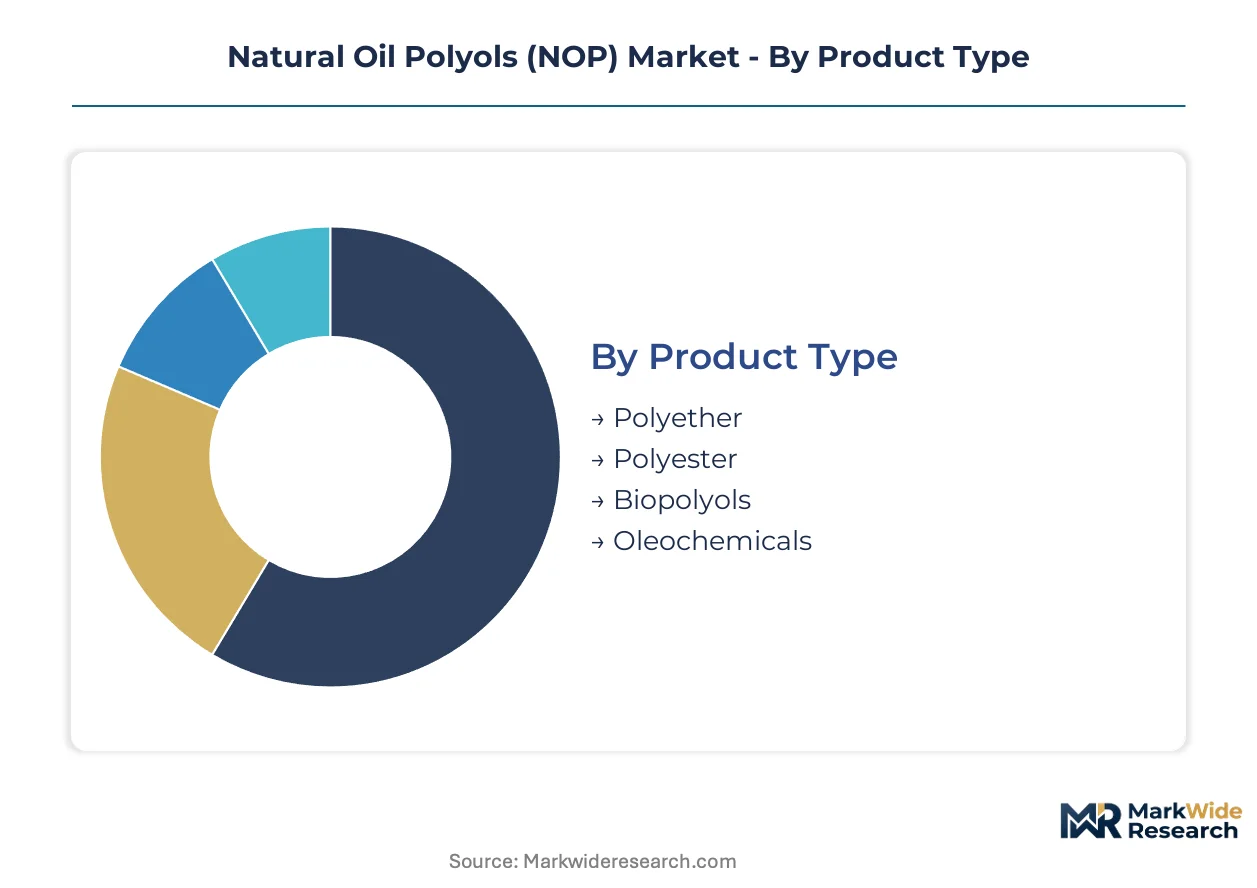
Segmentation in natural oil polyols reveals how feedstock chemistry, processing intensity, and end-use certification requirements fragment margin capture across the value chain. Buyers prioritize different performance attributes—automotive seating demands consistent hydroxyl values, while construction insulation prioritizes cost-per-R-value—creating parallel specification tiers.
Product Type:
Margin pools concentrate in specialty biopolyols where ASTM D6866 certification commands formulation premiums, while commodity polyether competes on throughput scale.
- Polyether:Mature processing infrastructure supports broad isocyanate compatibility across flexible foam applications. Automotive seating plants in Stuttgart and Detroit specify polyether-based systems for validated supply security under compressed OEM timelines.
- Biopolyols:Hydroxyl-functionalized vegetable oil derivatives achieve cost parity with petrochemical routes in North American flexible foam production. REACH substance restrictions and EPA BioPreferred procurement jointly redirect formulation investments toward certified bio-content grades.
- Polyester:Ester backbone structures serve niche coatings applications requiring hydrolytic stability.
- Oleochemicals:Basic fatty acid derivatives supply intermediate positions in personal care and lubricant adjacents.
The dominant share belongs to polyether, while biopolyols are closing the gap fastest.
Application:
Application segmentation tracks regulatory pressure intensity, with coatings facing the tightest VOC constraints and rigid foam tied to building code enforcement.
- Flexible Foam:Polyurethane cushioning for automotive seating and furniture applications demands consistent load-bearing properties. German and Chinese tier-one suppliers are validating natural oil polyol formulations ahead of petroleum-derived alternatives under tightening OEM sustainability mandates.
- Coatings:Decorative and industrial finishes face ECHA microplastic restriction proposals and EPA VOC limits. Low-VOC biopolyol grades command 15-25 percent formulation premiums in European architectural coatings.
- Rigid Foam:Insulation panels for construction thermal performance. Germany's EnEV standards and comparable Chinese building codes drive specification of high-functionality NOP grades.
- Adhesives:Bonding applications in packaging and assembly where bio-content certification supports brand positioning.
Flexible foam holds the largest volume position, though coatings delivers the steepest margin expansion trajectory.
End User:
End user segmentation reflects procurement consolidation patterns, with automotive buyers consolidating around vertically integrated suppliers capable of chain-of-custody certification.
- Automotive:Seating, interior trim, and underhood applications where OEM sustainability mandates compress specification cycles. Tier-one suppliers in Detroit and Stuttgart are displacing multi-source commodity purchasing with sole-source partnership models anchored to crushing capacity.
- Construction:Insulation panels and spray foam governed by national energy-efficiency codes. São Paulo and Rio de Janeiro metro regions drive import-substitution potential for local NOP production under Brazilian building regulations.
- Furniture:Bedding and cushioning where legacy petroleum-polyol supply relationships face gradual displacement.
- Consumer Goods:Molding applications where FDA food-contact guidelines and OSHA workplace exposure limits constrain conventional polyol handling.
Construction maintains the deepest volume base, while automotive is expanding most quickly as procurement shifts accelerate.
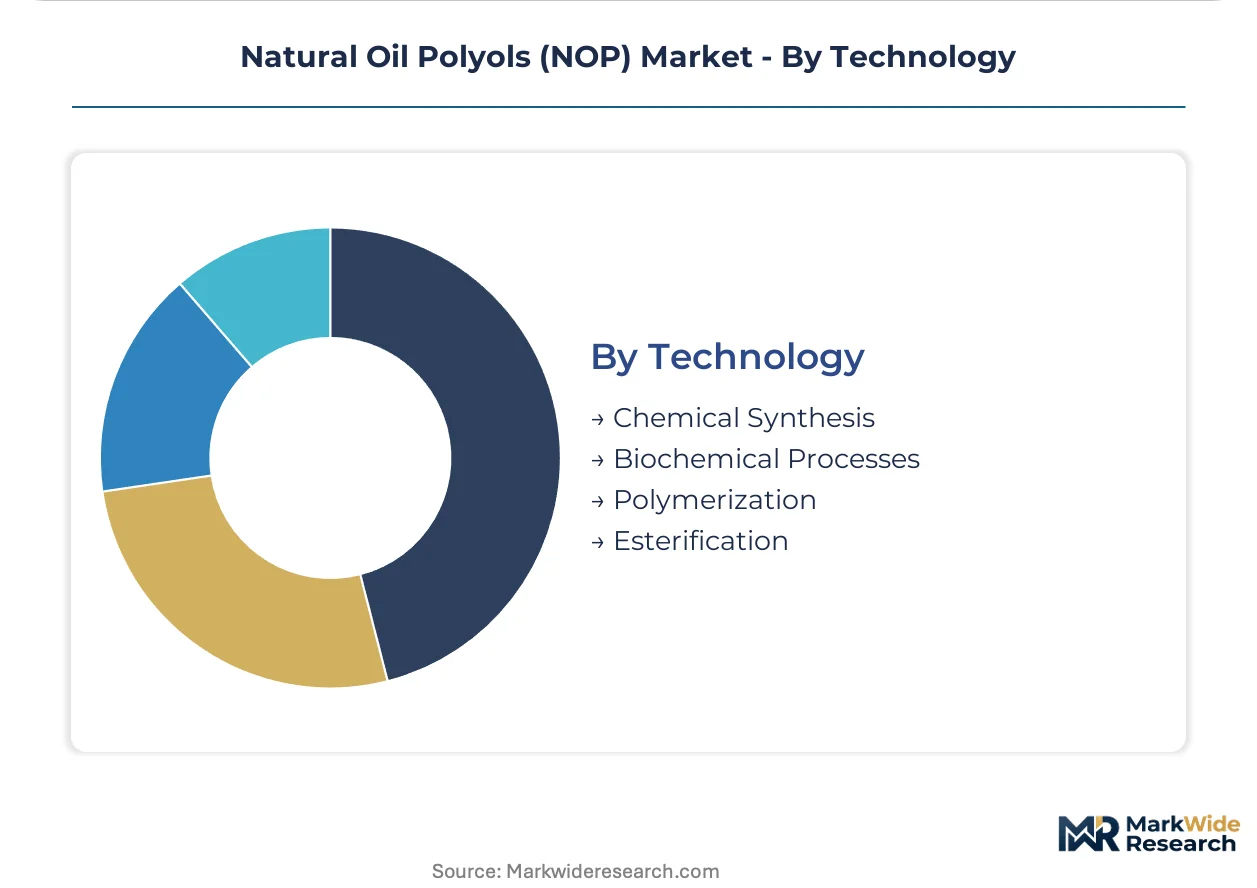
Technology:
Technology segmentation fragments between capital-intensive chemical synthesis and emerging biochemical routes, with catalyst selection determining regional equipment vendor relationships.
- Chemical Synthesis:Epoxidation-ring opening and transesterification via heterogeneous catalysis dominate current flexible foam production. Advanced catalytic pathways for soybean and castor oil modification achieve cost parity with petrochemical polyols at North American processing facilities.
- Biochemical Processes:Enzymatic transesterification and fermentation-derived pathways reduce energy intensity. Tier-one automotive suppliers in Germany and China are piloting enzymatic and heterogeneous chemical routes simultaneously, fragmenting technical service requirements.
- Polymerization:Step-growth and addition polymerization for high-functionality rigid foam grades.
- Esterification:Specialty acid-alcohol condensation for coatings-grade biopolyols where Stepan Company's expertise occupies niche premium positions.
Chemical synthesis retains the dominant installed base, though biochemical processes are gaining share fastest as pilot scale-ups advance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Castor oil crushing in Gujarat, India, supplies over 60 percent of global feedstock for high-functionality grades, while soybean processing clusters in the United States and Brazil compete for flexible foam volume. This geographic concentration creates divergent regulatory exposure and procurement strategies across major consuming markets.
United States
Automotive seating plants in Detroit and Stuttgart specification cycles drive bio-based polyurethane validation. EPA BioPreferred procurement standards create guaranteed offtake volume for federal construction and furnishing contracts. Iowa and Illinois processing corridors anchor North American soybean oil polyol production.
Germany
EnEV building energy-efficiency standards mandate rigid foam insulation performance in new construction. ECHA REACH substance restrictions on aromatic amines redirect formulation investments toward vegetable-oil-derived alternatives. Bavarian automotive clusters accelerate NOP qualification ahead of 2027 OEM sustainability deadlines.
China
Construction thermal-performance codes in Beijing-Tianjin-Hebei and Yangtze River Delta regions drive rigid foam specification. MIIT industrial policy supports biobased material substitution in automotive supply chains. Shanghai and Guangzhou tier-one suppliers pilot enzymatic transesterification alongside heterogeneous chemical routes.
Brazil
São Paulo and Rio de Janeiro metro regions generate polyurethane insulation demand under national energy-efficiency building regulations. ANVISA bio-content guidelines align with export market certification requirements. Local soybean crushing capacity determines supplier selection criteria for import-substitution polyol production.
India
Gujarat state dominates global castor oil production, creating geographic single-point vulnerability for specialty grade suppliers. BIS standards for biobased content certification remain under development compared to ASTM D6866 timelines. Maharashtra chemical processing corridors process imported oilseeds for domestic flexible foam applications.
Natural Oil Polyols (NOP) Market Vendor Landscape
Concentration sits with vertically integrated agribusiness conglomerates controlling oilseed crushing and downstream polyol conversion. Three to five multinational chemical specialists compete on polymerization technology and formulation expertise. The vendor base separates into captive feedstock operators, technology licensors, and specialty esterification houses. Capacity expansion and strategic partnerships dominate competitive moves as OEMs consolidate supplier relationships around chain-of-custody certification capability.
Among integrated agribusiness operators, Cargill Incorporated anchors North American supply chains through captive soybean processing. BASF SE and Stepan Company exemplify divergent technology-led strategies—BASF sustaining R&D intensity in high-performance rigid foam formulations, Stepan occupying niche coatings-grade positions through specialty esterification expertise. Mitsui Chemicals, Inc. represents Asian chemical conglomerate participation in regional biopolyol development.
| Leading Market Players |
|---|
| Croda International PLC |
| Stepan Company |
| Cargill Incorporated |
| Mitsui Chemicals, Inc. |
| Elevance Renewable Sciences Inc. |
| BASF SE |
| Oléon-Novance (Avril) |
| Emery Oleochemicals |
| Covestro AG |
| Others |
Supply Flow & Price Mechanics
ASTM D6866 radiocarbon certification gates both supply qualification and price differentiation simultaneously, forcing formulators to absorb 6-12 month validation timelines before accessing premium tiers while buyers demand documented bio-content for specification lock-in.
Pricing Analysis
REACH substance restrictions dictate the pricing tier structure across European automotive and construction applications. Three-tier pricing structure across premium, standard, and economy levels separates ASTM-certified biopolyols from uncertified grades and commodity polyether alternatives. Cost compression in standard-tier flexible foam is intensifying because soybean oil commodity swings transmit directly to feedstock costs. Tier-one automotive seating buyers show least price sensitivity due to sole-source partnership models, while furniture molders remain most sensitive to per-kilogram differentials.
Supply Chain Analysis
India and Brazil anchor global castor and soybean oil feedstock production respectively. Gujarat state draws from over 60 percent of worldwide castor crushing capacity, while Iowa and Illinois corridors source from North American soybean processing clusters. Single-source vulnerability concentrates in Indian castor supply for high-functionality grades. Distribution runs through vertically integrated oilseed-to-polyol producers capable of chain-of-custody certification.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Natural oil polyols sit in early-cycle expansion as automotive OEM sustainability mandates compress specification cycles ahead of petroleum-derived alternatives, creating first-mover advantages for validated suppliers.
For Market Incumbents: Secure formulation lock-in at major OEMs before 18-24 month requalification cycles harden around incumbent polyether systems. Deepen backward integration into crushing operations to buffer margin stability against oilseed commodity swings. Prioritize ASTM D6866 certification investment to defend premium positioning against emerging biochemical pathway competitors. For New Entrants and Emerging Players: Lead with coatings-grade biopolyol white space where specialty esterification expertise commands formulation premiums in low-VOC decorative and industrial finishes. Target São Paulo and Rio de Janeiro metro construction clusters under Brazilian energy-efficiency building codes for import-substitution positioning. Emphasize enzymatic transesterification pilot credentials to differentiate from heterogeneous chemical route incumbents. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across biochemical process pilot scale-ups as enzymatic pathways advance toward commercial viability. Five-to-ten year viability favors acquisition targets with captive oilseed crushing and downstream polyol conversion capabilities. Watch for tier-one automotive supplier consolidation announcements as signal of specification cycle hardening.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Cargill's captive soybean processing anchors North American supply security against commodity volatility. |
| ASTM D6866 Certification Investment | Documented bio-content unlocks EPA BioPreferred federal procurement mandates for guaranteed offtake volume. |
| Enzymatic Transesterification Scale-Up | German and Chinese tier-one suppliers pilot reduced energy intensity routes to challenge chemical synthesis economics. |
| Coatings-Grade Specialty Esterification | Stepan's niche expertise captures 15-25 percent formulation premiums in low-VOC architectural applications. |
| Brazilian Local Production Partnership | São Paulo metro insulation demand under national building codes creates import-substitution opportunity for crushing-integrated entrants. |
Methodological Framework
Operator-level perspectives from polyol plant managers, tier-one automotive procurement leads, coatings formulators, and oilseed crushing operations anchored the qualitative base. Primary interview findings triangulated against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and OEM sustainability disclosure documents. Bottom-up volume modeling across feedstock chemistry and application segments converged with top-down market sizing from regulatory mandate penetration rates.
Sensitivity analysis tested forecast robustness across oilseed price volatility scenarios and certification timeline delays over the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry, technology pathway, and regional production hub clustering. CAGRs derived from regression analysis of historical substitution rates against regulatory enforcement intensity, incorporating construction energy-efficiency code adoption curves and automotive OEM mandate disclosure timelines as industry-specific inputs.
Forecasts assume regulatory continuity in REACH substance restrictions and EPA BioPreferred procurement standards; material policy shifts would require re-modeling. Specific risks include ECHA microplastic restriction proposal implementation scope and isocyanate pairing compatibility breakthroughs altering substitution economics. Recalibration cycles align with material shifts in OEM specification timelines and bio-content certification scheme harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Styrene Acrylonitrile (SAN) Resins Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Europe Superabsorbent Polymers Market
Polymers & Resins
Caprolactam (Nylon 6 Fiber and Nylon 6 Resin) Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polycarbonate Resin Market
Polymers & Resins
Medical Polymers Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Global Polyamide Market
Polymers & Resins
North America and Europe Phenolic Resin Market