
 Chemical Synthesizer Market | 2026-2036
Chemical Synthesizer Market Size, Share, and Industry Trends Forecast 2026-2036
Chemical Synthesizer Market Outlook
The EU Green Deal is decoupling European process chemistry from solvent-heavy batch traditions. Thermo Fisher Scientific leverages its integrated systems portfolio to anchor North American laboratory demand. Merck KGaA sustains dominance in high-purity reagent supply chains across German pharmaceutical clusters. BASF competes through backward integration into catalytic process development at its Ludwigshafen headquarters.
A chemical synthesizer is an automated or semi-automated reactor system that executes controlled chemical reactions with precise temperature, pressure, and stoichiometric parameters, typically operating between -80°C and 300°C with bar-to-megapascal pressure ranges. Its primary industrial purpose is to manufacture active pharmaceutical ingredients, agrochemical intermediates, and specialty molecules with reproducible yield profiles and minimized human intervention. Continuous flow reactor systems are capturing margin pools from batch reactors in pharmaceutical applications where reaction selectivity directly determines downstream purification costs. Microreactor technology leads growth in electrochemical synthesis segments where surface-area-to-volume ratios enable dangerous chemistries at bench scale. Catalytic processes remain the mature revenue base, though photocatalysis segments are expanding fastest among research institutions pursuing visible-light-driven bond formations.
EPA industrial effluent guidelines and REACH substance authorization requirements are forcing solvent recovery retrofits onto legacy batch installations across US and European manufacturing sites. FDA process analytical technology guidance shapes demand for real-time spectroscopic monitoring modules that verify reaction completion before workup. China's GB standards on chemical process safety and SAMR equipment certification rules govern market access for imported synthesis platforms. Stakeholders must monitor how electrochemical synthesis patent landscapes evolve as pharmaceutical firms evaluate capital shifts away from precious-metal catalysis.
Market Dynamics
Continuous flow reactor systems are rewriting competitive economics in pharmaceutical process chemistry by collapsing purification costs through superior reaction selectivity. The EU Green Deal's solvent restrictions and FDA process analytical technology mandates are forcing parallel capital redeployment across legacy batch infrastructure.
Growth Catalysts
- EU Green Deal decarbonization mandates:Solvent-intensive batch processes face phase-out timelines across German and Dutch chemical corridors, redirecting capital toward closed-loop synthesis platforms.
- Microreactor electrochemistry:Surface-area-to-volume ratios enable hazardous chemistries at bench scale, opening patent white space previously inaccessible to pharmaceutical discovery teams.
- FDA process analytical technology guidance:Real-time spectroscopic monitoring modules are becoming mandatory for reaction completion verification, embedding hardware demand into regulatory compliance budgets.
Market Restraints
- Precious-metal catalyst cost volatility:Ruthenium and iridium price swings compress margin predictability for contract manufacturers dependent on homogeneous catalysis.
- REACH substance authorization delays:ECHA's backlog in novel reagent approvals extends commercialization timelines for innovative synthesis routes by 18-36 months.
- Photocatalysis technical immaturity:Visible-light-driven bond formation remains confined to gram-scale demonstration, limiting industrial adoption despite research interest.
Strategic Opportunities
- India's PLI scheme for active pharmaceutical ingredients:Domestic synthesis platform demand is accelerating as import substitution policies reshape procurement geography.
- Electrochemical synthesis patent expiration wave:Pharmaceutical firms are evaluating capital shifts away from precious-metal catalysis as foundational electrochemistry patents enter public domain.
- Modular continuous flow skids:Containerized reactor systems are penetrating distributed manufacturing networks, enabling point-of-use synthesis for high-potency compounds.
Industry Challenges
- Process chemist talent scarcity:The intersection of flow chemistry expertise and regulatory submission experience commands premium compensation, constraining scale-up velocity.
- Legacy batch retrofit complexity:Brownfield solvent recovery installations require extended downtime coordination with commercial production schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chemical Synthesizer Market |
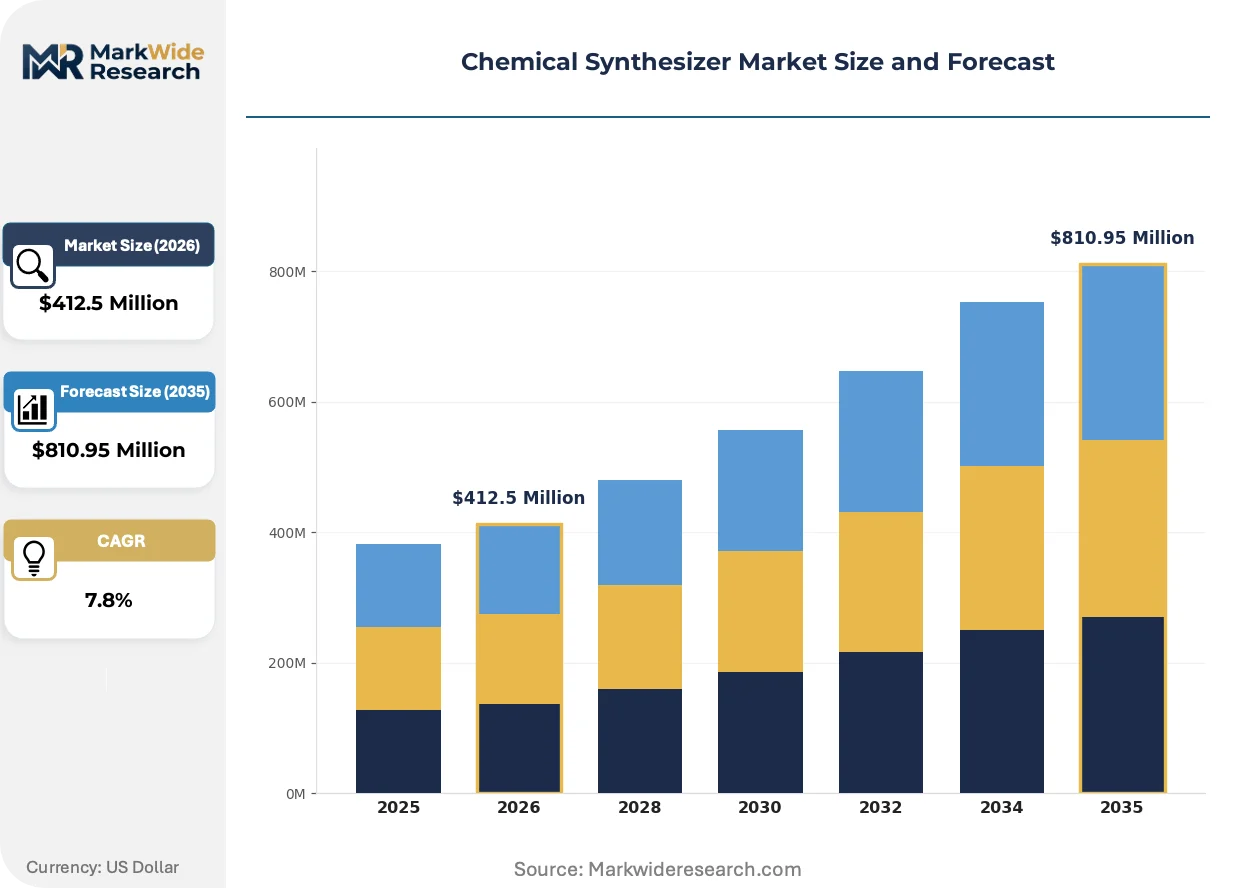
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $810.95 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Flow, Batch Reactors, Microreactors, Integrated Systems Application: Pharmaceuticals, Agrochemicals, Specialty Chemicals, Biofuels Technology: Catalytic Processes, Electrochemical Synthesis, Photocatalysis, Biocatalysis End User: Manufacturers, Research Institutions, Biotechnology Firms, Government Labs |
| Companies Covered | Thermo Fisher Scientific, Merck KGaA, Agilent Technologies, BASF, Lonza Group, Danaher Corporation, Evonik Industries, Waters Corporation, MilliporeSigma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chemical Synthesizer Market Strategic Shifts
Automation architectures are compressing the gap between discovery-scale experimentation and manufacturing-scale deployment. Three distinct vectors are reconfiguring how synthesis platforms are specified, procured, and operated across pharmaceutical and agrochemical value chains.
Microreactor technology is rewriting the risk calculus for exothermic and toxic chemistries. Pharmaceutical discovery groups at Merck KGaA and BASF are deploying electrochemical microreactors for nitration and fluorination steps previously requiring dedicated hazard facilities. The surface-area-to-volume geometry permits thermal runaway containment without engineered relief systems, collapsing capital requirements for dangerous reaction classes.
REACH substance authorization requirements are forcing solvent recovery retrofits onto legacy batch installations across European manufacturing sites. ECHA's tightening restrictions on dipolar aprotic solvents are redirecting process development toward aqueous and supercritical CO2 media. German pharmaceutical clusters around Ludwigshafen are prioritizing catalytic hydrogen transfer methods that eliminate stoichiometric reductant waste streams.
Service unbundling is fragmenting the traditional synthesis platform procurement model. Pharmaceutical manufacturers are separating hardware acquisition from method development contracts, engaging specialized flow chemistry consultancies for process translation rather than turnkey system vendors. This pattern concentrates in mid-sized European contract manufacturers lacking in-house continuous flow expertise but facing EU Green Deal compliance deadlines.
Chemical Synthesizer Market Segmentation
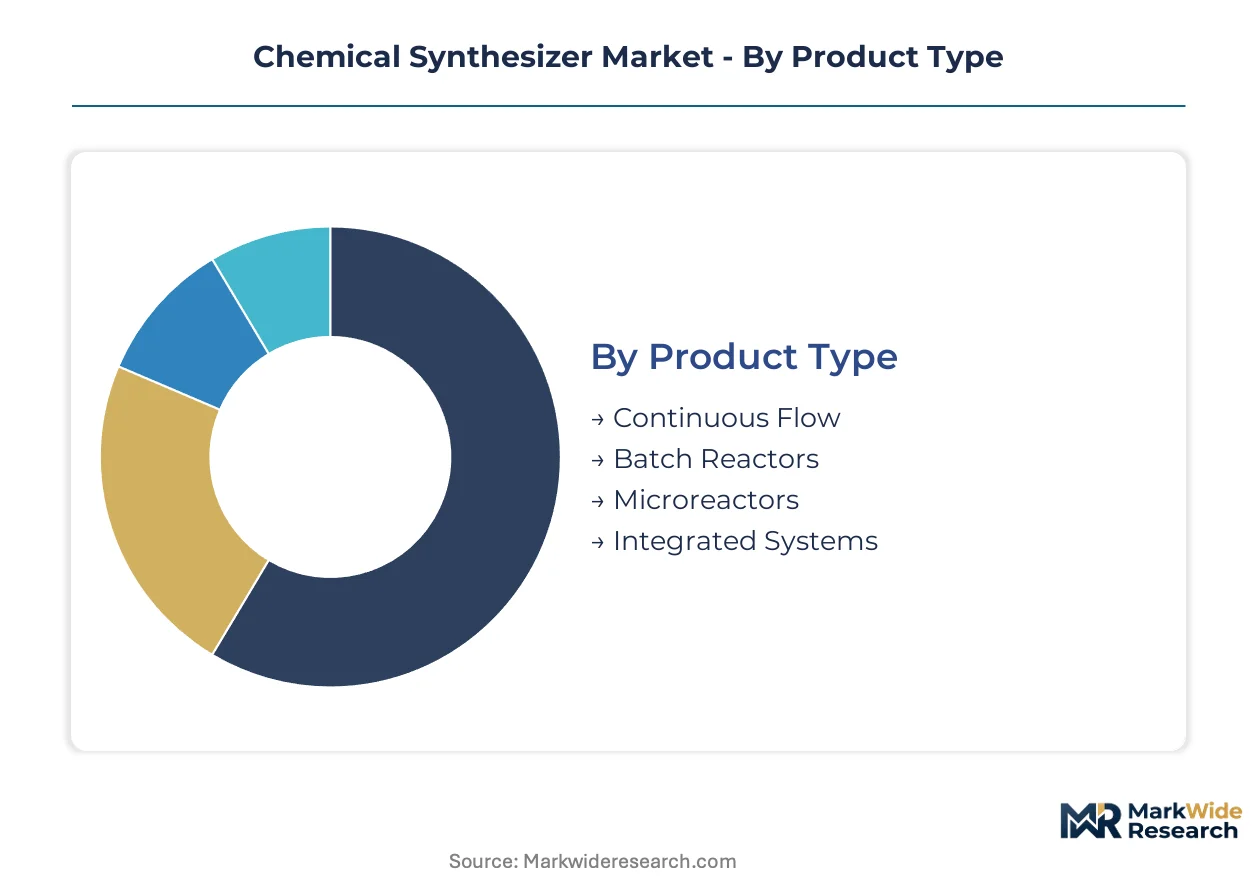
Procurement patterns diverge sharply between mass-scale pharmaceutical manufacturers seeking throughput certainty and research institutions prioritizing experimental flexibility. Understanding these fault lines clarifies where technology investments concentrate and which synthesis modalities capture capital allocation.
Product Type:
Capital deployment intensity separates buyers in this category, with large manufacturers favoring integrated platforms while contract research organizations minimize upfront commitment.
- Continuous Flow:These systems channel reagents through fixed-bed or tubular reactors under precise thermal and pressure control, enabling reaction times from milliseconds to minutes. Pharmaceutical manufacturers at BASF's Ludwigshafen complex deploy these for high-volume active pharmaceutical ingredient steps where selectivity directly determines downstream crystallization burden. FDA process analytical technology mandates accelerate replacement of legacy batch infrastructure with real-time monitored flow architectures.
- Batch Reactors:Vessel-based systems execute discrete reaction cycles with complete material loading and unloading sequences, dominating existing installed bases across solvent-intensive process chemistry. German chemical clusters face EU Green Deal solvent restriction timelines that compress remaining economic life for unretrofitted batch assets, forcing accelerated depreciation decisions.
- Microreactors:Millimeter-scale channel geometries deliver extreme surface-area-to-volume ratios for hazardous chemistries.
- Integrated Systems:Pre-configured platforms combine reaction, workup, and analytical modules for rapid deployment.
Volume sits with Batch Reactors; growth tilts toward Continuous Flow.
Application:
Regulatory stringency and molecule complexity determine synthesis platform specifications across end-use verticals.
- Pharmaceuticals:Active pharmaceutical ingredient manufacturing demands reproducible yield profiles and exhaustive documentation for regulatory submission. Thermo Fisher Scientific anchors North American laboratory demand with integrated systems that compress method transfer from discovery to quality control.
- Agrochemicals:Intermediate synthesis for crop protection chemistry operates at larger scale with lower purity thresholds than pharmaceutical applications. Merck KGaA sustains dominance in high-purity reagent supply chains across German agricultural chemistry clusters.
- Specialty Chemicals:Custom synthesis for electronics, coatings, and fragrance molecules requires rapid campaign changeover.
- Biofuels:Catalytic upgrading of lipid and lignocellulosic feedstocks employs high-pressure hydrogenation platforms.
Revenue concentrates in Pharmaceuticals; Specialty Chemicals gain share fastest.
Technology:
Maturity gradients separate established catalytic methods from emerging modalities still confined to demonstration scale.
- Catalytic Processes:Heterogeneous and homogeneous catalysis remain the mature revenue base, with precious-metal systems dominating pharmaceutical carbon-carbon and carbon-heteroatom bond formation. Ruthenium and iridium price volatility compress margin predictability for contract manufacturers dependent on homogeneous catalysis.
- Electrochemical Synthesis:Direct electron-driven bond formation eliminates stoichiometric oxidant or reductant requirements, collapsing waste generation. Microreactor electrochemistry enables hazardous chemistries at bench scale, opening patent white space previously inaccessible to pharmaceutical discovery teams.
- Photocatalysis:Visible-light-driven reactions remain confined to gram-scale demonstration despite research interest.
- Biocatalysis:Enzyme-mediated transformations deliver stereoselectivity unattainable through chemical catalysis.
Deployment volume favors Catalytic Processes; Electrochemical Synthesis shows steepest expansion trajectory.
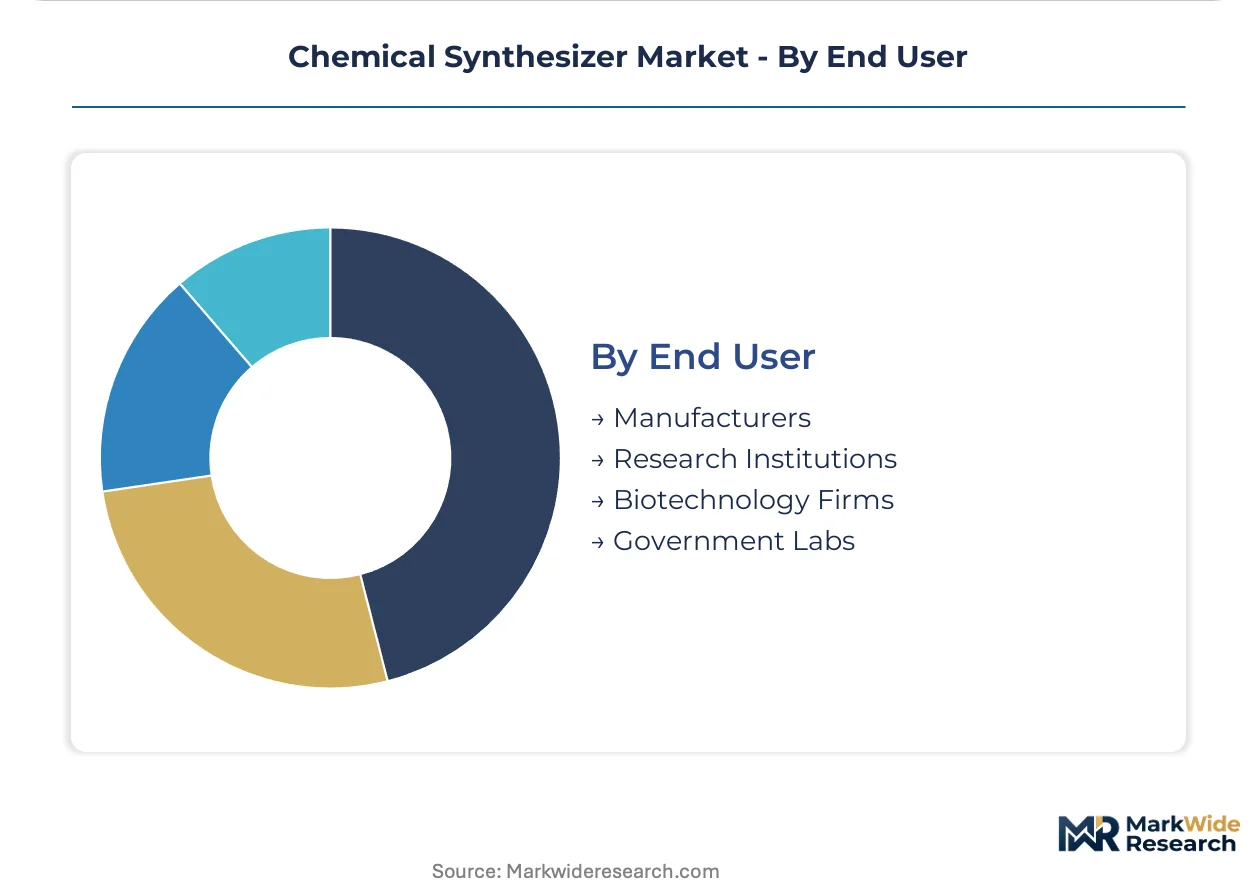
End User:
Organizational scale and regulatory exposure shape procurement authority and platform sophistication requirements.
- Manufacturers:Commercial-scale pharmaceutical and agrochemical producers specify systems for validated, reproducible production with full batch records. India's PLI scheme for active pharmaceutical ingredients accelerates domestic synthesis platform demand as import substitution policies reshape procurement geography.
- Research Institutions:Academic and government laboratories prioritize experimental flexibility and publication-grade data generation over throughput metrics. Process chemist talent scarcity at the intersection of flow chemistry expertise and regulatory submission experience constrains scale-up velocity for institutions lacking manufacturing partnerships.
- Biotechnology Firms:Cell therapy and biologic developers require specialized synthesis for linker-payload and modified nucleotide production.
- Government Labs:National research facilities pursue early-stage technology demonstration with limited commercialization timelines.
Capital deployment concentrates with Manufacturers; Biotechnology Firms expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates production capacity for high-purity synthesis platforms while the United States absorbs the largest share of laboratory-scale demand. India and China are scaling domestic manufacturing under import substitution mandates. Switzerland and Japan retain specialized positions in precision instrumentation and catalytic process development.
Germany
Pharmaceutical manufacturers at BASF's Ludwigshafen complex and Bayer's Leverkusen headquarters deploy continuous flow systems for active pharmaceutical ingredient production. The EU Green Deal's solvent restriction timelines force accelerated depreciation of unretrofitted batch assets across the chemical corridor. ECHA's REACH substance authorization backlog extends commercialization timelines for novel synthesis routes by 18-36 months.
United States
FDA process analytical technology guidance embeds hardware demand for real-time spectroscopic monitoring into regulatory compliance budgets. EPA industrial effluent guidelines mandate solvent recovery retrofits onto legacy batch installations across pharmaceutical manufacturing sites. Thermo Fisher Scientific anchors laboratory demand through integrated systems that compress method transfer from discovery to quality control.
India
The PLI scheme for active pharmaceutical ingredients accelerates domestic synthesis platform procurement as import substitution policies reshape procurement geography. CDSCO's tightening process validation requirements drive adoption of automated platforms with exhaustive batch documentation capabilities. Contract manufacturers in Hyderabad and Ahmedabad face talent scarcity at the intersection of flow chemistry expertise and regulatory submission experience.
China
GB standards on chemical process safety and SAMR equipment certification rules govern market access for imported synthesis platforms. Domestic pharmaceutical clusters in Jiangsu and Zhejiang provinces scale electrochemical synthesis capacity as foundational patents enter the public domain. NMPA's alignment with ICH guidelines accelerates demand for platforms supporting regulatory submission packages.
Switzerland
Specialty chemical manufacturers around Basel leverage precision engineering capabilities for high-pressure hydrogenation and supercritical CO2 platforms. Swissmedic's stringent manufacturing authorization requirements favor validated, reproducible production systems with full batch records. Lonza Group's Visp facility exemplifies integration of continuous flow architectures into commercial-scale biologic manufacturing.
Chemical Synthesizer Market Competitive Environment
The competitive structure tilts toward diversified laboratory technology conglomerates with integrated systems portfolios. Three archetypes dominate: precision instrumentation specialists with analytical module integration, chemical manufacturers with backward integration into catalytic process development, and contract development organizations with captive synthesis platform deployment. Consolidation pressures concentrate around M&A targeting flow chemistry consultancies and strategic partnerships linking hardware vendors with method development capabilities.
Among diversified laboratory technology conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify the integrated systems archetype that compresses method transfer timelines. Merck KGaA occupies a distinct position as a chemical manufacturer with backward integration into high-purity reagent supply chains. BASF represents the industrial chemical producer archetype with captive catalytic process development capabilities at its Ludwigshafen headquarters.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Merck KGaA |
| Agilent Technologies |
| BASF |
| Lonza Group |
| Danaher Corporation |
| Evonik Industries |
| Waters Corporation |
| MilliporeSigma |
| Others |
Value Chain & Pricing Dynamics
Ruthenium and iridium price indices cascade through contract manufacturing economics, compressing margin predictability for homogeneous catalysis-dependent producers while forcing tiered pricing stratification across precious-metal-intensive versus base-metal synthesis platforms.
Pricing Analysis
Yield-guarantee contracts anchor value-based pricing for continuous flow reactor systems, with pharmaceutical manufacturers paying premium tariffs for validated throughput commitments and real-time spectroscopic monitoring modules. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated production systems from laboratory-scale research units and refurbished legacy batch assets. Cost compression in standard-tier equipment is intensifying because Chinese domestic manufacturers are scaling electrochemical synthesis capacity under SAMR certification rules. Contract research organizations exhibit highest price sensitivity, prioritizing leasing arrangements and method-development-unbundled procurement over capital-intensive integrated platform acquisitions.
Supply Chain Analysis
Precious-metal catalyst supply rests on South African platinum-group metal refiners, German specialty chemical producers around Ludwigshafen, and Chinese rare earth processors in Jiangxi province. High-purity stainless steel reactor vessels, quartz microchannel substrates, and spectroscopic-grade optical components constitute critical component dependencies. Single-source vulnerability concentrates in iridium crucible supply for high-temperature catalytic applications. Distribution runs through authorized distributor networks serving pharmaceutical clusters, with direct OEM relationships dominating large manufacturer procurement above threshold scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
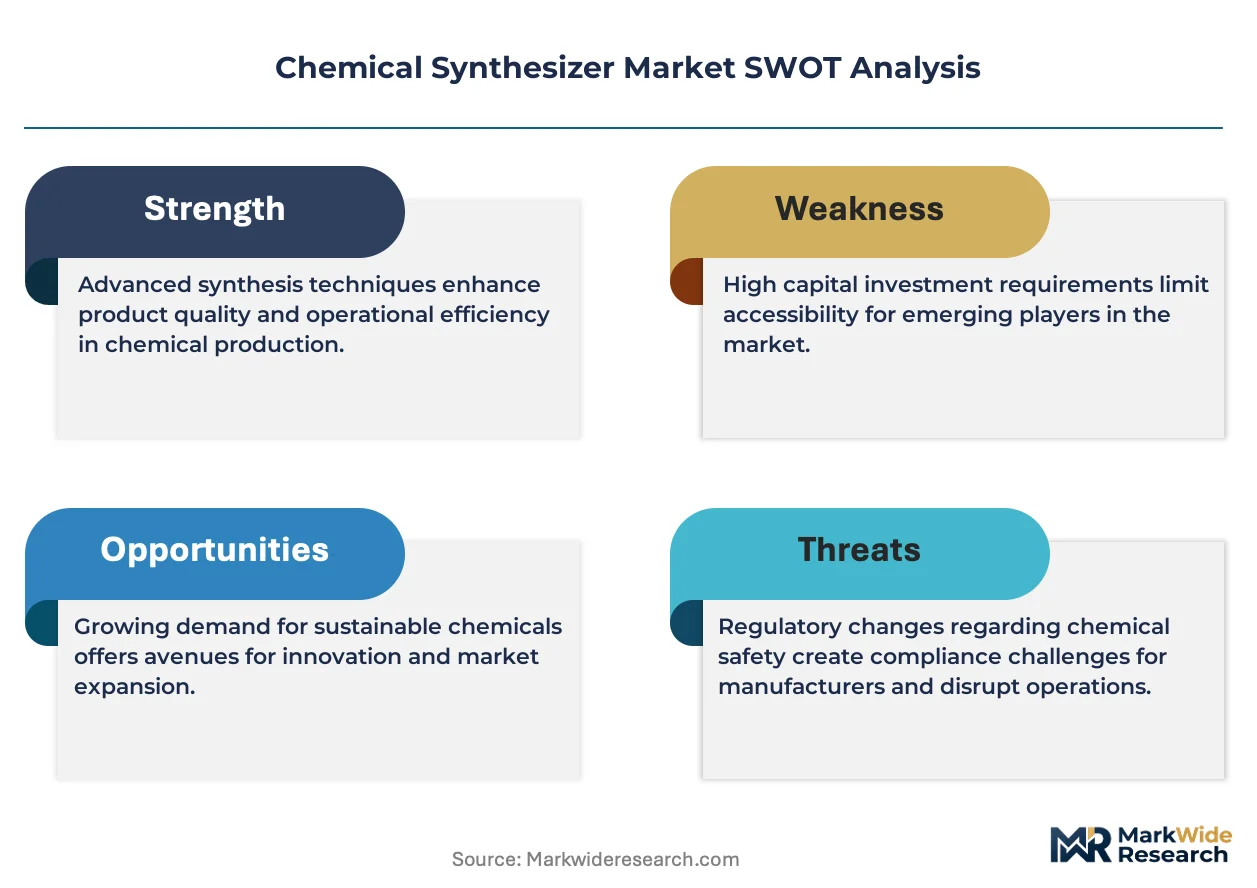
Specialized flow chemistry engineering talent scarcity props pricing power for incumbent platform vendors, constraining rapid capacity expansion despite accelerating EU Green Deal compliance deadlines.
For Market Incumbents: Anticipate electrochemical synthesis patent expiration waves eroding precious-metal catalyst lock-in, and preemptively acquire flow chemistry consultancies in German chemical corridors to capture unbundled method development demand. Backward integration into catalytic process development at Ludwigshafen-scale facilities defends margin position against modular continuous flow skid competitors penetrating distributed manufacturing networks. For New Entrants and Emerging Players: Microreactor electrochemistry for hazardous nitration and fluorination steps offers the most penetrable white space, with pharmaceutical discovery groups at Merck KGaA and BASF actively outsourcing bench-scale dangerous chemistry capabilities. India's PLI scheme for active pharmaceutical ingredients creates geographic procurement shift opportunity for domestic synthesis platform assembly. Containerized reactor systems for point-of-use high-potency compound production provide differentiated go-to-market positioning against integrated platform incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap European contract manufacturers facing EU Green Deal solvent restriction timelines but lacking in-house continuous flow expertise, with extended depreciation decisions forcing asset sales. Long-term viability centers on electrochemical synthesis capability stacks displacing homogeneous catalysis dependency. Watch ECHA REACH substance authorization backlog resolution velocity as inflection indicator for novel reagent commercialization timeline compression.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalytic Process Development | BASF's Ludwigshafen headquarters exemplifies captive capability reducing precious-metal cost volatility exposure. |
| Acquisition of Flow Chemistry Consultancies | Service unbundling concentrates procurement authority with specialized method development partners rather than turnkey vendors. |
| Modular Continuous Flow Skid Deployment | Containerized systems penetrate distributed manufacturing networks for high-potency pharmaceutical compound point-of-use synthesis. |
| Electrochemical Synthesis Patent Positioning | Foundational electrochemistry patent expirations enable capital shifts away from ruthenium and iridium dependency. |
| EU Green Deal Compliance Infrastructure Retrofit | ECHA solvent restrictions force accelerated depreciation decisions across unretrofitted batch reactor installed bases. |
Study Parameters
Independent corroboration across process chemist interviews at BASF and Merck KGaA, regulatory affairs leads navigating ECHA REACH submissions, and procurement directors at Indian CDSCO-registered contract manufacturers underwrites the qualitative findings. Secondary validation draws from FDA process analytical technology guidance documents, EPA industrial effluent guideline updates, SAMR equipment certification rulemakings, and SEC 10-K disclosures from diversified laboratory technology conglomerates. Bottom-up synthesis platform shipment data triangulates against top-down pharmaceutical capital expenditure surveys across German, US, Indian, and Chinese manufacturing clusters.
Comparable-period anchoring to pre-EU Green Deal baseline years establishes trajectory calibration for solvent restriction impact modeling across the analysis window. Segmentation dimensions span reactor architecture type, pharmaceutical versus agrochemical application, catalytic versus electrochemical technology modality, and manufacturer versus research institution end-user category. CAGRs derive from installed base replacement velocity assumptions tied to regulatory compliance deadline clustering. Forecast inputs incorporate precious-metal price volatility scenarios and electrochemical synthesis patent landscape evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA authorization backlog extension or sudden iridium supply disruption conditions. Projections reflect documented assumptions regarding EU Green Deal implementation pace and FDA process analytical technology mandate enforcement intensity. A small set of named triggers—REACH substance authorization resolution velocity, electrochemical synthesis patent expiration sequencing, and Indian PLI scheme disbursement timing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Diketene Derivatives Market
Chemical Intermediates
US Acids Market
Chemical Intermediates
Global Glycinates Market
Chemical Intermediates
Nickel Acetate Market
Chemical Intermediates
Pigment Intermediates Market
Chemical Intermediates
Enzyme Substrates Market
Chemical Intermediates
Duloxetine Intermediate and Atorvastatin Intermediates Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Acetamide MEA Market
Chemical Intermediates
Lauoryl Chloride Market
Chemical Intermediates
Methoxypropylamine (MOPA) Market
Chemical Intermediates
Organometallic Compounds Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Metaphenoxy Benzaldehyde (MPBD) Market
Chemical Intermediates
Global Iron Chelates Market
Chemical Intermediates
Metal Alkyls Market