
 Global Alpha Olefins Market | 2026-2036
Global Alpha Olefins Market Size, Share, and Industry Trends Forecast 2026-2036
Global Alpha Olefins Market Analysis
Direct supply contracts between alpha olefin producers and polyethylene manufacturers is tilting toward long-term offtake agreements with embedded price formulas. Chevron Phillips Chemical Company LLC leverages its US Gulf Coast ethylene integration to anchor 1-hexene supply to domestic LLDPE operations. INEOS sustains European market presence through its Chocolate Bayou complex and differentiated co-monomer blends. Shell plc competes via its Geismar, Louisiana, facility and global shipping logistics that reach Asian polymer compounders.
Alpha olefins are linear hydrocarbons with terminal double bonds, typically produced through ethylene oligomerization using either ziegler-type or SHOP (Shell Higher Olefins Process) catalyst systems, yielding chain lengths from C4 to C30+ for downstream functionalization. 1-Hexene and 1-Octene dominate product type volumes as co-monomers in linear low-density polyethylene, where precise branching control determines film tensile strength and seal performance. Surfactant and detergent alcohol applications occupy mature margin pools with stable offtake, while lubricant-grade 1-decene and 1-dodecene segments attract premium pricing from synthetic polyalphaolefin base stock demand.
EPA fuel economy standards and REACH chemical registration requirements shape product purity specifications and market access conditions for alpha olefin derivatives used in automotive and personal care formulations. ECHA substance evaluation protocols and EPA TSCA Section 5 notifications constrain new entrant timelines for novel co-monomer grades. Stakeholders must monitor feedstock cost spreads between ethane and naphtha cracking economics, as these differentials determine regional production competitiveness and capital allocation for oligomerization expansions.
Market Dynamics
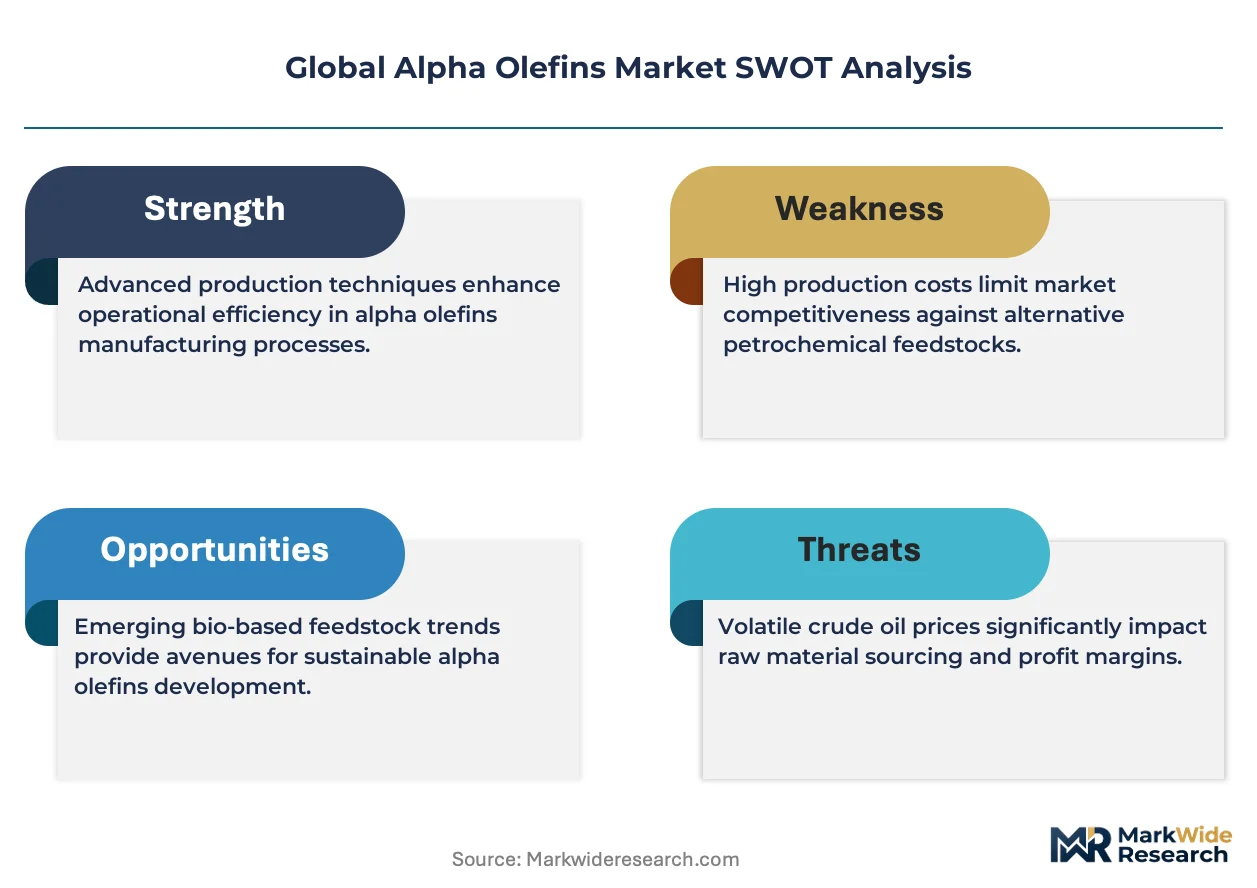
Ethylene feedstock cost differentials between US shale-based ethane and European naphtha cracking are forcing capacity relocation toward the US Gulf Coast and Middle East, compressing European producer margins and reshaping long-term contract structures.
Growth Catalysts
- Automotive Lightweighting Mandates:EPA fuel economy standards and EU CO2 fleet emission targets are accelerating LLDPE penetration in vehicle panels and fuel systems, pulling 1-hexene and 1-octene demand from polymer compounders in Michigan and Lower Saxony.
- REACH Chemical Registration:ECHA substance evaluation protocols for surfactant-grade C12-C14 alpha olefins are locking in compliant suppliers and creating barrier-protected market positions for established European producers.
- Ethylene Oligomerization Advances:Next-generation ziegler-type catalyst systems with improved selectivity toward 1-hexene are reducing byproduct formation and raising nameplate capacity utilization at integrated crackers.
Market Restraints
- Feedstock Cost Volatility:Naphtha cracking economics in Rotterdam and Antwerp remain exposed to Brent crude fluctuations, eroding margin stability for European SHOP-process operators against US ethane-advantaged competitors.
- Supply Concentration Risk:Over half of merchant 1-octene supply originates from three Louisiana corridor facilities, creating vulnerability to Gulf Coast hurricane disruption and pipeline logistics constraints.
- Regulatory Friction:EPA TSCA Section 5 notification requirements for novel co-monomer grades extend commercialization timelines by 18-24 months, delaying specialty alpha olefin introductions.
Strategic Opportunities
- Underpenetrated Indian Polymer Market:BIS certification alignment for LLDPE film grades in Maharashtra and Gujarat packaging hubs offers first-mover positioning as domestic polyethylene capacity scales under PLI scheme incentives.
- Synthetic Lubricant Base Stocks:Polyalphaolefin demand from electric vehicle thermal management fluids is opening premium pricing tiers for 1-decene and 1-dodecene fractions previously confined to industrial applications.
- Maritime Fuel Sulfur Regulations:IMO 2020 low-sulfur marine fuel standards are redirecting refinery C4 streams toward alpha olefin oligomerization, expanding feedstock optionality for integrated producers.
Industry Challenges
- Catalyst Specialist Talent Scarcity:Organometallic chemistry expertise for ziegler and metallocene system optimization is concentrating at three US and German university pipelines, constraining R&D expansion for second-tier producers.
- Legacy System Integration:Digital process control retrofits at 1980s-vintage SHOP units face compatibility gaps with modern distributed control architectures, delaying yield optimization programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Alpha Olefins Market |
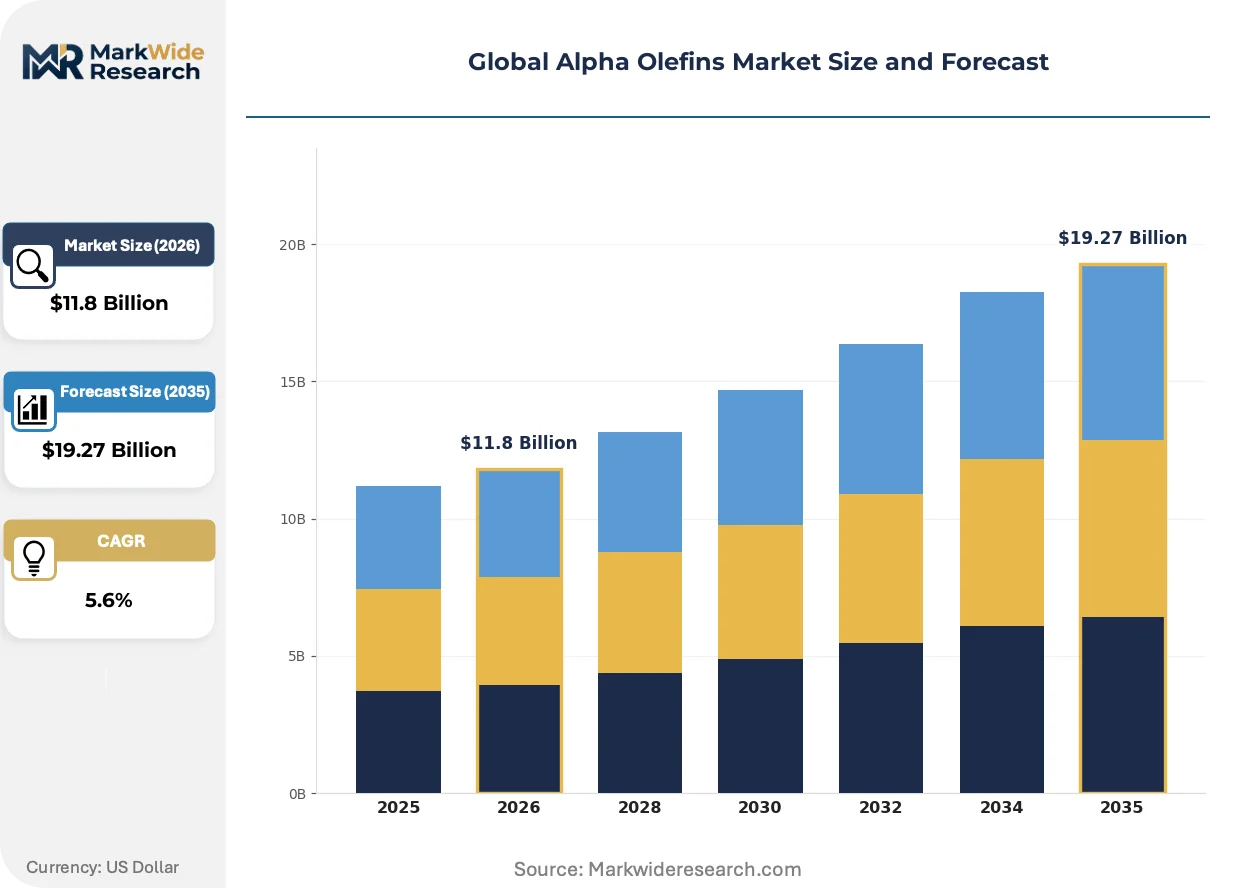
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 1-Hexene, 1-Octene, 1-Decene, 1-Dodecene Application: Detergent Alcohols, Packaging Materials, Lubricants, Surfactants End User: Automotive, Personal Care, Construction, Pharmaceuticals Distribution Channel: Direct Sales, Distributors, Online Retail, Others |
| Companies Covered | Chevron Phillips Chemical Company LLC, INEOS, Shell plc, Exxon Mobil Corporation, SABIC, Sasol Limited, Qatar Chemical Company Ltd, Idemitsu Kosan Co., Ltd., Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Alpha Olefins Market Emerging Trajectories
Process intensification and regulatory compliance automation are converging to redefine production economics, with digital twin deployment and catalyst precision engineering emerging as the primary vectors of competitive differentiation.
Advanced molecular simulation software is virtualizing catalyst design cycles for ethylene oligomerization, compressing experimental screening from months to weeks. Polyethylene producers in Texas and Louisiana are adopting these in-silico platforms to co-develop bespoke 1-hexene/1-octene blends. This capability is virtualizing traditional trial-and-error product development, enabling faster response to automotive OEM specification changes.
REACH authorization requirements for C6-C8 linear alpha olefins used in surfactant applications are tightening purity thresholds for trace aromatic content. European formulators in the Netherlands and Belgium are demanding certificate-of-analysis documentation at ppb detection levels. Specialty detergent alcohol producers are responding by investing in dedicated hydrogenation finishing units to secure downstream supply contracts.
Direct polymer producer-processor partnerships are displacing merchant market spot purchasing for co-monomer grades. LLDPE compounders in China and South Korea are embedding alpha olefin suppliers into multi-year offtake structures with price-indexed formulas. This pattern is most visible in Zhejiang province, where integrated film extruders are consolidating supply relationships to three preferred vendors.
Global Alpha Olefins Market Segmentation
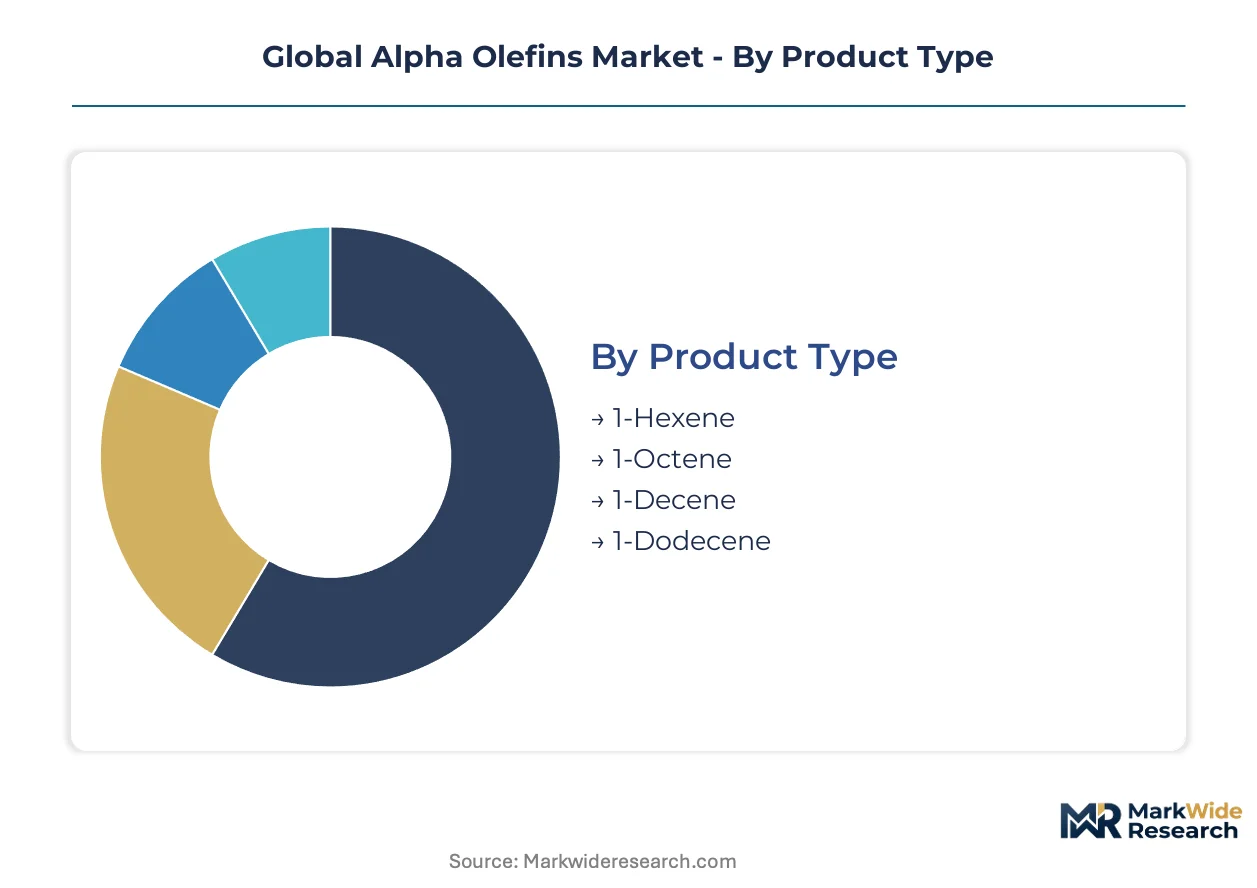
Alpha olefin segmentation tracks molecular chain length precision, downstream functionalization pathways, and procurement channel structures that determine margin capture across polymer, surfactant, and synthetic lubricant value chains.
Product Type:
Carbon chain distribution spans C6 to C12+ fractions, with each grade commanding distinct specification tolerances and end-use premiums based on branching control and terminal double bond purity.
- 1-Hexene:Six-carbon linear alpha olefin serving as the dominant co-monomer for LLDPE film grades. Michigan and Lower Saxony automotive compounders anchor demand through lightweighting programs targeting EPA and EU CO2 compliance.
- 1-Octene:Eight-carbon grade enabling superior tear resistance in high-performance packaging films. Zhejiang province extruders in China are embedding this grade into multi-year offtake contracts with price-indexed formulas tied to ethylene spreads.
- 1-Decene:Ten-carbon fraction refined into synthetic polyalphaolefin base stocks for thermal management fluids in electric vehicles.
- 1-Dodecene:Twelve-carbon grade supplying detergent alcohol precursors subject to REACH purity thresholds for trace aromatic content.
The dominant share belongs to 1-Hexene, while 1-Octene is closing the gap fastest.
Application:
Functional end-uses divide between polymer co-monomer absorption, surface-active formulations, and friction-reduction chemistry, with regulatory purity gates determining supplier qualification.
- Packaging Materials:LLDPE film and sheet applications consuming 1-hexene and 1-octene for seal strength and puncture resistance. Maharashtra and Gujarat packaging hubs under India's PLI scheme are scaling domestic polyethylene capacity.
- Lubricants:Synthetic base stock formulations leveraging 1-decene and 1-dodecene for viscosity index stability. Electric vehicle thermal management specifications from OEMs in Germany and South Korea are opening premium pricing tiers.
- Detergent Alcohols:Ethoxylated surfactant precursors derived from C12-C14 cuts. ECHA substance evaluation protocols for REACH compliance are locking in approved supplier lists at ppb detection thresholds.
- Surfactants:Industrial and personal care formulations requiring narrow polydispersity. Rotterdam and Antwerp formulators demand certificate-of-analysis documentation for aromatic content.
Packaging Materials holds the volume lead, though Lubricants is climbing fastest on electric vehicle fluid specifications.
End User:
Customer industries span mobility, consumer goods, infrastructure, and regulated healthcare, each imposing distinct certification and specification protocols on alpha olefin procurement.
- Automotive:Fuel system and interior panel LLDPE applications driven by EPA fuel economy standards. Tier-1 compounders in Michigan and Lower Saxony specify 1-hexene/1-octene blends for lightweighting mandates.
- Personal Care:Surfactant and emollient formulations subject to REACH registration and EPA TSCA Section 5 notification timelines. Dutch and Belgian formulators lead purity documentation requirements.
- Construction:Geomembrane and pipe applications using medium-density polyethylene co-monomer blends.
- Pharmaceuticals:Excipient and active ingredient synthesis requiring GMP-aligned supply chains and batch traceability.
Automotive commands the largest procurement volumes, with Personal Care expanding most quickly on regulatory-compliant supplier consolidation.
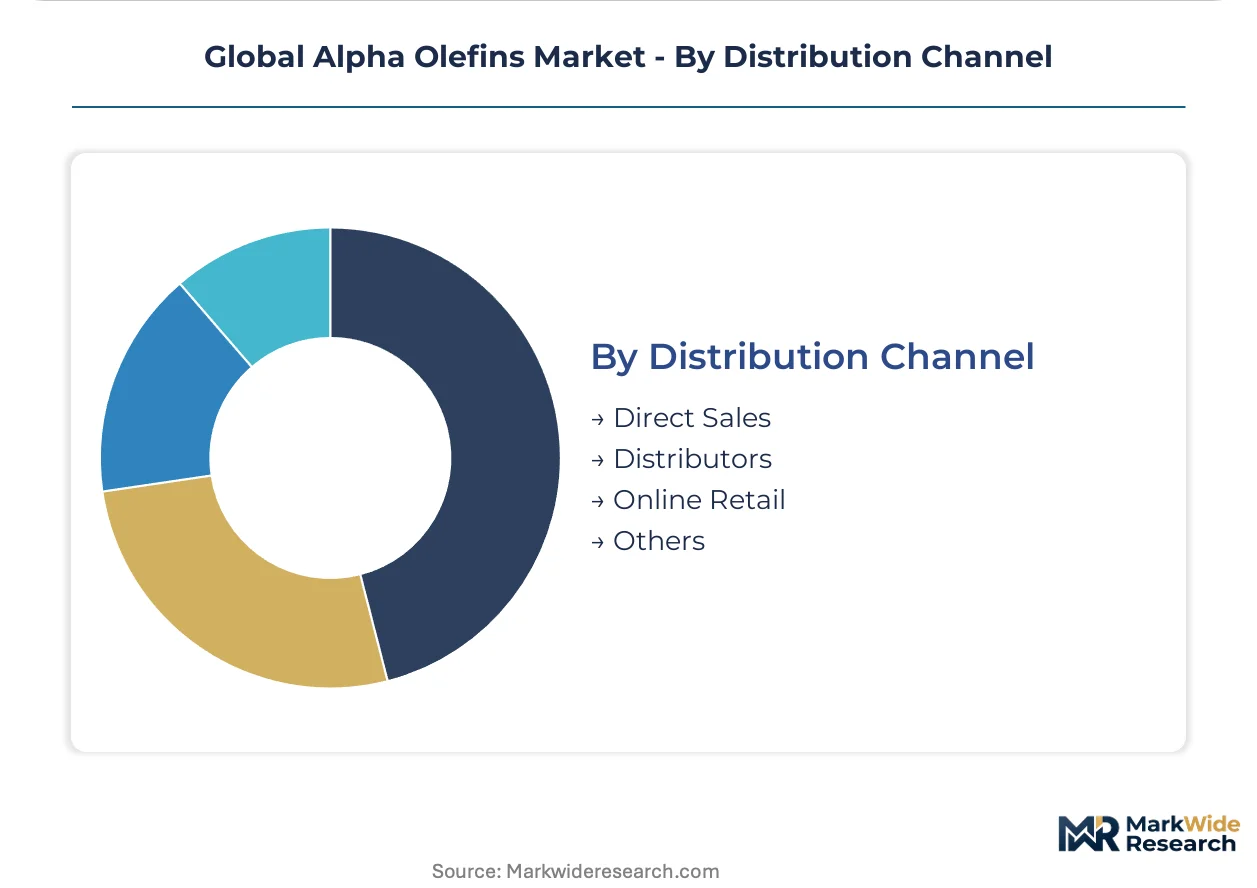
Distribution Channel:
Supply route structures reflect contract tenure, volume scale, and technical service intensity required for co-monomer specification support.
- Direct Sales:Long-term offtake agreements with embedded price formulas between alpha olefin producers and polyethylene manufacturers. Chevron Phillips Chemical Company LLC leverages US Gulf Coast integration for domestic LLDPE supply.
- Distributors:Merchant market spot and contract sales for smaller compounders and regional formulators lacking scale for direct negotiation.
- Online Retail:Digital procurement platforms for specialty grades and sample quantities, constrained by hazardous material shipping regulations.
- Others:Agent-mediated transactions and toll manufacturing arrangements for custom-blended co-monomer specifications.
Direct Sales captures the dominant contract value, while Distributors is gaining share fastest among mid-scale compounders in India and Southeast Asia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA emissions rules and ethylene feedstock access anchor US Gulf Coast capacity investments, while REACH compliance locks in European supplier positions and China's polymer expansion reshapes Asian demand geography.
United States
Shale-based ethane cracking economics drive 1-hexene and 1-octene production concentration along the Louisiana-Texas corridor. EPA fuel economy standards accelerate LLDPE penetration in Michigan automotive lightweighting programs. Chevron Phillips Chemical Company LLC leverages integrated ethylene supply at its Cedar Bayou complex to serve domestic polyethylene compounders.
China
Zhejiang province film extruders embed alpha olefin suppliers into multi-year offtake structures with price-indexed formulas. NMPA chemical registration protocols and GB standards for packaging materials constrain import qualification timelines. Yangtze River Delta polymer compounders scale domestic LLDPE capacity under dual carbon goals and provincial industrial upgrading mandates.
Germany
Lower Saxony automotive compounders specify 1-hexene/1-octene blends for EU CO2 fleet emission compliance in fuel system applications. ECHA substance evaluation protocols for REACH-registered surfactant grades lock in approved supplier lists at ppb aromatic detection thresholds. BASF and LANXESS supply chain integration in Ludwigshafen anchors detergent alcohol precursor demand.
Saudi Arabia
SABIC and Qatar Chemical Company Ltd anchor Middle East alpha olefin supply through ethane-advantaged cracking at Jubail Industrial City. SFDA chemical registration requirements for personal care formulations shape export qualification protocols. Eastern Province petrochemical integration redirects C4 refinery streams toward oligomerization feedstock pools.
India
Maharashtra and Gujarat packaging hubs scale LLDPE film grade production under PLI scheme incentives for domestic polymer capacity. BIS certification alignment for co-monomer specifications creates first-mover positioning opportunities. Reliance Industries and Indian Oil Corporation anchor demand concentration in the Mumbai-Ahmedabad industrial corridor.
Global Alpha Olefins Market Vendor Landscape
Integrated petrochemical majors and merchant specialty producers split the market along feedstock access and specification depth vectors. The vendor base concentrates around ethane-advantaged Gulf Coast corridors and naphtha-integrated European complexes, with Middle Eastern entrants capturing cost-position gains. Three archetypes dominate: backward-integrated ethylene crackers, SHOP-process technology licensors, and regional distribution specialists. Capacity expansion and long-term offtake anchoring represent the dominant competitive moves, with direct polymer producer partnerships displacing spot market procurement.
Within the integrated-major tier, Chevron Phillips Chemical Company LLC and Shell plc exemplify ethylene-oligomerization scale positions, while INEOS occupies the European REACH-compliant supplier archetype. Chevron Phillips leverages US Gulf Coast ethane integration to anchor domestic LLDPE supply relationships. Shell's Geismar facility represents global shipping logistics reach toward Asian polymer compounders. INEOS sustains market presence through Chocolate Bayou complex operations and differentiated co-monomer blend capabilities.
| Leading Market Players |
|---|
| Chevron Phillips Chemical Company LLC |
| INEOS |
| Shell plc |
| Exxon Mobil Corporation |
| SABIC |
| Sasol Limited |
| Qatar Chemical Company Ltd |
| Idemitsu Kosan Co., Ltd. |
| Mitsubishi Chemical Group Corporation |
| Others |
Supply Flow & Price Mechanics
The Louisiana-Texas corridor's ethane-advantaged crackers concentrate 1-hexene and 1-octene capacity, granting integrated producers substantial leverage over polyethylene compounders negotiating long-term offtake formulas. This supply concentration translates directly into pricing power, as Gulf Coast hurricanes or pipeline disruptions immediately tighten co-monomer availability and reset contract negotiations.
Pricing Analysis
US Gulf Coast-to-Rotterdam price spreads for 1-octene reflect ethane-naphtha cracking cost differentials, with contract-based long-term offtake structures dominating procurement between alpha olefin producers and LLDPE manufacturers. Price differentiation hinges on purity grade and REACH certification status, with automotive compounders in Michigan and Lower Saxony least sensitive due to specification lock-in, while Indian packaging hubs under PLI schemes exhibit highest price sensitivity. Cost compression in standard-grade 1-hexene is intensifying because Middle Eastern ethane-advantaged capacity is expanding merchant supply.
Supply Chain Analysis
Export-control regimes for ziegler-type catalyst technology limit technology transfer to unlicensed operators, constraining new capacity buildout in target geographies. Supply concentrates in the United States, Saudi Arabia, and Germany, with ethylene feedstock drawing from shale gas, refinery C4 streams, and naphtha cracking respectively. Organometallic catalyst precursors and specialized hydrogenation units constitute critical dependencies. Single-source vulnerability runs through the Louisiana corridor's three-facility 1-octene cluster. Distribution feeds from direct producer-to-polymer-manufacturer contracts for volume grades, with distributors handling specialty cuts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Alpha olefins markets track ethylene cracking cycle troughs and peaks, with current positioning reflecting recovery momentum from automotive lightweighting mandates and electric vehicle fluid specifications.
For Market Incumbents: Build switching-cost moats through embedded technical service teams at polymer compounder facilities. Anchor capacity expansion in ethane-advantaged corridors to defend margin position against Middle Eastern entrants. Deepen catalyst R&D partnerships with German and US university pipelines to lock in organometallic chemistry talent scarcity. Secure REACH pre-registration for C6-C8 surfactant grades to foreclose European competitor repositioning. For New Entrants and Emerging Players: Build out toll manufacturing arrangements with Indian domestic polyethylene capacity scaling under PLI incentives, targeting Maharashtra and Gujarat packaging hubs. Penetrate the synthetic lubricant base stock segment through 1-decene and 1-dodecene fractions for electric vehicle thermal management fluids, where specification premiums exceed commodity co-monomer economics. Pursue BIS certification alignment as the primary go-to-market credential for qualified supplier status. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors backward-integrated ethylene crackers with catalyst licensing capabilities over pure-play merchant operators. Long-term viability across the projection horizon rests on feedstock cost position and regulatory compliance infrastructure rather than scale alone. Watch ethane-naphtha spread compression as the inflection signal for European asset restructuring and US Gulf Coast expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Cracking | Captures ethane cost advantage at US Gulf Coast and Middle Eastern production hubs. |
| Long-term Supply Agreement with Polymer Producers | Locks in offtake volume from Michigan and Zhejiang automotive and packaging compounders. |
| Catalyst Technology Licensing | Generates royalty streams while constraining competitor access to ziegler system advances. |
| REACH Certification Investment | Secures approved supplier status for C12-C14 surfactant grades in Rotterdam and Antwerp markets. |
| Joint Venture for Indian Market Entry | Combines domestic BIS certification pathways with international catalyst and process expertise. |
Methodological Framework
Initial hypotheses were tested against primary input from oligomerization plant managers, polyethylene procurement leads at automotive compounders, surfactant formulator technical directors, and catalyst R&D specialists, then refined through secondary validation against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings from integrated petrochemical majors, and EPA TSCA notification databases. Bottom-up capacity and demand modeling triangulated with top-down ethylene derivative consumption analysis.
Demand-supply balance dynamics across the modeling period anchored volume projections, with segmentation across carbon chain length grade, end-use application, and regional production hub informing price and margin trajectories. CAGRs derived from ethylene feedstock cost curve shifts, automotive lightweighting penetration rates, and electric vehicle fluid specification adoption curves.
Sensitivities concentrate around ethane-naphtha spread volatility, Gulf Coast hurricane disruption frequency, and REACH authorization timeline extensions for novel co-monomer grades. Forecasts reflect documented assumptions on catalyst yield improvements and cracker utilization rates. Material shifts in EPA fuel economy standard stringency or EU CO2 fleet targets would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Soft PVC Sealing Strip Market
Polymers & Resins
North America Fluoropolymer Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Chlorinated Polyvinyl Chloride (CPVC) Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Asia-Pacific Flooring Resins Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Polyether Polyols Market