
 Chloro-Sulfonated Polyethylene Market | 2026-2036
Chloro-Sulfonated Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Chloro-Sulfonated Polyethylene Market Outlook
Specialized polymer chemist availability is collapsing across mature manufacturing regions, forcing compounders to relocate technical operations or automate formulation labs. Tosoh Corporation sustains its position through captive chlorination infrastructure and long-tenured technical staff in Japan. Jilin Petrochemical Company anchors supply for domestic automotive OEMs through backward integration into ethylene feedstock. DuPont differentiates via legacy brand equity in aerospace and defense specifications where certification timelines deter new entrants.
Chloro-sulfonated polyethylene is a synthetic elastomer produced by simultaneous chlorination and chlorosulfonation of polyethylene, yielding a polymer with 25-43% chlorine content and 1.0-2.0% sulfur that exhibits superior ozone, weather, and chemical resistance. The material serves primarily as a specialty rubber for molded seals, protective linings, and insulated cable jackets operating in harsh environments. High molecular weight grades dominate volume due to their tensile strength advantage in automotive seals and roofing membranes, while specialty grades command premium positioning in chemical processing equipment where FDA and NSF compliance is mandatory. Cable insulation represents the fastest-expanding application segment, driven by offshore wind farm buildouts requiring subsea cable sheathing with extended service life.
EPA oversight under the Toxic Substances Control Act shapes permissible chlorinated compound formulations for US industrial applications, while REACH registration requirements in Europe impose downstream communication obligations on importers and compounders. China's SAMR enforces GB standards for rubber products used in construction and transportation infrastructure, creating a fragmented compliance landscape for multinational suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and reformulation costs as sustainability mandates tighten across end-use sectors.
Market Dynamics
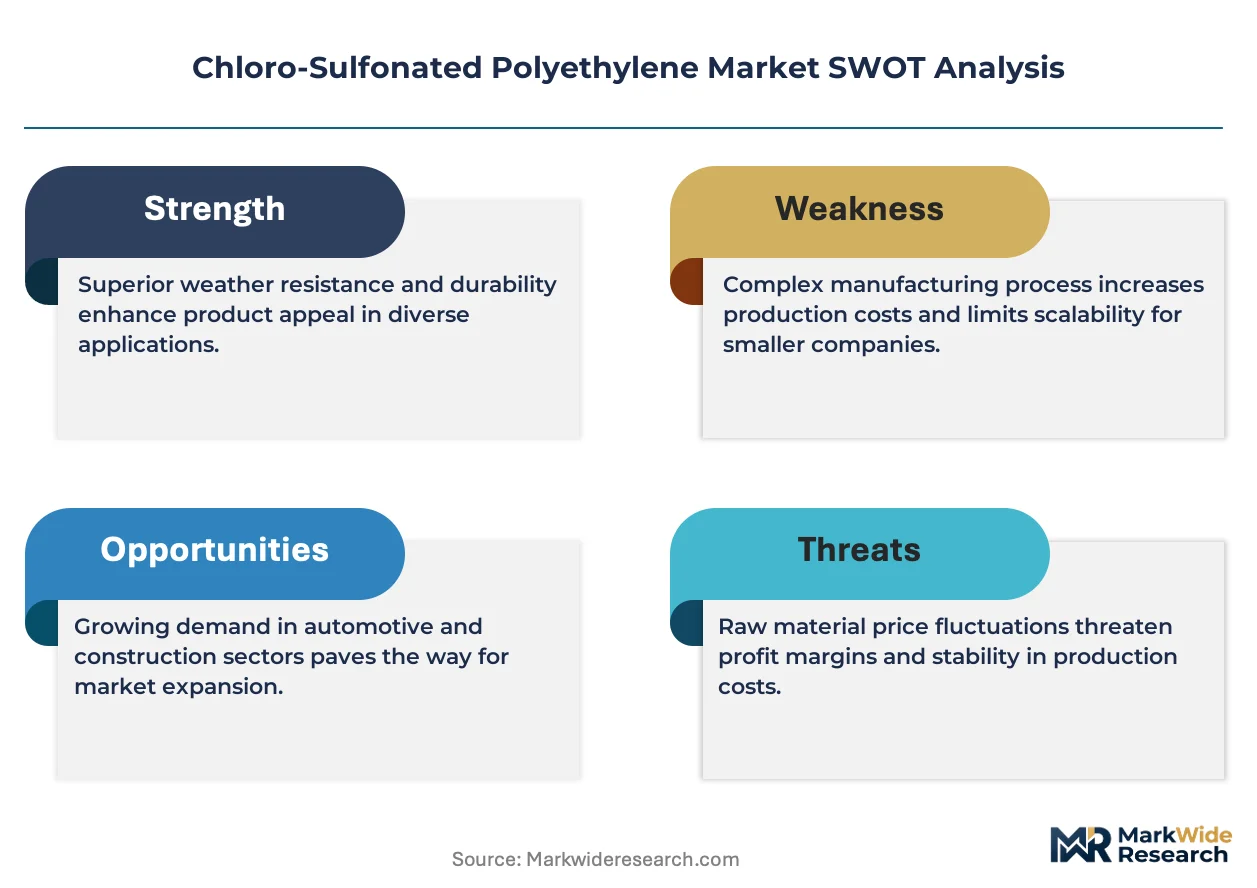
Specialty rubber compounders face a tightening squeeze between automotive OEM specification upgrades and the collapse of experienced chlorination chemists in mature manufacturing regions, forcing technical operations toward automation or geographic relocation.
Growth Catalysts
- Offshore Wind Cable Buildouts:Subsea cable sheathing specifications from European wind farm developers are accelerating procurement of high molecular weight grades with extended ozone resistance ratings.
- REACH Article 33 Communication:Downstream disclosure obligations for chlorinated compounds are consolidating purchasing among compliant compounders with established registration dossiers.
- Automotive Under-the-Hood Seals:Thermal management system redesigns for electric powertrains are specifying chloro-sulfonated polyethylene for coolant hose connectors and battery pack gaskets.
Market Restraints
- Ethylene Feedstock Volatility:Crude-linked naphtha pricing swings compress margin predictability for non-integrated compounders lacking captive ethylene supply.
- Specialty Chemist Scarcity:Retirement waves across Japan and Germany are depleting the pool of technicians capable of managing chlorination reaction kinetics and molecular weight control.
- Thermoplastic Elastomer Substitution:TPV and TPO materials are displacing conventional rubber in non-critical automotive weatherstripping where temperature extremes are moderate.
Strategic Opportunities
- India Automotive Localization:PLI scheme incentives for advanced chemistry manufacturing are attracting technical joint ventures to serve domestic OEMs seeking import substitution.
- FDA-Compliant Processing Equipment:Food contact certification for chloro-sulfonated polyethylene linings opens pharmaceutical and beverage processing applications previously served by fluoropolymers.
- Digital Formulation Platforms:AI-driven polymer design tools are compressing development cycles for custom grades targeting specific Shore hardness and compression set requirements.
Industry Challenges
- Aerospace Certification Timelines:MIL-SPEC and SAE qualification protocols for defense and commercial aviation applications demand 18-36 month validation periods that strain working capital.
- Legacy Equipment Retrofit Costs:Chlorination reactor upgrades to meet MEE emissions standards in China require capital outlays that mid-scale compounders struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chloro-Sulfonated Polyethylene Market |
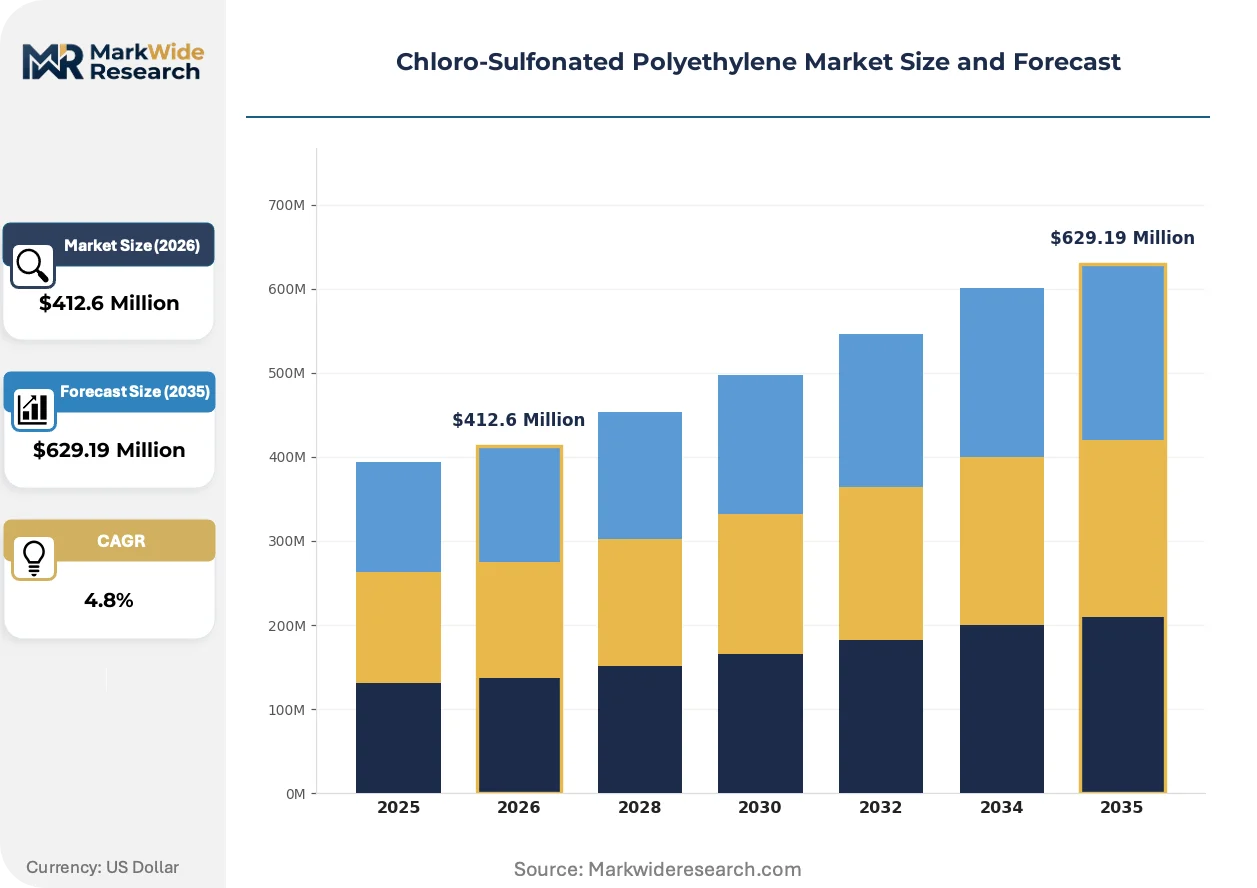
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Molecular Weight, Low Molecular Weight, Medium Molecular Weight, Specialty Grades Application: Automotive Seals, Roofing Membranes, Cable Insulation, Chemical Resistant Linings End User: Construction, Automotive, Electronics, Industrial Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Tosoh Corporation, Jilin Petrochemical Company, Lianyungang JTD Rubber Material, Jiangxi Hongrun Chemical Industry, Hejian Lixing Special Rubber, Lianda Corporation, Shandong Xinlong Group, Ningbo Huaxia Chemical, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chloro-Sulfonated Polyethylene Market Strategic Shifts
Formulation science and regulatory disclosure requirements are converging to reshape how specialty elastomer suppliers compete, with technical transparency and molecular precision replacing commodity volume as the basis for differentiation.
Advanced chlorination control systems are fragmenting the traditional high-volume grade hierarchy. Precision chlorine distribution mapping enables tailored 28-35% chlorine content variants that match specific automotive OEM seal specifications without over-engineering. Tier 1 suppliers in Germany and Japan are adopting these systems to reduce raw material waste and shorten customer qualification cycles. The technology is fragmenting the market into micro-segments defined by exact chlorine percentage rather than broad high-medium-low classifications.
EPA TSCA Section 5 pre-manufacture notification requirements are tightening timelines for modified chloro-sulfonated polyethylene introductions. New chemical substance determinations for altered chlorine ratios or sulfur levels now trigger 90-day review windows that compounders must navigate before commercial sampling. Automotive seal manufacturers in Michigan and Ohio are responding by consolidating supplier relationships with established PMN holders rather than qualifying novel formulations.
Specification-driven procurement is compressing supplier lists across European automotive value chains. OEMs are requiring compound-level REACH SCIP database entries and full substance disclosure to 0.1% thresholds, disqualifying traders and non-integrated distributors. Tier 2 molders in France and Italy are bypassing traditional rubber merchants to contract directly with chlorination specialists with in-house polymerization and captive sulfonation capacity.
Chloro-Sulfonated Polyethylene Market Segmentation
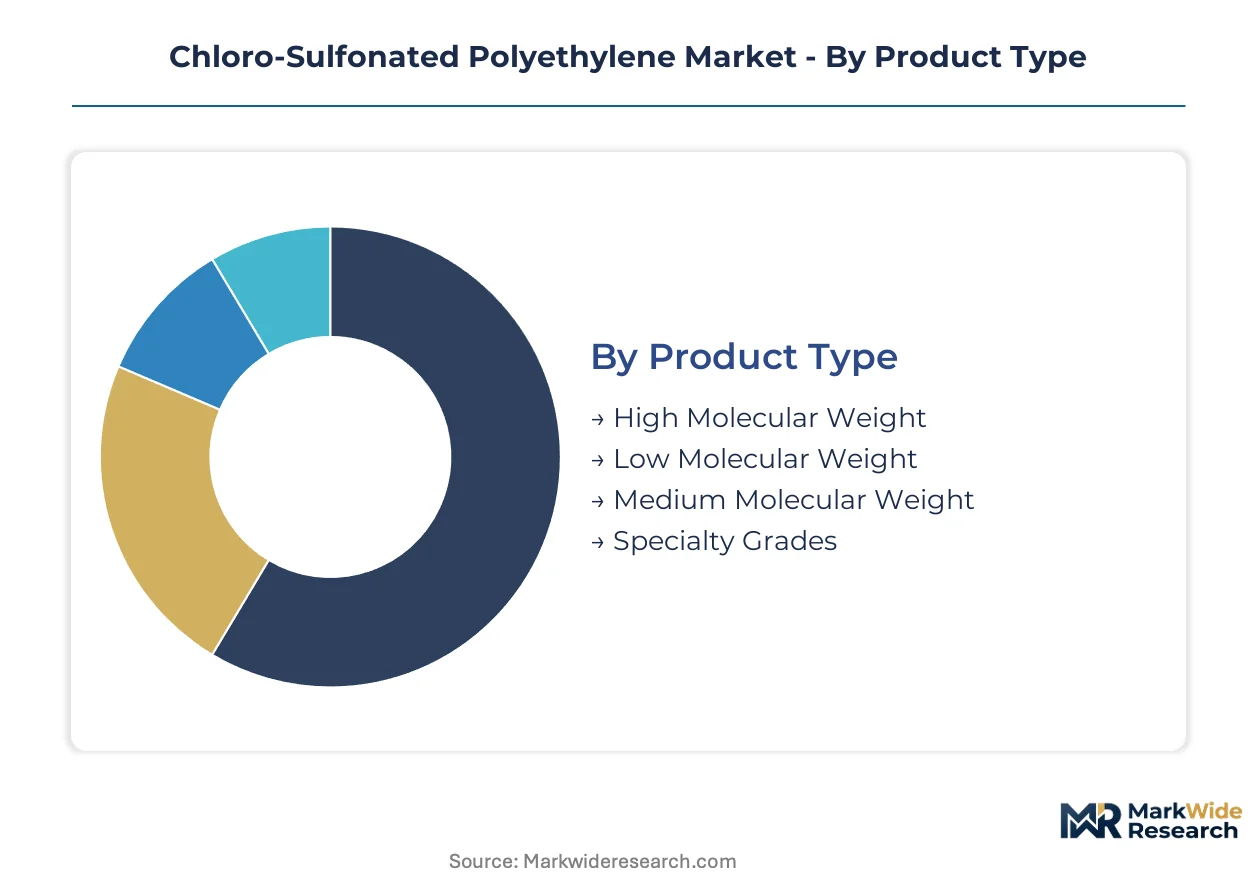
Segmentation in chloro-sulfonated polyethylene reveals how molecular architecture and end-use certification requirements fragment procurement patterns across automotive, construction, and cable infrastructure verticals. Suppliers must align grade portfolios with specific OEM specifications or risk disqualification from qualified vendor lists.
Product Type:
Thermoplastic elastomer substitution pressures vary sharply by molecular weight tier, with mid-range grades facing the most displacement risk from TPV materials in non-critical automotive weatherstripping.
- High Molecular Weight:These grades contain extended polymer chains delivering tensile strength above 20 MPa and superior abrasion resistance for dynamic seals. Demand concentrates in German and Japanese automotive under-the-hood applications where SAE specifications mandate compression set performance below 25% at 150°C. OEM qualification timelines here exceed 18 months, creating defensive moats against substitute materials.
- Specialty Grades:FDA-compliant variants with controlled extractables below 0.5% serve pharmaceutical processing equipment and beverage tank linings. Procurement is accelerating in Switzerland and Germany where food contact certification replaces fluoropolymer solutions in cost-sensitive installations.
- Low Molecular Weight:Shorter chain structures enable easier processing in injection molding of small automotive grommets and connector seals.
- Medium Molecular Weight:Balanced performance characteristics position these grades for general-purpose roofing membranes and industrial hose covers.
High molecular weight grades anchor the volume base while specialty grades gain share at the steepest rate.
Application:
Cost tier stratification separates specification-critical uses from commodity replacements, with premium cable sheathing commanding 3-4x the per-kilogram price of standard roofing applications.
- Cable Insulation:Subsea and offshore wind farm specifications require ozone resistance ratings exceeding 500 pphm and 30-year service life predictions. European wind developers in Denmark and the Netherlands are consolidating procurement around compounders with IEC 60811 test data packages.
- Automotive Seals:Coolant hose connectors and battery pack gaskets for electric powertrains specify chloro-sulfonated polyethylene for thermal stability across -40°C to 150°C operating windows. Shandong province compounders are expanding capacity to serve domestic OEM localization mandates.
- Roofing Membranes:Single-ply systems leverage weathering resistance for commercial building envelopes in coastal environments.
- Chemical Resistant Linings:Tank and vessel coatings protect against sulfuric acid and sodium hypochlorite exposure in chlor-alkali plants.
Automotive seals generate the highest absolute volume while cable insulation expands most quickly.
End User:
Customer type determines margin structure, with automotive OEMs demanding just-in-time delivery and construction buyers accepting longer lead times for bulk membrane orders.
- Automotive:Tier 1 seal manufacturers in Michigan, Stuttgart, and Nagoya specify exact chlorine content ranges and batch-to-batch consistency for under-the-hood components. Contracts typically run 5-7 years with price renegotiation clauses tied to ethylene feedstock indices.
- Construction:Roofing contractors and waterproofing specialists in China's Jiangsu corridor purchase high molecular weight grades for stadium and airport membrane systems.
- Industrial:Chemical processors specify lining materials for storage tanks and reactor vessels handling aggressive media.
- Electronics:Cable assemblers serving data center and telecommunications infrastructure procure jacketing compounds with low smoke and halogen characteristics.
Construction anchors the volume base while automotive gains share at the steepest rate.
Distribution Channel:
Supply concentration favors direct relationships with chlorination specialists, squeezing traditional rubber merchants out of qualified supply chains.
- Direct Sales:Major compounders in Japan and Germany maintain dedicated technical service teams for automotive OEM qualification support. These relationships bypass distributors entirely for specification-grade materials.
- Distributors:Regional rubber merchants in France and Italy survive by stocking standard grades for construction and general industrial accounts.
- Online Retail:Limited to small-volume sample orders and technical documentation access for compounders.
- Wholesalers:Bulk roofing membrane distributors in North America handle logistics for construction seasonality.
Direct sales anchors the volume base while distributor relationships contract fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA chemical exposure standards in the United States anchor the dominant geography, with regulatory tightening across multiple jurisdictions reshaping where chloro-sulfonated polyethylene production and consumption concentrate.
United States
Automotive seal manufacturers in Michigan and Ohio are expanding procurement for electric powertrain thermal management components. EPA TSCA Section 5 pre-manufacture notification requirements now trigger 90-day review windows for modified formulations. Detroit-area compounders are consolidating supplier relationships with established PMN holders to avoid qualification delays.
China
Shandong and Jiangsu industrial corridors host specialty rubber compounders clustering near downstream automotive OEMs. SAMR enforces GB standards for construction and transportation infrastructure applications. MEE emissions standards are forcing chlorination reactor upgrades that mid-scale producers struggle to finance.
Germany
Tier 1 automotive suppliers in Stuttgart specify exact chlorine content ranges for under-the-hood seals with SAE-mandated compression set performance. REACH Article 33 disclosure obligations to 0.1% thresholds are disqualifying non-integrated distributors. Bavarian compounders with captive sulfonation capacity are capturing direct contracts from molders.
Japan
Nagoya-based seal manufacturers source high molecular weight grades for dynamic automotive applications requiring 18-month qualification timelines. METI industrial standards shape permissible formulations for domestic OEM supply chains. Tosoh Corporation's captive chlorination infrastructure in the Kanto region sustains technical staff retention against retirement waves.
India
Domestic automotive OEMs are accelerating import substitution for specialty elastomer feedstocks. PLI scheme incentives for advanced chemistry manufacturing are attracting technical joint ventures from multinational compounders. Maharashtra and Gujarat industrial zones are emerging as formulation hubs for regional automotive supply chains.
Chloro-Sulfonated Polyethylene Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with backward integration into ethylene feedstock and captive chlorination infrastructure separating the two groups. The market structure rewards compounders with in-house polymerization, sulfonation, and technical service capabilities for automotive OEM qualification. Three archetypes dominate: integrated petrochemical majors with captive supply chains, mid-scale regional specialists with formulation expertise, and trading entities being squeezed out by specification-driven procurement. Competitive moves center on M&A to acquire chlorination chemist talent and capacity expansion in China's Shandong corridor to serve domestic automotive localization.
Among Japanese integrated producers, Tosoh Corporation exemplifies the captive-infrastructure archetype through long-tenured technical staff retention. Jilin Petrochemical Company anchors the state-backed petrochemical tier with backward integration into ethylene feedstock for domestic OEM supply. DuPont occupies a position in the specification-premium segment where aerospace and defense certification timelines deter new entrants.
| Leading Market Players |
|---|
| Tosoh Corporation |
| Jilin Petrochemical Company |
| Lianyungang JTD Rubber Material |
| Jiangxi Hongrun Chemical Industry |
| Hejian Lixing Special Rubber |
| Lianda Corporation |
| Shandong Xinlong Group |
| Ningbo Huaxia Chemical |
| DuPont |
| Others |
Value Chain & Pricing Dynamics
Long-term offtake contracts with automotive OEMs in Germany and Japan lock in both supply access and price visibility for high molecular weight grades, insulating integrated compounders from ethylene feedstock volatility while exposing non-integrated distributors to margin compression.
Pricing Analysis
Price spreads between Japanese and Chinese compounders reflect captive chlorination infrastructure advantages versus third-party tolling dependencies. Three-tier pricing structure across aerospace-certified, automotive-qualified, and general industrial grades separates specification-critical applications from commodity roofing membranes. Cost compression in mid-range automotive weatherstripping intensifies as TPV substitution accelerates in non-critical seals. Construction buyers in China's Jiangsu corridor exhibit highest price sensitivity, while aerospace OEMs in Stuttgart and Nagoya accept premium positioning for MIL-SPEC validation.
Supply Chain Analysis
China and Japan anchor chloro-sulfonated polyethylene production, with Shandong province compounders feeding domestic automotive localization and Kanto-region producers serving Nagoya seal manufacturers. Manufacturing draws from ethylene feedstock, chlorine gas, and sulfur dioxide as primary inputs. Single-source vulnerability concentrates in specialty chlorination chemist talent pools depleted by retirement waves across mature manufacturing regions. Distribution runs through direct technical service relationships for automotive qualification support, bypassing traditional rubber merchants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among Tier 1 automotive seal manufacturers consolidating qualified vendor lists, squeezing margin capture for non-integrated compounders unable to meet REACH disclosure thresholds.
For Market Incumbents: Consolidate formulation expertise through selective acquisition of mid-scale chlorination specialists in China's Shandong corridor, securing captive technical staff against retirement-driven capability erosion. Defensive positioning requires backward integration into ethylene feedstock or joint venture structures with petrochemical majors to insulate margin structures from naphtha-linked volatility. For New Entrants and Emerging Players: FDA-compliant processing equipment certification offers a fast-track into pharmaceutical and beverage tank lining applications where fluoropolymer displacement creates white-space opportunity. Target India's Maharashtra and Gujarat industrial zones under PLI scheme incentives, partnering with domestic automotive OEMs seeking import substitution for specialty elastomer feedstocks. For Investors and Strategic Acquirers: Capital is best deployed toward integrated compounders with captive sulfonation capacity and established REACH registration dossiers, positioned to capture specification-driven procurement consolidation. Long-term viability hinges on chlorination reactor upgrade completion under China's MEE emissions standards. The signal to watch is automotive OEM qualification timeline compression for electric powertrain thermal management components.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstock | Jilin Petrochemical's captive supply model anchors margin predictability against naphtha volatility. |
| Chlorination Reactor Upgrade | MEE compliance investments in Shandong separate viable producers from stranded mid-scale compounders. |
| REACH Registration Dossier Expansion | ECHA-compliant compounders capture Tier 1 automotive procurement bypassing traditional distributors. |
| Technical Joint Venture Formation | PLI scheme partnerships in Maharashtra accelerate domestic formulation capacity for Indian OEMs. |
| Digital Formulation Platform Deployment | AI-driven polymer design compresses custom grade development cycles for specific Shore hardness requirements. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with chlorination chemists, automotive Tier 1 procurement leads, and specialty rubber distribution channel partners; and secondary validation through customs trade data, SEC 10-K filings of integrated petrochemical majors, and ECHA REACH registration databases. Bottom-up grade-volume estimates triangulated against top-down ethylene derivative consumption patterns across automotive, construction, and cable infrastructure verticals.
The projection horizon spans molecular weight tier, application certification level, and regional production hub segmentation dimensions. CAGRs were derived from ethylene feedstock demand elasticity modeling and OEM specification upgrade velocity analysis. Forecast inputs incorporated offshore wind farm cable procurement schedules and automotive electric powertrain thermal management system redesign timelines.
Decision-makers should treat outputs as directional under sustained EPA TSCA enforcement and REACH Article 33 disclosure tightening; material deviation in regulatory stringency or chemist talent availability would warrant model refresh. Recalibration cycles align with material shifts in automotive OEM qualification protocols and chlorination reactor emissions standard enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Polybutadiene Elastomers Market
Rubber
Performance Elastomers Market
Rubber
Global Medical Rubber Stopper Market
Rubber
Hydrogenated Nitrile Butadiene Rubber (HNBR) Market
Rubber
Rubber Tapes Market
Rubber
Specialty Nitrile Butadiene Rubber (NBR) Market
Rubber
Plastomers Market
Rubber
Fast Curing Nitrile Butadiene Rubber (NBR) Market
Rubber
Chloroprene Rubber Tape Market
Rubber
Isoprene Rubber (IR) Latex Market
Rubber
Europe Silicone Rubber Market
Rubber
Flexible Rubber Sheets Market
Rubber
Rubber Coatings Market
Rubber
Isobutylene Market
Rubber
Styrene Butadiene (SB) Latex Market
Rubber
Global Crumb Rubber Market