
 Cellular Rubber Market | 2026-2036
Cellular Rubber Market Size, Share, and Industry Trends Forecast 2026-2036
Cellular Rubber Market Analysis
Electric vehicle thermal management is expanding its share of cellular rubber procurement as battery pack sealing and coolant line gaskets displace legacy internal-combustion applications. Saint-Gobain Performance Plastics leverages its fluoropolymer compounding expertise to anchor high-temperature gasket supply for EV platforms. 3M competes through adhesive-backed foam architectures that simplify assembly line integration. Rogers Foam Corporation specializes in closed-cell silicone sheeting for aerospace flame-retardant specifications.
Cellular rubber denotes elastomeric materials manufactured with intentional gas-inclusion structures, typically achieving densities between 160 and 480 kg/m³ through chemical blowing agents or physical foaming processes, engineered primarily for compression set resistance, energy absorption, and environmental sealing across industrial assemblies. EPDM formulations dominate outdoor construction and automotive weatherstrip segments due to ozone stability and cost positioning, while silicone grades command premium margins in aerospace and medical end uses where temperature extremes exceed 200°C. Neoprene retains volume leadership in marine and industrial gasket applications where oil resistance remains non-negotiable.
EPA toxics release standards and REACH substance restrictions are forcing reformulation of azodicarbonamide blowing agents and certain phthalate plasticizers across North American and European supply chains. China's GB standards for volatile organic compound emissions in building materials are tightening import specifications for construction-grade foam products. ISO 1629 nomenclature and ASTM D1056 classification frameworks govern material designation and testing protocols, creating compliance barriers for unqualified suppliers. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded inventory and certification gaps.
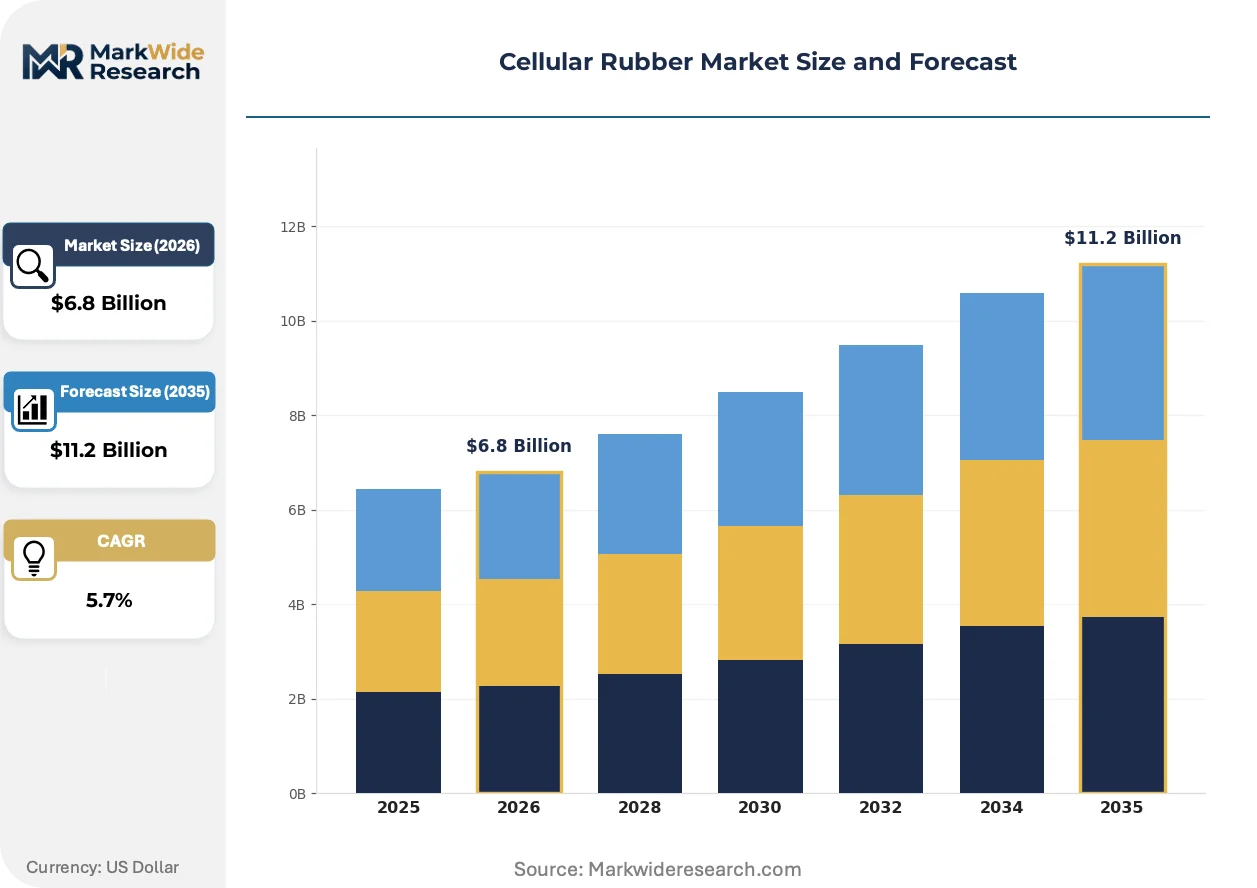
Market Dynamics
Automotive electrification is compressing legacy internal-combustion gasket volumes while simultaneously expanding thermal management foam procurement for battery packs and coolant systems across OEM supply chains.
Growth Catalysts
- EV Thermal Sealing Demand:Battery enclosure gaskets and coolant line seals now constitute the fastest-expanding procurement category within electrified vehicle platforms, displacing conventional engine bay applications.
- REACH Substance Restrictions:ECHA's tightening azodicarbonamide and phthalate thresholds are accelerating reformulation investments toward bio-based blowing agents and non-plasticized EPDM compounds.
- Germany's Industrial Cluster:Stuttgart and Wolfsburg anchor concentrated OEM engineering centers that drive specification standards across European and export supply chains.
Market Restraints
- Petrochemical Feedstock Volatility:Ethylene and propylene monomer prices exhibit cyclical swings that compress compounder margins, particularly for EPDM and neoprene formulations.
- China Supply Concentration:Over half of global azodicarbonamide blowing agent capacity resides in Shandong and Jiangsu provinces, creating single-source vulnerability for Western foam manufacturers.
- Silicone Temperature Ceiling:Standard silicone cellular grades degrade above 230°C, excluding them from emerging solid-state battery thermal interface applications requiring 300°C+ continuous operation.
Strategic Opportunities
- India Automotive Localization:PLI scheme incentives for EV component manufacturing are drawing Saint-Gobain and Rogers Foam to establish compounding facilities near Chennai and Pune production hubs.
- Green Hydrogen Infrastructure:Electrolyzer sealing applications represent an emerging high-value niche requiring fluoropolymer-lined cellular gaskets resistant to caustic KOH environments.
- GB Standard Alignment:China's VOC emission protocols for building materials are creating certification arbitrage opportunities for European producers with existing REACH-compliant formulations.
Industry Challenges
- Formulation Chemistry Expertise Gap:Compounders struggle to recruit polymer scientists capable of balancing compression set performance with bio-based blowing agent compatibility.
- Multi-Jurisdiction Certification Timelines:Parallel UL 94 flammability, ASTM D1056, and OEM-specific PPAP approvals extend new product introduction cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cellular Rubber Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Neoprene, EPDM, Silicon, PVC Application: Automotive Seals, Sound Insulation, Gaskets, Vibration Dampening End User: Aerospace, Electronics, Construction, Consumer Goods Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Rogers Foam Corporation, GCP Applied Technologies Inc, Saint-Gobain Performance Plastics, Nitto Denko, 3M, Monmouth Rubber & Plastics Corp, American Foam Rubber, Momentive, Stockwell Elastomerics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cellular Rubber Market Emerging Trajectories
Material science breakthroughs and regulatory compression are converging to redefine competitive advantage across cellular rubber supply chains, favoring compounders with integrated formulation-to-fabrication capabilities.
Physical foaming with supercritical CO2 is electrifying closed-cell silicone production by eliminating residual chemical blowing agent byproducts. Medical device manufacturers in Minnesota and Massachusetts are qualifying these grades for implantable drug-delivery seals, compressing traditional platinum-cured silicone foam market share in premium healthcare applications.
EPA's revised National Emission Standards for Hazardous Air Pollutants (NESHAP) for polymer manufacturing are forcing foam producers to install thermal oxidizers or switch to water-blown systems. Automotive weatherstrip suppliers in Michigan and Ohio face the steepest compliance costs, accelerating consolidation toward vertically integrated compounders with captive emission control infrastructure.
Specification-led procurement now dominates aerospace and medical segments, where buyers mandate lot-traceable compression set data and batch-level FTIR spectra rather than relying on supplier certificates of analysis. Tier-1 distributors in Southern California and New England are responding by investing in in-house testing laboratories to preserve channel position against direct mill relationships.
Cellular Rubber Market Segmentation
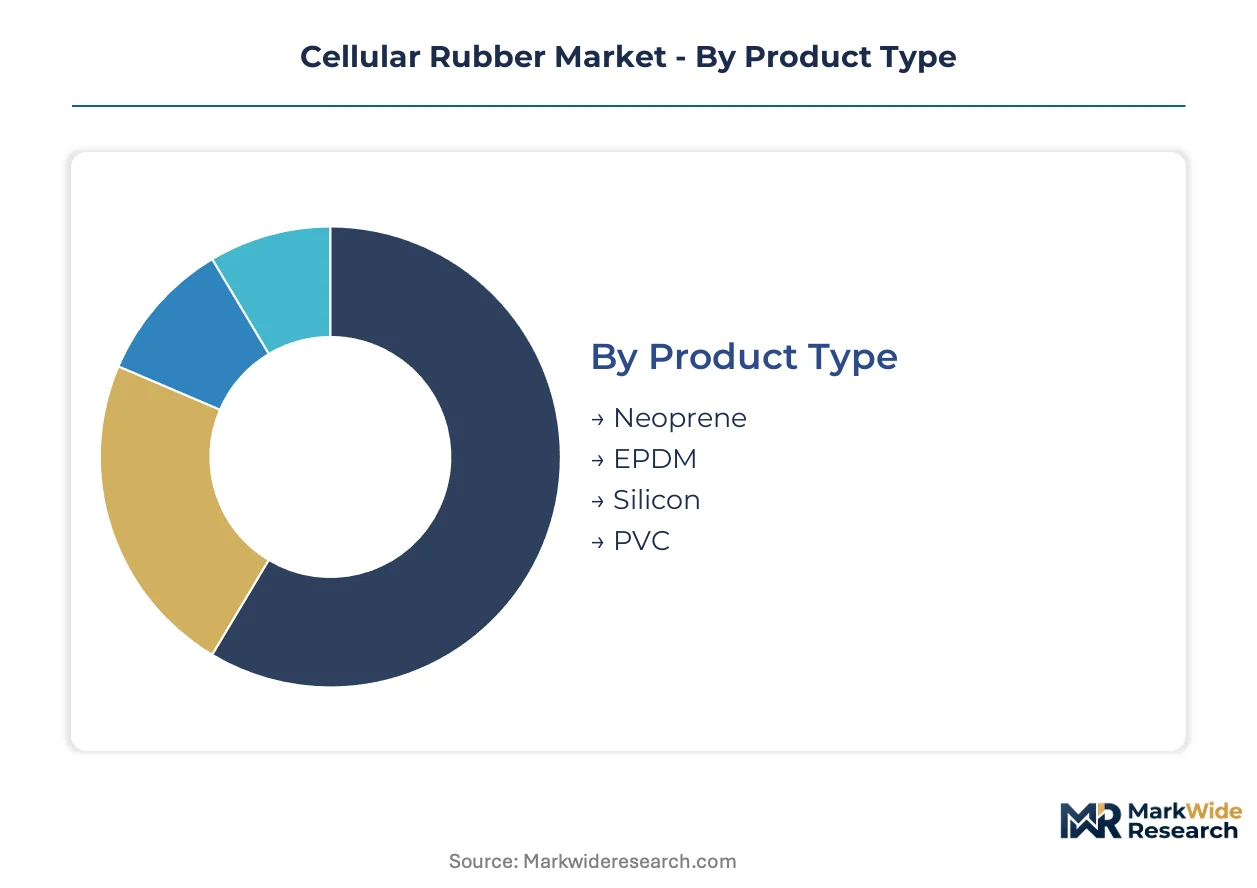
Cellular rubber procurement patterns diverge sharply across material chemistry, end-use performance requirements, and channel economics. Specification intensity varies from commodity construction grades to aerospace-certified formulations with full lot traceability.
Product Type:
EPDM and neoprene formulations command disproportionate compounder investment due to feedstock integration advantages and established automotive qualification pathways.
- EPDM:Ethylene-propylene-diene terpolymer formulations achieve superior ozone resistance and thermal stability across -50°C to 150°C operating windows. German automotive weatherstrip procurement in Stuttgart and Wolfsburg clusters drives volume concentration, though REACH azodicarbonamide restrictions are forcing bio-based blowing agent transitions that compress margin structures.
- Neoprene:Chloroprene-based closed-cell grades deliver non-negotiable oil and fuel resistance for marine decking and industrial gasket applications. Demand concentrates in Gulf Coast petrochemical maintenance cycles and Japanese shipbuilding yards, with formulation expertise concentrated among legacy US and European compounders possessing captive polychloroprene supply agreements.
- Silicon:Platinum-cured cellular silicone commands aerospace and medical premiums through UL 94 V-0 flame retardancy and biocompatibility certifications.
- PVC:Plasticized open-cell and closed-cell variants serve cost-sensitive construction and consumer packaging segments with limited temperature performance requirements.
EPDM absorbs the bulk of installed capacity; silicone is expanding most quickly.
Application:
Application segmentation reflects divergent performance certification burdens, with automotive and aerospace specifications requiring 18-24 month qualification timelines versus commodity construction approvals.
- Automotive Seals:Door weatherstrip, hood seals, and glass-run channels constitute the highest-volume specification category. EV battery enclosure gaskets and coolant line seals are displacing legacy engine bay applications as OEM procurement priorities shift toward thermal management systems in Germany, China, and US Midwest manufacturing clusters.
- Gaskets:Compression-molded and die-cut cellular rubber gaskets serve industrial flange sealing, HVAC equipment, and plumbing fixtures. Demand concentrates in MRO replacement cycles and new commercial construction, with fluoropolymer-lined grades gaining traction in green hydrogen electrolyzer applications requiring KOH chemical resistance.
- Sound Insulation:Engine bay NVH pads and architectural acoustic barriers utilize denser closed-cell grades with specific airflow resistance targets.
- Vibration Dampening:Machinery mounts and electronics isolation pads prioritize loss factor and dynamic stiffness specifications over environmental sealing performance.
Automotive seals command the dominant share of qualified supplier capacity; battery thermal gaskets are climbing the fastest.
End User:
End-user concentration determines pricing architecture, with aerospace and medical segments accepting 3-5x material premiums for batch-level FTIR documentation and lot-traceable compression set data.
- Aerospace:Flame-retardant silicone foam for cabin insulation, gaskets, and seals must satisfy FAA flammability requirements and OEM-specific PPAP protocols. Rogers Foam and specialized fabricators dominate through AS9100-certified manufacturing cells with captive testing laboratories.
- Construction:EPDM and PVC cellular profiles for window glazing, expansion joints, and roofing membranes represent the most price-sensitive volume category. China's GB standards for VOC emissions are tightening import specifications and favoring domestic producers with integrated blowing agent manufacturing.
- Electronics:EMI shielding gaskets and device sealing applications require conductive particle loading or precision thickness control for miniaturized assemblies.
- Consumer Goods:Sporting equipment padding, footwear midsoles, and protective packaging utilize lower-density open-cell formulations with minimal certification overhead.
Construction absorbs the bulk of tonnage; aerospace is gaining share fastest on value metrics.
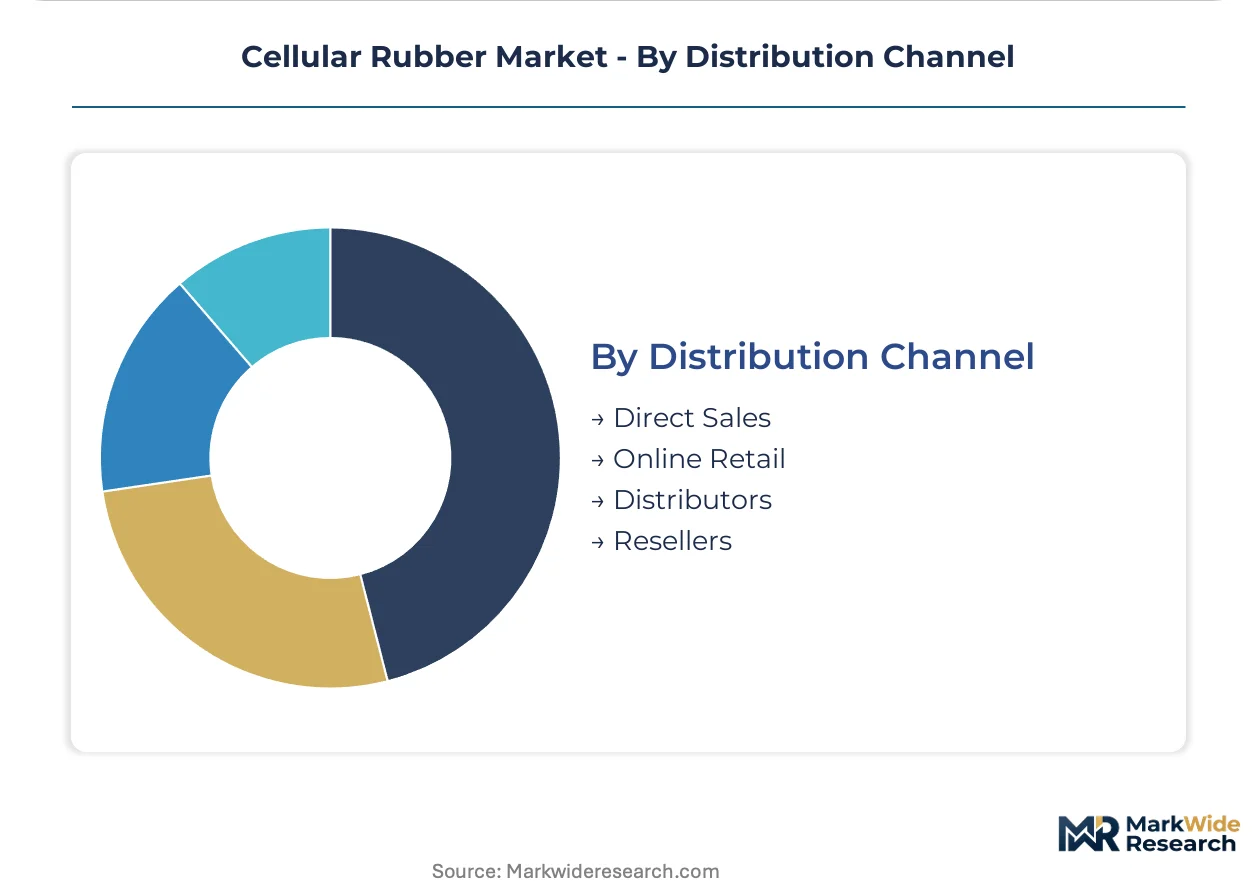
Distribution Channel:
Channel structure reflects specification complexity, with direct mill relationships dominating certified applications and distributor networks serving fragmented MRO demand.
- Direct Sales:Tier-1 automotive and aerospace OEMs negotiate multi-year supply agreements with compounders possessing in-house formulation, calendering, and fabrication capabilities. Saint-Gobain and 3M leverage direct relationships to anchor specification control and block competitor substitution.
- Distributors:Industrial supply houses in Southern California and New England maintain regional inventory positions for construction and MRO gasket demand, increasingly investing in in-house testing laboratories to preserve channel position against direct sourcing.
- Online Retail:E-commerce platforms serve prototype quantities and small-batch custom cutting for R&D and repair applications with limited technical support requirements.
- Resellers:Secondary market participants aggregate surplus inventory and discontinued specifications for legacy equipment maintenance in industrial sectors.
Direct sales capture the dominant share of qualified revenue; distributor value-added services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Stuttgart, Wolfsburg, and Shandong province concentrate cellular rubber compounding capacity through tax-advantaged manufacturing hubs. These zones anchor formulation expertise and OEM qualification pathways across three continents.
Germany
Automotive electrification in Stuttgart and Wolfsburg drives EPDM weatherstrip demand for battery thermal management systems. ECHA REACH restrictions on azodicarbonamide blowing agents force compounders toward bio-based alternatives. The Baden-Württemberg industrial cluster hosts Saint-Gobain engineering centers that set specification standards for European OEM supply chains.
China
GB standards for VOC emissions in construction materials tighten import specifications for EPDM foam profiles. The Shandong and Jiangsu provinces concentrate over half of global azodicarbonamide blowing agent capacity. Yangtze River Delta manufacturing hubs supply domestic automotive OEMs while facing compliance pressure from MEE environmental inspections.
United States
EPA NESHAP standards for polymer manufacturing force Michigan and Ohio weatherstrip suppliers to install thermal oxidizers or switch to water-blown systems. The Midwest automotive corridor anchors coolant line gasket procurement for EV platforms. Southern California distributors invest in in-house testing laboratories to preserve channel position against direct mill relationships.
India
PLI scheme incentives for EV component manufacturing draw compounders toward Chennai and Pune production hubs. BIS certification requirements for automotive materials extend product introduction timelines. The Maharashtra-Tamil Nadu manufacturing belt concentrates domestic EPDM compounding capacity for two-wheeler and passenger vehicle weatherstrip applications.
Japan
METI carbon neutrality roadmaps accelerate fluoropolymer gasket development for hydrogen infrastructure applications. JIS standards govern material designation protocols for industrial sealing products. The Nagoya-Toyota industrial corridor anchors precision calendering expertise for aerospace-certified silicone foam specifications.
Cellular Rubber Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-intensive aerospace and medical applications favoring direct mill relationships while construction and MRO demand flows through distributor networks. The vendor base organizes around three archetypes: integrated compounder-fabricators with captive formulation capabilities, regional foam converters serving price-sensitive construction segments, and specialty distributors investing in certification infrastructure. Consolidation pressure concentrates among Midwest automotive suppliers facing EPA compliance costs, while Asian markets retain fragmentation due to raw material integration advantages. Strategic moves center on backward integration into blowing agent supply and geographic expansion toward Indian PLI zones.
Within the integrated compounder tier, Saint-Gobain Performance Plastics and 3M occupy positions defined by fluoropolymer compounding expertise and adhesive-backed foam architectures respectively. Rogers Foam Corporation exemplifies the specialty fabricator archetype through its focus on closed-cell silicone sheeting. Among Japanese material suppliers, Nitto Denko represents the diversified industrial conglomerate model with cross-segment polymer capabilities. These three anchors illustrate how competitive positioning diverges between specification-led premium tiers and scale-driven construction grades.
| Leading Market Players |
|---|
| Rogers Foam Corporation |
| GCP Applied Technologies Inc |
| Saint-Gobain Performance Plastics |
| Nitto Denko |
| 3M |
| Monmouth Rubber & Plastics Corp |
| American Foam Rubber |
| Momentive |
| Stockwell Elastomerics |
| Others |
Supply Flow & Price Mechanics
Certification-grade bifurcation between aerospace-qualified silicone foam and commodity construction EPDM creates divergent margin architectures across the cellular rubber value chain. REACH-compliant formulations command 3-5x premiums over standard grades, while procurement lead times stretch to 18-24 months for lot-traceable aerospace specifications versus spot-market availability for construction profiles.
Pricing Analysis
Short lead-time premiums dominate pricing negotiations, with automotive OEMs paying significant markups for expedited battery gasket qualification cycles. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden: aerospace and medical buyers accept material premiums for batch-level FTIR documentation, while construction segments prioritize volume scale over performance certification. Cost compression in commodity EPDM weatherstrip grades is intensifying because Shandong-based blowing agent suppliers face MEE environmental inspection pressure. Price-sensitive construction buyers in China's Yangtze River Delta drive spot-market volatility, whereas least-sensitive aerospace procurement in Nagoya-Toyota corridors locks in multi-year supply agreements.
Supply Chain Analysis
Dual-sourcing requirements from Tier-1 automotive OEMs mandate multi-supplier qualification for battery enclosure gasket programs, fragmenting procurement across Saint-Gobain, 3M, and regional compounders. Geographic supply concentration centers on Germany, China, and the United States, where Stuttgart engineering centers, Shandong blowing agent capacity, and Michigan weatherstrip fabrication anchor global output. Raw material dependencies draw from ethylene-propylene monomer streams, azodicarbonamide and bio-based blowing agents, and fluoropolymer liner stocks. Single-source vulnerability runs through China's concentrated azodicarbonamide capacity. Distribution runs through direct mill relationships for qualified automotive and aerospace applications, with regional distributors serving fragmented MRO construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
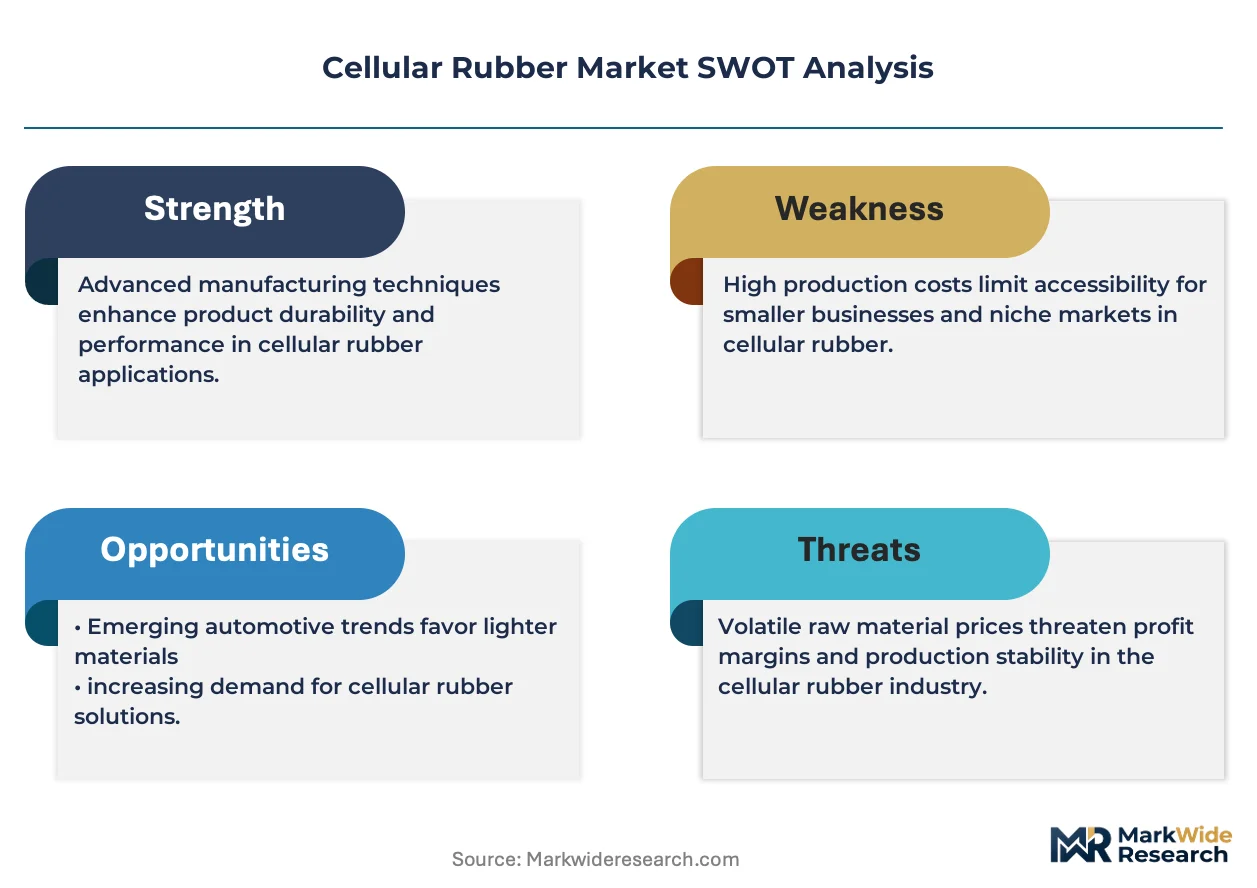
This market reads as a cost-of-compliance story where ECHA REACH substance restrictions on azodicarbonamide and phthalates erect formidable barrier-to-entry moats for compounders with captive reformulation capabilities and emission control infrastructure.
For Market Incumbents: Acquire captive blowing agent manufacturing assets to secure supply continuity against Shandong concentration risk. Incumbent compounders should expand AS9100-certified fabrication cells in Baden-Württemberg to block specialty distributor encroachment in aerospace channel control. Defensive consolidation toward bio-based blowing agent R&D preserves margin structures as ECHA thresholds tighten further. For New Entrants and Emerging Players: Supercritical CO2 physical foaming technology offers a technology-first wedge into medical device sealing applications in Minnesota and Massachusetts corridors. White-space targets concentrate on green hydrogen electrolyzer gasket niches requiring fluoropolymer-lined cellular grades resistant to caustic KOH environments. India's PLI scheme zones near Chennai present the most penetrable geography for EV thermal management component localization. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by diversified materials conglomerates seeking REACH-compliant formulation capabilities. Long-term viability favors compounders with integrated calendering-fabrication infrastructure and established OEM PPAP qualification histories. The signal to watch is EPA NESHAP enforcement intensity in Michigan and Ohio corridors, which would accelerate distressed asset availability among non-compliant weatherstrip suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Blowing Agent Supply | Captive azodicarbonamide or bio-based agent production reduces Shandong supply vulnerability for Western compounders. |
| AS9100 Certification Investment | Aerospace-qualified manufacturing cells with lot-traceable testing block distributor substitution in FAA-regulated procurement. |
| Geographic Expansion to Indian PLI Zones | Chennai and Pune production hubs capture EV component localization incentives under India's PLI scheme. |
| Supercritical CO2 Process Conversion | Eliminates residual chemical blowing agent byproducts for medical device implantable seal qualification. |
| Long-term Supply Agreement with OEMs | Multi-year thermal management gasket contracts anchor specification control against spot-market competitors. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this cellular rubber market assessment. Primary interviews with polymer compounder R&D directors, automotive Tier-1 procurement managers, aerospace OEM specification engineers, and industrial distributor channel heads combined with secondary validation from ECHA substance restriction databases, EPA NESHAP implementation records, and China customs import statistics. Bottom-up modeling of EPDM, neoprene, silicone, and PVC grade volumes triangulated against top-down automotive production and construction activity indicators.
Granularity-level framing applied chemistry-grade, end-use application, and regional production hub dimensions across the analysis window. Segmentation modeling captured material type, automotive versus aerospace versus construction end-use, and direct versus distributor channel splits. CAGRs derived from regression analysis against EV battery pack production forecasts and green hydrogen infrastructure deployment trajectories. Industry-specific inputs included azodicarbonamide price series and OEM thermal management content-per-vehicle assumptions.
Several conditions sit outside the modeled scope, including abrupt REACH substance list expansion, geopolitical disruption of Shandong chemical manufacturing corridors, and solid-state battery thermal interface material substitution above 230°C silicone ceilings. Forecasts reflect assumptions regarding ECHA enforcement consistency and PLI scheme continuity in India. Deviation in EPA NESHAP compliance cost trajectories would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rubber
Isoprene Rubber Market
Rubber
Global Rubber Market
Rubber
Nitrile Butadiene Rubber (NBR) Latex Market
Rubber
Chloro-Sulfonated Polyethylene Market
Rubber
Rubber Seal Plugs Market
Rubber
US Nitrile Gloves Market
Rubber
Global Liquid Synthetic Rubber Market
Rubber
Global Styrene Butadiene Styrene Market
Rubber
Rubber Rollers Market
Rubber
Fluorosilicone (FVMQ) Rubber Market
Rubber
Rubber Choppers Market
Rubber
Rubber Gloves Market
Rubber
Europe Rubber Derived Unrefined Pyrolysis Oil Market
Rubber
Europe Neoprene Market
Rubber
Synthetic Rubber Market
Rubber
Polybutadiene Market