
 Steel Testing Equipment Market | 2026-2036
Steel Testing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Testing Equipment Market Outlook
Aftermarket service revenue is reconfiguring how equipment vendors capture lifetime value from installed tensile and hardness testing systems. ZwickRoell leverages its calibration and retrofit services to sustain recurring income streams beyond initial hardware sales. Instron anchors its competitive stance through deep R&D intensity in digital load cell architectures. MTS Systems Corporation dominates high-force fatigue testing platforms for structural steel verification.
Steel testing equipment encompasses mechanical and non-destructive instruments that measure tensile strength, hardness, impact resistance, and fatigue life of ferrous alloys, typically operating across load ranges from kilonewtons to meganewtons to certify compliance with ASTM E8 and ISO 6892 standards. Tensile testers command the largest installed base due to universal material certification requirements, while ultrasonic testing systems represent the fastest-expanding technology segment as manufacturers shift toward in-line non-destructive verification. Quality control applications absorb the majority of unit volume, though research development deployments carry higher per-unit margins.
ISO 6892 material testing standards, ASTM E23 impact test protocols, and EU CE marking requirements under the Machinery Directive collectively shape product design specifications and market access conditions for equipment vendors. The US OSHA workplace safety framework and China's GB standards further calibrate regional demand for automated testing systems with integrated data logging. Stakeholders must weigh capital deployment between universal testing machine refreshes and specialized ultrasonic platform investments as end-user certification protocols diverge across geographies.
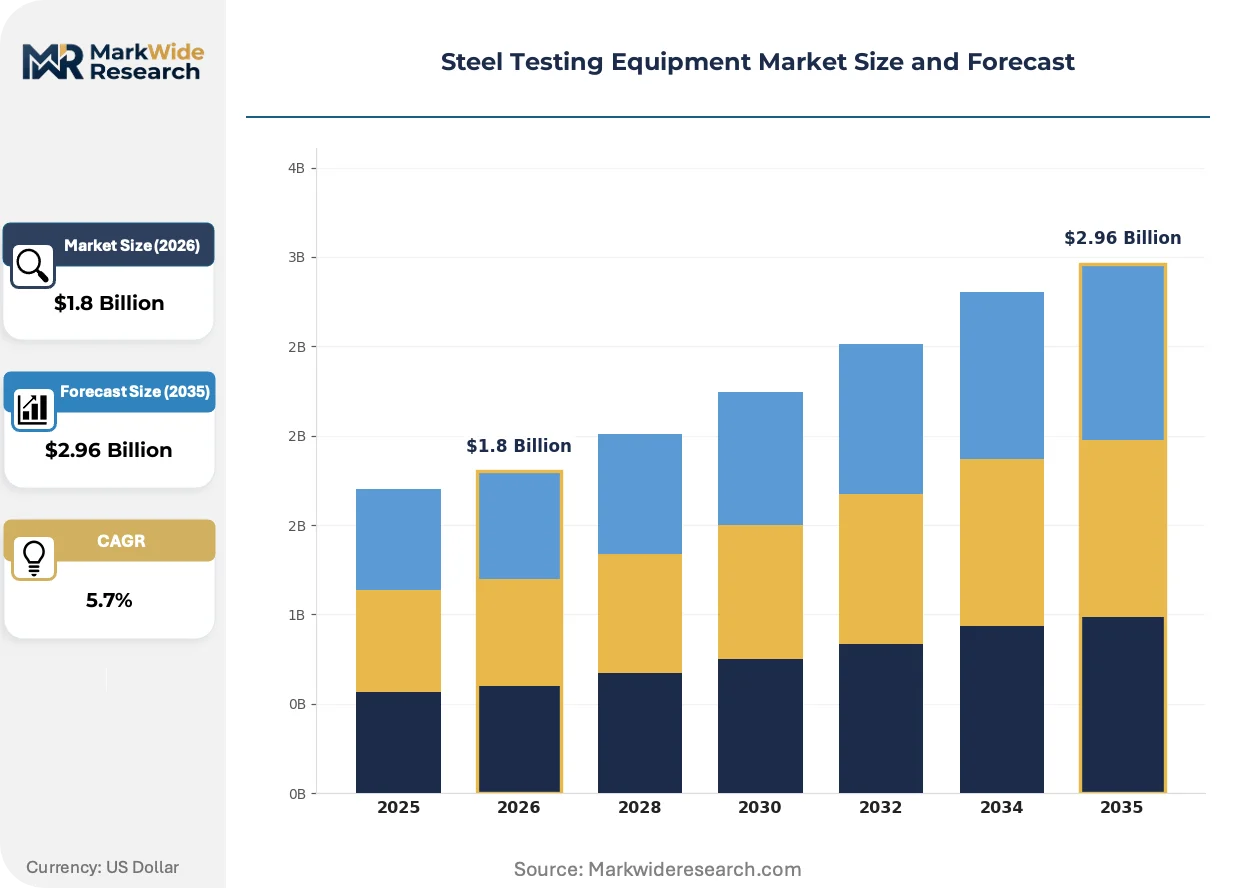
Market Dynamics
The steel testing equipment market is being restructured by the divergence between universal testing machine refreshes and specialized ultrasonic platform investments, as end-user certification protocols fragment across ISO 6892, ASTM E8, and national GB standards.
Growth Catalysts
- ISO 6892-1 compliance mandates:European structural steel fabricators must upgrade tensile testing systems to meet updated strain-rate control specifications, forcing equipment replacement cycles.
- China's infrastructure buildout:State-backed high-speed rail and bridge projects require continuous quality verification, sustaining demand for high-force fatigue testing platforms.
- Ultrasonic phased array adoption:In-line non-destructive testing integration allows steel mills to shift from batch sampling to 100% inspection coverage.
Market Restraints
- Load cell precision input costs:Strain-gauge and digital load cell architectures depend on specialized semiconductor substrates subject to supply volatility.
- German equipment supplier concentration:High-force fatigue testing platform manufacturing clusters in Baden-Württemberg, creating single-source vulnerability for structural verification systems.
- ASTM E23 protocol complexity:Charpy impact test certification requirements vary by specimen geometry and temperature, complicating universal machine design standardization.
Strategic Opportunities
- India's BIS certification expansion:Mandatory steel quality marking for construction and automotive applications is opening demand for automated hardness testing systems.
- Digital twin convergence:Integration of physical testing data with finite element analysis software enables predictive material behavior modeling for R&D laboratories.
- Retrofit service channels:Equipment vendors can capture recurring revenue by offering calibration and control system upgrades to installed tensile tester bases.
Industry Challenges
- Metallurgical technician scarcity:Operators capable of interpreting fracture surface analysis and aligning specimens per ISO 6892-1 are in short supply across testing laboratories.
- Multi-standard certification timelines:Equipment manufacturers must secure separate CE marking, OSHA compliance, and China GB approvals, extending product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Testing Equipment Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tensile Testers, Hardness Testers, Impact Testers, Fatigue Testers Technology: Universal Testing Machines, Digital Load Cells, Ultrasonic Testing Systems, Non-Destructive Testing End User: Manufacturers, Construction Companies, Research Labs, Quality Assurance Agencies Application: Structural Testing, Material Certification, Research Development, Quality Control |
| Companies Covered | ZwickRoell, Instron, MTS Systems Corporation, Shimadzu Corporation, Tinius Olsen, Ametek, Hegewald & Peschke, Qualitest, Buehler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Testing Equipment Market Strategic Shifts
Digital instrumentation architectures and automated specimen handling are compressing test cycle times while expanding data granularity beyond traditional pass-fail reporting. Equipment vendors are racing to embed connectivity protocols that feed directly into plant-level quality management systems.
Digital image correlation systems are migrating from research laboratory environments to production-floor tensile testing installations. Automotive tier-one suppliers in Germany and Japan are adopting these optical strain measurement technologies to eliminate extensometer contact artifacts. The shift is migrating from displacement-based measurement toward full-field deformation mapping, enabling material anisotropy detection that mechanical sensors cannot capture.
The EU Machinery Directive's updated safety requirements for automated testing cells are mandating integrated light curtains and force-limited robotic specimen loaders. Steel service centers must retrofit existing universal testing machines or purchase new certified platforms to maintain CE marking validity. High-volume Chinese producers are responding by developing domestic automated handling systems that undercut European safety-integrated equipment on capital cost.
Steel buyers are consolidating testing service contracts with fewer accredited laboratories, demanding ISO 17025-certified data packages with full raw strain curves rather than summary reports. This specification tightening is eliminating small regional testing houses from supplier qualification processes. The concentration is most visible in Germany's automotive supply chain, where OEMs now require direct data portal access to subcontractor test results.
Steel Testing Equipment Market Segmentation
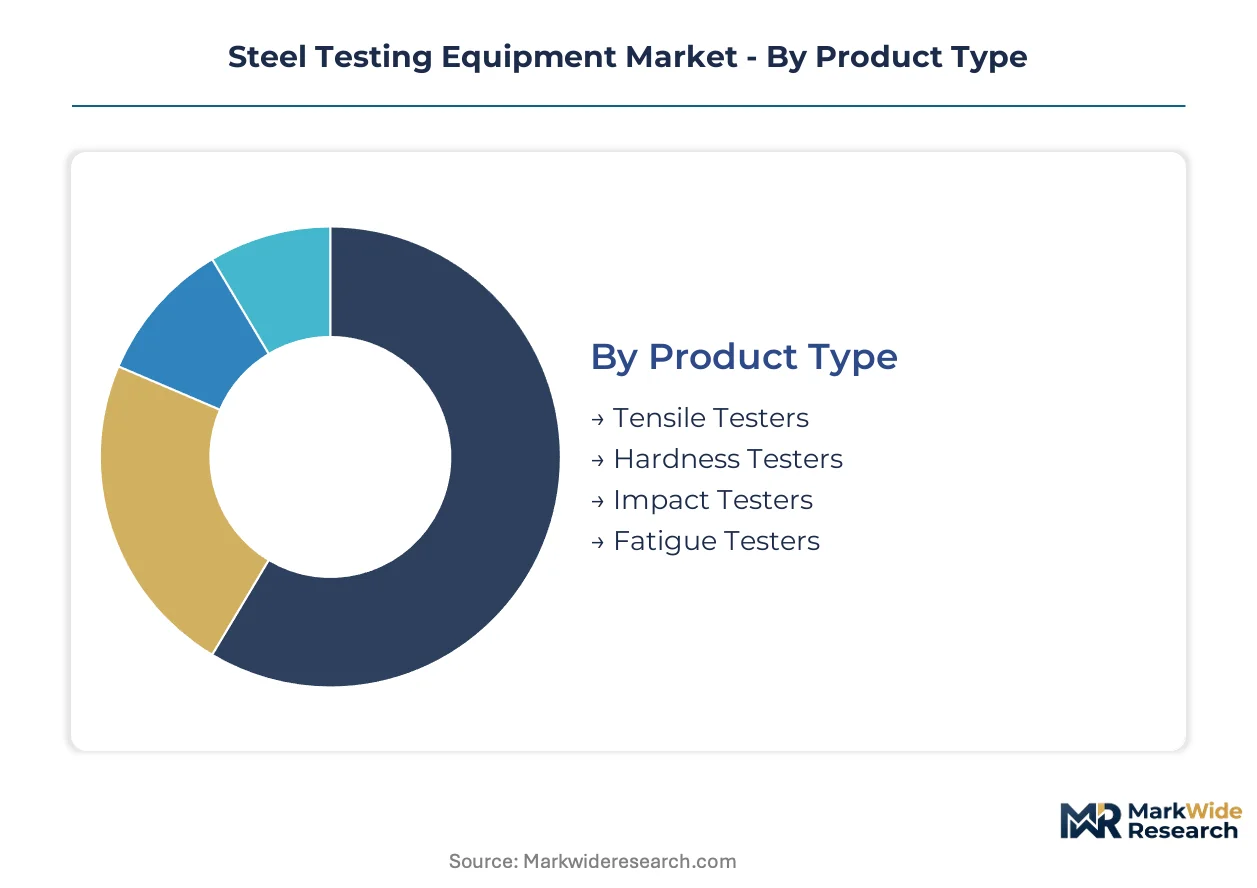
Steel testing equipment procurement cycles vary dramatically across product categories, with tensile testers refreshing every 7-10 years while ultrasonic systems face 3-5 year technology obsolescence pressures. Understanding these replacement velocities helps vendors calibrate service attach rates and inventory planning across installed bases.
Product Type:
Tensile testers and hardness systems anchor the longest replacement cycles, while fatigue and impact platforms turn over faster as force-range requirements evolve with new steel grades.
- Tensile Testers:These universal material certification systems apply controlled axial loads from kilonewtons to meganewtons to generate stress-strain curves per ASTM E8 and ISO 6892 protocols. Chinese steel mills operating continuous casting lines represent the densest installed base, driven by mandatory quality verification for GB-standard structural grades.
- Hardness Testers:Rockwell, Brinell, and Vickers indentation systems deliver rapid batch screening for heat-treatment verification. India's BIS certification expansion for construction steel is concentrating demand for automated Brinell platforms in Mumbai and Delhi NCR fabrication corridors.
- Impact Testers:Charpy and Izod pendulum systems measure fracture energy at calibrated temperatures. German automotive suppliers specify these for high-strength steel weld qualification.
- Fatigue Testers:High-cycle and low-cycle systems subject specimens to repetitive stress amplitude. Japanese shipyards deploy these for hull plate certification under ClassNK rules.
Tensile testers anchor the volume base while ultrasonic-integrated fatigue platforms gain share at the steepest rate.
Technology:
Equipment sophistication stratifies sharply by semiconductor content and software dependency, with digital architectures commanding 40-60% price premiums over analog predecessors.
- Universal Testing Machines:Electromechanical and hydraulic frames accommodate interchangeable grips and fixtures across test modes. South Korean steel producers favor these for multi-standard flexibility serving export markets.
- Digital Load Cells:Strain-gauge and capacitive force transducers with direct USB/Ethernet output eliminate analog signal conditioning. Brazilian flat-rolled mills are retrofitting these to legacy frames for ISO 17025 data integrity compliance.
- Ultrasonic Testing Systems:Phased-array and time-of-flight diffraction hardware enable volumetric defect mapping without specimen destruction. These systems are climbing the fastest as Chinese seamless pipe producers shift from batch sampling to 100% inline inspection.
- Non-Destructive Testing:Eddy current, magnetic particle, and radiographic methods supplement ultrasonic coverage. Saudi Aramco's steel plate specifications for pipeline projects mandate these for hydrogen-induced cracking detection.
Universal testing machines dominate installed value while ultrasonic testing systems expand most quickly through greenfield mill investments.
End User:
Procurement authority concentrates with quality assurance functions, though research laboratories exercise disproportionate influence over technology roadmaps through early adoption.
- Manufacturers:Integrated steel producers and rolling mills operate the largest in-house testing capacities. POSCO's Gwangyang works maintains over 200 automated testing stations across finishing lines.
- Construction Companies:Engineering-procurement-construction contractors deploy field-portable hardness and tensile systems for weld procedure qualification. Turkey's bridge and tunnel projects are driving mobile lab containerization.
- Research Labs:University and national laboratory facilities prioritize extensibility and multi-physics measurement. Germany's Fraunhofer Institutes specify digital image correlation add-ons for anisotropy studies.
- Quality Assurance Agencies:Third-party certification bodies require audit-trail documentation and interlaboratory proficiency testing. SGS and Bureau Veritas are consolidating their steel testing footprints in Vietnam and Indonesia.
Manufacturers command the deepest installed base while quality assurance agencies are capturing the steepest spending growth as outsourcing accelerates.
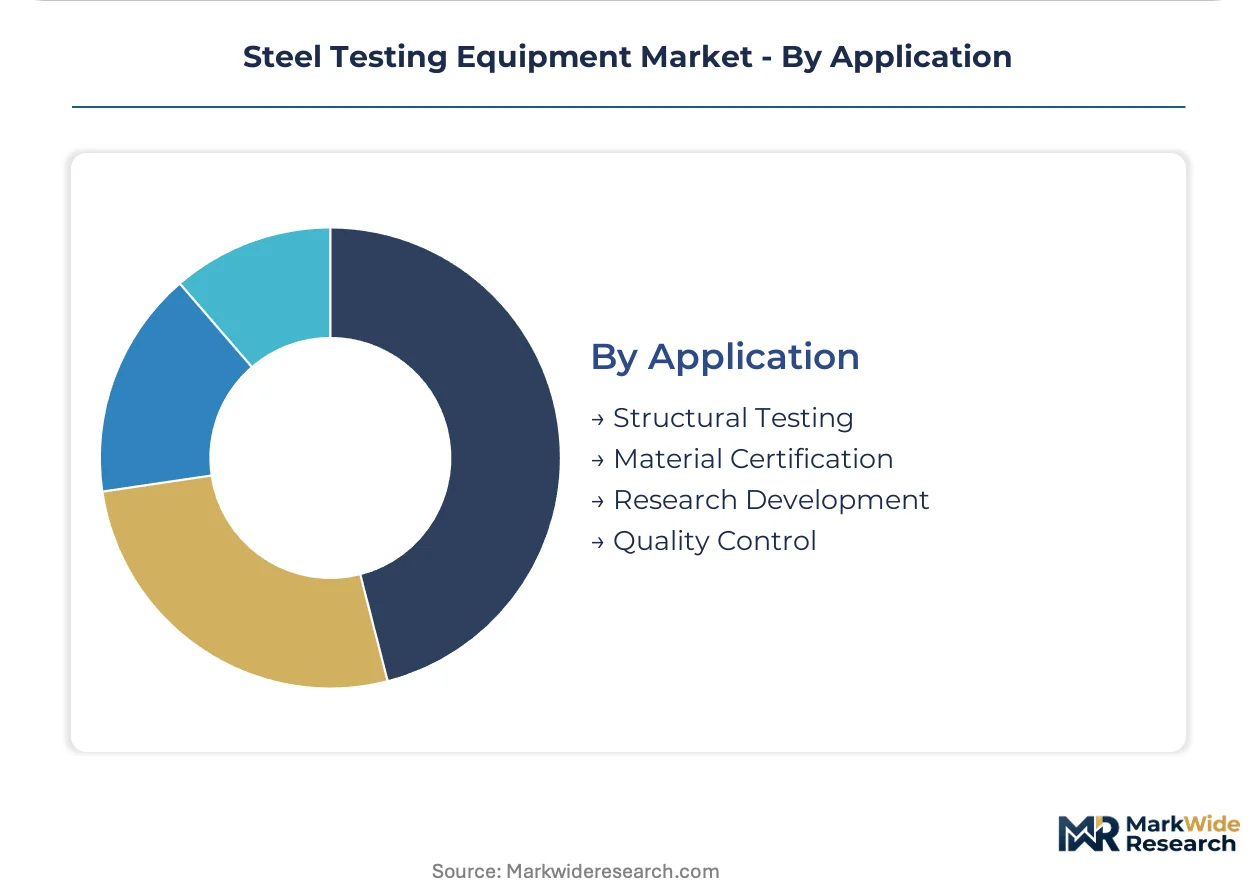
Application:
Margin structures invert between high-volume quality control and low-volume research development, with the latter sustaining 2-3x per-test pricing through specialized operator labor.
- Structural Testing:Load-bearing capacity verification for beams, columns, and connection details per Eurocode 3 and AISC specifications. Australian infrastructure contractors are expanding these capabilities for mega-project compliance.
- Material Certification:Mill test report generation for commercial shipment release. This segment represents the highest transaction velocity, with Chinese producers issuing millions of certificates annually.
- Research Development:Novel alloy characterization and processing-microstructure-property correlation. Nippon Steel's Advanced Technology Research Laboratories operate the most sophisticated multi-axial testing capabilities globally.
- Quality Control:In-process monitoring at casting, rolling, and heat-treatment stages. This application is expanding most rapidly as Industry 4.0 integration enables real-time SPC feedback.
Material certification generates the highest transaction volume while research development commands the steepest margin expansion through digital twin integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel testing equipment consumption varies sharply by geography: Chinese producers prioritize high-throughput inline systems for continuous casting verification, while German automotive suppliers demand multi-standard flexibility for export certification, and Indian fabricators focus on automated hardness platforms for BIS compliance.
China
State-backed high-speed rail and bridge projects sustain demand for high-force fatigue testing platforms. GB standards mandate continuous quality verification at steel mills operating continuous casting lines. Shanghai and Hebei province host the densest installed bases, with producers issuing millions of mill test certificates annually for structural steel shipments.
Germany
Automotive tier-one suppliers specify Charpy impact testers for high-strength steel weld qualification under OEM protocols. CE marking requirements under the EU Machinery Directive mandate integrated safety systems for automated testing cells. Baden-Württemberg clusters high-force fatigue platform manufacturing, creating concentrated supply for structural verification systems.
United States
OSHA workplace safety frameworks calibrate demand for automated testing systems with integrated data logging across fabrication corridors. ASTM E8 and E23 protocol complexity drives universal machine refreshes for strain-rate control compliance. Houston and Chicago metropolitan areas concentrate steel service center testing capacity for oilfield and construction applications.
India
Mandatory BIS certification for construction and automotive steel is opening demand for automated Brinell hardness testing systems. The country's national standards body enforces quality marking protocols that eliminate small regional testing houses from supplier qualification. Mumbai and Delhi NCR fabrication corridors concentrate procurement of mobile lab containerization for infrastructure projects.
Japan
Shipyards deploy fatigue testers for hull plate certification under ClassNK classification society rules. METI industrial policy supports digital image correlation adoption for full-field deformation mapping in automotive supply chains. Nagoya and Osaka industrial zones anchor R&D laboratory demand for multi-axial testing capabilities.
Steel Testing Equipment Market Competitive Environment
Capability concentration sits with one tier; scale advantage sits with another. German and Japanese precision engineering houses anchor high-margin fatigue and impact testing platforms, while Chinese fabricators capture volume through cost-optimized automated handling systems. Three strategic archetypes dominate: universal testing machine specialists, non-destructive testing platform developers, and aftermarket service integrators. Competitive moves center on calibration network expansion and control system retrofit offerings to installed bases.
Among German-based precision engineering groups, ZwickRoell GmbH & Co. KG and Hegewald & Peschke Meß- und Prüftechnik GmbH occupy positions within the high-force structural verification tier. Shimadzu Corporation represents Japanese multi-physics instrumentation capabilities spanning materials characterization. These three exemplify the capability-scale divergence: European houses emphasize service attach rates and calibration recurring revenue, while the Japanese conglomerate anchors research laboratory influence through early technology adoption.
| Leading Market Players |
|---|
| ZwickRoell |
| Instron |
| MTS Systems Corporation |
| Shimadzu Corporation |
| Tinius Olsen |
| Ametek |
| Hegewald & Peschke |
| Qualitest |
| Buehler |
| Others |
Value Chain & Pricing Dynamics
German equipment supplier concentration in Baden-Württemberg creates single-source vulnerability for high-force fatigue testing platforms, compressing pricing tier spreads between premium CE-marked systems and economy-grade Chinese alternatives while forcing buyers into extended payment term negotiations with concentrated vendors.
Pricing Analysis
Long-term offtake contracts dominate procurement for integrated steel mills, while spot purchases and project-based tenders serve construction contractors and quality assurance agencies. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with ISO 17025-compliant systems commanding substantial premiums over basic GB-standard units. Cost compression in the economy tier is intensifying because Chinese fabricators are undercutting European safety-integrated equipment on capital cost. Construction companies exhibit the highest price sensitivity due to project-based budgeting, whereas research laboratories prioritize extensibility over unit economics.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities have become critical negotiation levers as equipment vendors manage semiconductor substrate procurement volatility. Manufacturing concentrates in Germany, Japan, and China, with strain-gauge and digital load cell architectures drawing from specialized semiconductor supply channels anchored in Taiwan and South Korea. Single-source vulnerability runs through the Baden-Württemberg cluster for high-force structural verification systems. Distribution runs through direct vendor sales for large mill accounts and regional distributor networks for mid-market construction and laboratory segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Steel testing equipment procurement is approaching a platform-economics inflection as digital twin convergence and Industry 4.0 integration create interoperability requirements that favor vendors with open data architectures over closed legacy systems.
For Market Incumbents: Entrench calibration network density and retrofit service capabilities to capture recurring revenue from installed tensile tester bases. Expand control system upgrade offerings for legacy frames to defend against Chinese automated handling system entrants. Prioritize R&D investment in digital image correlation add-ons to maintain research laboratory influence against Shimadzu's multi-physics instrumentation push. For New Entrants and Emerging Players: Establish a beachhead in India's BIS certification expansion corridor, where mandatory quality marking for construction steel is opening demand for automated Brinell hardness testing systems. Target mobile lab containerization for Turkish bridge and tunnel projects as the most penetrable infrastructure application. Lead with cost-optimized ultrasonic phased array platforms to exploit the shift from batch sampling to 100% inline inspection at Chinese seamless pipe producers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors aftermarket service integrators with dense calibration footprints over pure hardware manufacturers. Long-term viability rests on recurring revenue attach rates rather than replacement cycle dependency. Signal to watch: accelerated outsourcing of testing services to ISO 17025-certified agencies as steel buyers consolidate contracts and eliminate small regional laboratories.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Network Expansion | ZwickRoell's service attach rate model sustains recurring revenue beyond initial hardware sales. |
| Digital Twin Integration | Physical testing data convergence with finite element analysis enables predictive material modeling for R&D laboratories. |
| Retrofit Service Channel Development | Control system upgrades to installed tensile tester bases capture lifetime value from aging universal testing machines. |
| Automated Handling System Certification | EU Machinery Directive safety requirements for robotic specimen loaders create compliance barriers for economy-tier entrants. |
| Ultrasonic Phased Array Platform Launch | Inline non-destructive testing integration allows steel mills to shift from batch sampling to full inspection coverage. |
Study Parameters
The analysis maps tensile testing systems, hardness platforms, fatigue testers, and ultrasonic inspection equipment, each validated through quality assurance directors, plant engineers at integrated steel mills, and aftermarket service heads. Primary interviews with laboratory managers at Fraunhofer Institutes and SGS certification bodies combined with secondary validation against ISO standards documentation, ASTM protocol publications, and national GB standard filings. Bottom-up equipment shipment tracking and top-down steel production correlation anchored market sizing across the projection horizon.
Assumptions held fixed include continued ISO 6892-1 compliance mandate enforcement and China's infrastructure buildout trajectory, while variables included ultrasonic technology adoption rates and BIS certification expansion pacing. Segmentation modeling covered product type, technology architecture, end-user category, and application intensity across the analysis window. CAGRs derived from replacement cycle velocity differentials between 7-10 year tensile tester refreshes and 3-5 year ultrasonic obsolescence pressures, with steel grade evolution and force-range requirement shifts as industry-specific inputs.
Sensitivities concentrate around semiconductor substrate supply volatility, metallurgical technician scarcity, and multi-standard certification timeline extensions. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and infrastructure investment commitment. Macroeconomic contraction, regulatory harmonization failure, or disruptive non-destructive testing technology emergence would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Environmental Testing Equipment Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market
Testing Equipment
Chromatography Systems Market
Testing Equipment
Global Online Coal Ash Analyzers Market
Testing Equipment
Chromatography Market
Testing Equipment
Grease Analyzer Market
Testing Equipment
Asia-Pacific Process Analytics Market
Testing Equipment
Water Test Kits Market
Testing Equipment
Europe Non-Destructive Testing Market
Testing Equipment
Hydrogen Peroxide Measurement Market
Testing Equipment
Rheology Controller Market
Testing Equipment
Global Rheometer and Viscometer Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Japan Material Testing Market
Testing Equipment
Geochemical Services Market
Testing Equipment
Chemical Analyzer Market