
 Bio-Based Epoxy Resin Market | 2026-2036
Bio-Based Epoxy Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Bio-Based Epoxy Resin Market Analysis
Automotive OEM demand is hardening as manufacturers substitute conventional epoxy with plant-derived formulations in structural composites and underbody coatings. Huntsman leverages its thermosetting technology leadership to supply certified bio-based systems to European automakers. Kukdo Chemical anchors Asian supply through high-volume manufacturing of hybrid epoxy intermediates. SPOLCHEMIE specializes in custom liquid resins for marine and construction applications, competing on specification breadth rather than scale alone.
Bio-based epoxy resin comprises epoxide functional groups synthesized from renewable feedstocks such as epichlorohydrin derived from glycerol or plant oils like cashew nut shell liquid, with typical bio-content ranging from 30% to 70% depending on certification standard. These resins cure through thermosetting crosslinking to deliver adhesion, chemical resistance, and mechanical strength for coatings, composites, and electrical encapsulation. Liquid formulations dominate volume consumption in coatings and adhesives due to ease of application and compatibility with existing spray and dip equipment. Composites represent the fastest-growing application segment as wind blade manufacturers and automotive tier suppliers adopt bio-based prepregs to meet scope 3 emissions targets. Solid and powder grades occupy narrower but higher-margin niches in powder coatings and electrical encapsulation where thermal stability requirements are stringent.
REACH registration requirements in Europe, EPA bio-preferred procurement guidelines in the United States, and BIS certification pathways in India collectively shape product formulation standards and market access conditions for bio-based epoxy suppliers. The EU Green Deal's embedded carbon reporting mandates are forcing downstream users to document renewable content share, directly steering R&D budgets toward certified bio-based feedstocks. Stakeholders must monitor evolving lifecycle assessment methodologies and certification scheme harmonization between ISO standards and regional bio-content labeling rules to avoid compliance fragmentation that could strand inventory or lock out market segments.
Market Dynamics
Automotive OEMs and wind blade manufacturers are forcing feedstock certification upstream, converting renewable carbon accounting from marketing claim to procurement gate. Suppliers without ISO 16620 or USDA BioPreferred documentation face exclusion from tier-one supplier lists.
Growth Catalysts
- EU Green Deal embedded carbon mandates:Downstream manufacturers must document scope 3 emissions reductions, directing R&D budgets toward certified bio-based epoxy systems for composites and coatings.
- Wind energy capacity expansion:Blade producers specify bio-based prepregs to meet sustainability targets, creating pull-through demand for plant-derived resin formulations in turbine manufacturing.
- Germany's automotive cluster concentration:Stuttgart and Munich anchor lightweight composite adoption, with OEMs substituting conventional epoxy in structural panels and underbody applications.
Market Restraints
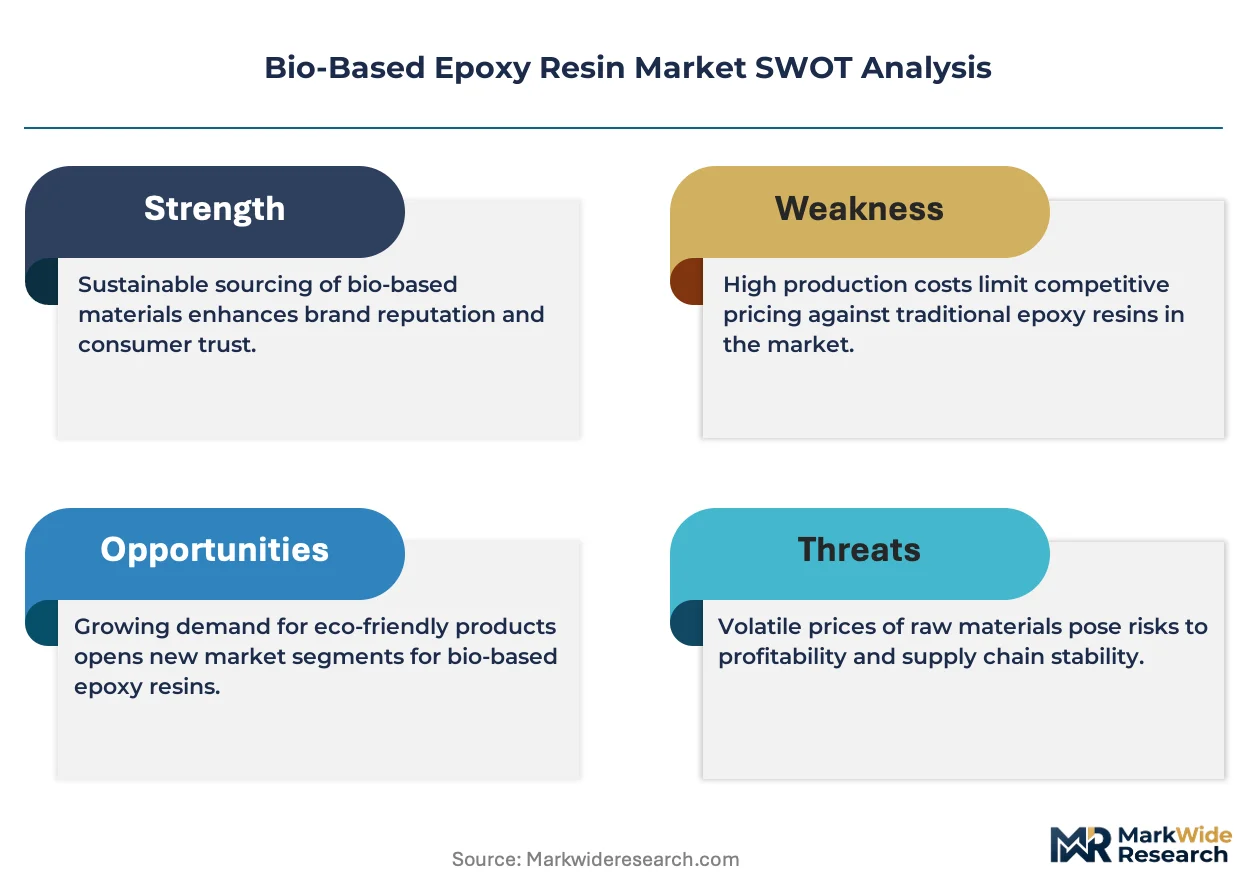
- Epichlorohydrin feedstock volatility:Glycerol-derived supply chains compete with biodiesel and oleochemical markets, creating price instability for bio-based epoxy intermediates.
- Asian supply concentration:Hybrid epoxy manufacturing clusters in South Korea and China create geographic risk for European formulators dependent on imported intermediates.
- Performance gaps in high-temperature applications:Bio-based systems exhibit lower glass transition temperatures than petroleum analogs, limiting adoption in powder coatings and electrical encapsulation.
Strategic Opportunities
- India's BIS certification pathway:National bio-content labeling standards create first-mover advantage for suppliers establishing local formulation partnerships ahead of formal mandate rollout.
- Marine coating retrofit demand:Shipyard maintenance cycles in Northern Europe present conversion opportunity from solvent-based systems to bio-based epoxy hull coatings.
- Digital inventory platforms:Blockchain-tracked renewable content certificates enable spot-market trading of bio-based epoxy grades, reducing working capital burdens for small-batch formulators.
Industry Challenges
- Cross-functional formulation expertise scarcity:Chemists capable of balancing bio-content targets with cure kinetics and mechanical performance command premium compensation, constraining R&D team scaling.
- Multi-certification timeline compression:Simultaneous pursuit of REACH registration, USDA BioPreferred approval, and ISO 16620 compliance extends product launch cycles by 18-24 months.
- Legacy equipment compatibility testing:Spray and dip line operators require validation runs to confirm bio-based epoxy viscosity and pot-life match existing automation parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bio-Based Epoxy Resin Market |
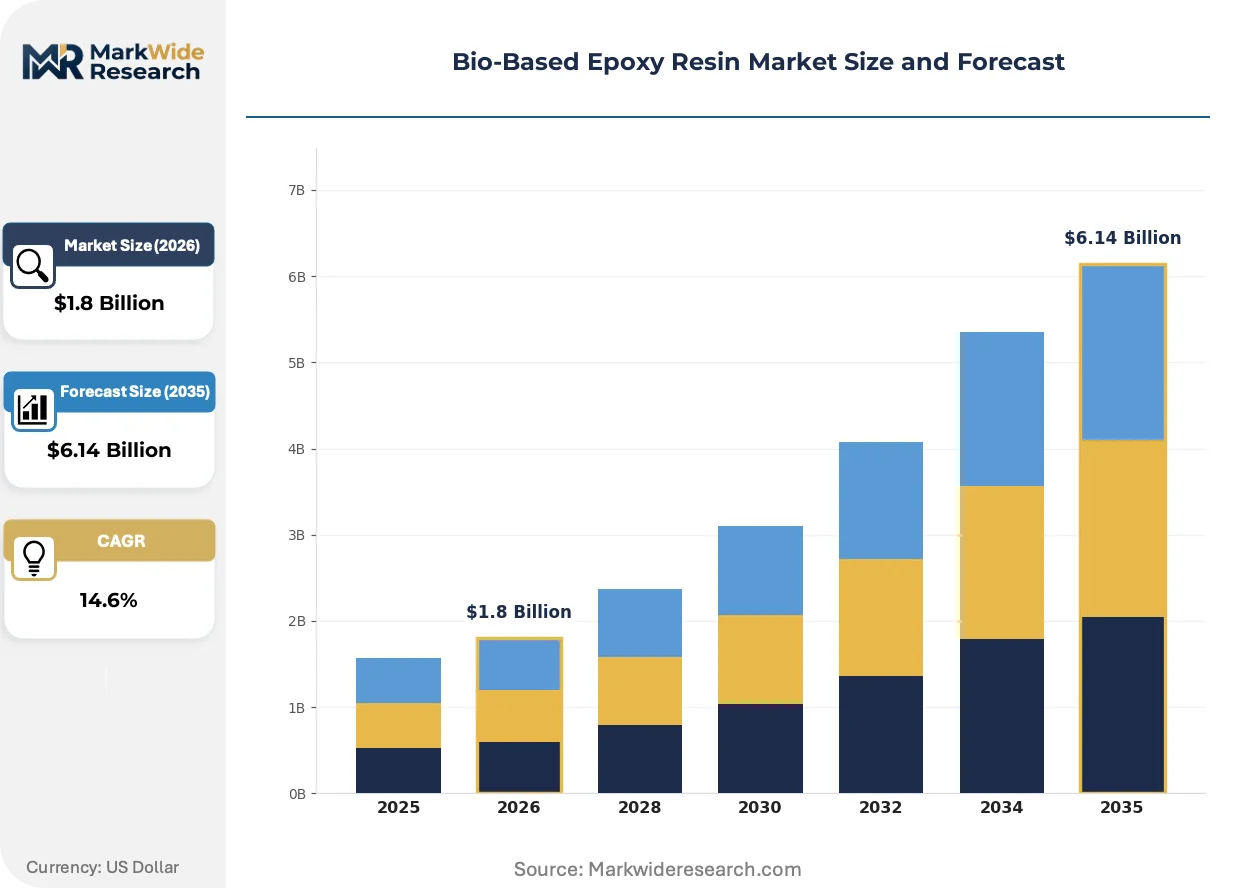
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Powder, Gel End User: Aerospace, Automotive OEMs, Construction, Marine Application: Coatings, Adhesives, Composites, Electrical Encapsulation Technology: Thermosetting, Bio-based, Hybrid, Waterborne |
| Companies Covered | Kukdo Chemical, Huntsman, SPOLCHEMIE, Entropy Resins, ECOPOXY Inc, Sicomin Epoxy Systems, Cardolite Corporation, Bitrez Ltd, Change Climate Pty Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bio-Based Epoxy Resin Market Emerging Trajectories
Process intensification and digital traceability are compressing development cycles while hardening compliance requirements. Formulators now compete on certification breadth and carbon accounting transparency rather than price alone.
Hybrid curing technology combining UV-initiated and thermal crosslinking mechanisms is unifying processing flexibility with mechanical performance. Automotive tier suppliers in Germany adopt these systems for complex geometries requiring rapid tack-free handling. The technology is unifying previously separate equipment investments, allowing coating lines to switch between bio-based epoxy grades without dedicated thermal ovens.
REACH authorization requirements for conventional epoxy precursors are tightening petrochemical pathways across Europe. ECHA's substance evaluation program is restricting bisphenol-A derivatives in consumer-facing applications. Marine coating formulators in the Netherlands and Denmark accelerate bio-based substitution to preempt regulatory displacement.
Certificate-of-origin purchasing is displacing spot-market commodity buying among wind energy OEMs. Vestas and Siemens Gamesa now contract directly for glycerol-derivation documentation, bypassing distributor opacity. This behavioral shift concentrates procurement leverage with resin suppliers possessing integrated feedstock traceability systems.
Bio-Based Epoxy Resin Market Segmentation
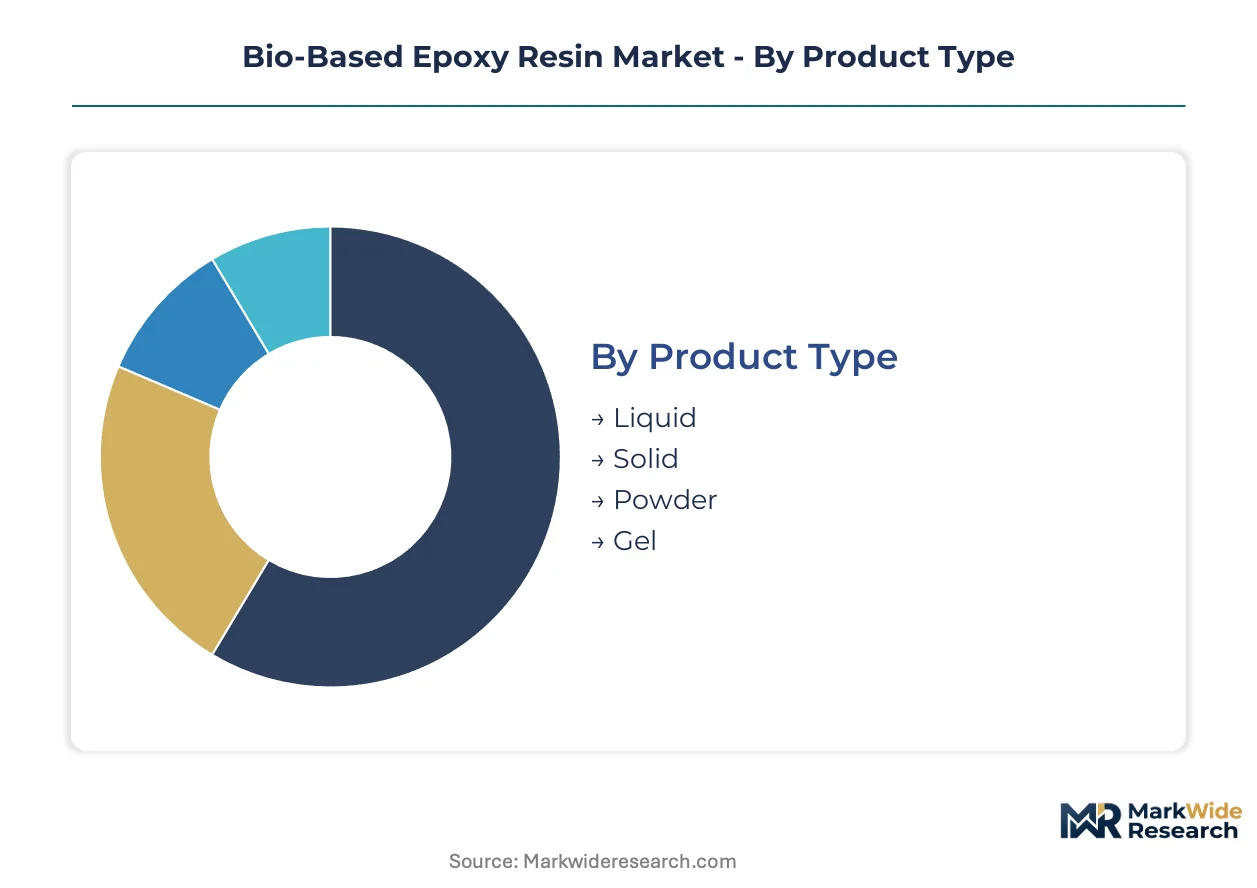
Formulators compete across four intersecting dimensions where technical specifications, regulatory compliance, and end-use performance requirements create distinct competitive battlegrounds. Product type determines processing infrastructure compatibility. Application and end-user specifications dictate certification requirements and carbon accounting rigor.
Product Type:
Liquid grades concentrate manufacturing capacity among integrated glycerol-derivation facilities in Germany and the Netherlands, while solid and powder formulations remain fragmented across specialty batch producers.
- Liquid:Dominates volume consumption through ease of spray and dip application in coatings and adhesives. Automotive OEMs in Stuttgart and Munich specify liquid bio-based epoxy for underbody coatings and structural composite matrices, driven by EU Green Deal embedded carbon reporting mandates.
- Solid:Requires elevated cure temperatures but delivers superior thermal stability for electrical encapsulation and powder coating precursors. Demand concentrates in German industrial electronics manufacturing where REACH restrictions on conventional bisphenol-A derivatives accelerate substitution.
- Powder:Occupies narrow high-margin niches in electrical insulation and protective coatings where zero-VOC requirements intersect with thermal performance needs.
- Gel:Serves marine repair and construction gap-filling applications where thixotropic behavior enables vertical surface application without sag.
Today's leader: Liquid. Tomorrow's challenger: Solid.
End User:
Procurement authority varies sharply across end users, with automotive OEMs and wind energy blade manufacturers wielding tier-one supplier list exclusion power while construction remains price-sensitive and specification-loose.
- Automotive OEMs:Command the most stringent feedstock certification requirements, mandating ISO 16620 documentation and blockchain-tracked renewable content certificates for structural composite panels.
- Aerospace:Imposes aerospace-grade qualification timelines extending 24-36 months for new bio-based epoxy systems, creating barrier-to-entry moats for qualified suppliers.
- Construction:Absorbs volume through flooring and adhesive applications where cost parity with petroleum alternatives determines specification, particularly in German commercial building retrofits.
- Marine:Presents retrofit opportunity in Northern European shipyard maintenance cycles, with Dutch and Danish yards converting solvent-based hull coatings to bio-based epoxy systems ahead of ECHA substance evaluation restrictions.
Automotive OEMs set certification standards. Marine offers conversion volume.
Application:
Application selection determines margin structure, with composites commanding premium pricing for carbon-accounted prepregs while coatings compete on throughput efficiency and equipment compatibility.
- Composites:Expanding most quickly as Vestas and Siemens Gamesa contract directly for glycerol-derivation documentation, bypassing distributor opacity to meet scope 3 emissions targets in wind blade manufacturing.
- Coatings:Retains volume leadership through automotive underbody and marine hull applications where spray line compatibility and pot-life predictability outweigh bio-content maximization.
- Adhesives:Serves construction and transportation assembly where gap-filling strength and environmental durability specifications dominate procurement criteria.
- Electrical Encapsulation:Demands highest thermal stability grades, limiting bio-based adoption where glass transition temperature gaps persist against petroleum analogs.
Composites climb fastest. Coatings defend volume base.
Technology:
Technology selection reflects trade-offs between processing flexibility, certification compliance cost, and performance envelope, with hybrid systems capturing investment from formulators seeking to bridge these tensions.
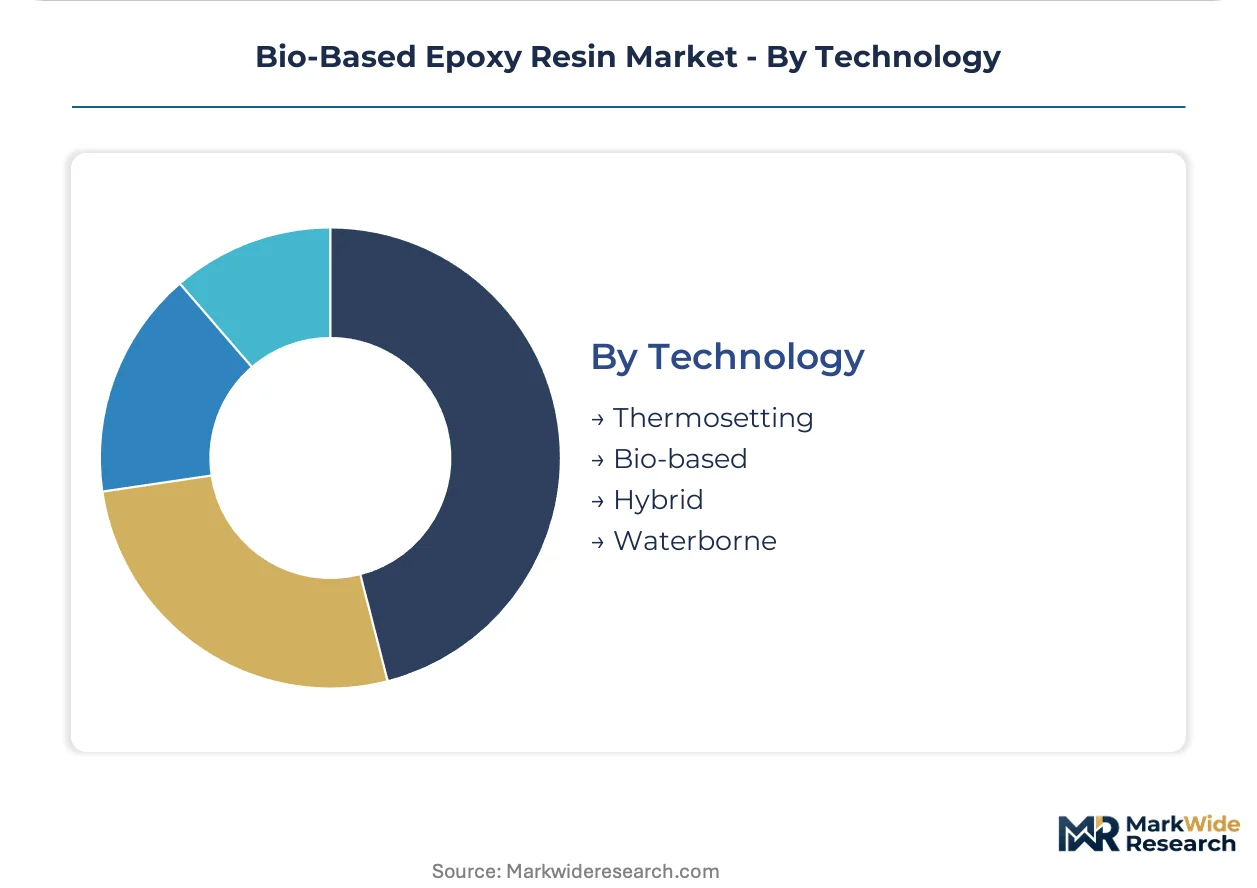
- Thermosetting:Anchors commercial production through proven crosslinking kinetics and established supply chains for glycerol-derived epichlorohydrin feedstocks.
- Bio-based:Pure formulations target USDA BioPreferred and EU organic content labeling, commanding 15-30% price premiums where procurement mandates require maximum renewable share.
- Hybrid:Combines bio-derived and petroleum-derived intermediates to balance cost, performance, and certification compliance, dominating Asian manufacturing output from South Korean integrated producers.
- Waterborne:Addresses VOC regulatory pressure in consumer-facing applications, with ECHA restrictions on solvent-based systems driving substitution in European decorative coatings.
Hybrid holds installed base. Waterborne gains regulatory tailwind.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as manufacturers relocate formulation capacity to jurisdictions with streamlined bio-content certification pathways and lower compliance overhead.
Germany
Automotive OEM procurement mandates from Stuttgart and Munich clusters drive certified bio-based epoxy consumption for structural composites and underbody coatings. REACH registration requirements and EU Green Deal embedded carbon reporting force suppliers to document renewable content share through ISO 16620 certification. The Baden-Württemberg automotive corridor anchors lightweight materials adoption, with tier-one suppliers converting spray lines to bio-based liquid formulations.
United States
Wind blade manufacturers and marine coating formulators generate pull-through demand for plant-derived resin systems to meet scope 3 emissions targets. EPA bio-preferred procurement guidelines shape federal purchasing standards, while state-level low-carbon fuel standards in California create secondary demand signals. The Gulf Coast petrochemical corridor hosts emerging glycerol-derivation facilities competing with traditional epichlorohydrin supply chains.
China
Dual carbon goals and GB standards for bio-based materials are accelerating domestic formulation capacity expansion for electrical encapsulation and construction adhesives. The Ministry of Ecology and Environment tightening VOC regulations in the Yangtze River Delta pushes coating manufacturers toward waterborne and bio-based epoxy alternatives. Shanghai and Jiangsu province industrial parks concentrate hybrid epoxy manufacturing for export markets.
India
BIS certification pathways for national bio-content labeling standards create first-mover positioning opportunities ahead of formal mandate rollout. Construction sector demand for flooring and adhesive applications concentrates in Maharashtra and Gujarat commercial building retrofits. The Mumbai-Pune industrial corridor anchors formulation partnerships between domestic distributors and international resin suppliers.
South Korea
Integrated hybrid epoxy manufacturing clusters serve Asian export markets through high-volume production of glycerol-derived intermediates. MFDS and national green procurement standards shape domestic certification requirements for electronics encapsulation grades. The Ulsan petrochemical complex and Daegu-Gyeongbuk region host backward-integrated producers controlling feedstock derivation through captive glycerol supply.
Bio-Based Epoxy Resin Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with formulation expertise and certification breadth determining tier-one supplier list inclusion rather than scale alone. Market structure concentrates among integrated glycerol-derivation facilities in Germany and the Netherlands, while Asian manufacturing clusters fragment around hybrid production systems. Three archetypes dominate: thermosetting technology leaders with established automotive relationships, high-volume hybrid epoxy producers serving export markets, and specialty batch manufacturers competing on specification breadth. Capacity expansion and strategic partnerships represent the dominant competitive moves, as suppliers secure feedstock traceability systems and regional formulation partnerships.
Within the technology-leader tier, Huntsman Corporation and Kukdo Chemical exemplify divergent geographic strategies, with the former anchoring European automotive supply chains and the latter dominating Asian hybrid manufacturing output. SPOLCHEMIE occupies a position among specialty liquid resin producers, competing on custom formulation breadth for marine and construction applications rather than production scale. These three companies represent the archetype spectrum spanning integrated petrochemical heritage, Asian high-volume manufacturing, and European specialty batch production.
| Leading Market Players |
|---|
| Kukdo Chemical |
| Huntsman |
| SPOLCHEMIE |
| Entropy Resins |
| ECOPOXY Inc |
| Sicomin Epoxy Systems |
| Cardolite Corporation |
| Bitrez Ltd |
| Change Climate Pty Ltd |
| Others |
Supply Flow & Price Mechanics
Glycerol-derived epichlorohydrin feedstock costs cascade through three pricing tiers as bio-content certification thresholds harden. Contract buyers with ISO 16620 documentation command 15-30% premiums over uncertified spot grades, while hybrid formulations occupy a compressed mid-tier where Asian manufacturers compete on volume scale.
Pricing Analysis
Distributor margins compress most severely in the standard hybrid tier where South Korean integrated producers compete directly. Three-tier pricing structure across premium certified, standard hybrid, and economy petroleum-adjacent levels reflects certification investment recovery and feedstock traceability costs. Pricing pressure stems from glycerol supply competition with biodiesel markets, squeezing intermediate margins. Automotive OEMs exhibit lowest price sensitivity due to scope 3 compliance mandates, while construction flooring contractors resist premiums above petroleum parity.
Supply Chain Analysis
Certification gating concentrates procurement leverage with suppliers possessing blockchain-tracked renewable content systems. Manufacturing gravity centers on Germany, the Netherlands, and South Korea, with glycerol derivation, hybrid epoxy synthesis, and electrical-grade solid resin production anchoring respective hubs. Feedstock draws from biodiesel byproduct streams, cashew nut shell liquid plantations, and petroleum-adjacent epichlorohydrin. Single-source vulnerability runs through glycerol supply concentration in Southeast Asian oleochemical processing. Distribution runs through direct OEM contracts displacing distributor opacity in wind energy and automotive segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bio-based epoxy resin market reads as a late-cycle quality story where procurement mandates for certified feedstocks displace commodity spot buying. Automotive OEM scope 3 reporting requirements pull specification premiums toward maximum bio-content grades.
For Market Incumbents: Hedge epichlorohydrin feedstock exposure through backward integration into glycerol derivation or captive supply partnerships with biodiesel producers. Fortify certification breadth by pursuing simultaneous USDA BioPreferred and ISO 16620 documentation to preempt tier-one supplier list exclusion. Capacity addition in India ahead of BIS mandate rollout captures first-mover positioning in construction adhesives. For New Entrants and Emerging Players: Marine coating retrofit channels in Northern European shipyards offer lowest competitive density against entrenched automotive suppliers. India's BIS certification pathway presents penetrable white space ahead of formal standard enforcement. Construction flooring applications in Maharashtra commercial retrofits tolerate hybrid formulations where cost parity outweighs maximum bio-content marketing. For Investors and Strategic Acquirers: Consolidation pressure builds where certification timeline compression and multi-standard compliance costs strand sub-scale formulators. Five-to-ten year viability favors integrated glycerol-derivation facilities with established automotive relationships over pure-play batch producers. Watch for ECHA substance evaluation acceleration on bisphenol-A derivatives as inflection trigger for bio-based substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glycerol Derivation | Captive feedstock supply insulates margin compression from biodiesel market competition. |
| Multi-Certification Investment | Simultaneous ISO 16620 and USDA BioPreferred pursuit unlocks tier-one automotive procurement lists. |
| Regional Formulation Partnership | Local production in India ahead of BIS mandate rollout secures first-mover certification positioning. |
| Blockchain Traceability Deployment | Digital renewable content certificates enable spot-market trading and reduce working capital burdens. |
| Hybrid Technology Scale-Up | UV-thermal curing systems unify processing flexibility for complex automotive geometries without dedicated thermal ovens. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged resin formulators, automotive tier-one procurement leads, wind blade manufacturing engineers, marine coating technical directors, and construction adhesive distributors. Secondary validation drew from ECHA substance evaluation databases, REACH registration filings, EU Green Deal implementation trackers, and customs trade data for glycerol-derived intermediates. Bottom-up segment sizing triangulated against top-down macro demand indicators.
Segment-weighting distributed value and volume across product type, application, end-user, and technology dimensions. The analytical framework modeled bio-content certification tier, regional regulatory cluster, and feedstock derivation pathway throughout the forecast period. CAGRs derived from segment-level demand elasticity and substitution rate assumptions. Industry-specific inputs included wind energy capacity expansion pipelines, automotive lightweighting content-per-vehicle trajectories, and ECHA restriction timeline probabilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to glycerol supply competition with biodiesel markets and harmonization failures between ISO and regional bio-content labeling standards. Model outputs reflect assumptions on certification adoption curves and OEM procurement mandate enforcement intensity. A model refresh is warranted upon material change in ECHA bisphenol-A derivative evaluation timelines or BIS standard formalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
Africa Polyethylene Terephthalate (PET) Market
Polymers & Resins
Phenoxy Resins Market
Polymers & Resins
Nylon Resins Market
Polymers & Resins
Global Polyoxymethylene (POM) Market
Polymers & Resins
Global Polymer Dispersion Market
Polymers & Resins
Cathodic Acrylic Market
Polymers & Resins
Global Bio-Based Polyethylene Market
Polymers & Resins
Geopolymer Market
Polymers & Resins
Rosin Resin Market
Polymers & Resins
Polyglycerates Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Global Synthetic Polymers Market
Polymers & Resins
C5 Resin Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
India Flooring Resins Market